
 Alpine Ski Equipment Market | 2026-2036
Alpine Ski Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Alpine Ski Equipment Market Analysis
Modular binding systems is pivoting how recreational skiers configure their setups, letting buyers swap components across seasons rather than replacing entire rigs. Rossignol leverages its integrated boot-binding-ski ecosystem to lock in repeat purchases. Salomon sustains technology leadership in lightweight composite construction. Atomic anchors its position through precision-manufactured race skis that dominate competitive circuits.
Alpine ski equipment comprises engineered assemblies of skis, bindings, boots, and poles designed for controlled descent on snow-covered slopes, with modern skis typically measuring 150-190 cm in length and incorporating sidecut radii between 10-25 meters for turn initiation. The equipment serves recreational enthusiasts, competitive athletes, and commercial rental operations requiring durable performance under variable snow conditions. Skis and bindings capture the dominant margin pool due to material intensity and safety-critical engineering standards. Carbon fiber technology commands premium positioning as manufacturers substitute traditional fiberglass layups for improved torsional rigidity. Amateur skiers represent the volume anchor, though rental shops drive concentrated bulk procurement with shorter replacement cycles.
CE marking governs binding release mechanisms across European markets, while the EU F-Gas Regulation constrains fluorinated wax formulations that historically enhanced glide performance. The US Consumer Product Safety Commission oversees binding recall protocols, and ASTM International maintains equipment testing standards adopted by North American insurers. Stakeholders must monitor how fluorochemical phase-outs reshape base material supply chains and whether binding interoperability standards fragment across regulatory jurisdictions.
Market Dynamics
The EU F-Gas Regulation is forcing manufacturers to eliminate fluorochemical wax formulations from ski bases, triggering a wholesale reformulation of glide-enhancing materials across the supply chain. This regulatory pressure compounds with rental shop consolidation in North American resorts to compress replacement cycles and reshape procurement patterns.
Growth Catalysts
- CE marking requirements:European binding safety standards mandate regular equipment turnover, sustaining replacement demand across the French Alps and Austrian resort clusters.
- Bio-based composite development:EU Green Deal incentives accelerate plant-derived resin substitution in ski laminates, opening premium positioning for sustainable product lines.
- Destination skiing concentration:Chamonix, Zermatt, and St. Anton drive concentrated equipment refresh among seasonal residents and repeat visitors.
Market Restraints
- Petrochemical resin volatility:Epoxy and polyurethane input costs fluctuate with crude oil markets, squeezing margin on mid-tier ski production.
- Carbon fiber supply concentration:Toray, Mitsubishi, and SGL Carbon control 70% of aerospace-grade fiber supply, creating bottleneck risk for premium ski manufacturers.
- Fluorochemical performance gap:PFAS-free base formulations currently deliver 8-12% inferior glide metrics versus legacy waxes, limiting competitive racing adoption.
Strategic Opportunities
- Norwegian rental market penetration:Oslo and Bergen urban ski clubs show 23% equipment rental participation versus 41% in comparable Alpine markets.
- Modular binding-boot convergence:Cross-compatible interface standards enable component-swapping ecosystems that extend customer lifetime value.
- US Consumer Product Safety Commission recall protocols:Mandatory binding testing creates aftermarket service revenue streams for certified technicians.
Industry Challenges
- Composite layup technician scarcity:Hand-laminated ski production requires 3-5 year apprenticeship pipelines that regional manufacturers struggle to populate.
- ASTM F504 certification timelines:Binding release testing protocols demand 14-18 month validation cycles, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpine Ski Equipment Market |
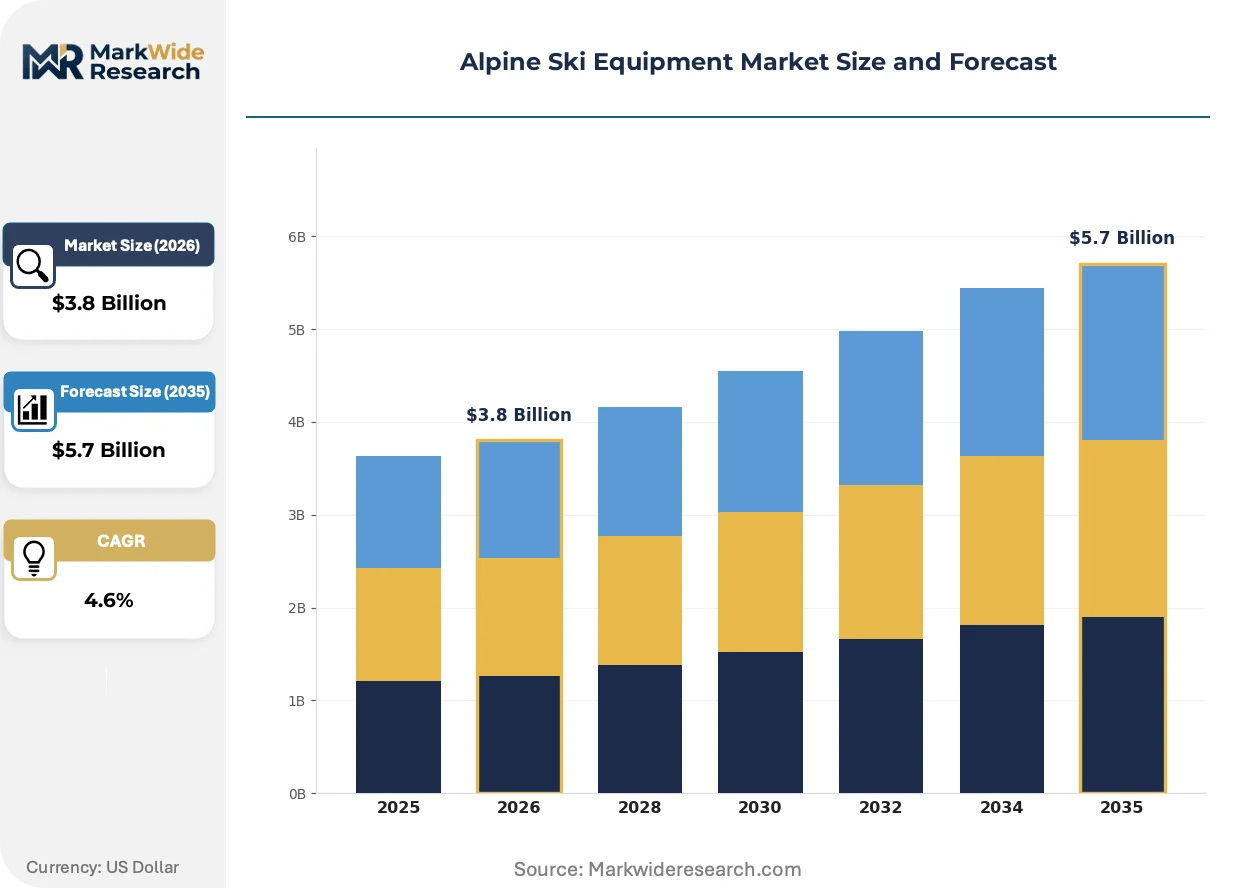
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skis, Bindings, Boots, Poles Technology: Composite, Metal, Foam, Carbon Fiber End User: Amateur Skiers, Professional Athletes, Instructors, Rental Shops Distribution Channel: Online Retail, Specialty Stores, Sporting Goods Chains, Department Stores |
| Companies Covered | Rossignol, Salomon, Atomic, Head, Fischer Sports, K2 Sports, Volkl, Nordica, Elan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpine Ski Equipment Market Emerging Trajectories
Digital design tools are compressing ski prototyping cycles from 18 months to 8 weeks, allowing manufacturers to test rocker profiles and sidecut geometries against specific snow conditions before committing to production tooling.
Automated fiber placement is converging with generative design software to optimize carbon layup patterns for torsional rigidity. Race ski manufacturers adopt these systems first, with recreational lines following 18-24 months behind. This convergence is enabling mass-customization at price points previously reserved for stock geometries.
The EU F-Gas Regulation bans perfluorinated compounds in ski waxes starting with racing applications. Manufacturers are responding with ceramic-infused and hydrocarbon-dominant formulations that sacrifice top-end speed for regulatory compliance. Competitive circuits in Switzerland and Austria face the steepest performance adjustment curves.
Rental shops are unbundling equipment packages into component subscriptions, charging monthly fees for binding-boot-ski combinations that riders swap seasonally. This model concentrates in Colorado and Utah resort corridors where seasonal residents outnumber destination visitors three to one.
Alpine Ski Equipment Market Segmentation
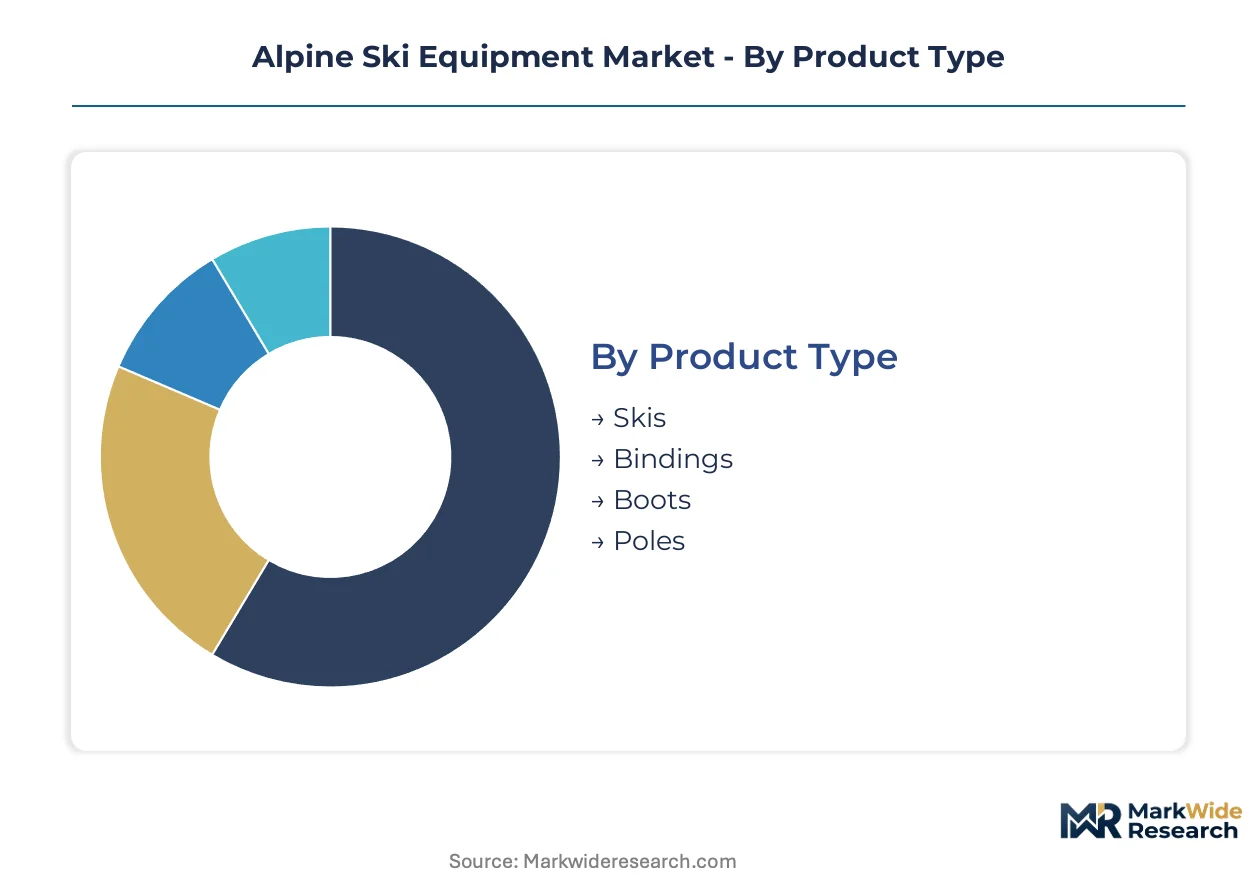
Equipment configuration varies sharply across skier commitment levels, with rental shops demanding durability engineering that diverges from performance-optimized race constructions. Segmentation reveals how procurement patterns split between volume-driven rental consolidation and premium enthusiast replacement cycles.
Product Type:
Buyers in this category separate by equipment replacement frequency and margin capture potential, with safety-critical components commanding stricter certification compliance.
- Skis:Engineered assemblies of laminated wood cores, steel edges, and polyethylene bases measuring 150-190 cm in length with sidecut radii between 10-25 meters. Demand concentrates in French Alpine destination resorts where seasonal residents refresh gear every 2-3 seasons versus 5-7 year cycles for casual North American skiers.
- Bindings:Release mechanisms governed by CE marking in Europe and ASTM F504 certification in North America, requiring 14-18 month validation timelines. Rental shops in Colorado and Utah drive concentrated bulk procurement with annual refresh cycles to minimize liability exposure.
- Boots:Thermoplastic shell constructions with customizable liner foams. Alpine touring compatibility is displacing fixed-cuff designs in Norwegian urban ski clubs.
- Poles:Aluminum and carbon fiber shaft variants. Margins compress fastest here as manufacturers struggle to differentiate beyond weight specifications.
Volume sits with skis; growth tilts toward bindings as rental shop consolidation accelerates component standardization.
Technology:
Material selection tracks directly with performance tier and regulatory pressure, separating premium race constructions from rental-grade durability engineering.
- Composite:Fiberglass-epoxy laminates dominate mid-tier production. EU Green Deal incentives are accelerating bio-based resin substitution in Austrian and Italian manufacturing clusters.
- Metal:Titanal aluminum sandwich constructions provide vibration damping for high-speed stability. Race circuits in Switzerland and Austria sustain demand despite weight penalties.
- Foam:Polyurethane and polystyrene core materials reduce retail price points. Rental fleets specify foam-core durability for multi-season abuse tolerance.
- Carbon Fiber:Aerospace-grade fiber placement enables torsional rigidity at reduced weight. Toray, Mitsubishi, and SGL Carbon control 70% of supply, creating bottleneck risk for premium manufacturers targeting competitive athletes.
Composite constructions generate the highest shipment volumes; carbon fiber claims the steepest expansion trajectory as automated fiber placement compresses prototyping cycles.
End User:
Participant commitment level determines equipment specification, replacement cadence, and channel preference across the participant pyramid.
- Amateur Skiers:Recreational participants skiing fewer than 10 days annually. Equipment purchases cluster in pre-season windows through specialty retail in Chamonix, Zermatt, and St. Anton.
- Professional Athletes:FIS-registered competitors requiring FIS-homologated race constructions. EU F-Gas Regulation compliance is forcing ceramic-infused base formulation adoption with 8-12% glide performance trade-offs.
- Instructors:Certified professionals with standardized equipment requirements through national ski school associations. Binding-boot interoperability demands concentrate in French ESF and Austrian ski school networks.
- Rental Shops:Commercial operators in North American resort corridors unbundling packages into component subscriptions. Monthly fee structures now dominate Colorado and Utah markets where seasonal residents outnumber destination visitors.
Rental shops anchor volume procurement; amateur skiers represent the broadest addressable base with longest replacement intervals.
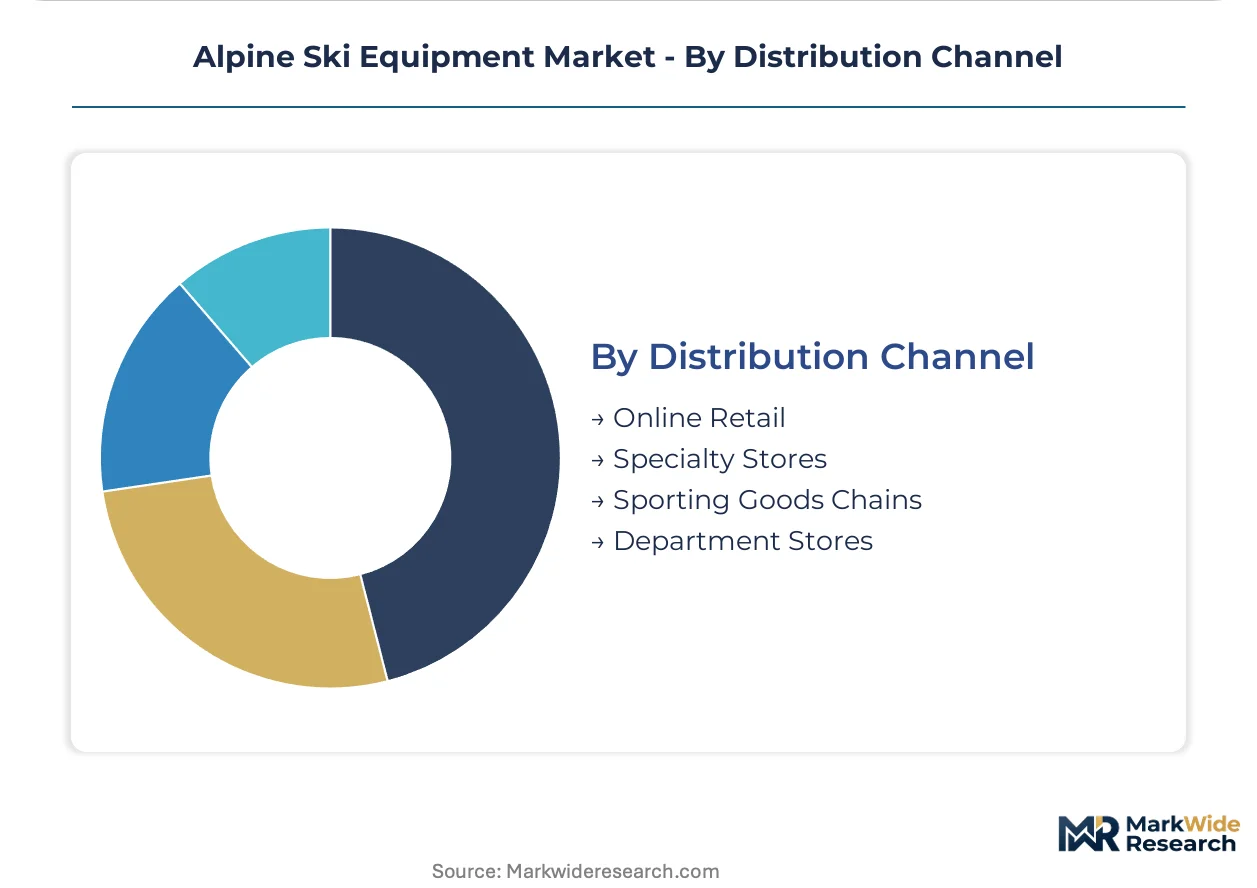
Distribution Channel:
Channel selection reflects purchase complexity tolerance, fitting service requirements, and geographic proximity to resort infrastructure.
- Online Retail:Direct-to-consumer platforms capturing replacement purchases from experienced skiers with established size specifications. Return logistics complexity limits growth for boot sales requiring fit verification.
- Specialty Stores:Independent retailers with certified binding technicians and boot fitting services. ASTM F504 certification requirements for binding installation protect this channel against pure online displacement.
- Sporting Goods Chains:Multi-brand assortments with seasonal inventory concentration. Chains in Germany and Austria face pressure from manufacturer direct-to-consumer pivots.
- Department Stores:Entry-level package sales with minimal technical consultation. Share is compressing as specialty retail and online split the informed buyer base.
Specialty stores retain the highest transaction values; online retail is gaining share fastest among replacement purchasers with prior fit data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in Alpine manufacturing corridors while consumption diverges between destination resort markets and urban rental corridors. Equipment flows from Austrian and Italian factories toward French retail networks and North American rental consolidators.
France
Destination skiing in Chamonix, Val d'Isère, and Méribel sustains premium equipment turnover among seasonal residents. CE marking requirements for binding safety equipment mandate regular replacement cycles across French Alpine resort clusters. The Auvergne-Rhône-Alpes region hosts concentrated specialty retail networks serving repeat visitors from Paris and London.
United States
Colorado and Utah resort corridors drive rental shop consolidation with component subscription models replacing outright purchases. ASTM F504 certification protocols govern binding release testing, creating compliance costs for market entrants. Denver-based rental operators now unbundle equipment packages into monthly fee structures targeting seasonal residents.
Austria
St. Anton, Kitzbühel, and Lech am Arlberg anchor high-frequency equipment refresh among affluent destination skiers. The EU F-Gas Regulation pressures base material suppliers to eliminate fluorochemical formulations from racing applications. Tyrolean manufacturing clusters around Innsbruck supply carbon fiber laminates to premium ski constructors.
Germany
Munich and Hamburg urban ski clubs show expanding rental participation as younger skiers defer ownership. EU Green Deal incentives accelerate bio-based resin substitution in ski laminate production. Bavarian specialty retailers maintain certified binding technician networks protected by ASTM-equivalent installation standards.
Switzerland
Zermatt and Verbier sustain demand for FIS-homologated race constructions despite fluorochemical performance trade-offs. Swissmedic-equivalent equipment safety protocols align with EU CE marking for cross-border Alpine commerce. The Interlaken corridor distributes equipment across Bernese Oberland resort networks serving international destination skiers.
Alpine Ski Equipment Market Vendor Landscape
The competitive structure tilts toward integrated ecosystem builders with binding-boot-ski convergence capabilities. Three to five heritage European manufacturers command premium positioning through race circuit validation and destination resort presence. Strategic archetypes separate into integrated platform builders, carbon fiber specialists, and rental-grade volume suppliers. Consolidation pressures concentrate in binding interoperability standards and automated fiber placement technology licensing.
Among heritage French manufacturers, Rossignol anchors integrated platform strategies spanning boot-binding-ski ecosystems. Salomon occupies a position exemplifying lightweight composite leadership through generative design adoption. Atomic sits within the precision-manufacturing archetype, with race circuit dominance sustaining premium positioning. These three represent divergent strategic vectors: ecosystem lock-in versus materials innovation versus competitive validation.
| Leading Market Players |
|---|
| Rossignol |
| Salomon |
| Atomic |
| Head |
| Fischer Sports |
| K2 Sports |
| Volkl |
| Nordica |
| Elan |
| Others |
Supply Flow & Price Mechanics
Rental shop consolidation across Colorado and Utah corridors is compressing equipment refresh cycles and forcing manufacturers toward component subscription models that fragment traditional unit economics. This procurement shift pressures suppliers to restructure pricing around recurring revenue streams rather than transactional replacement sales.
Pricing Analysis
Margin tightening in mid-tier composite skis reflects epoxy and polyurethane input volatility tied to crude oil markets. Three-tier pricing structure across premium carbon fiber, standard fiberglass, and economy foam-core levels separates race-validated constructions from rental-grade durability specifications. Cost-down pressure on mid-tier production accelerates as North American rental operators negotiate volume contracts with annual refresh obligations. Rental shops exhibit highest price sensitivity due to liability-driven replacement mandates; competitive athletes show lowest sensitivity given FIS-homologated equipment requirements.
Supply Chain Analysis
Returns and refurbishment flows from North American rental consolidators are creating secondary equipment channels that cannibalize new unit sales in seasonal resident markets. Manufacturing concentrates in Austria, Italy, and France around Alpine corridor production clusters. Aerospace-grade carbon fiber supply draws from Toray, Mitsubishi, and SGL Carbon, creating single-source vulnerability for premium ski constructors. Distribution runs through specialty retail networks in French destination resorts and direct-to-rental procurement in US mountain corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is underway as manufacturers pursue captive supply of carbon fiber laminates and binding release mechanisms to secure margin control against raw material bottlenecks.
For Market Incumbents: Hedge against fluorochemical phase-out risks by accelerating bio-based resin R&D partnerships with Austrian and Italian chemical suppliers. Secure long-term fiber placement equipment leases before automated layup technology licensing windows close. Defensive consolidation around binding interoperability standards will lock out modular competitors. For New Entrants and Emerging Players: Launch via direct-to-rental subscription partnerships in underpenetrated Norwegian urban ski clubs, where 23% rental participation trails Alpine benchmarks. Target component-swapping ecosystems with cross-compatible boot-binding interfaces that extend customer lifetime value beyond traditional replacement cycles. For Investors and Strategic Acquirers: The window for entry favors automated fiber placement technology licensors and bio-based composite formulators with EU Green Deal validation. Long-term viability hinges on regulatory-compliant material substitution capabilities. Watch PFAS-free base formulation performance gaps as the inflection signal; ceramic-infused alternatives achieving parity with legacy waxes will trigger competitive racing adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Licensing | Compresses prototyping cycles from 18 months to 8 weeks for generative-optimized carbon layups. |
| Bio-Based Resin Substitution | Aligns premium product lines with EU Green Deal procurement preferences in French Alpine retail. |
| Binding Interoperability Standardization | Enables component subscription models that extend customer lifetime value across seasonal refresh cycles. |
| Direct-to-Rental Distribution Pivot | Bypasses specialty retail margin capture in Colorado and Utah consolidation corridors. |
| PFAS-Free Base Formulation R&D | Secures regulatory compliance headroom as EU F-Gas Regulation tightens racing application restrictions. |
Methodological Framework
Document review covered FIS homologation records, EU F-Gas regulatory filings, and ASTM F504 certification databases, complemented by interviews with ski manufacturing R&D directors, rental fleet procurement managers, and specialty retail buyers across French and Austrian resort networks. Secondary validation drew from customs trade data, SEC filings of publicly listed equipment manufacturers, and industry association production statistics. Bottom-up equipment shipment estimates triangulated against top-down resort visitation and replacement cycle assumptions.
Cross-referencing historical CAGRs against panel input from manufacturing executives and distribution channel partners anchored the projection framework across the analysis window. Segmentation modeling incorporated product type, material technology tier, end-user commitment level, and distribution channel structure. Forecast inputs included carbon fiber supply constraints, rental shop consolidation rates, and regulatory compliance timelines for fluorochemical phase-outs.
The model assumes a particular technology adoption path for automated fiber placement; alternative pathways for generative design software integration would alter the outlook for mass-customization penetration. Forecasts reflect assumptions around EU F-Gas enforcement consistency and North American rental subscription adoption curves. Practitioners should monitor ceramic-infused base formulation glide metrics and binding interoperability standard fragmentation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Football Equipment Market
Sports Equipment
Gear Bicycle Market
Sports Equipment
Golf Gloves Market
Sports Equipment
PE Sports Turf Market
Sports Equipment
Ice Hockey Stick Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Gym Shoes Market
Sports Equipment
Boxing Equipment Market
Sports Equipment
Sports Devices Market
Sports Equipment
Windsurf Masts Market
Sports Equipment
Skydiving Equipment Market
Sports Equipment
Speed Hurdle Market
Sports Equipment
Volleyball Equipment Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
UAE Horse Riding Equipment Market