
 Riding Gear Market | 2026-2036
Riding Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Riding Gear Market Analytics
CE marking under the EU PPE Regulation is shifting the cost-of-entry calculus for riding gear manufacturers seeking European market access. Alpinestars leverages its vertically integrated manufacturing in Italy to sustain compliance without outsourcing certification steps. KLIM anchors its premium positioning through R&D intensity in breathable membrane technology for extreme-condition riders. Troy Lee Designs competes on graphic customization and motocross-specific fit profiles that differentiate it from road-racing specialists.
Riding gear encompasses protective apparel and equipment designed to absorb impact, resist abrasion, and shield against environmental exposure during motorized and non-motorized vehicle operation, typically constructed with reinforced stitching, CE-rated armor inserts, and multi-layer textile or leather assemblies. Its primary commercial purpose centers on reducing injury severity across recreational, professional, and commuter use cases. Helmets occupy the largest value pool due to mandatory-wear laws across most jurisdictions, while carbon fiber material grades command premium pricing in professional racing segments where weight reduction directly affects performance outcomes. Motorcycle Riders represent the dominant end-user category, though waterproof-featured gear is gaining traction among urban commuters facing unpredictable weather patterns.
FDA oversight applies to antimicrobial liner treatments in helmet interiors, while ECE 22.06 helmet standards govern type-approval across European markets and directly shape product development timelines for manufacturers. The EU AI Act introduces emerging compliance considerations for smart helmets integrating heads-up displays and crash-detection sensors. Stakeholders must monitor how evolving PPE certification timelines interact with connected-technology integration roadmaps to avoid stranded development investments.
Market Dynamics
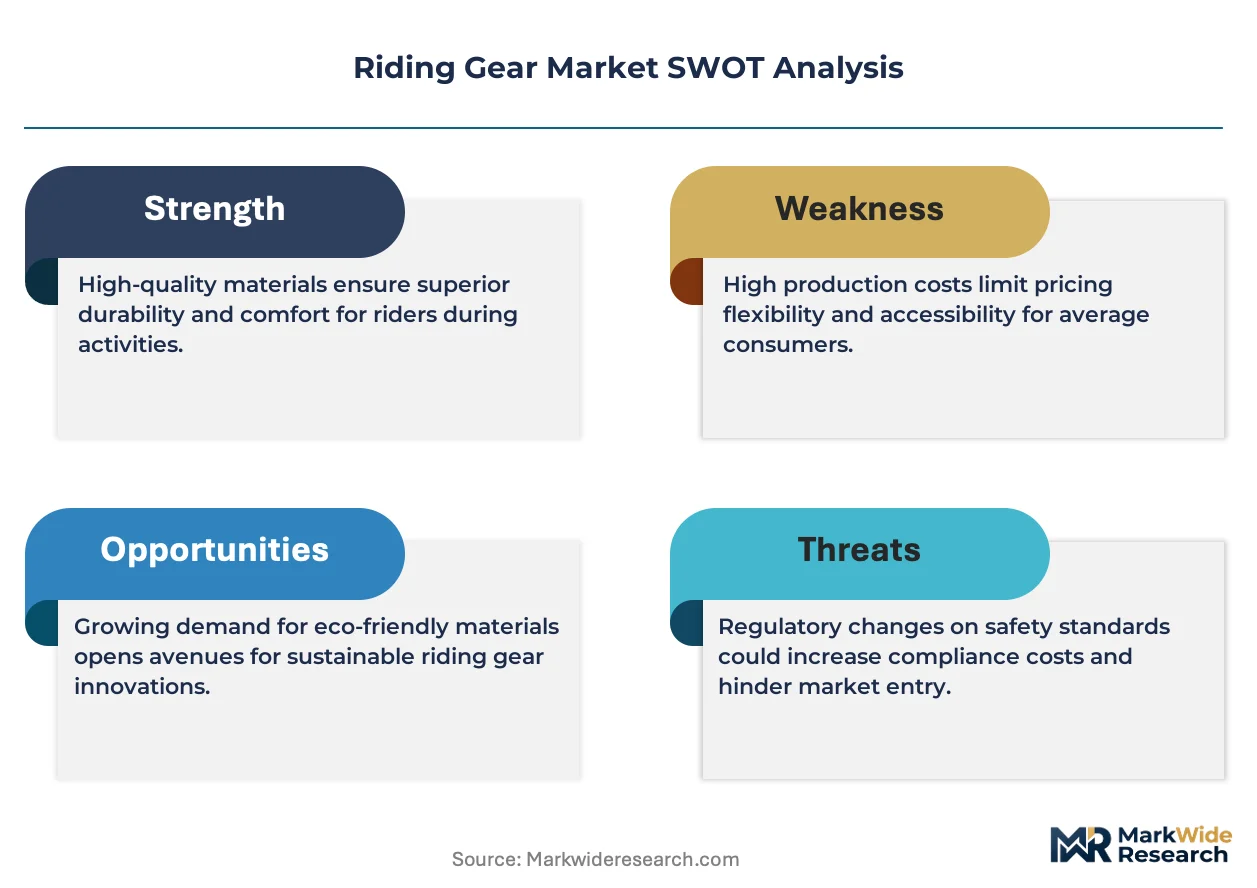
The Riding Gear Market is undergoing structural compression as CE marking requirements under the EU PPE Regulation force consolidation among smaller manufacturers unable to absorb certification costs, while urban motorcycle commuting in Southeast Asia accelerates volume demand.
Growth Catalysts
- Urban congestion in Jakarta and Bangkok:Motorcycle commuting hours have doubled in these metropolitan areas, pushing riders toward protective gear as daily necessity rather than recreational accessory.
- ECE 22.06 helmet standards:European type-approval mandates are upgrading replacement cycles as older inventory phases out, creating forced refresh demand across EU member states.
- Carbon fiber manufacturing scale:Automated layup processes are reducing per-unit material costs, enabling premium protection tiers to penetrate mid-market price points previously served by fiberglass composites.
Market Restraints
- Kevlar and aramid fiber price volatility:Petrochemical feedstock fluctuations and aerospace sector competition for high-tenacity yarns are squeezing margin structures for abrasion-resistant textile producers.
- Italian and Portuguese leather tanning concentration:Premium hide processing clusters in these two countries create geographic single-point vulnerability for full-grain leather jacket supply chains.
- CE PPE certification timeline friction:New entrant manufacturers face 12-18 month approval windows that lock working capital in pre-revenue inventory positions.
Strategic Opportunities
- India's two-wheeler safety awareness campaigns:State-level helmet mandates in Maharashtra and Karnataka are creating first-time buyer populations in tier-2 and tier-3 cities previously served by unorganized roadside vendors.
- Smart helmet HUD integration:Convergence of miniaturized display optics with crash-detection telemetry is opening premium price tiers for connected rider ecosystems.
- Direct-to-rider subscription models:Gear rental and seasonal exchange programs are penetrating European urban commuter segments where storage constraints and multi-season versatility drive preference.
Industry Challenges
- Pattern-making talent scarcity:Motocross and road-racing fit engineering requires specialized anthropometric knowledge that aging European ateliers struggle to replenish.
- Multi-standard inventory complexity:Simultaneous ECE, DOT, and Snell certification requirements force SKU proliferation that strains forecasting accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Riding Gear Market |
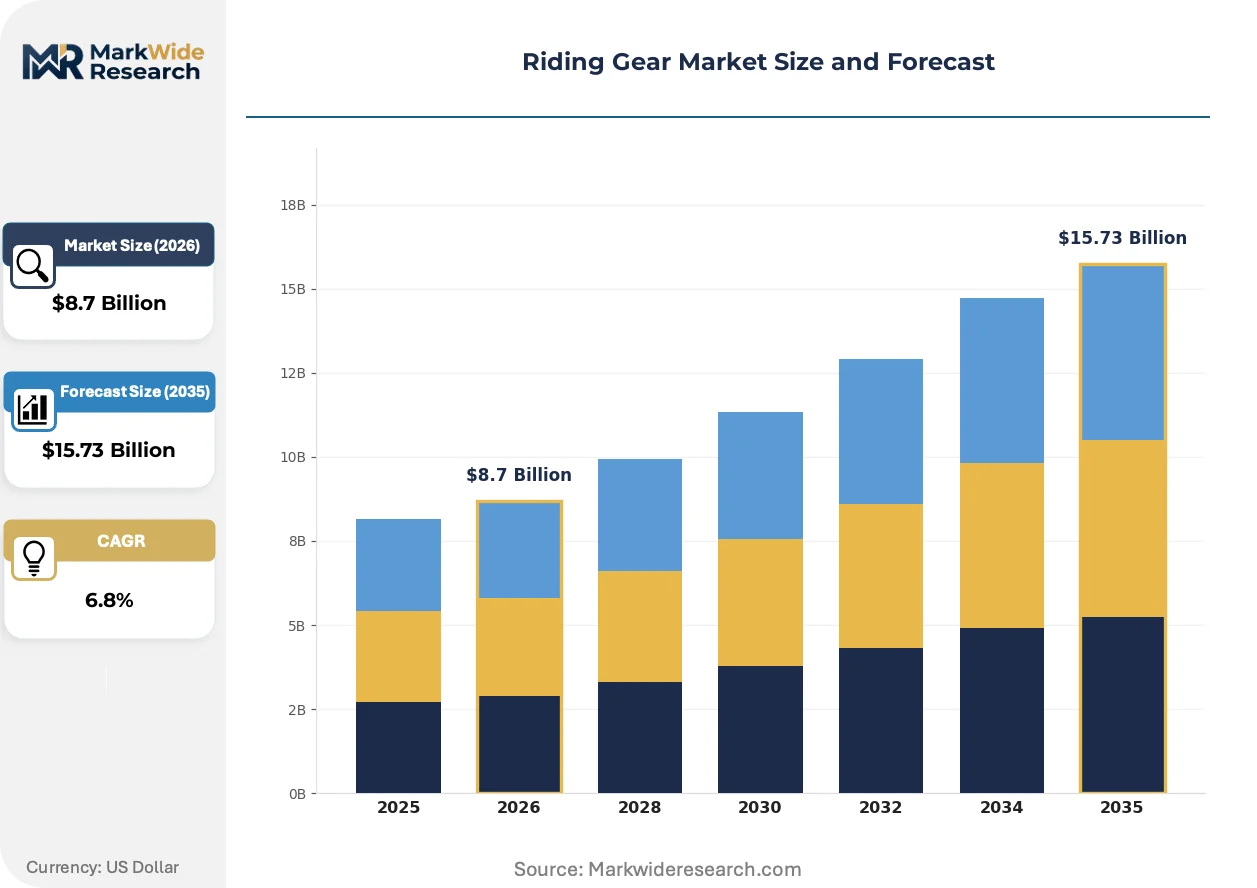
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmets, Jackets, Pants, Gloves Material: Leather, Textile, Carbon Fiber, Polyester End User: Motorcycle Riders, Equestrian, ATV Enthusiasts, Dirt Bikers Feature: Waterproof, Breathable, Lightweight, Reflective |
| Companies Covered | Alpinestars, Arai, KLIM, Sidi, Held, Troy Lee Designs, Schuberth, Fly Racing, Scorpion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Riding Gear Market Evolving Landscape
Material science advances and regulatory tightening are compressing product development cycles while fragmenting competitive positioning between heritage leather houses and technical textile specialists.
Multi-layer laminated membranes with active moisture transport are overtaking traditional waxed cotton and basic polyurethane coatings in commuter-oriented jackets. Urban riders in Northern European cities with unpredictable precipitation patterns are adopting these breathable assemblies at rates that outpace historical waterproof gear replacement cycles. The shift is overtaking established price-performance hierarchies and forcing mid-tier manufacturers to source membrane licenses or exit the weatherproof category entirely.
The EU AI Act is introducing conformity assessment obligations for helmets integrating heads-up displays, biometric sensors, and automated emergency notification systems. Manufacturers must now navigate overlapping PPE and AI system compliance pathways that extend development timelines and require specialized legal expertise. Racing-oriented product lines with integrated telemetry are experiencing the most acute certification bottlenecks as notified bodies develop interpretive guidance.
Riders are consolidating purchase decisions around certification-grade transparency rather than brand heritage or aesthetic differentiation. Specialty retailers in Germany and France are responding by unbundling after-sales fitting services from product margins, shifting toward consultation fees and custom alteration revenue. This behavioral pivot is most pronounced among touring motorcyclists aged 35-50 who prioritize documented protection ratings over discretionary design elements.
Riding Gear Market Segmentation
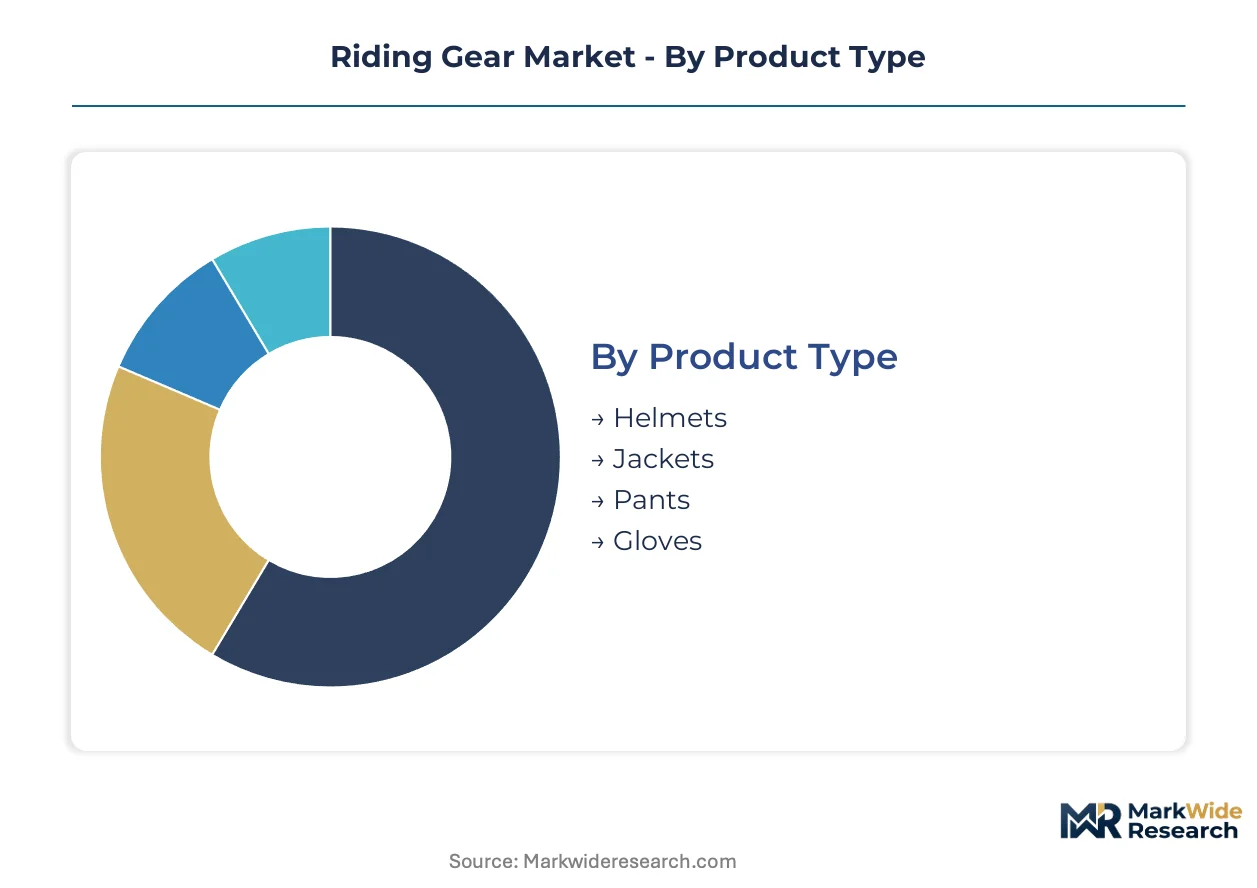
Segmentation in riding gear reveals divergent upgrade cycles across protective categories, with replacement timelines stretching from mandatory helmet refresh intervals to discretionary jacket purchases. Understanding these cadences shapes inventory planning and margin capture strategies for manufacturers serving distinct rider psychographics.
Product Type:
Replacement-cycle dynamics vary sharply across protective categories, with regulatory mandates forcing predictable refresh intervals on some items while others follow wear-based or fashion-driven schedules.
- Helmets:Polycarbonate and composite shell assemblies with EPS impact liners require replacement every 3-5 years due to material degradation, with ECE 22.06 and DOT recertification deadlines in Germany and the United States compressing effective usage windows. Volume concentrates among urban commuters in Jakarta and Bangkok where mandatory-wear enforcement has tightened; premium carbon fiber grades climb fastest among track-day enthusiasts seeking weight reduction.
- Jackets:Multi-layer textile or leather constructions with CE-rated armor inserts and abrasion-resistant panels serve as the primary discretionary purchase, with seasonal fashion cycles and crash damage driving replacement. Demand clusters in Northern European cities with unpredictable precipitation patterns; breathable membrane integration represents the fastest technology shift.
- Pants:Reinforced denim or leather assemblies with hip and knee armor pockets complete lower-body protection sets, typically purchased as jacket companions or standalone commuter necessities. Adoption accelerates among motorcycle taxi operators in Maharashtra and Karnataka where state-level safety mandates have expanded beyond helmets.
- Gloves:Short-cuff urban designs and gauntlet touring configurations with knuckle protection and palm sliders experience fastest wear-based replacement due to contact abrasion and seam stress. Volume placements concentrate in entry-level synthetic leather; technical kangaroo-hide racing gloves gain share fastest among sportbike segments.
Volume placements concentrate in Helmets; the faster expansion belongs to Jackets with membrane technology integration.
Material:
Cost-tier positioning separates heritage material suppliers from technical textile innovators, with raw material sourcing geography directly shaping margin structures and certification pathways.
- Leather:Full-grain cowhide and kangaroo constructions processed through Italian and Portuguese tanning clusters deliver abrasion resistance benchmarks for racing and premium touring segments. Supply vulnerability concentrates in these two countries; exotic hide alternatives expand fastest among vegan-conscious urban commuters.
- Textile:High-tenacity nylon and aramid woven assemblies with laminated waterproof membranes dominate mid-market commuter positioning through versatility across weather conditions. Demand clusters in Germany and France where multi-season utility drives preference; Cordura and similar branded fibers gain specification fastest.
- Carbon Fiber:Autoclave-cured composite shells and weave patterns deliver maximum strength-to-weight ratios for professional racing helmets and protective inserts. Premium penetration accelerates as automated layup reduces per-unit costs; track-day adoption in the United States and Japan climbs steepest.
- Polyester:Basic woven and mesh constructions serve entry-level price points with limited abrasion resistance, common in warm-climate commuter gloves and budget jacket liners. Volume concentrates in Southeast Asian markets; reflective thread integration represents the fastest feature addition.
Volume placements concentrate in Textile; the steepest expansion trajectory belongs to Carbon Fiber as manufacturing scale economics improve.
End User:
Application-specific anthropometrics and crash kinematics force distinct pattern-making disciplines, with each user category demanding specialized fit engineering and protection zone prioritization.
- Motorcycle Riders:Road-racing, touring, and urban commuter subsegments with distinct posture requirements—tucked, upright, or neutral—drive the largest addressable demand pool. Dominance is absolute across all major markets; electric motorcycle adoption in India and Vietnam creates fastest-growing subsegment.
- Equestrian:Helmet designs with broader coverage and flexible visor attachments address fall patterns distinct from motorized impact, with velvet-covered show helmets and vented cross-country configurations serving separate use cases. Demand concentrates in the United Kingdom and Germany; back protector integration climbs fastest.
- ATV Enthusiasts:Four-wheel off-road operators face rollover and collision risks requiring chest protectors and full-face helmets with enhanced ventilation for low-speed technical riding. Adoption clusters in rural United States and Australian territories; youth sizing represents fastest-expanding category.
- Dirt Bikers:Motocross and enduro specialists demand lightweight, maximum-ventilation gear with roost deflection and roost protection prioritized over weather sealing. Volume concentrates in California and Florida riding zones; knee brace compatibility in pant design gains specification fastest.
Volume placements concentrate in Motorcycle Riders; the fastest climb belongs to Dirt Bikers as motocross participation surges in Western United States markets.
Feature:
Customer-type differentiation separates weather-utility seekers from performance purists, with feature bundling strategies determining price-band placement and retail channel selection.
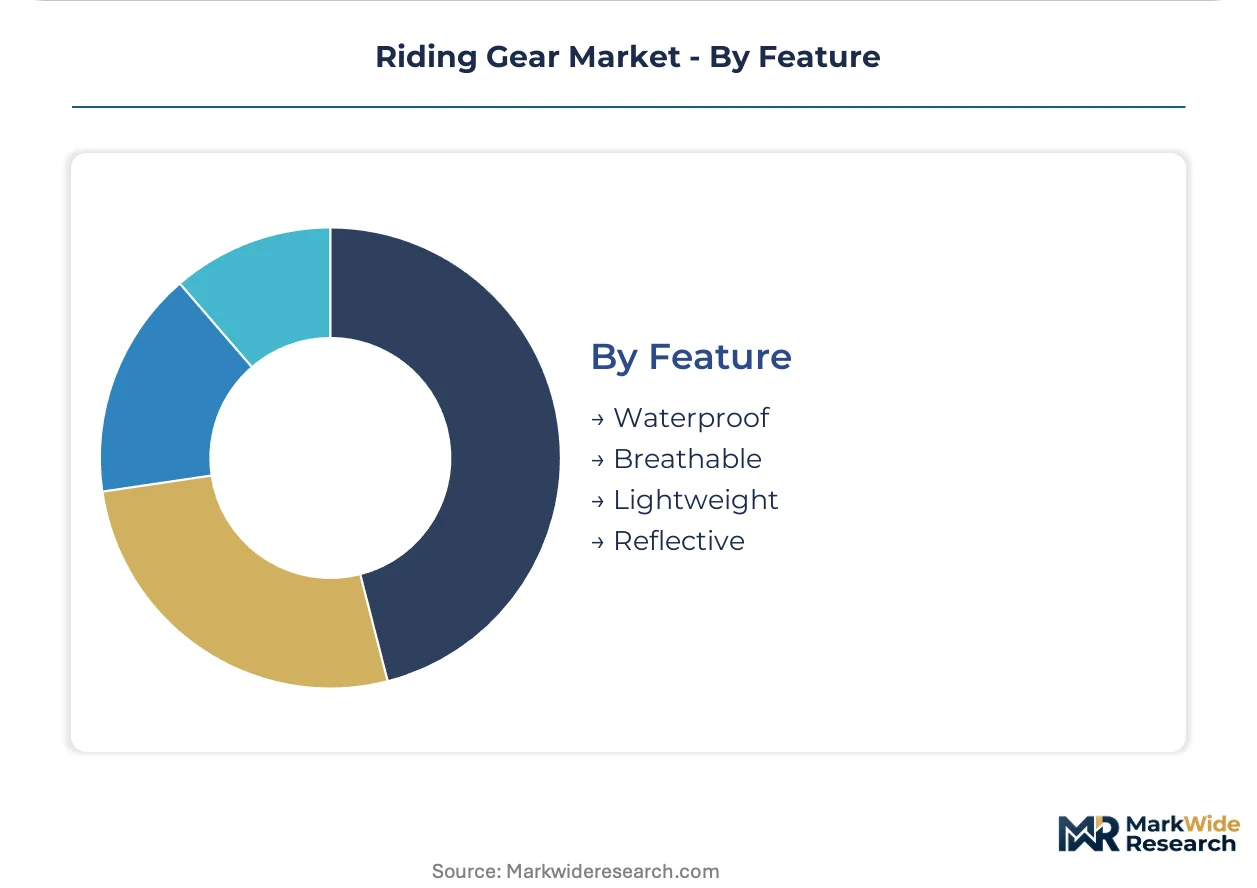
- Waterproof:Laminated membrane or coated fabric constructions with sealed seams and water-resistant zippers address commuter necessity in precipitation-prone climates. Demand concentrates in Northern European cities; breathable waterproof combinations displace basic coated alternatives fastest.
- Breathable:Active moisture transport through hydrophilic membrane layers or mesh ventilation panels prevents heat buildup during exertion, critical for touring and adventure riding. Adoption accelerates among long-distance riders in Australia and South Africa; pit-zip ventilation designs gain preference fastest.
- Lightweight:Material minimization and armor reduction for hot-climate comfort or competition weight savings, achieved through advanced textiles and selective protection zone coverage. Preference clusters in Southeast Asian urban commuting and professional racing; gram-counting specification spreads fastest.
- Reflective:High-visibility tape, piping, and panel treatments enhancing conspicuity in low-light conditions, often integrated as removable or permanently bonded elements. Mandate-driven adoption strengthens in France and Belgium where daytime visibility requirements exist; integrated LED systems gain traction fastest.
Volume placements concentrate in Waterproof; the fastest expansion belongs to Breathable as adventure-touring participation broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the fastest volume expansion as two-wheeler ownership and state-level helmet mandates reshape commuter behavior. Southeast Asian urban corridors and European regulatory upgrade cycles anchor complementary demand poles across the forecast window.
India
Maharashtra and Karnataka state helmet mandates are converting unorganized roadside vendors into certified gear purchasers across tier-2 and tier-3 cities. The Ministry of Road Transport and Highways enforces stricter BIS certification timelines for protective headgear. Manufacturing clusters in Gurgaon and Pune are scaling polycarbonate shell production to serve domestic replacement cycles.
Germany
ECE 22.06 recertification deadlines are compressing effective helmet usage windows and forcing inventory refresh across Bavaria and North Rhine-Westphalia. The KBA administers type-approval protocols that directly shape product development timelines for notified bodies. Stuttgart-based engineering consultancies are specializing in dual PPE-AI Act compliance for connected helmet architectures.
United States
Track-day participation in California and Florida is accelerating carbon fiber helmet adoption among weight-sensitive performance riders. The NHTSA maintains DOT certification as baseline market access while Snell standards anchor premium positioning. Arizona and Texas distribution hubs are consolidating direct-to-rider subscription logistics for seasonal gear exchange programs.
Indonesia
Jakarta metropolitan motorcycle commuting hours have doubled since 2019, elevating protective gear from recreational accessory to daily necessity. The National Standardization Agency enforces SNI helmet marking that phases out uncertified imports. Surabaya and Bandung assembly plants are expanding textile jacket capacity for tropical climate ventilation requirements.
Italy
Heritage leather tanning clusters in Tuscany and Veneto sustain premium abrasion-resistance benchmarks for racing and touring segments. CE marking under the EU PPE Regulation elevates certification costs that favor vertically integrated domestic producers. Alpinestars anchors its manufacturing footprint in Asolo to control compliance workflows without outsourcing certification steps.
Riding Gear Market Competitive Landscape
Italian producers anchor the premium heritage tier; American technical specialists hold the innovation-driven mid-market. The vendor base splits between consolidated leather houses with captive tanning supply and fragmented textile assemblers sourcing membrane licenses. Three archetypes dominate: vertically integrated European heritage brands, R&D-intensive membrane technology developers, and graphic-focused motocross specialists. Competitive moves concentrate on backward integration into raw material processing and strategic partnerships with notified bodies for accelerated certification timelines.
Within the heritage tier, Alpinestars and Sidi exemplify vertically integrated positioning through Italian manufacturing footprints that sustain CE compliance control. Among technical specialists, KLIM occupies a position defined by membrane R&D intensity for extreme-condition applications. Troy Lee Designs sits within the graphic customization archetype, differentiating through motocross-specific fit profiles rather than road-racing engineering. These three anchors represent the strategic spectrum: European integration, American technical innovation, and niche design specialization.
| Leading Market Players |
|---|
| Alpinestars |
| Arai |
| KLIM |
| Sidi |
| Held |
| Troy Lee Designs |
| Schuberth |
| Fly Racing |
| Scorpion |
| Others |
Value Network & Pricing Analysis
Mandatory ECE 22.06 recertification deadlines across Germany and France are compressing effective helmet usage windows and forcing inventory refresh cycles that strain polycarbonate shell suppliers. This specification-driven demand surge is reshaping procurement patterns as manufacturers race to secure certified EPS liner capacity before peak replacement seasons.
Pricing Analysis
Volume placements concentrate in entry-level polycarbonate helmets where thin margins resist input cost pass-through, while carbon fiber racing tiers retain pricing power through gram-counting specification and track-day prestige. Three-tier pricing structure across premium, standard, and economy levels separates CE-rated membrane jackets from basic coated alternatives, with certification grade as the primary price differentiation driver. Cost compression in mid-market textile segments is intensifying because aramid fiber price volatility squeezes producers unable to hedge petrochemical feedstock exposure. Urban commuters in Southeast Asia exhibit highest price sensitivity, while professional racing teams demonstrate lowest elasticity due to performance-weight tradeoff requirements.
Supply Chain Analysis
Dual-sourcing requirements from European notified bodies mandate that manufacturers qualify multiple EPS liner suppliers and membrane licensees to mitigate single-point certification failure risk. Geographic supply concentration centers on Italy and Portugal for full-grain leather tanning, Taiwan and South Korea for carbon fiber pre-preg, and China for polycarbonate shell molding. Raw material dependencies draw from petrochemical derivatives for aramid yarns, bovine hides from Brazilian and Argentinian ranching clusters, and rare earth elements for helmet visor optical coatings. Tariff exposure on Chinese-molded polycarbonate shells creates margin vulnerability for budget-tier assemblers. Distribution runs through specialty motorsport retailers in Germany and France, direct-to-rider subscription platforms in Arizona and Texas, and roadside vendor networks across Maharashtra and Karnataka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Riding Gear Market sits at a technology-transition inflection as breathable laminated membranes displace waxed cotton and basic polyurethane coatings in commuter-oriented jackets. Smart helmet architectures integrating heads-up displays and crash-detection telemetry are displacing passive protection as the next value-capture frontier.
For Market Incumbents: Cement certification-grade transparency as the primary competitive moat by accelerating dual PPE-AI Act compliance workflows before notified body bottlenecks intensify. Deepen upstream control over Italian tanning clusters and Portuguese hide processing to defend against exotic material substitution threats from vegan-conscious urban commuters. Prioritize R&D investment in miniaturized display optics to capture premium positioning in connected rider ecosystems. For New Entrants and Emerging Players: Motorcycle taxi operators in Maharashtra and Karnataka represent an underserved buyer archetype with expanding state-level safety mandates beyond helmet requirements. White-space targets include tier-2 and tier-3 Indian cities converting from unorganized roadside vendors to certified gear purchasers, and European urban commuters seeking seasonal gear exchange programs due to storage constraints. A direct-to-rider subscription go-to-market angle bypasses established specialty retail channel gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with membrane technology developers given convergence of adventure-touring participation expansion and active moisture transport specification. Long-term viability over a five-to-ten year window favors R&D-intensive technical specialists with captive intellectual property in breathable laminates rather than heritage leather houses dependent on geographic supply concentration. The signal to watch is ECE 22.06 recertification deadline acceleration compressing replacement cycles and elevating working capital intensity for inventory-heavy assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| CE PPE-AI Act Dual Certification | Stuttgart-based engineering consultancies specialize in overlapping compliance pathways for connected helmet architectures. |
| Membrane Technology Licensing | KLIM anchors premium positioning through R&D intensity in breathable laminates for extreme-condition riders. |
| Direct-to-Rider Subscription Launch | Arizona and Texas distribution hubs consolidate logistics for seasonal gear exchange programs targeting storage-constrained urban commuters. |
| Backward Integration into Tanning | Alpinestars sustains compliance control through vertically integrated Italian manufacturing footprints in Asolo. |
| Smart Helmet Platform Integration | EU AI Act conformity assessment obligations extend development timelines for heads-up display and biometric sensor integration. |
Research Methodology
Document review covered ECE 22.06 type-approval protocols, BIS certification timelines, and SNI helmet marking regulations, complemented by interviews with product development directors at Italian heritage manufacturers, regulatory affairs leads at notified bodies, procurement managers at German specialty retailers, and pattern-making engineers at Portuguese tanning clusters. Secondary validation drew from KBA administration records, Ministry of Road Transport and Highways enforcement data, and National Standardization Agency import phase-out schedules. Bottom-up unit economics triangulated against top-down market sizing across helmet, jacket, pant, and glove categories.
Cross-referencing historical replacement cycle data against panel input from distribution channel partners shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade, end-user application, and feature bundling strategy. CAGRs were derived from demand elasticity estimates and regulatory mandate acceleration curves. Industry-specific forecast inputs encompassed state-level helmet mandate expansion timelines in India and carbon fiber automated layup cost reduction trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aramid fiber petrochemical feedstock volatility and CE PPE certification timeline friction. A model refresh is warranted upon material change in ECE 22.06 recertification deadline enforcement or EU AI Act interpretive guidance from notified bodies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Sports Sunglasses Market
Sports Equipment
Winter Sports Equipment Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Dirt Bike Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Waist Support Belt Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Kids Sports Equipment and Accessories Market
Sports Equipment
Sports Equipment Market
Sports Equipment
Europe Kickboxing Equipment Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
Global Weighted Hula Hoop Market
Sports Equipment
Global Pickleball Equipment Market
Sports Equipment
Speed Hurdle Market
Sports Equipment
Ice Hockey Equipment Market