
 Global Kinesio Tape Market | 2026-2036
Global Kinesio Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Global Kinesio Tape Market Foresight
Hospital procurement departments is collapsing into physiotherapist-led purchasing as clinical users gain direct buying authority over consumable rehabilitation supplies. KT Health LLC leverages its brand recognition among athletic trainers to sustain premium positioning in direct-to-practitioner channels. RockTape competes through event sponsorships and education-centric marketing that dominates CrossFit and functional fitness segments. Nitto Denko Corporation anchors industrial-scale manufacturing capacity for medical-grade adhesives that supply multiple tape converters worldwide.
Kinesio tape comprises a cotton or synthetic fiber substrate coated with a hypoallergenic acrylic adhesive engineered to permit longitudinal stretch of 40-60% while restricting lateral deformation, enabling lifting of the epidermis to promote lymphatic flow and proprioceptive feedback during movement. Elastic tape holds the largest revenue share due to its versatility across sports medicine and post-surgical rehabilitation protocols, while pre-cut tape configurations represent the fastest-growing product format as clinics prioritize application efficiency and reduced staff training time. Pain management applications command concentrated margin pools owing to chronic condition patient volumes and repeat purchase frequency, though sports injury prevention generates higher absolute unit demand from institutional buyers.
FDA regulates kinesio tape marketed with therapeutic claims as Class I medical devices requiring adherence to quality system regulations, while the EU MDR imposes stricter clinical evidence requirements for adhesive tapes bearing CE marks under expanded medical device definitions. ISO 10993 biocompatibility testing standards govern cytotoxicity and skin sensitization protocols that manufacturers must document for regulatory submissions across multiple jurisdictions. Stakeholders should monitor evolving MDR notified body capacity constraints and FDA enforcement discretion policies that could reshape market access timelines for emerging tape formulations.
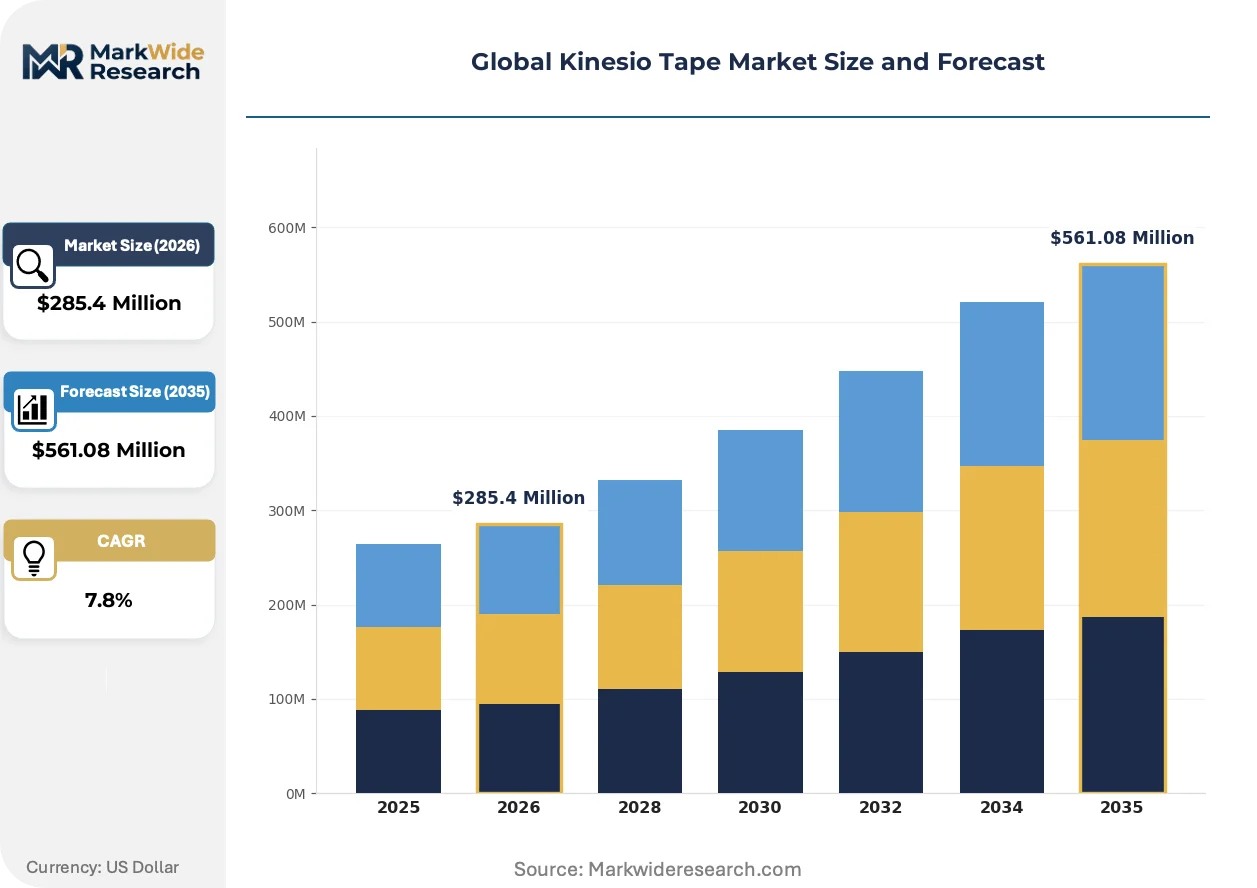
Market Dynamics
The EU Medical Device Regulation (MDR) reclassification of adhesive therapeutic tapes is compressing market access timelines and forcing manufacturers to rebuild clinical evidence portfolios for European entry. This regulatory pivot is reshaping competitive positioning as notified body capacity constraints create bottlenecks that favor incumbents with established conformity assessment documentation.
Growth Catalysts
- Bundesliga procurement concentration:German professional football clubs and private physiotherapy networks maintain high-volume supply contracts that normalize kinesiology tape as standard injury prevention equipment across European sports medicine.
- FDA Class I medical device pathway:The streamlined quality system regulation framework for therapeutic claims enables faster market entry for US manufacturers compared to European MDR compliance burdens.
- ISO 10993 biocompatibility standardization:Harmonized cytotoxicity and skin sensitization testing protocols reduce redundant documentation requirements across multiple export jurisdictions.
Market Restraints
- Acrylic adhesive input volatility:Medical-grade acrylic polymer supply concentrates among Japanese and German chemical producers, exposing tape converters to petrochemical price swings and currency fluctuation risks.
- Notified body capacity scarcity:EU MDR implementation has collapsed the number of designated conformity assessment organizations, extending CE mark timelines for new tape formulations by 12-18 months.
- Rigid athletic tape substitution:Traditional zinc oxide athletic tape retains cost advantage in price-sensitive institutional procurement, limiting kinesiology tape penetration in high school and amateur league segments.
Strategic Opportunities
- Pre-cut tape format expansion:Clinics in Australia and Canada are prioritizing application-efficient configurations that reduce staff training time and enable faster patient throughput in high-volume rehabilitation centers.
- Chronic pain management protocols:Osteoarthritis and fibromyalgia patient populations represent underpenetrated repeat-purchase segments with higher margin profiles than acute sports injury applications.
- Direct-to-practitioner e-commerce channels:Athletic trainers and physical therapists are migrating procurement to specialized medical supply platforms that bypass traditional distributor markups.
Industry Challenges
- Application technique standardization gaps:Inconsistent taping methodology training across physiotherapy education programs creates variable clinical outcomes that undermine product efficacy claims.
- CE mark clinical evidence generation costs:MDR-mandated biocompatibility studies and performance testing for expanded medical device definitions require capital deployment that strains mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Kinesio Tape Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $561.08 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Tape, Rigid Tape, Adhesive Tape, Pre-cut Tape Application: Sports Injury Prevention, Rehabilitation, Pain Management, Postural Correction, Lymphatic Drainage End User: Physiotherapists, Chiropractors, Athletic Trainers, Orthopedic Clinics, Wellness Centers Distribution Channel: Online Retail, Pharmacies, Specialty Stores, Hospitals & Clinics, Direct Sales |
| Companies Covered | Kinesio Holding Corporation, RockTape, Mueller Sports Medicine Inc., Nitto Denko Corporation, SpiderTech Inc., KT Health LLC, StrengthTape, Atex Medical Co. Ltd., DL Medical & Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Kinesio Tape Market Shifts & Advancements
Synthetic fiber substrates and intelligent adhesive formulations are displacing traditional cotton-based tape constructions across premium sports medicine segments. Material science advances are enabling differentiated performance claims that support price stratification.
Silicone-based medical adhesives are supplanting acrylic formulations in hypoallergenic tape segments targeting sensitive-skin patient populations. Pediatric oncology units and geriatric rehabilitation facilities in Switzerland and the Netherlands are adopting these alternatives at accelerated rates. The shift is compressing margins for legacy acrylic-dependent product lines while opening premium positioning for biocompatible silicone substrates.
EU MDR clinical evidence requirements for adhesive tapes bearing expanded medical device definitions are forcing manufacturers to commission biocompatibility studies that were previously exempt. German notified bodies are rejecting legacy technical documentation that lacked ISO 10993 cytotoxicity testing. Pain management tape categories face the steepest compliance burden as their therapeutic claims trigger stricter conformity assessment pathways.
Hospital supply chain departments are ceding purchasing authority for rehabilitation consumables directly to clinical users. Physiotherapists in US academic medical centers now control vendor selection for kinesiology tape through specialty-specific procurement cards. This disintermediation is most visible in California and Texas health systems where value-analysis committees have delegated low-cost consumable decisions to department-level buyers.
Global Kinesio Tape Market Segmentation
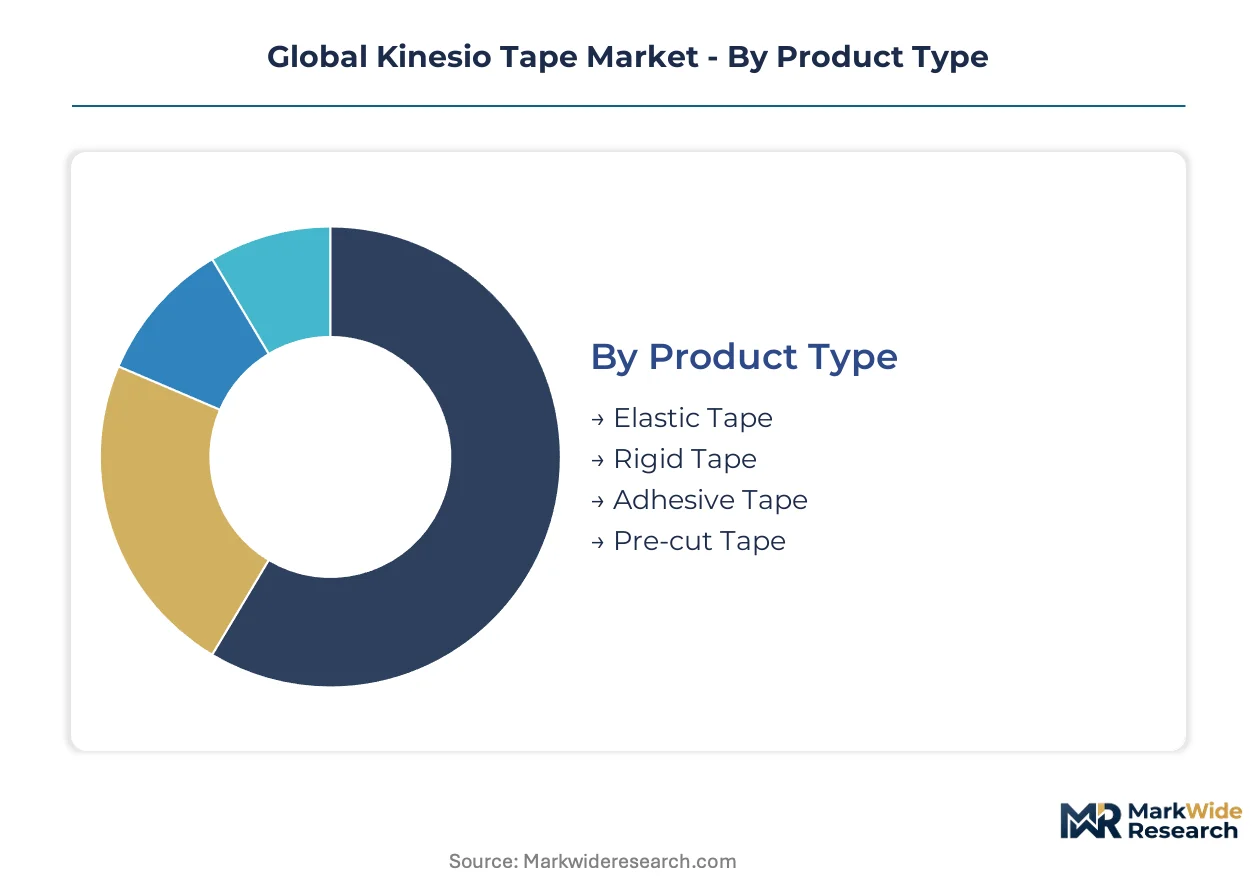
Segmentation in kinesiology tape markets reveals how regulatory pathways, application settings, and procurement authority redistribute margin capture across the value chain. Manufacturers must align product formats with specific end-user workflows and jurisdiction-specific compliance burdens.
Product Type:
FDA Class I designation and EU MDR conformity requirements diverge sharply across substrate-adhesive combinations, creating tiered market access costs that favor certain constructions over others.
- Elastic Tape:Cotton or synthetic fiber substrates with hypoallergenic acrylic adhesive engineered for 40-60% longitudinal stretch while restricting lateral deformation. German Bundesliga clubs and private physiotherapy networks in Munich and Hamburg maintain high-volume supply contracts that normalize this format as standard injury prevention equipment.
- Pre-cut Tape:Factory-configured shapes and lengths eliminate on-site cutting requirements. Clinics in Australia and Canada prioritize this format to reduce staff training time and accelerate patient throughput in high-volume rehabilitation centers.
- Rigid Tape:Zinc oxide adhesive formulations with minimal stretch characteristics. Traditional athletic programs in Texas and Florida high schools favor cost-sensitive procurement of this established alternative.
- Adhesive Tape:Base pressure-sensitive constructions without kinesiology-specific elasticity. Industrial converters in Japan supply medical-grade acrylic polymers to multiple downstream tape manufacturers.
Elastic tape handles the majority of throughput; pre-cut tape is the fastest mover on share.
Application:
Pain management protocols command concentrated margin pools from repeat-purchase chronic condition patients, while sports applications generate higher absolute unit volumes from institutional buyers with standardized procurement cycles.
- Pain Management:Osteoarthritis and fibromyalgia patient populations drive repeat purchase frequency with premium pricing tolerance. Swiss and Dutch geriatric rehabilitation facilities are adopting silicone-based alternatives at accelerated rates for sensitive-skin populations.
- Sports Injury Prevention:Professional and amateur athletic programs require standardized taping protocols for load-bearing joints. Olympic training facilities in Colorado Springs and Canberra are expanding procurement for preventive use.
- Rehabilitation:Post-surgical and injury-recovery protocols in orthopedic settings. California academic medical centers delegate vendor selection directly to physiotherapy departments through specialty procurement cards.
- Postural Correction:Ergonomic intervention for occupational and chronic postural dysfunction. Corporate wellness programs in London and Singapore pilot tape-based interventions for desk-worker populations.
- Lymphatic Drainage:Specialized application techniques targeting edema reduction. Oncology units in Geneva and Rotterdam integrate tape protocols into pediatric and adult cancer care pathways.
Sports injury prevention dominates absolute volume; pain management delivers the steepest expansion trajectory on margin contribution.
End User:
Procurement authority migration from hospital supply chains to clinical end-users is reshaping vendor selection criteria toward application-specific efficacy rather than bulk pricing.
- Physiotherapists:Direct purchasing control over rehabilitation consumables in US academic medical centers and German private practice networks. These practitioners prioritize tape formats with demonstrated lymphatic flow and proprioceptive outcomes.
- Athletic Trainers:Sideline and training room procurement for professional and collegiate sports programs. KT Health LLC leverages brand recognition to sustain premium positioning in direct-to-practitioner channels serving this segment.
- Chiropractors:Spinal and extremity adjustment complementary applications. North American practice consolidation is standardizing supply preferences across multi-clinic networks.
- Orthopedic Clinics:Post-surgical rehabilitation protocols with insurance-reimbursable supply components. Texas and Florida health systems delegate low-cost consumable decisions to department-level buyers.
- Wellness Centers:Non-clinical performance and recovery applications. CrossFit and functional fitness segments in California and Australia drive education-centric marketing investment.
Physiotherapists control the largest addressable spend base; athletic trainers are gaining procurement authority fastest.
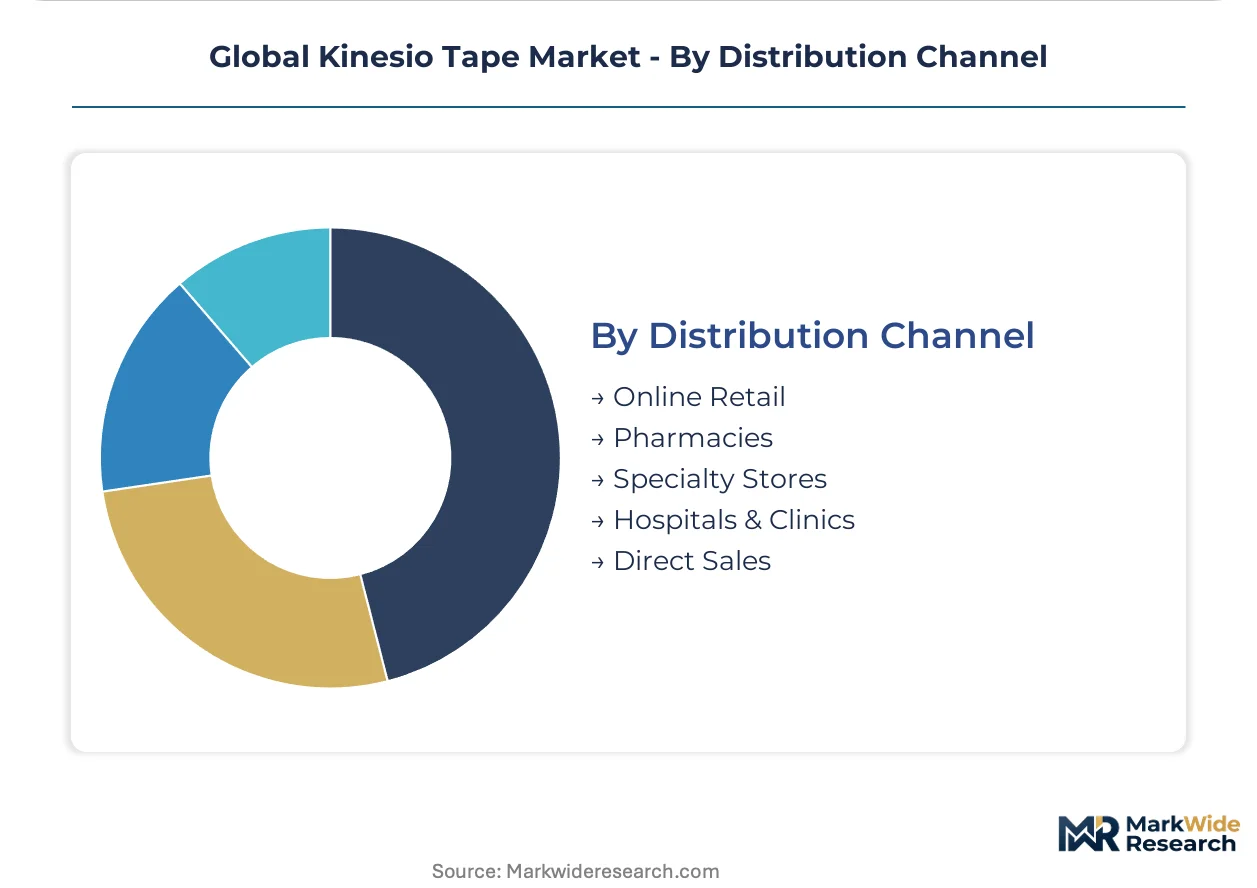
Distribution Channel:
Channel economics reflect markup compression from disintermediation versus compliance documentation burdens that favor established distributor relationships.
- Direct Sales:Manufacturer-to-practitioner relationships bypass traditional distributor markups. Specialized medical supply platforms are capturing athletic trainer and physical therapist procurement migration.
- Hospitals & Clinics:Institutional procurement with value-analysis committee oversight. California and Texas health systems have recently delegated kinesiology tape decisions to department-level clinical buyers.
- Online Retail:Consumer-direct and small-practice procurement with price transparency. Australian and Canadian clinics increasingly source pre-cut formats through specialized e-commerce platforms.
- Pharmacies:Over-the-counter availability for consumer self-application. EU MDR reclassification is tightening conformity assessment requirements for therapeutic claims in European retail channels.
- Specialty Stores:Sporting goods and fitness equipment retailers with staff-trained recommendation capability. Event sponsorships dominate brand building in CrossFit and functional fitness segments.
Hospitals and clinics still process the bulk of institutional volume; direct sales channels are climbing the fastest on practitioner preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export medical-grade adhesive substrates to tape converters across North America and Asia-Pacific, establishing a trade-flow corridor that concentrates high-value component supply in Central Europe while finished goods distribution radiates outward.
United States
Olympic training facilities in Colorado Springs and collegiate athletic programs drive institutional procurement volume. FDA Class I medical device designation streamlines quality system regulation compliance for therapeutic claims. California academic medical centers delegate vendor selection directly to physiotherapy departments through specialty procurement cards.
Germany
Bundesliga football clubs and private physiotherapy networks in Munich and Hamburg maintain high-volume supply contracts that normalize kinesiology tape as standard injury prevention equipment. EU MDR notified bodies in Berlin and Frankfurt reject legacy technical documentation lacking ISO 10993 cytotoxicity testing. Industrial-scale medical adhesive production concentrates in North Rhine-Westphalia.
Australia
High-volume rehabilitation centers in Sydney and Melbourne prioritize pre-cut tape configurations to accelerate patient throughput. TGA therapeutic goods administration governs medical device conformity assessment for imported adhesive tapes. Specialized e-commerce platforms capture clinic procurement migration from traditional distributor channels.
Japan
PMDA pharmaceutical and medical device regulation shapes biocompatibility documentation requirements for domestic and export markets. Industrial converters in Osaka and Tokyo supply medical-grade acrylic polymers to downstream tape manufacturers worldwide. METI industrial policy supports advanced material science R&D in silicone-based hypoallergenic formulations.
Switzerland
Geriatric rehabilitation facilities in Geneva and pediatric oncology units in Basel adopt silicone-based medical adhesives at accelerated rates for sensitive-skin populations. Swissmedic medical device regulation imposes stringent clinical evidence requirements comparable to EU MDR standards. Premium positioning concentrates in Zurich private practice networks serving chronic pain management protocols.
Global Kinesio Tape Market Competitive Landscape
Player mix skews toward specialized medical device manufacturers with adhesive material science capabilities rather than diversified healthcare conglomerates. Tiered competitive positioning separates premium brand-recognized suppliers from industrial-scale substrate converters and regional private-label fabricators. Dominant competitive moves include direct-to-practitioner channel expansion and MDR compliance documentation investments that exploit notified body capacity bottlenecks.
Among North American brand-recognized suppliers, KT Health LLC and RockTape exemplify premium positioning archetypes that leverage athletic trainer relationships and event sponsorship strategies. Nitto Denko Corporation anchors the industrial-scale substrate tier with medical-grade adhesive manufacturing capacity supplying multiple downstream converters. These three companies represent the strategic spectrum from practitioner-facing brand equity to upstream material control.
| Leading Market Players |
|---|
| Kinesio Holding Corporation |
| RockTape |
| Mueller Sports Medicine Inc. |
| Nitto Denko Corporation |
| SpiderTech Inc. |
| KT Health LLC |
| StrengthTape |
| Atex Medical Co. Ltd. |
| DL Medical & Health |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German Bundesliga clubs and medical-grade adhesive suppliers lock in supply access and price visibility across multi-season procurement cycles. These contracts insulate high-volume buyers from acrylic polymer volatility while compressing margins for spot-market purchasers in fragmented physiotherapy networks.
Pricing Analysis
Synthetic fiber substrate formulations command a 15-25% premium over legacy cotton constructions due to enhanced durability claims. Pricing stratifies across premium silicone-adhesive tiers for sensitive-skin populations, standard acrylic-based configurations for institutional sports programs, and economy zinc oxide alternatives for price-sensitive high school athletic departments. Cost compression in the economy tier is intensifying because rigid athletic tape substitution limits kinesiology tape penetration. Amateur leagues and recreational fitness centers exhibit the highest price sensitivity; Olympic training facilities and professional sports franchises demonstrate the lowest.
Supply Chain Analysis
Strategic stockpiling of medical-grade acrylic polymers dominates procurement behavior among Japanese and German industrial converters facing petrochemical price swings. Supply concentrates in Japan, Germany, and the United States for substrate-adhesive combinations. Downstream tape manufacturers draw from Osaka-based polymer specialists, North Rhine-Westphalia chemical producers, and FDA-registered US coating facilities. Single-source vulnerability in Japanese acrylic supply creates exposure to currency fluctuation and shipping route disruption. Distribution runs through specialized medical supply platforms that bypass traditional distributor markups for direct-to-practitioner fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where EU MDR compliance documentation creates switching costs that cement incumbent positions. Notified body capacity scarcity extends CE mark timelines for new entrants, widening the moat around established conformity assessment portfolios.
For Market Incumbents: Consolidate notified body relationships and backward integration into medical-grade adhesive production to defend against emerging Asian substrate converters. Capacity addition in Germany preserves proximity to Bundesliga procurement decision-makers. MDR clinical evidence investments represent the critical lever for maintaining European market access against mid-tier challengers lacking capital deployment capacity. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways offer lower regulatory barriers than EU MDR conformity assessment for initial market entry. Chronic pain management protocols in Swiss and Dutch geriatric facilities represent the most penetrable white-space segment with premium pricing tolerance. Direct-to-practitioner e-commerce channels enable bypass of distributor-controlled hospital procurement committees. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier manufacturers with incomplete MDR documentation but established ISO 10993 testing relationships that accelerate conformity assessment completion. Long-term viability hinges on adhesive material science capabilities rather than brand equity alone. The signal to watch is notified body designation expansion in Germany and France as an inflection indicator for European market access timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Conformity Assessment Investment | CE marking pathway through German notified bodies secures European market access against capacity-constrained competitors. |
| Silicone Adhesive Formulation Development | Swissmedic-compliant biocompatibility testing opens pediatric oncology and geriatric rehabilitation premium segments. |
| Pre-cut Tape Format Expansion | Australian TGA-registered configurations accelerate patient throughput in high-volume Sydney rehabilitation centers. |
| Direct-to-Practitioner Channel Buildout | Specialized medical supply platforms capture athletic trainer procurement migration from traditional distributors. |
| ISO 10993 Testing Documentation | Cytotoxicity and skin sensitization protocols satisfy FDA and EU MDR requirements for multi-jurisdiction market entry. |
Research Methodology
A spread of perspectives from physiotherapy department heads, athletic training staff, hospital procurement managers, and medical device regulatory consultants converged on the working assumptions for market sizing and growth trajectory. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR notified body designation records, TGA therapeutic goods registers, and ISO 10993 biocompatibility testing documentation. Bottom-up demand modeling across product formats and top-down supply-side capacity analysis triangulated volume and value estimates.
Segmentation dimensions modeled include substrate material, adhesive chemistry, product configuration, application protocol, end-user specialty, and distribution channel across the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking regulatory timeline assumptions. Forecast inputs incorporated Bundesliga supply contract renewal cycles, MDR implementation phase-in schedules, and silicone-adhesive substitution rates in sensitive-skin patient populations.
Decision-makers should treat outputs as directional under assumptions of stable acrylic polymer supply and sustained notified body capacity constraints; material deviation would warrant model refresh. Specific risk factors include PMDA regulatory alignment changes in Japan, METI industrial policy shifts affecting silicone R&D subsidies, and FDA enforcement discretion modifications for therapeutic claim classifications. Revision becomes warranted when EU MDR notified body designation expansion crosses thresholds that compress CE mark timelines below 12 months.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Golf Gloves Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Speed Hurdle Market
Sports Equipment
Global Golf Training Aids Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
North America Sporting Goods Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
US Fencing Market
Sports Equipment
Pickleball Pitching Machine Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
Gym Bag Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
High-End Bicycle Market
Sports Equipment
Global Pickleball Equipment Market
Sports Equipment
Air Sports Equipment Market