
 Global Bicycle Market | 2026-2036
Global Bicycle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bicycle Market Analysis
Subscription-based maintenance and software-enabled performance tracking is pivoting the bicycle industry from one-time hardware sales toward recurring revenue relationships. Trek Bicycle Corporation leverages its dealer network to control service touchpoints across North America. Giant Manufacturing Co. Ltd anchors production scale through in-house carbon fiber layup and frame manufacturing in Taiwan. Specialized Bicycle Components differentiates through proprietary Retül fit technology and direct-to-consumer digital channels.
A bicycle is a human-powered, single-track vehicle consisting of a diamond or step-through frame, two wheels with pneumatic tires, a chain-driven drivetrain with variable gearing, and hand-operated rim or disc brakes, engineered for individual transportation, recreation, or sport. Carbon fiber and aluminum dominate frame material selection, with titanium occupying premium custom builds where fatigue resistance justifies cost. Mountain bikes and hybrid categories capture expanding commuter and trail-riding demand, while road bikes retain concentrated margin pools among competitive cyclists and club riders. Online retail and specialty stores split distribution, with the former scaling entry-level volume and the latter securing high-attachment-rate service revenue.
The EU Green Deal and F-Gas Regulation shape European product standards and subsidy eligibility for low-carbon mobility alternatives. The EPA and NHTSA in the United States influence safety testing protocols and consumer protection frameworks for imported cycles. Stakeholders must monitor how evolving carbon accounting rules and infrastructure appropriations in Germany, Japan, and the Netherlands determine where demand materializes fastest.
Market Dynamics
The bicycle market pivots on infrastructure-led demand activation, where protected lane networks in Amsterdam, Copenhagen, and Utrecht demonstrate that physical pathway investment precedes and multiplies hardware sales more predictably than product innovation cycles.
Growth Catalysts
- EU Green Deal mobility subsidies:Member states redirect vehicle taxation revenue toward cycle-to-work schemes and e-bike purchase incentives, compressing payback periods for commuter conversion.
- Carbon fiber layup automation:Taiwanese frame houses deploy robotic fiber placement to cut labor hours per monocoque, narrowing cost gaps with aluminum at premium price points.
- Netherlands infrastructure density:The national node network of 35,000 kilometers of separated paths creates reference infrastructure that neighboring Belgium and Germany replicate with federal transport appropriations.
Market Restraints
- Titanium supply concentration:Sponge production clusters in Russia and Kazakhstan expose premium frame builders to raw material sanctions risk and price volatility.
- REACH chemical compliance:European paint and resin formulations face substitution mandates for chromium-based corrosion inhibitors, forcing reformulation cycles that extend product development timelines.
- Lithium-ion cell allocation:E-bike motor systems compete with automotive and grid storage for cylindrical cell supply, constraining mid-motor production scaling during demand surges.
Strategic Opportunities
- Indonesia archipelago mobility:The Jokowi administration's trans-Java cycling corridor investments open fleet sales channels for cargo bikes and last-mile delivery vehicles.
- Software-enabled maintenance subscriptions:Predictive wear algorithms tied to power meter data create recurring revenue attachment at the point of original equipment sale.
- Japan's METI carbon accounting rules:Corporate mobility scope-three reporting requirements position bicycle commuting as verifiable emission reduction for large employers.
Industry Challenges
- Frame alignment technician scarcity:Carbon repair and Retül-grade fitting demand outpaces certified training program throughput in North American dealer networks.
- ISO 4210 testing backlog:Safety certification queue lengths at accredited laboratories delay new model introductions by two to three production cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bicycle Market |
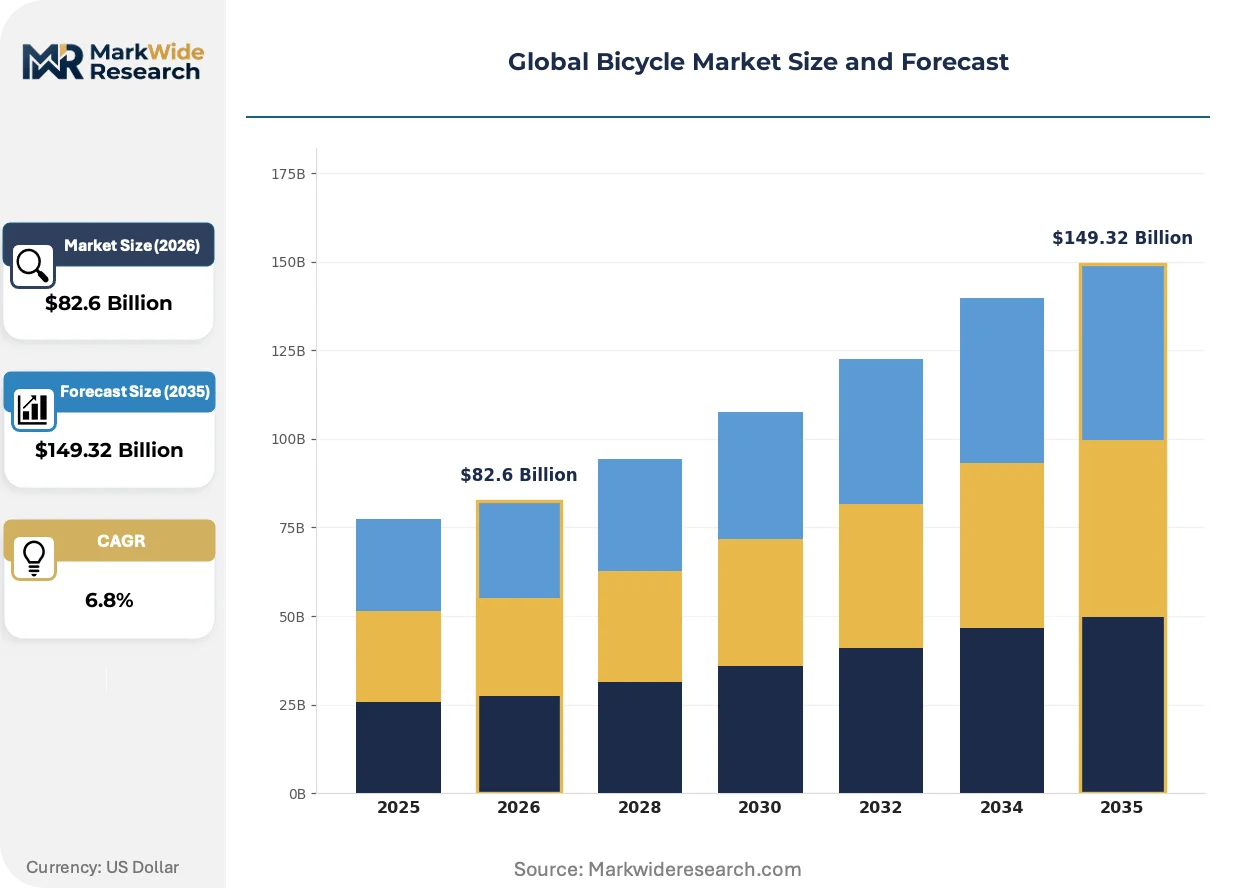
| Market Size in 2026 | $82.6 Billion |
| Market Size in 2035 | $149.32 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain Bikes, Road Bikes, Hybrid Bikes, Folding Bikes Material: Aluminum, Carbon Fiber, Steel, Titanium End User: Children, Adults, Commuters, Fitness Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | Trek Bicycle Corporation, Giant Manufacturing Co. Ltd, Specialized Bicycle Components, Merida Industry Co. Ltd, Accell Group, SCOTT Sports SA, Pon Holdings BV, Cervelo, Dorel Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bicycle Market Emerging Trajectories
Electronics penetration is rewiring bicycle architecture from mechanical simplicity toward sensor-rich platforms, with power measurement, theft tracking, and crash detection becoming standard equipment expectations rather than premium add-ons.
Wireless electronic shifting is integrating battery-powered derailleurs with handlebar-mounted satellite buttons to eliminate cable housing routing through internal frame channels. Competitive cyclists and gran fondo participants adopt SRAM and Shimano Di2 platforms at replacement cycle compression rates of three to four years. This integration is enabling frame designers to optimize aerodynamic tube profiles without mechanical accommodation constraints.
The EU F-Gas Regulation phases down hydrofluorocarbon propellants used in tire sealant aerosols, forcing manufacturers toward CO2-based or pump-dependent inflation systems. Industrial consequence includes reformulation investment and packaging line retooling for sealant suppliers. Mountain bike and gravel segments in Germany and Austria respond fastest, with consumer education campaigns converting riders to tubeless setup pumps.
Corporate fleet procurement now bundles bicycles with maintenance contracts and telematics tracking, displacing one-time capital expenditure models for urban delivery and campus mobility operators. Municipalities and logistics platforms in the Netherlands and Denmark pilot subscription-based cargo bike pools. This pattern concentrates most visibly in Copenhagen's municipal procurement, where service-level agreements now dominate tender specifications over hardware ownership.
Global Bicycle Market Segmentation
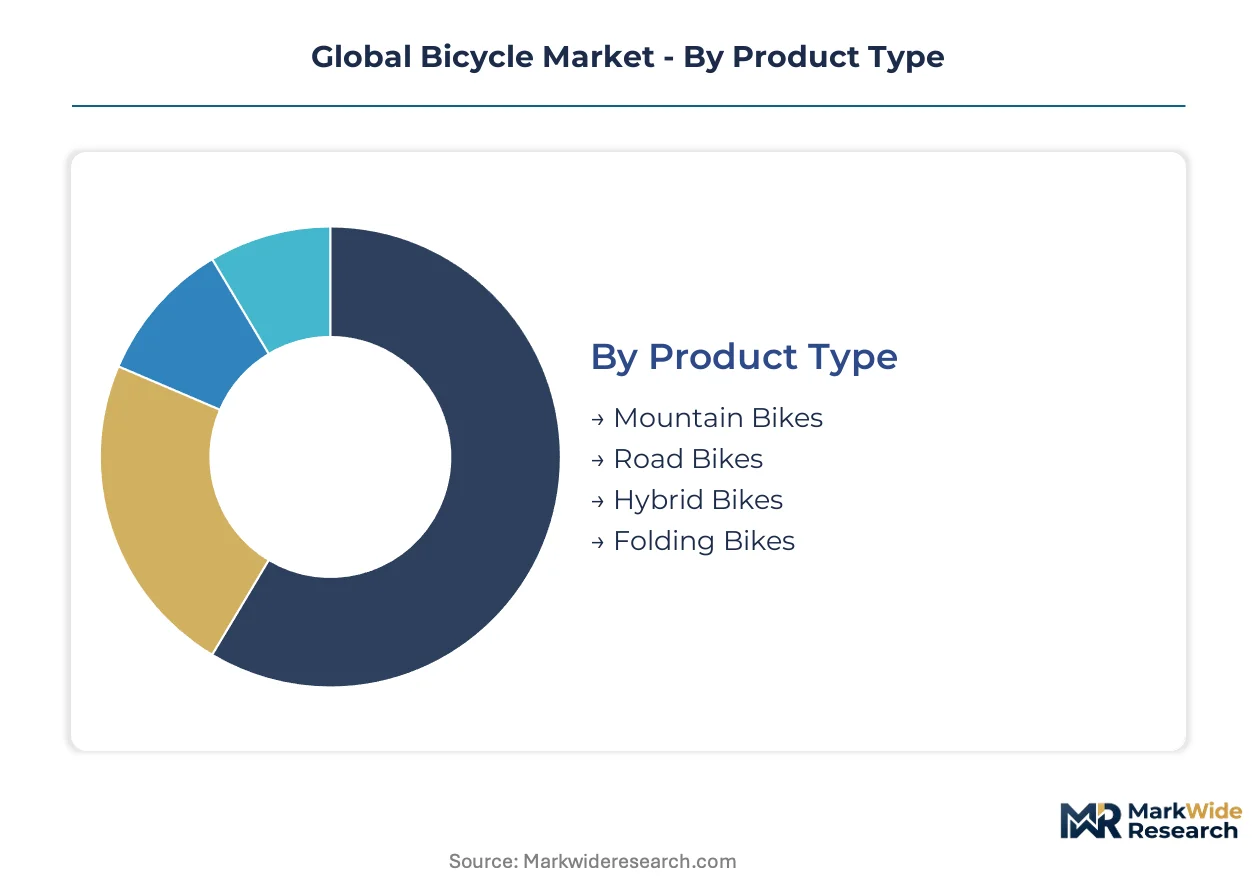
Segmentation in the bicycle market reveals how infrastructure investment, material science, and channel economics split demand across distinct buyer profiles. Understanding these divides helps manufacturers allocate R&D resources and align production capacity with where purchasing decisions actually form.
Product Type:
Purchase intent in this category hinges on terrain access and commute distance rather than price sensitivity alone.
- Mountain Bikes:Suspension-equipped frames with 27.5-inch or 29-inch wheel diameters dominate trail-accessible regions in Germany and Austria. Demand concentrates in Bavaria and Tyrol where federal forest trail networks expand seasonally, though winter weather compresses replacement cycles in Nordic markets.
- Road Bikes:Drop-bar geometries with carbon fiber monocoque construction target competitive cyclists and gran fondo participants in Italy and France. The Netherlands shows surprising road bike attachment among long-distance commuters who prioritize aerodynamic efficiency on flat infrastructure.
- Hybrid Bikes:Flat-bar frames with mid-range gearing suit mixed-surface urban commuting in Belgian and Dutch cities where cobblestone sectors interrupt asphalt pathways.
- Folding Bikes:Hinge-frame designs with 16-inch or 20-inch wheels address multi-modal transit integration in Tokyo and London, where rail operators impose dimensional restrictions during peak hours.
Volume sits with Hybrid Bikes; growth tilts toward Mountain Bikes.
Material:
Frame material selection tracks performance requirements and repair infrastructure availability across buyer segments.
- Aluminum:6061-T6 alloy tubing with hydroformed shaping delivers strength-to-weight ratios adequate for mass-market road and hybrid categories. Taiwanese extrusion houses in Taichung supply global OEMs with just-in-time frame sets, though energy costs at primary smelters in Quebec and Iceland influence input pricing.
- Carbon Fiber:Toray T800 and T1000 prepreg layups enable sub-800-gram frame weights for professional racing applications. Italian frame builders in Veneto and Emilia-Romagna maintain manual layup expertise for custom geometries, while Giant Manufacturing automates monocoque production at scale in Taiwan.
- Steel:Chromoly and Reynolds 853 tubing persists in touring and cargo bike segments where fatigue resistance and field repairability matter more than weight minimization.
- Titanium:Grade 9 alloy frames from Russian VSMPO sponge feedstock occupy premium custom builds, though sanctions exposure has pushed some builders toward Japanese Kobe Steel sources.
Aluminum commands unit volume; carbon fiber captures margin expansion.
End User:
User life stage and mobility purpose determine feature prioritization and service attachment rates.
- Commuters:Integrated lighting, fender compatibility, and rack mounting points dominate specification sheets in Copenhagen and Amsterdam, where employers subsidize cycle-to-work schemes through salary sacrifice arrangements.
- Adults:General recreational riders in suburban France and Germany prioritize comfort geometries and step-through frame access, particularly among buyers returning to cycling after decades of automobile dependency.
- Fitness Enthusiasts:Power meter integration and GPS computer compatibility drive component upgrade cycles in competitive club environments across Italy and Spain.
- Children:Growth-adjustable frame designs and coaster brake simplicity address parental safety concerns in Japanese and South Korean markets with aging demographics and low birth rates.
Adults generate baseline volume; commuters show steepest expansion trajectory.
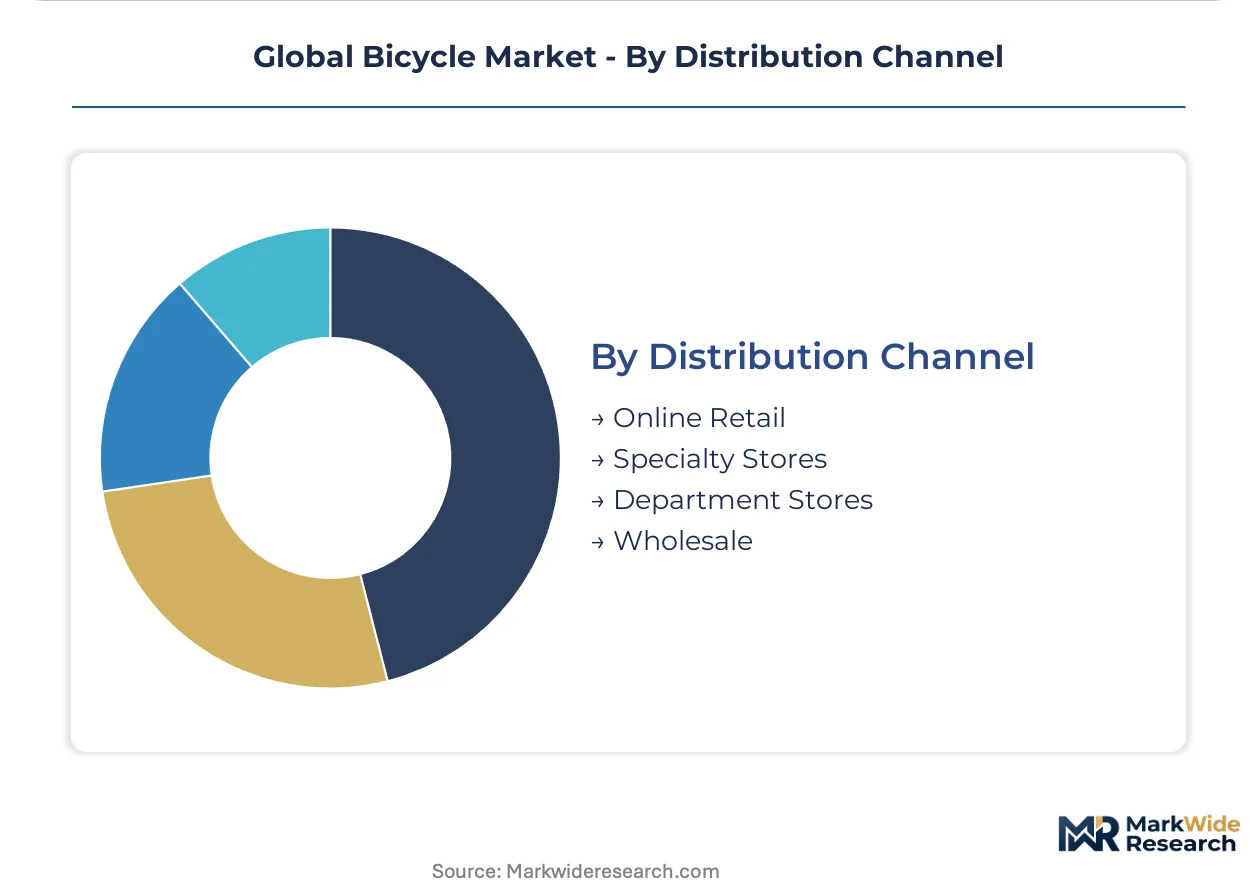
Distribution Channel:
Channel selection reflects service dependency and purchase urgency across buyer maturity levels.
- Specialty Stores:Retül-grade fitting services and maintenance contract attachment secure high lifetime value per customer in North American and Western European markets. Trek Bicycle Corporation's dealer network exemplifies this model, controlling service touchpoints that drive repeat purchase loyalty.
- Online Retail:Direct-to-consumer platforms with assembly-included delivery capture entry-level volume in price-sensitive segments, though return logistics for oversized bicycle cartons erode margin at scale.
- Wholesale:Fleet procurement for municipal bike-share systems and corporate campus mobility concentrates in Copenhagen and Utrecht, where service-level agreements displace hardware ownership in tender specifications.
- Department Stores:Mass-market price points with limited service support serve occasional recreational buyers in suburban Japan and Australia, though quality perception gaps persist against specialty channel offerings.
Specialty Stores retain service-driven margin; online channels scale entry-level acquisition fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan concentrates carbon fiber frame manufacturing, while the Netherlands and Denmark absorb the highest per-capita bicycle consumption. Germany and the United States split demand between commuter conversion and recreational trail access.
Netherlands
The national node network of 35,000 kilometers of protected lanes sustains the densest cycling infrastructure worldwide. The EU Green Deal channels mobility subsidies through Dutch cycle-to-work schemes, compressing commuter conversion payback periods. Amsterdam and Utrecht host municipal procurement pilots where service-level agreements displace hardware ownership in cargo bike tenders.
Germany
Federal transport appropriations replicate Dutch infrastructure patterns across North Rhine-Westphalia and Bavaria, where forest trail networks expand seasonally. The KBA enforces safety testing protocols that align with EU-wide ISO 4210 certification requirements. Taichung-based frame houses supply German OEMs through just-in-time extrusion contracts.
United States
Urban commuter adoption accelerates in coastal metros where employer-sponsored cycle-to-work programs expand. The EPA influences safety testing protocols for imported frames, while NHTSA consumer protection frameworks govern component liability. Trek Bicycle Corporation's dealer network controls service touchpoints across North American markets.
Japan
METI carbon accounting rules position bicycle commuting as verifiable scope-three emission reduction for large employers. Folding bike demand concentrates in Tokyo, where rail operators impose dimensional restrictions during peak hours. Kobe Steel supplies titanium sponge to premium custom frame builders facing Russian feedstock sanctions exposure.
Indonesia
The Jokowi administration's trans-Java cycling corridor investments open fleet sales channels for cargo bikes and last-mile delivery vehicles. Domestic regulations favor low-carbon mobility alternatives in archipelago logistics. Jakarta and Surabaya anchor procurement concentration for municipal bike-share system expansion.
Global Bicycle Market Vendor Landscape
Top-tier vendors anchor premium carbon fiber and electronic integration, while mid-tier specialists compete on aluminum frame scale and regional dealer density. The vendor base spans Taiwanese manufacturing conglomerates, European premium specialists, and North American brand-marketing entities. Three archetypes dominate: vertically integrated frame houses controlling carbon layup, brand-owners outsourcing production to captive Asian suppliers, and subscription-service platforms capturing recurring maintenance revenue. M&A activity concentrates on software-enabled performance tracking startups, while capacity expansion targets Indonesian and Vietnamese assembly plants.
Among North American brand-owners, Trek Bicycle Corporation exemplifies dealer-network control over service touchpoints. Giant Manufacturing Co. Ltd represents the vertically integrated archetype through in-house carbon fiber production. Specialized Bicycle Components occupies a position within the premium tier through proprietary fit technology and direct-to-consumer digital channels.
| Leading Market Players |
|---|
| Trek Bicycle Corporation |
| Giant Manufacturing Co. Ltd |
| Specialized Bicycle Components |
| Merida Industry Co. Ltd |
| Accell Group |
| SCOTT Sports SA |
| Pon Holdings BV |
| Cervelo |
| Dorel Industries Inc. |
| Others |
Supply Flow & Price Mechanics
Carbon fiber-to-aluminum frame bifurcation separates premium racing builds from mass-market commuter units, with that material divergence mapping onto distinct supplier geographies and procurement contract structures. Taiwanese automated layup houses command pricing power at the carbon tier through captive fiber placement technology, while aluminum extruders in Quebec and Iceland face energy cost pass-through volatility that compresses margin stability at volume price points.
Pricing Analysis
Margin tightening in aluminum road and hybrid categories reflects energy cost volatility at primary smelters in Quebec and Iceland, forcing OEMs toward longer-term offtake contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by frame material grade and ISO 4210 certification tier, with carbon monocoque builds capturing brand premium and entry-level aluminum facing acute price sensitivity among first-time commuter buyers in German and Dutch cycle-to-work schemes.
Supply Chain Analysis
Container freight rate swings on Asia-Europe lanes directly impact landed cost structures for frame sets and complete builds sourced from Taichung manufacturing clusters. Production gravity centers on Taiwan for carbon fiber layup, China for aluminum extrusion and component assembly, and Vietnam for emerging capacity in mid-tier frame finishing. Raw material dependencies span Toray prepreg carbon fiber, 6061-T6 aluminum billet, and Russian-origin titanium sponge now facing sanctions-driven substitution toward Japanese Kobe Steel sources. Single-source vulnerability concentrates in carbon fiber precursor supply, while distribution runs through specialty dealer networks in North America and direct-to-consumer platforms in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bicycle market functions as a vertical-integration race where upstream control over carbon fiber layup automation and downstream capture of maintenance subscription revenue determine margin sustainability. Players securing both levers will outcompete pure brand-owners dependent on outsourced manufacturing.
For Market Incumbents: Acquire predictive maintenance software platforms and certified fitting service networks to lock in recurring revenue attachment at point of sale. Defensive consolidation must address frame alignment technician scarcity through captive training academy investments, while carbon fiber repair certification creates switching costs against direct-to-consumer entrants. Threat substitution from e-bike motor systems competing for lithium-ion cell allocation with automotive demand requires battery supply partnerships or backward integration into cell procurement. For New Entrants and Emerging Players: The mid-tier aluminum commuter gap between premium carbon builds and mass-market department store offerings presents the most penetrable white-space for regional assembly operations in Indonesia and Vietnam. Target cargo bike fleet procurement for last-mile logistics operators in Jakarta and Surabaya, where Jokowi administration infrastructure investment precedes hardware demand. Go-to-market leverage rests on subscription-based service bundling that displaces capital expenditure models in municipal tenders. For Investors and Strategic Acquirers: Exit pathways concentrate in software-enabled performance tracking startups with power meter data integration and predictive wear algorithms. Long-term viability across the analysis window hinges on acquiring assets with demonstrated recurring revenue attachment rates above hardware-only peers. The inflection signal to watch is corporate fleet procurement velocity in the Netherlands and Denmark, where service-level agreement penetration indicates market readiness for subscription business model scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Layup Automation Investment | Taiwanese frame houses deploying robotic fiber placement cut labor hours and narrow cost gaps with aluminum. |
| Maintenance Subscription Platform Launch | Predictive wear algorithms tied to power meter data create recurring revenue at original equipment sale point. |
| Certified Technician Training Academy Buildout | Retül-grade fitting and carbon repair certification outpaces training program throughput in North American networks. |
| Indonesian Assembly Capacity Expansion | Trans-Java cycling corridor investments open fleet sales channels for cargo bikes and last-mile delivery vehicles. |
| Battery Supply Partnership Structuring | E-bike motor systems compete with automotive and grid storage for cylindrical cell allocation during demand surges. |
Methodological Framework
Document review covered EU transport appropriation filings, Taiwan Bicycle Association production statistics, and ISO 4210 safety certification databases, complemented by interviews with frame manufacturing plant managers, specialty bicycle retailer owners, OEM procurement directors, and municipal fleet procurement officers across the Netherlands, Germany, and Indonesia. Secondary validation drew from customs trade data, SEC 10-K filings of listed component suppliers, and national cycling infrastructure investment disclosures. Bottom-up unit shipment estimates triangulated against top-down mobility subsidy allocation models.
Segment-level projections across product type, frame material, end user category, and distribution channel fed into analytical framework outputs over the projection horizon. CAGRs derived from infrastructure investment lag analysis correlating protected lane network expansion with hardware demand activation in Amsterdam, Copenhagen, and Utrecht reference markets. Industry-specific forecast inputs incorporated EU Green Deal subsidy phase-in schedules and lithium-ion cell allocation constraints affecting e-bike motor system production scaling.
Underlying measurement precision varies by segment; commuter and e-bike categories carry tighter precision than children's and recreational segments due to more complete subsidy tracking and fleet procurement disclosure. Forecasts reflect assumptions on infrastructure investment continuity and raw material sanctions exposure that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Racket Sports Equipment Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Europe Stand-Up Paddleboard Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Slam Ball Market
Sports Equipment
Ladderball Market
Sports Equipment
North America Sporting Goods Market
Sports Equipment
Basketball Gear Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Fencing Equipment Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Dirt Bike Market
Sports Equipment
Global Basketball Shoes Market
Sports Equipment
Power Sports Aftermarket Market