
 Playground Sets and Equipment Market | 2026-2036
Playground Sets and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Playground Sets and Equipment Market Analytics
The capital-intensity gap between integrated manufacturers and assembly-only operators is rotating competitive advantage toward firms with in-house rotational molding and steel fabrication capabilities. PlayCore leverages captive polymer production across multiple US facilities to control raw material costs and delivery timelines. Kompan anchors European demand through its specialized engineering of inclusive and accessible play solutions. Landscape Structures competes via extensive dealer networks that dominate municipal procurement channels in North America.
Playground sets and equipment encompass engineered outdoor recreational structures fabricated from galvanized steel, rotationally molded polyethylene, pressure-treated timber, or fiber-reinforced composite materials, designed to withstand cyclic loading, UV degradation, and impact forces while supporting child development through physical activity. Climbing structures fabricated from powder-coated steel and roto-molded plastic dominate commercial installations due to their durability and modular expandability. Composite materials command premium positioning in coastal and high-humidity environments where wood decay accelerates replacement cycles. Permanent installations sustain the largest revenue pool, though modular systems are capturing share in urban districts with constrained footprint flexibility.
The US Consumer Product Safety Commission enforces ASTM F1487 standards that mandate impact attenuation surfaces and entrapment hazard elimination, directly elevating surfacing material costs and installation complexity. European EN 1176 certification administered by national standards bodies requires third-party conformity assessment for public playground equipment, creating compliance barriers for non-EU manufacturers. Stakeholders must monitor evolving accessibility mandates under the US ADA and European accessibility acts, as these frameworks increasingly specify sensory-inclusive design elements that reshape R&D allocation and product portfolio composition.
Market Dynamics
Federal infrastructure grants and state-level early childhood education investments in the United States are compressing playground modernization cycles from decade-long replacement schedules to five-to-seven-year refresh mandates, forcing municipal procurement departments to restructure capital allocation frameworks and vendor qualification protocols.
Growth Catalysts
- ASTM F1487 enforcement:The US Consumer Product Safety Commission's tightened impact attenuation mandates are compelling park districts to replace aging equipment, creating sustained replacement demand across thousands of municipal installations.
- Inclusive design mandates:ADA accessibility requirements and European accessibility acts are specifying sensory-inclusive elements that expand addressable market scope beyond traditional physical play structures.
- Rotational molding adoption:Municipal buyers are specifying rotationally molded polyethylene components for their UV stability and modular expandability, favoring suppliers with captive polymer production capabilities.
Market Restraints
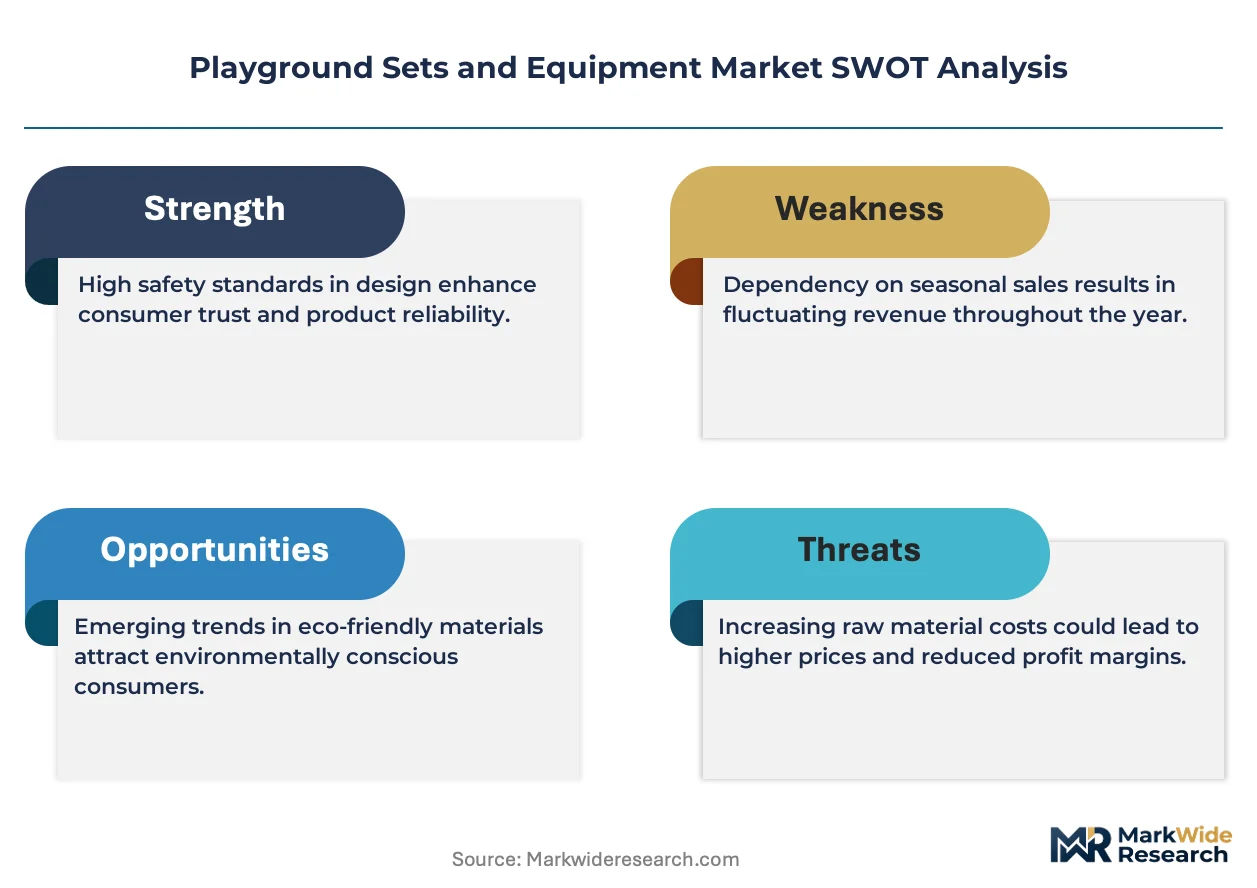
- Steel and resin cost volatility:Galvanized steel and polyethylene feedstock prices fluctuate with energy markets, compressing margins for assembly-only operators lacking backward integration into raw material production.
- European certification barriers:EN 1176 third-party conformity assessment requirements administered by national standards bodies create compliance friction for non-EU manufacturers seeking public sector contracts.
- Installation labor scarcity:Certified playground safety inspectors and specialized installation crews are concentrated in metropolitan corridors, extending project timelines in secondary markets.
Strategic Opportunities
- Urban modular systems:Districts with constrained footprint flexibility are specifying reconfigurable climbing structures that maximize play value per square meter, opening premium positioning for adaptable product portfolios.
- Composite material premiumization:Fiber-reinforced composite manufacturers can target coastal municipalities and high-humidity environments where pressure-treated timber decay accelerates replacement cycles.
- Sensory-inclusive R&D allocation:Federal and state disability accommodation incentives are funding procurement of equipment with auditory, tactile, and visual accessibility features that command price premiums.
Industry Challenges
- Certification timeline compression:ASTM F1487 and EN 1176 testing protocols require extended third-party validation periods that conflict with municipal fiscal-year procurement deadlines.
- Dealer network coordination:Manufacturers relying on independent distributor channels face inventory misalignment and installation quality variance across dispersed geographic territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Playground Sets and Equipment Market |
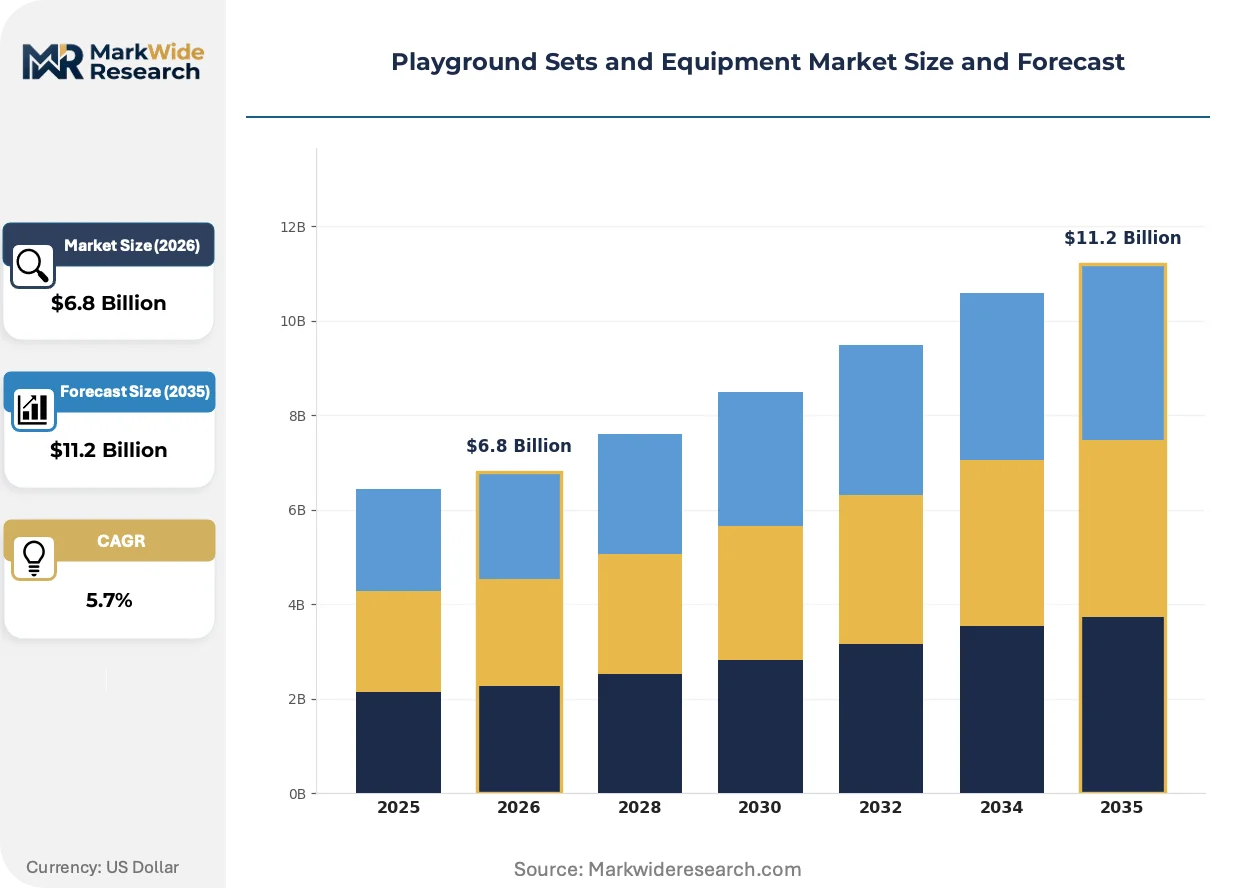
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swings, Slides, Climbing Structures, Seesaws Material: Wood, Metal, Plastic, Composite Age Group: Toddlers, Preschoolers, School-Aged Children, Teenagers Installation Type: Permanent, Portable, Modular, Custom |
| Companies Covered | PlayCore, Kompan, GameTime, Landscape Structures, Playworld, ELI, Qitele, BigToys, Playcraft Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Playground Sets and Equipment Market Evolving Landscape
Material science advances and regulatory accessibility mandates are restructuring competitive advantage around in-house manufacturing capabilities and specialized engineering competencies rather than distribution scale alone.
Smart surfacing technology incorporating embedded sensors for usage monitoring and maintenance alerting is bifurcating the installed base. Park districts in major metropolitan areas are piloting these systems for liability documentation and asset management. The technology is bifurcating procurement criteria between technology-forward districts and cost-constrained municipalities that prioritize capital expenditure minimization over operational data capture.
European EN 1176 certification harmonization across national standards bodies is elevating documentation requirements for public playground equipment. Manufacturers must now maintain technical files with design calculations, risk assessments, and test reports for decade-long retention periods. Smaller fabricators lacking dedicated compliance staff are ceding municipal contracts to firms with established European notified body relationships.
Municipal procurement departments are consolidating vendor relationships through cooperative purchasing agreements and state-level contracts. Large park districts in Texas, California, and Florida are aggregating demand through shared services alliances that bypass traditional dealer networks. This concentration is visible most acutely in states with centralized early childhood education infrastructure grant administration, where single-source specifications now dominate regional procurement patterns.
Playground Sets and Equipment Market Segmentation
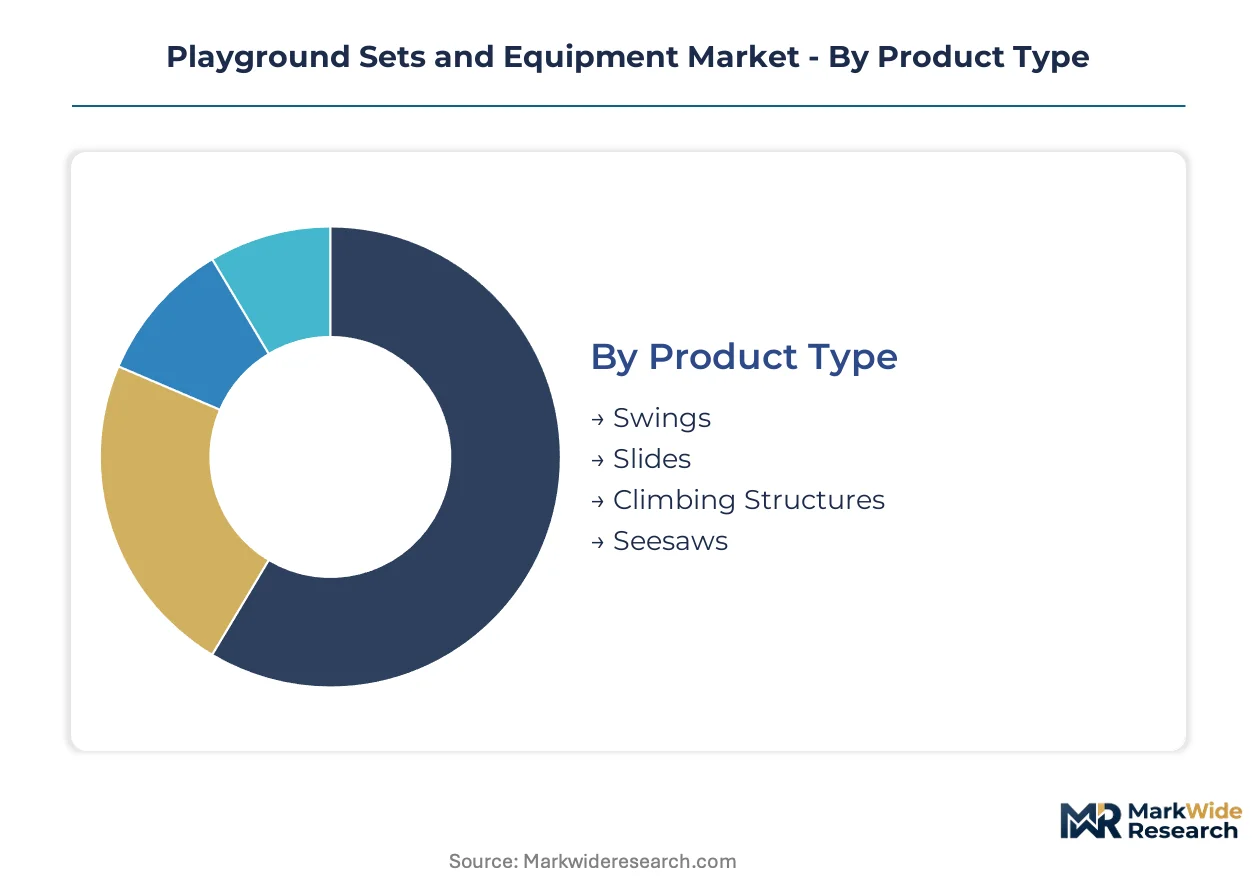
Segmentation in playground equipment reveals how procurement patterns diverge across institutional buyers, material preferences, and age-specific safety standards. Municipal park departments, school districts, and private developers each impose distinct technical specifications that reshape manufacturing priorities and distribution channels.
Product Type:
Domestic procurement dominates swings and slides through standardized municipal contracts, while climbing structures and seesaws attract specialized export demand from international school infrastructure programs.
- Swings:Suspended seat assemblies fabricated from roto-molded polyethylene buckets or rubberized flat seats attached to galvanized steel A-frames or arch supports. US municipal park departments concentrate orders in standardized two-bay and four-bay configurations to satisfy ASTM F1487 entrapment prevention mandates.
- Climbing Structures:Engineered frameworks combining powder-coated steel tubes, HDPE panels, and rope netting systems designed for modular expansion. European EN 1176 certification requirements drive specification of these systems in Germany, France, and Nordic countries where inclusive design mandates are most stringent.
- Slides:Single or multi-lane descent chutes formed through rotational molding or stainless steel fabrication with integrated hoods and side rails. School districts in Texas, California, and Florida specify these through cooperative purchasing agreements.
- Seesaws:Lever-action balancing equipment with spring-centered or fulcrum-based pivot mechanisms, often incorporating hand grips and foot rests molded from UV-stabilized polymers.
Swings command the established base. The steepest expansion runs through climbing structures.
Material:
Cost tier differentiation separates premium composite offerings from commodity metal and plastic alternatives, with wood occupying a contracting middle position pressured by maintenance liability concerns.
- Metal:Galvanized steel frameworks with polyester powder coating deliver structural integrity for high-traffic municipal installations. US park districts specify these for durability in freeze-thaw cycles, though resin cost volatility compresses margins for fabricators lacking captive polymer supply.
- Composite:Fiber-reinforced polymer matrices combining glass or carbon fibers with thermoset resins, engineered for coastal humidity and salt-air corrosion resistance. Municipalities in Florida and Gulf Coast states specify these to accelerate replacement cycles beyond pressure-treated timber decay timelines.
- Wood:Pressure-treated lumber or certified hardwoods requiring periodic sealing and inspection for splintering, rot, and fastener corrosion. Demand concentrates in private residential and nature-play segments.
- Plastic:Rotationally molded polyethylene components valued for UV stability, color retention, and impact absorption in modular system designs.
Metal captures volume leadership. Composite materials are climbing the fastest.
Age Group:
Application focus varies sharply: toddler equipment serves early childhood education grants, while school-aged and teenage segments align with municipal recreation budgets and competitive sports infrastructure.
- Toddlers:Low-height structures with enclosed platforms, bucket swings, and ground-level activity panels designed for 6-23 month developmental stages. US federal Head Start and state early childhood education investments concentrate procurement in Head Start centers and licensed childcare facilities.
- School-Aged Children:Elevated platforms, complex climbing networks, and multi-user apparatus engineered for 5-12 year physical development and social play patterns. Municipal park departments in metropolitan corridors drive specification through five-to-seven-year refresh mandates.
- Preschoolers:Intermediate-height equipment with graduated challenge levels bridging toddler and school-aged categories, common in church-based and private preschool installations.
- Teenagers:Fitness-focused apparatus, parkour elements, and challenge courses designed for adolescent strength training and competitive recreation, often specified through joint-use agreements between schools and municipal recreation departments.
School-aged children command the established base. Toddlers are expanding most quickly.
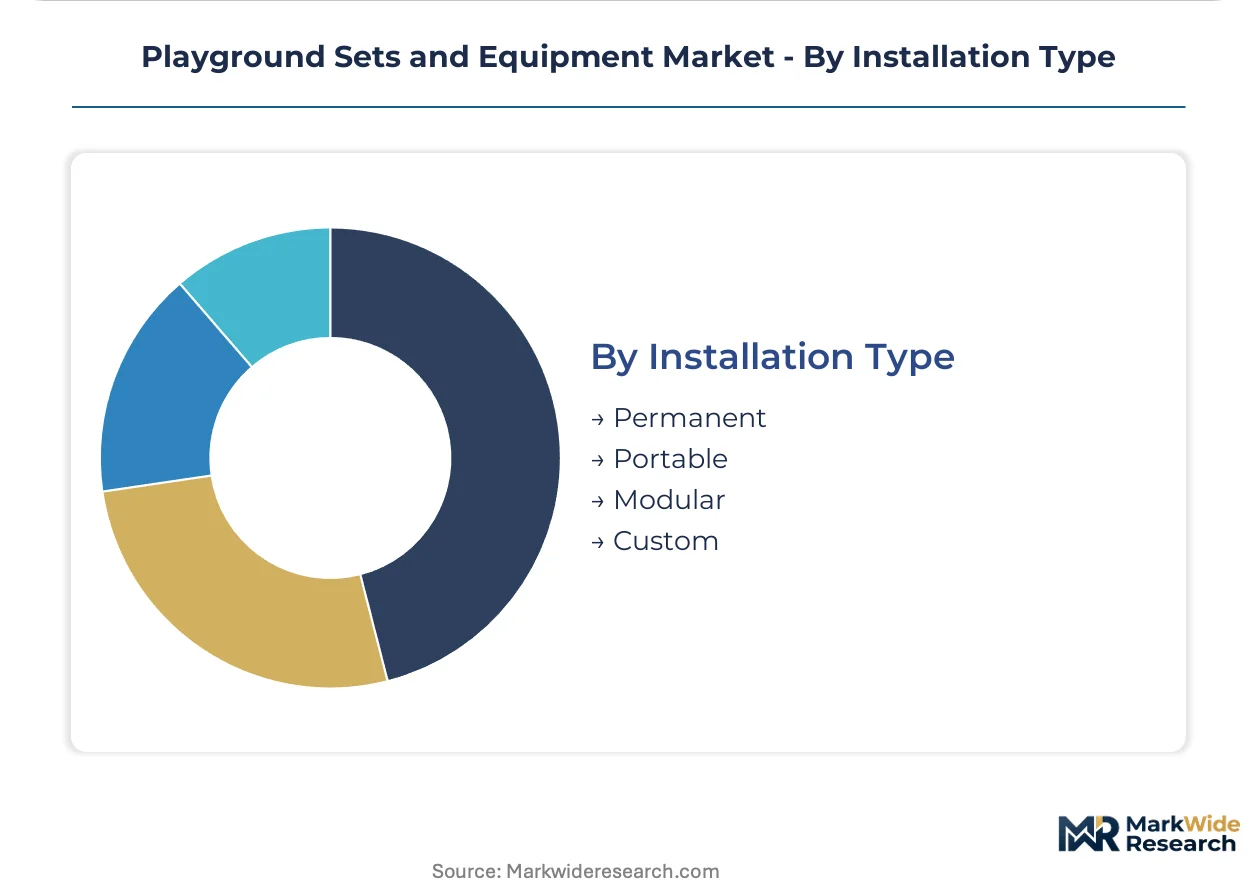
Installation Type:
Customer type segmentation separates permanent municipal installations from portable and modular systems serving private developers and urban districts with constrained footprint flexibility.
- Permanent:In-ground anchored structures with concrete footings and fixed surfacing systems, specified for durability and liability protection in public parks. US Consumer Product Safety Commission impact attenuation mandates elevate installation complexity and certified inspector requirements.
- Modular:Reconfigurable component systems enabling footprint adaptation and phased expansion across constrained urban sites. Districts in Chicago, New York, and Los Angeles specify these to maximize play value per square meter.
- Portable:Surface-mounted or weighted-base equipment relocatable without excavation, common in temporary installations and leased facilities.
- Custom:Site-specific engineered solutions incorporating thematic elements, terrain integration, or specialized accessibility features for unique municipal or institutional requirements.
Permanent installations command the established base. Modular systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US municipal buyers demonstrate the lowest price elasticity as federal infrastructure grants compress replacement cycles, while European park departments show moderate sensitivity to steel and resin volatility, and emerging market procurement remains acutely cost-constrained.
United States
Federal Head Start expansion and state-level early childhood education bonds are accelerating equipment refresh mandates from decade-long cycles to five-to-seven-year intervals. The Consumer Product Safety Commission enforces ASTM F1487 impact attenuation standards that elevate surfacing material specifications and installation costs. Texas, California, and Florida park districts aggregate demand through cooperative purchasing agreements that bypass traditional dealer networks.
Germany
Municipal park departments prioritize EN 1176-certified inclusive play structures as federal inclusion mandates expand sensory-accessible design requirements. The German Institute for Standardization administers third-party conformity assessment protocols that create compliance barriers for non-EU fabricators. Industrial concentration clusters in North Rhine-Westphalia and Bavaria where specialized engineering firms supply modular climbing systems to Nordic export markets.
France
Urban districts in Paris and Lyon specify reconfigurable equipment to maximize play value per square meter on constrained sites. The French National Agency for Food, Environmental and Occupational Health Safety enforces European accessibility act provisions that mandate tactile and auditory inclusion elements. Manufacturers in the Auvergne-Rhône-Alpes region engineer composite-material solutions for Mediterranean coastal humidity resistance.
United Kingdom
Local authority budget pressures following fiscal consolidation are extending equipment replacement timelines despite rising maintenance liability exposure. The British Standards Institution maintains EN 1176 alignment post-Brexit, preserving certification continuity for EU suppliers. Greater Manchester and West Midlands procurement consortia are consolidating vendor relationships through framework agreements that favor established notified body partnerships.
Canada
Provincial early learning infrastructure programs in Ontario and British Columbia are expanding licensed childcare facility equipment procurement. Health Canada coordinates with the Consumer Product Safety Commission on ASTM F1487 harmonization for cross-border municipal contracts. Toronto and Vancouver park boards pilot smart surfacing technology with embedded usage sensors for asset management optimization.
Playground Sets and Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding municipal procurement channels through captive polymer production and the latter competing on modular customization for constrained urban footprints. The structure rewards backward integration into rotational molding and steel fabrication while penalizing assembly-only operators exposed to resin cost volatility. Three archetypes dominate: integrated manufacturers with in-house polymer supply, engineering specialists in inclusive accessibility design, and dealer-network-dependent fabricators with broad geographic coverage. Consolidation pressure is driving cooperative purchasing aggregation and selective capacity expansion in high-growth metropolitan corridors.
Among North American integrated producers, PlayCore and Landscape Structures occupy positions defined by manufacturing depth and distribution architecture respectively, while Kompan anchors European demand through specialized engineering capabilities. PlayCore exemplifies the captive-supply archetype with multi-facility polymer production, Landscape Structures represents dealer-network scale in municipal channel dominance, and Kompan sits within the inclusive-design specialist tier serving stringent Nordic and German accessibility mandates. These three illustrate how competitive advantage rotates toward firms controlling raw material costs and certified installation protocols rather than distribution breadth alone.
| Leading Market Players |
|---|
| PlayCore |
| Kompan |
| GameTime |
| Landscape Structures |
| Playworld |
| ELI |
| Qitele |
| BigToys |
| Playcraft Systems |
| Others |
Value Network & Pricing Analysis
Captive rotational molding capacity across multiple US facilities creates scale economies that compress unit costs and elevate price floors for assembly-only competitors lacking backward integration into polyethylene production. Municipal procurement consolidation through cooperative purchasing agreements in Texas, California, and Florida concentrates buyer leverage, forcing tiered pricing structures that separate premium certified installations from economy-grade residential offerings.
Pricing Analysis
After-sales service contracts and certified inspection renewals drive lifetime value beyond initial equipment sales, with municipal park departments locking multi-year maintenance agreements alongside capital purchases. Three-tier pricing structure across premium, standard, and economy levels separates EN 1176-certified inclusive systems from ASTM F1487-compliant standard installations and unlicensed residential equipment. Cost compression in the economy tier intensifies because resin cost volatility squeezes margins for fabricators without captive polymer supply. Private developers exhibit acute price sensitivity compared to municipal buyers shielded by federal infrastructure grants.
Supply Chain Analysis
China and South Korea anchor global polyethylene resin production, while US Gulf Coast petrochemical clusters feed domestic rotational molding operations. Galvanized steel frameworks draw from Mexican and Canadian metal fabrication capacity, with powder coating services concentrated in Ohio and Pennsylvania industrial corridors. Single-source vulnerability in certified safety surfacing materials creates procurement risk when municipal fiscal-year deadlines collide with extended third-party testing timelines. Distribution runs through independent dealer networks in North America and direct municipal contracts in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal cooperative purchasing aggregation across Texas, California, and Florida shifts buyer power toward consolidated procurement consortia, fragmenting vendor relationships and compressing margins for dealer-network-dependent fabricators.
For Market Incumbents: Fortify captive polymer production capabilities and EN 1176 certification relationships to defend against emerging composite-material specialists targeting coastal humidity environments. Expand installation inspector training programs in secondary metropolitan corridors to resolve labor scarcity extending project timelines. Prioritize smart surfacing technology R&D to capture technology-forward district budgets before cost-constrained municipalities consolidate around legacy specifications. For New Entrants and Emerging Players: Anchor in modular system design for urban districts with constrained footprint flexibility, where reconfigurable climbing structures command premium positioning absent from standardized municipal contracts. Target sensory-inclusive equipment procurement funded by federal disability accommodation incentives, penetrating the fastest-expanding segment with engineering capabilities larger incumbents underweight. Pursue direct relationships with early childhood education grant administrators bypassing traditional park department procurement channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with in-house rotational molding and established European notified body relationships over assembly-only operators exposed to resin volatility. Long-term viability rests on backward integration depth and certification asset durability rather than distribution scale alone. Watch cooperative purchasing consolidation velocity as inflection indicator for margin compression severity across dealer-dependent revenue streams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive polyethylene supply insulates margins from resin cost volatility affecting assembly-only competitors. |
| EN 1176 Certification Investment | European notified body relationships unlock municipal contracts in Germany and Nordic accessibility-mandate markets. |
| Smart Surfacing Technology Development | Embedded sensor systems capture liability documentation budgets in technology-forward metropolitan park districts. |
| Installation Inspector Training Expansion | Certified crew availability resolves labor scarcity extending timelines in secondary markets beyond urban corridors. |
| Sensory-Inclusive R&D Allocation | Federal disability accommodation incentives fund auditory and tactile accessibility features commanding price premiums. |
Research Methodology
Initial hypotheses were tested against primary input from municipal procurement directors, certified playground safety inspectors, rotational molding plant managers, and early childhood education grant administrators and refined through secondary validation. Municipal budget documents, ASTM F1487 enforcement records, EN 1176 certification databases, and cooperative purchasing agreement disclosures provided triangulation anchors. Bottom-up equipment shipment estimates and top-down municipal capital expenditure aggregates converged through iterative reconciliation.
Variance decomposition across product type, material grade, age group specification, and installation permanence dimensions structured the analytical framework. CAGRs were derived from installed base refresh cycle compression and grant funding trajectory modeling. Raw material cost indices, certification timeline distributions, and labor availability metrics informed industry-specific forecast inputs throughout the projection horizon.
Decision-makers should treat outputs as directional under sustained federal infrastructure grant authorization and EN 1176 harmonization assumptions; material deviation in municipal fiscal health or regulatory enforcement intensity would warrant model refresh. Recalibration cycles align with material shifts in procurement consolidation patterns and accessibility mandate expansion timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Surfboard Market
Sports Equipment
Parallel Bars Market
Sports Equipment
Diving Board Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Gym Bag Market
Sports Equipment
Racket Sports Equipment Market
Sports Equipment
Spain Horse Riding Equipment Market
Sports Equipment
Global Skateboard Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
BMX Bikes Market
Sports Equipment
Golf Ball Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Concussion Helmets Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
Ice Hockey Stick Market