
 France Artificial Turf Market | 2026-2036
France Artificial Turf Market Size, Share, and Industry Trends Forecast 2026-2036
France Artificial Turf Market Foresight
Buyer concentration among French municipal authorities and sports club federations is consolidating, with larger procurement contracts replacing fragmented local purchases. FieldTurf leverages its installation network across French stadiums to sustain project pipeline visibility. Sport Group anchors supply through its European manufacturing footprint, while SIS Pitches specializes in elite-tier pitch certifications that differentiate its offer from commoditized alternatives.
Artificial turf comprises synthetic fiber surfaces engineered from polyethylene, polypropylene, or nylon polymers, tufted into permeable backings and often combined with infill layers to replicate natural grass play characteristics and drainage performance. The material serves commercial and institutional users requiring durable, low-maintenance ground cover for high-traffic athletic and recreational zones. Polyethylene fibers dominate installed volume due to softer hand-feel and UV stability suited to French climatic conditions, while sports fields command the largest application share though residential landscaping exhibits faster expansion as water restrictions intensify across southern départements.
France's national environmental agency enforces REACH chemical compliance and AGEC circular-economy provisions on synthetic surface producers, restricting hazardous substance content and mandating recyclability disclosures that reshape product design priorities. The French sports ministry's technical guidelines for certified playing surfaces further gate market access by requiring lab-tested shock absorption and rotational resistance metrics. Stakeholders must monitor pending EU-wide microplastic restrictions on infill materials, as these regulations will force rapid reformulation decisions across the supply base.
Market Dynamics
Municipal procurement consolidation across French metropolitan areas is compressing vendor margins while accelerating specification standardization for synthetic playing surfaces. The AGEC law's recyclability mandates and REACH chemical compliance are forcing simultaneous reformulation of fiber chemistries and backing materials.
Growth Catalysts
- Water restriction mandates:Southern French départements facing irrigation bans are converting natural grass schoolyards and municipal pitches to synthetic surfaces, creating institutional demand clusters around Marseille, Toulouse, and Montpellier.
- EU Green Deal alignment:National stadium renovation programs tied to carbon-reduction targets specify low-emission turf systems, channeling public investment toward certified sustainable installations.
- Shock-absorption certification:The French sports ministry's technical guidelines for player-safety metrics are disqualifying uncertified products, concentrating volume among compliant suppliers.
Market Restraints
- Petrochemical input volatility:Polyethylene and polypropylene resin prices fluctuate with naphtha feedstock costs, compressing margin predictability for tufting operations.
- Infill material restrictions:Pending EU-wide microplastic regulations on crumb rubber and alternative infills threaten to obsolete current product formulations without ready substitutes at scale.
- Heat retention physics:Synthetic surfaces in Mediterranean climates reach temperatures exceeding player-safety thresholds during summer months, limiting adoption for unshaded installations.
Strategic Opportunities
- Île-de-France schoolyard conversions:Paris-area municipal authorities hold multi-year replacement schedules for aging asphalt surfaces, creating predictable project pipelines for qualified installers.
- Biobased polymer integration:Converging bio-polyethylene production with existing tufting infrastructure offers pathways to AGEC-compliant products with differentiated circular-economy credentials.
- Maintenance service bundling:Long-term surface-performance contracts combining installation with scheduled rejuvenation and infill management are displacing transactional product sales in federation procurement.
Industry Challenges
- Certification timeline compression:Laboratory testing for shock absorption and rotational resistance under French sports ministry protocols extends product development cycles by 8-14 months.
- Installation labor scarcity:Specialized crews for sub-base preparation and seam welding face recruitment gaps as infrastructure project volumes expand across multiple surface types.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Artificial Turf Market |
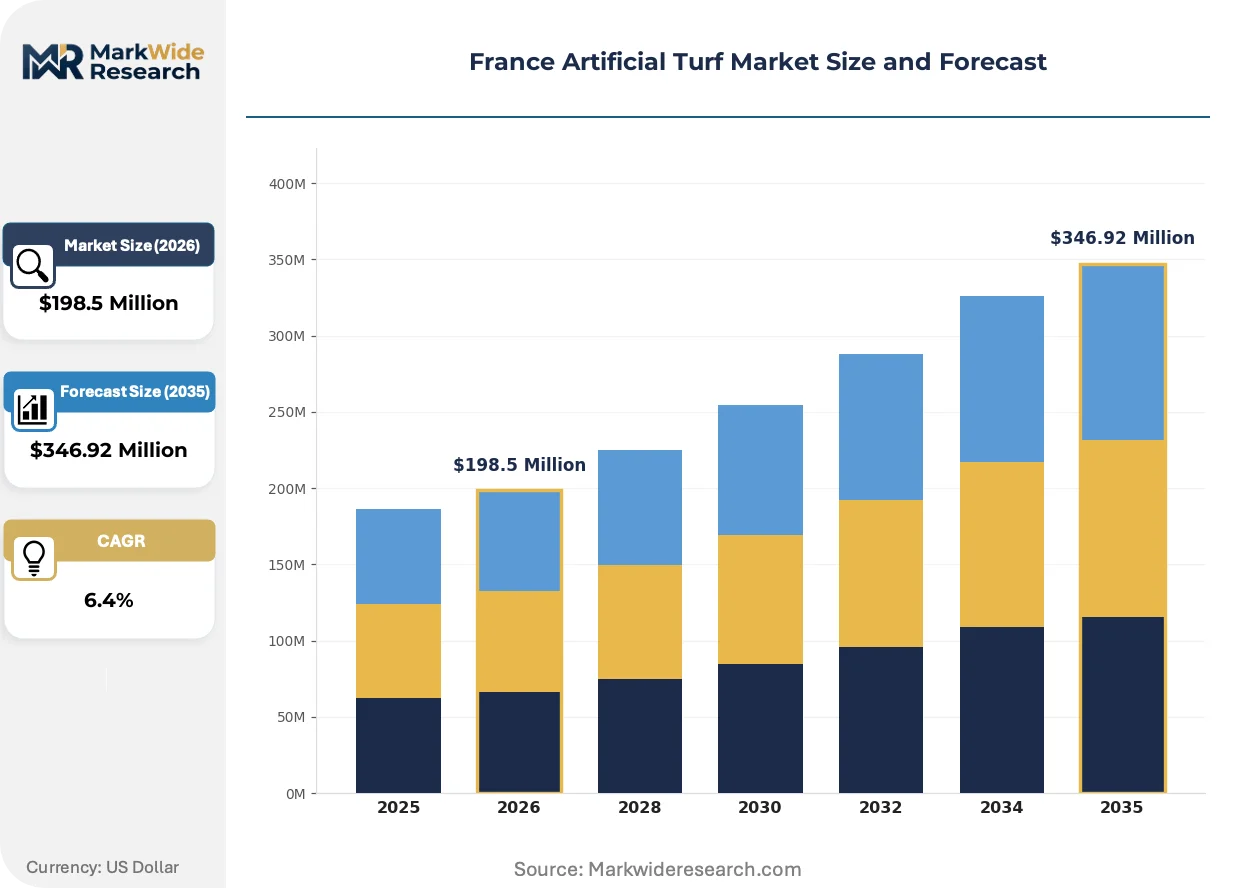
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $346.92 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, Monofilament, Texturized, Thatch Application: Sports Fields, Landscaping, Residential Lawns, Commercial Spaces, Playground Areas, Pet Facilities Installation Type: Infill, Non-Infill, Semi-Recessed, Modular Tiles End User: Educational Institutions, Government Facilities, Sports Clubs, Recreational Centers |
| Companies Covered | Tarkett, FieldTurf, Sport Group, SIS Pitches, Limonta, Victoria PLC, TenCate Grass, Domo Sports Grass, GreenFields, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Artificial Turf Market Shifts & Advancements
Material science advances and regulatory stringency are converging to redefine product specifications and procurement criteria across French synthetic surface markets. Three developments are restructuring competitive positioning.
Monofilament polyethylene fiber with integrated UV stabilizers is unifying durability and player-comfort specifications previously requiring blended fiber constructions. Municipal stadium operators in Lyon and Bordeaux are specifying these systems for high-rotation training pitches. The technology is compressing price differentiation between mid-tier and premium product lines as performance thresholds standardize.
AGEC circular-economy provisions are mandating recyclability disclosures and recycled-content minimums for synthetic surfaces sold in France. Producers must now document end-of-life processing pathways and material traceability through supply chains. Sports field applications face the tightest compliance timelines, with certification bodies expanding laboratory capacity to clear backlog.
French sports club federations are consolidating purchasing through centralized procurement frameworks that bundle multiple pitch installations into single-tender awards. Regional league offices are displacing individual club negotiations, concentrating volume among vendors with installation networks spanning multiple départements. This pattern is most visible in football and rugby governing bodies across Occitanie and Provence-Alpes-Côte d'Azur regions.
France Artificial Turf Market Segmentation
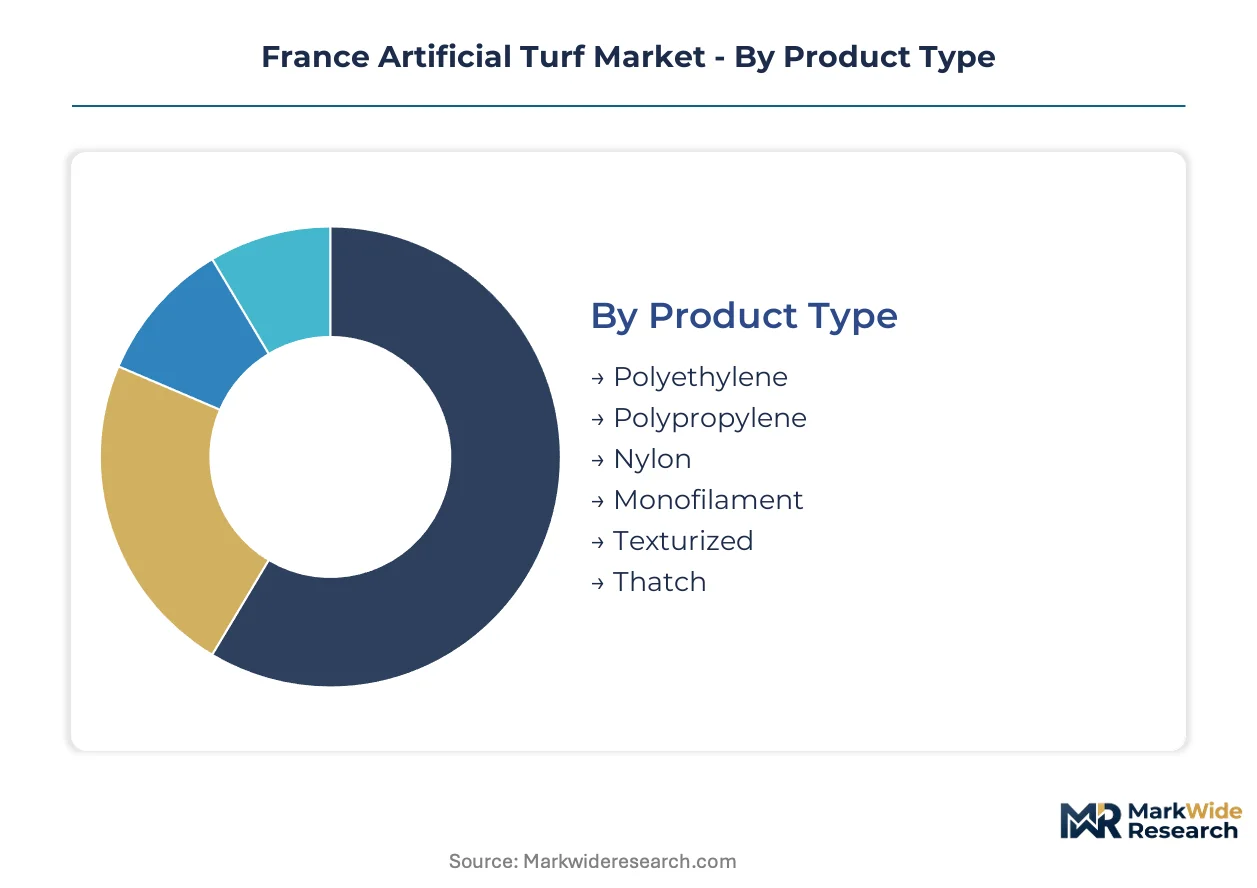
France's artificial turf market segments reflect divergent compliance burdens and specification intensities. Product chemistry determines REACH chemical testing requirements, while application type dictates whether AGEC circular-economy disclosures or sports ministry safety certifications dominate procurement criteria.
Product Type:
REACH chemical compliance and AGEC recyclability disclosures apply differentially across polymer chemistries, with fiber composition governing laboratory testing timelines and documentation burdens for market access.
- Polyethylene:Soft hand-feel and superior UV stability suit French climatic conditions from Mediterranean summers to Atlantic moisture. Demand concentrates in municipal stadium renovations across Île-de-France and schoolyard conversions in southern départements facing irrigation restrictions.
- Monofilament:Integrated UV stabilizers unify durability and player-comfort specifications previously requiring blended constructions. Lyon and Bordeaux municipal operators specify these systems for high-rotation training pitches where performance thresholds are standardizing price tiers.
- Polypropylene:Stiffer fiber structure suits landscaping applications with lower traffic intensity.
- Nylon:Highest abrasion resistance commands premium positioning for elite-tier sports installations.
- Texturized:Curled fiber construction enhances surface density for aesthetic residential applications.
- Thatch:Root-zone replication layer improves visual authenticity in landscaping deployments.
Leading the category by volume: Polyethylene. Expanding most quickly: Monofilament.
Application:
Specification intensity varies sharply across use cases, with sports ministry certification requirements creating compliance moats around athletic installations absent from aesthetic landscaping deployments.
- Sports Fields:French sports ministry protocols mandate lab-tested shock absorption and rotational resistance metrics that extend product development cycles. Federation procurement consolidation across Occitanie and Provence-Alpes-Côte d'Azur concentrates volume among certified suppliers with multi-département installation networks.
- Residential Lawns:Water restriction mandates across southern départements are accelerating conversions from natural grass. Marseille, Toulouse, and Montpellier municipal clusters drive institutional demand that suppliers are extending to adjacent residential segments through certified installer networks.
- Landscaping:Commercial aesthetic applications with moderate traffic requirements and lighter certification burdens.
- Commercial Spaces:Corporate and retail installations prioritizing visual consistency over performance metrics.
- Playground Areas:Safety-critical applications requiring fall-height certification under separate technical guidelines.
- Pet Facilities:Odor-resistant backing specifications for kennel and veterinary deployments.
Dominant by revenue: Sports Fields. Gaining share fastest: Residential Lawns.
Installation Type:
Pending EU microplastic restrictions on infill materials are forcing rapid reformulation decisions, with system architecture determining exposure to regulatory obsolescence risk.
- Infill:Crumb rubber and alternative infill layers face pending EU-wide microplastic regulations that threaten current formulations. French sports ministry shock-absorption certification requirements currently favor these systems, creating tension between compliance regimes.
- Non-Infill:Dense fiber construction eliminates infill dependency entirely. AGEC-aligned procurement frameworks in Paris-area schoolyard conversions specify these systems to preempt regulatory exposure.
- Semi-Recessed:Hybrid systems reducing infill volume while retaining performance characteristics.
- Modular Tiles:Interlocking panel systems enabling rapid deployment and reconfiguration for temporary installations.
Highest volume: Infill. Steepest expansion trajectory: Non-Infill.
End User:
Procurement consolidation patterns diverge across institutional buyer types, with centralized frameworks displacing fragmented purchasing in federations while municipal authorities retain project-level discretion.
- Sports Clubs:Regional league offices are consolidating purchasing through single-tender awards bundling multiple pitch installations. Football and rugby governing bodies are displacing individual club negotiations, concentrating volume among vendors with installation networks spanning multiple départements.
- Educational Institutions:Paris-area municipal authorities hold multi-year replacement schedules for aging asphalt schoolyard surfaces. Predictable project pipelines favor qualified installers with maintenance service bundling capabilities.
- Government Facilities:Municipal procurement standardization compresses margins while accelerating specification harmonization.
- Recreational Centers:Mixed-use facilities balancing athletic performance with general public access requirements.
Largest buyer segment by contract value: Sports Clubs. Fastest procurement consolidation: Educational Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters heavily in French metropolitan zones where municipal procurement consolidation and water restriction mandates are restructuring geographic deployment patterns for synthetic surface installations.
Île-de-France
Paris-area stadium renovations and schoolyard conversions dominate contract volume, with municipal authorities holding multi-year replacement schedules for aging asphalt surfaces. The French sports ministry's technical guidelines for certified playing surfaces gate market access through lab-tested shock absorption requirements. Installation networks concentrate around Greater Paris, where federation procurement consolidation channels volume toward qualified vendors.
Provence-Alpes-Côte d'Azur
Irrigation bans across southern départements are accelerating conversions from natural grass schoolyards and municipal pitches to synthetic surfaces. The AGEC law on circular economy mandates recyclability disclosures that reshape product design priorities for suppliers serving this zone. Marseille and Nice municipal clusters drive institutional demand that extends to adjacent residential segments through certified installer networks.
Occitanie
Regional league offices for football and rugby governing bodies are consolidating purchasing through single-tender awards bundling multiple pitch installations. EU REACH framework compliance on chemical safety restricts hazardous substance content in fiber chemistries. Toulouse and Montpellier anchor demand concentration, with water restriction mandates intensifying across the region's Mediterranean climate zones.
Auvergne-Rhône-Alpes
Lyon municipal operators specify monofilament polyethylene systems for high-rotation training pitches where performance thresholds are standardizing price tiers. Pending EU-wide microplastic regulations on infill materials force rapid reformulation decisions among suppliers active in this cluster. Grenoble and Saint-Étienne expand the geographic footprint of federation procurement consolidation.
Nouvelle-Aquitaine
Bordeaux municipal stadium operators drive specification adoption for integrated UV stabilizer technologies that unify durability and player-comfort metrics. The French national environmental agency enforces AGEC circular-economy provisions mandating end-of-life processing pathway documentation. Coastal and inland départements balance sports field certification requirements with residential landscaping demand from water-conscious property owners.
France Artificial Turf Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biobased polymer integration and maintenance service bundling as differentiation vectors. The vendor base stratifies across three archetypes: European manufacturing footprint holders, elite-tier pitch certification specialists, and installation-network-dependent project pipeline managers. Consolidation pressures intensify as municipal procurement standardization compresses margins and accelerates specification harmonization. Dominant competitive moves include strategic partnerships for bio-polyethylene supply chain access and geographic expansion through maintenance service contract anchoring.
Within the European manufacturing tier, Tarkett and Sport Group exemplify scale-driven positioning through continental production footprints that anchor supply security for French municipal buyers. FieldTurf represents the installation-network archetype, with stadium project visibility sustained through deployment density across French metropolitan areas. SIS Pitches occupies the certification-specialist position, differentiating through elite-tier pitch credentials that command premium positioning in federation procurement frameworks. These three patterns—manufacturing scale, installation reach, and certification intensity—structure competitive rivalry as AGEC compliance timelines and REACH chemical testing requirements extend product development cycles.
| Leading Market Players |
|---|
| Tarkett |
| FieldTurf |
| Sport Group |
| SIS Pitches |
| Limonta |
| Victoria PLC |
| TenCate Grass |
| Domo Sports Grass |
| GreenFields |
| Others |
Supply & Pricing Matrix
Municipal procurement consolidation across French metropolitan areas is compressing vendor margins while forcing supply base rationalization toward larger polymer resin offtakers with certified installation networks. This buyer-side concentration is reshaping how tufting operations source polyethylene and polypropylene feedstock, with volume commitments increasingly determining pricing access.
Pricing Analysis
High-volume municipal contracts trade margin for pipeline visibility, while smaller federation installations retain pricing power through certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates elite-tier pitch certifications from commoditized landscaping alternatives. Cost compression in standard-tier municipal segments is intensifying because AGEC compliance timelines extend product development cycles. Educational institutions exhibit highest price sensitivity due to multi-year replacement schedules, whereas professional sports federations prioritize performance certification over unit economics.
Supply Chain Analysis
Freight costs from German and Belgian polymer resin producers to French tufting operations are amplifying geographic sourcing advantages for continental European manufacturers. Raw material supply draws from Saudi Arabian naphtha derivatives, German chemical processing clusters, and Italian fiber extrusion specialists. Single-source vulnerability concentrates in specialized UV stabilizer additives subject to REACH authorization delays. Distribution runs through certified installer networks that bundle sub-base preparation with seam welding services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's artificial turf market is consolidating into a three-tier vendor structure where AGEC compliance investments are forcing sub-scale producers toward exit or acquisition. Municipal procurement standardization is the primary pressure eliminating fragmented local suppliers.
For Market Incumbents: Deepen backward integration into bio-polyethylene supply chains to secure AGEC-aligned circular-economy credentials before recyclability mandates tighten. Expand laboratory certification capacity to compress 8-14 month testing timelines that currently constrain product launch velocity. Anchor maintenance service bundling capabilities to displace transactional competitors in federation procurement frameworks. For New Entrants and Emerging Players: Residential lawn installers in southern French départements facing irrigation bans represent the most penetrable buyer archetype underserved by incumbent stadium-focused networks. Target Marseille and Toulouse municipal clusters with non-infill system offerings that preempt pending EU microplastic restrictions. Pursue certified installer partnerships rather than direct manufacturing scale to bypass capital-intensive tufting infrastructure. For Investors and Strategic Acquirers: The window for entry favors installation-network operators with multi-département coverage and maintenance contract anchoring. Mid-sized French turf installers with established federation relationships offer viable acquisition profiles. Monitor EU microplastic regulatory finalization as the critical inflection signal determining which infill-dependent product portfolios face obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Biobased Polymer Integration | AGEC compliance positions producers ahead of circular-economy mandates in French institutional procurement. |
| Maintenance Service Bundling | Long-term performance contracts displace transactional sales in federation and municipal tender frameworks. |
| Certification Laboratory Investment | In-house shock absorption testing compresses product development cycles by 8-14 months under French sports ministry protocols. |
| Installer Network Expansion | Multi-département coverage qualifies vendors for consolidated federation procurement across Occitanie and Provence-Alpes-Côte d'Azur. |
| Non-Infill System Development | Eliminates regulatory exposure from pending EU microplastic restrictions on crumb rubber alternatives. |
Research Methodology
Document review covered customs trade databases, EU REACH registration filings, and French municipal procurement records, complemented by interviews with synthetic surface plant managers, sports federation procurement directors, and certified installation contractors. Secondary validation drew from AGEC implementation guidance, French sports ministry technical bulletins, and polymer resin customs data. Bottom-up volume estimates triangulated against top-down market sizing from construction project pipelines.
Cross-referencing historical installation volumes with primary panel input on replacement schedules and specification shifts anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include polymer chemistry, application type, installation architecture, and end-user procurement structure. CAGRs derived from fitted trend analysis incorporating municipal budget allocation patterns and regulatory compliance timeline impacts.
Revisions become necessary when EU microplastic restrictions on infill materials materialize with accelerated enforcement timelines, or when REACH chemical authorization delays extend beyond modeled product development cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Parallel Bars Market
Sports Equipment
Ergonomic Strap Systems Market
Sports Equipment
Starting Blocks Market
Sports Equipment
Sports Devices Market
Sports Equipment
Bicycle Shoe Market
Sports Equipment
Ice Hockey Stick Market
Sports Equipment
China Sports Optic Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Badminton Equipment and Products Market
Sports Equipment
Rowing Oars Market
Sports Equipment
Sponge Wrestling Mat Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Agility Ladders Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Skydiving Equipment Market
Sports Equipment
Rubber Fitness Flooring Market