
 Air Cushion Basketball Shoes Market | 2026-2036
Air Cushion Basketball Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cushion Basketball Shoes Market Insights
The premium-commodity split in air cushion basketball footwear is rebalancing as performance-grade units separate sharply from mass-market alternatives on cushioning density, thermoplastic urethane grade, and stitch-count tolerances. Nike leverages proprietary Zoom Air units and carbon-fiber shanks to command top-tier positioning, while Li-Ning anchors its portfolio with domestically sourced TPU bladders and regionally tuned lasts. Anta competes through aggressive backward integration into midsole molding facilities across Fujian province.
Air cushion basketball shoes are athletic footwear incorporating pressurized gas or foam-encapsulated chambers within the midsole to attenuate vertical ground reaction forces during jumping and cutting maneuvers; these systems typically operate at internal pressures between fifteen and twenty-five psi and rely on thermoplastic films welded into sealed pods. The primary commercial purpose is to reduce tibial and patellar load during repetitive plyometric activity, thereby extending playable career duration for competitive and recreational users. High-Top configurations dominate unit volume among organized league participants seeking combined ankle stabilization, while the Athletes end-user segment captures disproportionate margin through sponsorship-linked limited releases and custom orthotic compatibility. Synthetic uppers now lead material mix for their weldability and weight reduction versus full-grain leather alternatives.
REACH compliance in the European Union and GB standards administered by SAMR in China both mandate restricted substance thresholds in outsole rubber and adhesive formulations, directly influencing supplier qualification and batch-testing costs for export-oriented factories. The US Consumer Product Safety Commission monitors mechanical failure rates in pressurized cushioning systems through incident reporting databases, creating liability exposure for brands with field degradation issues. Stakeholders must monitor evolving biomechanical research on energy return coefficients versus injury prevention claims, as regulatory scrutiny on performance marketing tightens across major jurisdictions.
Market Dynamics
REACH compliance and China's GB standards are bifurcating supplier bases, forcing dual-certification investments that favor midsole molders with captive testing labs while marginalizing smaller TPU bladder converters lacking batch-traceability infrastructure.
Growth Catalysts
- Recreational league expansion:Amateur basketball participation in China's tier-two cities is generating volume orders for regionally tuned lasts that accommodate wider forefoot anatomies.
- Phthalate-free compound mandates:ECHA's restricted substance list is accelerating R&D into bio-based thermoplastic urethane alternatives that maintain weld seam integrity at 20 psi operating pressure.
- Carbon-fiber shank integration:Torsional plate technology is migrating from professional sponsorship tiers to mass-market high-tops, reducing midfoot fatigue during lateral cutting.
Market Restraints
- TPU film supply concentration:Biaxially oriented thermoplastic urethane membrane production clusters in Fujian and Zhejiang provinces, exposing brands to regional logistics disruptions.
- Pressurized pod failure liability:The US Consumer Product Safety Commission's incident reporting database creates retroactive exposure for field degradation in gas-chamber units.
- Biomechanical claim scrutiny:Energy return coefficient marketing faces tightening substantiation requirements from national advertising regulators across multiple jurisdictions.
Strategic Opportunities
- Custom orthotic compatibility:Removable sockliner architectures with adjustable arch heights are opening podiatrist-channel distribution for post-injury rehabilitation segments.
- SAMR green certification:China's eco-design standards for footwear create preferential procurement status for brands with verified recycled-content outsoles.
- Direct-to-consumer 3D scanning:Mobile foot-mapping applications are enabling made-to-measure midsole cavity geometries without traditional retail inventory risk.
Industry Challenges
- Weld technician scarcity:Radio-frequency sealing of thermoplastic films requires specialized operators whose training pipelines lag behind molding capacity expansion.
- Dual-certification testing costs:Simultaneous REACH and GB standard compliance demands redundant batch analysis, compressing margin on sub-$120 retail price points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cushion Basketball Shoes Market |
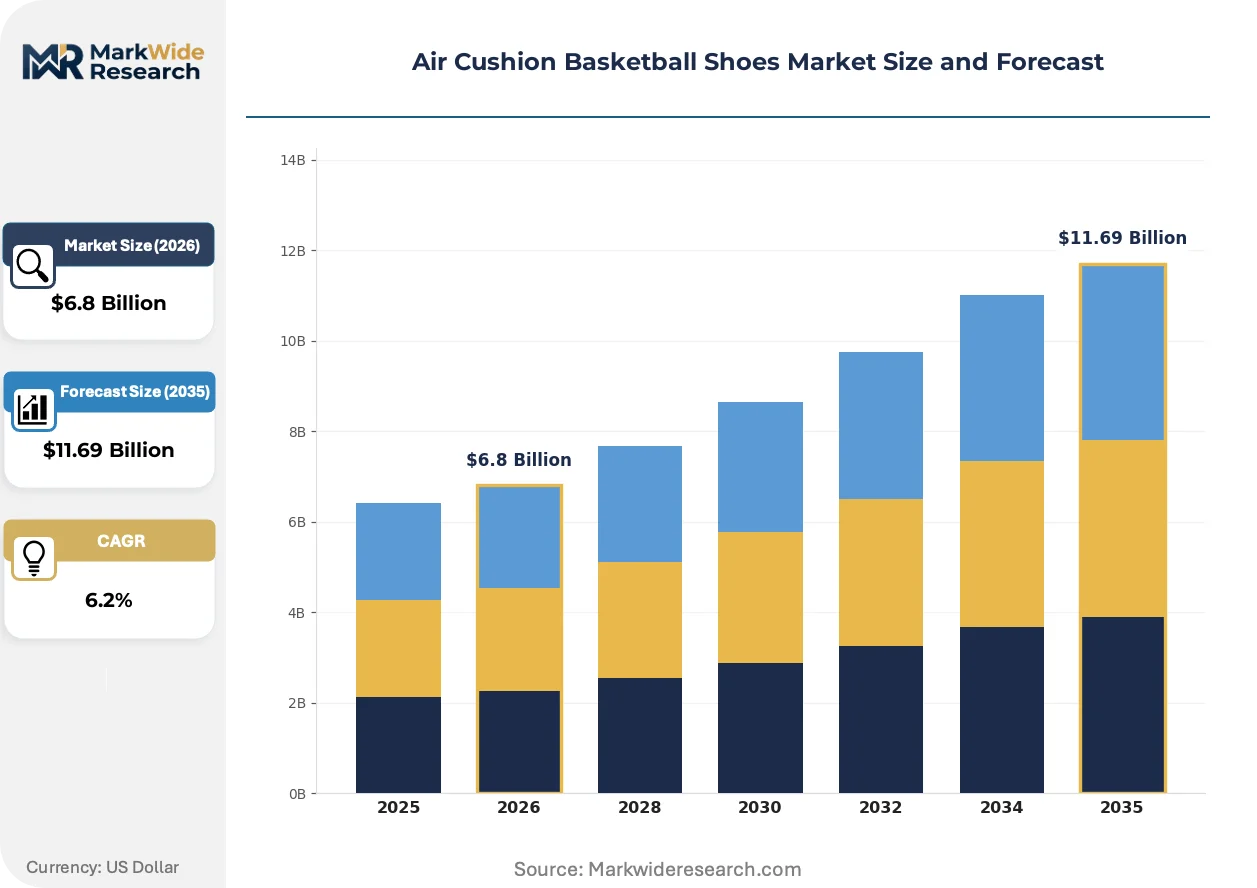
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Top, Low-Top, Mid-Top, Ankle Support End User: Men, Women, Kids, Athletes Material: Mesh, Leather, Synthetic, Rubber Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Nike, adidas, Under Armour, Li-Ning, PEAK, 361 Degrees, Anta, Jordan Brand, Reebok, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cushion Basketball Shoes Market Trends and Innovations
Digital manufacturing workflows and regulatory disclosure requirements are compressing product development cycles while fragmenting the traditional wholesale model into hybrid direct-retail ecosystems.
Modular air chamber systems is decentralizing repair and replacement economics across the footwear lifecycle. Professional teams and collegiate programs now specify field-replaceable cushioning pods rather than full-midsole replacement. This architecture is decentralizing aftermarket revenue from authorized service centers toward third-party pod suppliers with compatible weld geometries.
EU Green Deal due diligence rules are mandating supply chain carbon intensity disclosure for imported footwear. Outsole rubber compounders must now document Scope 3 emissions from synthetic polymer feedstocks. High-volume manufacturers with vertically integrated compounding facilities are absorbing compliance costs more efficiently than contract-dependent brands.
Specialty basketball retailers are unbundling fitting services from inventory carrying risk. Players now book motion-capture gait analysis sessions at flagship stores, then order configured units through brand-owned channels. This behavior is most pronounced in Shanghai and Shenzhen, where mall operators have renegotiated lease structures to accommodate showroom-only footprints with minimal backstock.
Air Cushion Basketball Shoes Market Segmentation
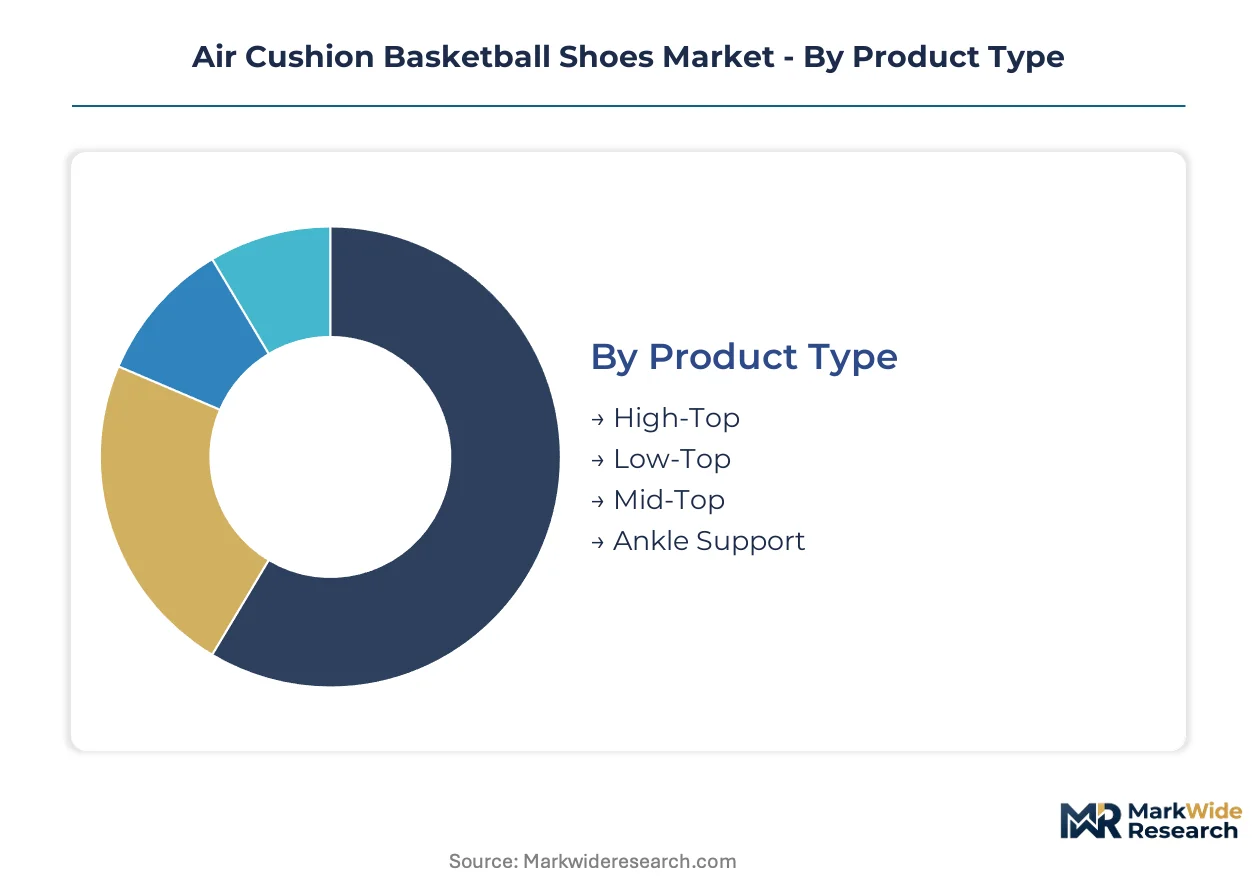
Air cushion basketball shoes fragment across four distinct dimensions that govern manufacturing configuration, margin capture, and channel strategy. Each segmentation axis imposes specific tooling investments and regulatory compliance burdens on suppliers.
Product Type:
Supply concentration in high-top tooling clusters across Fujian province dictates competitive positioning for this category.
- High-Top:Extended collar construction integrates ankle stabilization with pressurized midsole chambers. Organized league participants in China's tier-two cities drive procurement volumes for wide-forefoot anatomical lasts.
- Low-Top:Cut-down upper reduces material input costs while preserving full-length Zoom Air or equivalent cushioning systems. Recreational players seeking court feel over joint protection concentrate demand in North American urban markets.
- Mid-Top:Hybrid collar height balances mobility and support for transitional athletes.
- Ankle Support:Reinforced heel counters and external brace compatibility target post-injury rehabilitation segments.
High-Top absorbs the bulk of installed capacity; Low-Top is expanding most quickly.
End User:
Application-specific biomechanical requirements separate professional-grade specifications from mass-market tolerances.
- Men:Standard width lasts dominate production runs with established mold libraries. Amateur league expansion across China's interior provinces sustains volume throughput for domestic brands.
- Athletes:Custom orthotic compatibility and sponsorship-linked limited releases command disproportionate margin. Carbon-fiber shank integration and thermoplastic urethane grade differentiation separate this tier from commercial alternatives.
- Women:Narrower heel-to-ball ratios require dedicated last development with slower amortization curves.
- Kids:Growth-accommodating sizing and simplified lacing systems prioritize parental purchase triggers over performance metrics.
Men's specifications anchor current manufacturing schedules; Athletes' custom configurations are climbing the fastest.
Material:
REACH compliance and GB standards bifurcate supplier qualification based on chemical disclosure capabilities.
- Synthetic:Thermoplastic weldability and weight reduction versus leather alternatives now lead professional-tier construction. Radio-frequency sealing of synthetic uppers to TPU midsole units requires specialized technician training pipelines.
- Mesh:Breathable knit constructions reduce thermal load during extended play sessions. Regional humidity differentials between Guangdong and Jiangsu provinces influence material selection for domestic distribution.
- Leather:Full-grain uppers persist in heritage-positioned retro releases with limited volume.
- Rubber:Outsole compounds face dual-certification testing costs for phthalate-free formulations under ECHA restrictions.
Synthetic uppers command the majority of compound purchasing; Mesh constructions are gaining share fastest.
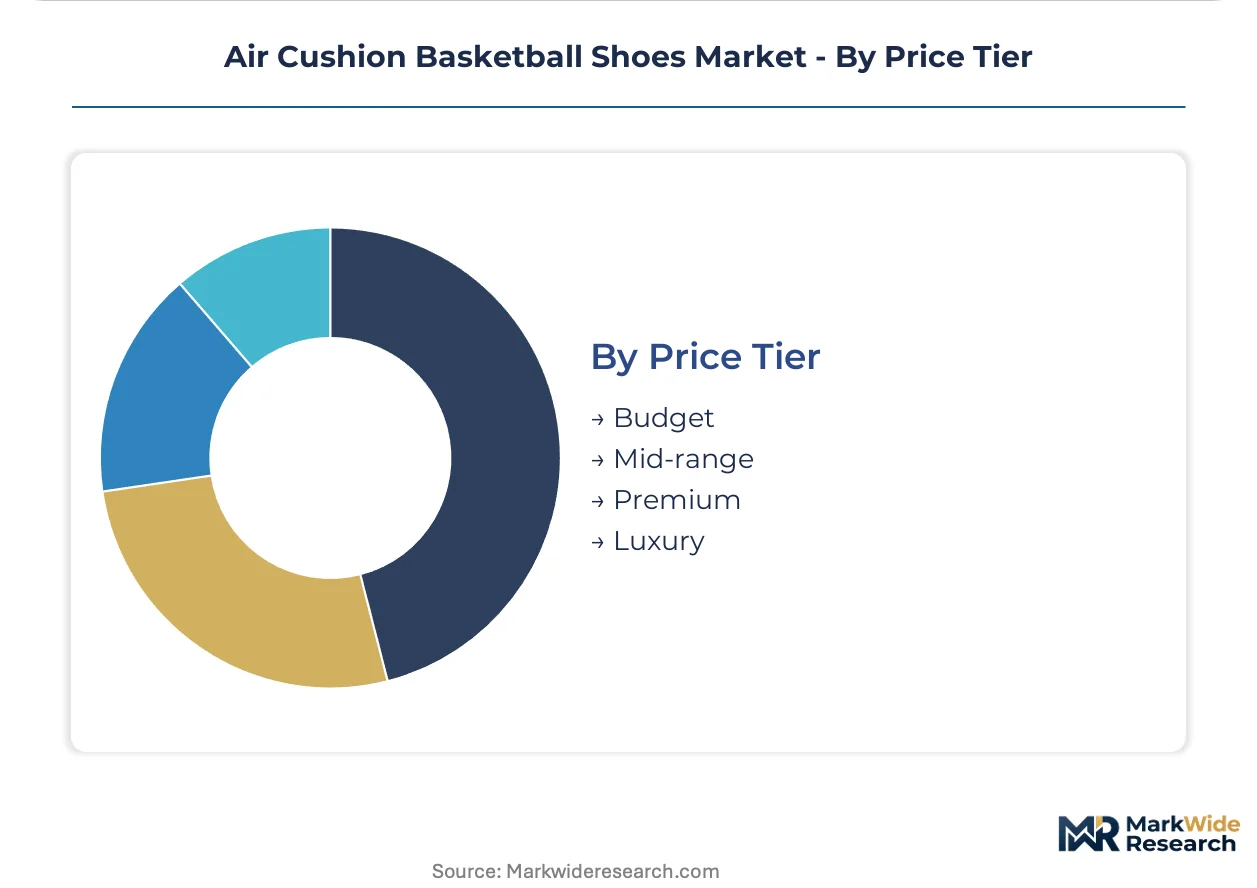
Price Tier:
Margin compression at sub-$120 retail points forces backward integration decisions among contract manufacturers.
- Premium:Proprietary air unit technologies and carbon-fiber torsional plates justify elevated price positioning. Nike's Zoom Air units and Li-Ning's domestically sourced TPU bladders compete through differentiated weld geometries and pressure tolerances.
- Luxury:Limited releases with verified recycled-content outsoles target SAMR green certification preferential procurement status. Direct-to-consumer 3D scanning integration enables made-to-measure midsole cavity geometries without inventory risk.
- Mid-range:Carbon-fiber shank migration from professional tiers sustains feature parity at reduced material grades.
- Budget:Simplified bladder architectures and regional logistics exposure from Fujian-Zhejiang supply concentration constrain quality consistency.
Premium tier absorbs dominant R&D investment; Luxury limited releases are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quanzhou anchors manufacturing gravity for air cushion basketball footwear, hosting dense clusters of midsole molding facilities and TPU bladder converters that supply both domestic Chinese labels and export-oriented contract producers.
China
Amateur league expansion across tier-two cities like Chengdu and Xi'an generates volume orders for wide-forefoot anatomical lasts. SAMR's GB standards on restricted substances in footwear materials mandate batch-traceability infrastructure that favors larger molders with captive testing labs. Fujian province's vertical integration into radio-frequency sealing equipment sustains cost advantages for synthetic upper construction.
United States
Recreational players in North American urban markets concentrate demand for low-top configurations prioritizing court feel over joint protection. The Consumer Product Safety Commission's incident reporting database on pressurized cushioning failures creates liability exposure that shapes warranty terms and field monitoring protocols. Los Angeles and New York City serve as launch markets for limited athlete-tier releases with custom orthotic compatibility.
Germany
REACH compliance on phthalate-free thermoplastic urethane compounds drives R&D investment into bio-based alternatives maintaining weld seam integrity. ECHA's restricted substance list forces dual-certification testing for brands exporting from Asian contract manufacturers. Bavaria's technical universities collaborate with footwear brands on biomechanical validation of energy return coefficient claims.
Japan
Specialty basketball retailers in Tokyo and Osaka unbundle fitting services from inventory carrying risk through motion-capture gait analysis showrooms. METI's support for digital manufacturing workflows accelerates adoption of 3D foot scanning for made-to-measure midsole geometries. Kansai region's precision molding heritage supplies high-grade carbon-fiber shank components for professional-tier specifications.
South Korea
Seoul's sneaker resale ecosystem creates aftermarket price discovery mechanisms for limited athlete-tier releases. MFDS monitoring of chemical safety in imported athletic footwear influences supplier qualification criteria for domestic distributors. Busan's port infrastructure handles bulk thermoplastic urethane film imports from Fujian and Zhejiang production clusters.
Air Cushion Basketball Shoes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where backward integration into midsole molding separates margin capture from brand licensing. The vendor base concentrates around three strategic archetypes: vertically integrated domestic champions with captive Fujian facilities, multinational sportswear houses leveraging proprietary air unit patents, and specialty contractors serving podiatrist-channel distribution. Competitive intensity manifests through carbon-fiber shank integration races at mass-market price points and direct-to-consumer 3D scanning platform deployment.
Among multinational sportswear houses, Nike and adidas occupy positions defined by proprietary cushioning technologies and athlete sponsorship networks. Li-Ning anchors the domestic Chinese tier through regionally tuned lasts and vertically controlled TPU bladder supply. Anta exemplifies aggressive backward integration strategy with in-house molding capacity across Fujian province. These three patterns—patent-protected air units, domestic supply chain control, and manufacturing asset ownership—represent the dominant competitive configurations shaping procurement relationships and retail margin distribution.
| Leading Market Players |
|---|
| Nike |
| adidas |
| Under Armour |
| Li-Ning |
| PEAK |
| 361 Degrees |
| Anta |
| Jordan Brand |
| Reebok |
| Others |
Pricing and Supply Chain Analysis
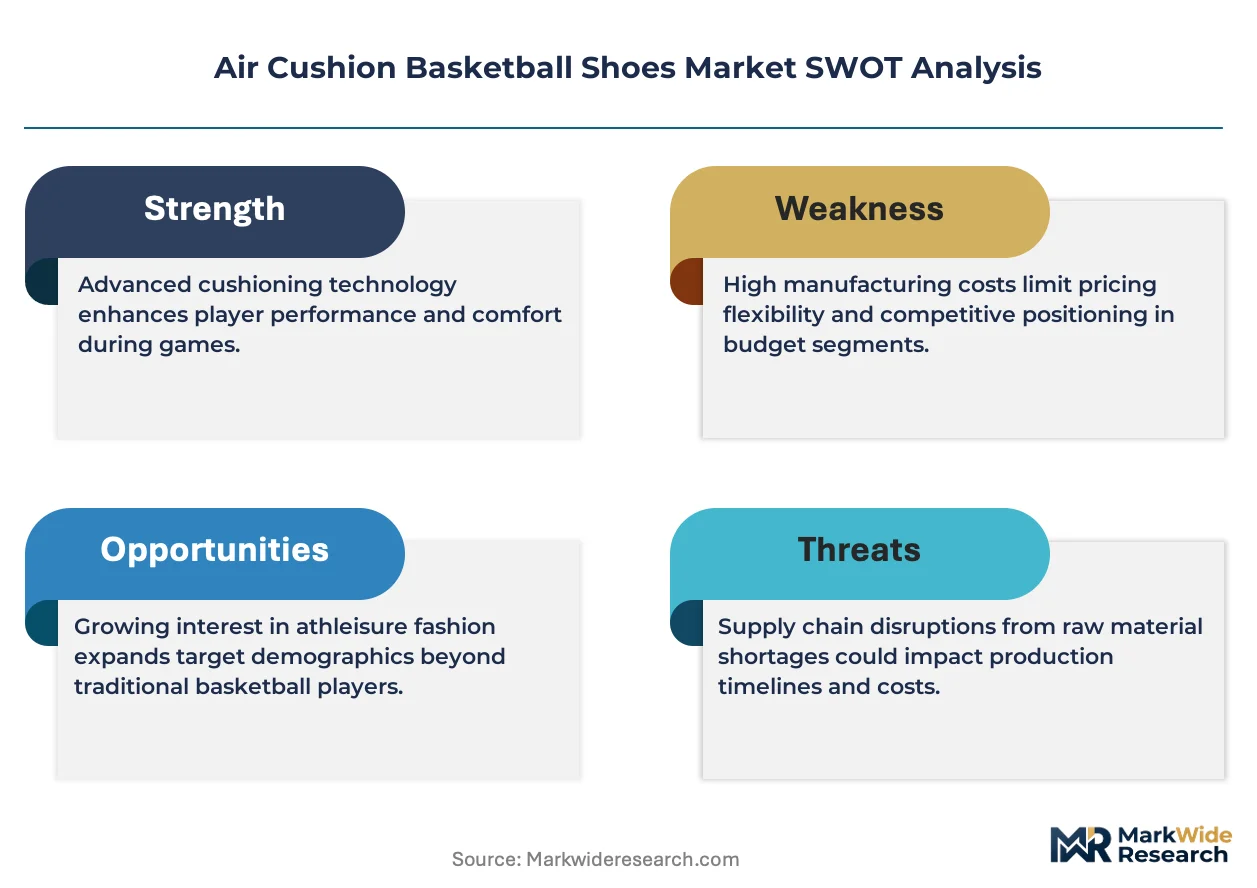
Captive TPU bladder production across Fujian province anchors both cost position and pricing power for air cushion basketball footwear manufacturers, with backward integration into radio-frequency sealing equipment insulating integrated players from margin erosion while contract-dependent brands absorb dual-certification testing burdens.
Pricing Analysis
Energy return coefficient performance anchors value-based pricing tiers across the market. Three-tier pricing structure across premium, standard, and economy levels separates proprietary Zoom Air-style units from domestically sourced TPU alternatives and simplified bladder architectures. Cost compression in sub-$120 retail tiers intensifies because redundant REACH and GB batch analysis compresses margin on volume orders. Amateur league participants in China's interior provinces exhibit highest price sensitivity, while professional athletes seeking custom orthotic compatibility demonstrate lowest.
Supply Chain Analysis
Dual-sourcing mandates from export-oriented brands require simultaneous qualification of Fujian and Zhejiang TPU film suppliers. Biaxially oriented thermoplastic urethane membrane production clusters in these provinces alongside carbon-fiber shank component manufacturing in Japan's Kansai region. Single-source vulnerability concentrates in weld technician training pipelines lagging behind molding capacity expansion. Distribution runs through hybrid direct-retail ecosystems with flagship showroom footprints in Shanghai and Shenzhen feeding brand-owned fulfillment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where dual-certification compliance costs force smaller TPU bladder converters without batch-traceability infrastructure toward exit or acquisition.
For Market Incumbents: Cement proprietary air unit patent positions through accelerated R&D into bio-based thermoplastic urethane alternatives maintaining weld seam integrity at operating pressure. Lock in podiatrist-channel distribution for post-injury rehabilitation segments before specialty contractors capture orthotic-compatible architectures. Carbon-fiber shank integration races at mass-market price points represent the immediate threat requiring capacity addition response. For New Entrants and Emerging Players: Direct-to-consumer 3D scanning platforms offer technology-first wedge into made-to-measure midsole cavity geometries without traditional retail inventory risk. Target China's tier-two city amateur leagues with regionally tuned wide-forefoot lasts underserved by multinational sportswear houses. Podiatrist-channel distribution for custom orthotic compatibility provides the most penetrable go-to-market angle with established referral economics. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated domestic champions seeking captive TPU bladder supply. Midsole molders with captive testing labs and SAMR green certification status demonstrate strongest five-to-ten year viability within regulatory tightening trajectories. Watch ECHA restricted substance list expansion velocity as the inflection indicator for bio-based compound R&D returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into TPU Bladder Production | Captive Fujian molding capacity insulates margin from dual-certification cost compression. |
| Bio-Based Thermoplastic Urethane R&D Program | ECHA phthalate-free mandates accelerate returns on REACH-compliant compound innovation. |
| Direct-to-Consumer 3D Scanning Platform Launch | Mobile foot-mapping applications eliminate inventory risk for made-to-measure geometries. |
| Podiatrist-Channel Distribution Partnership | Post-injury rehabilitation segments command premium pricing through orthotic compatibility. |
| SAMR Green Certification Achievement | Verified recycled-content outsoles unlock preferential procurement status in Chinese public tenders. |
Research Methodology
Independent corroboration across midsole molding facility operators, TPU bladder converter technical directors, and specialty basketball retail category managers underwrites the qualitative findings. Primary fieldwork incorporated structured interviews with procurement leads at export-oriented contract manufacturers, brand-side sustainability officers navigating EU Green Deal due diligence rules, and radio-frequency sealing equipment technicians. Secondary validation drew from SAMR GB standards documentation, ECHA restricted substance list updates, US Consumer Product Safety Commission incident reporting databases, and customs records of thermoplastic urethane film trade flows. Bottom-up unit economics from Fujian province production clusters were triangulated against top-down market sizing from athletic footwear import statistics.
Rate-of-change decomposition across the projection horizon separates volume expansion from value capture dynamics. The analytical framework models product type segmentation (high-top, low-top, mid-top, ankle support), end-user categories (men, athletes, women, kids), material composition (synthetic, mesh, leather, rubber), and price tier stratification. CAGRs were derived from elasticity-adjusted demand curves incorporating amateur league participation growth in China's tier-two cities and carbon-fiber shank technology migration patterns. Key forecast inputs include weld technician training pipeline throughput and REACH compliance cost trajectories for phthalate-free compound formulations.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting Fujian-Zhejiang logistics corridors, breakthrough energy return technologies displacing pressurized gas chamber architectures, and macroeconomic contraction in Chinese consumer discretionary spending. Deviation in dual-certification testing cost inflation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Golf Club Grips Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
Winter Sports Equipment Market
Sports Equipment
Global Weighted Hula Hoop Market
Sports Equipment
Alpine Ski Equipment Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
Golf Club Market
Sports Equipment
Ladderball Market
Sports Equipment
Gym Bag Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Surface Water Sports Equipment Market
Sports Equipment
Sports Mouthguard Market
Sports Equipment
Europe Archery Equipment Market