
 Automotive Battery Recycling Market | 2026-2036
Automotive Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Recycling Market Insights
EU Battery Regulation is decoupling compliance costs from virgin material sourcing, forcing recyclers to prove recovery rates for lithium, cobalt, and nickel. Umicore leverages pyrometallurgical expertise to dominate European cathode precursor production. Redwood Materials anchors its position through backward integration into battery collection networks across North America. Li-Cycle Corp. differentiates via hydrometallurgical processes that yield battery-grade lithium carbonate without smelting.
Automotive battery recycling encompasses the collection, dismantling, and material recovery of spent vehicle traction and starter batteries, typically targeting cathode metals above 95% purity through thermal or chemical separation. The primary purpose is closing the loop between end-of-life batteries and new cell manufacturing, reducing extraction dependency. Lithium-ion recycling now leads volume growth as EV penetration deepens, while lead-acid recycling remains structurally mature with thinner margin pools. Hydrometallurgical routes are expanding fastest due to lower energy intensity and higher selective recovery rates versus pyrometallurgical alternatives. OEMs represent the most concentrated end-user segment, with automakers securing offtake agreements to guarantee recycled feedstock for their gigafactories.
The EPA governs hazardous waste classification for spent batteries under RCRA, while the EU Battery Regulation mandates recycled content disclosures and collection targets. China's SAMR enforces GB standards for recycled material quality in domestic battery supply chains. Stakeholders must monitor how these frameworks evolve to determine where to build preprocessing capacity versus full refining operations.
Market Dynamics
Closed-loop material recovery programs are compressing supply chains between automakers and recyclers, as battery-grade metal offtake agreements replace spot-market purchasing for cathode precursor supply.
Growth Catalysts
- EU Battery Regulation:Mandated recycled content thresholds for lithium, cobalt, and nickel are pulling preprocessing capacity into European industrial corridors.
- EV traction battery volumes:Deepening electric vehicle penetration is expanding feedstock availability for hydrometallurgical recovery routes targeting battery-grade purity.
- Germany's recycling infrastructure buildout:Dedicated preprocessing hubs in the Rhine-Ruhr region are anchoring cathode metal refining clusters for continental supply.
Market Restraints
- Spent battery collection fragmentation:Dispersed end-of-life vehicle stocks across rural North American territories inflate reverse logistics costs for centralized refiners.
- Pyrometallurgical energy intensity:Smelting routes face margin pressure from European natural gas price volatility and carbon border adjustment exposure.
- Black mass trade restrictions:China's SAMR enforcement of GB quality standards limits export outlets for unrefined intermediate materials.
Strategic Opportunities
- US Inflation Reduction Act:Domestic content credits for recycled critical minerals are incentivizing North American cathode precursor production investments.
- Direct recycling technologies:Cathode rejuvenation without full elemental separation offers pathway to lower-cost battery-grade material for stationary storage applications.
- Automaker collection networks:Backward integration into dealer-based retrieval systems secures feedstock visibility independent of third-party aggregators.
Industry Challenges
- Battery-grade lithium carbonate certification:Hydrometallurgical refiners face extended qualification timelines with cell manufacturers demanding traceable impurity profiles.
- Fire suppression retrofitting:Preprocessing facilities handling high-nickel chemistries require capital-intensive thermal runaway containment systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Recycling Market |
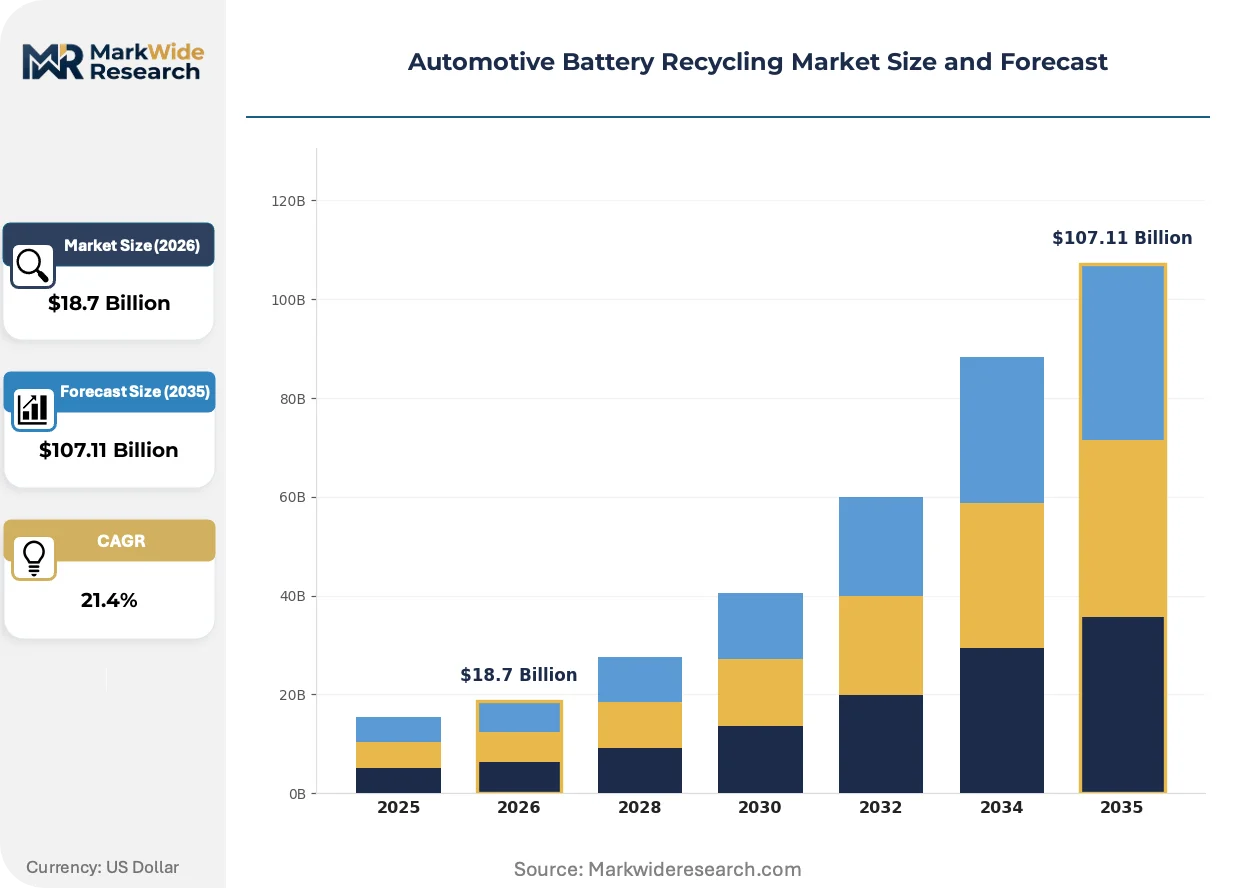
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $107.11 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Flow Batteries Recycling Process: Pyrometallurgical, Hydrometallurgical, Direct Recycling, Mechanical Processing End User: OEMs, Aftermarket Providers, Scrap Dealers, Recycling Facilities Service Type: Collection Services, Processing Services, Transportation Services, Consultation |
| Companies Covered | Umicore, Li-Cycle Corp., Redwood Materials Inc., Ecobat LLC, Glencore Plc, Accurec Recycling GmbH, American Manganese Inc., Retriev Technologies, East Penn Manufacturing Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Recycling Market Trends and Innovations
Process chemistry and regulatory disclosure requirements are jointly elevating selective recovery technologies over bulk smelting, while procurement contracts embed recycled-content verification deeper into supply agreements.
Direct cathode regeneration is rewriting competitive economics for lithium iron phosphate recovery. Stationary storage integrators are piloting rejuvenated cathode materials at scale. This pathway is compressing payback periods for recycling investments by bypassing elemental separation entirely.
REACH substance registration expansions are tightening traceability requirements for recovered cobalt and nickel entering European cell manufacturing. Industrial consequence includes mandatory chain-of-custody documentation from collection through refining. German and French battery producers are responding by qualifying domestic preprocessing partners ahead of enforcement deadlines.
Automakers are consolidating offtake negotiations with a shrinking pool of qualified refiners capable of battery-grade certification. Tier-one cell suppliers are displacing spot-market metal purchases with multi-year recycled feedstock contracts. This concentration is most visible in binding agreements between North American vehicle manufacturers and vertically integrated recycling operators.
Automotive Battery Recycling Market Segmentation
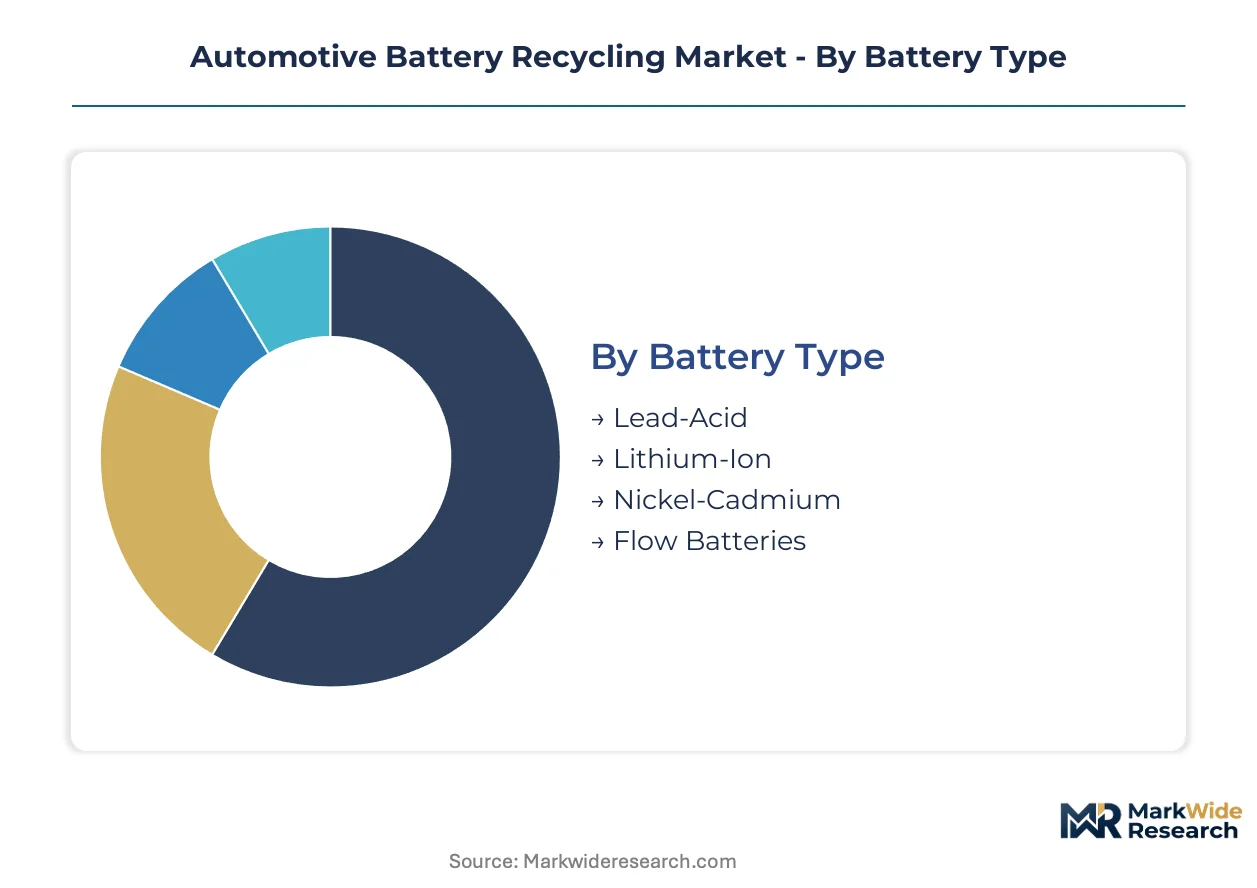
Automotive battery recycling segments reflect divergent technical requirements and margin structures. Battery chemistry dictates processing infrastructure investments, while end-user concentration shapes contract terms and feedstock security.
Battery Type:
Buyers in this category differentiate by energy density requirements and regulatory compliance burdens for hazardous material handling.
- Lithium-Ion:Cathode chemistries span NMC, LFP, and NCA formulations with varying nickel-cobalt ratios. Demand concentrates with EV manufacturers in Germany, China, and the United States as these nations scale gigafactory output and face EU Battery Regulation recycled content mandates.
- Lead-Acid:Mature recovery infrastructure achieves near-complete collection rates through established automotive aftermarket channels. Volume sits with starter battery replacement cycles in internal combustion vehicle fleets; growth tilts toward lithium-ion as electrification accelerates.
- Nickel-Cadmium:Legacy industrial applications and aviation backup systems generate limited but regulated feedstock streams requiring specialized cadmium separation.
- Flow Batteries:Vanadium redox systems from stationary storage installations represent emerging preprocessing opportunities with distinct electrolyte recovery requirements.
Processing economics favor high-volume lithium-ion streams; lead-acid margins compress from oversupply.
Recycling Process:
Technology selection hinges on energy costs, metal recovery rates, and qualification timelines for battery-grade output.
- Hydrometallurgical:Chemical leaching and solvent extraction achieve selective lithium, cobalt, and nickel recovery at lower energy intensity than thermal routes. European operators expand capacity to meet REACH traceability requirements for cathode precursor supply.
- Pyrometallurgical:High-temperature smelting processes mixed battery chemistries without extensive sorting but sacrifices lithium to slag. German refiners face margin pressure from natural gas price volatility and carbon border adjustment exposure.
- Direct Recycling:Cathode rejuvenation preserves crystal structure without full elemental separation, compressing processing costs for stationary storage applications.
- Mechanical Processing:Shredding and physical separation produces black mass intermediates for downstream refining, dominating preprocessing stages before hydrometallurgical or pyrometallurgical finishing.
Capital deployment concentrates in hydrometallurgical expansions; direct recycling climbs fastest from technology maturation.
End User:
Contract structures vary by feedstock control, offtake certainty, and integration depth into cell manufacturing.
- OEMs:Automakers secure multi-year recycled feedstock agreements to guarantee cathode material supply for gigafactories. Binding contracts with North American and European recyclers displace spot-market metal purchases.
- Aftermarket Providers:Independent service chains aggregate end-of-life batteries from vehicle repair networks, selling feedstock to processors without vertical integration.
- Scrap Dealers:Regional collectors handle dispersed battery stocks, facing margin compression from reverse logistics costs in rural territories.
- Recycling Facilities:Dedicated processors operate preprocessing and refining capacity, qualifying output against battery-grade specifications for cell manufacturer acceptance.
OEMs command pricing power through volume commitments; aftermarket providers expand through geographic coverage.
Service Type:
Value capture depends on asset intensity, regulatory licensing, and customer switching costs.
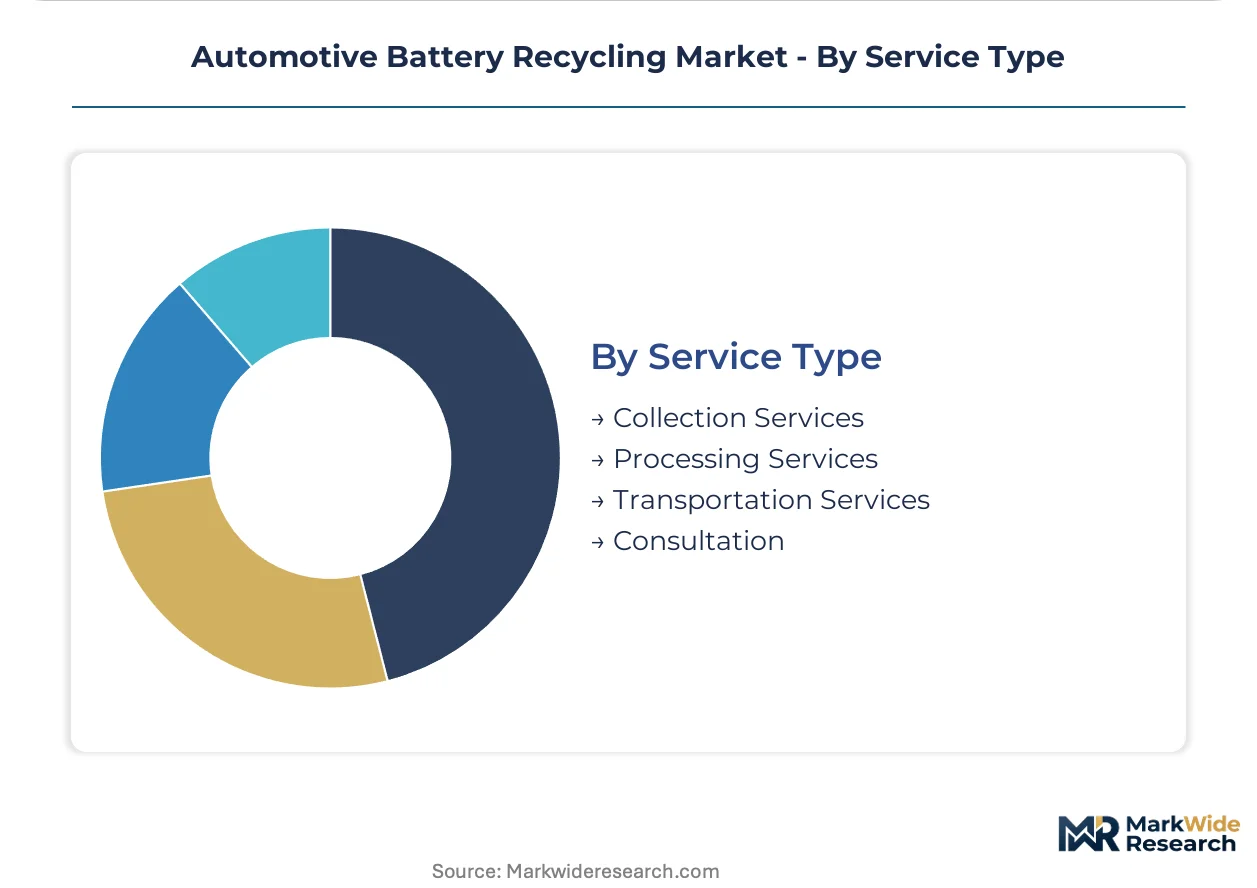
- Collection Services:Reverse logistics networks retrieve spent batteries from dealerships, repair shops, and end-of-life vehicle dismantlers. EPA RCRA hazardous waste classification governs US transport requirements.
- Processing Services:Dismantling, discharge, and mechanical separation operations require fire suppression retrofitting for high-nickel chemistries and thermal runaway containment capital.
- Transportation Services:Specialized hazmat carriers handle UN 3480 and UN 3481 classified lithium-ion shipments with temperature monitoring and incident response protocols.
- Consultation:Regulatory compliance advisory and recycling program design for automakers navigating EU Battery Regulation disclosure mandates and collection target calculations.
Processing services absorb capital concentration; collection services scale through network density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and the United States as these nations scale dedicated preprocessing infrastructure for cathode metal recovery. Automakers in each market are securing offtake agreements to guarantee recycled feedstock supply for gigafactory expansion.
United States
Domestic content credits under the Inflation Reduction Act are pulling cathode precursor investments into Nevada and the Carolinas. The EPA governs hazardous waste classification for spent batteries under RCRA, mandating specialized transport protocols. Redwood Materials anchors collection networks across the Southwest, integrating backward into dealer-based retrieval systems.
Germany
The Rhine-Ruhr region hosts preprocessing hubs supplying continental cell manufacturers with battery-grade nickel and cobalt. EU Battery Regulation mandates recycled content thresholds for lithium, cobalt, and nickel, forcing qualification timelines for domestic refiners. Umicore leverages pyrometallurgical expertise to dominate European cathode precursor production from Belgian-German border facilities.
China
GB standards enforced by SAMR limit export outlets for unrefined black mass intermediates, concentrating refining capacity domestically. The country's dual carbon goals accelerate hydrometallurgical expansions in Jiangsu and Hunan provinces. Major recyclers are building captive supply chains for domestic battery manufacturers expanding into European markets.
Japan
METI guidance on critical mineral security is incentivizing urban mining investments for lithium-ion recovery. JIS standards govern recycled material quality in domestic battery supply chains, extending qualification periods for foreign feedstock. Chubu region processors are piloting direct cathode regeneration technologies for stationary storage applications.
South Korea
Battery producers in the Seoul Capital Area are binding multi-year recycled feedstock contracts to displace spot-market metal purchases. MFDS alignment with REACH traceability requirements shapes import documentation for recovered cobalt. Busan-Ulsan industrial corridors are anchoring preprocessing partnerships with European automakers seeking compliant material.
Automotive Battery Recycling Market Competitive Landscape
European producers anchor one tier; North American specialists hold feedstock security advantages through collection network control. The vendor base splits between integrated refiners with pyrometallurgical heritage and hydrometallurgical pure-plays targeting battery-grade purity. Strategic archetypes include backward-integrated automaker partners, technology-licensing specialists, and regional preprocessing consolidators. Competitive moves concentrate on capacity expansion in industrial corridors and strategic partnerships securing offtake visibility.
Within the integrated refiner tier, Umicore and Glencore Plc occupy positions shaped by pyrometallurgical legacy and commodity trading infrastructure respectively. Li-Cycle Corp. exemplifies the hydrometallurgical pure-play archetype, differentiating through selective recovery routes that yield battery-grade lithium carbonate. Among North American operators, Redwood Materials sits within the backward-integrated category, leveraging collection network density to secure feedstock independent of third-party aggregators.
| Leading Market Players |
|---|
| Umicore |
| Li-Cycle Corp. |
| Redwood Materials Inc. |
| Ecobat LLC |
| Glencore Plc |
| Accurec Recycling GmbH |
| American Manganese Inc. |
| Retriev Technologies |
| East Penn Manufacturing Co. Inc. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into dealer-based retrieval systems anchors both feedstock security and pricing leverage for North American operators competing against spot-market metal purchases. Automaker offtake agreements compress margin volatility by replacing commodity exposure with contract-based cathode precursor supply.
Pricing Analysis
Volume scale separates contract-tier refiners serving OEM gigafactories from spot-market processors handling fragmented aftermarket streams. Pricing stratifies across battery-grade certification, hydrometallurgical purity premiums, and pyrometallurgical energy cost exposure. Cost compression in European smelting routes is intensifying because natural gas price volatility and carbon border adjustment mechanisms erode thermal process margins. Aftermarket providers and scrap dealers exhibit highest price sensitivity due to reverse logistics cost inflation; OEMs demonstrate lowest sensitivity through captive supply agreements.
Supply Chain Analysis
Reverse logistics networks for spent lithium-ion batteries draw from dispersed end-of-life vehicle stocks across rural North American territories, inflating collection costs before preprocessing. Raw material flows center on black mass intermediates, cathode metal concentrates, and battery-grade lithium carbonate outputs. Supply chain risk concentrates in China's SAMR enforcement of GB quality standards limiting export outlets for unrefined materials. Distribution runs through specialized hazmat carriers handling UN 3480 classified shipments toward centralized refining clusters in Germany, China, and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Battery Regulation compliance thresholds are forcing sub-scale preprocessors into acquisition targets as qualification timelines and capital requirements for battery-grade certification escalate.
For Market Incumbents: Lock in multi-year offtake agreements with European and North American automakers before REACH traceability enforcement tightens feedstock access. Expand hydrometallurgical capacity in the Rhine-Ruhr and Nevada industrial corridors to capture Inflation Reduction Act domestic content credits. Direct recycling technology maturation threatens elemental separation economics; secure pilot partnerships with stationary storage integrators testing cathode rejuvenation pathways. For New Entrants and Emerging Players: Independent service chains in rural North American territories represent the most penetrable collection segment, underserved by centralized refiner networks. Target preprocessing partnerships with Tier 2 battery producers seeking compliant feedstock outside automaker-captive supply. Go-to-market positioning should emphasize fire suppression retrofitting capabilities and thermal runaway containment certification for high-nickel chemistry handling. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by automakers and cathode producers seeking backward integration into collection and refining assets. Five-to-ten year viability favors hydrometallurgical pure-plays with proven lithium carbonate qualification timelines over pyrometallurgical legacy operators facing carbon cost exposure. Monitor EU Battery Regulation recycled content threshold enforcement dates as inflection indicators for preprocessing capacity valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Redwood Materials anchors feedstock security through dealer-based retrieval systems independent of third-party aggregators. |
| Hydrometallurgical Capacity Expansion | Li-Cycle Corp. scales selective recovery routes yielding battery-grade lithium carbonate without smelting energy exposure. |
| Direct Recycling Technology Partnership | Japanese processors pilot cathode rejuvenation for stationary storage applications compressing payback periods. |
| Multi-Year Offtake Agreement Negotiation | North American automakers bind recycled feedstock contracts displacing spot-market metal purchases for gigafactory supply. |
| Fire Suppression Retrofit Certification | Preprocessing facilities handling NMC chemistries invest in thermal runaway containment systems meeting EPA RCRA standards. |
Research Methodology
Document review covered EPA RCRA hazardous waste classifications, EU Battery Regulation compliance frameworks, and SAMR GB standards documentation, complemented by interviews with recycling facility operations directors, OEM procurement leads, cathode producer supply chain managers, and hazmat transportation specialists. Secondary validation drew from SEC filings of publicly traded recyclers, customs trade data for black mass intermediates, and vehicle registration databases tracking end-of-life battery generation. Bottom-up feedstock flow modeling triangulated against top-down gigafactory demand projections.
Segmentation outputs across battery chemistry, processing technology, end-user category, and service type were projected over the analysis window using installed capacity buildout timelines and regulatory enforcement schedules. CAGRs were derived from elasticity-adjusted demand curves incorporating EV penetration rates and recycled content mandate phase-ins. Forecast inputs included natural gas price volatility scenarios for pyrometallurgical cost modeling and lithium carbonate qualification timeline distributions for hydrometallurgical capacity utilization.
Caveats apply where EU Battery Regulation enforcement delays, China's black mass export restriction modifications, or direct recycling technology cost breakthroughs could materially shift the outlook. Practitioners should monitor carbon border adjustment mechanism implementation progress and stationary storage integrator pilot scale-up announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Battery Recycling
Europe Automotive Start-Stop Battery Market
Transportation Battery Recycling
Asia-Pacific Transportation Battery Recycling Market
Transportation Battery Recycling
Automobile Storage Battery Market
Transportation Battery Recycling
China Transportation Battery Recycling Market
Transportation Battery Recycling
Transportation Battery Market
Transportation Battery Recycling
Europe Train Battery Market
Transportation Battery Recycling
South Korea Transportation Battery Recycling Market
Transportation Battery Recycling
Two-Wheeler Battery Market
Transportation Battery Recycling
Transportation Battery Recycling Market
Transportation Battery Recycling
EV Battery Recycling Services Market
Transportation Battery Recycling
ASEAN Electric Vehicle Battery Anode Market
Transportation Battery Recycling
Automotive Energy Recovery System Market