
 North America Electric Vehicle Market | 2026-2036
North America Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Market Intelligence
The integration of subscription-based software services, such as enhanced autonomous driving features, is broadening the definition of an automotive product in North America. Tesla leverages its software-first approach and extensive Supercharger network to build a distinct ecosystem. Legacy automakers like General Motors and Ford Motor Company are rapidly scaling their own EV production and battery manufacturing capabilities. Rivian specializes in the adventure vehicle and commercial van segments, creating a niche market presence.
An electric vehicle utilizes one or more electric motors for propulsion, powered by a rechargeable battery pack or another energy storage device. Key performance parameters include battery capacity measured in kilowatt-hours (kWh), driving range, and charging speed, which depends on the vehicle's onboard charger and battery chemistry. Battery Electric Vehicles (BEVs) represent the fastest-growing segment, while Plug-in Hybrid Electric Vehicles (PHEVs) offer a transitional option. Demand from fleet operators is accelerating, driven by total cost of ownership advantages and corporate sustainability goals.
The regulatory environment in North America is shaped by the US Environmental Protection Agency (EPA) setting emissions targets and the National Highway Traffic Safety Administration (NHTSA) overseeing vehicle safety. Incentive programs, such as the US Inflation Reduction Act's tax credits and Canada's Incentives for Zero-Emission Vehicles (iZEV) Program, directly influence consumer purchasing decisions. Future competitiveness will depend on securing stable battery material supply chains and managing the expansion of public charging infrastructure.
Market Dynamics
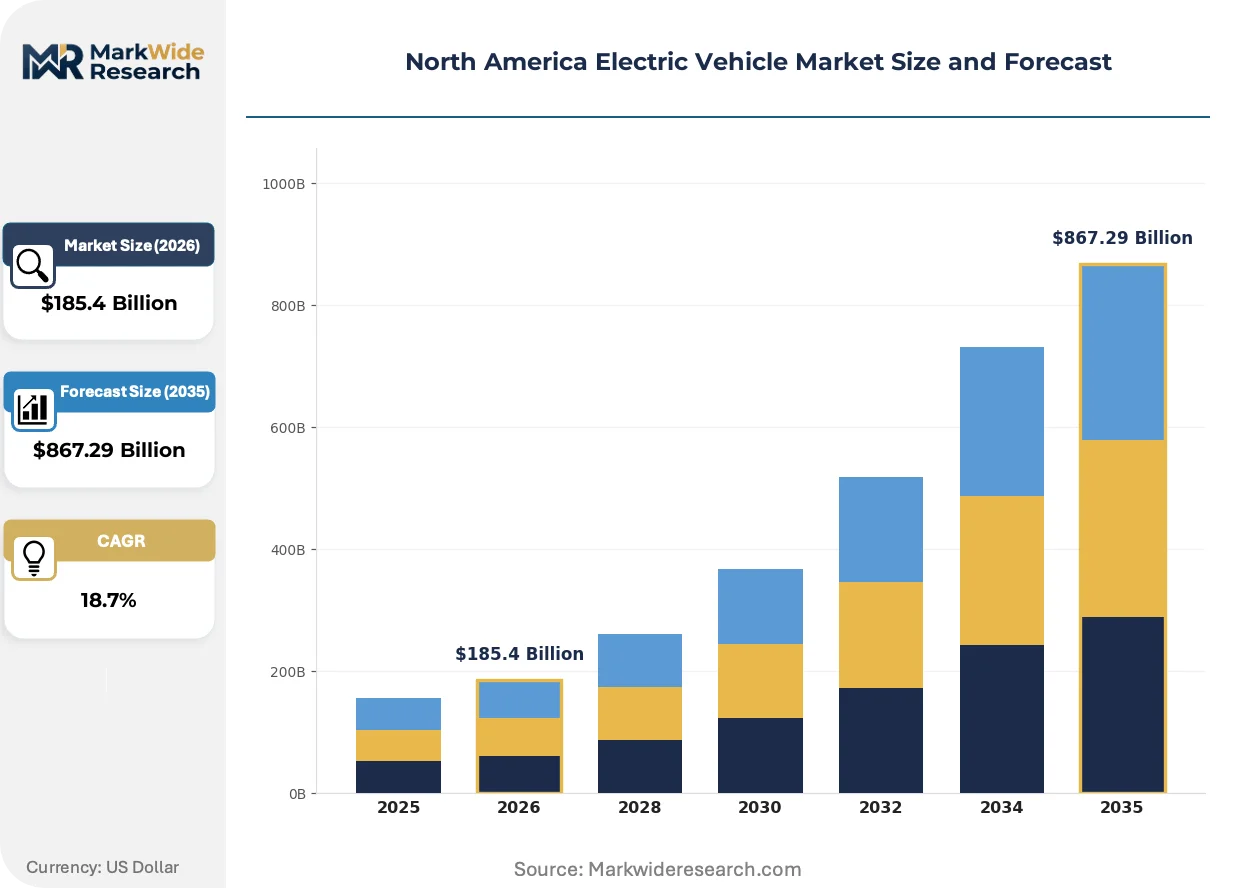
The market's trajectory is defined by the interaction between government incentives, like the Inflation Reduction Act, and accelerating demand from commercial fleet operators seeking to lower total cost of ownership and meet sustainability mandates.
Growth Catalysts
- Federal Incentives:The US Inflation Reduction Act provides substantial tax credits for both new and used EV purchases and for domestic battery manufacturing, directly stimulating consumer demand and localizing supply chains.
- Commercial Fleet Adoption:The logistics and delivery sectors are rapidly electrifying fleets, driven by lower fuel and maintenance costs which improve total cost of ownership, and corporate ESG commitments.
- Charging Network Expansion:Public-private partnerships are accelerating the build-out of high-speed charging stations along major transportation corridors, reducing range anxiety for both passenger and commercial users.
Market Restraints
- Battery Material Dependency:The North American supply chain remains highly dependent on imported critical minerals, such as lithium and cobalt, creating price volatility and geopolitical supply risks for battery manufacturers.
- Uneven Infrastructure:Public charging availability remains insufficient in many rural areas and multi-unit dwellings, creating a significant barrier to adoption for a large portion of the population.
- High Initial Vehicle Price:Despite incentives, the initial purchase price of many EVs remains higher than comparable internal combustion engine vehicles, limiting accessibility for price-sensitive consumer segments.
Strategic Opportunities
- Heavy-Duty Truck Electrification:Significant white space exists in electrifying Class 8 trucks for regional and long-haul freight, presenting a major opportunity to address a large source of emissions.
- Vehicle-to-Grid Services:The development of bidirectional charging technology opens new revenue streams for fleet operators and consumers by allowing them to sell stored energy back to the grid during peak demand.
- Mexico's Manufacturing Hub:Mexico is emerging as a critical EV manufacturing and assembly hub for the North American market, leveraging trade agreements and a skilled labor force to attract investment.
Industry Challenges
- Electrical Grid Strain:The rapid growth in EV charging demand poses a significant challenge to the capacity and stability of local and regional electricity grids, requiring substantial infrastructure upgrades.
- Technician Skill Gaps:A shortage of technicians trained in high-voltage systems and EV-specific software diagnostics hinders the scalability of service and repair networks across North America.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Market |
| Market Size in 2026 | $185.4 Billion |
| Market Size in 2035 | $867.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, Hybrid Electric Vehicles, Fuel Cell Electric Vehicles Powertrain: Lithium-Ion, Nickel-Metal Hydride, Solid State, Lead Acid Application: Personal Transport, Commercial Logistics, Public Transport, Specialty Vehicles Customer Type: Individual Consumers, Fleet Operators, Government Agencies, Corporate Buyers |
| Companies Covered | Tesla, General Motors, Ford Motor Company, Rivian, Lucid, Hyundai Motor Company, Toyota Motor Corporation, Nissan Motor Co., Ltd., Volkswagen Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Market Strategic Shifts & Innovations
A fundamental transformation is underway, shifting the automotive product from a static piece of hardware to a dynamic, software-centric platform. This evolution redefines value through ongoing services and updatable capabilities, altering the entire vehicle lifecycle.
Software-defined vehicle architecture centralizes electronic control units into a more powerful, consolidated computing system. Commercial and passenger vehicle manufacturers are aggressively adopting this approach to reduce complexity and enable new functions. This architecture is unifying previously siloed domains like powertrain control, advanced driver-assistance systems, and in-cabin infotainment into a cohesive, updatable software layer.
California’s Advanced Clean Fleets regulation establishes a mandatory schedule for commercial fleet operators to transition to zero-emission vehicles. This policy directly compels investment in electric trucks and vans for companies operating within the state's significant economy. Consequently, drayage and last-mile delivery segments are prioritizing ZEV procurement to meet escalating compliance deadlines set by the California Air Resources Board.
An unbundling of vehicle features into post-purchase subscriptions is gaining traction with consumers. This model disrupts the traditional one-time sale by allowing automakers to generate recurring revenue from services like enhanced autonomous driving or battery performance upgrades. The trend is most pronounced in the premium battery-electric vehicle segment in both the United States and Canada.
North America Electric Vehicle Market Segmentation
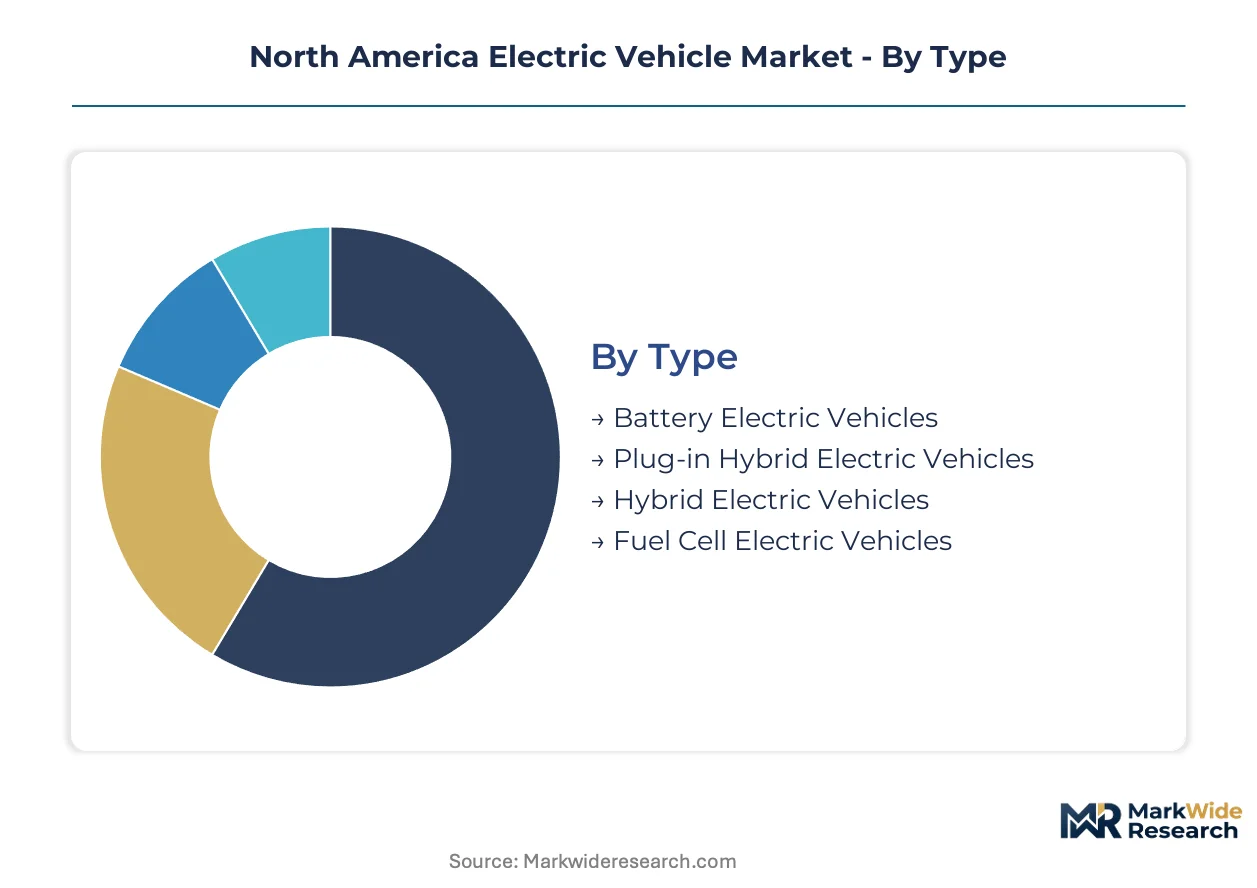
Understanding the North America Electric Vehicle Market requires a granular breakdown of its constituent elements. Segmentation analysis clarifies distinct product types, technological foundations, key applications, and purchasing entities. This detailed view illuminates where innovation is concentrated and demand drivers are most potent across the region.
Type:
The North American market's transition from traditional internal combustion engines to electric propulsion drives a continuous upgrade and replacement cycle across vehicle types.
- Battery Electric Vehicles:These vehicles rely solely on electric motors for propulsion, drawing power from a large, rechargeable battery pack. Demand concentrates heavily in US states like California due to stringent emissions mandates and robust charging infrastructure development.
- Plug-in Hybrid Electric Vehicles:PHEVs combine an internal combustion engine with an electric motor and a battery, allowing for all-electric range and gasoline backup. Adoption is strong in regions where charging infrastructure is still developing, offering a transitional solution for consumers in Canada.
- Hybrid Electric Vehicles:HEVs integrate an electric motor with a gasoline engine but cannot be charged externally, primarily improving fuel efficiency.
- Fuel Cell Electric Vehicles:FCEVs convert hydrogen into electricity to power an electric motor, emitting only water vapor, with limited infrastructure in North America.
Volume placements concentrate in Plug-in Hybrid Electric Vehicles; the faster expansion belongs to Battery Electric Vehicles.
Powertrain:
The market's long-term competitive positioning depends significantly on the underlying battery chemistry and its supply chain concentration.
- Lithium-Ion:This chemistry dominates current EV battery production due to its high energy density and long cycle life, powering the majority of electric vehicles. Supply chain resilience for lithium-ion cells is a strategic focus for manufacturers in the United States and Mexico.
- Solid State:Solid-state batteries utilize solid electrolytes instead of liquid, promising higher energy density, faster charging, and improved safety characteristics. Development is concentrated among advanced research institutions and automotive OEMs seeking next-generation performance in North America.
- Nickel-Metal Hydride:NiMH batteries are primarily found in older hybrid electric vehicles, offering proven reliability but lower energy density than lithium-ion.
- Lead Acid:Lead-acid batteries are used for auxiliary functions in EVs, such as powering 12V systems, rather than primary propulsion.
The long-term viability of electric powertrains hinges on securing stable supply chains for advanced battery materials.
Application:
Customer type and usage patterns define distinct application segments, each with unique performance requirements and operational demands.
- Commercial Logistics:This segment includes electric vans, trucks, and delivery vehicles used by fleet operators for goods transportation and last-mile delivery. Demand is accelerating due to total cost of ownership advantages and corporate sustainability goals for logistics companies in Canada and the US.
- Personal Transport:Passenger cars, SUVs, and light-duty vehicles for individual ownership constitute the largest volume segment within the North American EV market. Consumer purchasing decisions are heavily influenced by government incentives like the US Inflation Reduction Act and charging infrastructure availability.
- Public Transport:Electric buses and shuttles serve urban transit routes, driven by municipal sustainability targets and air quality mandates in major North American cities.
- Specialty Vehicles:This category encompasses electric vehicles for specific uses, such as airport ground support, construction, and agricultural machinery, often requiring customized power solutions.
The commercial sector demonstrates the steepest expansion trajectory, while personal transport maintains the largest market share.
Customer Type:
Market maturity and regulatory frameworks significantly influence purchasing behavior across different customer types in the North American EV landscape.
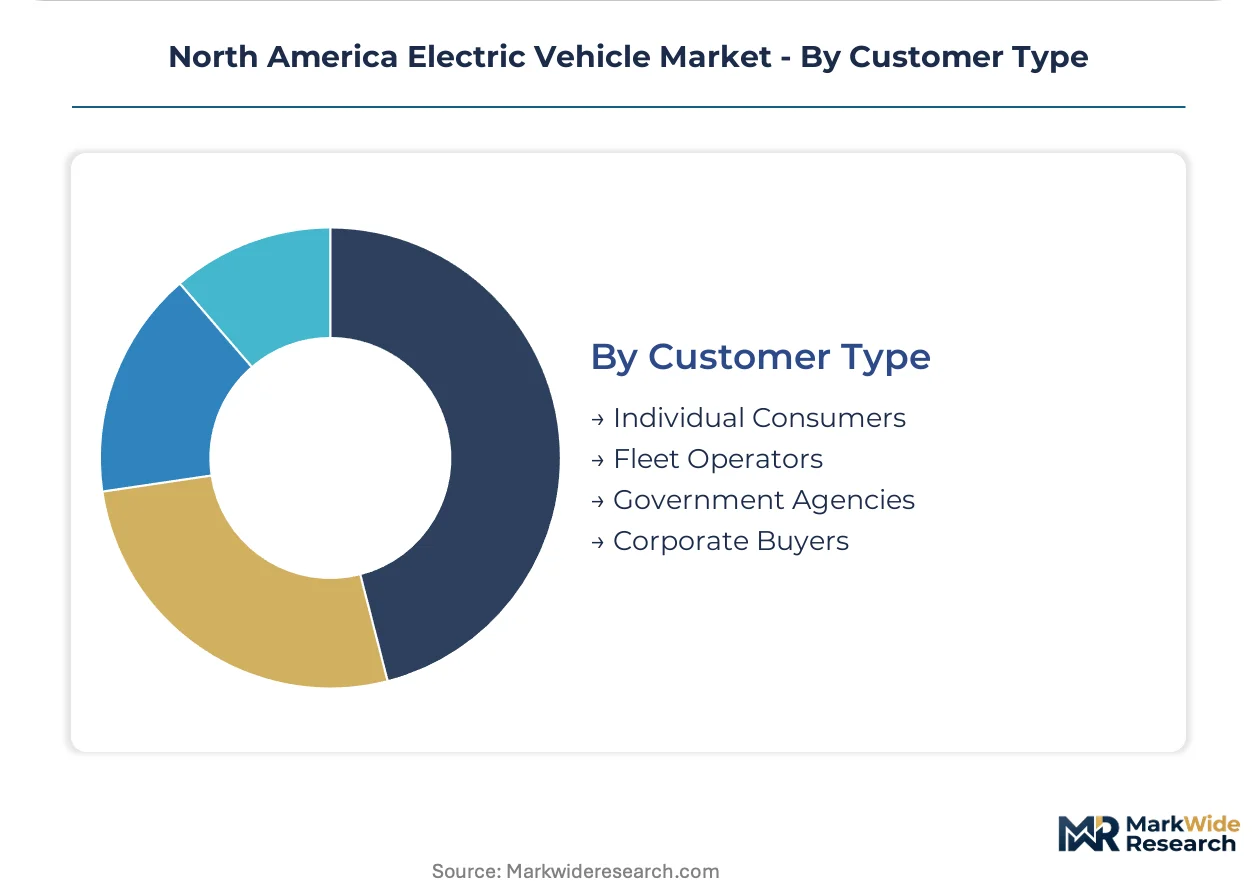
- Fleet Operators:Commercial businesses and logistics companies purchasing multiple EVs for their operational fleets drive significant volume. Their decisions prioritize total cost of ownership, operational efficiency, and compliance with regulations like California’s Advanced Clean Fleets.
- Individual Consumers:Private buyers acquiring EVs for personal use represent a substantial portion of the market, influenced by vehicle price, range anxiety, and government tax credits. The iZEV Program in Canada directly impacts individual purchasing decisions.
- Government Agencies:Federal, state, and municipal entities procure EVs for their vehicle fleets, aligning with public sector sustainability goals and emissions reduction targets.
- Corporate Buyers:Large corporations purchase EVs for employee fleets, executive transport, or company car programs, often driven by ESG commitments and brand image.
Individual consumers currently account for the largest volume, but fleet operators are rapidly gaining share in the North American market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American electric vehicle market presents a dynamic interplay between domestic manufacturing expansion and consumer demand. While significant consumption occurs, strategic efforts aim to localize the entire EV supply chain within the region, fostering economic growth. This balance influences market development and policy direction across the continent.
United States
Consumer purchasing decisions are heavily influenced by the Inflation Reduction Act's tax credits, stimulating demand for new and used electric vehicles. The US Environmental Protection Agency (EPA) sets stringent emissions targets, accelerating the transition across the automotive sector. Federal initiatives also support the build-out of high-speed charging stations along major transportation corridors, reducing range anxiety for users.
Canada
Adoption of electric vehicles is strong, particularly for Plug-in Hybrid Electric Vehicles, offering a transitional solution where charging infrastructure is still developing. Canada's Incentives for Zero-Emission Vehicles (iZEV) Program directly influences individual purchasing decisions by providing significant rebates. Ontario is attracting substantial investment in EV and battery manufacturing, bolstering the domestic supply chain and creating a strong industrial cluster.
Mexico
Mexico is rapidly emerging as a critical EV manufacturing and assembly hub, leveraging trade agreements and a skilled labor force. The country's favorable trade environment attracts significant foreign direct investment from major automakers, establishing new production facilities. Northern Border States are seeing increased activity in component production and vehicle assembly, integrating Mexico deeper into the North American EV ecosystem.
California
California represents a leading market for electric vehicle adoption due to its stringent environmental regulations and supportive policies. The California Air Resources Board (CARB) mandates zero-emission vehicle sales and establishes a schedule for commercial fleet transitions. The state's robust charging infrastructure and strong consumer awareness make it a key area for EV growth and innovation.
North America Electric Vehicle Market Key Industry Players
Capital-heavy producers compete with asset-light designers, shaping the North American electric vehicle market structure. The landscape features established automotive giants alongside innovative EV pure-plays, creating a tiered competitive environment. Strategic archetypes include vertically integrated manufacturers, technology specialists, and platform providers. Companies prioritize capacity expansion and strategic partnerships to secure battery material supply chains and expand charging networks.
Within the established automotive giant archetype, General Motors and Ford Motor Company exemplify the transition of legacy manufacturers into the electric vehicle space. These US-based corporations are rapidly scaling their own EV production and battery manufacturing capabilities, leveraging existing distribution networks. Tesla, a prominent US-based pure-play EV manufacturer, anchors the technology specialist segment, leveraging its software-first approach and extensive Supercharger network to build a distinct ecosystem. Rivian, another US-based company, occupies a niche in adventure vehicles and commercial vans, demonstrating focused product development for specific market segments.
| Leading Market Players |
|---|
| Tesla |
| General Motors |
| Ford Motor Company |
| Rivian |
| Lucid |
| Hyundai Motor Company |
| Toyota Motor Corporation |
| Nissan Motor Co., Ltd. |
| Volkswagen Group |
| Others |
Cost & Logistics Intelligence
Vertical integration into battery manufacturing anchors North American EV producers' supply position, significantly influencing their long-term pricing power. This strategic control over critical components mitigates external supply chain volatility.
Pricing Analysis
Cost-down pressure on mass-market Battery Electric Vehicles accelerates because of increased competition and manufacturing scale across North America. The market features a hybrid pricing model, combining per-unit transactional vehicle sales with subscription-based software services for enhanced features. Brand premium and after-sales services, such as access to charging networks, differentiate offerings. Individual consumers exhibit high price sensitivity, while commercial fleet operators prioritize total cost of ownership.
Supply Chain Analysis
Dual-sourcing requirements are becoming standard practice for North American EV manufacturers to mitigate material dependency risks. The supply of critical minerals like lithium and cobalt concentrates heavily in regions outside North America, creating geopolitical supply risks for battery manufacturers. Mexico and Canada are strengthening their roles in component production and vehicle assembly within the regional ecosystem. Distribution runs through established OEM-controlled dealership networks, alongside direct-to-consumer models favored by pure-play EV companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Electric Vehicle market increasingly operates as a cost-of-compliance narrative. Regulations like California's Advanced Clean Fleets establish a barrier-to-entry moat for businesses capable of meeting stringent zero-emission mandates.
For Market Incumbents: Deepen vertical integration into battery cell manufacturing and raw material sourcing to secure supply chains against geopolitical risks. Accelerate software-defined vehicle development to counter technology specialists and offer recurring revenue services. Invest in expanding charging infrastructure partnerships to enhance consumer and fleet operator adoption, addressing range anxiety. This strategy hedges against margin pressure from new entrants.
For New Entrants and Emerging Players: Commercial fleet management companies represent a penetrable segment for new entrants offering specialized electric vans and trucks. Focus on niche applications like last-mile delivery or heavy-duty regional hauling, where specific performance requirements create white space. Develop compelling total cost of ownership propositions to attract fleet operators. Go-to-market strategies should emphasize direct sales and tailored service agreements.
For Investors and Strategic Acquirers: Exit pathways concentrate in technology specialists offering advanced battery chemistries or software-defined vehicle platforms. Long-term viability, over the next decade, favors companies with proprietary technology and strong intellectual property in powertrain components. Acquire firms with established charging network solutions or unique battery material processing capabilities. A key signal to watch is the rapid expansion of domestic battery manufacturing capacity in the US and Canada.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Chain Localization | Secures critical material access for North American EV production, reducing dependency on imports. |
| Software-Defined Vehicle Architecture | Enables over-the-air updates and new subscription revenue streams for automotive manufacturers. |
| Commercial Fleet Electrification | Addresses sustainability goals and total cost of ownership advantages for logistics companies. |
| Charging Infrastructure Partnerships | Expands public and private charging access, mitigating consumer range anxiety across the region. |
| Heavy-Duty Truck Electrification | Targets a significant emissions source, opening a large new market segment for specialized EV manufacturers. |
Research Approach
Document review covered regulatory filings, industry whitepapers, and technical specifications, complemented by interviews with automotive OEMs, battery manufacturers, and fleet operators. Primary insights were gathered from R&D directors, procurement leads, and policy strategists across North America. Secondary sources included government reports from the US Environmental Protection Agency and National Highway Traffic Safety Administration. This involved bottom-up data collection and top-down validation, integrating diverse perspectives.
Historical market trends were cross-referenced with expert panel input to project market trajectories over the analysis window. The analytical framework modeled segmentation by vehicle type, powertrain, application, customer type, and regional adoption patterns across North America. Compound annual growth rates were derived from a synthesis of supply-side capacity expansions and demand-side adoption rates, incorporating battery cost curves.
Caveats apply where policy changes, battery technology breakthroughs, or geopolitical shifts could materially shift the outlook for the North America EV market. Forecasts reflect documented assumptions regarding regulatory stability and consumer incentives. Deviation in these factors would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
EV Platform Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Hoverboard Scooter Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
EV Condenser Market
Electric Vehicles
Central and Eastern Europe E-Bike Market