
 China Electric Truck Market | 2026-2036
China Electric Truck Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Truck Market Intelligence
Aftermarket battery refurbishment revenue is narrowing against first-life pack sales as fleet operators extend vehicle cycles. BYD leverages captive cell production to control replacement cost structures. Dongfeng Motor Corporation anchors its position through deep dealer networks in central China logistics corridors. Sany Group specializes in off-highway electric chassis for mining applications, differentiating from highway-focused rivals.
China electric trucks are commercial vehicles powered by battery electric, hydrogen fuel cell, or hybrid electric drivetrains with energy densities typically exceeding 160 Wh per kilogram and continuous power ratings above 200 kW for heavy-duty configurations, designed primarily for goods transport and industrial hauling with zero tailpipe emissions at point of use. Heavy duty vehicles dominate installed fleet value due to premium powertrain costs and longer operational lifecycles, while battery electric configurations lead unit shipments across logistics end users seeking depot-charging simplicity. Hydrogen fuel cell segments are gaining structural attention in long-haul corridors where fast refueling offsets battery weight penalties.
MIIT homologation rules and GB standards for electric commercial vehicles dictate motor efficiency thresholds and battery safety testing protocols that determine market access eligibility. SAMR enforcement of NEV subsidy compliance and MEE emissions zone designations in Beijing, Shanghai, and Guangzhou directly shape fleet procurement timelines and product specification requirements. Stakeholders must monitor how NMPA-aligned battery recycling mandates and provincial dual carbon targets redistribute capital allocation between charging infrastructure and vehicle manufacturing capacity.
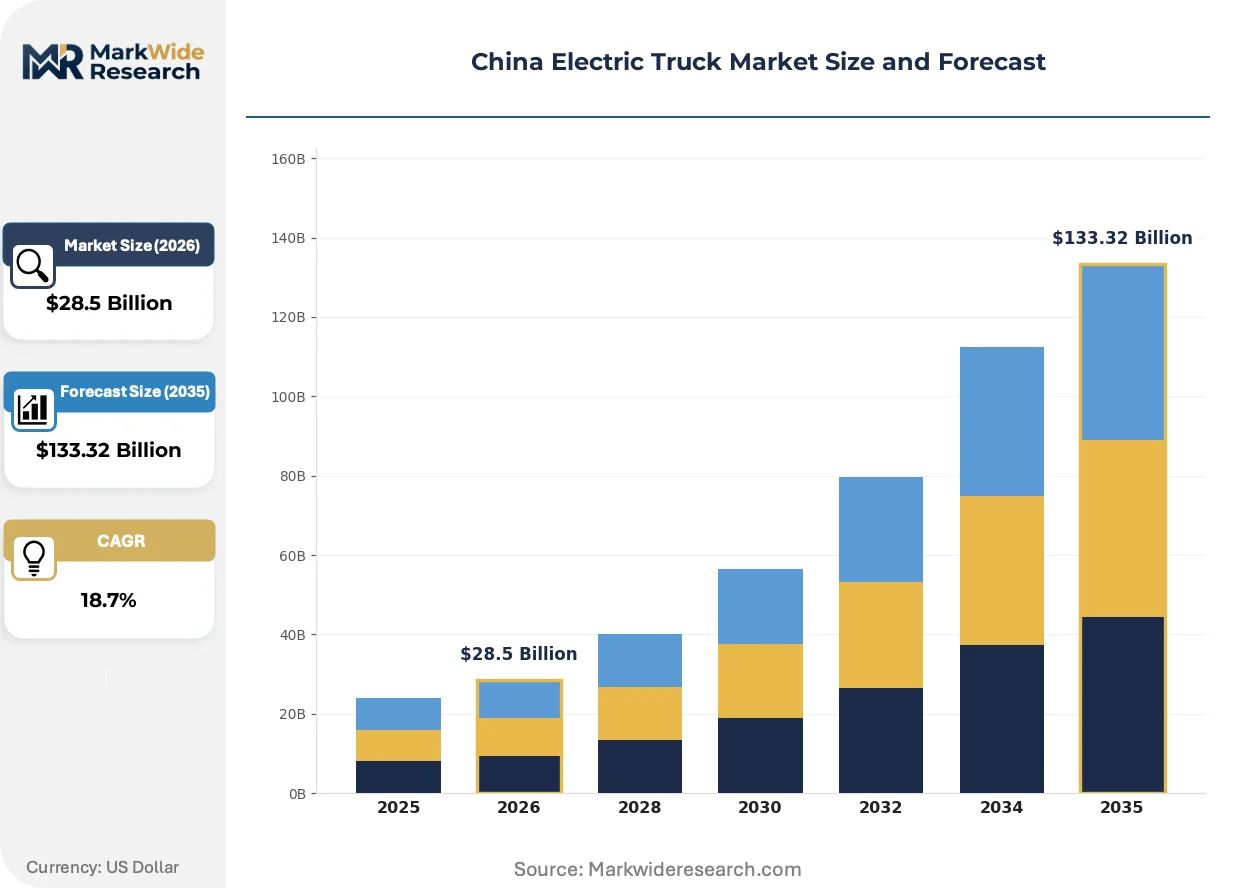
Market Dynamics
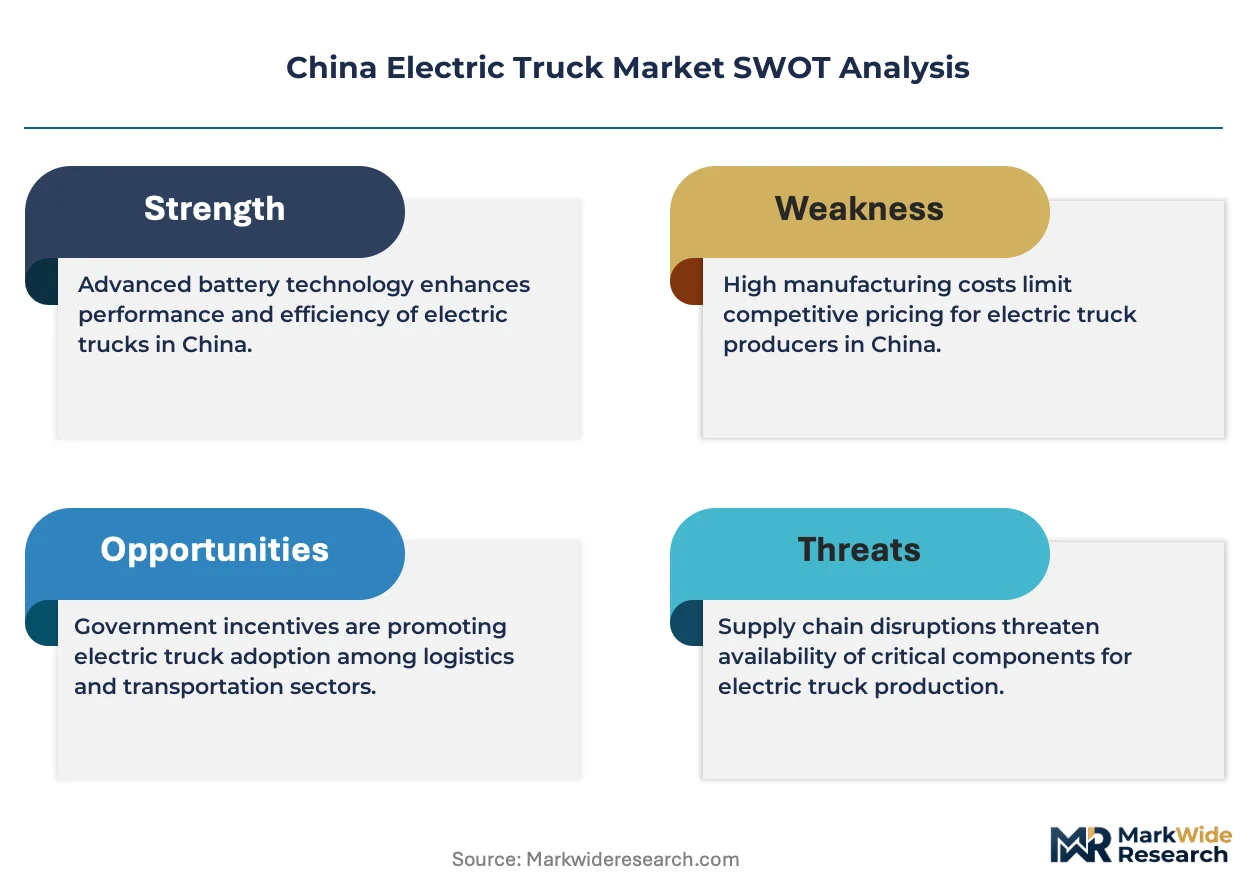
MIIT's tightening NEV mandates and provincial dual carbon targets are compressing fleet procurement timelines, forcing logistics operators to accelerate electrification roadmaps beyond natural replacement cycles.
Growth Catalysts
- MEE emissions zone designations:Beijing, Shanghai, and Guangzhou have established zero-emission freight corridors that mandate electric vehicle penetration for urban delivery fleets.
- Sodium-ion battery chemistry:CATL's breakthrough in sodium-ion cell production is reducing raw material dependency on lithium and compressing pack cost structures for heavy-duty configurations.
- Inner Mongolia mining haulage:Open-pit coal and rare earth operations are absorbing high volumes of electric mining trucks due to fixed-route duty cycles and depot-charging feasibility.
Market Restraints
- Lithium carbonate price volatility:Cathode material cost swings create margin instability for battery pack producers and fleet financing arrangements.
- GB standards homologation timelines:SAMR enforcement of revised motor efficiency and battery safety testing protocols extends product certification cycles by four to six months.
- Hydrogen fuel cell substitution:Long-haul corridor operators are piloting fuel cell trucks where fast refueling offsets battery weight penalties in high-mileage applications.
Strategic Opportunities
- Shandong Province port electrification:Qingdao and Yantai container terminals present concentrated demand for automated electric terminal tractors and short-haul shuttle trucks.
- NMPA-aligned battery recycling mandates:Closed-loop refurbishment and second-life energy storage applications are creating aftermarket revenue streams independent of vehicle sales.
- V2G depot infrastructure convergence:Grid-interactive charging systems enable fleet operators to monetize stationary battery capacity during peak demand periods.
Industry Challenges
- Power electronics engineering scarcity:Motor controller and inverter design talent is concentrated among a limited pool of suppliers, constraining product development velocity.
- Charging infrastructure capex intensity:Megawatt-class depot installations for heavy-duty fleets require grid upgrade coordination with provincial power utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Truck Market |
| Market Size in 2026 | $28.5 Billion |
| Market Size in 2035 | $133.32 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty, Medium Duty, Heavy Duty, Refuse Truck Power Source: Battery Electric, Hydrogen Fuel Cell, Hybrid Electric, Others End User: Logistics, Construction, Mining, Public Transport Charging Infrastructure: Public Charging Stations, Private Charging Solutions, Fast Charging, Wireless Charging |
| Companies Covered | BYD, Dongfeng Motor Corporation, Sany Group, SAIC Motor, Faw Jiefang, Sinotruk, Geely, Great Wall Motor, Li Auto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Truck Market Strategic Shifts & Innovations
Electrification architecture is bifurcating between battery-dominant urban logistics and fuel cell-enabled long-haul corridors, with powertrain selection increasingly dictated by route-specific energy logistics rather than vehicle class alone.
Sodium-ion battery chemistry is collapsing the total cost of ownership gap between electric and diesel powertrains for medium-duty distribution trucks. Logistics operators in Shenzhen and Chengdu are trialing sodium-ion packs for refrigerated delivery applications where thermal management demands strain conventional lithium-ion endurance. This chemistry shift is enabling OEMs to offer competitive leasing terms without subsidy dependence.
MIIT's revised GB/T standards for commercial vehicle motor efficiency are forcing redesigns of permanent magnet synchronous motor architectures. Suppliers must demonstrate 97% peak efficiency under new test cycles to maintain homologation eligibility. Heavy-duty mining truck producers in Shanxi and Hebei are prioritizing high-voltage 800V platforms to meet these thresholds while reducing copper winding mass.
Fleet procurement committees are consolidating vendor relationships around full-lifecycle service agreements rather than discrete vehicle transactions. Large express delivery operators in the Yangtze River Delta are negotiating battery-inclusive operating leases that transfer residual value risk to manufacturers. This model is visible among parcel sorting hubs in Hangzhou and Nanjing where uptime guarantees outweigh capital expenditure considerations.
China Electric Truck Market Segmentation
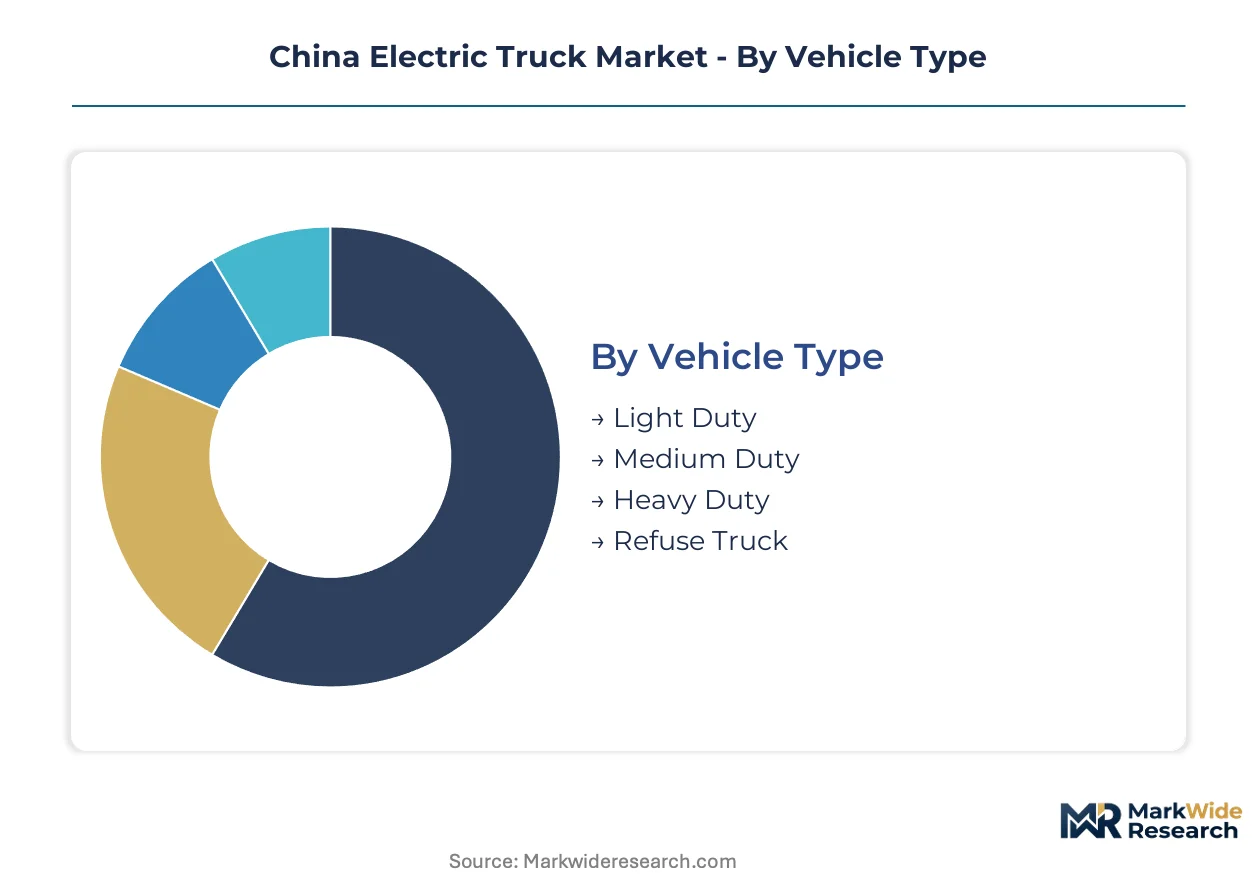
Segmentation reveals how electrification economics vary sharply across duty cycles and energy logistics. Fleet procurement committees weight total cost of ownership differently depending on route predictability, cargo density, and depot access.
Vehicle Type:
Mature highway logistics segments coexist with emerging specialized configurations as electrification penetrates deeper into vocational applications.
- Light Duty:Compact urban delivery vans and small box trucks with battery capacities between 60-100 kWh dominate last-mile parcel distribution. Express operators in Shenzhen and Hangzhou prioritize these units for depot-charging simplicity and narrow street maneuverability.
- Heavy Duty:Tractor-trailers and rigid trucks above 16 tonnes gross vehicle weight carry premium powertrain costs but absorb the highest fleet investment volumes due to fuel displacement economics. Long-haul corridors between Beijing and Shanghai are piloting these configurations with swappable battery systems.
- Medium Duty:Regional distribution trucks serving 200-500 kilometer radius routes from urban hubs.
- Refuse Truck:Low-speed municipal waste collection vehicles with regenerative braking optimization for stop-start duty cycles.
Light Duty retains volume leadership; Heavy Duty holds the steepest expansion curve.
Power Source:
Cost tier stratification separates subsidy-dependent chemistries from emerging alternatives with raw material independence.
- Battery Electric:Lithium-ion and sodium-ion cell configurations delivering zero tailpipe emissions through plug-in or pantograph charging. Logistics fleets in the Yangtze River Delta favor these for predictable depot-return routes with overnight charging windows.
- Hydrogen Fuel Cell:Proton exchange membrane stacks converting hydrogen to electricity for extended range without battery weight penalties. Inner Mongolia coal haulage operators are trialing these for 800-kilometer round trips where fast refueling offsets infrastructure capital intensity.
- Hybrid Electric:Parallel or series architectures combining downsized combustion engines with electric traction motors.
- Others:Emerging chemistries including solid-state prototypes and aluminum-air range extenders.
Battery Electric dominates unit shipments; Hydrogen Fuel Cell is gaining share fastest in long-haul corridors.
End User:
Application-specific duty cycles dictate powertrain selection more than vehicle class alone.
- Logistics:Parcel, cold chain, and general freight operators with predictable route structures and centralized depot networks. E-commerce fulfillment hubs in Guangzhou and Chengdu are consolidating procurement around full-lifecycle service agreements.
- Mining:Open-pit operations in Shanxi and Inner Mongolia with fixed haul roads and high-shift utilization. These sites absorb electric mining trucks with 300-tonne payload capacity and trolley-assist infrastructure for uphill segments.
- Construction:Urban building material delivery and equipment transport with intermittent duty cycles.
- Public Transport:Municipal service vehicles including street sweepers and utility maintenance trucks.
Logistics commands the largest addressable fleet; Mining shows the steepest adoption acceleration.
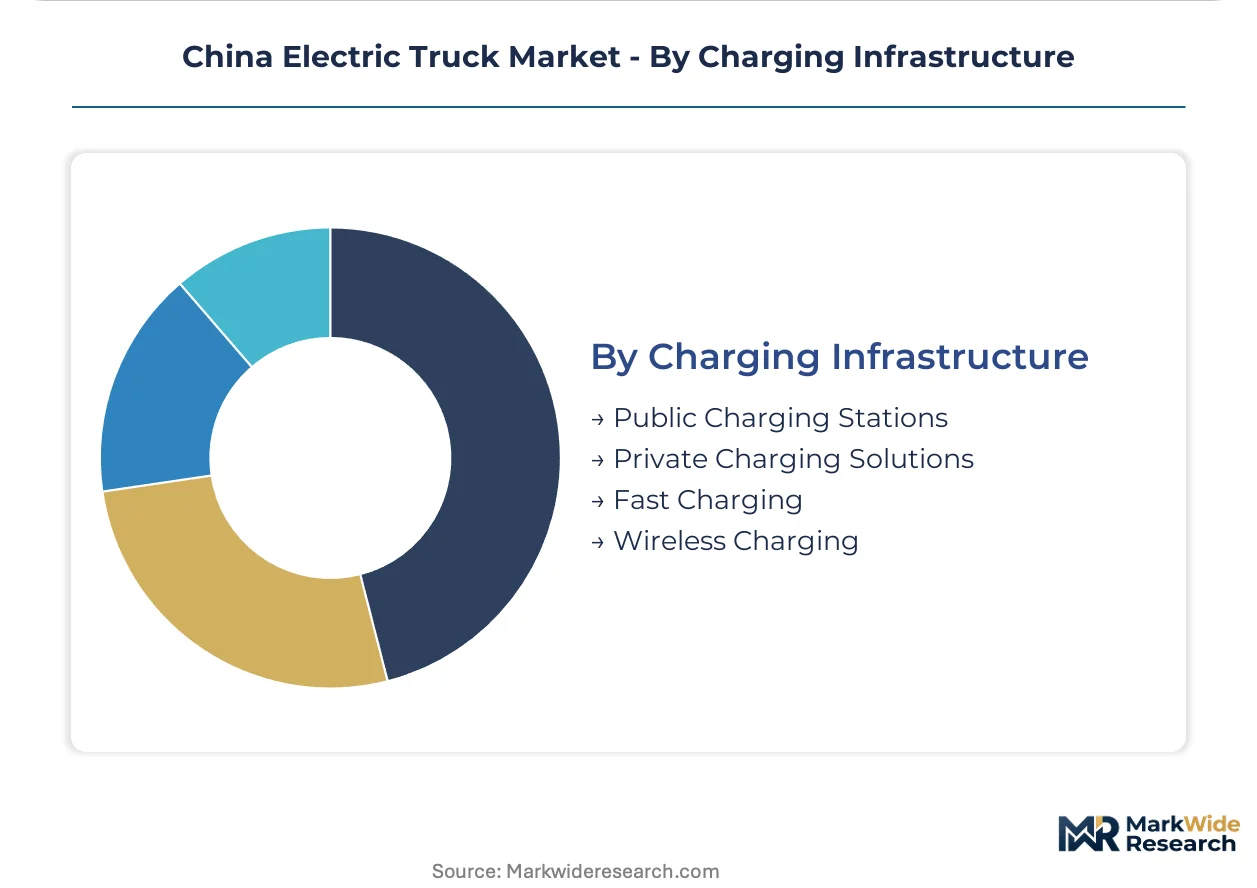
Charging Infrastructure:
Supply concentration in grid-interactive systems is reshaping fleet energy economics.
- Fast Charging:Megawatt-class DC systems delivering 80% state of charge within 45 minutes for heavy-duty tractors. Port terminals in Qingdao are deploying these for shuttle truck turnaround minimization.
- Private Charging Solutions:Depot-mounted AC and DC installations controlled by fleet operators for demand charge management. Large express delivery networks in Nanjing prioritize these for vehicle-to-grid revenue participation.
- Public Charging Stations:Highway corridor and urban curb-side infrastructure for opportunistic charging.
- Wireless Charging:Inductive pad systems for automated terminal tractors and bus rapid transit applications.
Private Charging Solutions retain deployment leadership; Fast Charging is climbing the fastest in heavy-duty corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal provinces deploy electric trucks for urban logistics with depot-charging infrastructure, while interior mining belts favor heavy-duty configurations with fixed-route duty cycles and trolley-assist systems.
Yangtze River Delta
Express delivery operators dominate procurement with full-lifecycle service agreements replacing discrete vehicle purchases. MIIT's NEV mandates accelerate fleet replacement timelines beyond natural cycles. Shanghai and Hangzhou parcel sorting hubs negotiate battery-inclusive operating leases that transfer residual value risk to manufacturers.
Pearl River Delta
Shenzhen's zero-emission freight corridors mandate electric penetration for urban delivery fleets with MEE enforcement. Cold chain logistics operators trial sodium-ion battery packs for refrigerated applications where thermal management demands strain conventional lithium-ion endurance. Guangzhou e-commerce fulfillment hubs consolidate vendor relationships around uptime guarantees.
Beijing-Tianjin-Hebei
Capital region emissions zone designations restrict diesel truck access to core urban areas during daylight hours. SAMR subsidy compliance verification shapes procurement specifications and certification timelines. Tianjin port terminals deploy automated electric terminal tractors for container shuttle operations.
Inner Mongolia
Open-pit coal and rare earth mining operations absorb high volumes of electric mining trucks with 300-tonne payload capacity. Fixed haul roads and high-shift utilization enable depot-charging feasibility and trolley-assist infrastructure for uphill segments. Baotou and Ordos mining clusters drive heavy-duty electrification adoption.
Shandong Peninsula
Qingdao and Yantai container terminals present concentrated demand for short-haul shuttle trucks and port electrification infrastructure. Megawatt-class fast charging systems minimize turnaround times for heavy-duty tractor units. Provincial dual carbon targets redistribute capital allocation between charging infrastructure and vehicle manufacturing capacity.
China Electric Truck Market Key Industry Players
Capability concentration sits with battery and powertrain specialists; scale advantage sits with diversified automotive conglomerates with deep manufacturing footprints. The market structure tiers between captive cell producers controlling replacement cost structures and highway-focused OEMs competing through dealer network density. Three archetypes dominate: integrated battery-vehicle producers, legacy truck manufacturers electrifying existing platforms, and off-highway specialists mining vocational applications. Competitive moves center on vertical integration into cell production and full-lifecycle service agreements transferring residual value risk.
Within the integrated tier, BYD exemplifies captive supply chain control, while Dongfeng Motor Corporation anchors central China logistics corridors through established distribution infrastructure. Sany Group occupies a distinct position among off-highway specialists targeting mining applications rather than highway freight.
| Leading Market Players |
|---|
| BYD |
| Dongfeng Motor Corporation |
| Sany Group |
| SAIC Motor |
| Faw Jiefang |
| Sinotruk |
| Geely |
| Great Wall Motor |
| Li Auto |
| Others |
Cost & Logistics Intelligence
Ningde battery cell manufacturing clusters anchor global cathode supply, translating raw material cost volatility directly into pack pricing power for heavy-duty configurations. Sodium-ion chemistry breakthroughs are redistributing that leverage toward logistics operators seeking subsidy-independent procurement terms.
Pricing Analysis
Long-term offtake contracts dominate fleet procurement, with battery-inclusive operating leases transferring residual value risk to manufacturers. Price differentiation hinges on cell chemistry tier and charging infrastructure bundling. Cost compression in lithium-dependent packs is intensifying because CATL's sodium-ion production is collapsing the total cost of ownership gap. Express delivery networks show highest price sensitivity; mining operators with fixed-route duty cycles show lowest.
Supply Chain Analysis
Tariff exposure between Australia and China for lithium spodumene concentrates dominates upstream risk calculus. Cathode active material production concentrates in China, South Korea, and Japan. Cell manufacturing draws from cobalt hydroxide, lithium carbonate, and nickel sulfate feedstocks. Single-source vulnerability sits with Australian hard-rock lithium extraction. Distribution runs through OEM captive service networks and independent dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring around V2G depot infrastructure convergence, where grid-interactive charging systems transform fleet batteries into distributed energy assets. Interoperability between vehicle telematics and utility demand response protocols is the ecosystem shift justifying this inflection.
For Market Incumbents: Pre-empt hydrogen fuel cell substitution in long-haul corridors by accelerating 800V platform deployment and swappable battery standardization. Backward integration into sodium-ion cell production controls replacement cost structures against emerging chemistry competitors. MIIT's tightening motor efficiency thresholds demand immediate R&D redeployment toward permanent magnet synchronous motor redesigns.
For New Entrants and Emerging Players: Establish a beachhead in Shandong Province port electrification, where Qingdao and Yantai container terminals present concentrated demand for automated terminal tractors. Off-highway mining applications in Inner Mongolia offer the most penetrable segment due to fixed-route duty cycles and trolley-assist infrastructure feasibility. Negotiate full-lifecycle service agreements with uptime guarantees rather than competing on vehicle transaction pricing.
For Investors and Strategic Acquirers: Long-term, this sits as a grid-interactive infrastructure play because V2G depot systems monetize stationary battery capacity during peak demand periods. Acquisition targets should concentrate on power electronics engineering specialists with motor controller and inverter design capabilities. The signal to watch is provincial dual carbon target acceleration compressing fleet procurement timelines beyond natural replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Sodium-Ion Battery Supply Agreement | CATL's chemistry breakthrough reduces lithium dependency and enables subsidy-independent fleet leasing terms. |
| 800V Platform Standardization | MIIT's revised GB/T motor efficiency thresholds force high-voltage architectures to maintain homologation eligibility. |
| V2G Depot Infrastructure Partnership | Grid-interactive charging systems allow Yangtze River Delta express operators to monetize stationary battery capacity. |
| Mining Application Specialization | Sany Group's off-highway chassis expertise captures fixed-route haulage demand in Inner Mongolia coal operations. |
| Full-Lifecycle Service Agreement | Battery-inclusive operating leases transfer residual value risk from Nanjing parcel hubs to manufacturers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across fleet procurement committees, OEM platform engineers, battery pack procurement leads, and charging infrastructure developers. Secondary validation drew from MIIT homologation filings, SAMR subsidy compliance records, GB standards documentation, and provincial dual carbon target disclosures. Bottom-up fleet deployment estimates triangulated against top-down powertrain production data.
Calibration against historical replacement cycles and subsidy phase-out schedules shaped the analytical framework across the analysis window. Segmentation modeled vehicle class, propulsion architecture, end-use application, and charging infrastructure type. CAGRs derived from installed base growth trajectories and average selling price evolution. Sodium-ion chemistry adoption curves and hydrogen fuel cell pilot scale-up served as industry-specific forecast inputs.
Sensitivities concentrate around lithium carbonate price volatility, GB standards homologation timeline extensions, and provincial emissions zone enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
France Electric Vehicle Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
North America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
South Korea E-Bike Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
Mexico Electric Bus Market