
 Automotive Energy Harvesting and Regeneration Market | 2026-2036
Automotive Energy Harvesting and Regeneration Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Energy Harvesting and Regeneration Market Analysis
Software-defined regenerative calibration is recalibrating what automakers purchase from Tier 1 suppliers. Robert Bosch GmbH leverages its powertrain electronics portfolio to embed adaptive energy recovery algorithms across hybrid platforms. Continental AG anchors its competitive stance through integrated brake-by-wire systems that merge mechanical regeneration with digital vehicle dynamics control. Denso Corporation specializes in thermal management interfaces that capture exhaust waste heat for auxiliary power generation.
Automotive energy harvesting and regeneration encompasses the capture, conversion, and storage of otherwise dissipated kinetic, thermal, and vibrational energy into reusable electrical power, typically operating at voltage ranges from 12V auxiliary circuits to 800V high-voltage traction systems for electric drivetrains. Regenerative braking systems dominate installed value due to their mandatory fitment across battery-electric and hybrid architectures, while thermoelectric generators occupy emerging margin pools as heavy-duty truck OEMs pursue idle-reduction compliance. Piezoelectric devices compete for cabin and chassis integration opportunities where vibration energy density supports low-power sensor networks.
The EPA, EU Green Deal framework, and NHTSA govern emissions thresholds and recoverable-energy credit mechanisms that determine product qualification for fleet compliance. EMA and REACH additionally shape material composition rules for thermoelectric substrates and piezoelectric ceramics sold into European vehicle assembly. Stakeholders must monitor regulatory calibration timelines in multiple jurisdictions to align R&D roadmaps with shifting certification requirements.
Market Dynamics
Electric vehicle OEM procurement of regenerative braking modules is accelerating as automakers pursue fleet efficiency targets, reshaping what Tier 1 suppliers must deliver.
Growth Catalysts
- EPA tailpipe emissions rules:Mandates for passenger and commercial vehicles in the United States are tightening recoverable-energy requirements, forcing OEMs to integrate regeneration systems.
- EU Green Deal framework:The European regulatory push is creating mandatory fitment obligations across battery-electric and hybrid architectures, driving installed value expansion.
- Heavy-duty truck idle-reduction compliance:Thermoelectric generator demand is concentrating in Germany, Japan, and the United States where Tier 1 suppliers co-locate engineering centers with manufacturing clusters.
Market Restraints
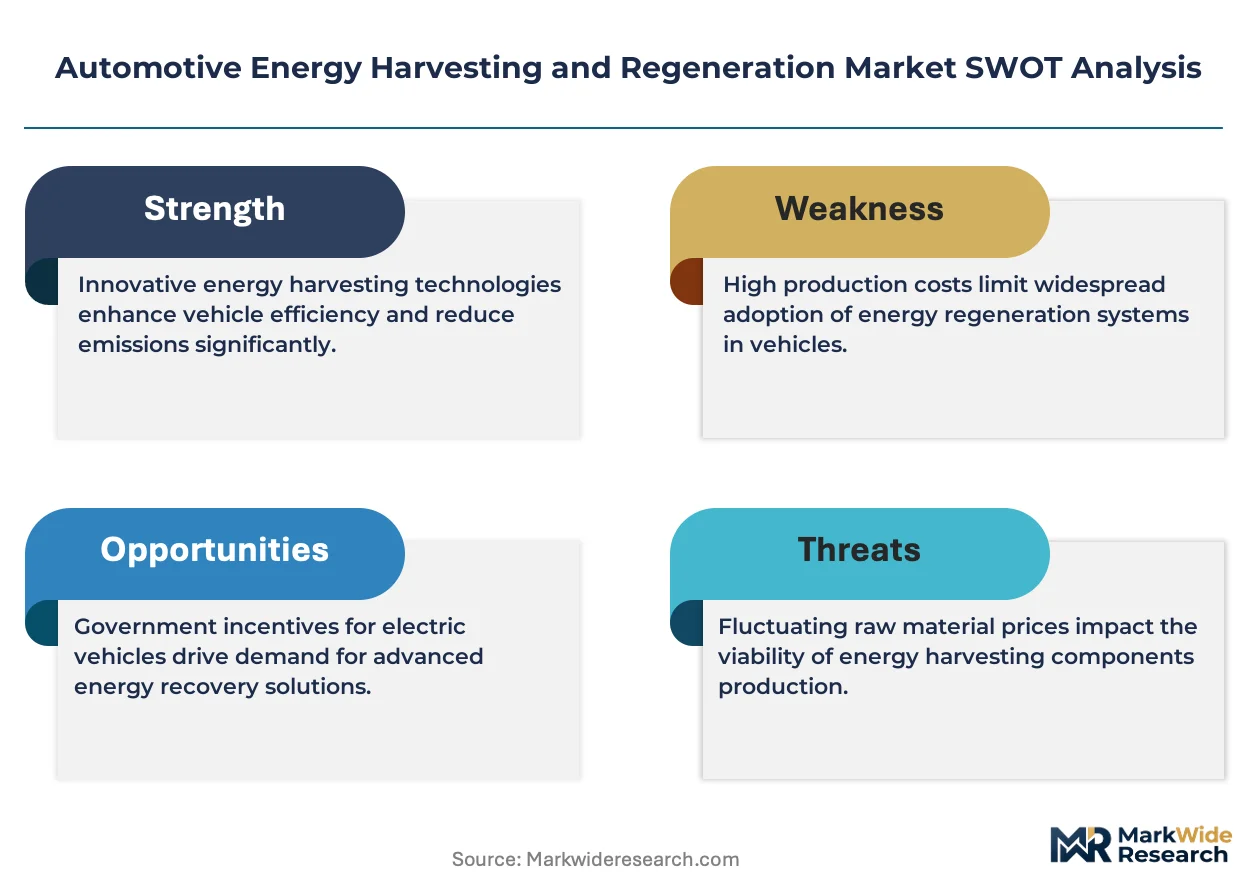
- Piezoelectric ceramic input cost volatility:Material composition rules under EMA and REACH constrain substrate sourcing flexibility for European vehicle assembly.
- High-voltage traction system supply concentration:800V component manufacturing clusters heavily in Germany and Japan, creating geographic dependency risk.
- Thermoelectric conversion efficiency ceiling:Exhaust waste heat capture rates remain technically bounded, limiting auxiliary power generation yields in heavy-duty applications.
Strategic Opportunities
- Software-defined regenerative calibration:Adaptive energy recovery algorithms embedded across hybrid platforms are absorbing engineering services revenue from hardware-only suppliers.
- Brake-by-wire system convergence:Integration of mechanical regeneration with digital vehicle dynamics control is opening margin pools for electronics-capable Tier 1s.
- Vibration energy density exploitation:Low-power sensor networks in cabin and chassis applications represent underpenetrated territory for piezoelectric device deployment.
Industry Challenges
- Multi-jurisdiction certification timeline alignment:Stakeholders must monitor EPA, EU Green Deal, and NHTSA regulatory calibration timelines simultaneously to maintain product qualification.
- Powertrain electronics skill scarcity:Embedded algorithm development and thermal management interface engineering require talent pools concentrated in Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Energy Harvesting and Regeneration Market |
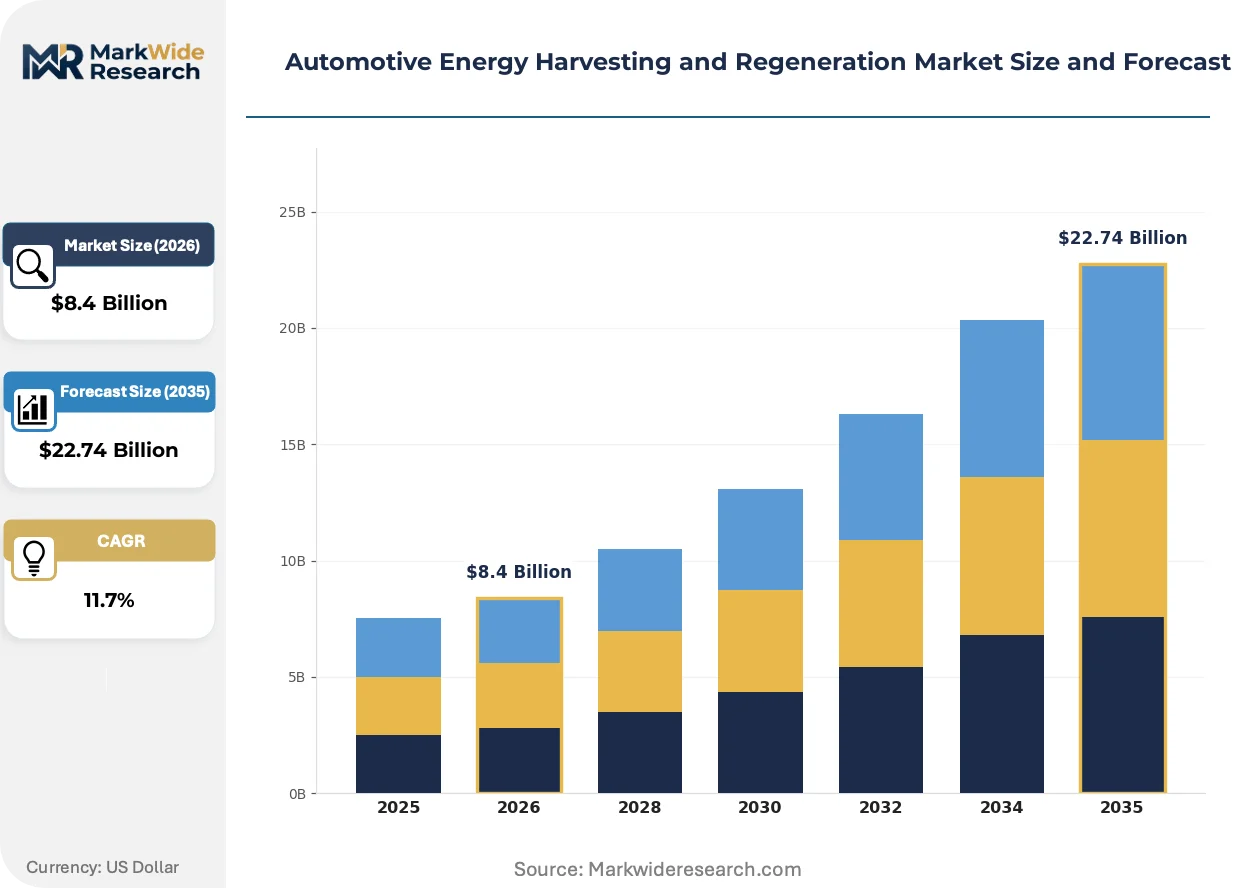
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regenerative Braking Systems, Thermoelectric Generators, Piezoelectric Devices, Kinetic Energy Recovery Systems Technology: Energy Storage, Energy Conversion, Sensors, Control Systems End User: OEMs, Aftermarket Providers, Fleet Operators, Automotive Manufacturers Application: Electric Vehicles, Hybrid Vehicles, Conventional Vehicles, Motorsport |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Gentherm Incorporated, Faurecia SA, Ricardo PLC, Tenneco Inc., Aptiv PLC, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Energy Harvesting and Regeneration Market Emerging Trajectories
Software-defined functionality is recalibrating supplier-OEM relationships across energy harvesting systems, while regulatory tightening and procurement model evolution reshape competitive requirements.
Brake-by-wire regeneration is absorbing mechanical component value as Continental AG and Robert Bosch GmbH embed digital control layers into integrated systems. Passenger vehicle OEMs in Germany are adopting these platforms fastest, compressing standalone brake supplier margins while expanding electronics contract scope.
REACH and RoHS material composition rules are forcing thermoelectric substrate reformulation across European vehicle assembly. The industrial consequence is extended qualification timelines for exhaust heat recovery modules. Heavy-duty truck OEMs targeting EU Green Deal compliance are absorbing these delays into product roadmaps.
Fleet efficiency target accountability is shifting procurement toward module-level performance guarantees rather than component specifications. Tier 1 suppliers now contract against recoverable energy output, not hardware delivery. This pattern concentrates in the United States where EPA tailpipe rules impose direct OEM liability.
Automotive Energy Harvesting and Regeneration Market Segmentation
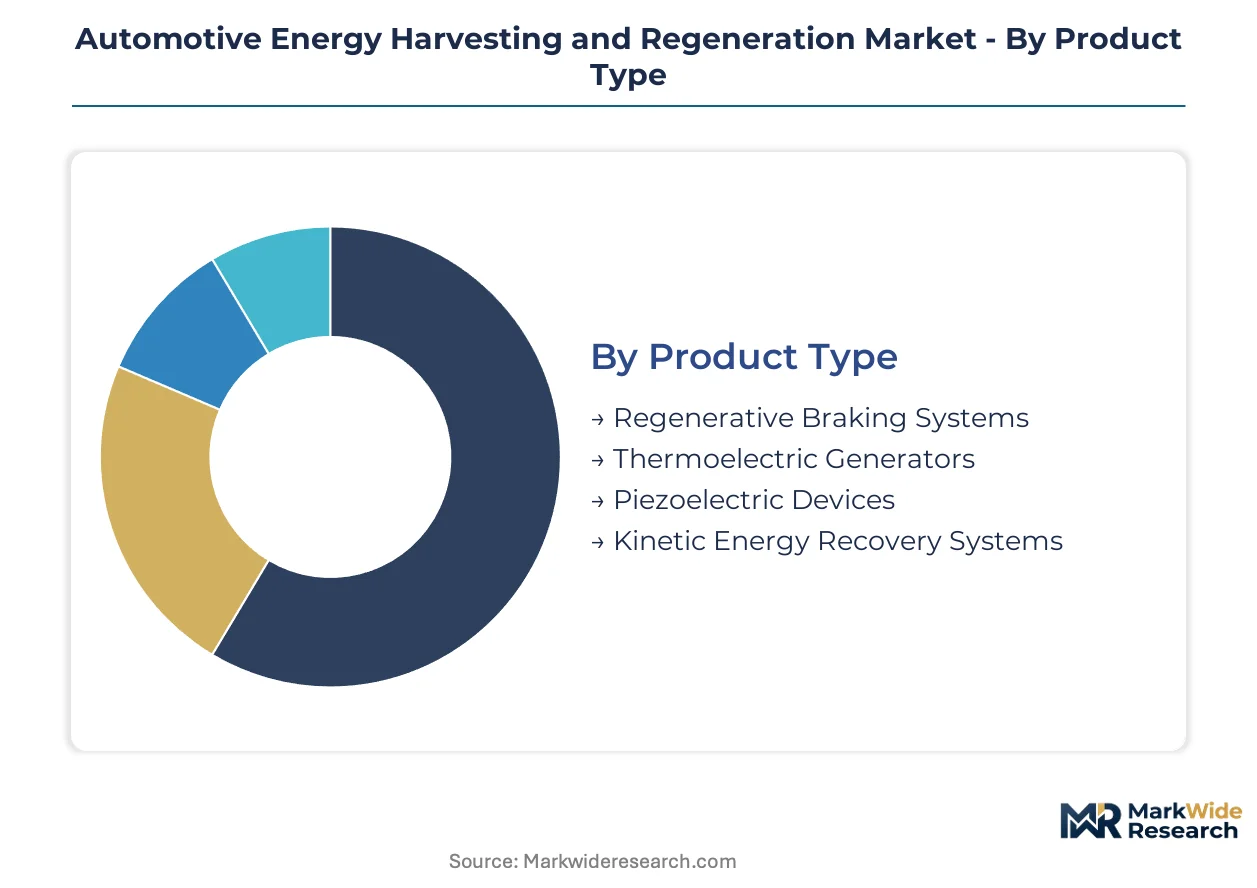
Automotive energy harvesting and regeneration technology deployment varies sharply by system architecture and voltage requirements. Product type segmentation reveals where engineering investment concentrates as OEMs balance efficiency gains against integration complexity.
Product Type:
Volume deployment favors regenerative braking systems, while premium pricing attaches to emerging thermal and vibration capture technologies.
- Regenerative Braking Systems:Kinetic-to-electrical conversion modules operating across 12V to 800V architectures dominate installed base. Passenger EV procurement in Germany and the United States concentrates demand as EPA and EU Green Deal mandates tighten fleet efficiency thresholds.
- Thermoelectric Generators:Exhaust waste heat recovery units utilizing semiconductor substrates capture thermal gradients for auxiliary power. Heavy-duty truck OEMs in Japan deploy these for idle-reduction compliance, though REACH material rules extend European qualification timelines.
- Piezoelectric Devices:Ceramic-based vibration harvesters power low-draw sensor networks in cabin and chassis applications.
- Kinetic Energy Recovery Systems:Flywheel-based mechanical storage competes in motorsport and select commercial vehicle prototypes.
Mature deployment sits with Regenerative Braking Systems. Newer deployment is concentrated in Thermoelectric Generators.
Technology:
Control and conversion layers command margin expansion as software-defined functionality displaces mechanical-only supply.
- Energy Storage:High-voltage battery interfaces and supercapacitor buffers manage power flow between harvesting sources and vehicle loads.
- Energy Conversion:DC-DC converters and power electronics modules transform variable harvester output into stable traction system voltage. Tier 1 suppliers in Germany embed adaptive algorithms here to meet OEM performance guarantees under EPA liability structures.
- Sensors:Current, temperature, and vibration transducers monitor system health and optimize recovery timing.
- Control Systems:Embedded software platforms coordinate multi-source harvesting across brake, thermal, and vibration inputs. Brake-by-wire integration in Japanese hybrid platforms absorbs engineering services revenue from hardware-only competitors.
Control Systems are climbing the fastest as procurement shifts toward module-level performance contracting.
End User:
Fleet-scale accountability is reshaping who specifies technical requirements and absorbs compliance risk.
- OEMs:Integrated vehicle manufacturers specify regenerative modules against direct EPA tailpipe liability in the United States.
- Aftermarket Providers:Retrofit specialists serve legacy fleet upgrades where factory regeneration was not fitted.
- Fleet Operators:Logistics and transit entities contract for energy recovery outcomes rather than component supply. Heavy-duty procurement in Germany concentrates here as EU Green Deal compliance deadlines approach.
- Automotive Manufacturers:Contract assemblers and platform specialists integrate Tier 1 modules into final vehicle architectures.
Procurement authority is concentrating with Fleet Operators. Technical specification authority remains with OEMs.
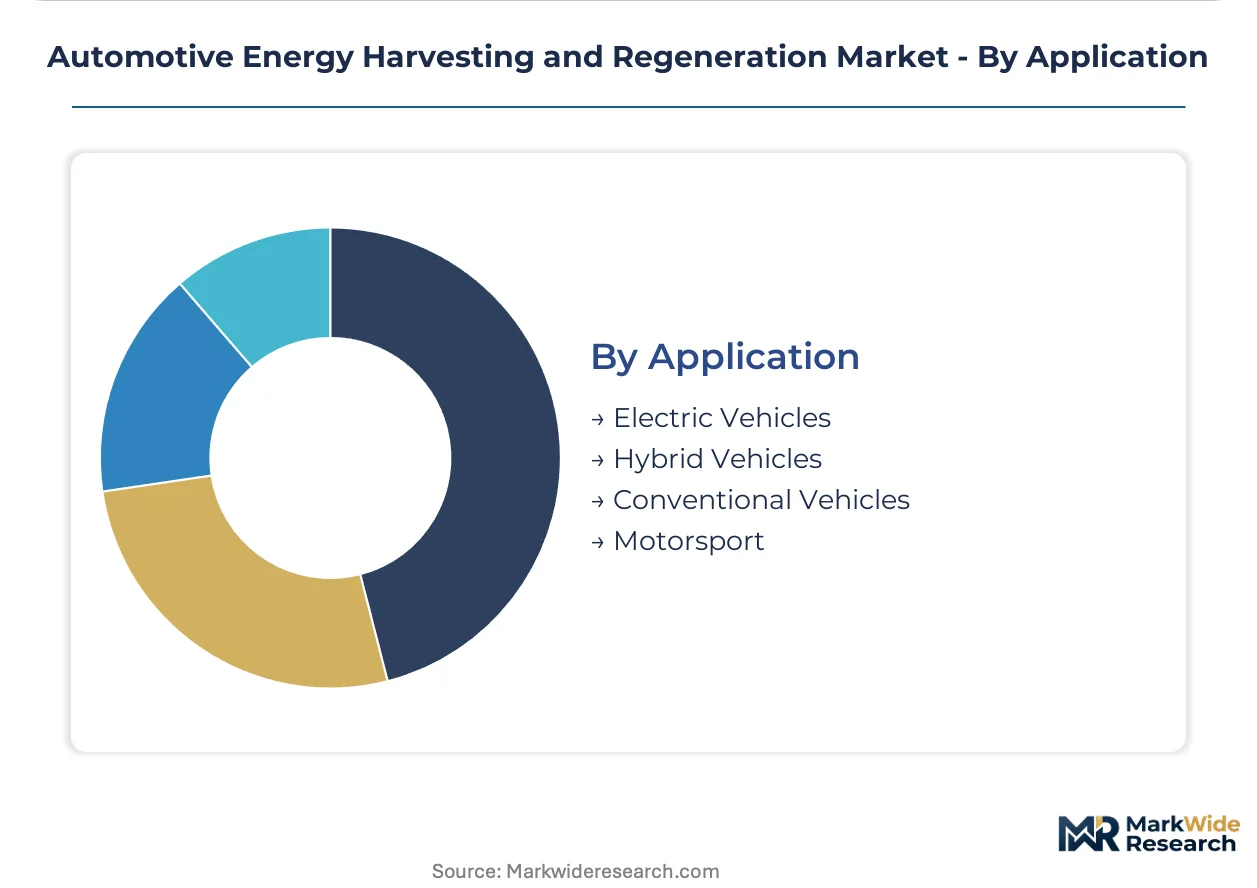
Application:
Electrification intensity determines harvester complexity and voltage architecture selection.
- Electric Vehicles:400V-800V traction systems mandate regenerative braking as primary range extension mechanism. Battery-electric platforms in the United States and Germany absorb the majority of high-voltage component output.
- Hybrid Vehicles:Dual-powertrain architectures optimize brake energy recovery alongside engine thermal management. Japanese OEMs lead integration density here, co-locating engineering with domestic Tier 1 electronics clusters.
- Conventional Vehicles:12V micro-hybrid systems capture limited brake energy for stop-start functionality.
- Motorsport:Kinetic recovery flywheels and extreme thermal harvesting serve FIA regulatory point systems.
Steepest expansion trajectory belongs to Electric Vehicles. Technical complexity peaks in Motorsport.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany, Japan, and the United States where Tier 1 suppliers co-locate engineering centers with automotive manufacturing clusters. Consumption spreads across these same markets as EPA and EU Green Deal mandates tighten recoverable-energy requirements for passenger and commercial vehicles.
United States
Fleet efficiency targets and EPA tailpipe emissions rules are accelerating electric vehicle OEM procurement of regenerative braking modules. NHTSA governs recoverable-energy credit mechanisms that determine product qualification for compliance. Detroit and the Southeast automotive corridor absorb the majority of high-voltage traction system manufacturing as suppliers expand 800V component capacity.
Germany
EU Green Deal framework mandates are creating mandatory fitment obligations across battery-electric and hybrid architectures. REACH and RoHS material composition rules constrain thermoelectric substrate sourcing for European vehicle assembly. Stuttgart and Munich anchor powertrain electronics engineering clusters where Bosch and Continental embed adaptive energy recovery algorithms.
Japan
Heavy-duty truck idle-reduction compliance is driving thermoelectric generator deployment for auxiliary power generation. METI standards coordinate with corporate average fuel economy targets to shape product development timelines. Nagoya and Tokyo metropolitan areas concentrate hybrid platform engineering where Denso specializes in thermal management interfaces.
China
Dual carbon goals and MIIT new energy vehicle mandates are expanding domestic regenerative braking system adoption across battery-electric platforms. GB standards govern high-voltage electrical safety for 400V-800V traction architectures. Shanghai and Shenzhen manufacturing clusters are absorbing capacity expansion from both domestic and joint-venture Tier 1 suppliers.
South Korea
Corporate carbon neutrality commitments from Hyundai-Kia and emerging battery-electric truck programs are creating demand for integrated energy recovery systems. MFDS and KSA standards intersect with automotive export requirements to shape certification protocols. Seoul Capital Area and Busan-Ulsan industrial zones concentrate electronics-capable supplier engineering for brake-by-wire integration.
Automotive Energy Harvesting and Regeneration Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the automotive energy harvesting value chain. The supplier base exhibits tiered concentration where integrated powertrain electronics specialists command premium positioning against mechanical component fabricators. Three archetypes dominate: full-system integrators owning brake-by-wire and thermal management interfaces; semiconductor substrate specialists supplying thermoelectric generator cores; and software-defined calibration providers absorbing engineering services revenue. Competitive moves center on strategic partnerships for 800V high-voltage component co-development and geographic expansion through engineering center co-location with OEM manufacturing clusters.
Among German-based integrated system suppliers, Robert Bosch GmbH and Continental AG exemplify the full-system integrator archetype through their embedded control platform portfolios. Denso Corporation occupies a position within the Japanese specialist tier, representing electronics-capable engineering concentration in thermal and powertrain interfaces. These three anchors illustrate how procurement authority is shifting toward module-level performance contracting rather than discrete component supply.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Gentherm Incorporated |
| Faurecia SA |
| Ricardo PLC |
| Tenneco Inc. |
| Aptiv PLC |
| ZF Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
Piezoelectric ceramic input cost volatility cascades through Tier 1 supplier pricing tiers as REACH material composition rules constrain substrate sourcing flexibility for European vehicle assembly, compressing margins on vibration harvester modules while elevating premium positioning for semiconductor-substrate thermoelectric generators.
Pricing Analysis
Cost-down pressure on standard-tier regenerative braking modules accelerates because OEM procurement is shifting toward module-level performance guarantees rather than component specifications. Three-tier pricing structure across premium, standard, and economy levels separates 800V high-voltage traction systems from 400V mid-tier architectures from 12V auxiliary circuits. Price differentiation traces to certification grade under EPA tailpipe rules and volume scale in fleet procurement contracts. Fleet operators exhibit highest price sensitivity due to direct energy recovery outcome accountability, while motorsport applications show lowest sensitivity given FIA regulatory point system requirements.
Supply Chain Analysis
Qualification timelines for exhaust heat recovery modules extend under REACH and RoHS substrate reformulation mandates, gating European market access for thermoelectric generator suppliers. Manufacturing concentrates in Germany, Japan, and the United States where Tier 1 engineering centers co-locate with automotive clusters. Semiconductor substrates for thermoelectric cores and high-voltage power electronics for traction systems anchor raw material dependencies. Single-source vulnerability concentrates in 800V component manufacturing clusters. Distribution runs through OEM direct procurement channels with aftermarket retrofit specialists serving legacy fleet upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as software-defined functionality absorbs engineering services revenue from hardware-only suppliers, forcing mechanical component fabricators toward strategic exit or electronics capability acquisition.
For Market Incumbents: Extend embedded algorithm development capabilities across brake-by-wire and thermal management interfaces to defend against electronics-capable competitors. Backward integration into semiconductor substrate sourcing mitigates REACH qualification timeline risk. Capacity addition in the United States Southeast automotive corridor captures EPA-driven OEM procurement acceleration. For New Entrants and Emerging Players: The price-point gap between premium 800V traction systems and economy 12V auxiliary circuits creates entry opportunity in 400V mid-tier hybrid architectures. White-space concentrates in piezoelectric cabin sensor networks where vibration energy density remains underexploited. Target aftermarket retrofit specialists serving legacy commercial fleets in Germany as the most penetrable channel. Go-to-market through fleet operator outcome-based contracting rather than OEM component supply. For Investors and Strategic Acquirers: Tier 1 supplier acquisition of software-defined calibration providers is the leading indicator that procurement authority has permanently shifted toward module-level performance contracting. Long-term viability favors full-system integrators owning brake-by-wire and thermal management interfaces over standalone mechanical fabricators. Target acquisition archetype: electronics-capable engineering shops with embedded control platforms and OEM qualification relationships. Signal to watch: EPA enforcement action accelerating under revised tailpipe emissions rules.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Adaptive energy recovery algorithms embedded across hybrid platforms absorb engineering services revenue from hardware-only competitors. |
| Battery Supply Agreement | High-voltage battery interfaces anchor power flow management between harvesting sources and 800V traction loads. |
| Platform Standardization | Brake-by-wire system convergence merges mechanical regeneration with digital vehicle dynamics control. |
| Geographic Manufacturing Footprint | Engineering center co-location with OEM clusters in Germany, Japan, and the United States accelerates qualification timelines. |
| Charging Infrastructure Partnership | Integrated energy recovery systems align with fleet electrification roadmaps and EU Green Deal compliance deadlines. |
Methodological Framework
Multi-period observation of vehicle production databases, IHS Markit registration data, and Tier 1 supplier engineering center expansion patterns anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers. Secondary validation drew from EPA tailpipe emissions filings, EU Green Deal regulatory calibration timelines, NHTSA recoverable-energy credit mechanism documentation, and REACH material composition rule updates. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-weighting across product type, technology layer, end-user archetype, application, and regional production cluster shaped the analytical framework. CAGRs were derived from installed base expansion modeling and replacement cycle dynamics throughout the forecast period. Vehicle electrification intensity curves and fleet efficiency target accountability patterns served as automotive-specific forecast inputs.
Inputs from OEM platform engineering disclosures and Tier 1 supplier qualification timelines were available through the study window; gaps in heavy-duty truck thermoelectric generator deployment data introduce uncertainty bands around idle-reduction compliance adoption curves. Forecasts reflect assumptions regarding EPA enforcement consistency and EU Green Deal mandate calibration. A model refresh is warranted upon material change in NHTSA recoverable-energy credit mechanism structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Van Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Middle-East E-Bike Market
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
E-SUV Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
Wireless Electric Vehicle Charging Market
Electric Vehicles
Canada E-Bike Market