
 Vietnam Solar E-Bike Market | 2026-2036
Vietnam Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Solar E-Bike Market Insights
Urban logistics is pivoting toward solar e-bikes as delivery services seek to trim operating expenditures. VinFast leverages its domestic manufacturing scale to control component costs across the Mekong Delta. Dat Bike anchors its position through in-house battery assembly and proprietary motor design. Pega competes on price-sensitive commuter segments while sustaining dealer density in secondary provinces.
A solar e-bike integrates photovoltaic cells into frame surfaces or detachable panels to supplement lithium-ion battery charge, extending range without grid dependency for urban and peri-urban mobility. Urban E-Bikes dominate unit volume due to commuter density in Hanoi and Da Nang, while Cargo E-Bikes capture expanding margin pools from delivery service procurement. Battery Technology stratification shows lithium-ion packs leading replacement cycles as lead acid faces phase-out pressure from national efficiency mandates.
Vietnam's Ministry of Transport and the national standards body shape vehicle classification and safety certification for electric two-wheelers, with import duty structures on solar components influencing local assembly economics. The country's national green growth strategy and provincial air quality directives are tightening emission norms for internal combustion engines, redirecting fleet procurement toward electrified alternatives. Stakeholders must monitor how rapidly charging infrastructure standards crystallize and whether solar panel efficiency gains alter total cost of ownership calculations for fleet operators.
Market Dynamics
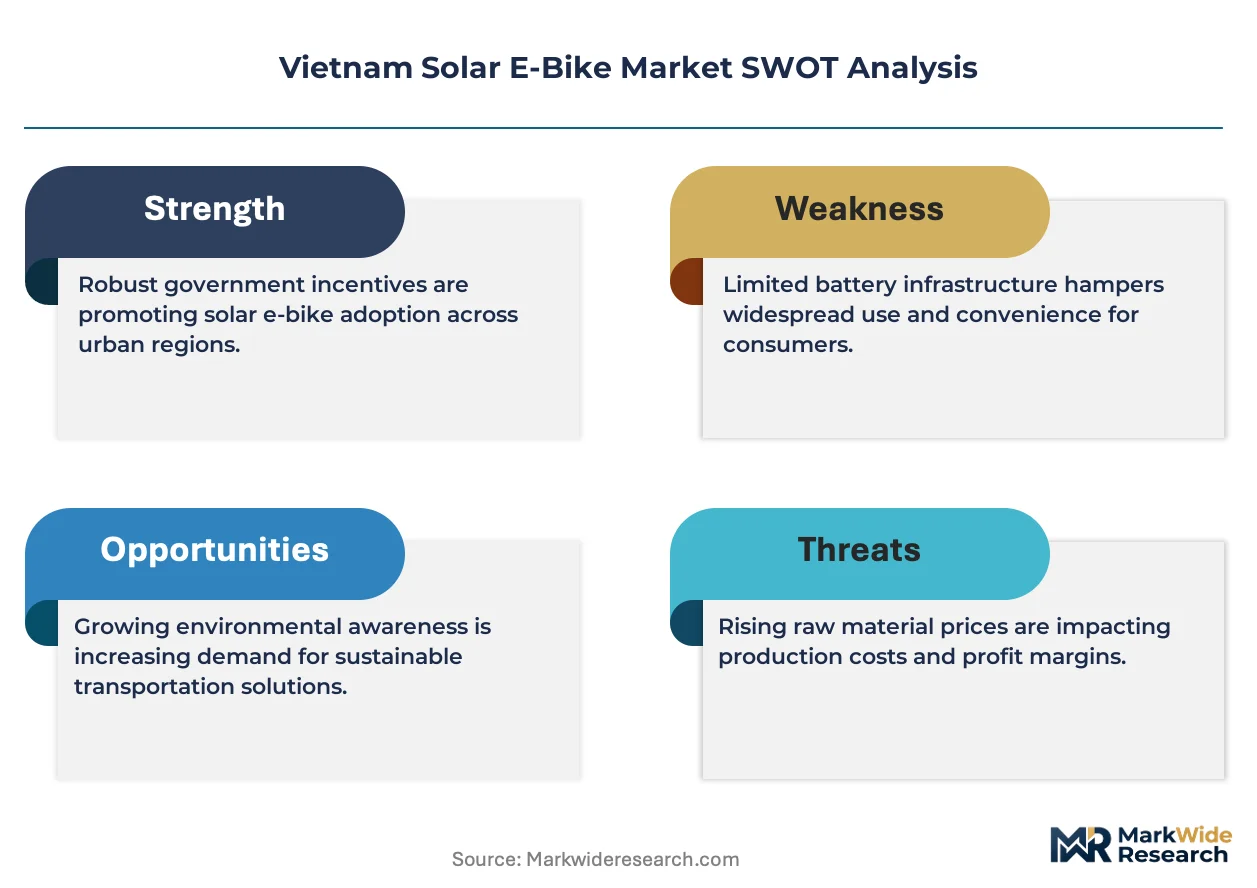
Last-mile delivery fleets in Vietnam are accelerating solar e-bike procurement as fuel cost volatility erodes internal combustion economics and national efficiency mandates tighten compliance windows for urban logistics operators.
Growth Catalysts
- National Green Growth Strategy:Vietnam's emission reduction targets redirect fleet procurement toward electrified alternatives, creating guaranteed demand pools for solar-assisted two-wheelers in commercial logistics.
- Solar irradiance concentration:Ho Chi Minh City and Mekong Delta industrial corridors receive sufficient photovoltaic exposure to support meaningful panel integration without grid dependency for daily charging cycles.
- Lead-acid phase-out pressure:National efficiency mandates are compressing replacement cycles toward lithium-ion packs, opening upgrade revenue streams for integrated solar-battery systems.
Market Restraints
- Import duty structures:Solar component tariffs inflate local assembly costs, compressing margin pools for domestic manufacturers against fully-imported conventional e-bike alternatives.
- Charging infrastructure standards:Uncrystallized technical specifications from Vietnam's national standards body create product certification friction and delay fleet-scale deployment timelines.
- Panel efficiency limitations:Current photovoltaic conversion rates on mobile surfaces limit meaningful range extension, constraining value propositions for long-haul delivery routes.
Strategic Opportunities
- Secondary province dealer networks:Density gaps in central and northern Vietnamese provinces beyond Hanoi and Da Nang create whitespace for solar e-bike distribution expansion before incumbent saturation.
- Peri-urban cargo applications:Agricultural supply chains and rural last-mile delivery present untapped use cases where grid infrastructure is sparse and solar self-sufficiency carries premium value.
- Battery-swapping convergence:Integration of photovoltaic charging with emerging swap-station networks could eliminate downtime constraints currently limiting fleet operator adoption thresholds.
Industry Challenges
- Photovoltaic integration engineering:Frame-embedded cell durability under vibration, moisture, and impact stress requires specialized R&D capabilities scarce in Vietnam's current supplier base.
- Dual certification timelines:Vehicle classification ambiguity between solar-assisted and standard electric two-wheelers forces manufacturers through overlapping safety review processes with Vietnam's Ministry of Transport.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Solar E-Bike Market |
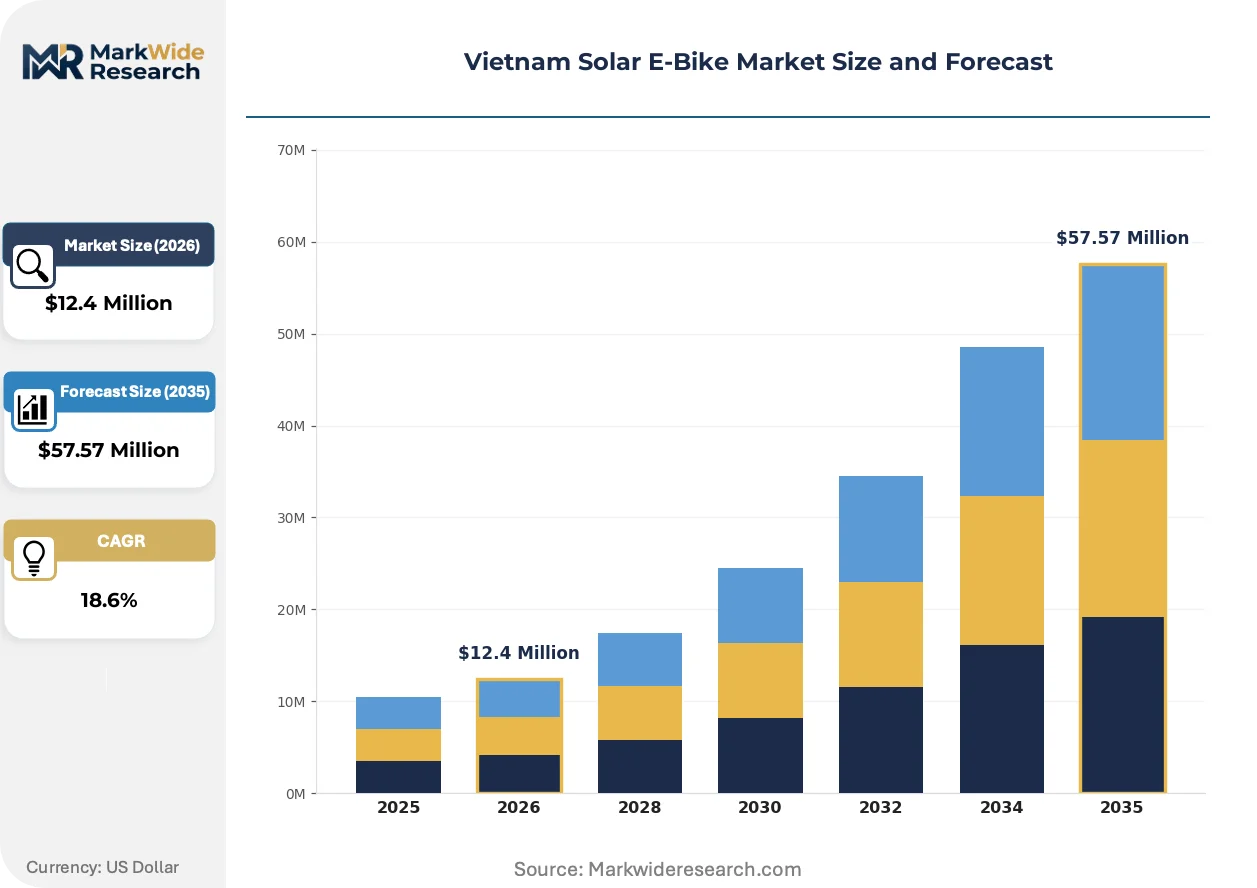
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $57.57 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urban E-Bikes, Off-Road E-Bikes, Folding E-Bikes, Cargo E-Bikes End User: Individuals, Delivery Services, Rental Services, Corporate Fleets Battery Technology: Lithium-Ion, Lead Acid, Nickel-Metal Hydride, Solid-State Sales Channel: Online Retailers, Physical Stores, Direct Sales, Distributors |
| Companies Covered | VinFast, Dat Bike, Pega, Honda, Yamaha, Yadea, Dibao, Anbico, Asama, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Solar E-Bike Market Trends and Innovations
Photovoltaic integration is moving from accessory add-on to core frame architecture, while regulatory pressure on urban emissions compresses procurement decision cycles for commercial fleet operators.
Perovskite-enhanced silicon photovoltaic cells are consolidating into solar e-bike designs as manufacturers seek higher conversion efficiency from limited surface area. Delivery fleet operators in Ho Chi Minh City's industrial zones are piloting these configurations to reduce grid charging dependency during peak tariff periods. The technology is consolidating supplier tiers around cell providers capable of meeting automotive-grade durability standards.
Vietnam's Ministry of Transport and national standards body are tightening vehicle classification protocols for electric two-wheelers with auxiliary power generation. The industrial consequence is a bifurcation between retrofit solar kits and factory-integrated systems, with the latter capturing fleet procurement preference due to streamlined homologation. Cargo e-bike segments face the steepest compliance burden as weight and power thresholds trigger commercial vehicle review.
Fleet operators are unbundling after-sales service contracts from hardware procurement, pressuring manufacturers to certify third-party maintenance networks. This procurement model change disrupts traditional dealer-dependent revenue structures and favors brands with standardized battery and panel architectures. The shift is most visible in Hanoi and Da Nang, where delivery service density supports dedicated technical service depots independent of retail channels.
Vietnam Solar E-Bike Market Segmentation
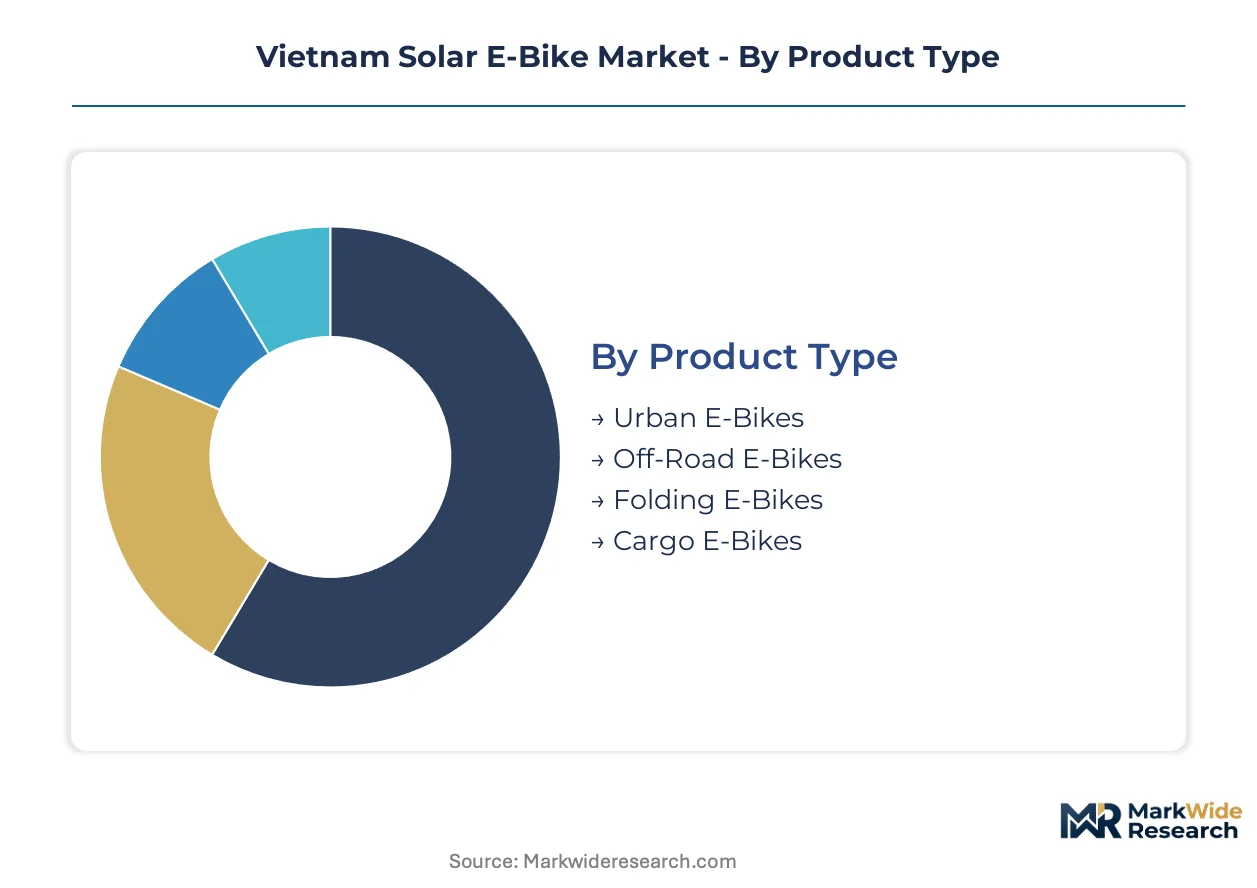
Vietnam's solar e-bike market fragments across four critical dimensions that determine pricing power, distribution economics, and regulatory exposure. Understanding these splits reveals where margin pools concentrate and which technology transitions will reshape competitive positioning over the forecast window.
Product Type:
Volume concentrates in commuter-optimized configurations while premium pricing attaches to specialized commercial applications.
- Urban E-Bikes:Frame-integrated photovoltaic cells supplement lithium-ion packs for daily commuting distances. Ho Chi Minh City and Hanoi account for the bulk of procurement as municipal emission directives tighten last-mile logistics compliance.
- Cargo E-Bikes:Reinforced chassis accommodate larger panel surfaces and heavier battery packs for commercial freight. Delivery services in Da Nang's industrial zones are piloting solar-assisted cargo configurations to reduce grid charging dependency during peak tariff periods.
- Off-Road E-Bikes:Ruggedized panel mounting suits agricultural and peri-urban terrain where grid infrastructure is sparse.
- Folding E-Bikes:Detachable solar arrays address space-constrained urban storage in high-density residential districts.
Today's leader: Urban E-Bikes. Tomorrow's challenger: Cargo E-Bikes.
End User:
Procurement patterns diverge sharply between price-sensitive individual buyers and total-cost-of-ownership-driven fleet operators.
- Delivery Services:Fleet-scale operators negotiate hardware-service unbundling and demand standardized battery architectures. Vietnam's Ministry of Transport vehicle classification protocols favor factory-integrated solar systems over retrofit kits for commercial homologation.
- Corporate Fleets:Employee mobility programs and campus logistics drive bulk procurement with dedicated technical service requirements.
- Individuals:Commuter density in secondary provinces beyond Hanoi and Da Nang creates whitespace before incumbent saturation.
- Rental Services:Shared mobility operators prioritize swap-compatible battery systems to minimize downtime.
Fleet operators now capture margin through operational efficiency rather than volume scale alone.
Battery Technology:
Efficiency mandates are compressing replacement cycles toward advanced chemistries that integrate with photovoltaic charging architectures.
- Lithium-Ion:Dominates replacement cycles as national efficiency mandates phase out lead-acid alternatives. Integrated solar-battery systems open upgrade revenue streams for manufacturers with in-house pack assembly.
- Solid-State:Emerging configurations promise higher energy density for limited frame space, though automotive-grade durability standards remain unproven in Vietnam's supplier base.
- Lead Acid:Faces phase-out pressure from national efficiency mandates, constraining addressable market.
- Nickel-Metal Hydride:Transitional chemistry losing share to lithium-ion cost parity.
Lithium-Ion holds installed base. Solid-State climbs the fastest.
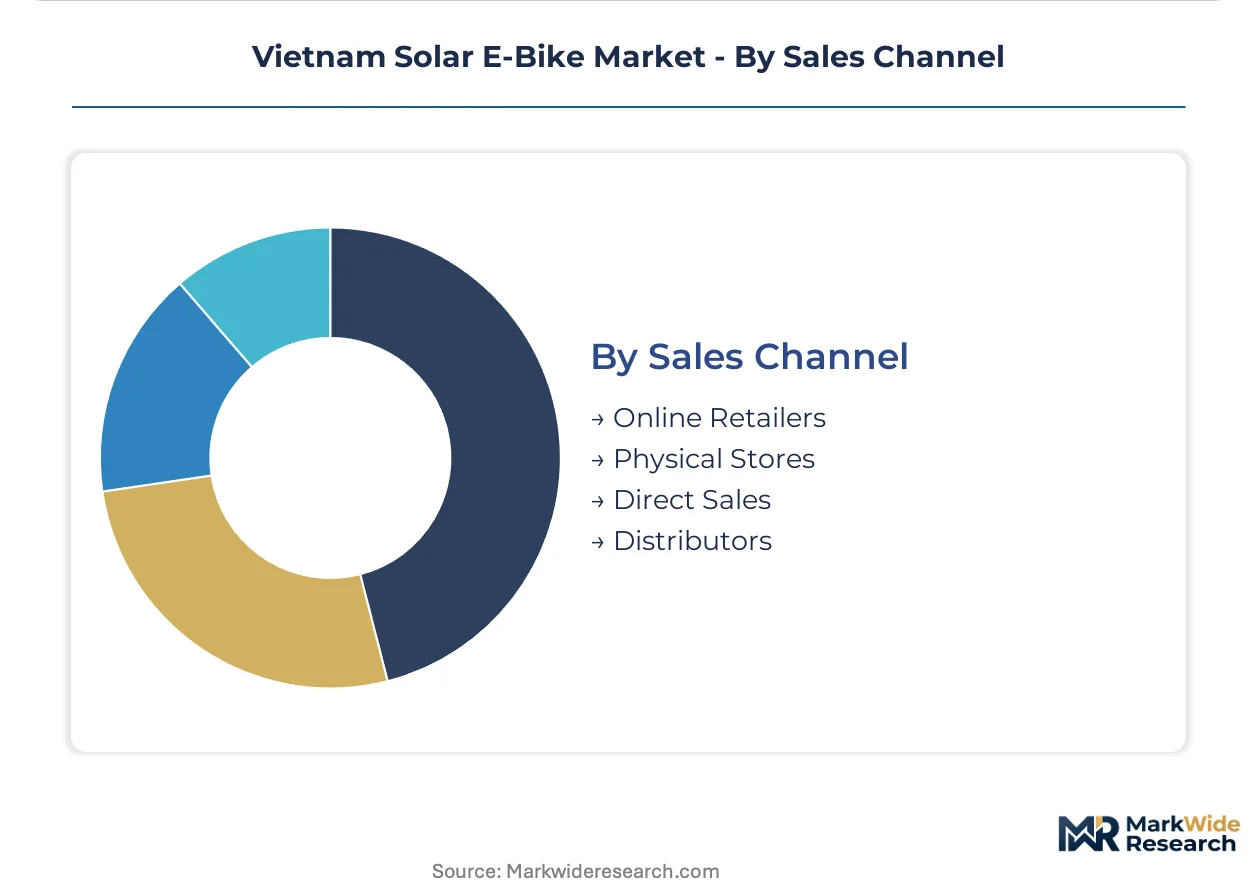
Sales Channel:
Distribution economics shift as fleet procurement bypasses traditional retail dependencies.
- Direct Sales:Large fleet operators negotiate hardware-procurement-only contracts, pressuring manufacturers to certify third-party maintenance networks independent of dealer channels.
- Distributors:Density gaps in central and northern Vietnamese provinces create whitespace for solar e-bike expansion before saturation.
- Physical Stores:Traditional dealer-dependent revenue structures face disruption from unbundled service models.
- Online Retailers:Price-transparent platforms suit individual commuter segments with standardized product specifications.
Direct Sales gains share fastest as fleet procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production arbitrage is steering assembly capacity toward provinces where Vietnam's Ministry of Transport maintains lighter homologation burdens for factory-integrated solar systems versus retrofit kit imports.
Ho Chi Minh City
Industrial corridor density and elevated solar irradiance attract fleet procurement from last-mile delivery operators. The municipal People's Committee enforces stricter emission compliance windows for urban logistics than national baselines. District 12 and Thu Duc City host technical service depots where delivery services pilot perovskite-enhanced panel configurations.
Hanoi
Commuter volume concentration drives urban e-bike replacement cycles as national efficiency mandates phase out lead-acid alternatives. The city's Department of Transport coordinates with Vietnam's national standards body on charging infrastructure siting. Cau Giay and Hai Ba Trung districts concentrate dealer networks facing disruption from unbundled hardware-service procurement models.
Da Nang
Secondary city whitespace and industrial zone expansion create cargo e-bike demand pools before incumbent saturation. Provincial authorities align with national green growth strategy targets for fleet electrification. Lien Chieu and Hoa Khanh industrial parks host delivery service pilots reducing grid charging dependency through solar-assisted configurations.
Can Tho
Mekong Delta agricultural supply chains present peri-urban cargo applications where grid infrastructure remains sparse. Provincial People's Committee regulations favor electrified alternatives for rural last-mile delivery under national emission reduction frameworks. Ninh Kieu and Cai Rang districts anchor distribution networks penetrating central Delta provinces.
Vietnam Solar E-Bike Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic manufacturers scale in-house battery assembly to capture lithium-ion replacement revenue streams. The vendor base stratifies between vertically integrated domestic assemblers, regional component importers, and multinational two-wheeler incumbents pivoting toward electrified lineups. Three archetypes occupy distinct competitive positions: integrated domestic manufacturers controlling upstream cell supply, price-optimized assemblers sourcing standardized kits, and legacy motorcycle brands leveraging dealer density for electrification transitions. M&A activity concentrates on battery technology acquisitions, while strategic partnerships proliferate around photovoltaic charging infrastructure deployment.
Among integrated domestic manufacturers, VinFast and Dat Bike exemplify the captive supply archetype through in-house component production. Pega occupies a position within the price-optimized tier, competing on dealer density penetration in secondary provinces beyond core urban markets. These three Vietnamese entities anchor the competitive structure against regional import competition and legacy multinational entrants.
| Leading Market Players |
|---|
| VinFast |
| Dat Bike |
| Pega |
| Honda |
| Yamaha |
| Yadea |
| Dibao |
| Anbico |
| Asama |
| Others |
Pricing and Supply Chain Analysis
Perovskite-enhanced photovoltaic cell adoption is compressing manufacturing cost curves while simultaneously redrawing supplier tier boundaries around automotive-grade durability certification. Vietnam's Ministry of Transport homologation requirements for factory-integrated solar systems create cost premiums that retrofit kit imports cannot match, concentrating pricing power among domestic assemblers with captive cell supply.
Pricing Analysis
Distributor margin compression in secondary provinces is forcing manufacturers toward direct fleet contracts that bypass traditional retail markups. Three-tier pricing structure across premium, standard, and economy levels separates VinFast's integrated factory systems from Pega's price-optimized kits and regional import alternatives. Cost compression in the economy tier is intensifying because import duty structures on solar components inflate local assembly economics. Individual commuters in Hanoi and Da Nang exhibit highest price sensitivity, while delivery services prioritize total cost of ownership over upfront hardware outlay.
Supply Chain Analysis
Dual-sourcing mandates from fleet operators are fragmenting cell procurement between Chinese photovoltaic suppliers and emerging Vietnamese domestic producers. Lithium-ion cell supply draws from China, South Korea, and Japan, while frame-embedded photovoltaic modules source primarily from Chinese tier-1 manufacturers. Single-source vulnerability in automotive-grade perovskite cell supply creates certification bottlenecks for manufacturers lacking established supplier relationships. Distribution runs through Ho Chi Minh City and Hanoi technical service depots that bypass traditional dealer networks for fleet-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's national green growth strategy operates as a regulatory compounder, with provincial emission compliance windows for urban logistics fleets guaranteeing demand pools for electrified alternatives.
For Market Incumbents: To counter price-optimized import competition from Chinese kit assemblers, VinFast and Dat Bike should deepen backward integration into lithium-ion cell production and secure exclusive perovskite supplier agreements. Certification investment in Vietnam's Ministry of Transport factory-integrated homologation protocols creates switching costs that retrofit competitors cannot replicate. Channel control through proprietary technical service depots in District 12 and Thu Duc City locks in fleet operator relationships.
For New Entrants and Emerging Players: Vietnam's Ministry of Transport vehicle classification protocols in cargo e-bike segments open a window for specialized manufacturers targeting commercial homologation gaps left by commuter-focused incumbents. Peri-urban agricultural supply chains in Can Tho and the Mekong Delta present the most penetrable whitespace before grid infrastructure expansion. A battery-swapping convergence go-to-market angle addresses fleet downtime constraints that current solar charging speeds cannot resolve.
For Investors and Strategic Acquirers: Valuations sit cheapest among price-optimized assemblers lacking in-house battery production, as lithium-ion replacement cycle revenue streams concentrate with integrated manufacturers. Long-term viability over the next decade hinges on photovoltaic efficiency gains altering total cost of ownership calculations for commercial operators. The signal to watch is crystallization of Vietnam's national standards body charging infrastructure specifications, which would trigger fleet-scale deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Cell Supplier Partnership | Secures automotive-grade durability certification from tier-1 Chinese photovoltaic manufacturers. |
| Battery Swapping Infrastructure Deployment | Eliminates fleet downtime constraints through integration with Vietnam's emerging swap-station networks. |
| Secondary Province Dealer Expansion | Captures whitespace in central and northern Vietnamese provinces before incumbent saturation. |
| Factory-Integrated Homologation Investment | Streamlines Vietnam's Ministry of Transport certification for commercial fleet procurement preference. |
| Third-Party Technical Service Certification | Supports unbundled hardware-service procurement models disrupting traditional dealer revenue structures. |
Research Methodology
Coverage spans Vietnam's four primary urban-industrial clusters, with primary inputs from each region's fleet operators and component suppliers. The research combines structured interviews with delivery service procurement directors, electric two-wheeler manufacturing executives, and Vietnam's Ministry of Transport regulatory affairs specialists with secondary validation from customs trade records, national standards body technical specifications, and provincial People's Committee emission directives. Bottom-up unit shipment modeling and top-down value estimation triangulate market size across the analysis window.
Rate-of-change decomposition separates volume growth from pricing evolution across product type, battery technology, end user, and sales channel segmentation dimensions. CAGRs derive from logistic diffusion curves fitted to fleet procurement timelines and individual replacement cycle patterns. Photovoltaic efficiency improvement trajectories and lithium-ion cost decline curves feed directly into total cost of ownership calculations for commercial operator adoption thresholds.
Revisions become necessary when Vietnam's national standards body crystallizes charging infrastructure specifications or when solar component import duty structures shift materially. Forecasts reflect documented assumptions regarding fleet electrification compliance windows and perovskite cell durability validation timelines. Deviation in provincial emission directive enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
South Korea E-Bike Market
Electric Vehicles
India Electric Car Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
UK Electric Vehicle Market
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
Electric Vehicle Control Unit Market
Electric Vehicles
Vietnam Electric Vehicle Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Vehicle Relay Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
Middle-East and Africa Electric Vehicle (EV) Fluids Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market