
 Automotive Battery Thermal Management System Market | 2026-2036
Automotive Battery Thermal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Thermal Management System Market Intelligence
Direct sourcing by automotive OEMs from specialized component manufacturers is reshaping the traditional tiered supply chain. MAHLE leverages its expertise in engine components to offer integrated thermal management modules for electric vehicles. Hanon Systems specializes in automotive climate control and thermal solutions, competing on system-level efficiency. Continental extends its broad electronics and powertrain portfolio to include sophisticated battery management systems that incorporate thermal control functions.
An automotive battery thermal management system is an integrated assembly designed to regulate a battery pack's temperature, typically maintaining it between 15°C and 35°C. Its primary function is to optimize battery performance, extend lifespan, and prevent thermal runaway events. Within technology segments, liquid cooling systems dominate due to their efficiency in high-power applications. The market is also seeing a shift towards active systems over passive ones for precise temperature control in next-generation electric vehicles.
Safety regulations, including China's GB standards and EU battery regulations under the Green Deal, mandate stringent thermal runaway prevention, directly influencing system design. In the United States, NHTSA oversight on vehicle safety standards compels automakers to adopt more effective thermal management solutions. Component suppliers must now decide between developing standardized, cost-effective modules for mass-market EVs or highly customized, performance-oriented systems for premium segments.
Market Dynamics
The central tension defining the market is the bifurcation of system design between cost-optimized modules for mass-market electric vehicles and high-performance, complex systems for premium models. This divergence is driven by the rapid evolution of battery chemistries and energy densities.
Growth Catalysts
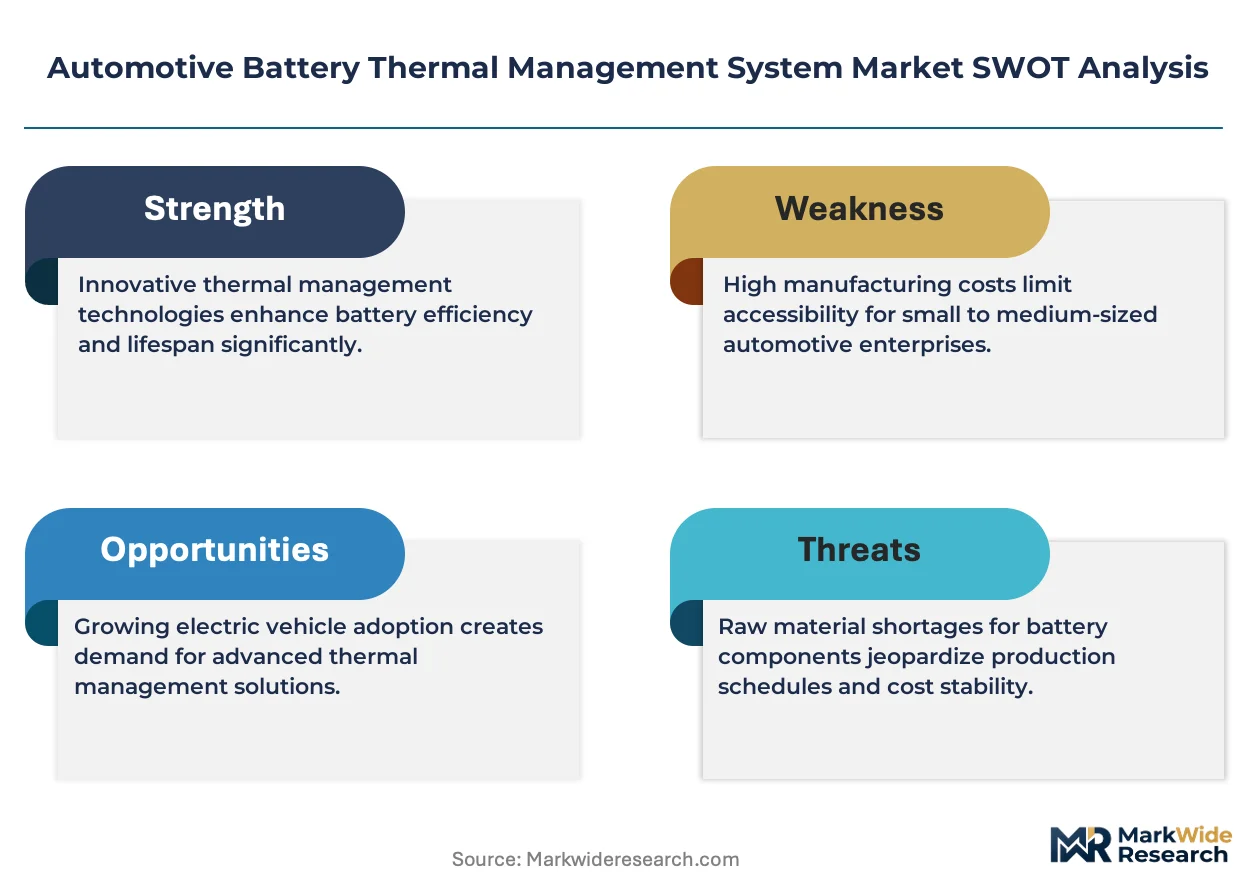
- Stringent Safety Mandates:Regulations like China's GB 38031 standard, which includes thermal runaway propagation tests, and EU battery regulations under the Green Deal directly compel automakers to integrate more sophisticated active thermal management systems.
- High-Energy-Density Batteries:The automotive industry's shift towards nickel-rich cathodes like NMC 811 and future solid-state chemistries generates significantly more heat, making advanced liquid cooling a prerequisite for performance and safety.
- Charging Infrastructure Expansion:The build-out of DC fast-charging networks enables higher power delivery to batteries, which in turn necessitates more robust thermal management to handle the resulting heat loads and maintain battery health.
Market Restraints
- System Cost and Complexity:The high upfront cost of active liquid cooling systems, including components like pumps, chillers, and specialized coolants, presents a significant barrier for adoption in budget-conscious, entry-level electric vehicle segments.
- Component Supply Chain Bottlenecks:The supply of critical components, such as high-precision sensors and specialized aluminum for cold plates and heat exchangers, is concentrated among a few suppliers, creating potential price volatility and lead-time risks.
- Integration Challenges:Integrating the battery thermal management system with the vehicle's main electronic control unit and HVAC system is technically complex, requiring significant R&D investment and validation time for automakers.
Strategic Opportunities
- Commercial Vehicle Electrification:Electric buses and trucks, with their large battery packs and demanding duty cycles, represent a significant opportunity for specialized, high-capacity thermal management solutions tailored for heavy-duty applications.
- Integrated Thermal Modules:The convergence of battery cooling, cabin climate control, and powertrain thermal management into a single, smart "heat pump" system offers a major opportunity for suppliers to deliver higher value and improved vehicle efficiency.
- Aftermarket and Service Solutions:As the global EV fleet ages, a market for replacement thermal management components, coolant flushing services, and diagnostic tools is emerging, offering a new revenue stream for specialized suppliers and service centers.
Industry Challenges
- Lack of Battery Pack Standardization:The wide variation in battery cell formats (cylindrical, pouch, prismatic) and pack designs across different automakers prevents the development of universal, off-the-shelf thermal management modules, increasing design costs.
- Cross-Disciplinary Talent Scarcity:A shortage of engineers possessing a combined expertise in thermodynamics, fluid dynamics, power electronics, and battery chemistry hinders rapid innovation and system optimization for component suppliers and OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Thermal Management System Market |
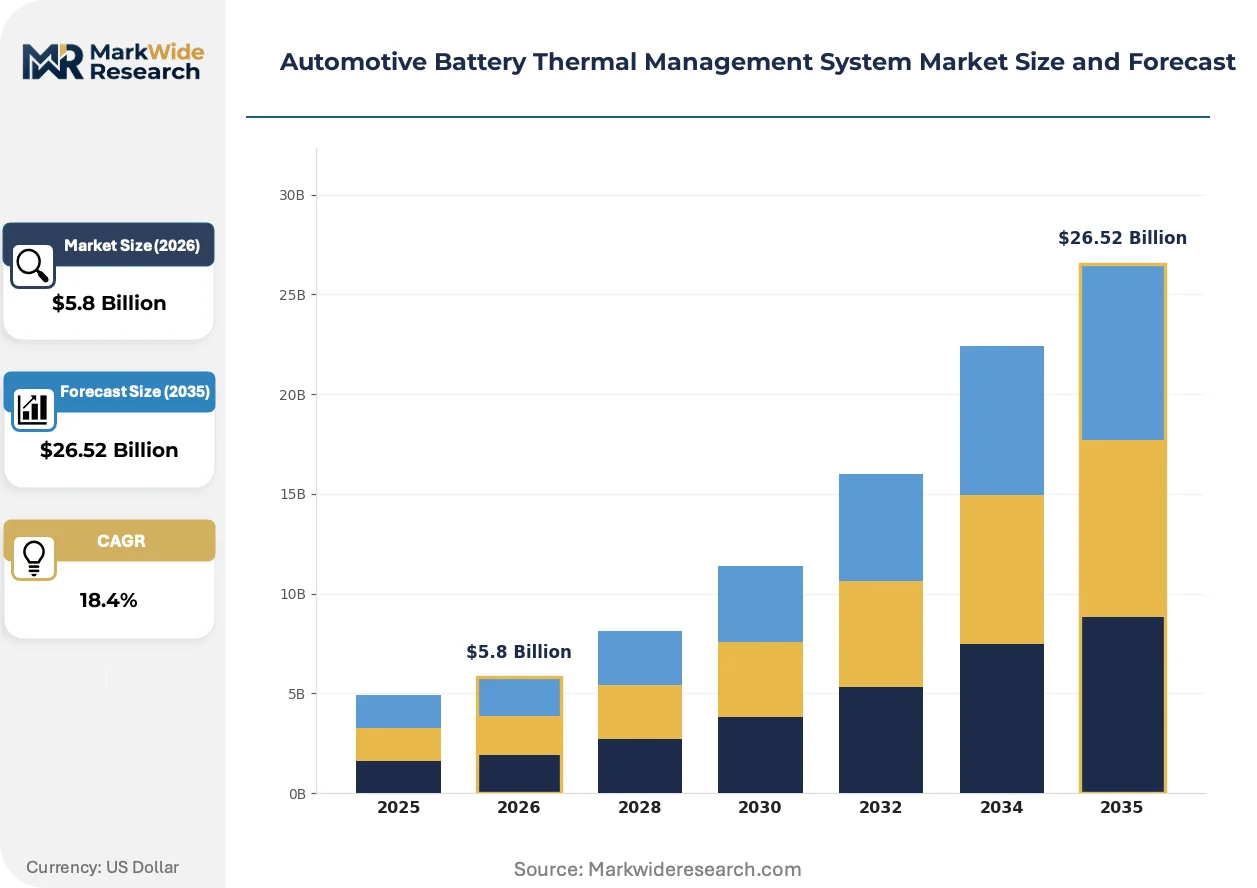
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $26.52 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Active, Passive, Hybrid, Phase Change Material Technology: Liquid Cooling, Air Cooling, Refrigerant Cooling, Heat Pipe Cooling, Thermoelectric Cooling Application: Electric Vehicles, Hybrid Vehicles, Commercial Transport, Two-Wheelers, Off-Road Vehicles End User: OEMs, Fleet Operators, Aftermarket Service Providers, Battery Manufacturers |
| Companies Covered | Robert Bosch, Continental, DENSO Corporation, Valeo, Hanon Systems, MAHLE, Dana, GENTHERM, LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Thermal Management System Market Strategic Shifts & Innovations
System design is evolving beyond a purely safety-focused role into a critical enabler of overall vehicle performance, efficiency, and charging speed. This shift elevates the thermal management system's importance within the electric vehicle architecture, making it a key point of competitive differentiation.
Immersion cooling, which utilizes dielectric fluids to directly contact and cool battery cells, provides superior heat transfer compared to indirect methods. High-performance EV and electric motorsport segments are the primary adopters, seeking to manage the intense heat generated during extreme fast charging and high-power discharge. The market's core thermal architecture is migrating from conventional cold plates toward these more complex but highly effective direct-contact cooling solutions for premium applications.
New regulations under the EU Green Deal, particularly the Battery Regulation, introduce mandates for battery durability, performance, and carbon footprint reporting. This directly impacts system design by requiring thermal management to not only ensure safety but also actively extend battery lifespan to meet regulatory longevity targets. Consequently, suppliers targeting the European Union are prioritizing system efficiency and control strategies that minimize battery degradation over the vehicle's life.
Automotive OEMs are increasingly unbundling the procurement of the thermal management system from the complete battery pack assembly. This sourcing strategy bypasses traditional Tier-1 integrators, allowing carmakers to work directly with thermal component specialists to gain greater control over system performance, design, and cost. This direct-sourcing model is most advanced in China, where domestic automakers seek to secure competitive advantages in the core technologies of their electric vehicles.
Automotive Battery Thermal Management System Market Segmentation
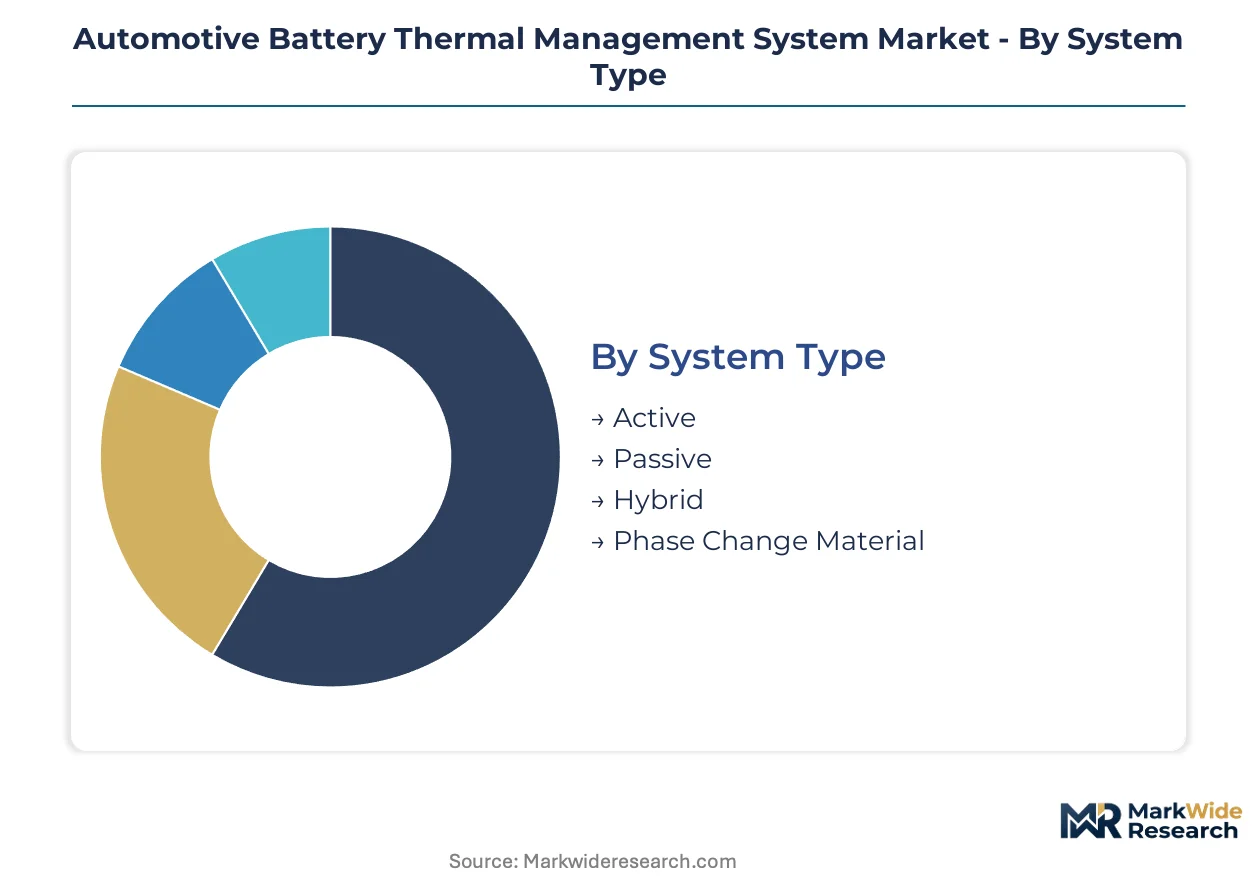
The Automotive Battery Thermal Management System Market is highly fragmented, with distinct segments addressing varied performance, cost, and safety needs across the rapidly expanding electric vehicle ecosystem. Understanding these segments is critical for component suppliers and vehicle manufacturers to align product development with specific market demands and regulatory pressures.
System Type:
After-sales service intensity varies significantly across system types, influencing long-term ownership costs and maintenance requirements for battery thermal management solutions.
- Active:These systems utilize pumps, fans, and refrigerants for dynamic temperature control, actively heating or cooling the battery pack as needed. High-performance electric vehicles and applications requiring rapid charging capabilities drive demand for robust active cooling solutions during peak thermal loads.
- Hybrid:Combining active and passive elements, hybrid systems offer a balanced approach to efficiency and cost management. Mass-market electric vehicles frequently integrate hybrid thermal management systems, balancing precise temperature regulation with overall energy consumption.
- Passive:Relies on natural convection and conduction, often using heat sinks or phase change materials for simpler, lower-cost solutions in less demanding applications.
- Phase Change Material:Employs specialized materials that absorb and release latent heat during phase transitions, providing localized temperature stabilization within the battery pack.
By volume, Active systems lead. By growth pace, Hybrid systems are ahead.
Technology:
Cost tiers for thermal management technologies vary widely, impacting adoption rates across different vehicle segments and performance requirements.
- Liquid Cooling:This technology circulates a coolant, typically a water-glycol mixture or dielectric fluid, through cold plates or internal channels within the battery pack. High-energy-density batteries in premium electric vehicles depend on liquid cooling for optimal performance, extended lifespan, and critical safety during operation.
- Refrigerant Cooling:Utilizes the vehicle's existing air conditioning refrigerant circuit to provide direct or indirect cooling to the battery cells. This technology is increasingly integrated into advanced electric vehicle architectures to optimize thermal performance, particularly during high-power charging events.
- Air Cooling:Employs ambient or cabin air to dissipate heat from the battery pack, suitable for smaller battery capacities or less demanding thermal management scenarios.
- Heat Pipe Cooling:Leverages heat pipes to efficiently transfer thermal energy from hot spots within the battery pack to a dedicated heat sink, offering localized temperature control.
- Thermoelectric Cooling:Utilizes the Peltier effect for precise temperature control, often employed in niche applications where exact temperature regulation is paramount, despite higher energy consumption.
Technologies with higher efficiency often command better margin profiles for suppliers.
Application:
Application segments reflect distinct volume requirements and operational demands for battery thermal management systems across various vehicle types.
- Electric Vehicles:This segment comprises passenger battery electric vehicles, which require sophisticated thermal management for maximizing driving range, enabling fast charging, and ensuring battery longevity. China and Europe drive significant demand for EV thermal solutions due to stringent emissions regulations and high consumer adoption rates.
- Commercial Transport:Includes electric buses, trucks, and vans, characterized by large battery packs and demanding duty cycles that generate substantial heat. Specialized high-capacity thermal management solutions are essential for heavy-duty commercial vehicles to ensure reliability and operational efficiency.
- Hybrid Vehicles:Integrate thermal management for smaller battery packs, balancing heat dissipation from the electric components with the thermal demands of the internal combustion engine.
- Two-Wheelers:Electric motorcycles and scooters require compact, lightweight thermal solutions due to inherent space constraints and competitive cost structures.
- Off-Road Vehicles:Electric construction, mining, and agricultural equipment need rugged, high-durability thermal systems designed to withstand extreme operating conditions and environmental factors.
Electrification initiatives are primary growth drivers across all these application sectors.
End User:
End-user segments represent distinct customer types with varied procurement strategies and service requirements for thermal management systems.
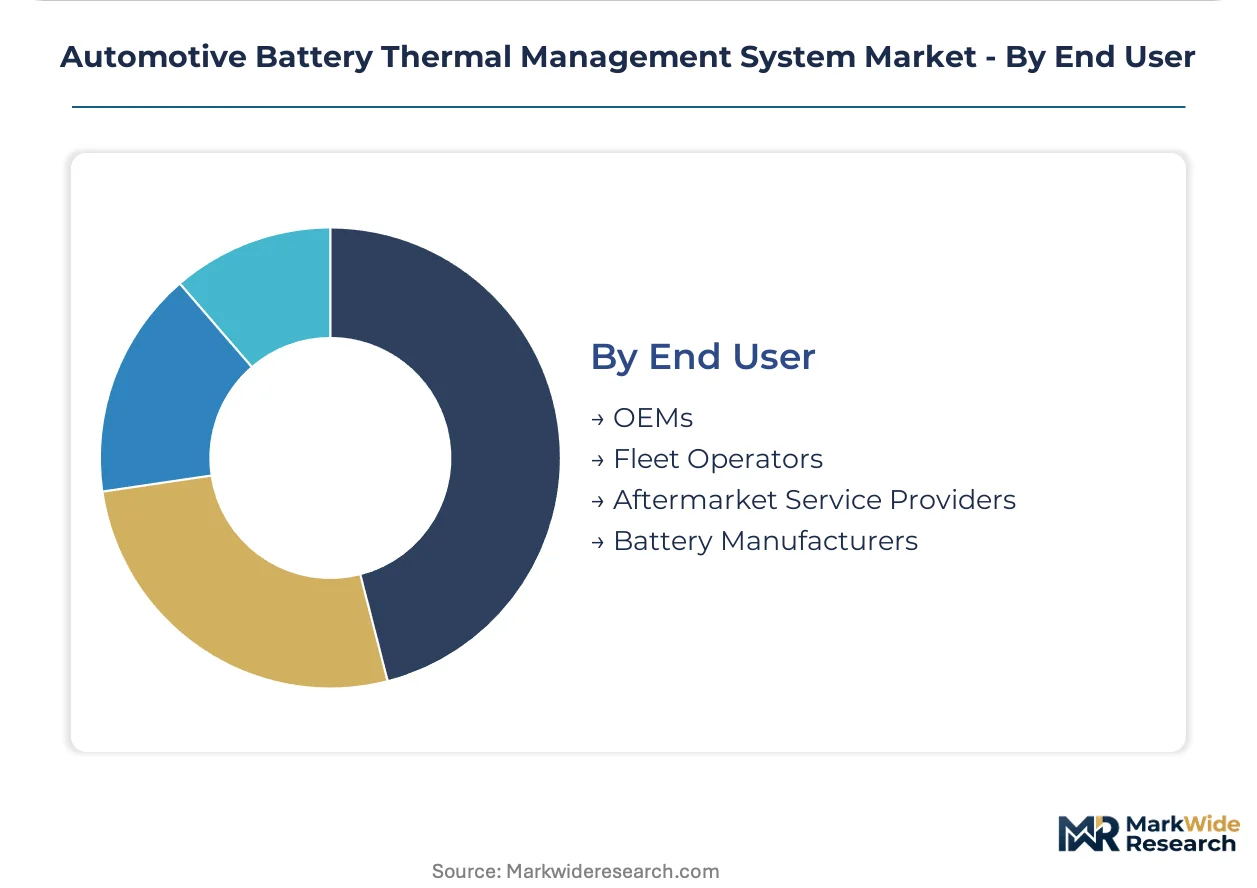
- OEMs:Automotive original equipment manufacturers integrate battery thermal management systems directly into their vehicle designs during the production phase. Direct sourcing from specialized component manufacturers is increasingly common among OEMs to gain greater control over system performance and cost.
- Fleet Operators:Manage large numbers of commercial vehicles, prioritizing system reliability, minimized maintenance costs, and maximum operational uptime. The electrification of delivery and logistics fleets creates specific demands for robust, long-lasting thermal management solutions.
- Aftermarket Service Providers:Offer repair, maintenance, and replacement services for thermal management components as the global electric vehicle fleet ages.
- Battery Manufacturers:Integrate thermal management solutions directly into their battery packs, often collaborating closely with OEMs on system design and validation.
OEMs exert significant influence over the thermal management system value chain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power for automotive battery thermal management systems exhibits asymmetry, with China's massive domestic market driving cost-optimized solutions while Germany and the United States command higher value for performance-oriented systems. This divergence reflects varying market maturity and regulatory landscapes across major automotive manufacturing hubs. Carmakers increasingly seek local sourcing to mitigate supply chain risks and meet regional content requirements.
China
China's robust electric vehicle adoption and extensive battery manufacturing base drive significant demand for advanced thermal management solutions. The GB 38031 standard mandates stringent thermal runaway prevention, directly influencing system design and component specifications. Major EV manufacturing clusters in Beijing, Shanghai, and Shenzhen lead innovation in integrated thermal modules for domestic and export markets.
Germany
Germany's premium automotive sector prioritizes high-performance and efficiency in battery thermal management systems for its rapidly expanding EV fleet. EU battery regulations under the Green Deal compel automakers to adopt solutions that extend battery lifespan and ensure safety. Automotive R&D centers in Stuttgart and Munich focus on developing sophisticated liquid cooling and heat pump systems.
United States
The United States market is experiencing substantial growth in electric vehicle sales, fueled by consumer incentives and infrastructure investments. NHTSA oversight on vehicle safety standards necessitates effective thermal management to prevent battery thermal events. Detroit and California serve as key automotive innovation hubs, developing advanced thermal solutions for both passenger and commercial EVs.
Japan
Japan's automotive industry emphasizes precision engineering and durability in battery thermal management systems, particularly for hybrid and high-performance electric vehicles. METI initiatives support the development of advanced battery technologies, requiring sophisticated thermal control. Manufacturing centers in Nagoya and Tokyo are pivotal for developing next-generation thermal components and system integration.
South Korea
South Korea's strong battery manufacturing sector and growing domestic EV market create demand for efficient and compact thermal management systems. The country's regulatory framework encourages the adoption of high-safety and high-performance battery solutions. Major automotive and battery production facilities in Ulsan and Seoul drive the integration of advanced cooling technologies.
Automotive Battery Thermal Management System Market Key Industry Players
Specialized component manufacturers and diversified automotive suppliers split the market for automotive battery thermal management systems. The market structure is highly dynamic, characterized by rapid technological advancements and evolving OEM sourcing strategies. Many players engage in strategic partnerships to integrate thermal solutions with broader vehicle architectures, while others focus on portfolio diversification to capture new market segments.
Within the integrated thermal module segment, companies like MAHLE leverage their engine component expertise to offer comprehensive thermal management units for electric vehicles. Hanon Systems, a South Korea-based specialist, competes on system-level efficiency and climate control integration, providing advanced thermal solutions. Continental, a German automotive technology company, extends its broad electronics and powertrain portfolio to incorporate sophisticated battery management systems with thermal control functions, serving a wide range of OEM clients.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental |
| DENSO Corporation |
| Valeo |
| Hanon Systems |
| MAHLE |
| Dana |
| GENTHERM |
| LG Energy Solution |
| Others |
Cost & Logistics Intelligence
Trans-Pacific freight costs, influenced by global trade dynamics, impact the cost structure of automotive battery thermal management systems, affecting supply concentration and downstream price differentiation across regions.
Pricing Analysis
Configured-to-order pricing for high-performance thermal management modules commands a premium over standardized solutions for mass-market vehicles. Price differentiation stems from the level of customization required for specific battery pack designs and the integration complexity with the vehicle's electronic control unit. Pricing softness for entry-level systems reflects intense competition and OEM demands for cost reduction. Mass-market electric vehicle manufacturers exhibit the highest price sensitivity, while premium segment brands prioritize performance over cost.
Supply Chain Analysis
Extended payment terms offered by suppliers provide crucial financing flexibility within the automotive battery thermal management supply chain. Geographic supply concentration for specialized components like high-precision sensors and advanced aluminum for cold plates centers significantly in China and South Korea. The supply chain relies on critical inputs such as specialized coolants and advanced polymers. Single-source vulnerability for these highly engineered components poses a structural risk. Downstream distribution runs through direct sourcing by automotive OEMs from specialized component manufacturers, bypassing traditional Tier-1 integrators for core thermal solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive moat story, largely justified by regulatory entrenchment that mandates sophisticated thermal management solutions for electric vehicle safety and performance.
For Market Incumbents: Pre-empt margin erosion by investing heavily in integrated thermal modules that combine battery cooling with cabin climate control, offering superior system efficiency. Secure long-term supply agreements for critical raw materials to mitigate commodity price volatility. This strategy helps counter the threat from cost-optimized solutions emerging from new entrants in Asia. Prioritize R&D in advanced liquid cooling and heat pump systems to maintain a technological lead.
For New Entrants and Emerging Players: Establish a beachhead in the commercial vehicle electrification segment, which requires specialized, high-capacity thermal management solutions for demanding duty cycles. Focus on developing cost-effective, modular solutions for specific battery cell formats where standardization is emerging. A go-to-market angle emphasizing rapid customization and robust durability for heavy-duty applications can differentiate offerings effectively.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive suppliers seeking to streamline their portfolios, offering focused expertise in thermal management. The long-term viability of this market over a 5-10 year window remains strong due to sustained electric vehicle penetration. Acquisition targets should include specialized component manufacturers with proprietary materials science or advanced software for thermal control. The signal to watch is the broader adoption of integrated heat pump systems across mid-market EV platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization Investment | OEMs reduce costs and complexity across diverse electric vehicle architectures. |
| Advanced Cooling Material R&D | Essential for managing heat from high-energy-density battery chemistries. |
| Integrated Thermal Module Expansion | Suppliers deliver higher value and improved vehicle efficiency with comprehensive systems. |
| Commercial EV Solutions Development | Addresses the demanding duty cycles and large battery packs of electric buses. |
| Aftermarket Service Network Expansion | Captures new revenue streams from the maintenance and repair of aging EV fleets. |
Research Approach
Initial hypotheses were tested against primary input from OEM thermal engineers, Tier-1 component procurement managers, battery cell developers, and EV fleet operators, then refined through iterative analysis. This approach combined in-depth primary interviews with comprehensive secondary validation, triangulating findings from both bottom-up market sizing and top-down industry analysis.
The analytical framework balanced demand-supply dynamics across the modeling period, segmenting the market by system type, technology, application, end user, and regional market dynamics. Compound annual growth rates were derived through regression analysis and market share projections, incorporating industry-specific forecast inputs such as EV production forecasts and battery energy density trends.
Sensitivities concentrate around raw material price volatility, shifts in EV policy, and unexpected technological breakthroughs in cooling. Forecasts reflect assumptions documented through extensive primary and secondary research. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
E-Bike Battery Pack Market
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Solar Vehicle Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Wireless Electric Vehicle Charging Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market