
 Bus Pantograph Charger Market | 2026-2036
Bus Pantograph Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Bus Pantograph Charger Market Outlook
EU F-Gas Regulation is consolidating compliance costs for refrigerant-dependent thermal management systems in pantograph charger cabinets. Schunk Transit Systems GmbH leverages its Stuttgart engineering base to sustain dominance in precision contact-head manufacturing. Siemens AG anchors European market presence through integrated rail-to-road electrification portfolios. Kempower competes with modular power-stack architectures that reduce installation footprint for Nordic depot operators.
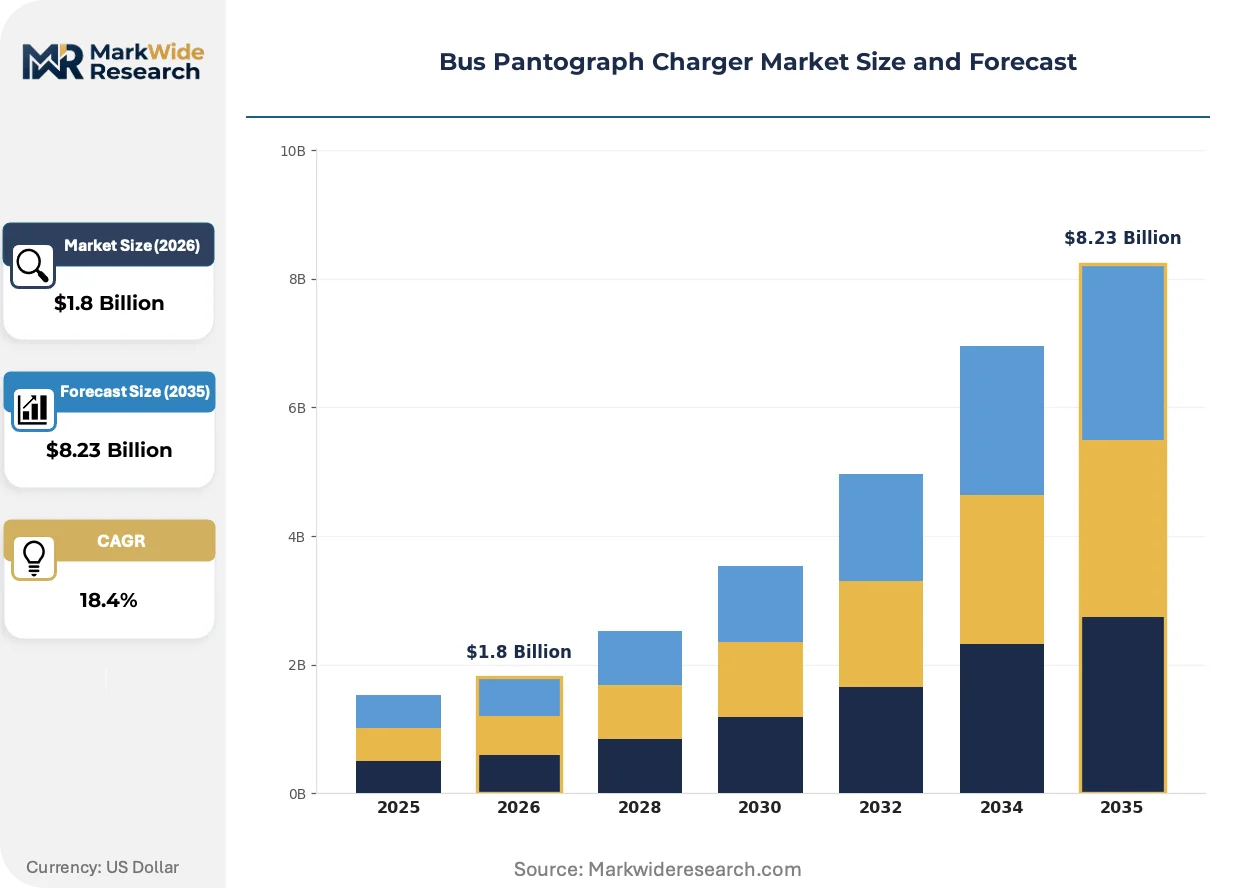
Bus pantograph chargers deploy telescoping current collectors that mate with overhead conductive rails, delivering DC power at 150 kW to 600 kW for opportunity charging during scheduled route stops. DC charging technology leads installed base volumes while smart charging systems represent the fastest-expanding segment as grid-integration software becomes standard in new tenders. Public transport agencies occupy the largest end-user share, though fleet management companies are gaining procurement influence through mobility-as-a-service contracts that consolidate charging responsibility across operator networks.
EMA device standards, EU Green Deal emission benchmarks, and national F-Gas compliance frameworks collectively shape product certification requirements and market access across European deployments. China's GB standards and MIIT charging protocols govern interoperability for pantograph systems in the world's largest electric bus fleet. Stakeholders must monitor evolving grid-connection codes and carbon-border adjustment mechanisms as these will determine which charger architectures qualify for public procurement funding.
Market Dynamics
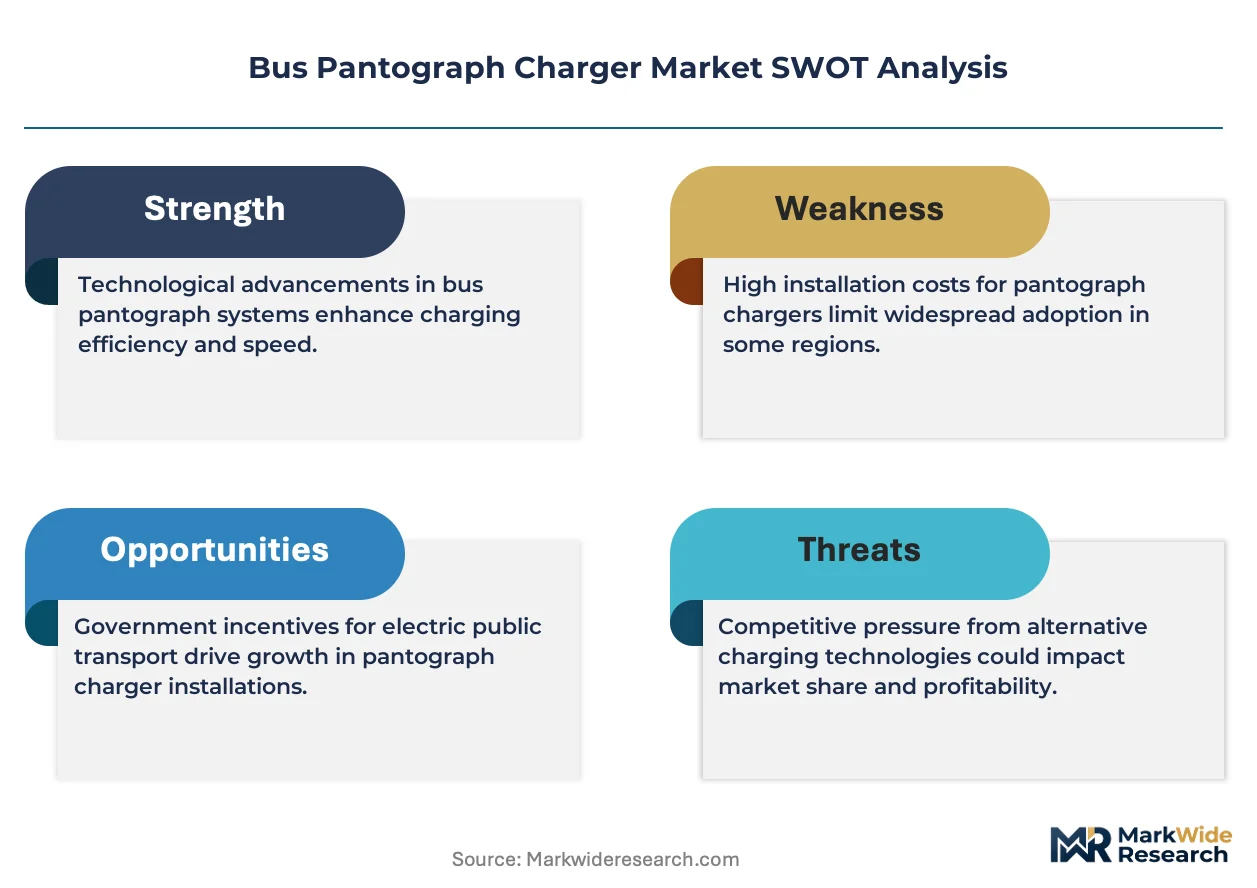
The EU Green Deal mandate for municipal fleet decarbonization is forcing transit agencies to replace overnight depot charging with opportunity charging infrastructure that minimizes bus downtime and grid peak loads.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down rules are accelerating replacement of thermal management systems in charger cabinets, creating refresh demand across German and Nordic bus fleets.
- China's MIIT protocols:Standardized pantograph-to-bus communication interfaces are reducing interoperability barriers for DC fast-charging deployments in megacity transit networks.
- Mobility-as-a-service consolidation:Fleet management companies are aggregating charging responsibility across operator networks, concentrating procurement volumes for high-power pantograph systems.
Market Restraints
- Copper and rare-earth magnet costs:Contact-head assemblies and power electronics depend on volatile commodity inputs that compress manufacturer margins during supply shocks.
- Stuttgart-centered supplier concentration:Precision-engineered contact-head manufacturing clusters in southwestern Germany, creating single-point vulnerability for European deployments.
- Grid-connection code fragmentation:National utility interconnection standards vary across EU member states, delaying site commissioning and inflating engineering costs.
Strategic Opportunities
- India's PLI scheme for electric buses:Production-linked incentives for domestic e-bus manufacturing are opening first-mover positioning for pantograph charger suppliers in depot infrastructure.
- Smart charging convergence:Bidirectional power electronics and vehicle-to-grid software are creating new revenue streams from grid services contracts.
- Carbon-border adjustment mechanisms:EU CBAM compliance requirements favor locally manufactured charger components over imported alternatives in public tenders.
Industry Challenges
- High-voltage technician scarcity:Installation and maintenance of 600 kW DC systems requires certified specialists that transit agencies struggle to recruit and retain.
- Legacy depot electrical infrastructure:Aging substations in municipal bus yards require costly upgrades before pantograph systems can achieve rated power delivery.
- EMA device certification timelines:Medical-adjacent electromagnetic compatibility testing creates 8-14 month approval delays for charger control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus Pantograph Charger Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Overhead Charger, Compact Charger, Fast Charger, Standard Charger End User: Public Transport Agencies, Private Bus Operators, Fleet Management Companies, Logistics Providers Technology: DC Charging, AC Charging, Wireless Charging, Smart Charging Installation Type: On-Vehicle, Stationary Charging Stations, Portable Chargers, Integrated Systems |
| Companies Covered | Schunk Transit Systems GmbH, Vector Informatik GmbH, ABB Ltd., Valmont Industries, Inc., SETEC Power, Siemens AG, BYD Company Limited, Kempower, Wabtec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus Pantograph Charger Market Strategic Shifts
Hardware-software integration is redefining competitive advantage as charging infrastructure becomes a grid node rather than a passive load.
Silicon carbide power semiconductors are replacing insulated-gate bipolar transistors in DC conversion stages, enabling higher switching frequencies that shrink magnetic component size. Chinese transit authorities are specifying SiC-based architectures in new tenders for 600 kW systems. This technology is converging with dynamic load management software to create charging networks that modulate power delivery based on real-time grid frequency signals.
The EU F-Gas Regulation's stepped refrigerant phase-down is eliminating hydrofluorocarbon-dependent cooling from pantograph charger cabinets by 2030. Manufacturers are redesigning thermal management around CO2 heat pumps and liquid cooling loops. Nordic depot operators are demanding F-Gas-compliant systems ahead of mandate deadlines to secure Green Deal funding eligibility.
Public transport agencies are unbundling charging infrastructure ownership from bus operations through energy-as-a-service contracts. Fleet management companies assume capex burden and monetize grid flexibility services. This model is displacing traditional municipal procurement in Germany and the Netherlands where transit authorities lack balance-sheet capacity for infrastructure investment.
Bus Pantograph Charger Market Segmentation
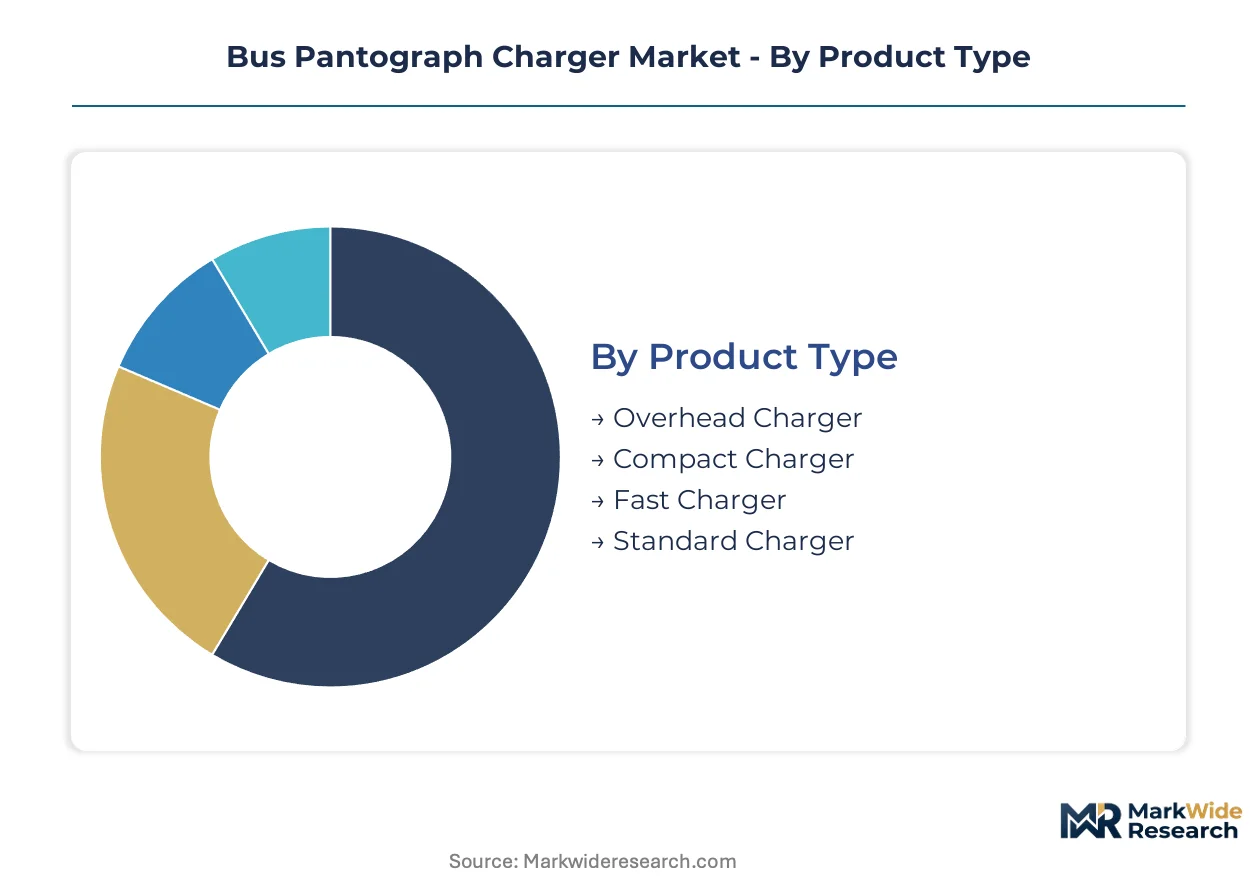
Pantograph charger procurement splits across four structural dimensions that determine certification pathways, installation complexity, and operational economics. Transit agencies weight technology maturity against grid-integration requirements when matching segment combinations to route profiles.
Product Type:
EMA device standards and EU F-Gas Regulation apply differentially across product configurations, with overhead systems facing the most stringent electromagnetic compatibility testing and refrigerant-phase compliance deadlines.
- Overhead Charger:Telescoping current collectors mate with conductive rails suspended above bus stops, delivering 150 kW to 600 kW during scheduled dwell times. German and Nordic municipal fleets under EU Green Deal mandates are consolidating procurement around these systems to minimize route downtime and depot land requirements.
- Fast Charger:High-power DC conversion enables 3-6 minute opportunity charging at terminus points, though installation demands certified high-voltage technicians that transit agencies struggle to recruit. China's megacity networks specify these architectures under MIIT protocols for interoperability across operator fleets.
- Compact Charger:Reduced-footprint cabinets suit constrained depot sites in dense European urban cores.
- Standard Charger:Lower-power overnight systems serve secondary routes with extended layover windows.
Overhead Charger sits at the top of the volume ranking, with Fast Charger climbing the fastest.
End User:
Customer-type concentration shapes pricing architecture and contract structure, with public procurement favoring capex-heavy ownership models while private operators gravitate toward service-based arrangements.
- Public Transport Agencies:Municipal authorities across Germany and the Netherlands retain infrastructure ownership under traditional procurement, though balance-sheet constraints are accelerating energy-as-a-service adoption. These entities face EU Green Deal emission benchmarks that mandate fleet electrification timelines.
- Fleet Management Companies:Mobility-as-a-service aggregators assume charging responsibility across operator networks, consolidating procurement volumes and monetizing grid flexibility services through bidirectional power contracts. This segment is gaining influence fastest as transit authorities unbundle infrastructure from operations.
- Private Bus Operators:Commercial route concessionaires prioritize equipment with rapid commissioning to minimize service disruption.
- Logistics Providers:Depot-based freight electrification creates adjacent demand for pantograph systems adapted to commercial vehicle duty cycles.
Public Transport Agencies command the dominant procurement share, with Fleet Management Companies expanding most quickly through consolidation mechanics.
Technology:
Power electronics architecture determines semiconductor content, thermal management requirements, and software integration depth, with silicon carbide adoption creating performance tiers that separate grid-interactive systems from passive loads.
- DC Charging:Direct current conversion at 150 kW to 600 kW dominates installed base volumes, with silicon carbide semiconductors replacing insulated-gate bipolar transistors to enable higher switching frequencies and reduced magnetic component size. Chinese tenders under GB standards increasingly specify SiC-based architectures for megacity deployments.
- Smart Charging:Bidirectional power electronics and vehicle-to-grid software modulate delivery based on real-time frequency signals, creating revenue streams from ancillary services contracts. Nordic depot operators demand these capabilities ahead of mandate deadlines to secure Green Deal funding eligibility.
- AC Charging:Alternating current systems persist in legacy depot installations with lower power requirements.
- Wireless Charging:Inductive power transfer remains pre-commercial for pantograph applications due to alignment precision demands.
DC Charging leads absolute deployment volumes, with Smart Charging exhibiting the steepest expansion trajectory as grid codes evolve.
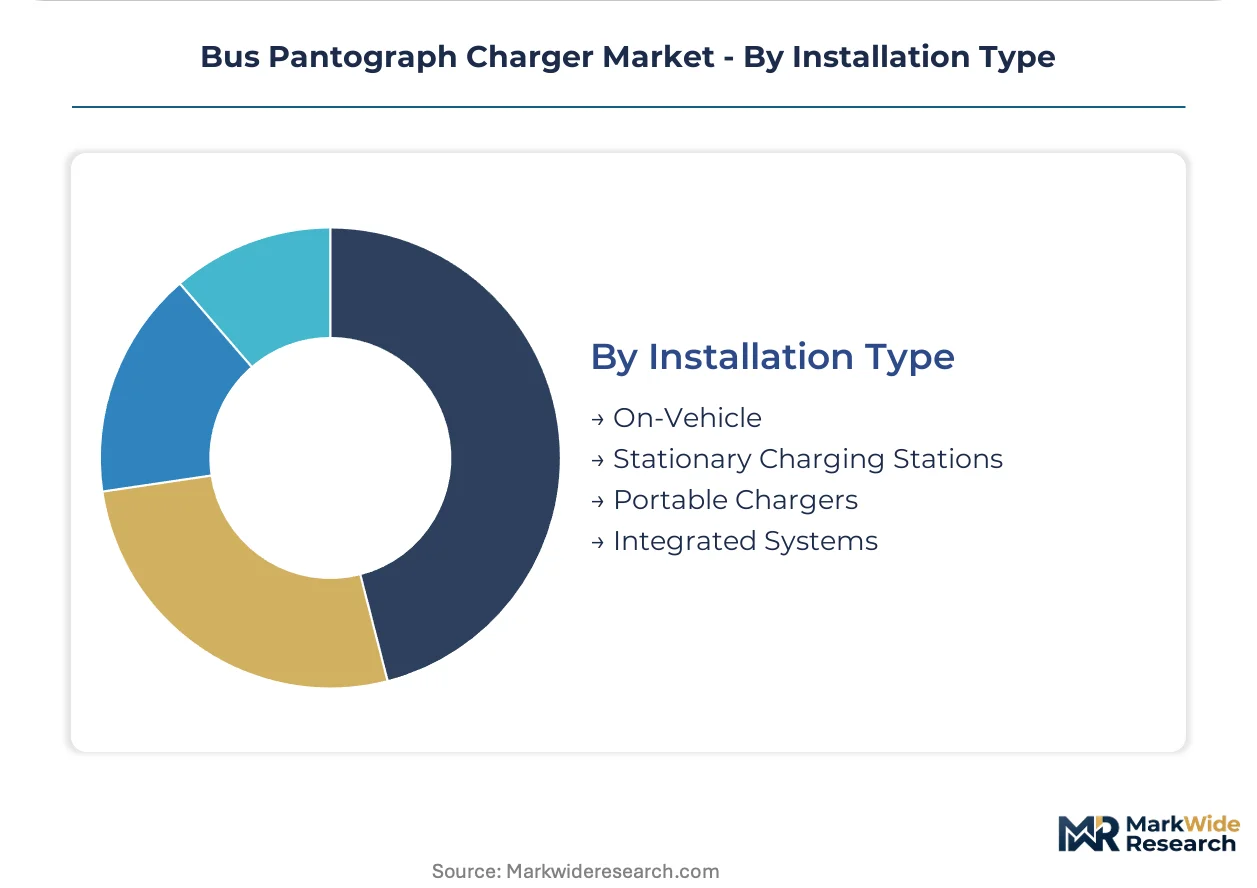
Installation Type:
Physical configuration dictates site preparation intensity, electrical infrastructure upgrade scope, and maintenance access protocols, with stationary systems requiring substation reinforcement that aging municipal bus yards often lack.
- Stationary Charging Stations:Fixed overhead conductive rails and ground-level cabinets require grid-connection approvals that vary across EU member states, inflating engineering costs and commissioning timelines. These installations concentrate in Germany's Stuttgart-centered manufacturing cluster and China's megacity transit networks.
- Integrated Systems:Combined pantograph and battery storage architectures reduce peak demand charges and enable resilience against grid instability. India's PLI scheme for electric buses is opening first-mover positioning for these configurations in domestic depot infrastructure.
- On-Vehicle:Mobile collector units mounted to bus roofs enable interoperability across multiple charging points.
- Portable Chargers:Temporary deployment options serve emergency fleet support and special event routing.
Stationary Charging Stations anchor current procurement volumes, with Integrated Systems gaining share fastest through storage convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bus pantograph charging infrastructure originated in German engineering clusters during the early 2010s electrification wave, then diffused through Nordic municipal networks and Chinese megacity transit authorities. Deployment patterns now track divergent regulatory timelines and grid interconnection standards across three continents.
Germany
Stuttgart and Mannheim host concentrated precision contact-head manufacturing operations serving municipal fleets across Baden-Württemberg. The EU F-Gas Regulation's refrigerant phase-down is accelerating thermal management system replacements in charger cabinets deployed under federal transit electrification programs. Schunk Transit Systems GmbH anchors southwestern Germany's supplier ecosystem through specialized engineering capabilities.
China
Beijing, Shanghai, and Shenzhen transit authorities specify 600 kW DC fast-charging pantograph systems under MIIT protocols for interoperability across operator fleets. GB standards govern pantograph-to-bus communication interfaces, reducing commissioning delays in megacity networks. BYD Company Limited exemplifies domestic vertical integration from bus manufacturing through charging infrastructure deployment.
Sweden
Stockholm and Gothenburg municipal agencies demand F-Gas-compliant charging systems ahead of EU mandate deadlines to secure Green Deal funding eligibility. Nordic depot operators prioritize smart charging capabilities with bidirectional power electronics for grid flexibility services. Kempower competes through modular power-stack architectures that minimize installation footprint in constrained urban sites.
United States
California transit agencies in Los Angeles and San Francisco Bay Area are piloting overhead conductive charging for depot-based fleet electrification under state zero-emission mandates. Federal IRA provisions support infrastructure investment, though utility interconnection standards vary across ISO territories. Valmont Industries, Inc. represents North American structural fabrication capabilities for overhead conductive rail systems.
India
Maharashtra and Karnataka state transport utilities are evaluating pantograph systems under the PLI scheme for domestic electric bus manufacturing. Delhi's cluster of depot infrastructure projects creates first-mover positioning opportunities for integrated battery storage configurations. BIS certification requirements and CEA grid codes shape product localization strategies for international suppliers entering the market.
Bus Pantograph Charger Market Competitive Environment
The competitive structure tilts toward precision engineering specialists with captive contact-head manufacturing capabilities. German and Chinese participants dominate high-power DC conversion architectures, while Nordic modular specialists compete on installation footprint reduction. Two strategic archetypes prevail: integrated rail-to-road electrification portfolios and focused component specialists. Consolidation mechanics concentrate through strategic partnerships for grid-software integration and geographic licensing arrangements for emerging markets.
Among German engineering specialists, Schunk Transit Systems GmbH and Vector Informatik GmbH exemplify Stuttgart-centered precision manufacturing archetypes. Siemens AG anchors integrated electrification portfolios spanning rail infrastructure through road transit applications. ABB Ltd. represents Swiss-Swedish industrial conglomerate positioning across power electronics and grid integration domains. These three participants illustrate divergent strategic postures: component depth versus systems integration versus diversified industrial scale.
| Leading Market Players |
|---|
| Schunk Transit Systems GmbH |
| Vector Informatik GmbH |
| ABB Ltd. |
| Valmont Industries, Inc. |
| SETEC Power |
| Siemens AG |
| BYD Company Limited |
| Kempower |
| Wabtec Corporation |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed transit electrification programs and municipal fleet operators anchor procurement volumes, creating pricing discipline that rewards certified suppliers with captive manufacturing capabilities while squeezing speculative entrants lacking established grid-interconnection track records.
Pricing Analysis
Project-based tender pricing with performance guarantees dominates municipal procurement, separating incumbent engineering specialists from modular system integrators through F-Gas compliance certification and silicon carbide semiconductor specifications. Price differentiation rests on contact-head precision grades and after-sales service bundling across 15-year asset lifecycles. Cost compression in standard DC conversion tiers is intensifying because Chinese state-owned transit authorities are consolidating procurement volumes under MIIT protocols. Fleet management companies exhibit highest price sensitivity as they model energy-as-a-service returns, while German municipal agencies prioritize total-cost-of-ownership over upfront capital outlays.
Supply Chain Analysis
Refurbishment flows for contact-head assemblies and power electronics modules are emerging as critical supply buffers against raw material volatility in copper and rare-earth magnet sourcing. Manufacturing concentrates in Germany, China, and South Korea, with precision machining clusters anchored around Stuttgart engineering bases. Component sourcing draws from Taiwanese semiconductor foundries for silicon carbide wafers and Chinese rare-earth processing facilities for magnetic assemblies. Single-source vulnerability concentrates in high-voltage ceramic insulator supply from Japanese specialty ceramics producers. Distribution runs through EPC contractors with utility interconnection expertise, extending commissioning timelines where national grid codes fragment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bus pantograph charging infrastructure has entered a late-cycle quality phase where EU Green Deal funding eligibility now requires F-Gas-compliant thermal management and bidirectional grid-interactive capabilities that premium-tier suppliers alone can certify.
For Market Incumbents: Deploy silicon carbide semiconductor roadmaps to defend margin position against Chinese state-backed competitors capturing standard DC conversion volumes through MIIT-mandated interoperability. Consolidate position by acquiring Nordic modular specialists with proven smart-charging software stacks, as fleet management companies consolidate procurement around integrated hardware-software offerings. EMA device certification bottlenecks threaten to delay product launches for challengers lacking established regulatory affairs capabilities. For New Entrants and Emerging Players: Digital-channel routes through energy-as-a-service platforms offer lowest-friction customer acquisition for depot operators unbundling infrastructure ownership from bus operations. India's PLI scheme for electric bus manufacturing presents the most penetrable geography, with Maharashtra and Karnataka state utilities evaluating first deployments ahead of national scale-up. Target integrated battery storage configurations where incumbent engineering specialists lack localized manufacturing presence. For Investors and Strategic Acquirers: Rail-to-road electrification conglomerates are the most active acquirers in this space, seeking contact-head manufacturing depth to complete integrated transit portfolios. Five-to-ten year viability hinges on carbon-border adjustment mechanism compliance positioning, favoring European manufacturing footprints over import-dependent assembly. Monitor EU F-Gas Regulation enforcement timelines as inflection indicator for thermal management system replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Semiconductor Transition | Chinese MIIT protocols now specify SiC architectures for 600 kW megacity deployments. |
| F-Gas Compliance Certification | Nordic depot operators demand CO2 heat pump systems ahead of EU mandate deadlines. |
| Energy-as-a-Service Platform Launch | German and Dutch transit authorities unbundle infrastructure ownership from operations. |
| Backward Integration into Contact-Head Manufacturing | Stuttgart-centered precision machining clusters create single-point supply vulnerability. |
| Smart Charging Software Acquisition | Bidirectional power electronics enable grid flexibility revenue streams for fleet operators. |
Study Parameters
Direct dialogue with transit agency procurement directors, high-voltage systems engineers, fleet management platform executives, and EPC contractors with utility interconnection expertise grounded qualitative demand assessment. Secondary validation drew from EU F-Gas Regulation implementation reports, MIIT protocol documentation, GB standards filings, and municipal tender databases across German, Nordic, and Chinese transit authorities. Bottom-up installation forecasts triangulated against top-down electrification spending commitments under EU Green Deal and China's dual carbon goals.
Segment-level volume and value trajectories across the analysis window reflect modeled deployment rates by product type, end-user concentration, power electronics architecture, and physical installation configuration. CAGRs derived from infrastructure investment schedules tied to fleet electrification mandates, with silicon carbide adoption curves and F-Gas replacement cycles as key forecast inputs.
Copper and rare-earth price volatility, EMA certification timeline extensions, and grid-connection code fragmentation across EU member states are the dominant revision risks to deployment assumptions. Practitioners should monitor refrigerant phase-down enforcement schedules and national utility interconnection standard harmonization progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
Silicone in Electric Vehicles Market
Electric Vehicles
Denmark Solar E-Bike Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Foldable Electric Car Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
North America Electric Truck Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
Used EV Market
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Singapore Electric Vehicle Market