
 Indonesia Infant Nutrition Market | 2026-2036
Indonesia Infant Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Infant Nutrition Market Insights
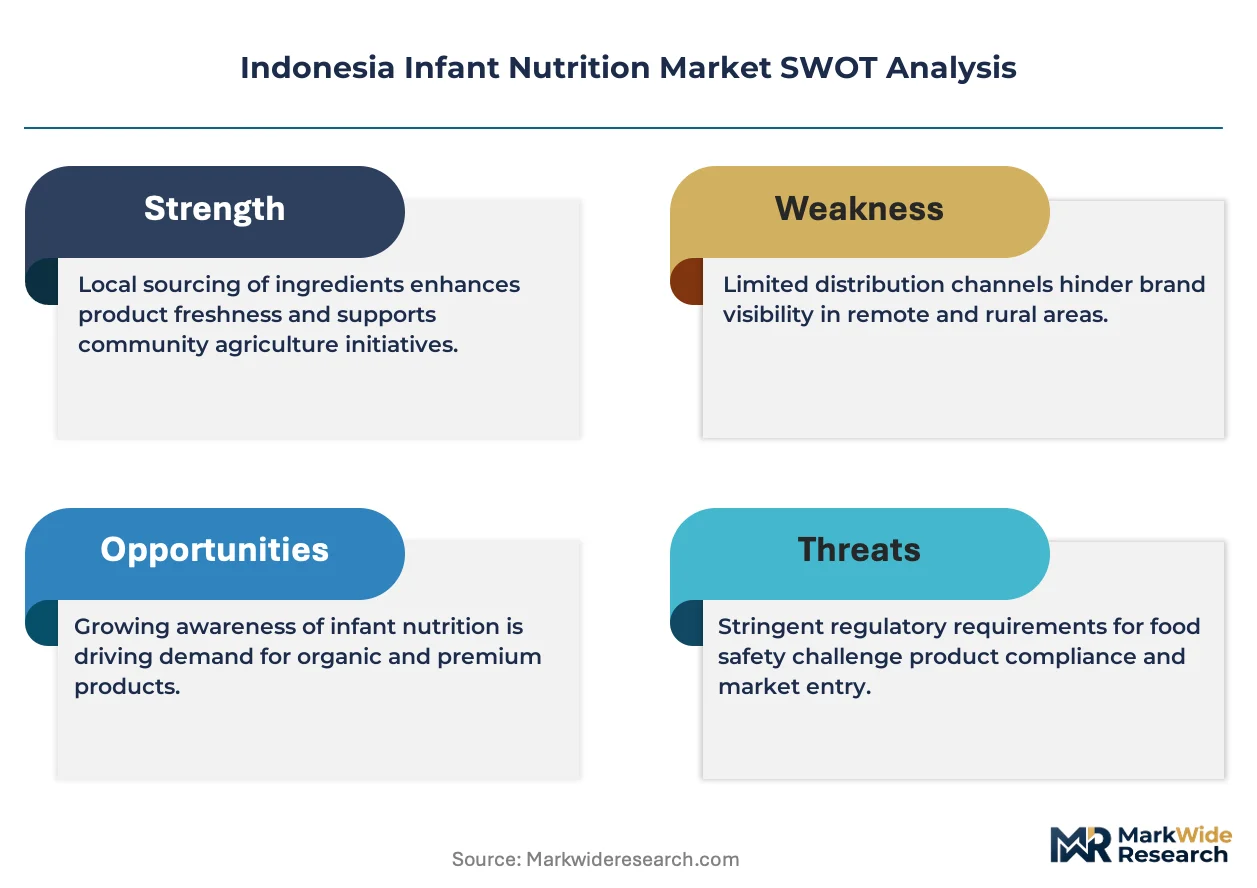
The Indonesia infant nutrition sector is pivoting along a widening gap between premium imported formulations and locally manufactured commodity lines. Nestle leverages its dairy sourcing networks to sustain cost advantages across mid-tier SKUs, while Danone differentiates through specialized metabolic and hypoallergenic ranges. Kalbe Farma anchors its position via pharmacy channel control and domestic manufacturing scale, competing directly with Mead Johnson Indonesia's clinician-focused educational programs.
Infant nutrition encompasses scientifically formulated products designed to deliver precise macronutrient ratios—typically protein at 1.8–2.2 g per 100 kcal, lipid fractions mirroring breast milk composition, and micronutrient fortification meeting Codex Alimentarius thresholds—for children from birth through 36 months. Formula dominates value generation due to higher per-unit pricing and repeat purchase frequency, while baby food and cereal segments expand through convenience-oriented urban consumption patterns. Online retail channels capture disproportionate growth velocity as pharmacy regulations restrict certain product promotions, concentrating margin pools in direct-to-parent digital platforms.
Indonesia's BPOM enforces strict halal certification and nutrient labeling requirements that elevate compliance costs for imported brands, while the Ministry of Health's national breastfeeding campaign restricts formula marketing to healthcare professionals. Sarihusada navigates these constraints through deep integration with Indonesia's Posyandu community health network, and Fonterra positions its ingredient supply business to capitalize on local production mandates. Stakeholders must monitor evolving halal traceability standards and provincial breastfeeding enforcement intensity to anticipate demand fluctuations.
Market Dynamics
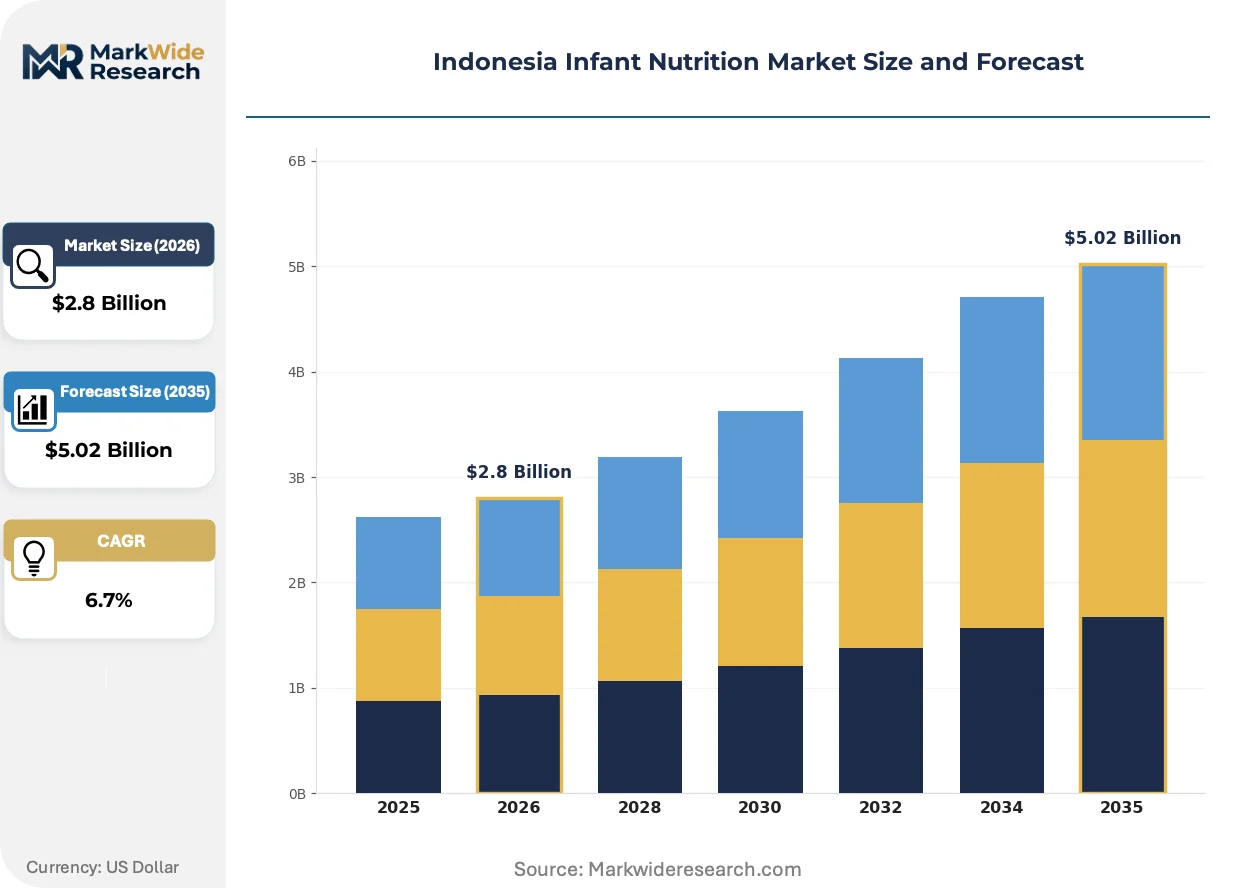
Indonesia's infant nutrition market is bifurcating between premium imported formulations and domestically manufactured commodity lines, driven by BPOM's halal certification mandates and the Ministry of Health's breastfeeding promotion policies that constrain formula marketing channels.
Growth Catalysts
- Urban Middle-Class Expansion:Jakarta and Surabaya metropolitan corridors concentrate demand for fortified formula products as modern trade penetration deepens and disposable incomes rise among young parents.
- BPOM Mandatory Fortification:Indonesia's national food and drug regulator enforces nutrient labeling requirements that elevate product quality standards and create compliance barriers for informal competitors.
- Posyandu Network Integration:Community health post distribution channels extend rural reach while embedding nutrition products within government maternal-child health programs.
Market Restraints
- Dairy Input Volatility:Global milk powder prices fluctuate with New Zealand and Australian supply conditions, compressing margins for locally blended formulations dependent on imported ingredients.
- Marketing Restrictions:Ministry of Health breastfeeding campaigns prohibit direct-to-consumer formula advertising, forcing brands to rely on clinician education with limited reach velocity.
- Import Dependency:Specialized lipid fractions and micronutrient premixes concentrate sourcing in European and North American suppliers, exposing distributors to currency and logistics risk.
Strategic Opportunities
- Eastern Indonesia Penetration:Sulawesi, Maluku, and Papua provinces remain underserved by modern retail, creating first-mover advantage for brands establishing cold-chain distribution.
- Digital Direct-to-Parent Platforms:Pharmacy promotion restrictions are concentrating margin pools in e-commerce channels that bypass traditional wholesale intermediaries.
- Halal Traceability Premiumization:BPOM's evolving certification standards enable domestic manufacturers to command price premiums through verifiable supply chain documentation.
Industry Challenges
- Pediatric Nutrition Specialist Shortage:Qualified formulation scientists and clinical affairs managers remain scarce in Indonesian labor markets, slowing product development cycles.
- Dual Certification Timelines:Simultaneous BPOM registration and MUI halal approval processes extend time-to-market by 18-24 months for new SKUs.
- Legacy Distributor Integration:Modern brands face friction consolidating fragmented traditional trade networks into centralized inventory and data systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Infant Nutrition Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Formula, Baby Food, Cereal, Snacks Distribution Channel: Supermarkets, Pharmacies, Online Retail, Convenience Stores Customer Type: Parents, Healthcare Professionals, Childcare Centers, Retailers Packaging Type: Flexible Pouches, Jars, Tetra Packs, Cans |
| Companies Covered | Nestle, Abbott, Danone, Kalbe Farma, Nutricia, Frisian Flag, Mead Johnson Indonesia, Sarihusada, Fonterra, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Infant Nutrition Market Trends and Innovations
Formulation science and distribution architecture are converging to reshape how infant nutrition reaches Indonesian households, with regulatory compliance and channel innovation becoming primary competitive differentiators rather than secondary operational concerns.
Precision fermentation for dairy protein analogs is decentralizing ingredient sourcing away from traditional agricultural supply chains. Domestic biotechnology startups in Bandung and Yogyakarta are piloting microbial-derived lactoferrin and alpha-lactalbumin production. This technology is decentralizing cost structures for mid-tier brands previously locked into volatile global commodity markets.
BPOM's 2023 implementation of electronic traceability systems for imported ingredients is tightening supply chain documentation requirements. Manufacturers must now submit batch-level halal certificates and nutrient assay reports through centralized digital portals. Specialized metabolic formulas containing hydrolyzed proteins face the steepest compliance burden, with several European brands withdrawing SKUs rather than adapting labeling.
Subscription-based replenishment models are displacing traditional pharmacy stock-up behavior among Jakarta's dual-income households. Parents in satellite cities like Tangerang and Bekasi increasingly auto-schedule monthly formula deliveries through integrated pediatric clinic partnerships. This shift concentrates lifetime value capture in platforms that embed growth-tracking apps and nutritional consultation services.
Indonesia Infant Nutrition Market Segmentation
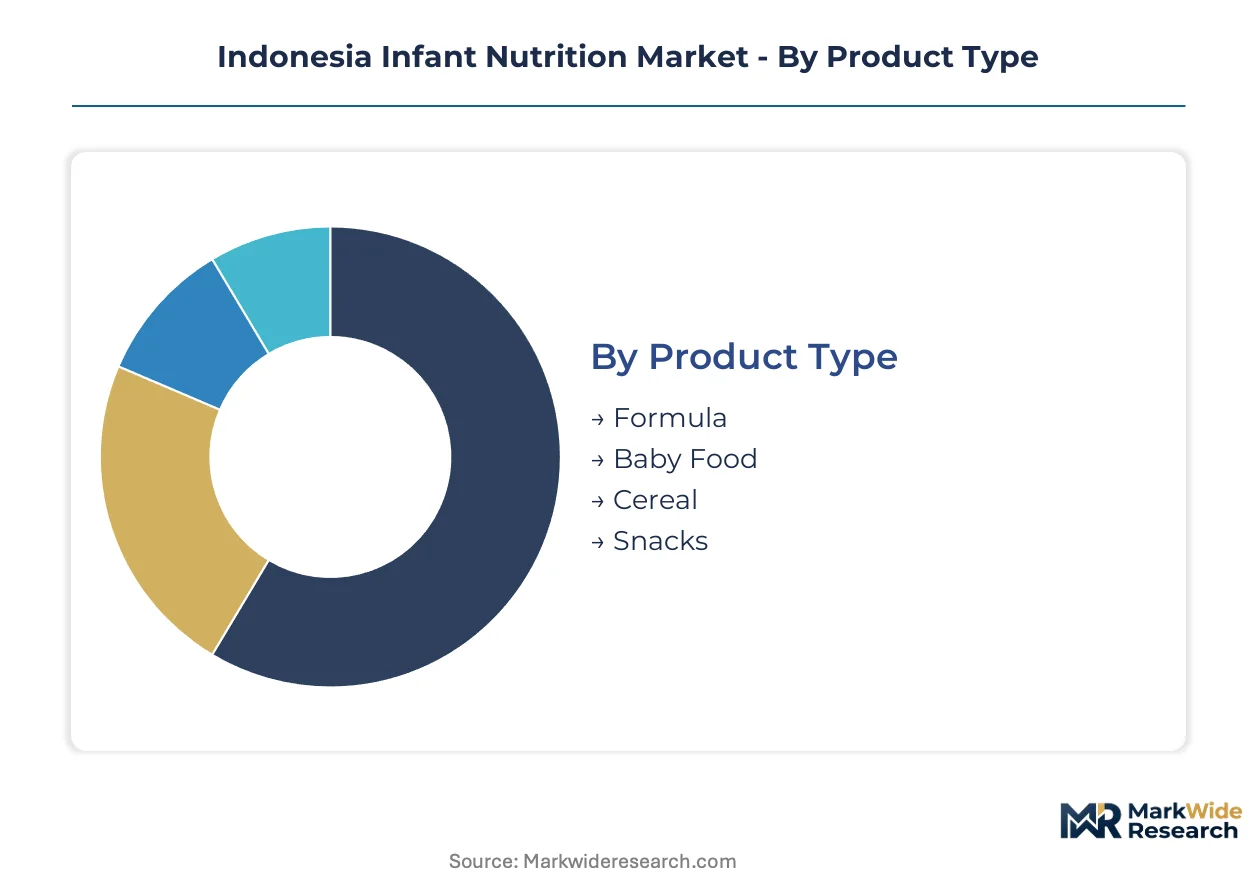
Segmentation in Indonesia's infant nutrition sector reveals how regulatory constraints and channel restrictions fragment demand across distinct purchasing contexts. Each dimension exposes different margin structures, compliance burdens, and customer relationship requirements that shape competitive positioning.
Product Type:
Standalone formulations command the highest per-unit economics, while complementary feeding systems embed into broader nutrition regimens through pediatric guidance.
- Formula:Scientifically formulated powder or liquid delivering precise macronutrient ratios—protein at 1.8–2.2 g per 100 kcal, lipid fractions mirroring breast milk composition, and micronutrient fortification meeting Codex Alimentarius thresholds. Demand concentrates in Jakarta and Surabaya metropolitan corridors where modern trade penetration and pediatric clinic density run highest, driven by dual-income households seeking convenience and clinical credibility.
- Baby Food:Pureed or textured preparations transitioning infants from exclusive milk feeding to solid food introduction, typically fruit and vegetable based with controlled sodium and sugar content. Java-based urban parents favor these for portability and portion control, though BPOM's halal certification requirements elevate compliance costs for imported variants.
- Cereal:Iron-fortified grain-based preparations designed for complementary feeding from six months, often blended with milk powder or fruit purees. Sarihusada leverages Posyandu network integration to extend rural reach for this segment.
- Snacks:Finger foods and teething biscuits targeting developmental motor skills, typically lower in nutritional density than core feeding products. These ride convenience-oriented urban consumption patterns in satellite cities like Tangerang and Bekasi.
Volume placements concentrate in Formula; the faster expansion belongs to Baby Food as complementary feeding windows lengthen.
Distribution Channel:
Channel selection determines margin capture velocity, with pharmacy restrictions forcing brands to rebuild customer relationships through alternative touchpoints.
- Supermarkets:Modern trade formats with centralized inventory management and promotional visibility, dominant in Jakarta and Surabaya corridors where shelf space competition intensifies. These channels face margin pressure from private label expansion and direct-to-consumer platform encroachment.
- Pharmacies:Licensed drugstores with clinician-adjacent credibility, historically the primary formula purchase point until Ministry of Health marketing restrictions limited promotional activity. Kalbe Farma anchors position here through deep pharmacy network control.
- Online Retail:E-commerce platforms and direct-to-parent digital channels capturing disproportionate growth velocity as pharmacy regulations restrict certain product promotions. Subscription-based replenishment models concentrate lifetime value in platforms embedding growth-tracking apps.
- Convenience Stores:Small-format neighborhood retailers with limited SKU depth, serving emergency or top-up purchases rather than planned nutrition procurement. Cold-chain limitations restrict fresh baby food presence in this channel.
Margin pools are shifting fastest into Online Retail; Supermarkets retain the deepest volume foundation.
Customer Type:
Purchasing authority fragments across household decision-makers and institutional gatekeepers, each demanding distinct evidence formats and relationship protocols.
- Parents:Primary household purchasers making final transaction decisions, increasingly urban middle-class dual-income couples in Java metropolitan areas. Their information sourcing shifts from clinician recommendations to peer networks and digital platforms.
- Healthcare Professionals:Pediatricians, nutritionists, and midwives influencing product selection through prescription-adjacent guidance, now the sole legally permitted marketing target under Ministry of Health breastfeeding promotion policies. Mead Johnson Indonesia invests heavily in clinician-focused educational programs.
- Childcare Centers:Institutional purchasers managing group feeding programs, requiring bulk formats and simplified preparation protocols. These entities face strict BPOM documentation requirements for supplied nutrition products.
- Retailers:Channel intermediaries controlling shelf placement and promotional execution, fragmented across modern trade chains and independent traditional trade networks in Eastern Indonesia provinces.
Healthcare Professionals control prescription-adjacent influence; Parents are gaining transactional autonomy fastest through digital channel migration.
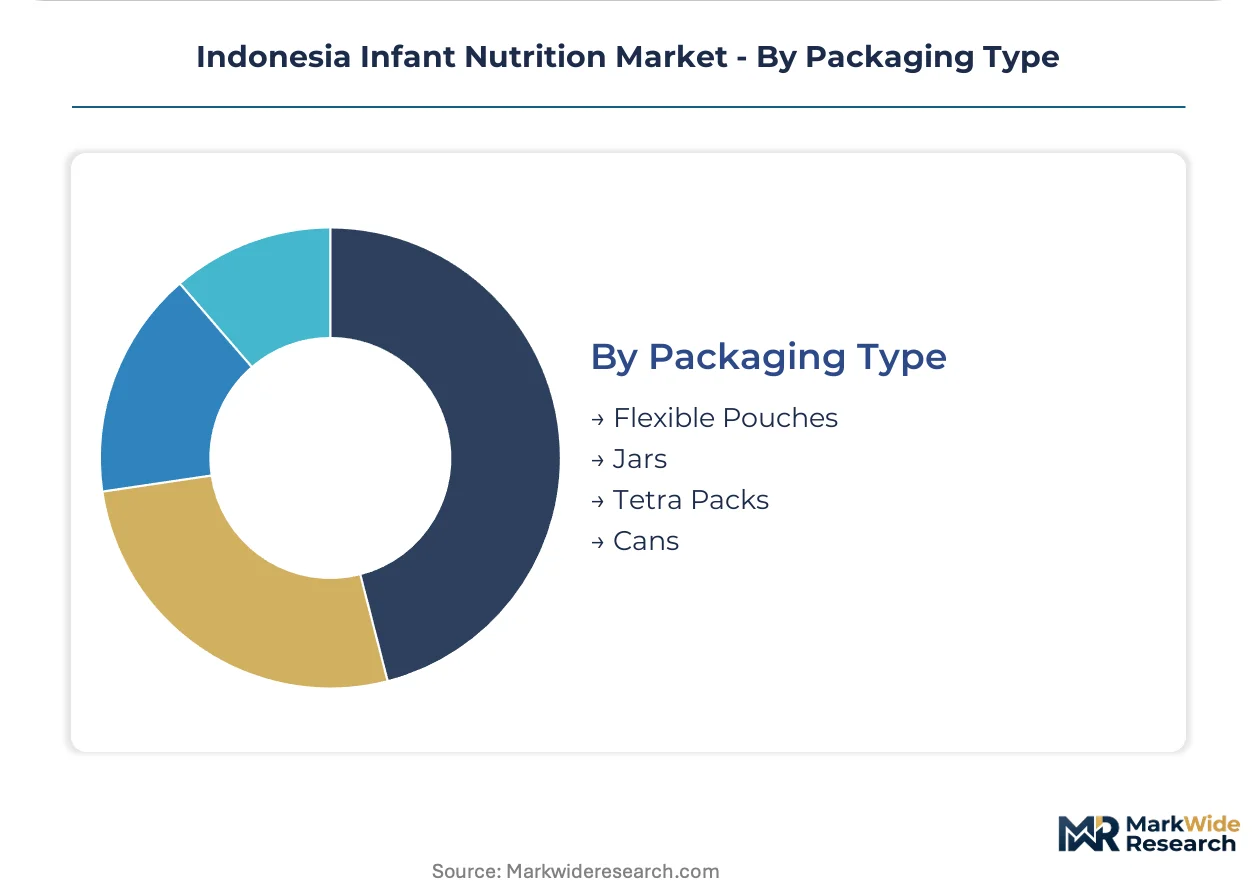
Packaging Type:
Format selection balances shelf stability, preparation convenience, and halal traceability documentation requirements across the supply chain.
- Flexible Pouches:Lightweight laminated film containers with resealable spouts, dominant in baby food and snack segments for portability and portion control. Urban parents in Bekasi and Tangerang satellite cities favor these for on-the-go feeding.
- Jars:Glass or rigid plastic containers with wide-mouth access, traditional format for cereal and pureed foods allowing visual quality inspection. These carry higher logistics costs and breakage risk in Eastern Indonesia's underdeveloped cold-chain infrastructure.
- Tetra Packs:Aseptic carton formats enabling ambient distribution of liquid formula and ready-to-feed preparations, reducing refrigeration dependency in Sulawesi and Papua provinces where cold-chain gaps persist.
- Cans:Metal containers for powdered formula with superior moisture and oxygen barrier properties, the standard for premium imported formulations subject to BPOM's electronic traceability documentation mandates.
Cans dominate premium formula placements; Flexible Pouches are climbing fastest as urban convenience preferences reshape baby food formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta anchors Indonesia's infant nutrition demand, with the Greater Jakarta metropolitan corridor generating concentrated purchasing power from dual-income households seeking fortified formula products and digital subscription services.
Java
Surabaya and Bandung metropolitan areas drive secondary demand clusters, with Surabaya's port infrastructure enabling faster imported ingredient clearance for local blenders. BPOM's electronic traceability mandates hit hardest here, where modern trade penetration and pharmacy network density run highest. East Java's manufacturing belt hosts Sarihusada's integrated production facilities serving Posyandu distribution channels.
Sumatra
Medan and Palembang concentrate North and South Sumatra demand respectively, with Medan's logistics hub status attracting cold-chain investments for liquid formula distribution. The Ministry of Health's breastfeeding promotion policies face enforcement variability across provincial health offices. Riau's industrial zones host dairy processing joint ventures supplying base powders to Jakarta blenders.
Sulawesi
Makassar anchors Eastern Indonesia's largest infant nutrition market, with first-mover brands establishing ambient-stable Tetra Pack distribution to bypass cold-chain gaps. BPOM halal certification requirements extend timelines for new entrants unfamiliar with MUI documentation protocols. North Sulawesi's Bitung port offers tariff advantages for Australian dairy ingredient imports.
Kalimantan
Balikpapan and Samarinda concentrate East Kalimantan demand among mining sector expatriate and professional households with premium imported formula preferences. Provincial health budgets limit Posyandu nutrition program coverage outside major urban centers. Tarakan's free trade zone status attracts regional distribution center investments for cross-border Borneo supply.
Papua
Jayapura and Sorong represent frontier markets with minimal modern retail penetration and reliance on church-affiliated health networks for product access. Fonterra's ingredient supply business targets local production mandates through partnerships with emerging domestic blenders. Logistics costs multiply landed prices, segmenting demand toward condensed milk alternatives in remote highland districts.
Indonesia Infant Nutrition Market Competitive Landscape
Capital-heavy producers compete with asset-light brand marketers across Indonesia's infant nutrition sector, with integrated dairy processors holding cost advantages in mid-tier powder formulations while specialized importers capture premium hypoallergenic segments. The market structure tilts toward consolidation among five dominant holding groups controlling pharmacy and modern trade shelf access. Three strategic archetypes define positioning: multinational dairy conglomerates with backward integration into ingredient supply, domestic pharmaceutical conglomerates leveraging distribution network control, and regional specialists in metabolic and allergy-focused formulations. Competitive moves concentrate on clinician education program expansion and direct-to-parent digital platform development.
Among multinational conglomerates, Nestle and Danone occupy positions exemplifying divergent sourcing strategies—Nestle leveraging global dairy network scale against Danone's specialized metabolic range focus. Kalbe Farma anchors the domestic pharmaceutical tier through pharmacy channel integration, while Mead Johnson Indonesia represents the clinician-education archetype with historical strength in hospital-linked distribution. Sarihusada sits within the Posyandu-embedded community health tier, its manufacturing scale enabling rural penetration that imported brands struggle to replicate.
| Leading Market Players |
|---|
| Nestle |
| Abbott |
| Danone |
| Kalbe Farma |
| Nutricia |
| Frisian Flag |
| Mead Johnson Indonesia |
| Sarihusada |
| Fonterra |
| Others |
Pricing and Supply Chain Analysis
BPOM's electronic traceability mandate for halal-certified ingredients gates both qualified supply access and premium-tier pricing power, forcing domestic blenders to absorb compliance costs while imported brands withdraw non-compliant SKUs rather than adapt documentation protocols.
Pricing Analysis
Clinician-endorsed credibility anchors value-based pricing for metabolic and hypoallergenic formulations, commanding sustained premiums over commodity powders despite Ministry of Health marketing restrictions limiting direct consumer reach. Price differentiation stems from MUI halal certification grade and pediatric specialist endorsement density. Cost compression in mid-tier SKUs is intensifying because Nestle's dairy sourcing scale advantages compress competitor margins. Pharmacy-dependent parents show highest price sensitivity; dual-income households subscribing through digital platforms demonstrate lowest sensitivity due to convenience bundling.
Supply Chain Analysis
Specialized lipid fraction supply rests on European and North American specialty chemical producers, with DSM and BASF dominating long-chain polyunsaturated fatty acid premix output. Domestic blenders draw whey protein concentrate and skim milk powder from New Zealand and Australian dairy processors, while micronutrient premixes source from Swiss and German ingredient houses. Single-source vulnerability concentrates in hydrolyzed protein variants where European suppliers control enzymatic processing IP. Distribution runs through Jakarta-centered pharmacy networks and modern trade chains, with cold-chain gaps in Eastern Indonesia forcing ambient-stable Tetra Pack formats for Sulawesi and Papua penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where BPOM's dual certification timelines—simultaneous registration and MUI halal approval extending 18-24 months—create a barrier-to-entry moat favoring incumbent pharmaceutical conglomerates with established regulatory affairs infrastructure.
For Market Incumbents: To counter precision fermentation startups in Bandung and Yogyakarta decentralizing dairy protein sourcing, deepen backward integration into domestic whey processing and lock exclusive pediatric clinic partnerships before subscription platforms consolidate parent relationships. Channel control through Posyandu network embedding remains the priority defensive lever against digital-native entrants. For New Entrants and Emerging Players: The 40-60% price-point gap between imported hypoallergenic formulations and locally manufactured commodity powders opens viable entry space for mid-tier halal-certified alternatives targeting Tangerang and Bekasi satellite cities. Eastern Indonesia provinces—Sulawesi, Maluku, Papua—offer the most penetrable geography given cold-chain infrastructure gaps that favor ambient-stable formats and first-mover distribution investments. For Investors and Strategic Acquirers: MUI halal certification backlog clearance acceleration is the leading indicator that regulatory capacity constraints are easing, signaling improved time-to-market economics for portfolio companies. Target domestic pharmaceutical conglomerates with integrated manufacturing scale and existing BPOM relationship density; watch for BPOM electronic traceability system expansion to additional ingredient categories as the inflection trigger for compliance-cost revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Traceability System Investment | BPOM electronic documentation mandates elevate compliance barriers for imported competitors. |
| Pediatric Clinic Partnership Network | Ministry of Health marketing restrictions concentrate influence through clinician-education channels. |
| Precision Fermentation Capacity Buildout | Domestic microbial-derived protein production reduces New Zealand dairy commodity dependency. |
| Eastern Indonesia Cold-Chain Infrastructure | Ambient-stable Tetra Pack distribution unlocks Sulawesi and Papua frontier market access. |
| Direct-to-Parent Subscription Platform | Pharmacy promotion restrictions concentrate margin pools in auto-replenishment digital channels. |
Research Methodology
Multi-period observation of BPOM registration timelines, MUI halal certification queue lengths, and pediatric clinic partnership densities anchored the trend analysis, supplemented by interviews with infant nutrition brand managers, regulatory affairs directors at pharmaceutical conglomerates, Posyandu program coordinators, and modern trade category buyers. Secondary validation drew from BPOM published registration data, Ministry of Health breastfeeding campaign expenditure disclosures, Indonesian Customs import records for dairy ingredients, and Nielsen retail audit data for formula and baby food segments. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates from household consumption surveys.
Segment-weighting applied product type, distribution channel, and customer type dimensions across the projection horizon, with formula, baby food, cereal, and snack categories modeled separately. Geographic clustering captured Java metropolitan corridor concentration against Eastern Indonesia dispersion patterns. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory event impacts and channel shift velocities. Forecast inputs incorporated dairy commodity price volatility assumptions and BPOM traceability mandate phase-in schedules.
Underlying measurement precision varies by segment; Java-based modern trade and pharmacy channels carry tighter precision than Eastern Indonesia traditional trade and Posyandu network estimates. Forecasts reflect documented assumptions regarding breastfeeding promotion policy enforcement intensity and halal certification processing capacity expansion. Dairy input cost spikes, provincial health budget fluctuations, and MUI documentation protocol changes warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Kids Food and Beverages Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Global Lactose-Free Infant Formula Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Growing Up Formula Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Pet Milk Replacers Market