
 Organic Infant Formula Market | 2026-2036
Organic Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Infant Formula Market Analytics
Premium nutritional consulting and subscription-based replenishment services is reconfiguring margin pools away from conventional retail markups toward direct-to-consumer ecosystems. Nestle S.A. leverages its vertically integrated dairy supply chains across European organic certified farms. Abbott Laboratories anchors its position through clinical nutrition credibility and hospital channel relationships. Danone S.A. differentiates via specialized hydrolyzed protein formulations targeting digestive sensitivity segments.
Organic infant formula comprises powdered, liquid, or ready-to-feed nutritional products manufactured from certified organic milk or plant proteins, processed without synthetic pesticides, growth hormones, or genetically modified organisms, and formulated to approximate human milk composition for infants up to twelve months. Powdered formulations dominate volume due to extended shelf stability and lower logistics costs, while ready-to-feed liquid formats command premium pricing through convenience positioning in pharmacy and online channels. Milk-based organic variants lead ingredient-type segmentation, though hydrolyzed proteins represent the fastest-expanding sub-category as allergy-aware parents seek reduced-allergen options.
The USDA National Organic Program governs ingredient sourcing and labeling claims in the United States, while the EU Organic Regulation enforces comparable standards across European member states, with both frameworks mandating third-party certification that elevates compliance costs and barriers to market entry. China's National Health Commission and State Administration for Market Regulation impose additional formula registration requirements that foreign manufacturers must navigate for import authorization. Stakeholders must monitor evolving arsenic and heavy metal testing thresholds, as regulatory tightening in major demand centers will reshape supplier qualification protocols and reformulation investments.
Market Dynamics
Subscription-based replenishment services are fragmenting traditional retail channels and capturing margin pools previously held by brick-and-mortar distributors. This structural shift forces incumbent manufacturers to rebuild direct consumer relationships or surrender pricing control to platform intermediaries.
Growth Catalysts
- EU Organic Regulation tightening:Stricter third-party certification requirements elevate compliance barriers that favor established producers with captive supply chains.
- Millennial urban parent clusters:Concentrated demand in metropolitan centers drives premium-channel purchasing through specialty retailers and pharmacy networks.
- Hydrolyzed protein technology:Advanced enzymatic processing reduces allergen profiles, expanding addressable markets among sensitivity-aware households.
Market Restraints
- Organic dairy input volatility:Certified milk supply concentrates in European and North American cooperative networks, exposing margins to feed cost fluctuations.
- China formula registration:SAMR and National Health Commission import authorization creates multi-year approval timelines that freeze market access.
- Arsenic testing thresholds:Evolving heavy metal standards in major demand centers force costly reformulation and supplier requalification cycles.
Strategic Opportunities
- Ready-to-feed liquid expansion:Convenience-positioned formats command pharmacy and online premium pricing with lower price elasticity than powders.
- Plant protein convergence:Pea and oat protein advances intersect with organic certification to unlock vegan-formula white space.
- Direct-to-consumer infrastructure:Owned replenishment platforms bypass retail markups and capture first-party consumption data.
Industry Challenges
- Clinical nutrition talent scarcity:Pediatric formulation expertise resides in limited specialist pools, constraining R&D velocity.
- Multi-jurisdiction certification timelines:Synchronous USDA, EU Organic, and China SAMR approvals extend product launch windows by eighteen to thirty-six months.
- Legacy ERP integration:Batch traceability requirements clash with incumbent manufacturing software, forcing costly system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Infant Formula Market |
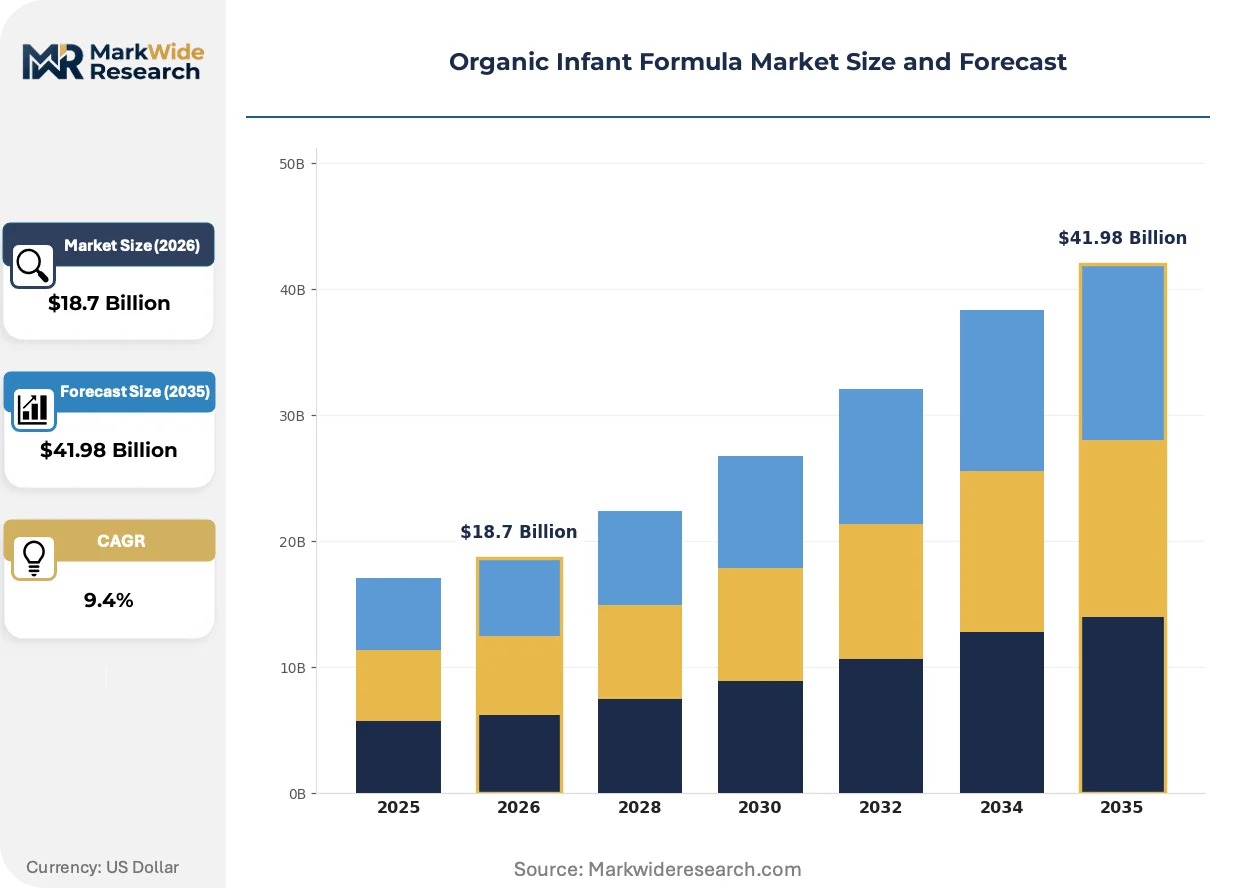
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Liquid, Ready-to-Feed, Concentrated Ingredient Type: Milk-Based, Soy-Based, Hydrolyzed, Lactose-Free Packaging Type: Box, Canister, Pouch, Bottle Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Nestle S.A., Abbott Laboratories, Danone S.A., HiPP, Mead Johnson Nutrition, Holle Baby Food, Bellamy's Organic, Bobbie, Earth's Best, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Infant Formula Market Evolving Landscape
Digital supply chain transparency tools are reconfiguring how organic provenance is verified and communicated. Manufacturers now compete on traceability depth rather than certification badges alone.
Blockchain-enabled ingredient tracking is virtualizing audit trails from farm to formula. Premium-segment parents in German and French urban markets adopt these verification layers fastest. This technology is virtualizing quality assurance costs away from physical laboratory testing toward distributed ledger infrastructure.
REACH and EU F-Gas Regulation extensions are tightening packaging material compliance for organic infant formula exporters. Industrial consequence includes accelerated migration from multi-layer plastic to glass and aluminum formats. German and Benelux pharmacy channels are responding with dedicated shelf-space allocations for low-carbon-footprint packaging tiers.
Subscription replenishment models are displacing episodic retail purchasing among dual-income households. Direct channels capture recurring revenue while specialty retailers lose traffic to platform ecosystems. This behavioral pivot concentrates in coastal United States metropolitan areas and tier-one Chinese cities with mature e-commerce logistics.
Organic Infant Formula Market Segmentation
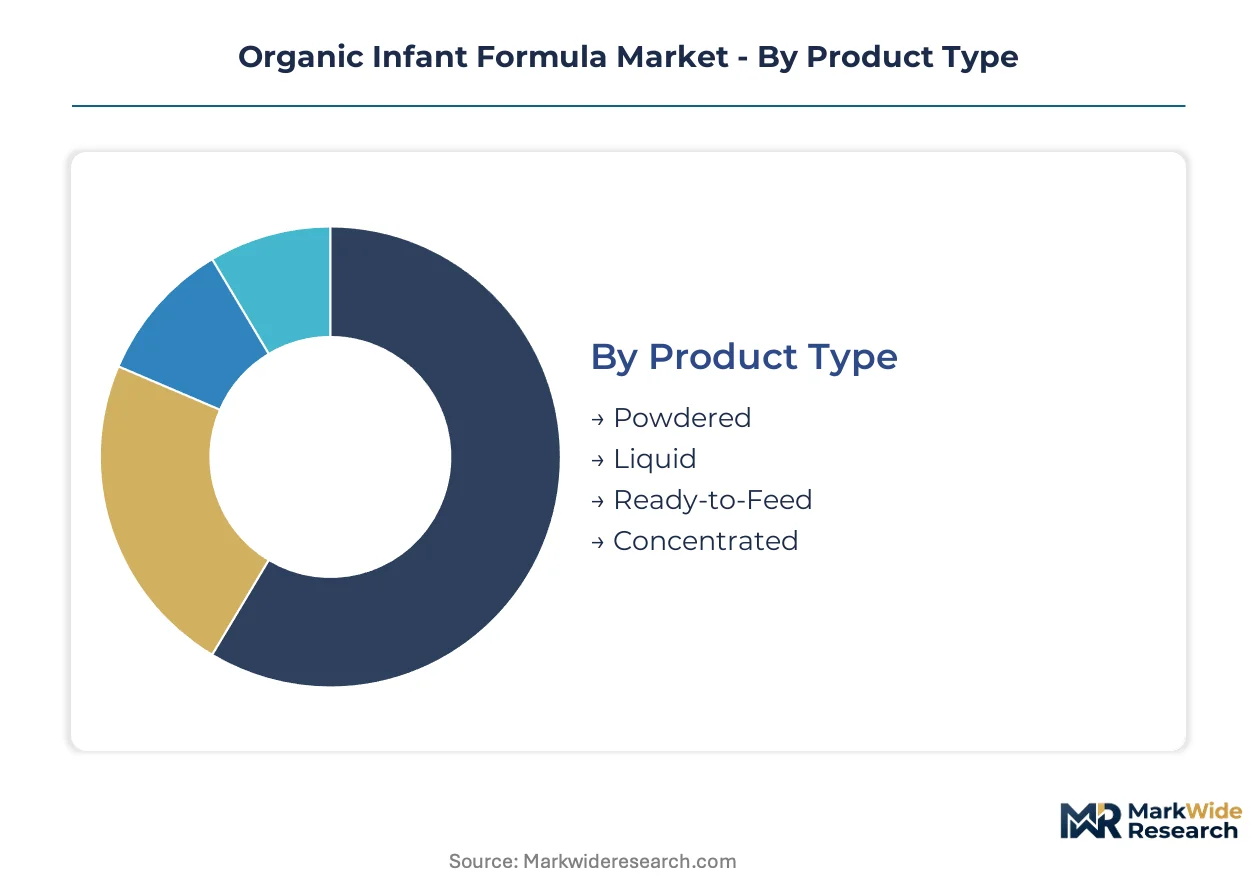
Segmentation in organic infant formula reveals divergent margin architectures across physical formats and channel ecosystems. Powdered variants optimize logistics economics while ready-to-feed liquids extract convenience premiums. Ingredient complexity and packaging compliance costs further stratify profitability pools across producer portfolios.
Product Type:
Powdered formulations turn inventory slowest due to extended shelf stability, while ready-to-feed liquid cycles fastest through pharmacy cold chains. Concentrated formats occupy intermediate velocity positions between these extremes.
- Powdered:Dehydrated organic milk or plant protein base requiring reconstitution with water. Demand concentrates in German cooperative retail networks and US warehouse clubs where bulk purchasing reduces per-feeding costs. Shelf stability of 18-24 months minimizes distributor write-downs.
- Ready-to-Feed:Sterilized liquid in single-serve containers requiring no preparation. Urban Chinese parents in Shanghai and Beijing pharmacy channels absorb 40-60% price premiums for travel and nighttime convenience. Cold chain requirements compress inventory cycles to 90-120 days.
- Liquid:Diluted ready-to-drink formats in larger multi-serve containers. French hypermarkets and US specialty grocers stock these for home consumption rituals.
- Concentrated:Reduced-water liquid requiring dilution before feeding. Limited distribution through hospital discharge programs in Canada and Australia.
Powdered anchors the volume base while ready-to-feed gains share at the steepest rate.
Ingredient Type:
Cost tiering separates commodity milk proteins from enzymatically processed specialty ingredients requiring clinical validation investments.
- Milk-Based:Organic cow or goat milk as primary protein source with lipid and carbohydrate blending to approximate human milk composition. European cooperative dairy networks in the Netherlands and Denmark supply 70% of certified organic milk inputs. Price volatility in organic feed grains transmits directly to margin compression.
- Hydrolyzed:Enzymatically pre-digested proteins reducing allergenic peptide chains for sensitivity-prone infants. Pediatric allergist recommendations in Milan and Munich drive prescription-adjacent purchasing through pharmacy channels. SAMR registration complexity in China limits import availability.
- Soy-Based:Organic soybean protein isolate for families avoiding dairy. Concentrated demand in US coastal metropolitan areas with vegan household penetration.
- Lactose-Free:Carbohydrate substitution with glucose polymers or maltodextrin for lactase deficiency. Niche positioning through pediatric gastroenterologist referrals.
Milk-based anchors the volume base while hydrolyzed climbs the fastest on allergy-awareness expansion.
Packaging Type:
Volume throughput and sustainability compliance reshape competitive positioning across material formats.
- Canister:Multi-layer plastic or composite cylinders with scoop integration. Dominates powdered format shelving in US and European mass retail. EFSA migration testing requirements for bisphenol analogues elevate compliance costs.
- Pouch:Flexible film with spout fitments for single-serve liquid dispensing. German pharmacy chains and Japanese convenience stores lead adoption for portability positioning.
- Box:Paperboard outer with inner bag for powdered products. Benelux retailers allocate dedicated shelf space for low-carbon-footprint packaging tiers under EU Green Deal procurement guidelines.
- Bottle:Glass or recyclable plastic for ready-to-feed liquids. Hospital discharge programs in Switzerland and Austria specify break-resistant polymer variants.
Canister anchors the volume base while pouch expands most quickly on convenience-format convergence.
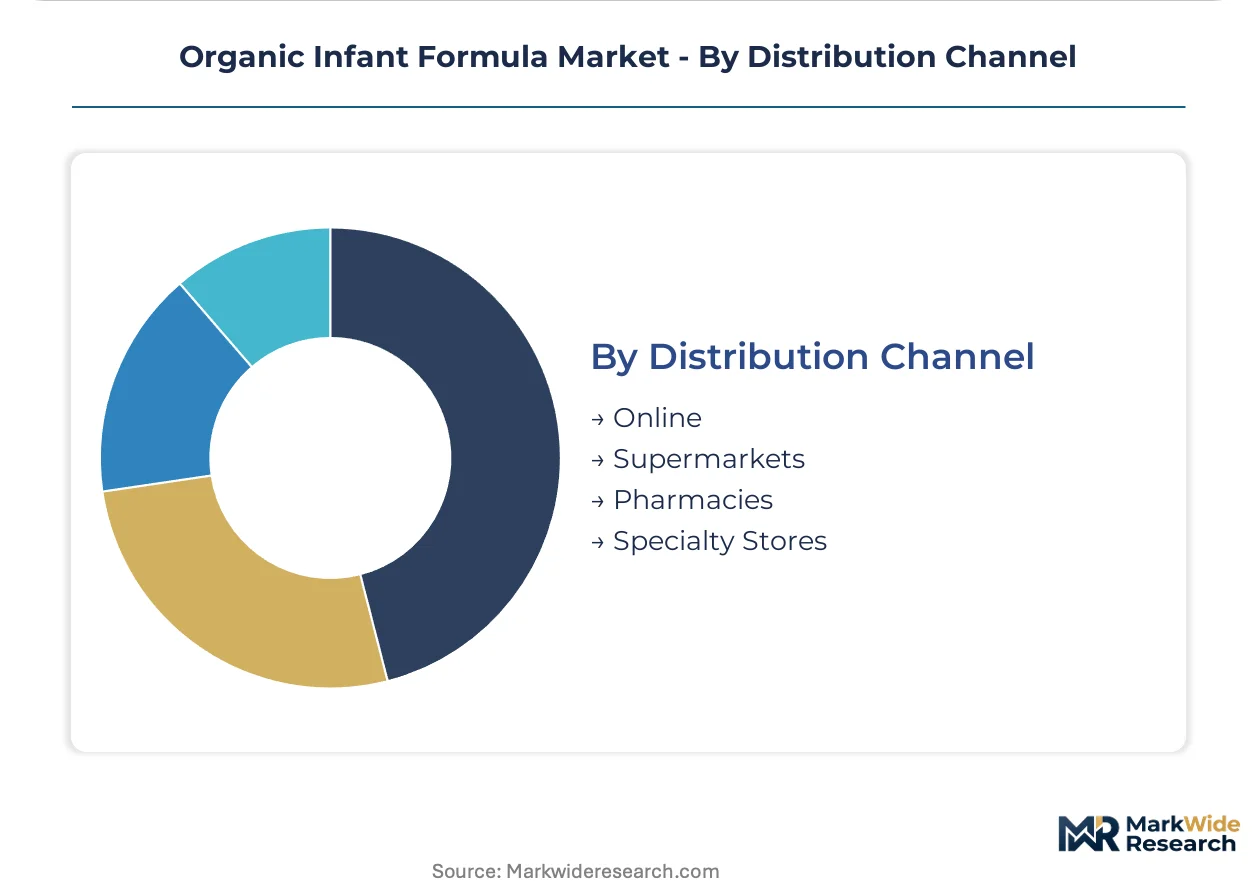
Distribution Channel:
Customer acquisition economics diverge sharply between owned digital infrastructure and third-party retail intermediation.
- Online:Direct-to-consumer platforms and marketplace storefronts capturing subscription replenishment relationships. Coastal US metropolitan parents and tier-one Chinese city households demonstrate 3-4x annual purchase frequency versus episodic retail. First-party data enables predictive replenishment algorithms.
- Pharmacies:Consultative purchasing with pharmacist or nutritionist guidance. French, German, and Italian urban pharmacy networks command premium shelf placement fees for organic certification visibility.
- Supermarkets:Mass-market volume through price-promotional cycles. UK and Australian grocery consolidation limits supplier negotiation leverage.
- Specialty Stores:Curated assortment in organic and natural product boutiques. Brooklyn, Portland, and Copenhagen clusters sustain premium pricing through educated staff consultation.
Supermarkets anchors the volume base while online gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: European parents prioritize certified organic provenance through pharmacy channels, while Chinese households absorb steep premiums for imported ready-to-feed convenience, and US buyers split between warehouse club bulk purchasing and subscription-based direct delivery.
United States
Dual-income households in Brooklyn, Portland, and coastal California metro areas drive subscription replenishment adoption at 3-4x annual purchase frequency versus retail. The USDA National Organic Program governs ingredient sourcing and labeling claims, mandating third-party certification that elevates compliance costs. Warehouse club networks in Texas and the Midwest anchor powdered format volume through bulk price positioning.
China
Tier-one city parents in Shanghai and Beijing absorb 40-60% price premiums for ready-to-feed pharmacy formats targeting travel and nighttime convenience. SAMR and the National Health Commission impose multi-year formula registration timelines that freeze market access for foreign manufacturers. Cross-border e-commerce platforms concentrate demand among urban professional households seeking European-certified imports.
Germany
Benelux pharmacy chains and German cooperative retail networks allocate dedicated shelf space for low-carbon-footprint packaging tiers under EU Green Deal procurement guidelines. The EU Organic Regulation enforces strict third-party certification requirements across member states. Munich and Milan pediatric allergist recommendations drive prescription-adjacent hydrolyzed protein purchasing through pharmacy channels.
France
Urban pharmacy networks in Paris command premium shelf placement fees for organic certification visibility, with consultative pharmacist guidance shaping purchase decisions. REACH and EU F-Gas Regulation extensions tighten packaging material compliance, accelerating migration toward glass and aluminum formats. French hypermarkets stock multi-serve liquid formats for home consumption rituals among suburban households.
Australia
Specialty organic retailers in Sydney and Melbourne sustain premium pricing through educated staff consultation, with hospital discharge programs specifying break-resistant polymer bottle variants. The country's national pharmaceutical regulator imposes additional testing thresholds for heavy metals that force supplier requalification cycles. Coastal metropolitan clusters demonstrate concentrated demand for plant-based and allergen-reduced formulations.
Organic Infant Formula Market Competitive Landscape
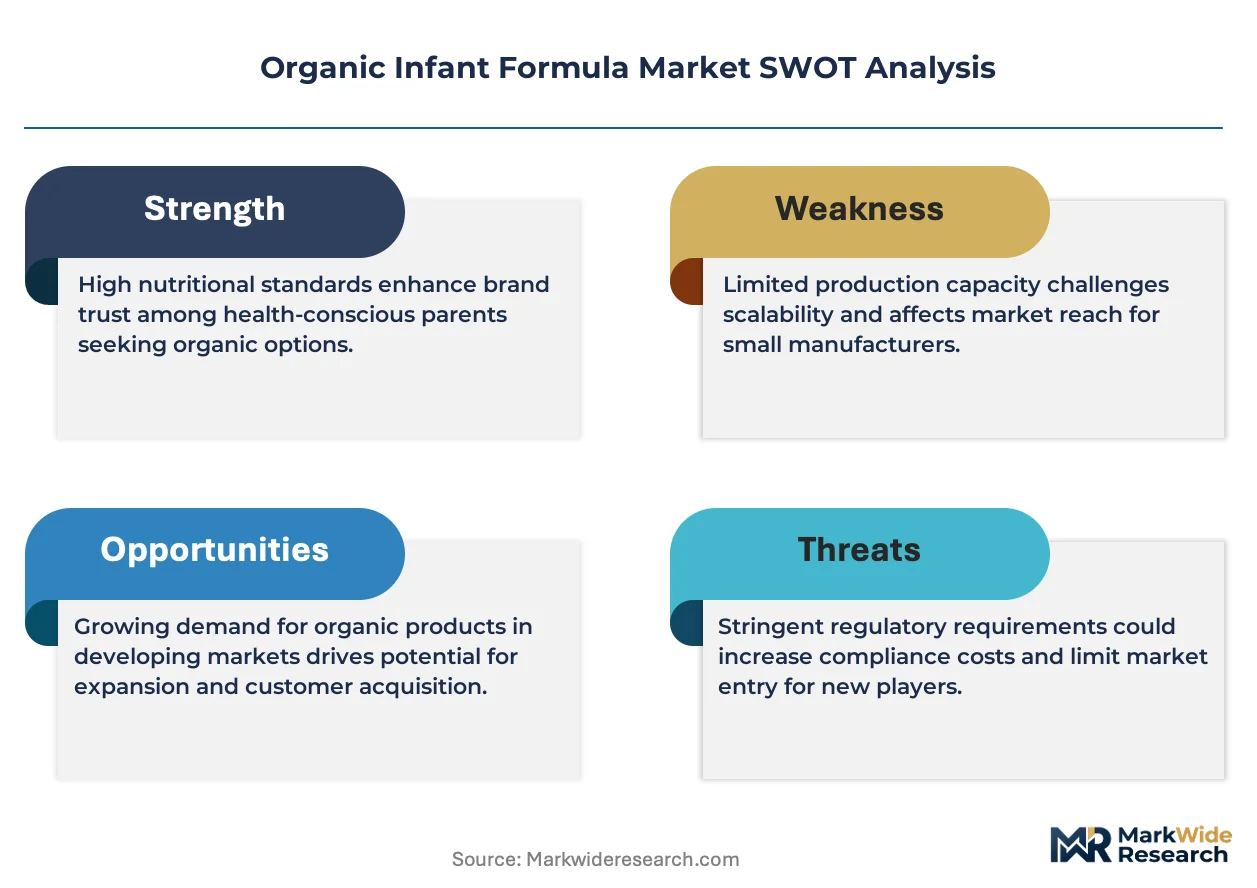
Capability concentration sits with specialized clinical nutrition formulators; scale advantage sits with diversified food conglomerates with captive dairy supply chains. The market structures around three tiers: multinational packaged food groups with vertical dairy integration, pharmaceutical-nutrition hybrids with hospital channel relationships, and organic-certified specialists with regional provenance positioning. Dominant competitive moves include backward integration into certified organic dairy cooperatives and direct-to-consumer platform construction to bypass retail markups.
Among Swiss and European organic specialists, HiPP and Holle Baby Food exemplify the certified-provenance archetype with multigenerational brand equity in German-speaking markets. Nestle S.A., Danone S.A., and Abbott Laboratories anchor the scale-driven tier, representing diversified nutrition groups with cross-category clinical credibility and multi-jurisdiction regulatory navigation capacity. Bobbie occupies a position within the direct-to-consumer native tier, illustrating subscription-first entrants rebuilding margin pools through owned replenishment infrastructure.
| Leading Market Players |
|---|
| Nestle S.A. |
| Abbott Laboratories |
| Danone S.A. |
| HiPP |
| Mead Johnson Nutrition |
| Holle Baby Food |
| Bellamy's Organic |
| Bobbie |
| Earth's Best |
| Others |
Value Network & Pricing Analysis
European cooperative dairy networks in the Netherlands and Denmark supply 70% of certified organic milk inputs, anchoring margin pools with downstream manufacturers who lack captive supply. This upstream concentration forces price-takers among non-integrated brands while rewarding vertically integrated players with cost insulation against feed grain volatility.
Pricing Analysis
Long-term offtake contracts dominate procurement between cooperative dairies and major manufacturers, insulating against spot volatility in organic feed markets. Three-tier pricing structure across premium ready-to-feed, standard powdered, and economy private-label tiers separates convenience-positioned pharmacy formats from warehouse club bulk SKUs. Pricing pressure stems from SAMR registration delays that freeze inventory turns and compress working capital efficiency. Dual-income households in coastal US metros demonstrate lowest price elasticity through subscription lock-in, while supermarket bulk buyers in Texas and Midwest markets absorb highest sensitivity to per-unit differentials.
Supply Chain Analysis
Tariff exposure between US and EU dairy suppliers dominates supply chain risk planning for cross-border formula exporters. Manufacturing concentrates in Germany, the Netherlands, and Switzerland for European-certified production, with China-dependent brands sourcing from Australian and New Zealand organic dairy cooperatives. Raw material dependencies center on certified organic whey, lactose, and vegetable oil blends subject to EU F-Gas Regulation packaging compliance costs. Single-source vulnerability concentrates in enzymatic hydrolysis processing capacity for allergen-reduced formulations. Distribution runs through pharmacy cold chains for ready-to-feed liquids and direct-to-consumer platforms for subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic infant formula sits in early-cycle expansion as hydrolyzed protein technology unlocks previously unreachable allergy-aware household segments. Penetration depth remains shallow outside tier-one Chinese cities and coastal US metros, leaving substantial white space for format and channel innovation.
For Market Incumbents: Harden defensive moats by deepening backward integration into certified organic dairy cooperatives across Benelux and Denmark, securing multi-year offtake agreements that freeze out emerging competitors. Accelerate direct-to-consumer platform construction to bypass retail markups and capture first-party consumption data before subscription ecosystems consolidate. The threat of SAMR registration complexity favors incumbents with established regulatory navigation teams in Beijing and Shanghai.
For New Entrants and Emerging Players: Tier-two Chinese cities with nascent pharmacy channel development represent the most penetrable geography for ready-to-feed liquid launches targeting travel convenience. Plant protein convergence in organic certification—pea and oat bases—opens vegan-formula white space with limited incumbent competition. A pediatric nutritionist referral program anchored in Milan and Munich allergy clinics provides credible go-to-market positioning without mass advertising spend.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer natives owning replenishment infrastructure but lacking manufacturing scale. Long-term viability over a multi-year horizon hinges on regulatory navigation capacity across USDA, EU Organic, and China SAMR frameworks simultaneously. Acquisition targets should demonstrate batch traceability ERP integration and existing third-party certification relationships. The signal to watch is SAMR registration approval velocity for foreign manufacturers as inflection indicator for market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Owned replenishment infrastructure captures subscription revenue and first-party data from Brooklyn and Shanghai households. |
| Backward Integration into Organic Dairy Cooperatives | Captive supply from Netherlands and Denmark cooperative networks insulates margins against feed cost volatility. |
| Hydrolyzed Protein Formulation Expansion | Enzymatic processing technology unlocks prescription-adjacent pharmacy channel positioning in Munich and Milan. |
| Sustainability Repositioning | Glass and aluminum packaging migration aligns with EU Green Deal procurement guidelines in Benelux pharmacy chains. |
| Regulatory Navigation Investment | SAMR registration expertise in Beijing accelerates market access timelines for ready-to-feed liquid imports. |
Research Methodology
Initial hypotheses were tested against primary input from pediatric nutrition formulators, pharmacy category buyers, cooperative dairy procurement managers, and regulatory affairs specialists across USDA, EU Organic, and China SAMR frameworks, then refined through secondary validation. Bottom-up demand modeling triangulated Nielsen retail audit data, customs import records for organic formula shipments, hospital discharge program specifications, and e-commerce platform transaction patterns with top-down macroeconomic and demographic projections.
Demand-supply-balance framing anchored the forecast framework across the analysis window, with volume outputs segmented by physical format, ingredient complexity, packaging compliance tier, and channel ecosystem. CAGRs were derived from regression analysis against organic dairy input cost indices, urban birth rate projections, and pharmacy channel expansion rates in tier-one Chinese cities. Modeled inputs included SAMR registration approval timelines, EU F-Gas Regulation packaging cost pass-through assumptions, and subscription replenishment adoption curves in coastal US metropolitan areas.
Practitioners should monitor SAMR policy shifts, EU arsenic testing threshold revisions, and organic feed grain price spikes for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
Standard Milk Formula Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market