
 North America Ship Bridge Simulators Market | 2026-2036
North America Ship Bridge Simulators Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ship Bridge Simulators Market Analytics
The capability gap between high-fidelity full-mission providers and desktop-only vendors is collapsing as software-defined visualization erodes hardware barriers to entry. Kongsberg Digital leverages its integrated vessel-control heritage to sustain premium positioning across integrated bridge systems. Wärtsilä anchors its North American presence through maritime training partnerships with Gulf Coast and Great Lakes port authorities. CAE competes by extending its defense aviation simulation expertise into naval bridge environments, occupying a distinct cross-domain niche.
North America ship bridge simulators replicate vessel command environments through motion platforms, 360-degree visual channels, and physics-based hydrodynamic modeling for officer training and certification. These systems integrate radar, ECDIS, autopilot, and GMDSS interfaces to reproduce operational conditions without maritime risk exposure. Full mission installations command the highest capital allocation from naval forces and coast guards, while cloud-based deployment is gaining traction among training institutions seeking distributed access with lower infrastructure commitment. Desktop and part-task configurations serve merchant shipping operators focused on recurrent competency drills rather than immersive scenario complexity.
The U.S. Coast Guard enforces STCW training standards under domestic maritime regulations, while Transport Canada administers parallel certification requirements through its marine safety directorate. These frameworks mandate periodic simulator assessment for deck officer credentials, directly sustaining replacement demand and capability upgrade cycles. Stakeholders must monitor how artificial intelligence integration into scenario generation reshapes procurement criteria and vendor qualification thresholds.
Market Dynamics
Software-defined visualization is collapsing the capability gap between high-fidelity full-mission systems and desktop configurations, eroding hardware barriers that once protected premium vendors and redistributing competitive advantage toward software-integrated platforms.
Growth Catalysts
- STCW compliance mandates:The U.S. Coast Guard's regulatory updates on training standards are accelerating replacement cycles for legacy equipment across maritime academies and commercial training centers.
- Gulf Coast maritime clusters:Concentrated port authority investment in integrated training infrastructure around Houston and New Orleans is generating sustained procurement demand for full-mission bridge systems.
- Cloud-based deployment models:Distributed access architectures are lowering infrastructure commitment thresholds for regional training institutions previously excluded from high-fidelity simulator acquisition.
Market Restraints
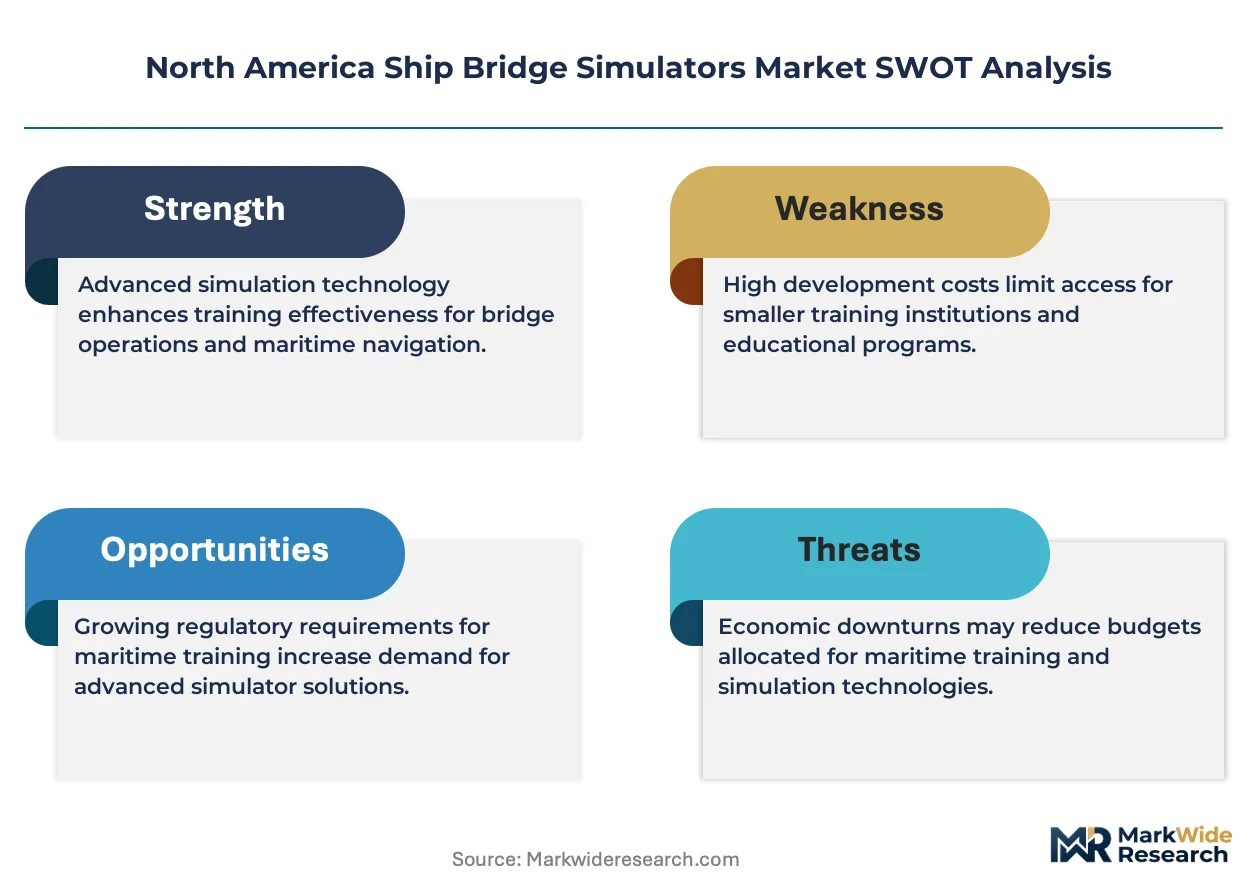
- Specialized motion platform supply:Hydraulic and electric motion base manufacturing concentrates among a limited set of European and Japanese suppliers, creating delivery bottlenecks for full-mission installations.
- Physics engine licensing costs:Proprietary hydrodynamic modeling software requires recurring license fees that inflate total cost of ownership for training institutions with constrained capital budgets.
- Facility retrofit requirements:Existing maritime training centers face structural modification costs for dome projection systems and vibration isolation that delay procurement decisions.
Strategic Opportunities
- Great Lakes training expansion:Canadian and U.S. port authorities around the St. Lawrence Seaway system remain underpenetrated relative to coastal maritime infrastructure investment levels.
- Artificial intelligence scenario generation:Machine learning integration into exercise scripting is enabling adaptive difficulty calibration and reducing instructor preparation burden.
- Remote proctored certification:Distributed simulator networks are creating pathways for at-sea crew to maintain credentials without shore leave scheduling constraints.
Industry Challenges
- Instructor technical proficiency:Scenario authoring and system administration for integrated bridge environments requires hybrid maritime-operational and IT skill sets that compete with commercial shipping salaries.
- Legacy ECDIS integration:Retrofitting older simulator installations with updated electronic chart display standards involves proprietary interface compatibility testing that extends deployment timelines.
- Cross-vendor scenario portability:Absence of standardized exercise file formats locks training institutions into single-supplier ecosystems and complicates competitive procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ship Bridge Simulators Market |
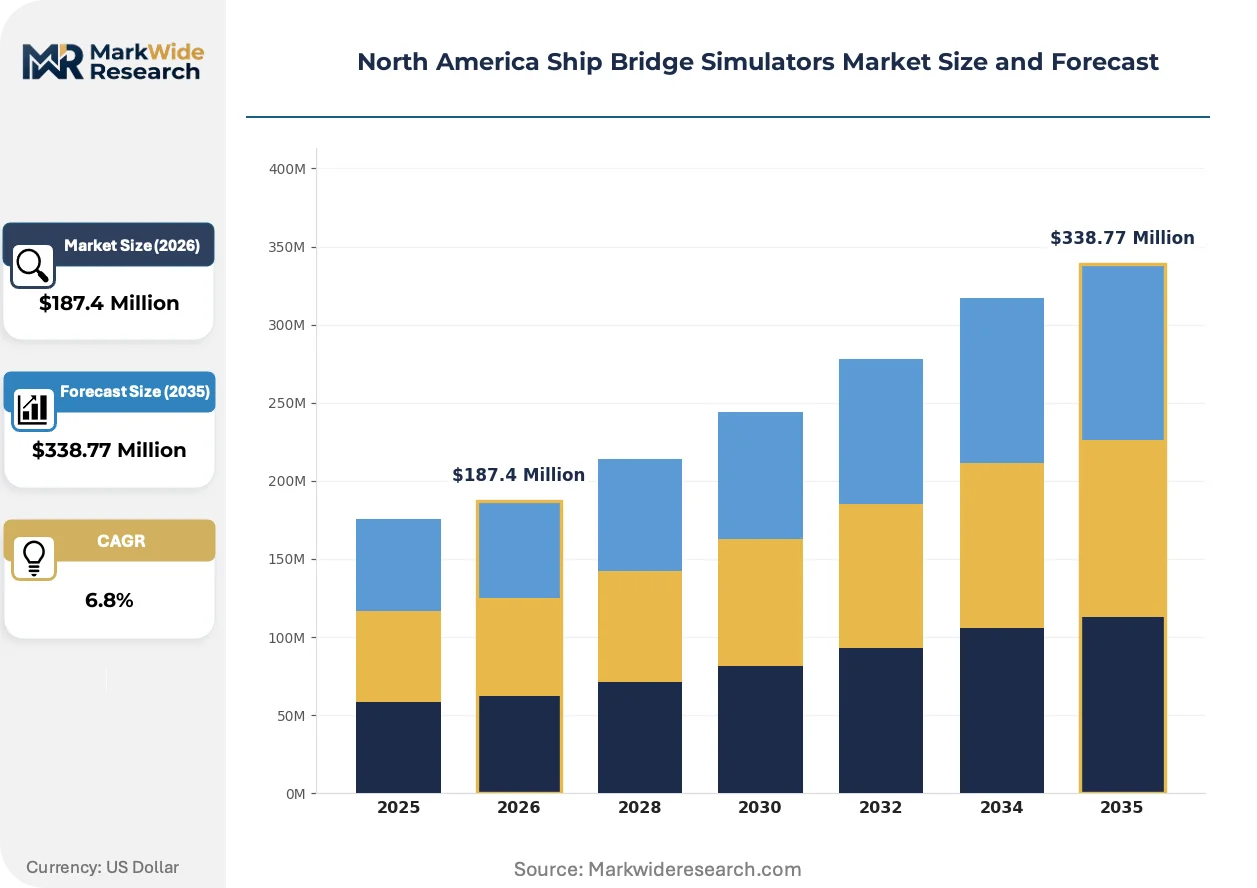
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Mission, Part Task, Desktop, Engine Room Simulator End User: Naval Forces, Coast Guards, Merchant Shipping, Training Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Remote Access Technology: Virtual Reality, Augmented Reality, Artificial Intelligence, Simulation Software |
| Companies Covered | Kongsberg Digital, Wärtsilä, CAE, L3Harris, General Dynamics Information Technology, Rheinmetall AG, ST Engineering, AVEVA Group plc, Presagis Canada Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ship Bridge Simulators Market Evolving Landscape
Artificial intelligence integration and software-defined architectures are restructuring how maritime training capabilities are delivered, purchased, and certified across North American institutions.
Physics-based hydrodynamic modeling is migrating from dedicated hardware arrays to GPU-accelerated software engines that replicate vessel handling characteristics with equivalent fidelity. Maritime academies in the Pacific Northwest and Gulf Coast regions are piloting these reduced-footprint configurations for intermediate certification modules. This shift is displacing the capital-intensive motion platform as the default threshold for credible training, compressing vendor pricing power at the mid-market tier.
Transport Canada's marine safety directorate has aligned domestic certification requirements with amended STCW guidelines on simulator-based assessment, creating parallel compliance obligations with U.S. regulatory frameworks. This harmonization reduces certification friction for cross-border crew mobility but intensifies documentation requirements for training providers seeking dual accreditation. Institutions operating near the Canada-U.S. border in the Great Lakes region are consolidating procurement to satisfy both regulatory regimes simultaneously.
Subscription-based access models are emerging as an alternative to capital purchase for smaller merchant operators and inland waterway training programs. Channel intermediaries including maritime industry associations are aggregating demand to negotiate fleet-wide simulator time allocations. This pattern is most visible among tug and barge operators along the Mississippi River system and intracoastal waterway networks seeking recurrent competency drills without facility ownership.
North America Ship Bridge Simulators Market Segmentation
Training mandates from the U.S. Coast Guard and Transport Canada create divergent procurement patterns across simulator configurations. Regulatory compliance tiers directly shape capital allocation between immersive full-mission systems and accessible desktop alternatives.
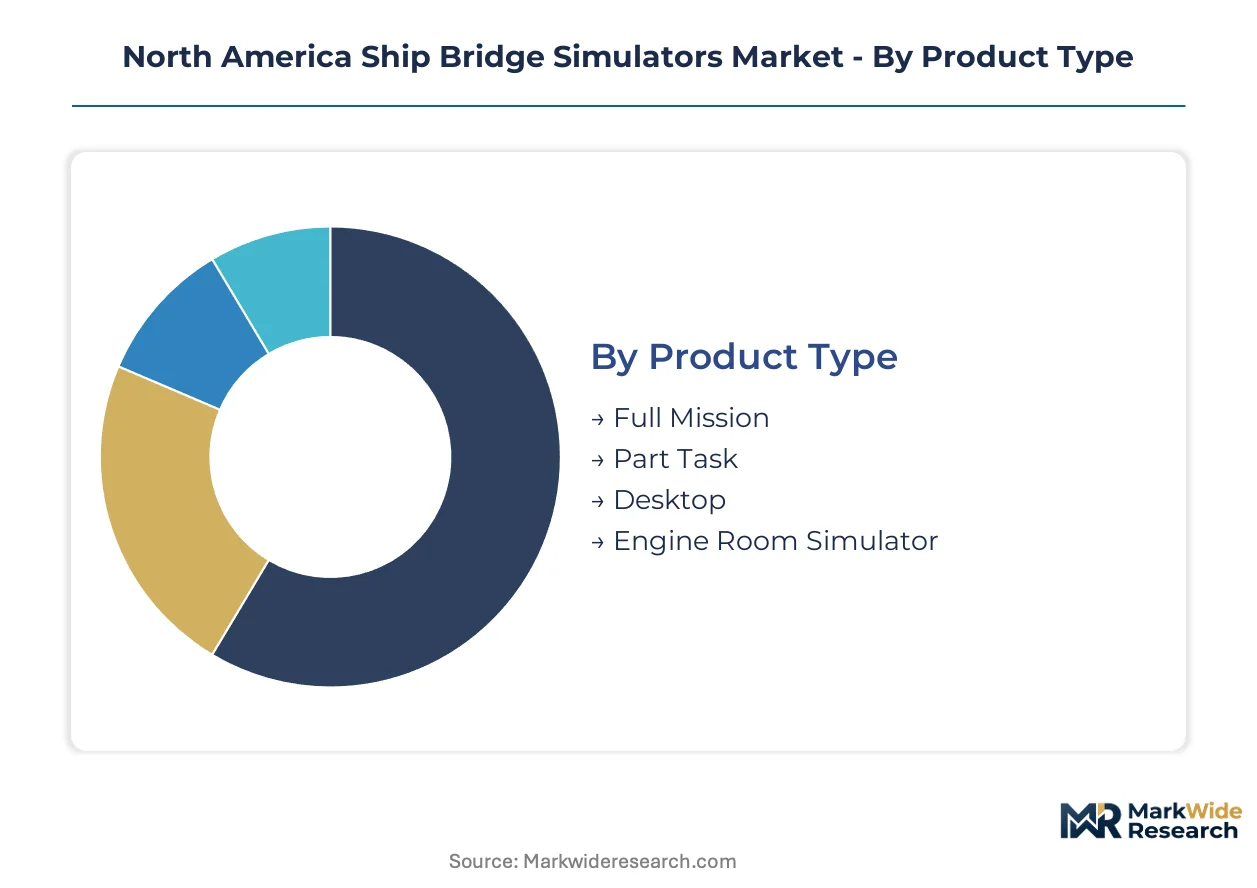
Product Type:
The U.S. Coast Guard's STCW assessment requirements differentiate acceptable simulator fidelity levels for deck officer certification, while Transport Canada's marine safety directorate maintains parallel but distinct equipment standards.
- Full Mission:These installations integrate 360-degree visual projection, motion platforms, and complete bridge instrumentation for immersive officer training. Gulf Coast maritime academies around Houston and New Orleans concentrate procurement here due to concentrated port authority investment in integrated training infrastructure.
- Part Task:Modular configurations isolate specific competencies such as radar plotting or ECDIS operation without full environmental simulation. Training institutions in the Pacific Northwest favor these systems for intermediate certification modules where capital constraints limit full-mission acquisition.
- Desktop:Screen-based interfaces deliver core navigation training without physical bridge replication. Mississippi River tug operators deploy these for recurrent competency drills between active duty rotations.
- Engine Room Simulator:Complementary systems replicate propulsion and auxiliary machinery control for integrated crew training. Great Lakes maritime programs use these to satisfy cross-border certification requirements covering both deck and engineering disciplines.
Full Mission handles the majority of throughput; Desktop is gaining share fastest as software-defined visualization erodes fidelity barriers.
End User:
Budget cycles and procurement authority structures vary sharply across institutional categories, with federal defense channels operating on multi-year capital programs while commercial operators favor operational expenditure models.
- Naval Forces:These customers demand classified-scenario capability and cybersecurity-hardened architectures for tactical training. U.S. Navy installations concentrate on the Atlantic and Pacific coasts with specialized requirements for combat information center integration.
- Coast Guards:Dual-mission training for search-and-rescue alongside law enforcement drives unique scenario libraries. The U.S. Coast Guard's training center in Yorktown, Virginia maintains the region's largest dedicated installation.
- Merchant Shipping:Container lines and bulk operators prioritize recurrent certification cost efficiency over scenario complexity. Gulf Coast headquarters of major operators sponsor shared training facilities to distribute capital burden.
- Training Institutions:Maritime academies and commercial centers balance regulatory compliance against enrollment scalability. California State University Maritime Academy and Texas A&M Maritime represent the largest academic procurement channels.
Training Institutions move the highest unit volumes; Merchant Shipping is expanding most quickly as fleet-wide certification mandates tighten.
Deployment:
Facility ownership economics and crew scheduling constraints determine architecture preference, with distributed access models gaining traction where shore leave limitations disrupt traditional training logistics.
- On-Premise:Dedicated physical installations with localized hardware and instructor presence dominate legacy procurement. Established maritime academies along the Atlantic seaboard maintain these configurations for regulatory audit traceability.
- Cloud-Based:Centralized scenario hosting with browser-delivered interfaces reduces infrastructure commitment for regional programs. Inland waterway training providers along the Ohio River system pilot these models for dispersed towboat operator access.
- Hybrid:Combinations reserve high-fidelity physical sessions for final assessment while delivering preparatory modules remotely. Canadian institutions near the St. Lawrence Seaway adopt this architecture to serve cross-border student populations.
- Remote Access:At-sea crew connect to shore-hosted simulators via satellite link for certification maintenance. Deep-water shipping operators in the Pacific Northwest deploy these for uninterrupted credential compliance during extended voyages.
On-Premise retains the installed base; Cloud-Based shows the steepest expansion trajectory as infrastructure-as-a-service models mature.
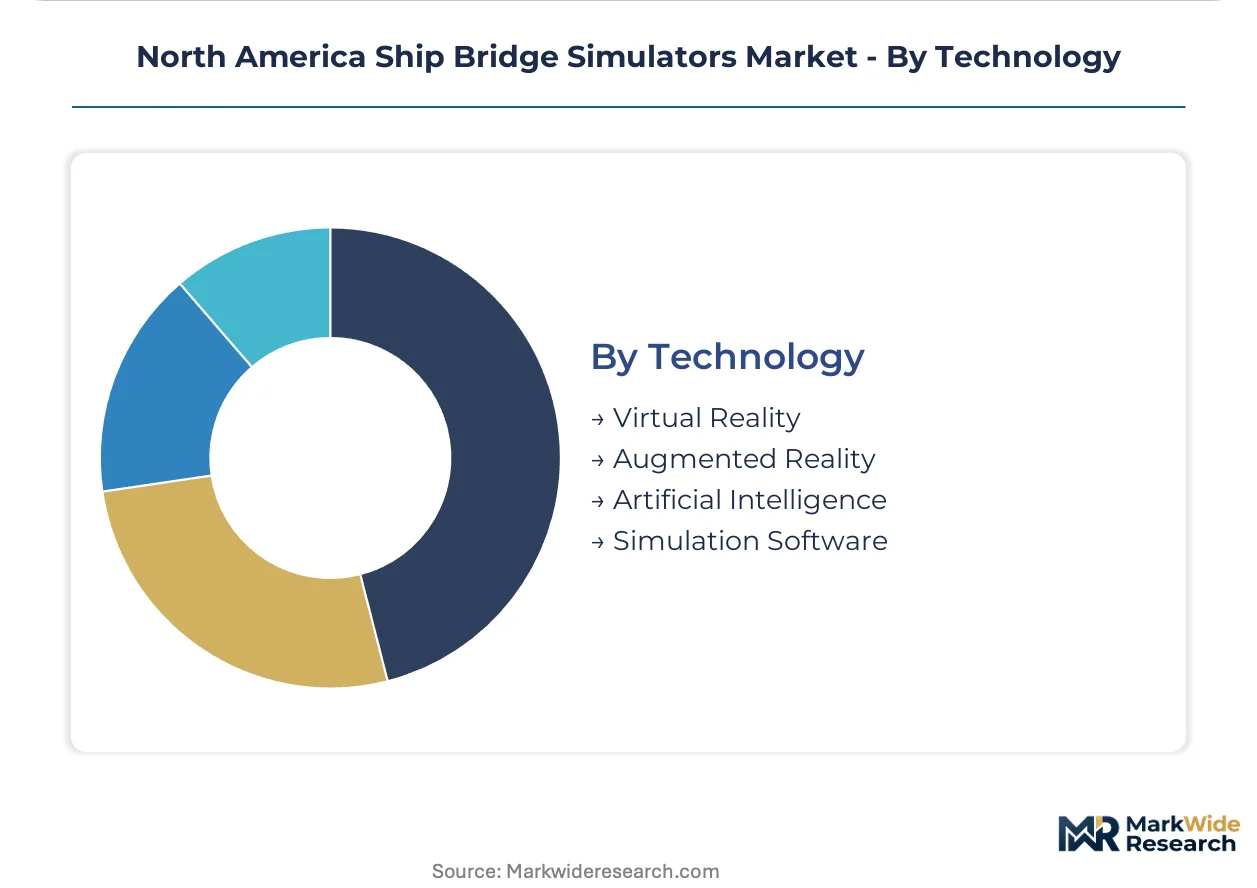
Technology:
Software maturity curves and hardware cost trajectories determine adoption sequencing, with artificial intelligence integration now reshaping procurement evaluation criteria across all customer categories.
- Virtual Reality:Head-mounted displays deliver immersive visual environments at reduced footprint compared to projection domes. Pacific Northwest pilot programs evaluate these for ice navigation and restricted visibility scenario training.
- Augmented Reality:Overlay systems blend physical bridge instrumentation with synthetic visual channels for hybrid training modes. Great Lakes operators test these for confined waterway maneuvering where local landmark recognition matters.
- Artificial Intelligence:Machine learning engines generate adaptive scenarios and automate instructor workload for exercise calibration. Both U.S. and Canadian regulators now reference AI integration in updated training equipment guidelines.
- Simulation Software:Physics engines and scenario authoring platforms constitute the core intellectual property layer across all hardware configurations. Licensing cost structures from European hydrodynamic modeling specialists influence total ownership economics.
Simulation Software underpins every deployment; Artificial Intelligence is climbing the fastest on vendor qualification priority lists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States Gulf Coast maritime clusters while Canadian Great Lakes institutions operate under tighter capital constraints, creating a two-tier procurement dynamic across the continent.
United States
Gulf Coast port authorities around Houston and New Orleans drive concentrated demand for full-mission bridge systems. The U.S. Coast Guard's STCW regulatory updates mandate accelerated replacement cycles for legacy training equipment. Pacific Northwest maritime academies in Washington and Oregon states pilot reduced-footprint configurations for intermediate certification modules.
Canada
Transport Canada's marine safety directorate enforces parallel certification requirements that intensify documentation burdens for dual-accredited training providers. Institutions near the St. Lawrence Seaway consolidate procurement to satisfy both Canadian and U.S. regulatory regimes simultaneously. Quebec and Ontario maritime programs face structural retrofit costs for dome projection systems that delay procurement timelines.
Mexico
Expansion of Pacific and Gulf coast container terminal capacity generates demand for officer training infrastructure. Mexico's federal maritime authority aligns domestic certification standards with international STCW amendments. Port modernization programs around Manzanillo and Veracruz incorporate simulator-based assessment into workforce development plans.
North America Ship Bridge Simulators Market Competitive Landscape
Concentration sits with integrated maritime technology conglomerates that combine vessel-control heritage with simulation software expertise. Three strategic archetypes dominate: full-mission system integrators leveraging motion platform partnerships, defense contractors extending naval simulation capabilities, and software specialists eroding hardware barriers through GPU-accelerated physics engines. Competitive moves center on strategic partnerships with port authorities and technology licensing arrangements for hydrodynamic modeling engines.
Among Nordic-integrated maritime technology providers, Kongsberg Digital and Wärtsilä exemplify the full-mission archetype through their vessel-control heritage and established Gulf Coast training partnerships. CAE occupies a distinct position as a cross-domain specialist extending defense aviation simulation expertise into naval bridge environments. These three companies anchor the premium tier where integrated bridge system knowledge sustains pricing power against software-defined challengers.
| Leading Market Players |
|---|
| Kongsberg Digital |
| Wärtsilä |
| CAE |
| L3Harris |
| General Dynamics Information Technology |
| Rheinmetall AG |
| ST Engineering |
| AVEVA Group plc |
| Presagis Canada Inc. |
| Others |
Value Network & Pricing Analysis
U.S. Coast Guard STCW certification requirements gate both vendor qualification and price differentiation, mandating specific fidelity thresholds that separate approved training equipment from non-compliant alternatives while creating tiered procurement budgets across institutional categories.
Pricing Analysis
Configured-to-order pricing for full-mission bridge systems commands substantial premiums over standard desktop configurations, with customization depth around motion platform specifications and visual channel count driving spreads. Three-tier pricing structure across premium, standard, and economy levels maps to certification grade requirements, where naval forces and coast guards occupy the premium tier while merchant operators cluster in standard configurations. Cost compression in the mid-market tier is intensifying because software-defined visualization erodes hardware-based fidelity premiums. Training institutions exhibit the highest price sensitivity due to capital budget constraints, whereas defense channels demonstrate lowest sensitivity given mission-critical procurement authority.
Supply Chain Analysis
Japan and Germany anchor motion platform manufacturing through specialized hydraulic and electric base suppliers that dominate full-mission system integration. Norway and Finland feed simulation software engines and hydrodynamic modeling intellectual property into hardware configurations. Taiwan sources GPU accelerators and projection components that enable reduced-footprint visual systems. Single-source vulnerability concentrates in European hydrodynamic modeling licenses that inflate total ownership costs through recurring fees. Distribution runs through direct vendor relationships with maritime academies and port authorities, supplemented by channel intermediaries aggregating fleet-wide access for smaller operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined architectures are disrupting established hardware barriers, creating acceleration windows for vendors that integrate AI-driven scenario generation before regulatory procurement criteria formalize around these capabilities.
For Market Incumbents: Fortify integrated bridge system knowledge through deeper partnerships with Gulf Coast port authorities and certification investment in AI-augmented training modules. Motion platform supply bottlenecks threaten delivery timelines; securing captive supply relationships with Japanese or German base manufacturers mitigates this exposure. Cloud-based deployment models from software specialists represent the primary substitution threat requiring defensive capability builds.
For New Entrants and Emerging Players: Differentiate on GPU-accelerated physics engines that replicate vessel handling without capital-intensive motion infrastructure. Great Lakes training institutions remain the most penetrable geography given underinvestment relative to coastal clusters. A subscription-based go-to-market angle targeting inland waterway operators along the Mississippi and Ohio River systems bypasses facility ownership economics that favor incumbents.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed maritime technology conglomerates seeking portfolio rationalization around simulation software divisions. Long-term viability hinges on AI integration depth and regulatory relationship maintenance across the analysis window. The signal to watch is Transport Canada and U.S. Coast Guard procurement guideline updates that explicitly reference machine learning scenario generation as evaluation criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Scenario Generation Integration | Machine learning engines reduce instructor burden while satisfying updated STCW assessment protocols. |
| Cloud-Based Deployment Expansion | Browser-delivered interfaces unlock regional training institutions previously excluded by infrastructure costs. |
| Motion Platform Supply Securement | Captive relationships with Japanese and German manufacturers mitigate delivery bottlenecks for full-mission orders. |
| Great Lakes Geographic Expansion | St. Lawrence Seaway institutions consolidate procurement to satisfy dual Canadian-U.S. regulatory requirements. |
| Remote Proctored Certification Development | Satellite-linked simulator access enables at-sea crew credential maintenance without shore leave disruption. |
Research Methodology
Cross-validation between primary interviews with maritime training directors and secondary validation through U.S. Coast Guard regulatory filings anchors the qualitative findings. Conversations covered simulation procurement officers at Gulf Coast maritime academies, fleet training managers at container line headquarters, port authority infrastructure planners, and commercial simulator center operators. Secondary sources integrated Transport Canada marine safety directives, maritime academy capital expenditure disclosures, and customs records for motion platform import flows. Bottom-up demand aggregation from institutional procurement pipelines combined with top-down market sizing through vendor revenue triangulation.
Sensitivity analysis around regulatory implementation timelines and software adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration tier, end-user institutional category, deployment architecture, and technology integration level. CAGRs derive from installed base replacement cycles, new training institution formation rates, and fleet-wide certification mandate expansion. Hydrodynamic modeling license cost trajectories and GPU processing cost curves constitute industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained STCW compliance stringency and software-defined visualization maturity; material deviation in regulatory enforcement or hardware cost compression would warrant model refresh. Recalibration cycles align with material shifts in Coast Guard procurement guidelines and Transport Canada certification harmonization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Pilot Training Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
Global Ship Bridge Simulators Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Air Traffic Control Simulation and Training Market
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
Simulators Market
Simulation and Training
Dynamic Flight Training Compartments Market
Simulation and Training
Flight Simulator Market
Simulation and Training
North America Simulator Windows and Simulator Skylights Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
Trainer Aircraft Market
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market