
 Global Ship Bridge Simulators Market | 2026-2036
Global Ship Bridge Simulators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ship Bridge Simulators Market Foresight
Defense forces and maritime academies is bifurcating demand away from shipping companies as procurement priorities shift toward mission-critical training environments. Kongsberg Digital dominates Nordic defense contracts through in-house production of high-fidelity bridge systems. Wärtsilä extends its installed base across Southeast Asian maritime academies via localized service networks. Rheinmetall AG competes in European naval modernization programs with specialized combat bridge configurations.
Ship bridge simulators replicate vessel control rooms with functional parameters including 360-degree visual projection, integrated navigation display systems, and real-time hydrodynamic modeling for maneuvering response. Their primary commercial purpose centers on risk-free competency validation for deck officers under STCW-mandated training regimes. Full Mission installations anchor capital expenditure in defense and academy sectors where regulatory compliance demands immersive physical environments. Cloud-Based delivery is displacing on-premise deployments among mid-tier shipping operators seeking distributed crew training without dedicated simulator infrastructure.
The IMO's STCW Convention shapes product standards by mandating minimum performance criteria for approved training equipment, while the EU's MDR framework governs certification pathways for simulators deployed in European maritime education. The US Coast Guard enforces equivalent approval protocols through NVIC guidelines that determine market access for simulator manufacturers. Stakeholders must monitor convergence between physical model fidelity requirements and software-only regulatory acceptance as cloud architectures challenge traditional hardware-intensive compliance models.
Market Dynamics
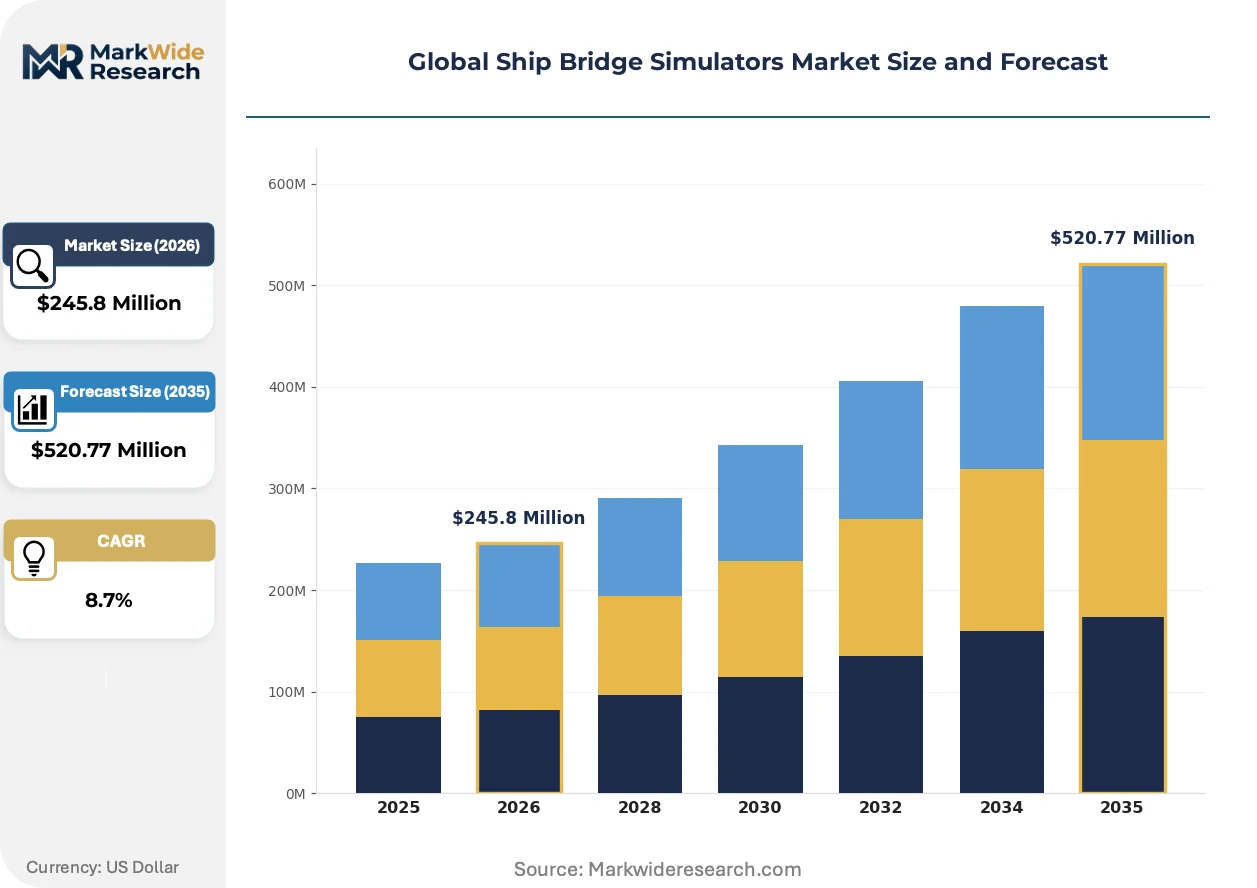
Cloud-based delivery architectures are compressing capital barriers for mid-tier shipping operators while defense and academy procurement clings to high-fidelity physical installations, splitting vendor strategies across divergent compliance and performance requirements.
Growth Catalysts
- STCW Convention Mandates:The IMO's competency-based certification framework obligates maritime academies to maintain approved training equipment, creating institutional demand for Full Mission bridge systems that satisfy performance criteria.
- Naval Modernization Programs:Defense forces in Norway, South Korea, and Singapore are accelerating simulator procurement to support fleet upgrades and mission-critical training environments for combat bridge operations.
- Hydrodynamic Modeling Advances:Real-time vessel response simulation now enables risk-free maneuvering practice in confined waterways, expanding training utility beyond open-sea scenarios.
Market Restraints
- Hardware-Intensive Compliance:The IMO's physical fidelity requirements for STCW-approved equipment preserve capital intensity, constraining adoption among smaller training institutions lacking dedicated infrastructure budgets.
- Nordic Supply Concentration:High-fidelity bridge system production clusters in Norway and Finland, exposing procurement timelines to regional manufacturing capacity constraints and specialized labor dependencies.
- Cloud Architecture Acceptance Gaps:Regulators in multiple jurisdictions maintain divergent standards for software-only training validation, fragmenting market access for distributed delivery models.
Strategic Opportunities
- Underpenetrated Maritime Clusters:Vietnam and Indonesia possess expanding commercial fleets with limited academy simulator infrastructure, presenting first-mover deployment potential for localized service networks.
- Dual-Use Naval-Commercial Configurations:Modular bridge designs that accommodate both civilian navigation and combat system training open cross-sector revenue streams from single installations.
- EU MDR Certification Pathways:The framework's harmonized approval protocols reduce regulatory friction for simulator manufacturers seeking access to European maritime education markets.
Industry Challenges
- Certified Instructor Scarcity:STCW-mandated training requires instructors holding specific simulator operation endorsements, creating bottlenecks for academy capacity expansion.
- Legacy System Integration:Maritime academies with existing simulator infrastructure face complex retrofit requirements when upgrading to current hydrodynamic engines and visual projection standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ship Bridge Simulators Market |
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $520.77 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Mission, Part Task, Desktop, Portable Technology: Virtual Reality, Augmented Reality, PC-Based, Cloud-Based, Physical Model Application: Officer Training, Safety Drills, Navigation Practice, Emergency Response, Maneuvering Skills End User: Maritime Academies, Shipping Companies, Defense Forces, Research Institutes |
| Companies Covered | Kongsberg Digital, Wärtsilä, Rheinmetall AG, FORCE Technology, ARI Simulation, VSTEP, PC Maritime, Aboa Mare, Presagis Canada Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ship Bridge Simulators Market Shifts & Advancements
Digital twin architectures and artificial intelligence are reconfiguring how vessel behavior is modeled and how training scenarios are generated, compressing the gap between simulated and actual bridge environments.
Extended reality headsets are fragmenting the visual display market for bridge simulators. These devices reduce physical footprint requirements for 360-degree situational awareness. Maritime academies in Singapore and South Korea are piloting mixed-reality installations for confined-waterway training. The technology is fragmenting demand away from projection dome suppliers toward headset manufacturers and software integrators.
The EU's MDR framework is tightening certification requirements for training equipment deployed in European maritime education. Simulator manufacturers must now demonstrate clinical-grade documentation of performance specifications. German and Dutch maritime academies are demanding MDR-aligned compliance packages, forcing vendors to restructure quality management systems.
Training-as-a-service models are emerging among mid-tier shipping operators seeking to avoid capital expenditure on dedicated simulator infrastructure. Crew training contracts now bundle cloud-based scenario access with certification tracking. Greek and Japanese shipping companies are consolidating vendor relationships around subscription-based delivery, displacing traditional equipment purchase cycles.
Global Ship Bridge Simulators Market Segmentation
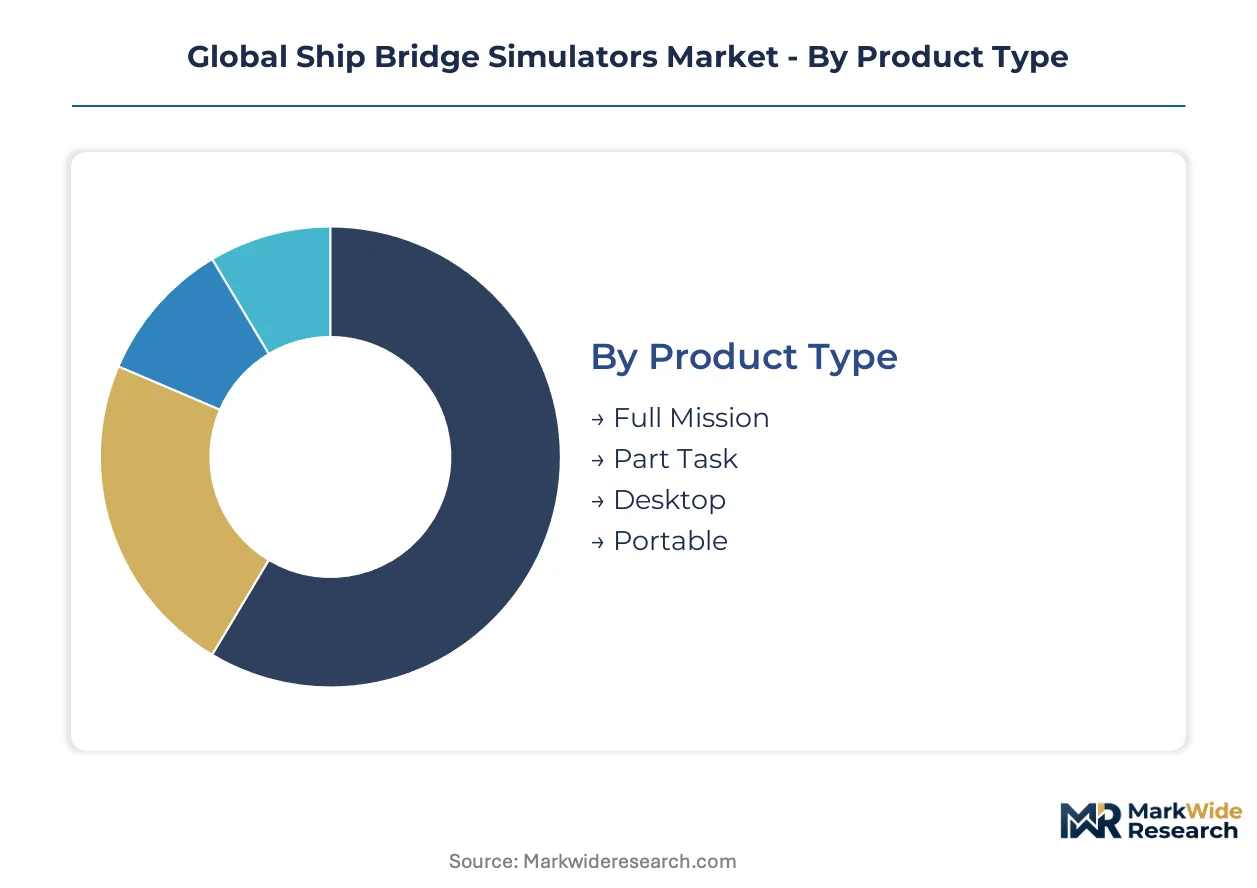
Ship bridge simulator procurement splits sharply across capital intensity thresholds and regulatory compliance tiers. Margin concentration tracks fidelity requirements and institutional approval status rather than unit volume.
Product Type:
Margin pools concentrate in installations requiring physical infrastructure and regulatory certification, while portable alternatives compete on accessibility.
- Full Mission:These installations replicate complete bridge environments with 360-degree visual projection, integrated navigation consoles, and real-time hydrodynamic feedback. Maritime academies in Norway and Singapore anchor procurement for these systems, driven by STCW Convention mandates for immersive competency validation.
- Part Task:Modular configurations isolate specific bridge functions such as radar operation or engine control for targeted skill development. Defense forces in South Korea are expanding procurement of these systems for combat bridge specialization training.
- Desktop:PC-based bridge stations deliver navigation software without physical console replication.
- Portable:Compact units deploy on vessels for underway crew certification.
The dominant share belongs to Full Mission, while Portable is closing the gap fastest.
Technology:
Adoption velocity diverges between hardware-intensive legacy architectures and software-defined delivery models reshaping mid-tier access.
- Cloud-Based:Distributed training delivery eliminates dedicated simulator infrastructure requirements through browser-accessible scenario libraries. Greek and Japanese shipping operators are consolidating procurement around these models to avoid capital expenditure on physical installations.
- Physical Model:Hardware-based systems with projection domes and physical consoles maintain institutional demand where regulatory approval requires demonstrated physical fidelity. German and Dutch maritime academies specify these configurations for STCW-compliant certification pathways.
- Virtual Reality:Headset-based immersion reduces footprint requirements for 360-degree situational awareness.
- Augmented Reality:Overlay systems blend physical bridge elements with digital scenario layers.
- PC-Based:Software-only delivery runs on standard computing hardware without specialized peripherals.
Physical Model retains institutional dominance, though Cloud-Based is expanding most quickly among commercial operators.
Application:
Training purpose determines scenario complexity requirements and contract value, with safety-critical applications commanding premium pricing.
- Officer Training:Comprehensive certification programs for deck officer licensing require progressive scenario difficulty and documented competency assessment. Maritime academies in Singapore and South Korea are scaling these programs to meet fleet expansion demands.
- Emergency Response:Crisis scenario simulation for engine failure, collision avoidance, and abandon-ship protocols demands high-stress environmental modeling. Defense forces prioritize these applications for mission-critical readiness validation.
- Safety Drills:Repetitive protocol rehearsal for fire, flooding, and man-overboard procedures.
- Navigation Practice:Route planning and collision avoidance in varied traffic densities.
- Maneuvering Skills:Berthing, unberthing, and confined waterway handling techniques.
Officer Training commands the largest contract values, while Emergency Response is gaining share fastest from naval modernization programs.
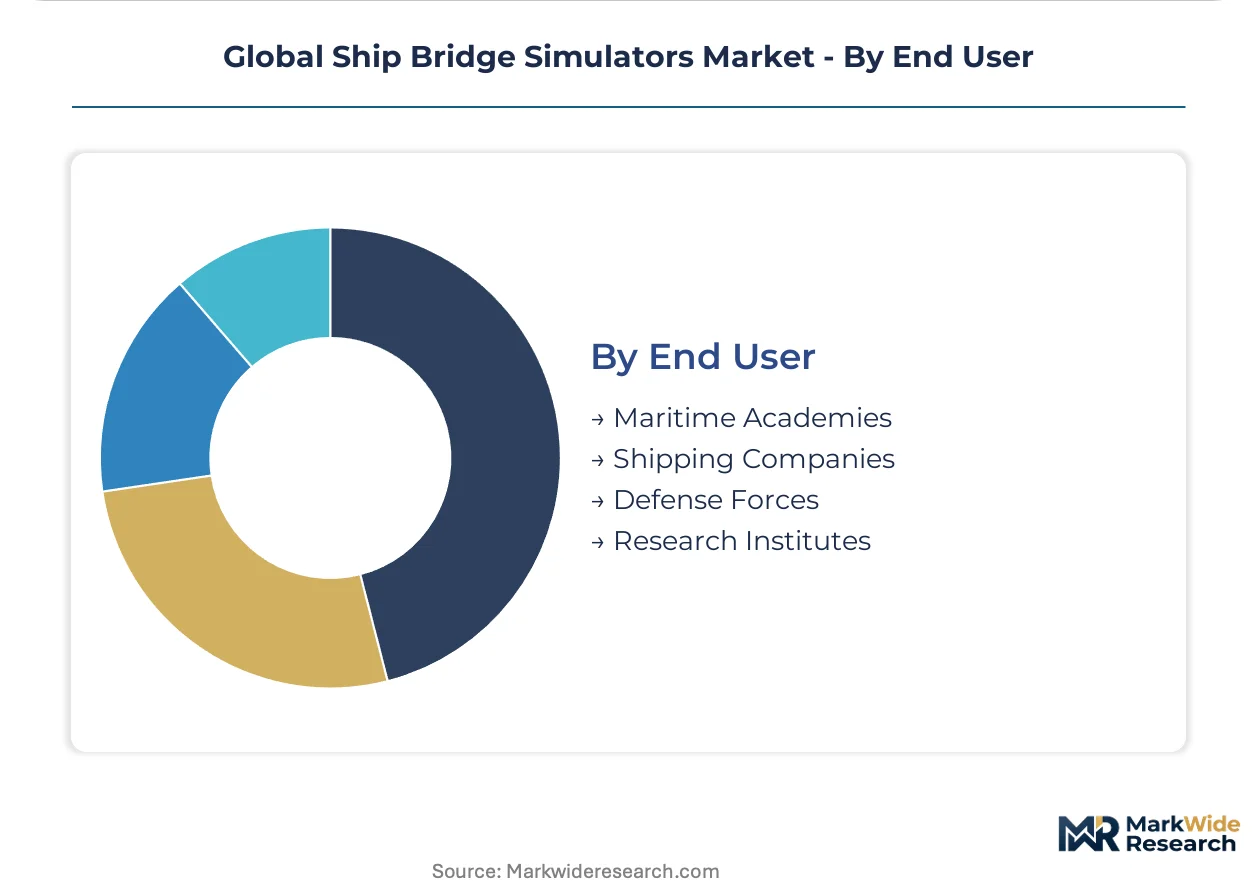
End User:
Procurement authority and budget scale fragment across institutional, commercial, and defense buyers with divergent compliance drivers.
- Maritime Academies:Accredited training institutions require STCW-approved equipment for official certification programs. Vietnam and Indonesia present deployment opportunities as commercial fleet expansion outpaces simulator infrastructure in these markets.
- Defense Forces:Naval modernization programs in Norway, South Korea, and Singapore are accelerating procurement for combat bridge training and fleet upgrade support.
- Shipping Companies:Commercial fleet operators invest in crew competency maintenance and insurance risk reduction.
- Research Institutes:Academic and government research facilities utilize simulators for human factors studies and navigation system development.
Maritime Academies anchor equipment demand, while Defense Forces are climbing the fastest on naval investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated vessel traffic management system anchors European demand for advanced bridge training infrastructure. Maritime academies along the Rhine corridor integrate simulator networks with live port data feeds. This physical-digital convergence shapes procurement specifications across the continent.
Norway
Naval modernization programs and offshore fleet expansion drive simulator procurement in Norwegian maritime clusters. The Norwegian Maritime Authority enforces STCW compliance through rigorous equipment certification protocols. Kongsberg's production facilities near Horten anchor Nordic supply chains for high-fidelity bridge systems.
Singapore
The Maritime and Port Authority's training subsidies accelerate academy infrastructure upgrades across the city-state. Tuas Port development demands specialized maneuvering simulation for ultra-large container vessel handling. MaritimeONE career initiatives channel public investment into simulation-based officer certification pathways.
South Korea
Naval fleet modernization and commercial shipbuilding dominance create dual demand streams for combat and civilian bridge training. The Korea Maritime Institute coordinates simulator standards with IMO guidelines. Busan maritime universities cluster procurement for integrated navigation training networks.
Germany
The EU MDR framework governs simulator certification for maritime academies in Hamburg and Bremen. German shipowners' liability insurance requirements mandate documented bridge crew competency validation. The Elbe River corridor concentrates training infrastructure near major container terminal operations.
United States
The US Coast Guard's NVIC guidelines determine market access for simulator manufacturers serving domestic maritime education. Great Lakes shipping operators invest in ice navigation simulation for seasonal route certification. Massachusetts Maritime Academy anchors federal procurement for full-mission bridge installations.
Global Ship Bridge Simulators Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity thresholds, fragmenting competitive dynamics by customer segment. Maritime academies and defense forces prioritize established vendors with regulatory approval track records, while commercial operators weigh subscription economics against ownership models. Three archetypes dominate: integrated maritime technology conglomerates, defense-focused simulation specialists, and software-native training platform vendors. Consolidation activity concentrates in Nordic manufacturing assets, while partnership strategies target cloud delivery scale in Asian commercial shipping markets.
Among Nordic-based system integrators, Kongsberg Digital and Wärtsilä occupy positions representing the integrated technology archetype, anchoring premium-tier procurement through in-house production capabilities. Rheinmetall AG exemplifies the defense-specialist positioning, serving naval modernization programs with mission-critical training configurations. These three entities collectively represent the capital-intensive segment where regulatory compliance and physical fidelity requirements sustain hardware-centric competitive moats.
| Leading Market Players |
|---|
| Kongsberg Digital |
| Wärtsilä |
| Rheinmetall AG |
| FORCE Technology |
| ARI Simulation |
| VSTEP |
| PC Maritime |
| Aboa Mare |
| Presagis Canada Inc. |
| Others |
Supply & Pricing Matrix
STCW Convention certification requirements gate both supplier qualification and price differentiation, forcing vendors to absorb compliance documentation costs while maritime academies pay premiums for approved equipment tiers.
Pricing Analysis
Volume-discount tiering structures separate Full Mission installations from Cloud-Based subscriptions, with pricing stratifying across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in mid-tier shipping operator segments is intensifying because subscription models displace capital purchases. Maritime academies exhibit least price sensitivity due to regulatory mandate adherence, while Greek and Japanese shipping companies drive hardest bargain negotiations.
Supply Chain Analysis
Strait of Malacca transit routes underwrite component logistics for Southeast Asian assembly, yet Nordic manufacturing clusters in Norway and Finland anchor high-fidelity system production. Production draws from specialized optical projection hardware, hydrodynamic modeling software licenses, and marine-grade console fabrication. Single-source vulnerability concentrates in precision motion platform suppliers. Distribution runs through direct defense procurement channels and maritime academy tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward maritime academies as STCW mandate consolidation concentrates procurement authority among accredited institutions, fragmenting vendor negotiation leverage across fewer high-volume customers.
For Market Incumbents: Secure regulatory approval moats through accelerated EU MDR documentation investments before harmonized standards harden. Deepen in-house production of hydrodynamic engines to offset substitute pressure from cloud-native entrants. Channel control over certified instructor training networks remains critical for academy retention. For New Entrants and Emerging Players: Lead with portable and Cloud-Based configurations targeting Vietnamese and Indonesian maritime academies where simulator infrastructure lags fleet expansion. White-space concentration sits in mixed-reality headset integration for confined-waterway training. Go-to-market through localized service partnerships bypasses Nordic incumbents' direct sales dominance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across Cloud-Based delivery sub-segments, compressing traditional hardware margin structures. Long-term viability favors software-native platforms with recurring revenue architectures over projection-dome manufacturers. Acquisition target archetype: regional simulation specialists with STCW approval track records in underpenetrated Asian markets. Signal to watch: IMO guidance evolution on software-only training validation acceptance.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Migration | Greek and Japanese operators consolidate procurement around subscription delivery models. |
| MDR Certification Investment | German and Dutch academies demand clinical-grade documentation forcing vendor quality restructuring. |
| Mixed-Reality Pilot Deployment | Singapore and South Korean academies test headset-based confined-waterway training scenarios. |
| Dual-Use Modular Design | Norwegian and South Korean defense programs open cross-sector revenue from single installations. |
| Localized Service Network Expansion | Vietnam and Indonesia infrastructure gaps present first-mover academy deployment opportunities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of IMO regulatory filings, EU MDR certification databases, and national maritime authority procurement records. Primary interviews engaged simulator manufacturer product directors, maritime academy training officers, and defense procurement officials across Norway, Singapore, and South Korea. Secondary validation incorporated customs trade data for simulation hardware imports, SEC disclosures from listed maritime technology conglomerates, and STCW equipment approval registries. Bottom-up academy installation counts triangulate against top-down defense budget allocations.
Segmentation dimensions modeled span product type, technology architecture, training application, and end-user category across the analysis window. CAGRs derive from installed base expansion rates, replacement cycle timing, and subscription conversion velocity in commercial shipping segments. Hydrodynamic engine upgrade frequencies and visual projection technology refresh timelines inform hardware revenue forecasting. Cloud-Based penetration curves incorporate bandwidth infrastructure readiness indices by country.
The analysis sits within stated boundaries; outcomes outside sustained naval modernization commitments and IMO regulatory stability would require recalibration. Forecasts reflect assumptions on STCW compliance continuity and cloud architecture acceptance trajectory. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and Asia-Pacific fleet expansion rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Flight Simulation Training Device Market
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Civil Aerospace Simulation and Training Market
Simulation and Training
Pilot Training Market
Simulation and Training
Trainer Aircraft Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
RADAR Simulator Market
Simulation and Training
Global Healthcare Games and Simulation Market
Simulation and Training
Military Simulation and Training Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
Flight Simulator Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
Air Traffic Control Simulator and Training Market
Simulation and Training
Dynamic Flight Training Compartments Market