
 North America Mobile Satellite Services Market | 2026-2036
North America Mobile Satellite Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mobile Satellite Services Market Analytics
The FCC's streamlined small satellite licensing framework is expanding market access for next-generation constellation operators. Iridium Communications Inc. leverages its completed NEXT constellation replacement to sustain full global coverage including polar regions. Viasat Inc. competes through high-throughput Ka-band capacity aimed at government and mobility segments. Globalstar Inc. anchors its position with specialized IoT and personal messaging services across remote North American territories.
Mobile satellite services deliver voice, data, and tracking connectivity via orbiting spacecraft to terminals beyond terrestrial network reach, operating across L-band, S-band, and Ka-band frequencies with orbital altitudes ranging from 600 km to 35,786 km depending on architecture. Low Earth Orbit technology leads deployment velocity due to reduced latency profiles demanded by real-time applications, while Geostationary systems retain margin concentration in broadcast and broadband trunking where fixed coverage patterns reduce ground infrastructure costs. Direct-to-Device service types are attracting capital as smartphone-integrated satellite messaging eliminates dedicated terminal requirements for consumer adoption.
The FCC governs spectrum allocation and orbital slot coordination across United States jurisdictions, while Industry Canada and the Secretariat of Infrastructure, Communications and Transportation in Mexico administer parallel national frameworks that operators must navigate for cross-border service continuity. FCC Part 25 licensing mandates shape terminal certification and interference standards that directly determine market entry timelines for new constellation providers. Stakeholders must monitor evolving spectrum sharing rules between terrestrial 5G and satellite operations as these decisions will reshape capacity economics and service reliability commitments across the region.
Market Dynamics
The FCC's accelerated licensing timelines for non-geostationary orbit systems are compressing constellation deployment cycles and reshaping competitive entry barriers across the North American market.
Growth Catalysts
- Emergency Response Mandates:Federal and state-level disaster preparedness protocols now require redundant satellite communications for first responder coordination across Alaska, Puerto Rico, and Gulf Coast hurricane corridors.
- Offshore Energy Expansion:Deepwater drilling operations in the Gulf of Mexico demand real-time telemetry and crew welfare connectivity beyond cellular range.
- 5G Spectrum Coexistence Rules:FCC Part 25 licensing frameworks are enabling dynamic spectrum sharing that expands satellite operator access to previously restricted frequency blocks.
Market Restraints
- Launch Capacity Bottlenecks:Limited heavy-lift vehicle availability from domestic and international launch providers constrains constellation refresh timelines.
- Terminal Cost Structure:Specialized L-band and Ka-band transceiver hardware remains prohibitively expensive for mass consumer adoption outside subsidized government programs.
- Polar Orbital Slot Scarcity:ITU coordination delays for high-inclination orbits restrict coverage expansion in Arctic territories where demand concentrates.
Strategic Opportunities
- Direct-to-Device Convergence:Smartphone-native satellite messaging eliminates dedicated hardware requirements and opens consumer volume segments previously unreachable.
- Mexico Rural Connectivity:The Secretariat of Infrastructure's universal service obligations create procurement channels for cross-border service providers targeting underserved agricultural and mining zones.
- IoT-Tracking Hybrid Services:Integration of narrowband data with precision location services addresses untapped demand in remote asset monitoring for pipeline and utility infrastructure.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized expertise in satellite-ground interference mitigation and antenna design commands premium compensation and extends hiring timelines.
- Multi-Orbit Integration Complexity:Operators blending geostationary and low Earth orbit architectures face substantial software-defined networking investments to maintain seamless handoffs.
- Type Certification Backlogs:FCC equipment authorization queues for novel terminal form factors delay revenue recognition by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mobile Satellite Services Market |
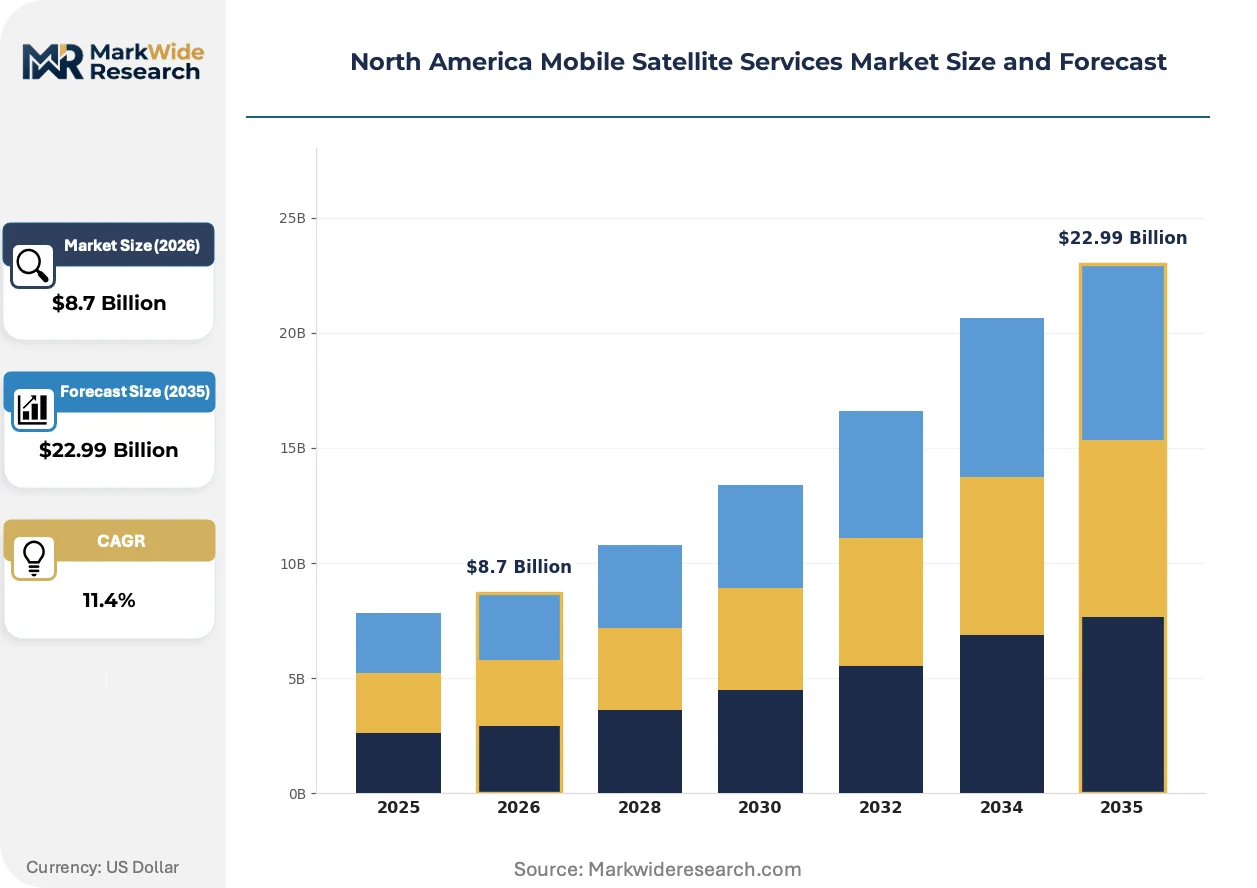
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Direct-to-Device, Forward Link, Interactive Services, Location-Based Services End User: Aerospace, Maritime, Emergency Services, Oil & Gas Technology: Geostationary, Low Earth Orbit, Medium Earth Orbit, Hybrid Systems Application: Telecommunication, Broadcasting, Internet Access, Remote Monitoring |
| Companies Covered | Iridium Communications Inc., Globalstar Inc., Inmarsat PLC, Intelsat S.A, Viasat Inc, SES S.A., Telesat Corporation, EchoStar Corporation, ORBCOMM Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mobile Satellite Services Market Evolving Landscape
Orbital architecture diversification and terminal miniaturization are compressing service delivery economics while regulatory frameworks race to accommodate hybrid space-terrestrial networks.
Software-defined payload technology is integrating digital beam-forming capabilities that allow single satellites to reconfigure coverage patterns in real time. Defense agencies and maritime operators are adopting these flexible capacity models fastest. This adaptability is integrating dynamic service allocation that matches supply to geographically shifting demand spikes.
FCC streamlined small satellite licensing is collapsing authorization timelines from twenty-four months to under six months for qualified operators. This regulatory compression is accelerating constellation refresh rates and lowering capital lockup periods. Alaska and Arctic operators are responding most aggressively, filing coordinated applications for polar coverage expansion.
Enterprise buyers are consolidating vendor relationships around multi-service contracts that bundle voice, data, and IoT tracking under single procurement frameworks. Traditional single-service resellers are losing position to integrated platform providers. This consolidation pattern is most visible across United States federal contracting and Canadian provincial emergency management agencies.
North America Mobile Satellite Services Market Segmentation
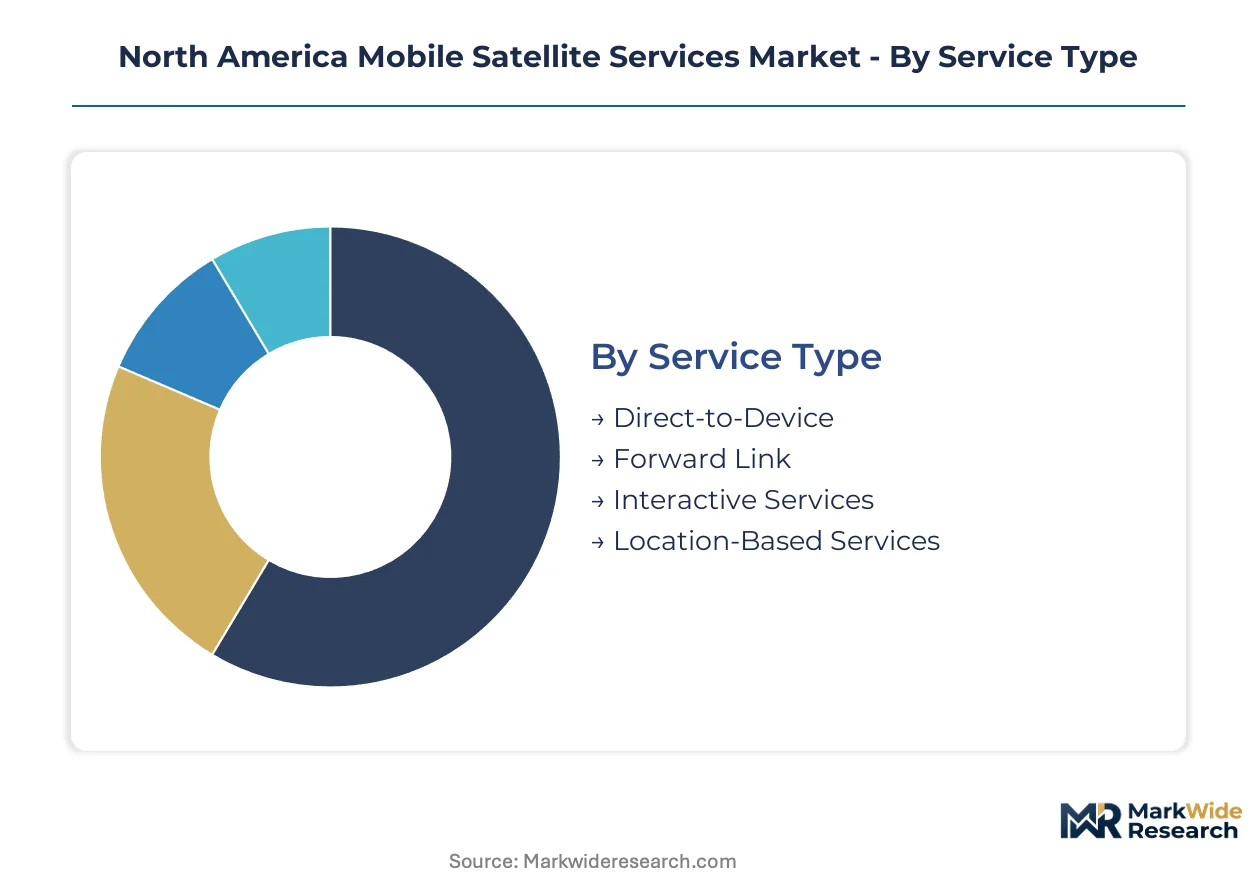
Mobile satellite services fragment across service delivery modes, orbital architectures, and vertical applications that each impose distinct latency, bandwidth, and terminal requirements. Procurement patterns diverge sharply between government buyers prioritizing coverage reliability and commercial operators optimizing throughput economics.
Service Type:
Buyer selection hinges on whether existing terrestrial infrastructure can be leveraged or bypassed entirely.
- Direct-to-Device:Smartphone-native connectivity eliminates dedicated terminal procurement, collapsing adoption barriers for consumer and prosumer segments. FCC streamlined licensing accelerates carrier partnerships with constellation operators across Alaska and Gulf Coast corridors where cellular dead zones persist.
- Forward Link:One-way broadcast distribution of content and software updates to passive receivers serves maritime entertainment and aeronautical information services. Demand concentrates in cruise line fleet modernization programs and commercial aviation retrofit cycles.
- Interactive Services:Two-way data exchange enabling voice, messaging, and transactional applications.
- Location-Based Services:Precision positioning and tracking layered with narrowband data transmission.
Direct-to-Device leads on scale; Forward Link leads on momentum.
End User:
Vertical specialization determines antenna specifications, service level agreements, and regulatory compliance burdens.
- Emergency Services:First responder agencies mandate redundant satellite pathways for disaster coordination where terrestrial networks fail. FEMA procurement protocols and state-level mutual aid compacts in hurricane-prone states drive multi-year contract structures with 99.9% availability guarantees.
- Oil & Gas:Offshore platforms and remote pipeline infrastructure require continuous telemetry and crew welfare connectivity. Deepwater Gulf of Mexico operations generate sustained demand for high-throughput links supporting real-time drilling analytics.
- Aerospace:Commercial and military aviation connectivity for cockpit communications and passenger broadband.
- Maritime:Merchant vessels, fishing fleets, and recreational craft operating beyond coastal cellular range.
Emergency Services commands premium pricing; Oil & Gas delivers volume concentration.
Technology:
Orbital altitude selection trades latency performance against coverage economics and ground infrastructure requirements.
- Low Earth Orbit:Constellations at 600-1,200 km altitude deliver sub-50 millisecond latency enabling real-time voice and interactive data. FCC accelerated licensing timelines compress deployment cycles for new entrants targeting polar coverage gaps in Alaska and Arctic territories.
- Geostationary:Fixed-position satellites at 35,786 km provide continuous regional coverage with minimal ground tracking infrastructure. Broadcast and broadband trunking applications favor this architecture where latency tolerance permits cost-optimized terminal designs.
- Medium Earth Orbit:Intermediate altitude systems balancing coverage footprint with latency reduction.
- Hybrid Systems:Multi-orbit architectures combining LEO responsiveness with GEO capacity density.
Geostationary retains installed base dominance; Low Earth Orbit captures deployment velocity.
Application:
Use case segmentation reflects whether connectivity serves human communication, content distribution, or machine telemetry.
- Internet Access:Broadband data delivery to unserved and underserved regions beyond fiber and cellular buildouts. Rural Alaska communities and Mexican agricultural zones drive subscriber growth for fixed and portable terminal services.
- Remote Monitoring:Machine-to-machine data collection from infrastructure assets requiring minimal bandwidth but continuous availability. Pipeline operators across Permian Basin and Alberta oil sands deploy narrowband links for pressure, flow, and integrity telemetry.
- Telecommunication:Voice and messaging services for individual and enterprise subscribers.
- Broadcasting:Content distribution to terrestrial rebroadcast stations and direct-to-home receivers.
Internet Access spans the broadest addressable market; Remote Monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile satellite services trace their commercial origins to early maritime distress systems developed in the United States during the 1970s, with subsequent constellation deployments scaling across North American territories before global expansion.
United States
Defense procurement and emergency response mandates drive demand concentration across Alaska's remote communities and the Gulf of Mexico offshore energy corridor. FCC Part 25 licensing frameworks govern spectrum allocation and terminal certification standards. Houston anchors oil and gas sector connectivity procurement, while Anchorage serves as the operational hub for polar coverage expansion.
Canada
Arctic sovereignty operations and northern indigenous community connectivity requirements sustain government satellite service contracts. Industry Canada administers parallel national spectrum frameworks that operators must navigate for cross-border continuity. Alberta's oil sands region generates concentrated demand for remote asset monitoring and pipeline telemetry services.
Mexico
Rural agricultural zones and mining operations in remote territories create procurement channels for universal service obligations. The Secretariat of Infrastructure, Communications and Transportation oversees licensing for cross-border service continuity. Northern border states and the Yucatán Peninsula concentrate demand for maritime and terrestrial connectivity beyond cellular infrastructure.
North America Mobile Satellite Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across spectrum access and orbital slot positioning, with constellation completeness determining pricing power in government and mobility segments. The vendor base organizes around three strategic archetypes: established constellation operators with completed infrastructure refresh cycles, legacy geostationary providers defending broadcast and trunking positions, and emerging direct-to-device specialists leveraging smartphone integration. Dominant competitive moves include multi-orbit architecture investments and strategic partnerships with terrestrial carriers for spectrum coexistence arrangements.
Within the established constellation tier, Iridium Communications Inc. and Globalstar Inc. occupy positions reflecting divergent strategic specializations, with the former exemplifying completed infrastructure replacement and the latter representing narrowband IoT and personal messaging focus. Viasat Inc. anchors the high-throughput Ka-band segment targeting government and mobility applications. These three entities collectively illustrate the competitive spectrum from polar coverage specialists to capacity-intensive broadband providers.
| Leading Market Players |
|---|
| Iridium Communications Inc. |
| Globalstar Inc. |
| Inmarsat PLC |
| Intelsat S.A |
| Viasat Inc |
| SES S.A. |
| Telesat Corporation |
| EchoStar Corporation |
| ORBCOMM Inc. |
| Others |
Value Network & Pricing Analysis
Launch vehicle capacity indices and satellite component commodity benchmarks cascade through North American mobile satellite services supply chains, compressing margins at the constellation deployment tier while concentrating pricing power among operators with secured orbital slots and completed infrastructure refresh cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the North American market by service reliability commitments and terminal sophistication. Premium tiers command substantial markups through MIL-STD-188 certification and polar coverage guarantees demanded by Alaska emergency responders and Gulf of Mexico offshore operators. Cost compression in the economy tier intensifies as direct-to-device smartphone integration eliminates dedicated hardware procurement. Government agencies exhibit the lowest price sensitivity due to mandated redundancy requirements, while agricultural IoT subscribers in Mexico's rural zones drive the most aggressive procurement negotiations.
Supply Chain Analysis
Terminal refurbishment and legacy satellite component remanufacturing flows extend equipment lifecycles for L-band transceiver hardware deployed across remote Alaskan communities. Manufacturing concentration rests on the United States, France, and Japan for specialized antenna subsystems and radiation-hardened electronics. Supply chains draw from gallium arsenide substrates, precision RF filters, and cryogenic propulsion units. Single-source vulnerability around heavy-lift launch manifests poses structural risk for constellation refresh timelines. Distribution runs through authorized service providers and direct government contracting channels rather than retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American mobile satellite services market functions as a regulatory compounder where FCC Part 25 licensing acceleration and streamlined small satellite frameworks directly expand addressable demand across emergency response and offshore energy verticals.
For Market Incumbents: Acquire polar orbital slot portfolios and ITU-coordinated frequency filings to defend coverage exclusivity in Alaska and Arctic territories. Consolidate around multi-orbit software-defined networking capabilities that neutralize emerging LEO constellation threats. Lock in long-term spectrum coexistence agreements with terrestrial 5G operators to secure interference-protected capacity economics. For New Entrants and Emerging Players: Smartphone-native direct-to-device technology offers the most penetrable wedge for bypassing dedicated terminal cost barriers and accessing consumer volume segments. Target Mexico's rural agricultural zones and northern mining corridors where universal service obligations create subsidized procurement channels. Pursue carrier partnership go-to-market models that leverage existing cellular retail footprints rather than building parallel distribution infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid architecture specialists combining LEO latency responsiveness with GEO capacity density for government and mobility applications. Five-to-ten year viability hinges on spectrum access durability rather than terminal technology differentiation. Monitor FCC equipment authorization queue lengths as the lead indicator for revenue recognition timing compression across the competitive set.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Architecture Integration | Software-defined handoffs between LEO and GEO layers enable seamless service continuity for maritime and aviation mobility segments. |
| Spectrum Coexistence Partnership | FCC Part 25 dynamic sharing agreements with terrestrial 5G carriers expand satellite operator access to previously restricted frequency blocks. |
| Polar Coverage Expansion Filing | ITU-coordinated high-inclination orbital slots secure exclusive Arctic territory access for Alaska emergency response and sovereignty operations. |
| Direct-to-Device Carrier Integration | Smartphone-native satellite messaging eliminates dedicated terminal procurement and collapses consumer adoption barriers across cellular dead zones. |
| IoT-Tracking Hybrid Service Launch | Narrowband data layered with precision positioning addresses untapped pipeline and utility infrastructure monitoring demand across Permian Basin and Alberta oil sands. |
Research Methodology
Bottom-up emergency services and oil and gas operator modeling reconciled against top-down constellation capacity and launch manifest tracking forms the analytical core of this study. Primary interviews with satellite procurement officers at federal agencies, state emergency management directors, offshore platform telecommunications managers, and rural connectivity program administrators were validated against secondary sources including FCC licensing databases, Industry Canada spectrum filings, SEC 10-K disclosures from publicly traded operators, and ITU satellite network coordination records. Triangulation between demand-side contract values and supply-side orbital slot filings ensures cross-verified market sizing.
Input-output matrices map service type, orbital architecture, and vertical application dimensions across the projection horizon. Modeled segmentation spans direct-to-device, forward link, interactive services, and location-based service types; LEO, GEO, MEO, and hybrid technology tiers; and emergency services, oil and gas, aerospace, and maritime end-use verticals. CAGRs were derived from deployment velocity curves weighted by regulatory approval timelines and launch capacity constraints. Forecast inputs incorporate FCC licensing acceleration effects and polar coverage gap closure trajectories.
The model holds under sustained regulatory streamlining and launch provider capacity expansion; deviation in ITU coordination delays or spectrum reallocation rulings would shift constellation deployment timelines and revenue recognition patterns. Practitioners should monitor FCC equipment authorization queue lengths and heavy-lift vehicle manifest availability for early signals of supply-side constraint intensification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Compass Market
Satellite
Satellite Launch Vehicle (SLV) Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
Satellite Antenna Market
Satellite
Satellite Operation Service Market
Satellite
Small Satellite Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Middle East Satellite Communications Market
Satellite
Tactical Satellite Market
Satellite
UK Satellite Imagery Services Market
Satellite
Military Satellite Market
Satellite
Asia-Pacific Remote Sensing Satellites Market
Satellite
Nanosatellite Market
Satellite
North America Remote Sensing Satellites Market