
 Europe Flight Training and Simulation Market | 2026-2036
Europe Flight Training and Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flight Training and Simulation Market Foresight
The EU Green Deal's aviation decarbonization targets are realigning training priorities toward fuel-efficient flight operations and next-generation aircraft handling. CAE Inc. leverages its extensive European training center network to sustain market presence across commercial and military segments. Thales anchors its position through integrated simulator hardware and software development. L3Harris Technologies Inc. competes on military training specialization across NATO member states.
Flight training and simulation encompasses synthetic training devices that replicate aircraft flight dynamics, cockpit environments, and emergency scenarios through motion platforms, visual systems, and computational aerodynamic models with fidelity levels certified by aviation authorities for pilot type ratings and recurrent qualification. Full Flight Simulator systems dominate capital expenditure pools due to Level D certification requirements for zero-flight-time training conversions. Virtual Reality segments show accelerated adoption in ab initio pilot programs where cost barriers limit access to full-motion platforms. Military Training end users maintain distinct procurement channels with classified performance specifications and sovereign security requirements.
EASA pilot training regulations, EU AI Act provisions for automated training systems, and national military procurement standards from Germany's BAAINBw and France's DGA collectively shape product certification pathways and market access conditions. The CSRD sustainability reporting mandate further pressures training providers to document simulator energy efficiency and lifecycle environmental impact. Stakeholders must monitor regulatory divergence between EASA harmonization efforts and emerging national cybersecurity requirements for connected training infrastructure.
Market Dynamics
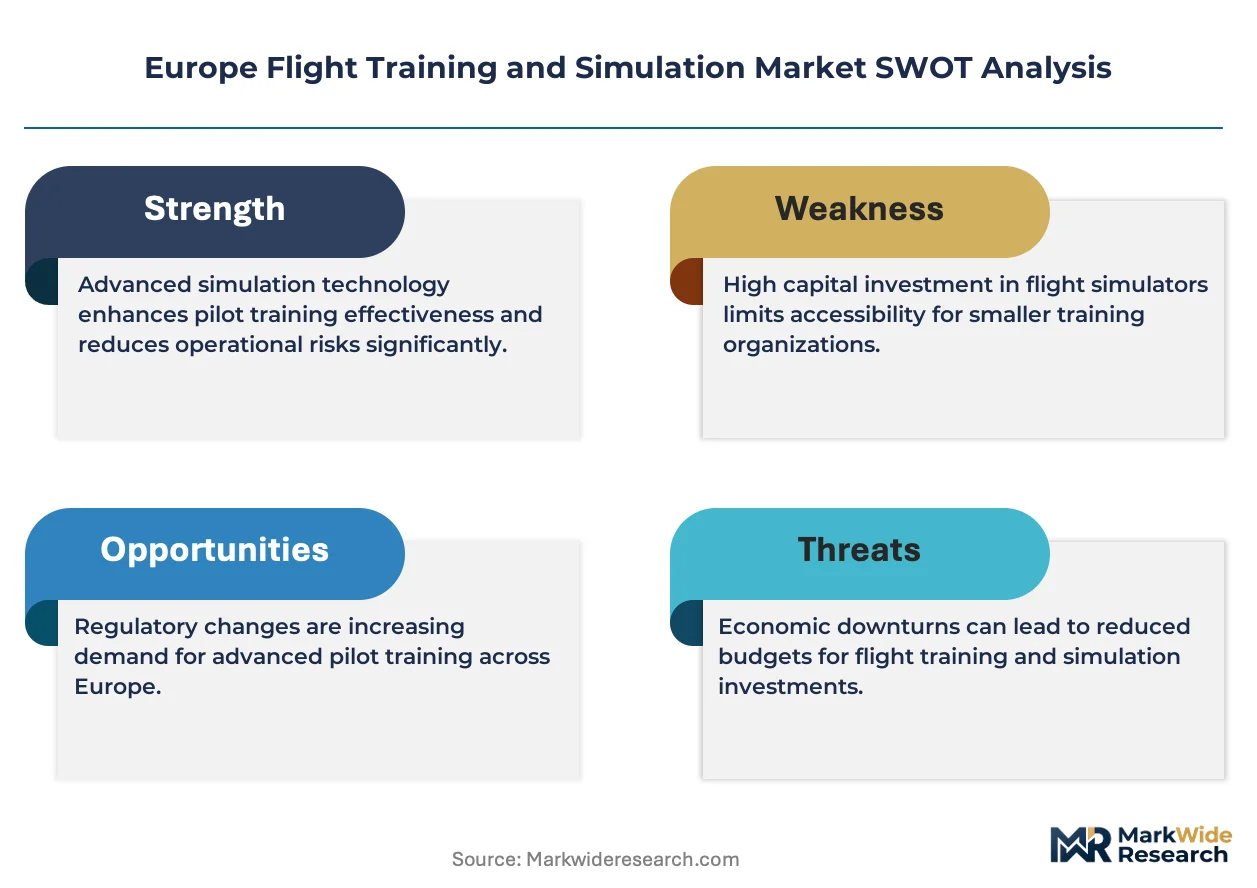
EASA's zero-flight-time training mandate for type rating conversions is compressing simulator deployment timelines across European training centers. This regulatory compression is forcing capital allocation decisions that favor Level D Full Flight Simulators over lower-fidelity alternatives, reshaping procurement patterns among major airline operators and independent training providers.
Growth Catalysts
- EU Green Deal aviation decarbonization targets:Airlines are reorienting recurrent training curricula toward fuel-efficient flight operations and sustainable aviation fuel handling protocols. This policy pressure is expanding simulator utilization for next-generation aircraft transition programs.
- Commercial airline fleet renewal cycles:Legacy narrowbody retirements and twin-aisle deliveries are generating type rating demand that outstocks available training capacity. Major carriers are securing long-term simulator access agreements to lock in pilot pipeline throughput.
- Extended Reality convergence:Mixed Reality headsets are penetrating ab initio training programs where full-motion platform economics prove prohibitive. Flight schools in Germany and France are piloting VR-first curricula for instrument procedure familiarization.
Market Restraints
- Motion platform component supply concentration:Hydraulic actuator and electric motion base manufacturing clusters in Germany and the United States create single-source vulnerability for European simulator integrators. Supply lead times now extend 18-24 months for critical subsystems.
- Visual system computational hardware cost volatility:GPU and image generator procurement costs fluctuate with semiconductor foundry capacity allocation. Training center operators face margin compression when refresh cycles coincide with component price spikes.
- EASA CS-FSTD certification timeline rigidity:Qualification test guide validation and recurrent evaluation intervals impose fixed compliance costs regardless of utilization rates. Smaller training providers struggle to amortize certification overhead across limited simulator hours.
Strategic Opportunities
- Central and Eastern European training hub development:Poland and Hungary offer cost-competitive real estate and technical labor pools for greenfield simulator centers. EU cohesion funding streams are subsidizing aviation infrastructure investments in these accession states.
- EU AI Act automated training system provisions:Regulatory clarity on machine learning-assisted instruction is opening product development pathways for adaptive learning platforms. Simulator manufacturers can now embed intelligent tutoring systems with defined compliance guardrails.
- Cross-domain military-civilian training convergence:NATO interoperability requirements are creating demand for multi-platform simulation environments that span transport, tanker, and rotary-wing configurations. Dual-use facilities in the United Kingdom and Germany capture defense and commercial revenue streams.
Industry Challenges
- Certified instructor pilot scarcity:EASA Flight Simulation Training Device instructor qualification requirements are tightening as experienced airline pilots prioritize line flying over training center assignments. Training providers are competing for a shrinking pool of examiner-rated personnel.
- Legacy simulator data package obsolescence:Aircraft OEM proprietary aerodynamic models and avionics software configurations require continuous update subscriptions. Operators of older simulator platforms face escalating license fees or platform replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flight Training and Simulation Market |
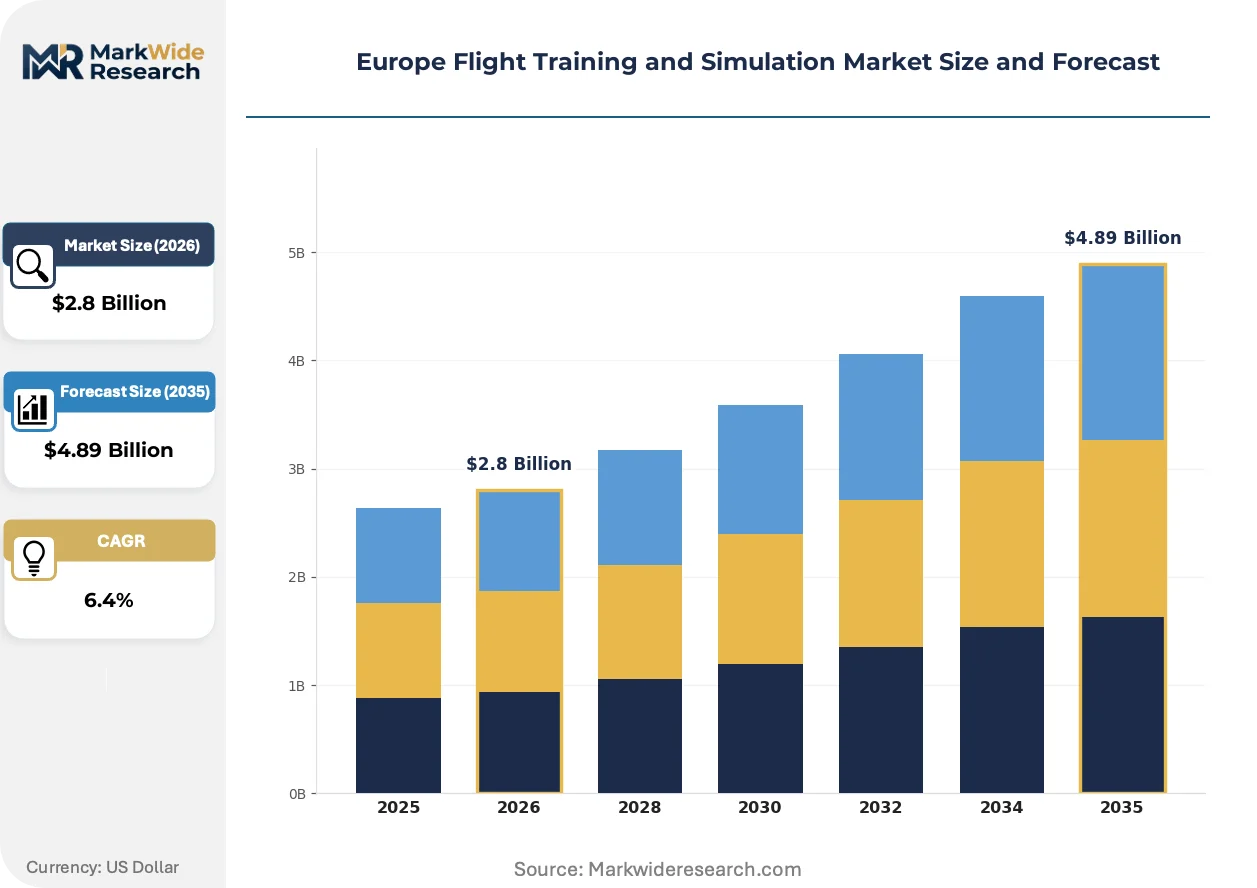
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Training Type: Pilot Training, Crew Resource Management, Simulator Training, Flight Operations Simulation Technology: Fixed Base Simulator, Full Flight Simulator, Virtual Reality, Augmented Reality End User: Commercial Airlines, Military Training, Private Aviation, Flight Schools Service Type: Course Development, Consulting Services, Training Delivery, Maintenance Services |
| Companies Covered | Thales, TRU Simulation + Training Inc., CAE Inc., ELITE Simulation Solutions AG, RTX Corporation, FlightSafety International, The Boeing Company, Multi Pilot Simulations BV, L3Harris Technologies Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flight Training and Simulation Market Shifts & Advancements
Computational architectures and regulatory frameworks are converging to redefine fidelity boundaries and training economics. Synthetic environments are absorbing functions previously requiring physical aircraft exposure, while sustainability mandates are reshaping infrastructure investment criteria across the European training landscape.
Cloud-based image generation is modularizing visual system deployment for Full Flight Simulators. Airlines with distributed training networks are adopting streaming render farms that centralize computational load while reducing per-site hardware footprints. This architecture is compressing capital requirements for secondary training locations and enabling rapid fleet type additions without complete platform replacement.
CSRD sustainability reporting mandates are imposing documentation requirements on training center energy consumption and equipment lifecycle impact. EASA is aligning certification processes with environmental disclosure standards, requiring simulator manufacturers to provide carbon footprint data alongside technical specifications. German and French training providers are responding by procuring energy-efficient electric motion systems and renewable power purchase agreements.
Airline procurement departments are unbundling simulator access from integrated training service contracts. Major carriers are negotiating direct platform leases or joint venture structures with independent training centers, displacing traditional bundled type rating packages. This fragmentation is most pronounced in the United Kingdom, where British Airways and easyJet have established captive training subsidiaries with open third-party enrollment.
Europe Flight Training and Simulation Market Segmentation
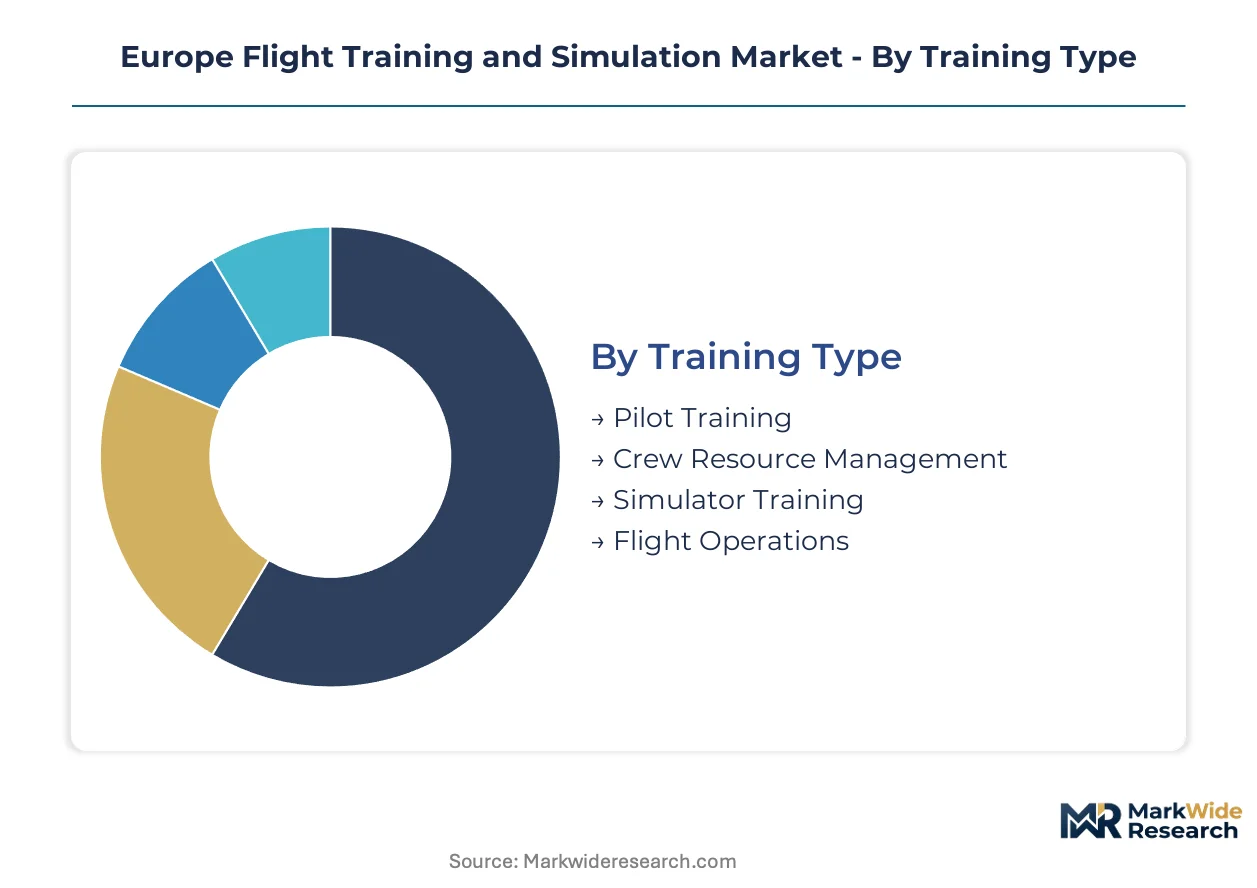
Segmentation reveals how capital flows diverge across training modalities and customer types in European aviation. Procurement patterns vary sharply between military sovereign requirements and commercial airline efficiency mandates.
Training Type:
Upgrade cycles for EASA certification compliance are reshaping curriculum investment priorities across European training centers.
- Pilot Training:Encompasses ab initio instruction through type rating certification for commercial, military, and private operator pathways. German and French carriers are expanding in-house programs to secure pipeline throughput amid instructor scarcity.
- Simulator Training:Device-based instruction for recurrent qualification, type conversion, and zero-flight-time certifications under EASA mandates. Demand concentrates at Level D Full Flight Simulator centers in the United Kingdom and Germany where airline headquarters cluster.
- Crew Resource Management:Team coordination and decision-making protocols for multi-crew flight deck operations. Integration with Extended Reality platforms is reducing reliance on physical simulator hours for initial CRM familiarization.
- Flight Operations:Dispatch, fuel planning, and route optimization training aligned with EU Green Deal decarbonization targets. Airlines in France are embedding sustainable aviation fuel handling modules into recurrent curricula.
Simulator Training sits at the top of the volume ranking, with Pilot Training climbing the fastest.
Simulation Technology:
Cost tier differentiation separates capital-intensive motion platforms from emerging software-defined alternatives.
- Full Flight Simulator:Level D certified systems with six-degree-of-freedom motion platforms and collimated visual displays for zero-flight-time training. EASA's regulatory compression on type rating timelines is extending order backlogs for CAE and Thales production lines.
- Virtual Reality:Headset-based immersive environments for procedural familiarization and emergency scenario rehearsal. Flight schools in Germany are piloting VR-first ab initio curricula where full-motion economics prove prohibitive.
- Fixed Base Simulator:Non-motion devices for instrument procedure training and cockpit systems familiarization. Polish and Hungarian training hubs are deploying these for cost-competitive instrument rating instruction.
- Augmented Reality:Overlay displays blending physical cockpit elements with synthetic visual augmentation. Military operators across NATO member states are evaluating AR for maintenance training convergence.
Full Flight Simulator commands the dominant revenue share, while Virtual Reality gains share fastest among new procurement decisions.
End User:
Customer type determines procurement channel structure and certification pathway complexity.
- Commercial Airlines:Scheduled carriers operating under EASA Part-ORO training requirements with fleet-specific simulator access needs. British Airways and easyJet have established captive training subsidiaries with open third-party enrollment in the United Kingdom.
- Military Training:Defense forces with classified performance specifications and sovereign security requirements for multi-platform environments. Dual-use facilities in Germany capture both defense and commercial revenue streams under NATO interoperability mandates.
- Flight Schools:Independent training organizations delivering modular pilot licensing under EASA Part-FCL frameworks. Consolidation pressure is mounting as CSRD sustainability reporting mandates raise compliance overhead.
- Private Aviation:Business jet operators and owner-pilots seeking type-specific recurrent training. Demand fragments across distributed European locations with limited simulator density outside major metropolitan centers.
Commercial Airlines anchor procurement volume, with Military Training expanding most quickly on sovereign capability investments.
Service Type:
Margin structure varies across intellectual property-intensive versus labor-dependent service delivery.
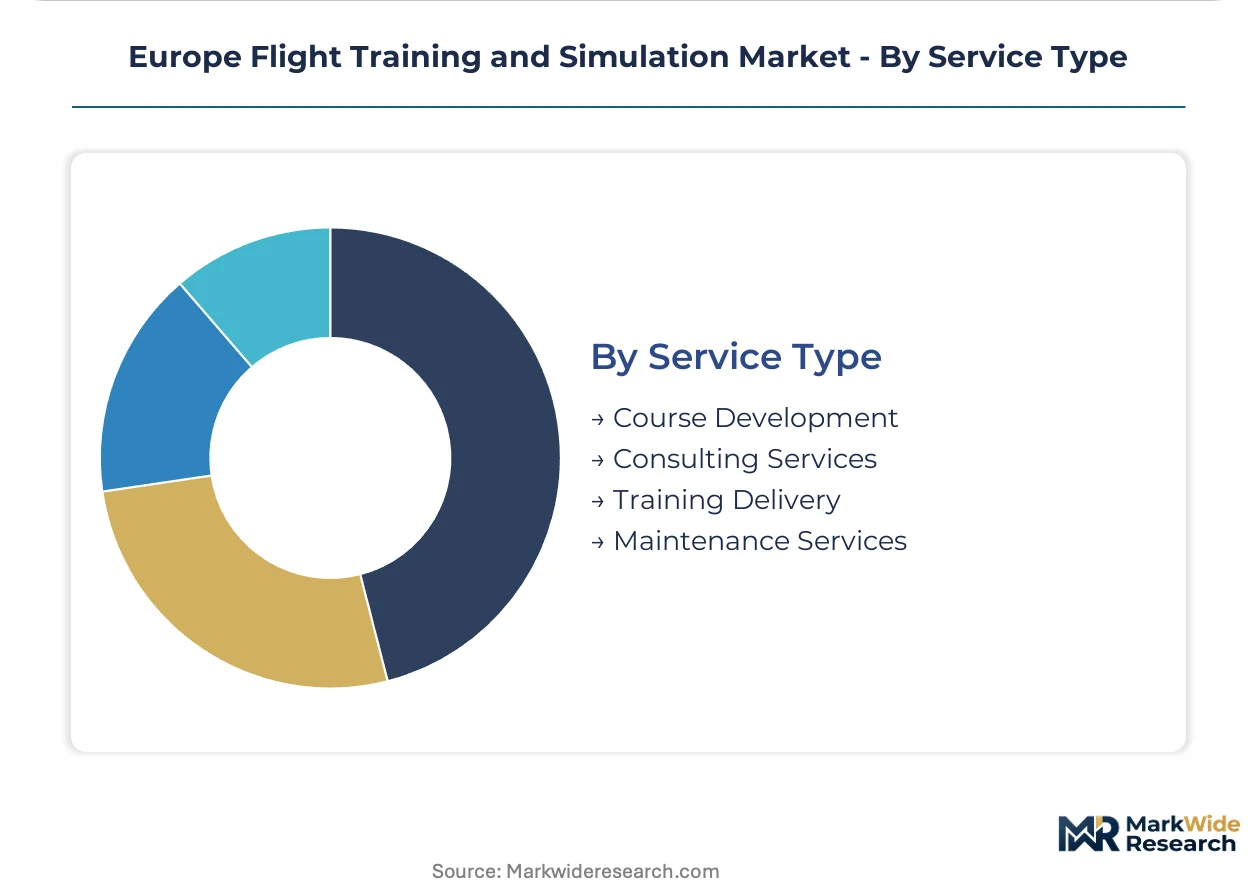
- Training Delivery:Direct instruction and simulator session operation for pilot qualification and recurrent certification. Independent centers in France are unbundling platform access from integrated service contracts to compete with airline captive operations.
- Maintenance Services:Hardware upkeep, software updates, and regulatory recertification for synthetic training devices. Legacy simulator data package obsolescence is escalating license fee pressure on operators of older platforms.
- Course Development:Curriculum design and regulatory alignment for operator-specific training programs. EU AI Act provisions are opening pathways for machine learning-assisted adaptive learning platform development.
- Consulting Services:Regulatory compliance advisory and training center design for greenfield investments. EU cohesion funding streams in Central and Eastern Europe are stimulating demand for aviation infrastructure planning expertise.
Training Delivery generates the largest revenue pool, while Maintenance Services shows the steepest expansion trajectory on fleet renewal cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's flight training and simulation industry traces its modern foundations to post-war aviation manufacturing clusters in France and the United Kingdom, where military airframe production seeded adjacent training infrastructure. EASA harmonization has since standardized certification pathways across member states, concentrating capital deployment near airline headquarters and defense procurement centers.
Germany
Commercial fleet renewal at Lufthansa Group and expanding NATO pilot training contracts drive simulator demand across Bavaria and North Rhine-Westphalia. BAAINBw procurement standards govern military qualification pathways, mandating sovereign data handling for classified training scenarios. CAE operates multiple Level D centers near Frankfurt and Munich, serving both airline type rating and Bundeswehr transport pilot pipelines.
United Kingdom
British Airways and easyJet have established captive training subsidiaries with open third-party enrollment, fragmenting traditional integrated service contracts. Military-civilian convergence accelerates under NATO interoperability requirements, with dual-use facilities near London and Bristol capturing defense and commercial revenue streams. The UK Ministry of Defence's Future Aircrew Training program is consolidating rotary-wing and fixed-wing simulation procurement.
France
Airbus headquarters proximity in Toulouse anchors Full Flight Simulator deployment for A320 and A350 family type ratings. Thales integrates simulator hardware and software development from its Paris-region engineering centers, supplying both domestic training centers and export markets. DGA certification requirements for military platforms create distinct procurement channels with classified performance specifications.
Poland
EU cohesion funding streams are subsidizing greenfield aviation infrastructure investments in Warsaw and Krakow, positioning the country as a cost-competitive training hub for Central and Eastern Europe. Polish flight schools are deploying Fixed Base Simulators for instrument rating instruction at price points below Western European competitors. LOT Polish Airlines' pilot pipeline requirements are stimulating domestic simulator capacity expansion.
Netherlands
KLM's training subsidiary near Amsterdam Schiphol serves as a regional center for SkyTeam alliance carrier crew qualification. Randstad logistics infrastructure supports rapid simulator component import from German motion base manufacturers. Dutch military pilot training consolidation at Woensdrecht Air Base is generating demand for multi-platform simulation environments spanning transport and helicopter configurations.
Europe Flight Training and Simulation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and motion platform fidelity, with Level D Full Flight Simulator integrators commanding pricing power that Fixed Base and VR providers cannot match. The vendor base stratifies into three tiers: diversified aerospace conglomerates with captive training divisions, specialized simulator manufacturers with EASA certification expertise, and emerging software-defined training platforms targeting ab initio segments. Consolidation pressure is mounting as airlines unbundle platform access from integrated service contracts, while cross-domain military-civilian facilities capture dual revenue streams under NATO interoperability mandates.
Within the diversified aerospace tier, Thales and CAE Inc. exemplify integrated hardware-software positioning, with the former anchoring French defense-commercial convergence and the latter leveraging extensive European training center networks. L3Harris Technologies Inc. occupies a specialist position in military training segmentation across NATO member states, reflecting US-European defense industrial cooperation patterns. These three entities represent distinct archetypes: Thales as sovereign-integrated systems provider, CAE as commercial training network operator, and L3Harris as defense-specialized platform integrator.
| Leading Market Players |
|---|
| Thales |
| TRU Simulation + Training Inc. |
| CAE Inc. |
| ELITE Simulation Solutions AG |
| RTX Corporation |
| FlightSafety International |
| The Boeing Company |
| Multi Pilot Simulations BV |
| L3Harris Technologies Inc. |
| Others |
Supply & Pricing Matrix
Certified instructor pilot scarcity in Germany and France compresses labor-cost differentials between premium Level D Full Flight Simulator centers and economy-tier Fixed Base Simulator operations. EASA's tightening Flight Simulation Training Device instructor qualification requirements widen pricing spreads as experienced airline pilots prioritize line flying over training assignments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Level D Full Flight Simulator access from Fixed Base Simulator hours and VR-based procedural training. Certification grade and geographic delivery cost differentiate tiers, with EASA CS-FSTD compliance overhead concentrated in premium offerings. Pricing pressure stems from airline procurement departments unbundling platform access from integrated service contracts. Flight schools and independent training centers exhibit highest price sensitivity, while military end users with sovereign security requirements show lowest.
Supply Chain Analysis
Regional distribution centers in Germany and the United States anchor hub-and-spoke patterns for motion platform component delivery to European simulator integrators. Manufacturing clusters for hydraulic actuators and electric motion bases in Germany and the United States create geographic supply concentration. GPU and image generator procurement for visual systems draws from semiconductor foundry capacity in Taiwan and South Korea. Single-source vulnerability for critical subsystems constitutes the dominant supply chain risk. Distribution runs through direct OEM relationships and specialized aviation component distributors serving training center operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Airline fleet renewal cycles are compressing type rating timelines toward premium Level D Full Flight Simulator specifications with zero-flight-time training mandates.
For Market Incumbents: Anticipate procurement fragmentation by securing long-term platform lease structures with independent training centers before airlines establish captive subsidiaries. EASA's regulatory compression on certification timelines threatens margin sustainability without vertical integration into motion base manufacturing. Prioritize examiner-rated instructor retention through compensation premiums and line flying schedule flexibility. For New Entrants and Emerging Players: Cloud-native image generation technology offers a wedge into secondary training locations where capital constraints limit full-motion platform deployment. Central and Eastern European greenfield simulator centers present the most penetrable geography, with EU cohesion funding subsidizing aviation infrastructure investments in Poland and Hungary. Pursue joint venture structures with established airlines seeking distributed training networks without complete platform ownership. For Investors and Strategic Acquirers: Defense contractors with NATO interoperability mandates are the most active acquirer in this space, capturing dual-use facilities that span military and commercial revenue streams. Long-term viability centers on cross-domain training convergence and adaptive learning platform development under EU AI Act compliance guardrails. Monitor EASA's alignment of certification processes with CSRD sustainability disclosure standards as inflection indicator for energy-efficient electric motion system procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Lease Restructuring | Airlines unbundle simulator access from bundled type rating contracts to lock in pilot pipeline throughput. |
| EU AI Act Compliance Investment | Simulator manufacturers embed intelligent tutoring systems with defined machine learning guardrails for adaptive instruction. |
| Central European Hub Development | Greenfield training centers in Poland and Hungary capture EU cohesion funding for cost-competitive infrastructure. |
| Energy-Efficient Motion System Procurement | German and French training providers respond to CSRD mandates with electric motion platforms and renewable power agreements. |
| Military-Civilian Facility Convergence | Dual-use centers in the United Kingdom and Germany capture NATO interoperability contracts alongside commercial airline demand. |
Research Methodology
Direct dialogue with training center operators, airline fleet management executives, EASA certification specialists, simulator manufacturer product managers, and defense procurement officers grounded qualitative findings. Secondary validation drew from EASA regulatory filings, EU AI Act implementation guidance, CSRD sustainability reporting standards, national military procurement documentation from Germany's BAAINBw and France's DGA, and aviation trade association training statistics. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Segmentation outputs across training type, simulation technology, end user, and service type dimensions structured the analytical framework over the projection horizon. CAGRs derived from regression analysis against fleet renewal cycles, regulatory mandate implementation schedules, and training capacity expansion patterns. Industry-specific forecast inputs incorporated EASA zero-flight-time training penetration assumptions and Extended Reality adoption curves in ab initio programs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry capacity allocation for visual system hardware and EASA regulatory divergence from emerging national cybersecurity requirements. Forecasts reflect documented assumptions around fleet renewal timing and regulatory harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Military Simulation Software Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
Civil Aerospace Simulation and Training Market
Simulation and Training
Satellite Simulator Market
Simulation and Training
Pilot Training Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
Trainer Aircraft Market
Simulation and Training
North America Simulator Windows and Simulator Skylights Market
Simulation and Training
RADAR Simulator Market
Simulation and Training
Middle East Civil Aviation Flight Training and Simulation Market
Simulation and Training
Air Traffic Control Simulator and Training Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Air Traffic Control Simulation and Training Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market