
 Glyphosate Herbicide Market | 2026-2036
Glyphosate Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
Glyphosate Herbicide Market Insights
Asset-light toll manufacturing and third-party formulation leasing is reshaping competitive entry in glyphosate supply, allowing regional blenders to scale without captive synthesis plants. Bayer AG leverages its integrated seed-trait-chemistry platform to sustain Roundup Ready system pull-through across the Americas. UPL Limited anchors its position through backward integration into technical-grade production in India and contract manufacturing partnerships in Latin America. Zhejiang Xinan Chemical Industrial Group dominates the export trade in glyphosate technical acid, supplying formulation houses across Southeast Asia and Africa.
Glyphosate herbicide is a broad-spectrum, post-emergent phosphonomethyl amino acid compound that inhibits the 5-enolpyruvylshikimate-3-phosphate synthase (EPSPS) enzyme in plants, typically manufactured through a catalytic oxidation process from phosphonomethyliminodiacetic acid (PMIDA) and formulated as isopropylamine or potassium salts for foliar application. Its primary commercial purpose is total vegetation control in agricultural row crops, orchards, and non-crop land management. Liquid formulations lead volume consumption due to ease of tank-mixing with dicamba and glufosinate in resistance-management programs, while soluble concentrate (SL) and suspension concentrate (SC) formats capture margin pools through drift-reduction adjuvant integration. Agricultural applications concentrate the bulk of demand, though industrial vegetation control along railways and utility corridors sustains premium pricing for specialized granule and powder packaging.
The US EPA governs glyphosate tolerance levels under the Federal Insecticide, Fungicide, and Rodenticide Act, while the EU's EFSA and ECHA jointly assess carcinogenicity and ecotoxicity benchmarks that determine reauthorization and import acceptance. Brazil's ANVISA and China's MEE enforce divergent residue standards that fragment formulation specifications and label claims across export destinations. Stakeholders must monitor regulatory arbitrage between jurisdictions where MRL tightening in one market can strand inventory formulated for another, forcing parallel product-line investments or selective market withdrawal.
Market Dynamics
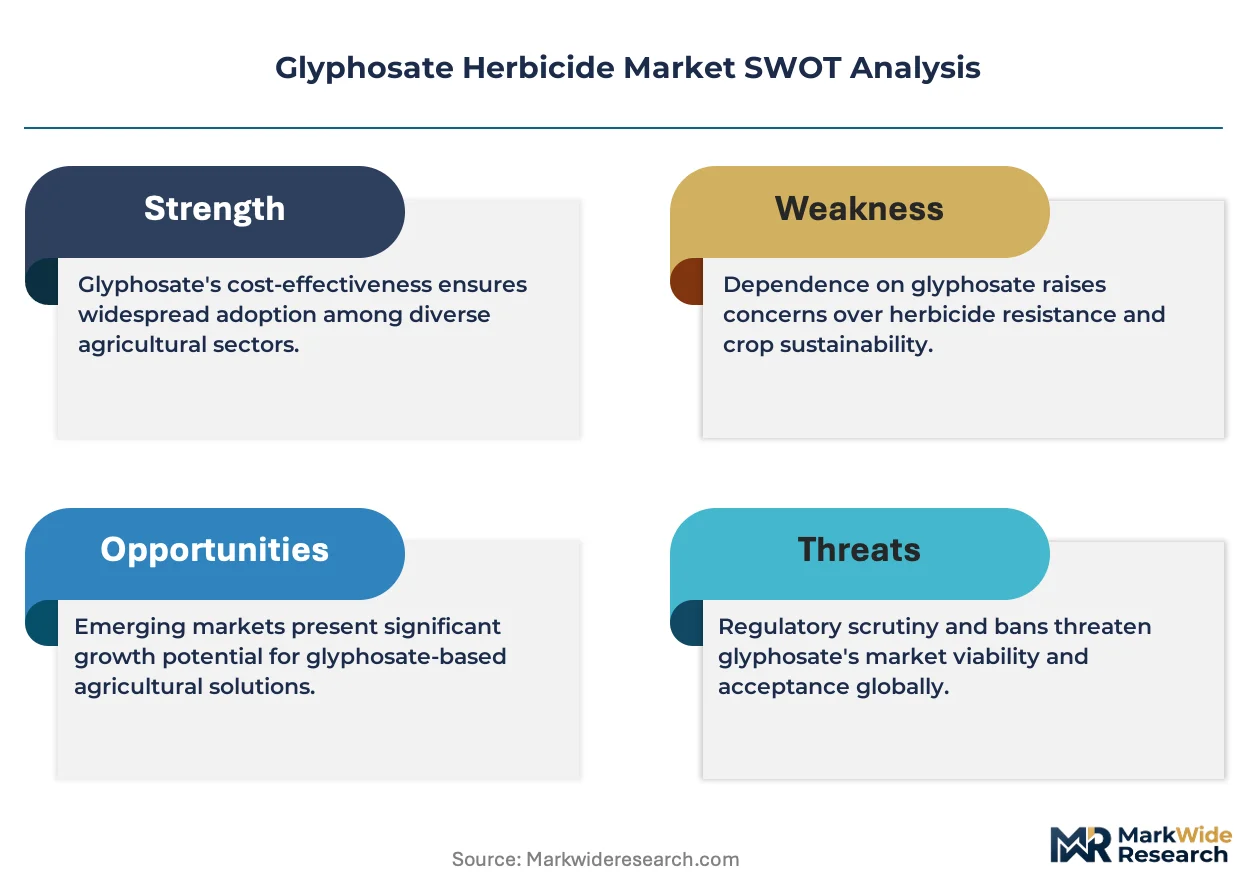
Co-formulant innovation pressure from EFSA buffer-zone mandates is fragmenting formulation specifications, forcing parallel product-line investments that reshape competitive economics across export destinations.
Growth Catalysts
- ANVISA residue harmonization:Brazil's alignment with Codex Alimentarius MRLs is streamlining import acceptance for Asian technical-grade suppliers, reducing reformulation costs for the Mercosur trade bloc.
- No-till agriculture expansion:Argentine Pampas soybean-corn rotations are sustaining bulk glyphosate procurement volumes as cover-crop adoption displaces mechanical tillage.
- Phosphonomethyliminodiacetic acid catalysis:Improved oxidation efficiency in PMIDA-to-glyphosate conversion is compressing manufacturing energy intensity for technical acid producers.
Market Restraints
- Chinese technical-grade concentration:Zhejiang and Jiangsu province production clusters account for dominant export volumes, creating single-source vulnerability for formulation houses in Southeast Asia and Africa.
- EPA tolerance reassessment timelines:Federal Insecticide, Fungicide, and Rodenticide Act registration review delays are extending product relabeling cycles and freezing formulation investments.
- Glufosinate-ammonium substitution:Bayer's LibertyLink seed-trait system is capturing resistance-management acres from glyphosate-tolerant varieties in US Plains states.
Strategic Opportunities
- Sub-Saharan Africa smallholder penetration:Soluble granule packaging formats are opening distribution channels previously blocked by liquid formulation cold-chain requirements.
- EU Green Deal Farm-to-Fork targets:Precision application mandates are creating demand for drift-reduction adjuvant integration in suspension concentrate formulations.
- Railway corridor vegetation management:Industrial non-crop contracts in Australia and Canada are sustaining premium pricing for specialized high-concentration powder packaging.
Industry Challenges
- Formulation chemist scarcity:Expertise in surfactant-salt compatibility for tank-mix stability is concentrating at legacy agrochemical firms, constraining regional blender scale-up.
- MEE environmental compliance capex:China's Ministry of Ecology and Environment wastewater discharge standards are requiring catalytic oxidation plant retrofits that strain mid-tier technical producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glyphosate Herbicide Market |
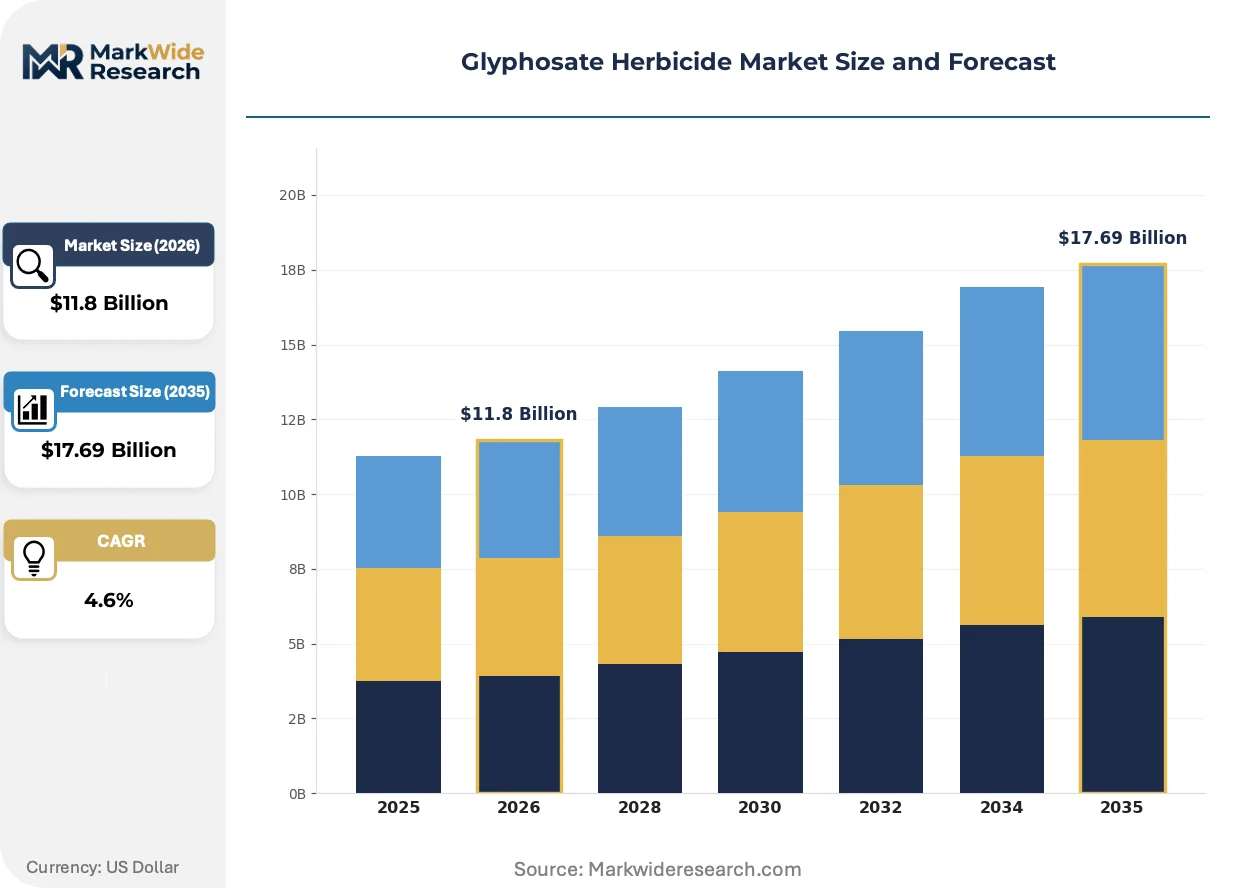
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Granules, Liquid, Powder Application: Agricultural, Industrial, Commercial, Residential Packaging Type: Bulk, Sachets, Bottles, Drums Formulation: SL, EC, WG, SC |
| Companies Covered | Bayer AG, Syngenta Group, UPL Limited, Zhejiang Xinan Chemical Industrial Group, BASF SE, ADAMA Agricultural Solutions, Albaugh, Nufarm Limited, FMC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glyphosate Herbicide Market Trends and Innovations
Formulation chemistry and application technology are converging to address drift liability and resistance management simultaneously, compressing the traditional separation between active ingredient supply and end-use performance.
Drift-reduction nozzle technology paired with high-viscosity suspension concentrates is collapsing the distance between aerial application and ground-rig efficacy standards. Brazilian soybean cooperatives are retrofitting existing sprayer fleets with air-induction nozzles at replacement cycle compression rates. This convergence is collapsing premium pricing for specialized aviation formulation grades as ground-rig performance parity eliminates application-method differentiation.
EFSA's 2023 updated ecotoxicity assessment framework for co-formulants is forcing reformulation of polyethoxylated tallowamine surfactants across EU-destined product lines. The industrial consequence is a 12-18 month relabeling cycle for established brands while new adjuvant chemistry clears hazard classification reviews. German and French formulation houses are responding with phosphate ester surfactant substitutions that sacrifice some rainfastness for regulatory certainty.
Grain elevator procurement consortia in Iowa and Illinois are consolidating annual glyphosate tenders into multi-year framework agreements with volume-floor guarantees. This buyer-side aggregation is displacing spot-market purchases and compressing distributor margin pools. The pattern is most visible in the US Corn Belt, where cooperative buying groups now account for dominant share of branded and generic volume allocation.
Glyphosate Herbicide Market Segmentation
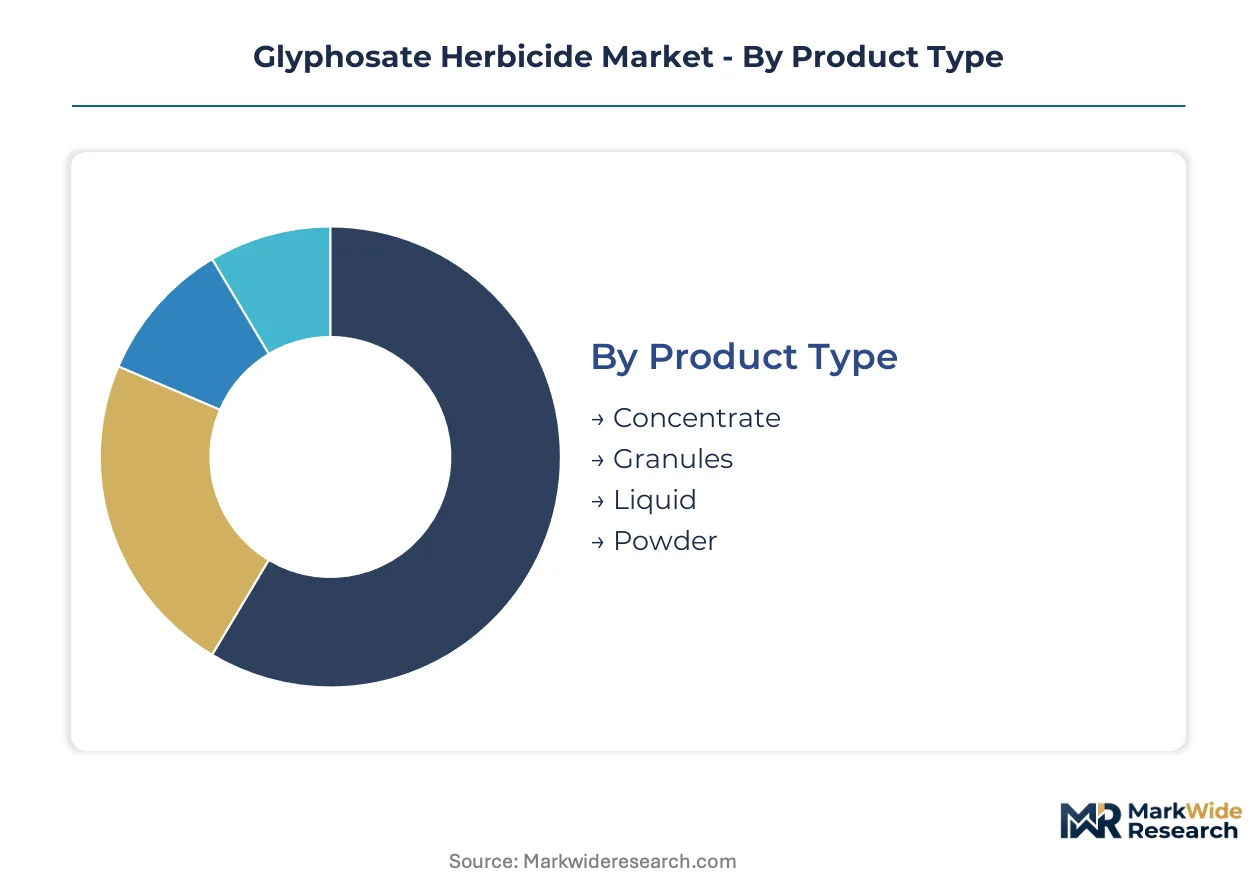
Segmentation in glyphosate herbicides determines formulation investment priorities, packaging logistics, and regulatory compliance pathways. Product type and formulation choices cascade into tank-mix compatibility, drift liability exposure, and end-user access models across agricultural and industrial channels.
Product Type:
Concentrate formats turn over fastest in high-volume agricultural procurement cycles, while powder and granule segments exhibit slower replacement rhythms tied to specialized application windows.
- Liquid:Isopropylamine and potassium salt solutions dominate tank-mix protocols with dicamba and glufosinate in resistance-management programs. Demand concentrates in Brazilian soybean cooperatives and US Corn Belt grain elevator consortia where bulk procurement volumes sustain annual tender cycles.
- Concentrate:High-active-load formulations reduce freight costs per treated hectare and enable regional blending operations without technical acid synthesis capability. Argentine Pampas distributors favor concentrate procurement for on-site dilution to finished spray solutions.
- Granules:Soluble granule formats bypass cold-chain requirements for Sub-Saharan African smallholder distribution channels. Water-dispersible packaging suits railway corridor vegetation management contracts in Australia and Canada.
- Powder:Dry formulations serve industrial non-crop applications requiring extended storage stability and precise metering equipment compatibility.
Liquid anchors the volume base while granules gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity agricultural volume from premium-priced industrial and commercial contracts with specialized liability coverage requirements.
- Agricultural:Row-crop soybean-corn rotations in Brazil, Argentina, and US Plains states consume the dominant share of glyphosate volume. No-till expansion and cover-crop adoption sustain bulk procurement through cooperative buying groups.
- Industrial:Railway, utility corridor, and pipeline vegetation management contracts command premium pricing for drift-reduction formulations and specialized application equipment. Australian and Canadian operators specify high-concentration powder packaging for remote access sites.
- Commercial:Golf course, municipal park, and cemetery maintenance programs require buffer-zone compliance formulations under tightening EFSA co-formulant standards.
- Residential:Consumer-ready packaging in retail garden centers faces regulatory pressure from municipal glyphosate restriction ordinances in selective EU member states and North American municipalities.
Agricultural absorbs the dominant procurement tonnage while industrial commands the widest pricing premium per active unit.
Packaging Type:
Customer type and procurement scale dictate packaging selection, with bulk formats serving institutional buyers and sachets penetrating smallholder channels lacking capital equipment.
- Bulk:Tanker and tote deliveries supply Brazilian cooperatives and US grain elevator consortia with multi-year framework agreements and volume-floor guarantees.
- Drums:Standard 200-liter containers serve regional formulation houses and commercial applicator fleets with intermediate storage requirements.
- Bottles:Retail-ready packaging for residential and commercial segments faces shelf-space competition from alternative herbicide chemistries in garden center distribution.
- Sachets:Single-use water-soluble packaging opens distribution to Sub-Saharan African smallholders without calibrated sprayer access or cold-chain infrastructure.
Bulk shipments anchor procurement economics while sachets expand addressable market geography fastest.
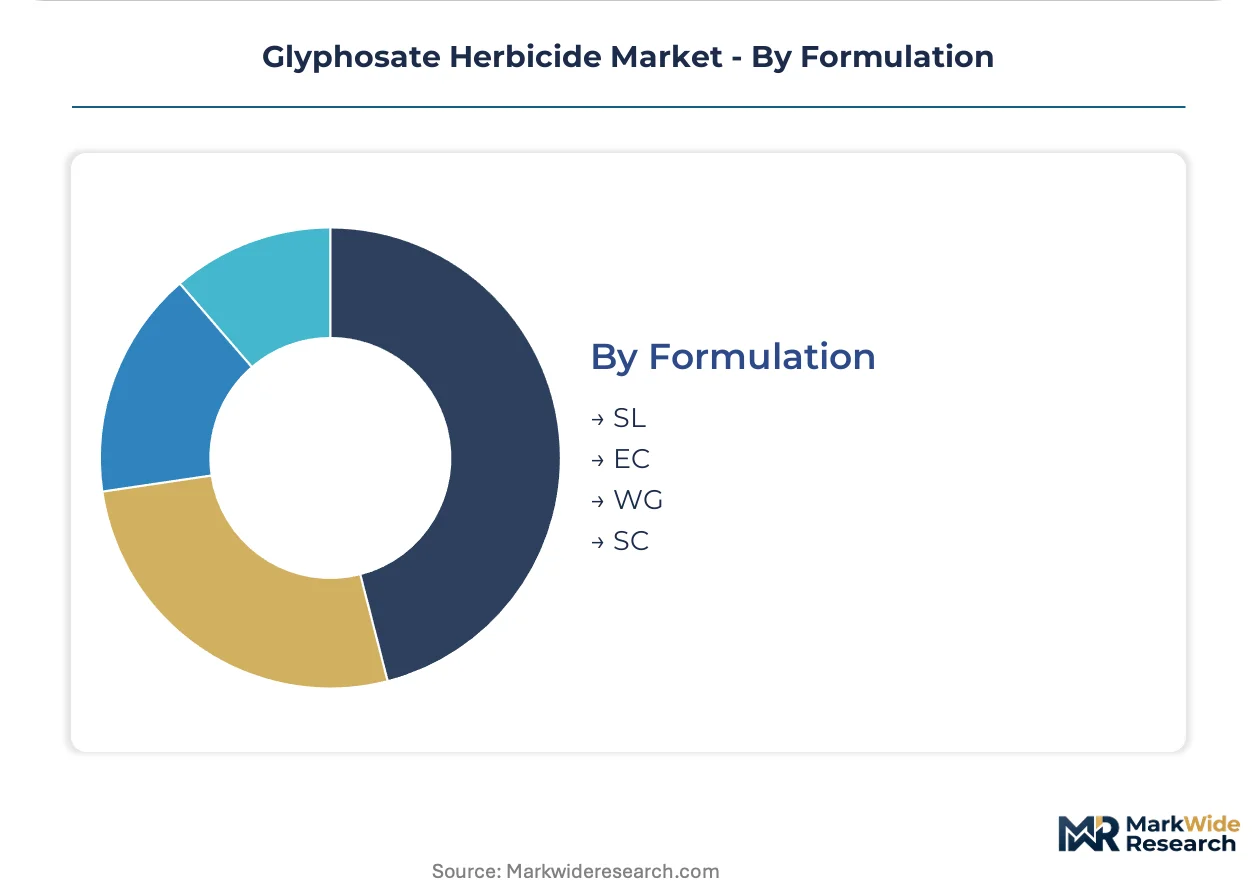
Formulation:
Margin structure and regulatory compliance burden vary sharply across formulation chemistry, with drift-reduction adjuvant integration commanding technology premiums.
- SL (Soluble Liquid):Isopropylamine salt solutions offer straightforward tank-mix compatibility and established residue tolerance databases across ANVISA, EPA, and Codex jurisdictions.
- SC (Suspension Concentrate):High-viscosity formulations with integrated drift-reduction adjuvants satisfy EFSA buffer-zone mandates and precision application requirements under EU Green Deal Farm-to-Fork targets.
- EC (Emulsifiable Concentrate):Oil-based carrier systems suit specialized industrial applications requiring extended rainfastness and foliar penetration enhancement.
- WG (Water-Dispersible Granules):Dry flowable formats combine storage stability with reduced packaging weight for remote site access and smallholder distribution.
SL formulations sustain the installed application base while SC climbs fastest on regulatory compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain elevator consortia in the US Corn Belt and Brazilian soybean cooperatives anchor procurement volumes, while formulation investments fragment across regulatory jurisdictions with divergent residue standards and buffer-zone mandates.
United States
US Plains states sustain dominant agricultural consumption through no-till soybean-corn rotations and cooperative buying groups with multi-year framework agreements. EPA registration review timelines under FIFRA extend product relabeling cycles and freeze formulation investments pending tolerance reassessments. Iowa and Illinois grain elevator procurement consortia now account for dominant share of branded and generic volume allocation.
Brazil
ANVISA residue harmonization with Codex Alimentarius MRLs streamlines import acceptance for Asian technical-grade suppliers and reduces reformulation costs across the Mercosur trade bloc. No-till agriculture expansion in Mato Grosso and Goiás sustains bulk glyphosate procurement volumes as cover-crop adoption displaces mechanical tillage. Brazilian soybean cooperatives retrofit existing sprayer fleets with air-induction nozzles at compressed replacement cycles.
Argentina
Pampas region soybean-corn rotations anchor off-label and branded consumption as no-till farming penetrates deeper into traditional tillage zones. Argentine distributors favor concentrate procurement for on-site dilution to finished spray solutions, reducing freight costs per treated hectare. Buenos Aires province formulation houses serve regional blenders without captive technical acid synthesis capability.
China
Zhejiang and Jiangsu province production clusters dominate export volumes of glyphosate technical acid, supplying formulation houses across Southeast Asia and Africa. MEE wastewater discharge standards require catalytic oxidation plant retrofits that strain mid-tier technical producers. Zhejiang Xinan Chemical Industrial Group anchors the export trade, creating single-source vulnerability for dependent formulation markets.
Germany
EFSA buffer-zone mandates and updated ecotoxicity assessment frameworks for co-formulants force reformulation of polyethoxylated tallowamine surfactants across EU-destined product lines. German formulation houses respond with phosphate ester surfactant substitutions that sacrifice rainfastness for regulatory certainty. Leverkusen-based integrated seed-trait-chemistry platforms sustain Roundup Ready system pull-through across affiliated Americas operations.
Glyphosate Herbicide Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where backward integration into technical-grade production separates volume leaders from regional blenders. The vendor base clusters around three archetypes: integrated agrochemical conglomerates with seed-trait platforms, technical-grade specialists with export-oriented synthesis capacity, and asset-light toll manufacturers leasing formulation capacity. Dominant competitive moves include strategic partnerships for regional distribution access and capacity expansion in low-cost technical acid production zones.
Among integrated agrochemical conglomerates, Bayer AG exemplifies the seed-trait-chemistry platform archetype, while UPL Limited represents backward integration into technical-grade production combined with contract manufacturing partnerships. Zhejiang Xinan Chemical Industrial Group occupies the export-oriented technical specialist position, anchoring supply relationships with formulation houses lacking captive synthesis capability. These three patterns illustrate how competitive positioning stratifies across upstream control, downstream channel access, and geographic specialization.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta Group |
| UPL Limited |
| Zhejiang Xinan Chemical Industrial Group |
| BASF SE |
| ADAMA Agricultural Solutions |
| Albaugh |
| Nufarm Limited |
| FMC Corporation |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Zhejiang and Jiangsu province technical acid production clusters determines both pricing tier spreads and supply chain shape across global formulation markets. Chinese MEE wastewater discharge compliance costs concentrate upstream pricing power while fragmenting downstream procurement economics.
Pricing Analysis
Cost-plus contracts with phosphonomethyliminodiacetic acid feedstock indexation anchor pricing structures for technical-grade suppliers. Three-tier pricing structure across drift-reduction suspension concentrates, standard soluble liquids, and economy granule formats separates premium EFSA-compliant formulations from commodity agricultural volumes. Price differentiation rests on surfactant-salt compatibility certification and volume-floor guarantees in multi-year framework agreements. Margins are tightening due to Brazilian cooperative buying group consolidation displacing spot-market purchases.
Supply Chain Analysis
Export-control scrutiny on catalytic oxidation technology transfers limits capacity expansion outside established production zones. Supply concentrates in China for technical acid, Brazil and Argentina for regional formulation, and India for backward-integrated technical production. Raw material dependencies span PMIDA precursors, phosphoric acid derivatives, and specialized surfactant chemistries. Single-source vulnerability from Zhejiang Xinan Chemical Industrial Group export dominance creates structural concentration risk. Distribution runs through toll manufacturing partnerships and asset-light regional blender networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glyphosate herbicide markets face high-growth disruption from EFSA co-formulant reformulation mandates and precision application technology convergence. Regulatory arbitrage between residue standard jurisdictions creates acquisition and partnership windows.
For Market Incumbents: Entrench seed-trait-chemistry platform pull-through by deepening captive technical acid supply and accelerating drift-reduction adjuvant R&D pipelines. Bayer AG's integrated model demonstrates defensive positioning against glufosinate-ammonium substitution threats from LibertyLink systems. Prioritize ANVISA-aligned formulation capacity in Mercosur markets to capture harmonization benefits. For New Entrants and Emerging Players: Establish a beachhead in Sub-Saharan African soluble granule distribution channels previously blocked by liquid cold-chain requirements. Target railway corridor vegetation management contracts in Australia and Canada where specialized high-concentration powder packaging commands premium pricing. Pursue toll manufacturing partnerships with existing technical acid suppliers to bypass catalytic oxidation plant capex barriers. For Investors and Strategic Acquirers: EPA tolerance reassessment timelines under FIFRA reshape the acquisition landscape by extending product relabeling cycles and freezing formulation investments. Five-to-ten year viability favors targets with EFSA-compliant surfactant substitutions already cleared. Watch for MEE environmental compliance capex strain forcing mid-tier Chinese technical producer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PMIDA Production | Captive feedstock supply insulates margin pressure from Chinese technical acid concentration. |
| Drift-Reduction Adjuvant R&D Partnership | EFSA buffer-zone compliance creates technology premium capture in EU-destined formulations. |
| Sub-Saharan African Distribution Alliance | Soluble granule packaging opens smallholder channels without cold-chain infrastructure investment. |
| Toll Manufacturing Capacity Expansion | Asset-light regional blender scale-up avoids stranded technical synthesis plant capex. |
| Multi-Year Framework Agreement Consolidation | Volume-floor guarantees with Brazilian cooperatives lock in procurement share against spot-market volatility. |
Research Methodology
Desk research of customs trade databases, EPA registration filings, and EFSA ecotoxicity assessment frameworks preceded structured interviews with formulation chemists, Brazilian cooperative procurement managers, Argentine distributor network heads, and Chinese technical acid plant operations directors. Primary fieldwork captured tank-mix compatibility protocols, drift-reduction nozzle retrofit cycles, and surfactant substitution decision timelines. Secondary validation drew from ANVISA residue standard harmonization documentation, MEE wastewater discharge compliance records, and grain elevator consortia tender specifications. Bottom-up volume modeling triangulated against top-down agricultural acreage and application rate assumptions.
Assumptions held fixed include EFSA co-formulant assessment methodologies, ANVISA-Codex MRL alignment trajectories, and no-till adoption rates across the Pampas and US Plains states. Variables stress-tested encompass EPA tolerance reassessment outcomes, Chinese environmental compliance enforcement intensity, and glufosinate-ammonium substitution elasticity. Segmentation dimensions spanned formulation chemistry, packaging format, application method, and regional regulatory cluster. CAGRs derived from acreage-intensity projections and active ingredient loading rate trends across soybean-corn rotation systems.
Stress conditions across Chinese technical acid export availability, Brazilian cooperative buying group consolidation pace, and EFSA buffer-zone mandate implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and variable boundaries. Material shifts in EPA carcinogenicity classification determinations or Chinese MEE catalytic oxidation plant shutdown enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
United States Feed Enzymes Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Asia Pacific Feed Pelletizing Agents Market
Agricultural Chemicals
South America Silage Inoculant Market