
 North America Feed Premix Market | 2026-2036
North America Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Premix Market Analytics
Poultry farming is realigning North American feed premix procurement patterns as integrators demand higher-density vitamin and amino acid formulations. Cargill Incorporated leverages its grain origination network to anchor premix distribution across Midwest production corridors. Kemin Industries Inc differentiates through specialty antioxidant and mold inhibitor portfolios that sustain premium positioning in high-value livestock segments.
Feed premix denotes a homogeneous blend of micro-ingredients including vitamins, minerals, amino acids, and functional additives dosed at 0.1-3.0% of finished feed weight, manufactured via sequential dilution and precision mixing to ensure uniform nutrient dispersion. Its primary purpose is to correct nutritional deficiencies in base feedstuffs and optimize metabolic performance across monogastric and ruminant species. Vitamin premix commands the deepest margin pools due to formulation complexity and stability requirements, while amino acid premix experiences the fastest volume growth as low-protein diet formulations expand. Mineral premix remains the most mature category with consolidated supply and price-transparent procurement.
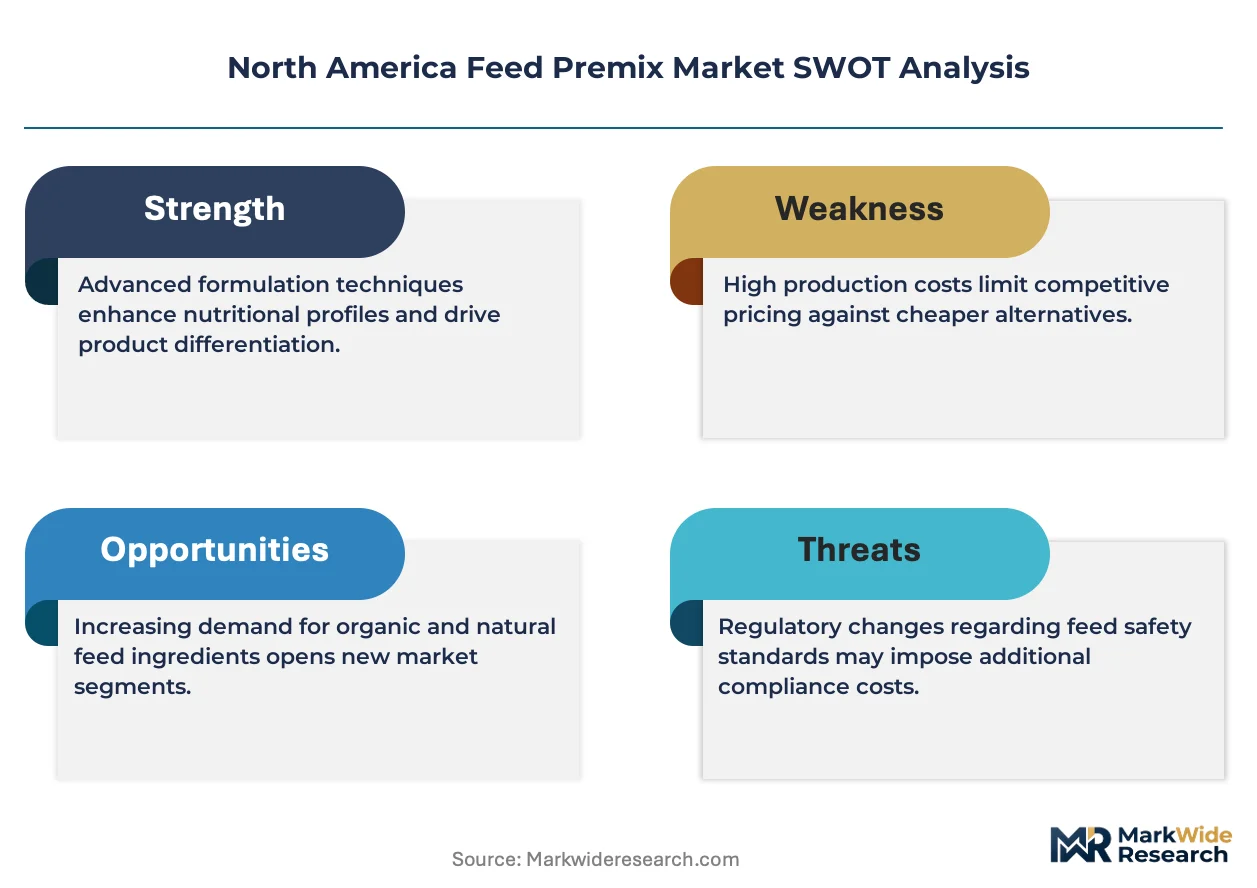
The FDA Veterinary Feed Directive and USDA Organic standards jointly constrain antibiotic premix access while elevating traceability requirements for mineral and vitamin sourcing. EPA nutrient management regulations in key livestock counties further tighten formulation precision to reduce nitrogen and phosphorus excretion. Stakeholders must monitor evolving state-level feed safety audits and ingredient origin documentation requirements as conditional approvals narrow and buyer liability expands.
Market Dynamics
Poultry integrators across the U.S. Corn Belt are consolidating procurement authority, forcing premix suppliers to reformulate around higher-density vitamin and amino acid specifications that optimize feed conversion ratios at commercial scale.
Growth Catalysts
- Precision nutrition protocols:Large-scale livestock integrators in Iowa and Nebraska now mandate premix formulations calibrated to individual growth-phase metabolomics, pulling demand for customized micro-ingredient blends.
- FDA Veterinary Feed Directive:Restrictions on medically important antibiotics in livestock feed have redirected formulation investment toward organic acid and phytogenic additive premix categories.
- Consolidated Midwest production corridors:Geographic concentration of finishing operations across Kansas, Oklahoma, and Texas creates procurement scale effects that reward premix suppliers with integrated grain origination capabilities.
Market Restraints
- Vitamin input cost volatility:Synthesis feedstock fluctuations for vitamin A and E precursors compress margin predictability for premix manufacturers serving price-sensitive ruminant segments.
- Supply concentration in mineral phosphates:Domestic sourcing dependence on a limited corridor of Florida and Idaho phosphate mining operations exposes premix formulators to geographic disruption risk.
- Stability limitations in organic trace minerals:Chelated mineral premix categories face technical constraints around shelf-life consistency that constrain premium pricing penetration in non-integrated livestock operations.
Strategic Opportunities
- Underpenetrated Canadian prairie provinces:Alberta and Saskatchewan feedlot expansion lags U.S. Corn Belt premix sophistication, creating white space for amino acid premix penetration in backgrounding operations.
- USDA Organic certification tailwinds:Accelerating organic livestock inventory across Vermont and Wisconsin generates demand for mineral and vitamin premixes with verified non-synthetic ingredient chains.
- Digital formulation-to-farm platforms:Integration of real-time near-infrared feed analysis with cloud-based premix ordering systems enables direct channel bypass of traditional distributor networks in Texas Panhandle poultry operations.
Industry Challenges
- Specialized formulation chemist scarcity:Premix manufacturers struggle to recruit talent capable of navigating simultaneous FDA feed safety rules and EPA nutrient discharge calculations for concentrated animal feeding operations.
- Legacy ERP integration friction:Transitioning from batch-based manufacturing execution systems to continuous premix production lines demands capital allocation that mid-tier suppliers in the Midwest find difficult to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Premix Market |
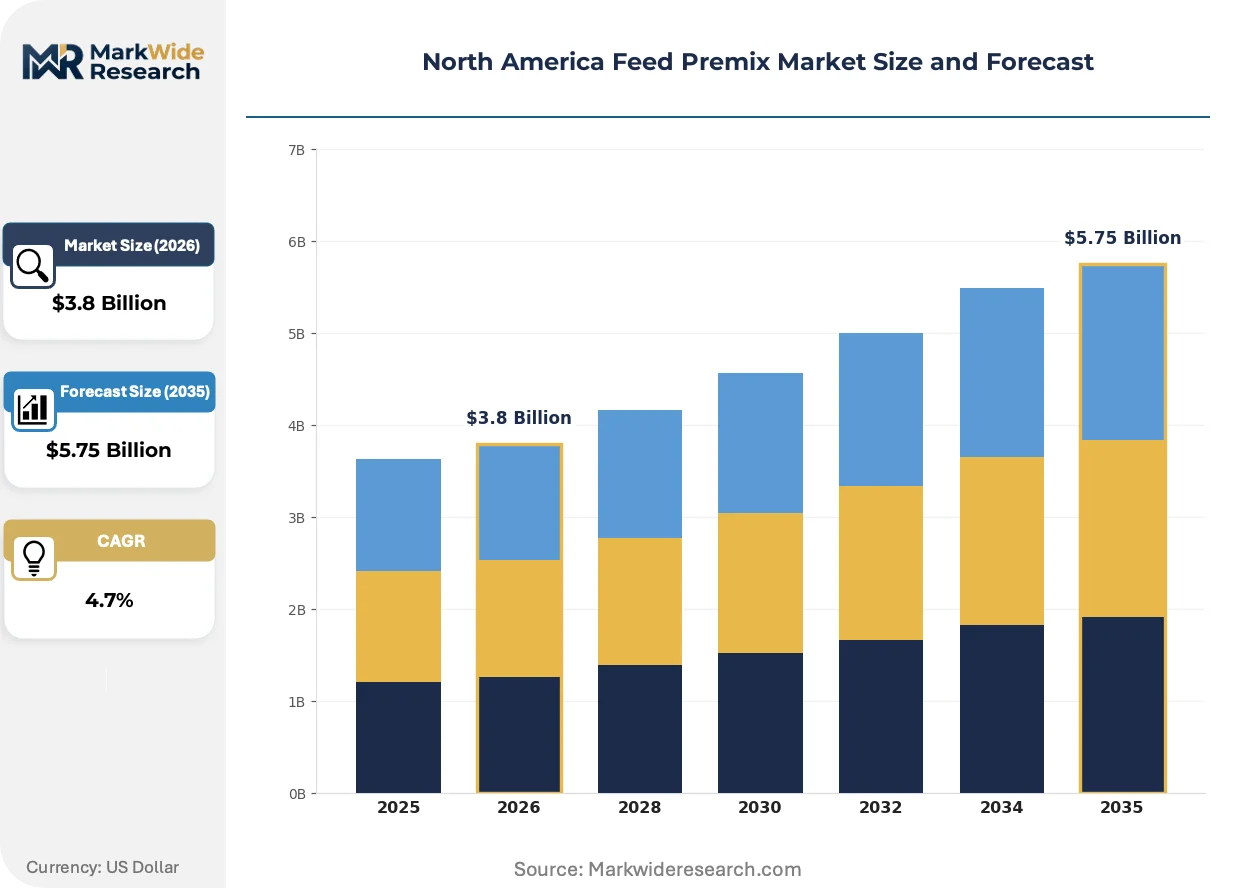
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Premix, Vitamin Premix, Amino Acid Premix, Antibiotic Premix End User: Pork Producers, Poultry Farmers, Dairy Farmers, Aquaculture Operators Form: Powder, Granules, Pellets, Liquid Distribution Channel: Online Sales, Direct Sales, Retail Outlets, Wholesale Distributors |
| Companies Covered | DSM-Firmenich AG, Kemin Industries Inc, Cargill Incorporated, CCPA GROUP, Trow Nutrition, BASF SE, Land O'Lakes Inc, Biomin, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Premix Market Evolving Landscape
Formulation science is converging with on-farm digital sensing, compressing the feedback loop between premix specification and livestock performance measurement in ways that reward real-time adjustable micro-ingredient dosing.
Encapsulated vitamin technologies using lipid-matrix and polymer-coating delivery systems are consolidating control over nutrient bioavailability in high-stress poultry environments. U.S. broiler integrators in Georgia and Arkansas have adopted these platforms at commercial scale since 2022. The technology is consolidating supplier margins into firms with captive encapsulation capabilities, compressing commodity premix competitors into price-taker positions.
The FDA Veterinary Feed Directive and parallel state-level antibiotic stewardship programs in California and Maryland are forcing reformulation of medicated premix portfolios toward ionophore coccidiostats and vaccine-compatible acidifiers. Feed mills serving independent hog finishers face compliance documentation burdens that favor vertically integrated protein companies with in-house regulatory affairs capacity. The swine premix segment is responding through consolidated procurement of pre-certified additive bundles rather than individual active ingredient sourcing.
Integrated livestock-protein companies are compressing their premix supplier rosters from multi-source to single-source or dual-source arrangements tied to long-term metabolizable energy guarantee contracts. This concentration is displacing independent distributors across the Texas and Oklahoma cattle feeding regions. The shift is most visible in dairy operations across Wisconsin and New York, where processor-owned heifer-raising facilities now contract directly with premix manufacturers for total mixed ration optimization services.
North America Feed Premix Market Segmentation
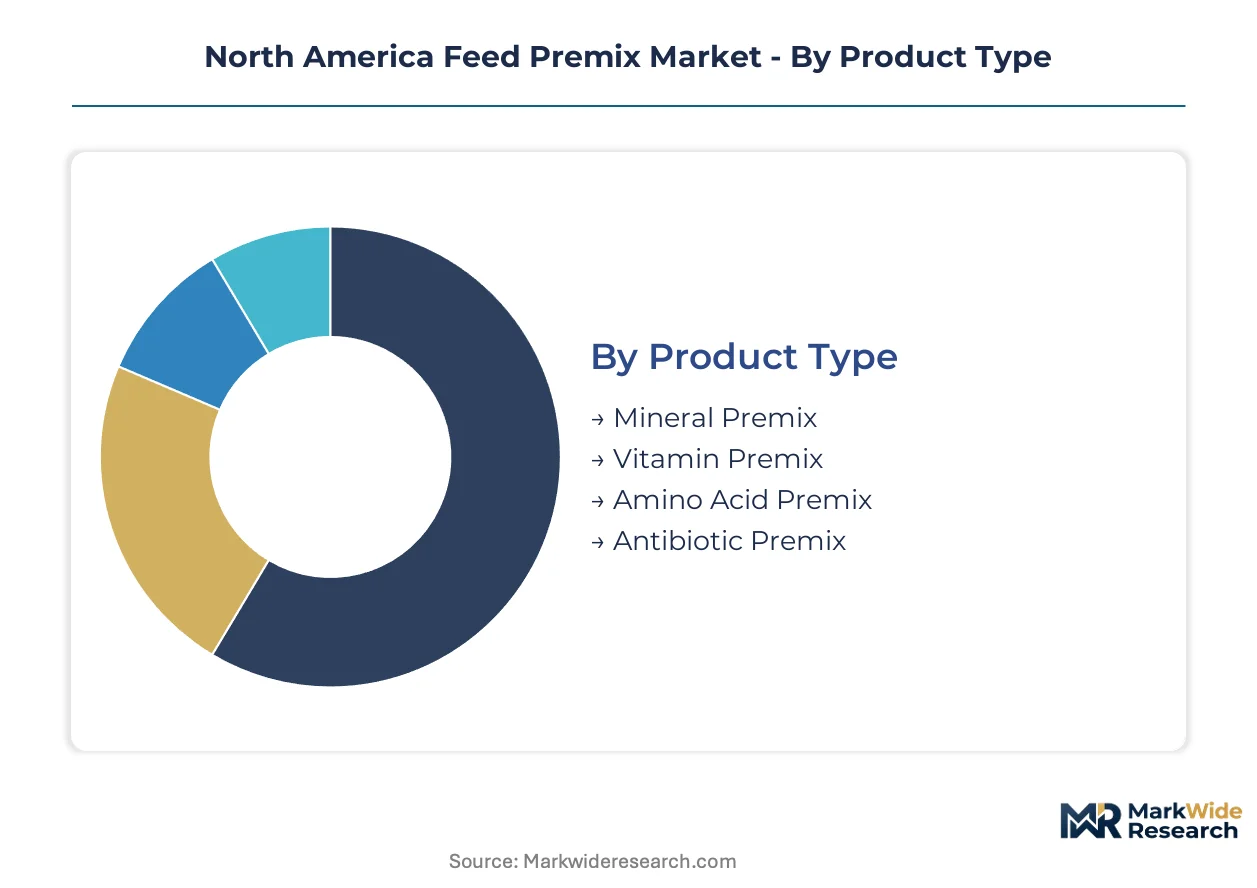
Feed premix segmentation in North America reflects divergent supply economics across micro-ingredient categories. Formulation complexity, regulatory exposure, and end-user scale requirements create distinct competitive arenas within each dimension.
Product Type:
Supply concentration varies sharply across premix categories, with vitamin synthesis requiring multi-step chemical processing that limits viable manufacturing sites.
- Vitamin Premix:Complex multi-vitamin blends requiring lipid stabilization and moisture-resistant carriers to prevent degradation during feed pelleting. Demand concentrates among Iowa and Nebraska poultry integrators seeking precision-dosed riboflavin and B-complex formulations for rapid-growth broiler phases.
- Amino Acid Premix:Lysine, methionine, and threonine blends enabling low-protein diet formulations that reduce nitrogen excretion compliance costs. Texas Panhandle cattle feeders are expanding procurement of rumen-protected amino acid premixes as EPA nutrient management enforcement tightens in high-density counties.
- Mineral Premix:Macro and trace mineral blends with established supply chains from Florida and Idaho phosphate operations serving mature ruminant nutrition programs.
- Antibiotic Premix:Medically important antibiotic formulations now restricted to veterinary prescription under FDA Veterinary Feed Directive, redirecting investment toward ionophore coccidiostats.
Vitamin premix absorbs the bulk of installed capacity; amino acid premix is expanding most quickly.
End User:
Customer scale and integration level determine formulation service intensity and contract structure across livestock sectors.
- Poultry Farmers:Vertically integrated broiler and layer operations in Georgia, Arkansas, and Mississippi demanding high-density vitamin and amino acid specifications calibrated to feed conversion ratio targets. Georgia integrators have adopted encapsulated vitamin technologies at commercial scale since 2022.
- Pork Producers:Consolidated hog finishing operations across Iowa, Minnesota, and North Carolina seeking phytogenic and organic acid premix alternatives as antibiotic growth promoter restrictions expand.
- Dairy Farmers:Wisconsin and New York processor-owned heifer-raising facilities contracting directly for total mixed ration optimization services.
- Aquaculture Operators:Emerging demand from catfish producers in Mississippi Delta and salmonid operations in Pacific Northwest requiring specialized marine-origin mineral formulations.
Poultry farmers command the deepest supplier relationships; aquaculture operators are gaining share fastest.
Form:
Physical presentation determines handling economics, shelf stability, and compatibility with automated feed mill infrastructure.
- Powder:Fine-ground homogeneous blends offering lowest production cost and maximum flexibility for custom formulation, dominant in independent feed mill operations across Kansas and Oklahoma.
- Pellets:Compressed forms reducing dust generation and improving flowability in high-throughput commercial feed manufacturing serving Corn Belt integrators.
- Granules:Intermediate particle size balancing dispersion uniformity with handling convenience for mid-scale dairy operations.
- Liquid:Pumpable suspensions enabling post-pelleting application of heat-sensitive additives, penetrating Texas and California feedlots with automated micro-ingredient dosing systems.
Powder forms retain the largest manufacturing footprint; liquid premix is climbing the fastest.
Distribution Channel:
Channel economics reflect customer scale, geographic density, and regulatory documentation burdens.
- Direct Sales:Manufacturer-to-integrator contracts bypassing distributor margins, consolidating across Wisconsin dairy and Texas cattle feeding regions as procurement authority centralizes.
- Wholesale Distributors:Regional feed ingredient merchants serving independent hog finishers and backgrounding operations with inventory buffering and credit terms.
- Online Sales:Emerging platform-based ordering with real-time formulation tools penetrating tech-adopting poultry operations in Nebraska and Iowa.
- Retail Outlets:Farm supply stores and cooperative locations serving small-scale livestock producers with standard premix SKUs.
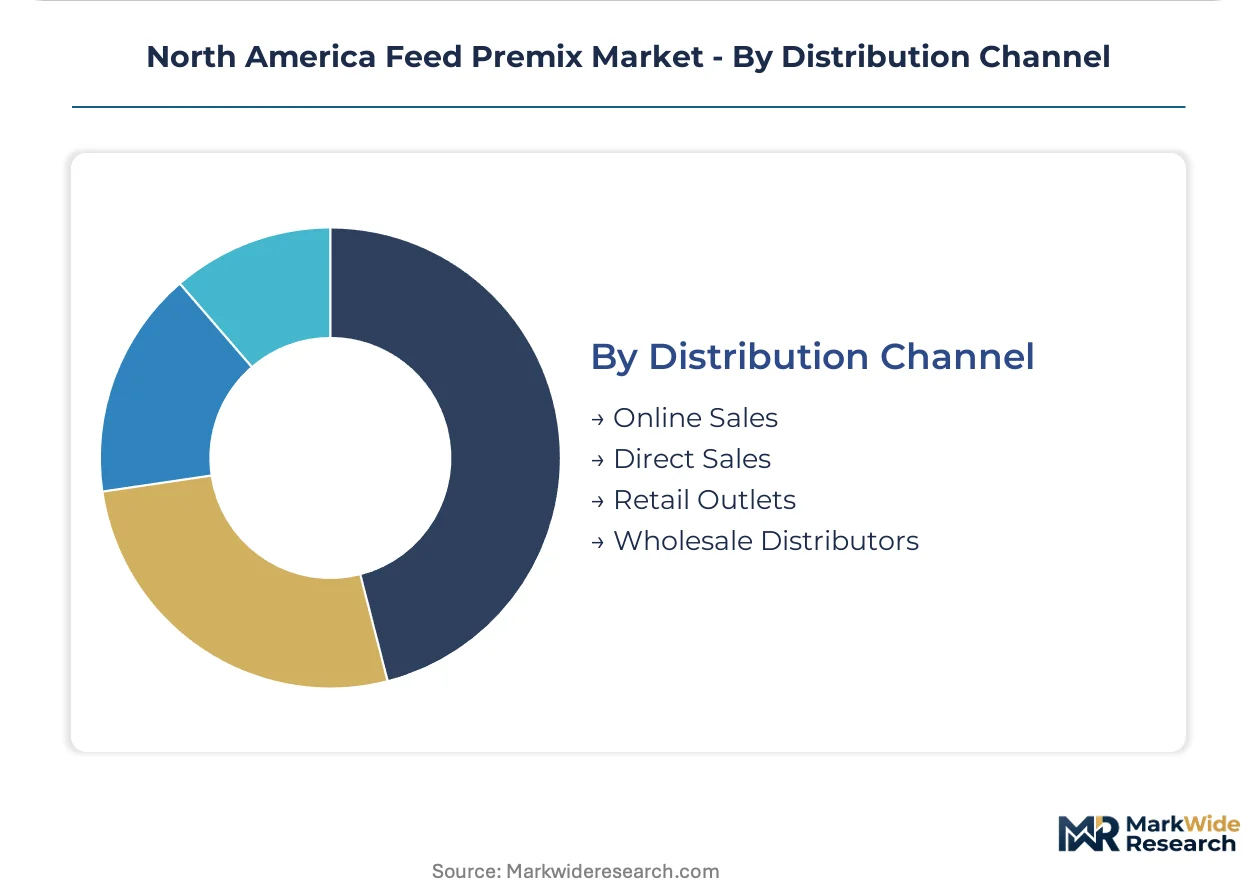
Direct sales channels capture the dominant volume flow; online sales is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of North American feed premix output, while Canadian prairie operations and Mexican poultry corridors represent expanding demand frontiers with distinct regulatory and procurement profiles.
United States
Iowa and Nebraska poultry integrators drive precision nutrition procurement for rapid-growth broiler phases. The FDA Veterinary Feed Directive restricts medically important antibiotics in livestock feed, redirecting formulation investment toward organic acid alternatives. Georgia and Arkansas broiler operations have adopted encapsulated vitamin technologies at commercial scale since 2022.
Canada
Alberta and Saskatchewan feedlot expansion lags U.S. premix sophistication, creating white space for amino acid penetration in backgrounding operations. Health Canada and the Canadian Food Inspection Agency enforce feed safety standards that mirror FDA traceability requirements. Prairie livestock operations concentrate procurement through regional cooperative networks serving dispersed cattle feeding infrastructure.
Mexico
Poultry and swine integrators across Querétaro and Guanajuato states expand commercial-scale finishing capacity. The country's national agricultural regulator enforces feed additive registration requirements that align with North American trade integration. Central Mexico's vertically integrated protein companies consolidate premix sourcing through direct manufacturer contracts bypassing traditional distribution.
North America Feed Premix Market Competitive Landscape
Top-tier vendors anchor the concentrated vitamin and amino acid synthesis tier, while mid-scale mineral blenders and regional distributors occupy fragmented positions downstream. The market structure favors integrated grain originators with captive distribution networks across Midwest production corridors. Strategic archetypes include captive supply chain integrators, specialty antioxidant formulators, and precision nutrition service providers. Competitive moves concentrate on backward integration into vitamin synthesis and geographic expansion through grain elevator co-location.
Within the integrated supply chain tier, Cargill Incorporated and Archer Daniels Midland Company represent the grain-origination-to-premix model, while DSM-Firmenich AG and BASF SE exemplify the specialty chemical synthesis archetype. Kemin Industries Inc occupies a position bridging specialty antioxidant formulation with direct technical service to high-value livestock segments. These anchors demonstrate how competitive positioning stratifies between commodity-scale mineral blending and premium vitamin encapsulation capabilities.
| Leading Market Players |
|---|
| DSM-Firmenich AG |
| Kemin Industries Inc |
| Cargill Incorporated |
| CCPA GROUP |
| Trow Nutrition |
| BASF SE |
| Land O'Lakes Inc |
| Biomin |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Poultry integrator mandates for encapsulated vitamin specifications are forcing premix manufacturers to absorb lipid-matrix coating costs or cede volume to captive suppliers, compressing margin pools for non-integrated formulators across Georgia and Arkansas operations.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Iowa and Nebraska integrators penalize suppliers exceeding 72-hour fulfillment windows. Three-tier pricing structure across premium encapsulated, standard dry-blend, and economy commodity premix levels reflects vitamin stability grade and bioavailability certification. Cost compression in standard dry-blend tiers is intensifying because Chinese vitamin A synthesis feedstock volatility feeds through to spot markets. Independent hog finishers in North Carolina exhibit highest price sensitivity, while processor-owned dairy heifer facilities in Wisconsin accept premium pricing for metabolizable energy guarantees.
Supply Chain Analysis
Domestic-content requirements under the FDA Veterinary Feed Directive and parallel state-level feed safety audits are reshaping sourcing toward verified North American mineral corridors. Supply concentrates in Florida and Idaho phosphate mining operations, with vitamin synthesis anchored in Illinois and New Jersey chemical processing hubs. Raw material dependencies span phosphate rock, vitamin A acetate precursors, and rumen-protected lysine intermediates. Single-source vulnerability in Florida phosphate corridors exposes formulators to hurricane disruption risk. Distribution runs through manufacturer-direct contracts with Corn Belt integrators, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive vitamin encapsulation capabilities separate margin leaders from price-takers. Players are pursuing backward integration into lipid-matrix coating technology to defend positioning.
For Market Incumbents: Hedge against vitamin input volatility through long-term offtake agreements with Illinois synthesis facilities. Lock in exclusive distribution rights across Kansas and Oklahoma grain elevator networks before regional cooperatives consolidate procurement authority. Encapsulation capability scarcity threatens commodity premix suppliers with permanent price-taker status. For New Entrants and Emerging Players: Begin with Alberta and Saskatchewan backgrounding operations where amino acid premix penetration lags U.S. sophistication. Target USDA Organic-certified dairy herds in Vermont and Wisconsin seeking verified non-synthetic mineral chains. Deploy digital formulation-to-farm platforms with real-time near-infrared integration as the primary go-to-market wedge. For Investors and Strategic Acquirers: The window for entry favors specialty antioxidant formulators with captive technical service teams. Over the coming decade, acquisition targets with encapsulated vitamin production assets and direct integrator relationships in the Texas Panhandle will command strategic premiums. Monitor FDA conditional approval narrowing for novel organic acid additives as the inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Encapsulation | Captive lipid-matrix coating capabilities consolidate margin control against Chinese synthesis volatility. |
| Grain Elevator Co-location Expansion | Midwest corridor positioning captures procurement scale effects from Iowa and Nebraska integrators. |
| USDA Organic Certification Investment | Vermont and Wisconsin dairy processor contracts require verified non-synthetic ingredient chain documentation. |
| Digital Platform Integration | Cloud-based premix ordering with real-time NIR analysis bypasses distributor networks in Texas Panhandle poultry. |
| Long-term Metabolizable Energy Contracts | Processor-owned heifer facilities in Wisconsin demand guaranteed performance metrics tied to direct manufacturer relationships. |
Research Methodology
Trade publications, USDA feed safety bulletins, and SEC filings from publicly listed grain processors formed the secondary backbone. Primary interviews with premix formulation chemists, livestock procurement directors at Iowa integrators, FDA regulatory affairs specialists, and regional feed cooperative managers validated demand-side assumptions. Bottom-up volume estimates from state-level livestock inventory data triangulated against top-down premix consumption projections.
Historical trendline analysis of vitamin and amino acid pricing volatility informed growth trajectory modeling across the projection horizon. Segmentation dimensions spanned product type, end-user livestock sector, physical form, and distribution channel structure, with regulatory compliance tier as an additional feed-industry-specific dimension. CAGRs derived from weighted average of input cost trajectories and livestock production forecasts, incorporating EPA nutrient management enforcement intensity and organic livestock inventory expansion as industry-specific forecast inputs.
Feed safety audit expansion, vitamin synthesis feedstock disruption, and integrator procurement consolidation are the dominant revision risks. Forecasts reflect documented assumptions regarding FDA enforcement continuity and Corn Belt livestock inventory stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Asia-Pacific Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
Feed Micronutrients Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Global Medicated Feed Additives Market
Agricultural Chemicals
Asia Pacific Feed Pelletizing Agents Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
Stored Grain Insecticides Market