
 Asia Pacific Feed Pelletizing Agents Market | 2026-2036
Asia Pacific Feed Pelletizing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Feed Pelletizing Agents Market Outlook
Aquaculture is broadening its share of pelletizing agent consumption across the Asia Pacific as marine and freshwater farming operations scale output. BASF SE leverages its specialty chemical portfolio to serve high-density shrimp feed mills in Vietnam and Thailand. Borregaard LignoTech anchors its position through lignin-based binder technology tailored to tropical humidity conditions. Uniscope Inc competes via mineral clay formulations optimized for pelleted aquafeed durability.
Feed pelletizing agents encompass binders, coatings, lubricants, and additives that confer mechanical integrity, moisture resistance, and nutrient protection to compounded feed during extrusion and handling; lignosulfonate and bentonite clay formulations typically achieve pellet durability indices above 90 percent under standardized tumble tests. Binders command the largest volume share due to their essential role in maintaining structural cohesion across high-moisture aquafeed and heat-stressed poultry rations. Liquid formulations are gaining traction among automated feed mills seeking precise dosing control and reduced dust exposure during processing.
China's SAMR enforces GB standards for feed additive safety that directly constrain binder chemistry selections and import eligibility. India's FSSAI and BIS jointly regulate feed quality parameters, compelling domestic mills to certify pelletizing agents for heavy metal limits and binding efficacy. Thailand's national feed safety framework aligns with ASEAN harmonization protocols, creating cross-border compliance complexity for suppliers. Stakeholders must monitor evolving ASEAN feed safety integration timelines and pre-position formulation registrations ahead of mutual recognition agreements.
Market Dynamics
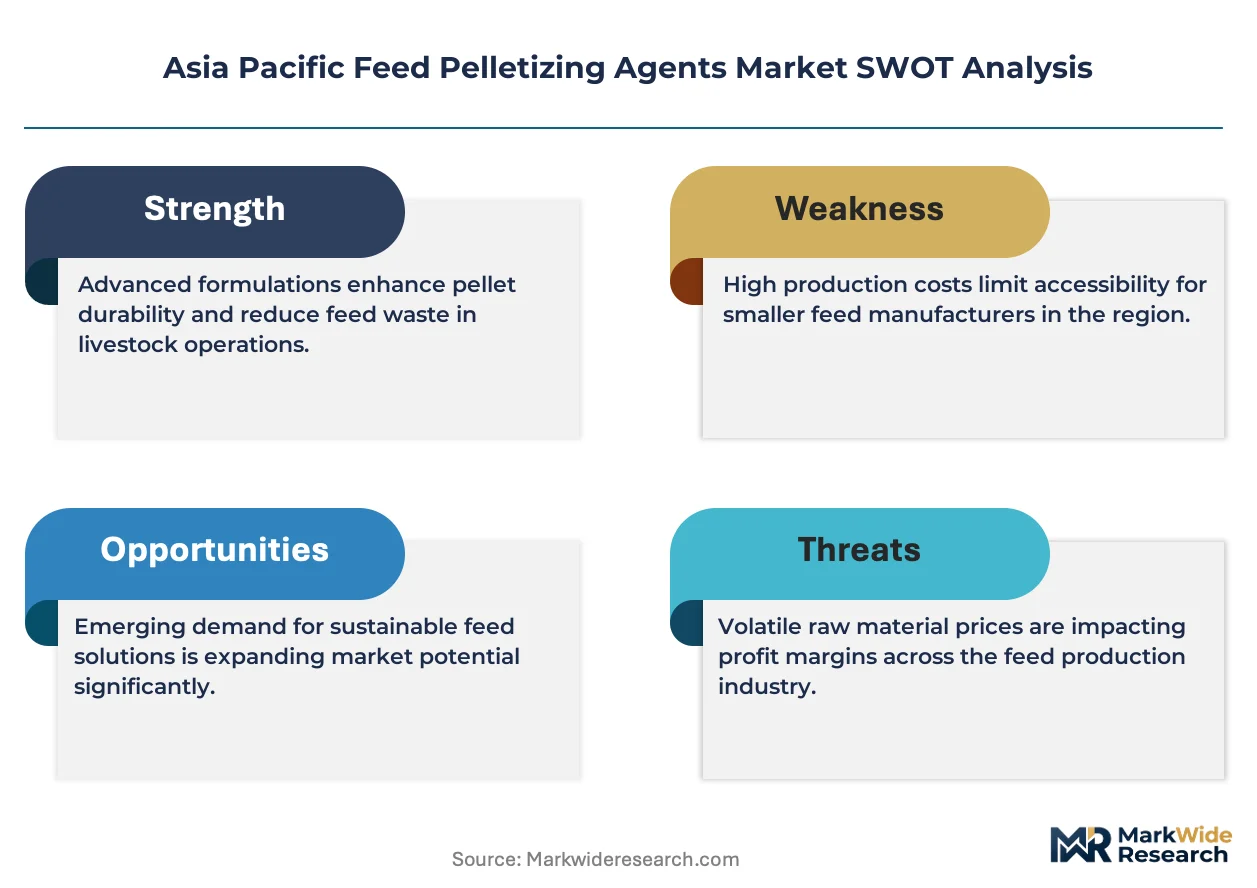
Intensive aquaculture expansion across Southeast Asia is compressing feed mill margins while demanding higher pellet durability under tropical humidity, forcing binder suppliers to reformulate for moisture resistance without cost escalation.
Growth Catalysts
- Shrimp farming intensification:Vietnam's Mekong Delta aquaculture belt is scaling high-density pond systems that require pelletizing agents capable of maintaining structural integrity through extended water immersion cycles.
- FSSAI feed quality mandates:India's binding agent specifications for heavy metal limits are compelling domestic mills to upgrade from conventional clay binders to certified lignosulfonate formulations.
- Extrusion automation:Liquid pelletizing agent dosing systems are penetrating Thailand's commercial feed mills, enabling precise viscosity control and reducing dust exposure during high-temperature processing.
Market Restraints
- Lignin supply concentration:Southeast Asian lignosulfonate procurement depends heavily on pulp mill byproduct streams concentrated in Indonesia and Malaysia, creating input vulnerability during fiber processing disruptions.
- GB standard chemistry constraints:China's SAMR feed additive safety protocols restrict certain synthetic binder chemistries, forcing reformulation cycles that extend product registration timelines.
- Mineral clay substitution pressure:Bentonite alternatives face displacement risk from processed lignin derivatives in premium aquafeed segments where pellet durability indices determine procurement decisions.
Strategic Opportunities
- Philippines aquaculture underpenetration:Mindanao and Visayas marine cage farming operations remain underserved by specialized humidity-resistant binder formulations designed for tropical monsoon conditions.
- ASEAN feed safety harmonization:Mutual recognition agreements under development will enable single-registration market access across Thailand, Vietnam, and Indonesia for compliant pelletizing agent suppliers.
- Smart dosing convergence:Integration of liquid binder systems with IoT-enabled extrusion controls is creating precision agriculture partnerships between chemical suppliers and feed mill automation vendors.
Industry Challenges
- Formulation chemist scarcity:Feed binder R&D talent pools are thinning across Vietnam and Indonesia as agrichemical multinationals compete for specialists capable of tropical stability testing.
- Dual certification timelines:Suppliers seeking simultaneous GB standard compliance and ASEAN harmonized registration face extended validation periods that delay revenue recognition in priority markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Feed Pelletizing Agents Market |
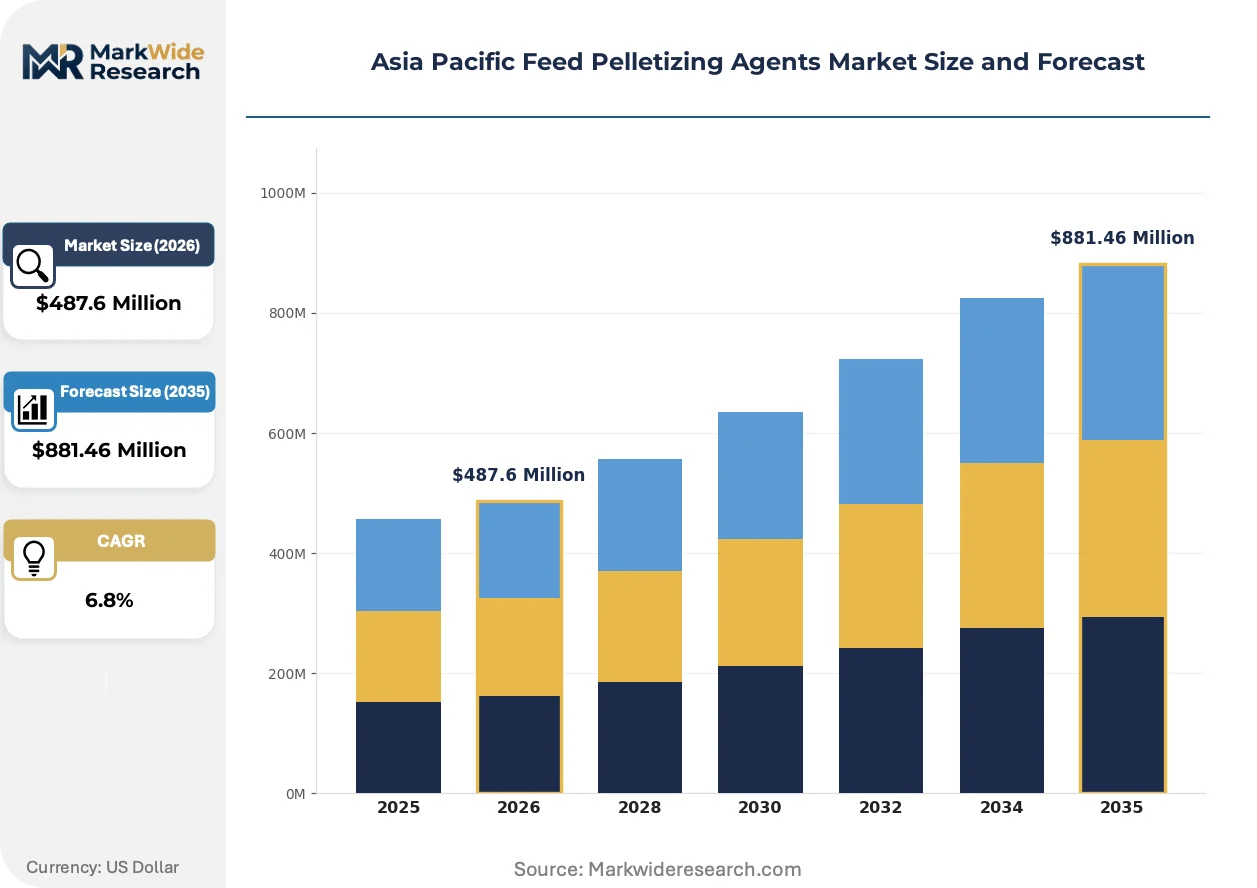
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binders, Coatings, Lubricants, Additives Form: Powder, Liquid, Granular, Paste Application: Agriculture, Livestock, Aquaculture, Pet Food Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Brenntag Group, Ashapura Group, BASF SE, AlAsia Chemical, Uniscope Inc, Archer Daniels Midland Company, Bentonite Performance Minerals LLC, Kiotechagi, Borregaard LignoTech, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Feed Pelletizing Agents Market Strategic Shifts
Enzymatic modification of lignin derivatives is reshaping binder performance benchmarks, while regulatory tightening and procurement centralization are compressing supplier margins and accelerating consolidation among regional distributors.
Modified lignosulfonate formulations with enhanced cross-linking density are electrifying high-end shrimp feed production in Vietnam and Thailand. Mekong Delta processing facilities are adopting these chemistries at accelerating rates to meet export market durability specifications. The technology is electrifying competitive differentiation, compressing price premiums for conventional bentonite binders in premium aquafeed segments.
China's SAMR enforcement of updated GB standards for feed additive safety is constraining import eligibility and domestic formulation choices. Industrial consequence includes accelerated substitution of unregistered synthetic binders with certified lignin-based alternatives. Vietnam-based exporters targeting Chinese aquafeed processors are pre-positioning dual-compliant product registrations ahead of anticipated mutual recognition protocols.
Feed mill procurement consolidation is concentrating binder purchasing decisions among integrated aquaculture conglomerates in Indonesia's poultry corridor and Vietnam's seafood processing zones. Traditional distributor networks face displacement from direct supplier-mill partnerships offering technical service bundled with volume pricing. This pattern is most visible in Thailand's Central Plains, where Charoen Pokphand-style integrated operations are internalizing formulation expertise and squeezing independent chemical distributors.
Asia Pacific Feed Pelletizing Agents Market Segmentation
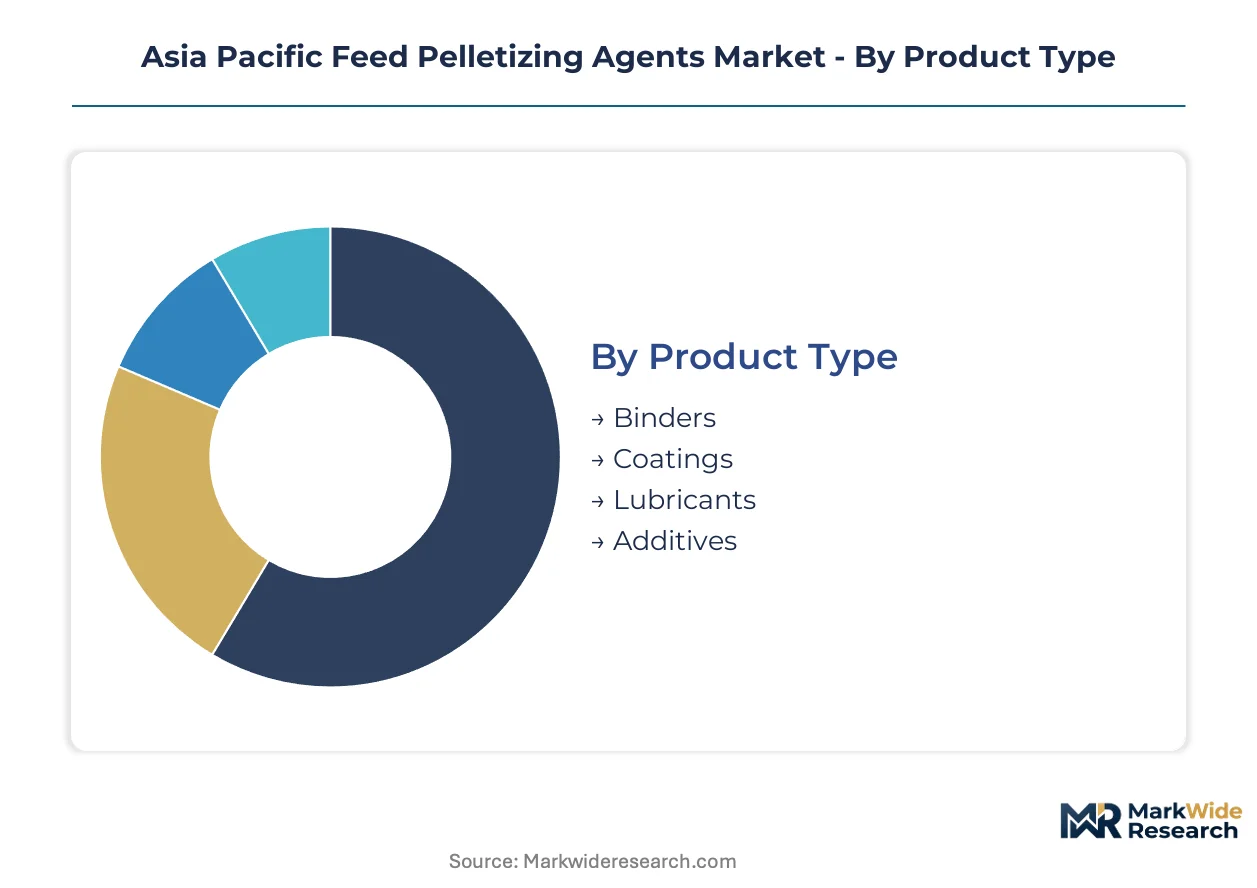
Pelletizing agent procurement in Asia Pacific follows distinct technical and commercial logics that reshape supplier priorities. Feed mills select formulations based on extrusion equipment compatibility, tropical climate resilience, and regulatory compliance pathways rather than commodity pricing alone.
Product Type:
Binders command purchasing attention due to their direct impact on pellet durability indices and export eligibility for finished feed.
- Binders:Lignosulfonate and bentonite clay formulations achieve pellet durability indices above 90 percent under standardized tumble tests. Vietnam's Mekong Delta shrimp feed mills prioritize these chemistries to meet EU and US import durability specifications for extended water immersion cycles.
- Coatings:Surface-applied lipid and polymer barriers protect nutrient integrity during tropical storage and transport. Indonesia's poultry corridor is scaling coating procurement as integrated operations extend feed shelf-life requirements across humid archipelago distribution networks.
- Lubricants:Reduce die wear and energy consumption during high-temperature extrusion.
- Additives:Encompass pH modifiers, anti-caking agents, and flow aids for specialized feed formulations.
Volume sits with binders; growth tilts toward coatings as aquafeed export specifications tighten.
Form:
Physical state determines dosing precision, dust exposure, and automation compatibility across mill infrastructure generations.
- Liquid:Enables precise viscosity control through automated dosing systems integrated with IoT-enabled extrusion controls. Thailand's commercial feed mills are penetrating liquid formulations fastest to reduce dust exposure and enable real-time process adjustments during high-temperature processing.
- Powder:Dominates legacy mill installations across Vietnam and Indonesia where capital replacement cycles lag.
- Granular:Balances flow properties with reduced dust generation for mid-scale operations.
- Paste:Serves niche applications requiring extreme binding strength for high-fat aquafeed formulations.
Procurement is shifting from powder toward liquid as automation investments accelerate.
Application:
End-use specifications diverge sharply between species-specific nutritional requirements and regulatory scrutiny levels.
- Aquaculture:Marine and freshwater farming operations demand moisture-resistant formulations capable of maintaining structural integrity through monsoon storage and extended water immersion. Vietnam and Thailand's export-oriented shrimp feed production anchors regional demand concentration.
- Livestock:Poultry and ruminant feed production across Indonesia's poultry corridor and India's dairy belts prioritizes heat-stress stability and mycotoxin binding capacity.
- Agriculture:Compound feed for swine and specialty species operates on less stringent durability specifications.
- Pet Food:Premium companion animal nutrition commands specialized palatability-enhancing coatings and novel protein binders.
Revenue concentrates in aquaculture; expansion tilts toward pet food as urbanization accelerates.
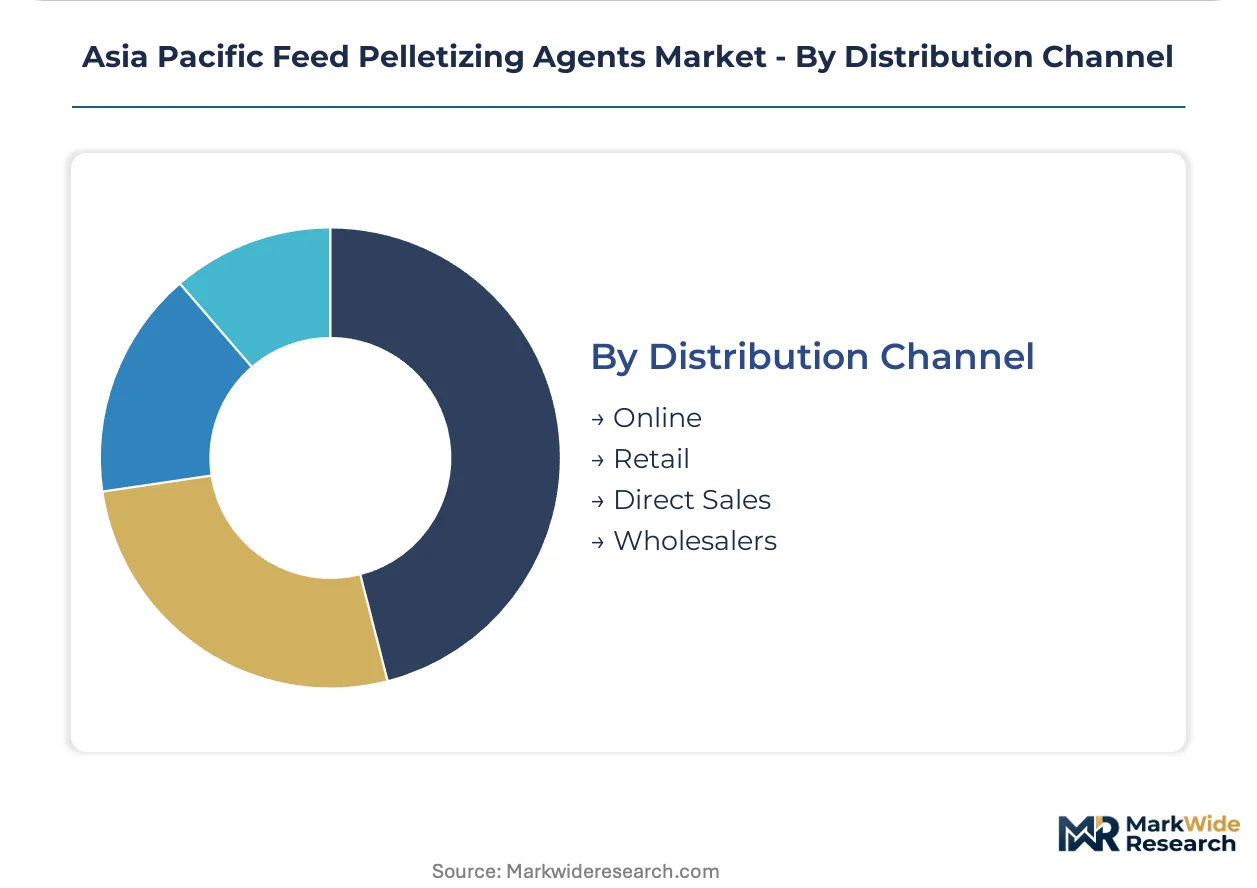
Distribution Channel:
Channel selection reflects mill scale, technical service requirements, and procurement centralization trends.
- Direct Sales:Integrated aquaculture conglomerates in Thailand's Central Plains and Indonesia's poultry corridor are internalizing formulation expertise through technical service partnerships that displace traditional distributor networks.
- Wholesalers:Serve fragmented small and mid-scale mills across the Philippines' Mindanao and Visayas regions where procurement lacks technical sophistication.
- Retail:Caters to micro-scale operations and specialty feed compounders.
- Online:Emerging for standardized commodity binders with established specification clarity.
Transaction flow concentrates through wholesalers; margin capture tilts toward direct sales as consolidation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates feed pelletizing agent production capacity while Vietnam and Thailand absorb disproportionate consumption volumes through export-oriented aquafeed processing. This production-consumption divide shapes procurement patterns and regulatory compliance strategies across the region.
China
SAMR enforces GB standards for feed additive safety that constrain binder chemistry selections and extend product registration timelines. Domestic mills serving the Yangtze River Delta aquaculture belt are substituting unregistered synthetic binders with certified lignin-based alternatives. Shandong Peninsula processing clusters are pre-positioning dual-compliant formulations ahead of anticipated ASEAN mutual recognition protocols.
Vietnam
Mekong Delta shrimp feed mills are scaling high-density pond systems that demand pelletizing agents capable of maintaining structural integrity through extended water immersion cycles. The country's national feed safety framework aligns with ASEAN harmonization protocols, creating cross-border compliance complexity for suppliers. Can Tho and An Giang provinces anchor regional demand concentration as export-oriented processing expands.
Thailand
Commercial feed mills across the Central Plains are penetrating liquid pelletizing agent dosing systems fastest to reduce dust exposure and enable real-time process adjustments. The national feed safety framework integrates ASEAN protocols while maintaining distinct local registration requirements. Charoen Pokphand-style integrated operations are internalizing formulation expertise and squeezing independent chemical distributors.
Indonesia
Poultry corridor operations across Java are scaling coating procurement as integrated operations extend feed shelf-life requirements across humid archipelago distribution networks. Lignosulfonate procurement depends heavily on pulp mill byproduct streams concentrated in Sumatra and Kalimantan, creating input vulnerability during fiber processing disruptions. Surabaya and Medan processing clusters are consolidating binder purchasing decisions among integrated aquaculture conglomerates.
India
FSSAI and BIS jointly regulate feed quality parameters, compelling domestic mills to certify pelletizing agents for heavy metal limits and binding efficacy. Dairy belt operations across Gujarat and Maharashtra are upgrading from conventional clay binders to certified lignosulfonate formulations. Haryana and Punjab poultry feed processors are navigating dual certification timelines that delay revenue recognition for compliant suppliers.
Asia Pacific Feed Pelletizing Agents Market Competitive Environment
Top-tier vendors anchor the specialty chemical segment, while regional distributors and mineral clay suppliers occupy mid-market and commodity tiers. The vendor base stratifies across three functional layers: multinational chemical conglomerates with tropical stability R&D capabilities, lignin derivative specialists leveraging pulp mill integration, and mineral processing firms competing on bentonite volume pricing. Strategic moves concentrate on direct technical service partnerships with integrated feed mills and enzymatic modification licensing for enhanced cross-linking density.
Within the lignin-based specialization tier, Borregaard LignoTech and BASF SE exemplify divergent approaches to tropical humidity resilience. Among mineral clay processors, Bentonite Performance Minerals LLC occupies a position tied to legacy mill infrastructure across Vietnam and Indonesia. Uniscope Inc represents the mid-scale formulation specialist archetype, sitting between commodity mineral suppliers and premium chemical innovators. These three anchors illustrate how procurement centralization is compressing margins for distributors while rewarding direct supplier-mill relationships.
| Leading Market Players |
|---|
| Brenntag Group |
| Ashapura Group |
| BASF SE |
| AlAsia Chemical |
| Uniscope Inc |
| Archer Daniels Midland Company |
| Bentonite Performance Minerals LLC |
| Kiotechagi |
| Borregaard LignoTech |
| Others |
Value Chain & Pricing Dynamics
Pulp mill byproduct indices for lignosulfonate and bentonite clay benchmarks cascade through Asia Pacific feed pelletizing agent supply chains, concentrating pricing power among integrated pulp-chemical suppliers while fragmenting bargaining leverage for standalone mineral processors serving Vietnam's Mekong Delta mills.
Pricing Analysis
Cost-down pressure on standard-grade binders accelerates because Indonesia's pulp corridor mills are internalizing lignin derivative output for captive aquafeed chemical production. Three-tier pricing structure across premium enzymatic-modified lignosulfonate, certified standard lignin, and unmodified bentonite separates procurement decisions by export eligibility tier. Vietnam's shrimp feed exporters exhibit lowest price sensitivity due to EU durability mandates, while India's domestic poultry mills face acute margin compression from FSSAI heavy-metal certification costs.
Supply Chain Analysis
Regional distribution centers in Surabaya, Bangkok, and Ho Chi Minh City anchor hub-and-spoke patterns radiating toward Mekong Delta processing clusters and Central Plains integrated operations. Lignosulfonate supply concentrates in Indonesia's Sumatra pulp belt and Malaysia's fiber processing zones, while bentonite extraction centers on India's Gujarat deposits and China's Inner Mongolia reserves. Single-source vulnerability pervades tropical-modified binder formulations where enzymatic cross-linking technology remains concentrated among three specialty chemical licensors. Distribution runs through direct mill partnerships displacing traditional chemical distributor networks across Thailand and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feed pelletizing agent competition is becoming a vertical-integration race as specialty chemical houses pursue backward control over pulp mill byproduct streams to secure lignin supply certainty against Indonesian fiber processing volatility.
For Market Incumbents: Deploy enzymatic modification licensing to lock in premium-tier pricing before ASEAN harmonization flattens certification premiums. BASF SE and Borregaard LignoTech should extend technical service teams into Vietnam's Can Tho processing corridor to defend against emerging Indian clay processors. Capacity addition in Indonesia's Sumatra pulp belt would neutralize raw material disruption threats from Malaysian fiber supply volatility. For New Entrants and Emerging Players: Digital channel partnerships with IoT-enabled extrusion control vendors offer the lowest-friction entry path for liquid binder dosing systems. Mindanao marine cage operations remain the most penetrable geography, lacking humidity-resistant formulation access despite scaling export-oriented production. White-space capture demands positioning enzymatic lignin alternatives at mid-tier pricing against incumbent mineral clay incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Vietnamese formulation specialists with dual GB-ASEAN registration progress but liquidity constraints from extended certification timelines. Long-term viability hinges on lignin supply integration rather than standalone R&D capability. Watch for SAMR-ASEAN mutual recognition protocol announcements as the inflection signal triggering consolidation premiums for pre-registered suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Mill Byproduct Streams | Captive lignin supply from Indonesia's Sumatra fiber processors neutralizes raw material disruption risk for aquafeed binder production. |
| Enzymatic Modification Licensing Program | Technology transfer agreements with Vietnam's Mekong Delta mills accelerate premium-tier penetration against conventional bentonite alternatives. |
| Dual GB-ASEAN Registration Pre-Positioning | Simultaneous compliance with China's SAMR standards and ASEAN harmonization protocols unlocks cross-border market access ahead of mutual recognition. |
| IoT-Enabled Liquid Dosing System Partnerships | Integration with Thailand's automated extrusion control vendors creates precision agriculture positioning for high-volume commercial feed mills. |
| Technical Service Team Expansion | Dedicated formulation support in Vietnam's Can Tho and An Giang provinces defends incumbent share against Indian mineral clay entrants. |
Study Parameters
Document review covered customs trade databases for lignosulfonate and bentonite flows, complemented by interviews with feed mill procurement directors, specialty chemical R&D leads, pulp mill byproduct sales managers, and ASEAN regulatory affairs specialists. Secondary validation drew from SAMR GB standard filings, FSSAI feed additive registrations, BIS quality certifications, and Vietnam's national feed safety framework documentation. Bottom-up volume estimates from individual mill consumption patterns were triangulated against top-down regional production capacity assessments.
Market size and growth trajectories across the projection horizon reflect segment-level modeling by product type, application species, physical form, and distribution channel. The analytical framework incorporated aquafeed export volume forecasts, poultry production expansion rates, and pet food urbanization indices as demand-side drivers. CAGRs were derived from regression analysis against historical binder intensity ratios and regulatory compliance cost trajectories.
The model holds under stable ASEAN harmonization timelines and continued pulp mill byproduct availability; deviation in SAMR enforcement intensity or Indonesian fiber processing disruptions would shift volume and value outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
South America Soil Treatment Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market