
 Global Cattle Feed and Feed Additives Market | 2026-2036
Global Cattle Feed and Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cattle Feed and Feed Additives Market Analysis
A shift from single-source to multi-source additive procurement is consolidating among large compounders. Cargill, Incorporated leverages its North American grain origination network to secure base-feed cost advantages. BASF SE anchors its position through synthetic vitamin A and E production scale. DSM differentiates via its premix and precision-nutrition services for dairy herd optimization.
Cattle feed and feed additives comprise formulated rations and functional micro-ingredients designed to optimize rumen fermentation, nutrient absorption, and animal health outcomes, typically incorporating 40-60% forage bases with protein meals, mineral premixes, and fermentation enhancers. Complete feed formulations command the largest revenue pool due to turnkey convenience for commercial feedlots, while probiotic additives represent the fastest-expanding category as livestock operators phase out growth-promotion antibiotics. Enzyme-enhanced concentrates capture premium margins in high-performance dairy systems where feed-conversion efficiency directly governs milk-yield economics.
The EU Green Deal's Farm to Fork Strategy, enforced by EFSA and national veterinary regulators, mandates measurable antibiotic reduction in cattle operations and reshapes additive demand toward microbiome-modulating alternatives. The US FDA's Veterinary Feed Directive continues restricting medically important antibiotics in feed, pushing producers toward mineral-vitamin fortification and ionophore alternatives. Stakeholders must monitor evolving residue-testing protocols and carbon-accounting requirements that will determine which additive categories retain formulation access across major beef and dairy supply chains.
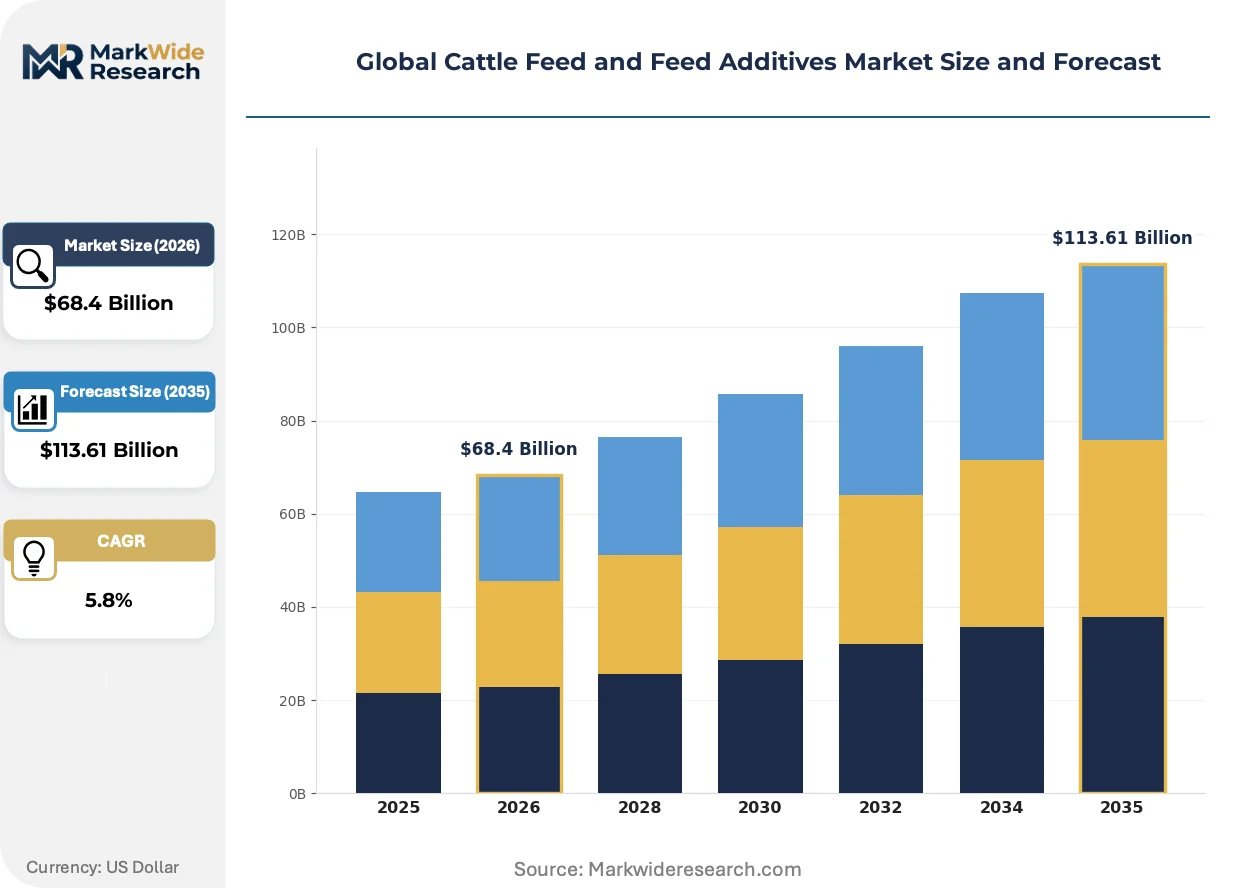
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing antibiotic use timelines across cattle operations, forcing feed compounders to reconfigure formulation portfolios toward microbiome-modulating alternatives before enforcement deadlines crystallize.
Growth Catalysts
- Precision-feeding infrastructure:Dairy cooperatives in the Netherlands are deploying sensor-based ration optimization systems that reduce feed waste and improve milk-yield consistency.
- EFSA antibiotic-reduction mandates:The EU Green Deal's tightening residue thresholds are redirecting additive procurement toward probiotic and enzyme-based growth promoters.
- Brazilian ranching belt concentration:Mato Grosso's commercial feedlot expansion is generating concentrated demand for complete feed formulations and mineral premixes.
Market Restraints
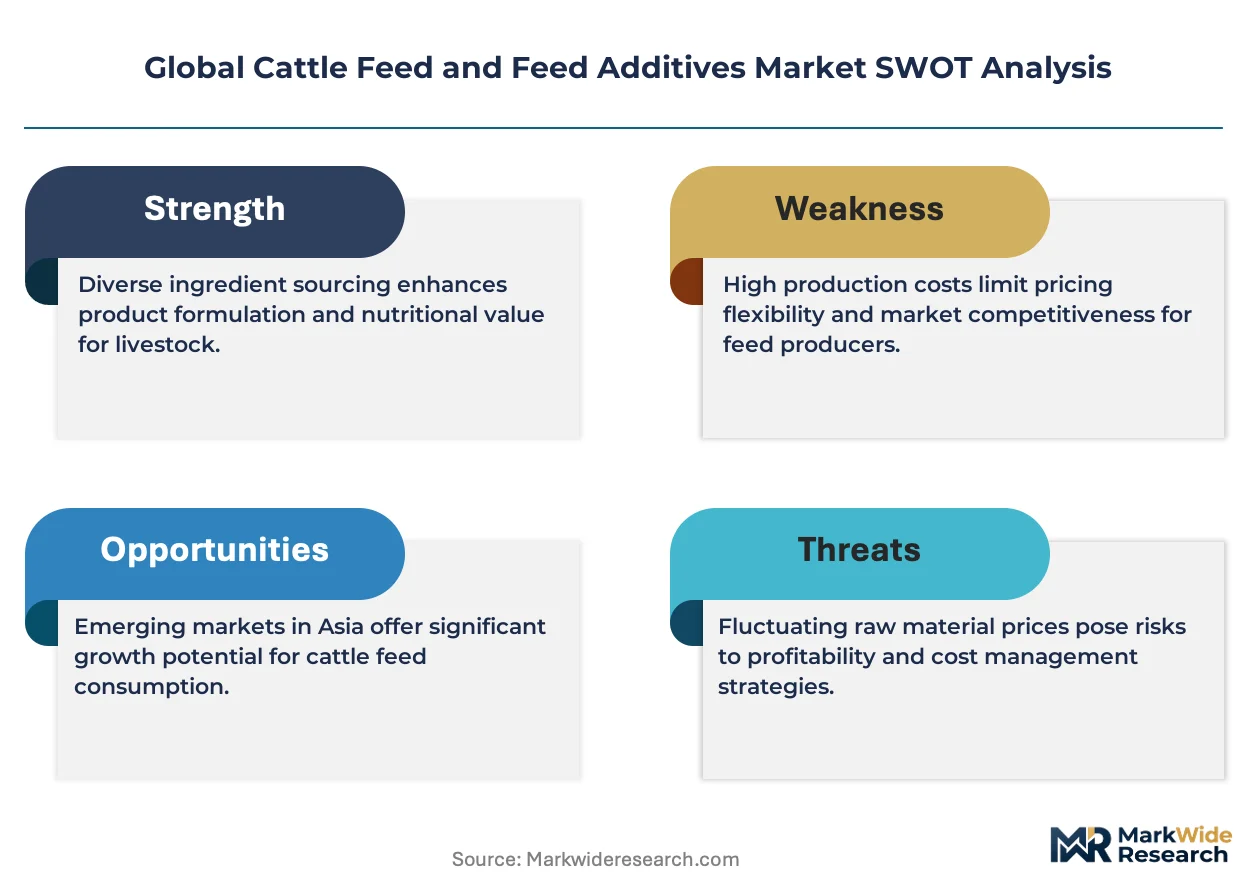
- Soybean meal price volatility:Base protein costs swing with South American harvest cycles and export policy shifts from Argentina and Brazil.
- Synthetic vitamin supply concentration:Vitamin A and E production clusters in China and Germany create single-source vulnerability for premix manufacturers.
- FDA Veterinary Feed Directive friction:Medically important antibiotic restrictions complicate herd health management for US cattle operators transitioning off growth-promotion protocols.
Strategic Opportunities
- Carbon-accounting integration:The EU Green Deal's emerging feed-carbon scoring requirements create first-mover advantage for suppliers with verified low-emission additive portfolios.
- Smallholder dairy penetration:India's cooperative dairy sector remains underpenetrated by precision-nutrition services, offering white-space for premix distributors.
- Enzyme-probiotic convergence:Rumen fermentation enhancers combining fibrolytic enzymes with live cultures are opening premium formulation tiers in high-performance dairy systems.
Industry Challenges
- Ruminant nutritionist scarcity:Precision-feeding program expansion outpaces qualified personnel supply, particularly for microbiome-modulation expertise.
- Multi-jurisdiction residue compliance:Cattle operators exporting to both EU and US markets face divergent maximum residue limit protocols from EFSA and FDA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cattle Feed and Feed Additives Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Concentrated Feed, Supplementary Feed, Medicated Feed Feed Additive Type: Vitamins, Minerals, Probiotics, Enzymes Livestock Type: Cattle, Dairy Cows, Beef Cattle, Calves Form: Pellets, Powder, Liquid, Granules |
| Companies Covered | Cargill, Incorporated, BASF SE, DSM, Evonik Industries AG, Archer Daniels Midland Company, Nutreco, ADM, Alltech, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cattle Feed and Feed Additives Market Emerging Trajectories
Formulation science is pivoting from single-function additives toward integrated rumen-health platforms, while regulatory pressure and procurement rationalization are compressing supplier bases toward technical-service-capable partners.
Precision-livestock monitoring hardware paired with algorithmic ration adjustment is decentralizing nutrition decision-making from centralized feed-mill formulators toward on-farm managers. Large dairy cooperatives in Denmark and the Netherlands are deploying these systems at commercial scale. The technology is decentralizing feed advisory relationships and compressing margins for traditional premix distributors who lack data-integration capabilities.
REACH registration requirements for novel feed additives are tightening toxicological data standards across European compounders. The regulation is extending product development timelines by 18-24 months for microbiome-modulating candidates. Enzyme-enhanced concentrates face the steepest compliance burden, pushing some suppliers toward GRAS-equivalent pathways in the US market.
Compound feed procurement is consolidating toward multi-year supply agreements with embedded technical-service clauses. Large Brazilian feedlots are displacing spot-market purchasing with performance-guaranteed contracts tied to feed-conversion metrics. This pattern is most visible in Mato Grosso, where integrated operators now specify additive inclusion rates rather than accepting standard formulations.
Global Cattle Feed and Feed Additives Market Segmentation
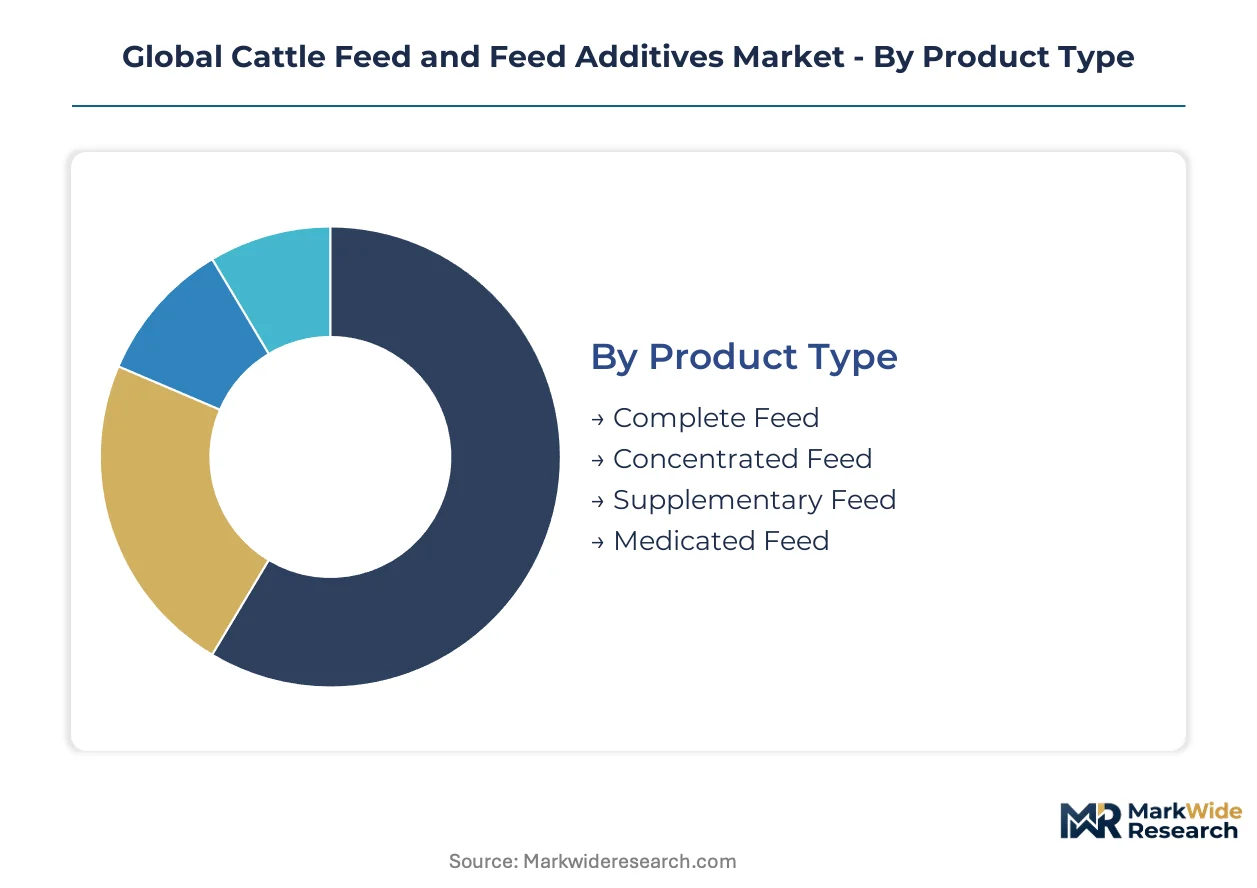
Segmentation in the cattle feed and feed additives market determines procurement patterns, margin structures, and regulatory exposure across distinct value chain tiers. Compounders configure production assets and technical service capabilities around specific product formats and livestock categories.
Product Type:
Supply concentration among large compounders favors turnkey formulations that embed technical advisory services and lock in multi-year offtake agreements.
- Complete Feed:Fully formulated rations incorporating 40-60% forage bases with protein meals, mineral premixes, and fermentation enhancers in ready-to-feed format. Demand concentrates in Brazil's Mato Grosso commercial feedlots where integrated operators specify additive inclusion rates rather than accepting standard formulations. This segment commands the largest revenue pool due to procurement consolidation toward performance-guaranteed contracts.
- Concentrated Feed:Nutrient-dense formulations requiring dilution with on-farm forages, typically 20-40% protein content with vitamin-mineral fortification. Dairy cooperatives in the Netherlands deploy these in sensor-based ration optimization systems that reduce feed waste and improve milk-yield consistency.
- Supplementary Feed:Targeted nutrient top-dressings for specific deficiency correction or production phase support.
- Medicated Feed:Therapeutic formulations incorporating approved veterinary pharmaceuticals under prescription protocols.
Today's leader: Complete Feed. Tomorrow's challenger: Concentrated Feed.
Feed Additive Type:
Cost tier stratification separates commodity mineral inputs from premium fermentation-modulating technologies that command formulation advisory fees.
- Vitamins:Synthetic fat-soluble and water-soluble micronutrients produced at scale for premix fortification, with vitamin A and E production clustering in China and Germany creating single-source vulnerability. EFSA antibiotic-reduction mandates redirect procurement toward microbiome-modulating alternatives that displace growth-promotion protocols.
- Minerals:Macro and trace element compounds for metabolic function and bone development, sourced through mining and chemical processing operations.
- Probiotics:Live microbial cultures for rumen fermentation optimization, representing the fastest-expanding category as livestock operators phase out growth-promotion antibiotics.
- Enzymes:Fibrolytic and proteolytic proteins for feed-conversion efficiency enhancement in high-performance dairy systems.
Probiotics gain share fastest; vitamins defend volume leadership through premix integration.
Livestock Type:
Application-specific nutrition requirements drive divergent formulation priorities across production systems with distinct economic metrics and health protocols.
- Cattle:Broad category encompassing mixed beef and dairy operations with generalized nutritional protocols.
- Dairy Cows:High-metabolism lactating animals requiring precision energy-protein balancing for milk-yield optimization. Denmark's cooperative sector deploys algorithmic ration adjustment at commercial scale, decentralizing nutrition decision-making toward on-farm managers.
- Beef Cattle:Feedlot-finished animals where feed-conversion efficiency governs margin economics and ionophore alternatives reshape additive demand.
- Calves:Pre-ruminant and transition-phase animals requiring specialized starter formulations and gut-development support.
Dairy Cows anchor additive value capture; Beef Cattle drive volume throughput.
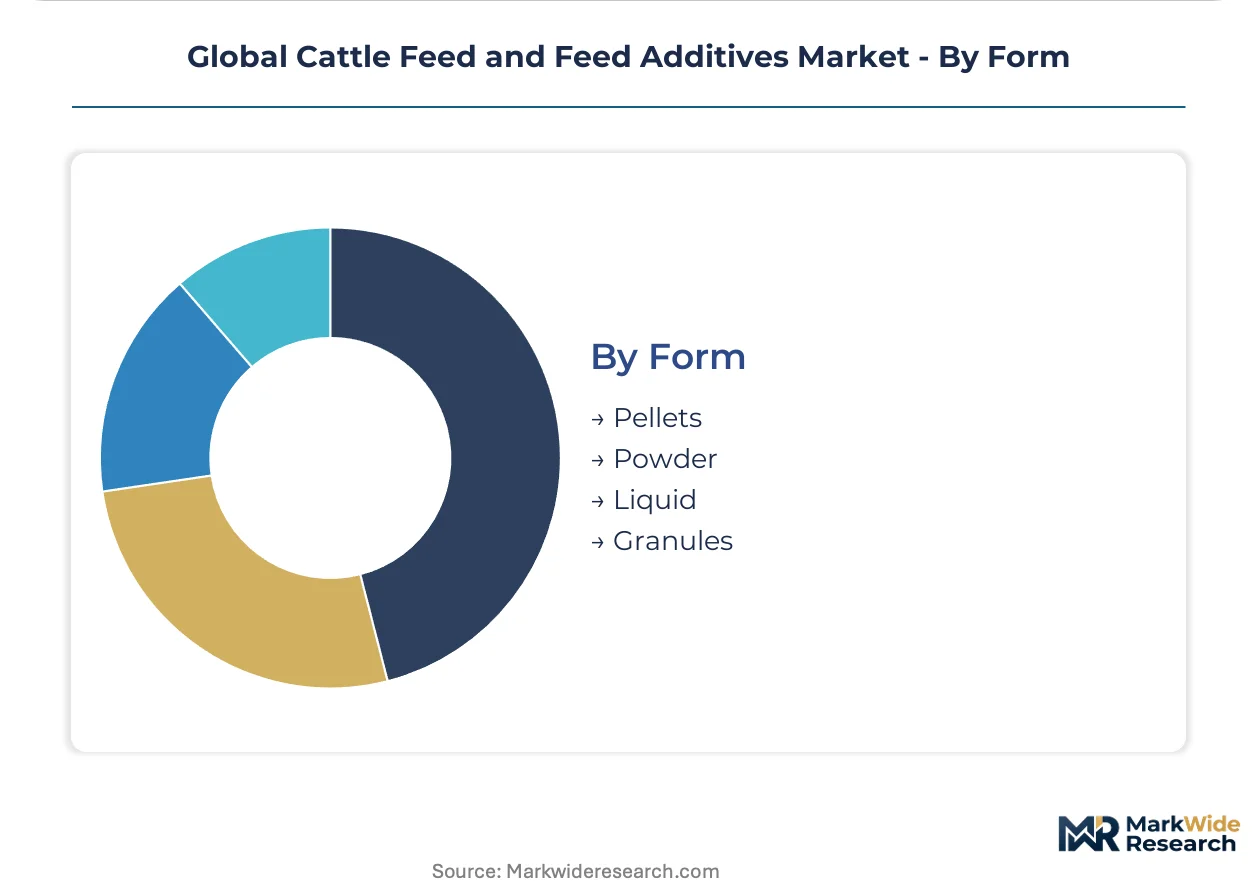
Form:
Manufacturing asset configuration and logistics economics determine format prevalence across distribution distances and farm storage capabilities.
- Pellets:Compressed cylindrical feed units with reduced dust, improved palatability, and controlled nutrient density for mechanized feeding systems.
- Powder:Fine-ground formulations for liquid suspension or top-dressing applications, common in mineral premix and enzyme delivery.
- Liquid:Aqueous suspensions and emulsions for automated dosing systems and trough administration, expanding in precision-feeding infrastructure.
- Granules:Intermediate particle size between pellets and powder, offering flowability without compression energy costs.
Pellets dominate commercial feedlot procurement; Liquid climbs fastest in automated dairy systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing cattle feed production capacity toward jurisdictions with lower compliance burdens and abundant feedstock access. Producers migrate operations where antibiotic-restriction timelines remain permissive and grain origination costs compress formulation economics.
United States
Commercial feedlot concentration in Texas Panhandle and Kansas generates concentrated demand for ionophore alternatives and mineral-vitamin fortification. FDA Veterinary Feed Directive restrictions on medically important antibiotics reshape procurement toward microbiome-modulating additives. Large integrators in Nebraska and Iowa now specify additive inclusion rates tied to feed-conversion guarantees.
Brazil
Mato Grosso's cattle ranching belt anchors South American demand for complete feed formulations and mineral premixes. ANVISA maintains less restrictive antibiotic frameworks than EFSA, attracting formulation investment from suppliers facing European compliance compression. Integrated operators in São Paulo state displace spot-market purchasing with performance-guaranteed supply contracts.
Netherlands
Dairy cooperatives deploy sensor-based ration optimization systems that reduce feed waste and improve milk-yield consistency. EFSA antibiotic-reduction mandates under EU Green Deal Farm to Fork Strategy redirect additive procurement toward probiotic and enzyme-based growth promoters. Friesland and Gelderland clusters concentrate precision-nutrition service providers serving high-performance dairy systems.
China
Domestic dairy herd expansion in Hebei and Shandong provinces drives demand for vitamin-mineral premix fortification. SAMR and MEE regulations on veterinary drug residues tighten enforcement timelines, forcing compounders toward fermentation-enhancer alternatives. Synthetic vitamin A and E production clusters in Jiangsu and Zhejiang create supply concentration for regional premix manufacturers.
India
Cooperative dairy sector penetration in Gujarat and Maharashtra remains underdeveloped for precision-nutrition services, offering white-space for premix distributors. FSSAI and BIS standards on feed quality create compliance differentiation for organized compounders against unorganized suppliers. Punjab's commercial dairy operations show early adoption of algorithmic ration adjustment technologies.
Global Cattle Feed and Feed Additives Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue microbiome-modulation and carbon-accounting certification as differentiation vectors. Market structure consolidates around large compounders with captive grain origination networks and technical-service capabilities. Three archetypes dominate: integrated agribusiness conglomerates with backward feedstock control, specialty additive manufacturers with fermentation-science expertise, and regional premix distributors with cooperative dairy relationships. Competitive intensity centers on multi-year supply agreements with embedded performance guarantees and geographic expansion into underpenetrated smallholder dairy markets.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven compounders with North American grain origination advantages. BASF SE anchors the synthetic vitamin production segment through manufacturing scale in China and Germany. DSM represents the precision-nutrition services archetype, with premix and herd-optimization advisory capabilities concentrated in European dairy markets.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| DSM |
| Evonik Industries AG |
| Archer Daniels Midland Company |
| Nutreco |
| ADM |
| Alltech |
| Kemin Industries |
| Others |
Supply Flow & Price Mechanics
Soybean meal price volatility cascades through formulation economics, compressing margins for premix manufacturers in Germany and China while Brazilian feedlots exploit South American harvest cycles to lock in multi-year offtake agreements below spot-market thresholds.
Pricing Analysis
Input-cost pass-through from vitamin A and E production clusters in Jiangsu and Zhejiang determines premix pricing tiers, with synthetic micronutrient volatility feeding directly into complete feed quotations. Three-tier pricing structure across premium, standard, and economy levels separates enzyme-enhanced concentrates with feed-conversion guarantees from commodity mineral fortification and unbranded base rations. Cost compression in standard-tier formulations is intensifying because Brazilian and Argentine export policy shifts destabilize protein meal procurement budgets. Smallholder dairy cooperatives in Gujarat and Maharashtra exhibit highest price sensitivity, while integrated Mato Grosso feedlots prioritize performance-guaranteed contracts over unit cost minimization.
Supply Chain Analysis
Regional distribution centers in São Paulo and Campinas anchor hub-and-spoke patterns serving Mato Grosso's commercial feedlot belt, with liquid additive suspensions dispatched through automated dosing infrastructure at cooperative dairy clusters in Friesland. Geographic supply concentration clusters synthetic vitamin production in China and Germany, probiotic culture fermentation in Denmark and the Netherlands, and protein meal crushing in Argentina and Brazil. Raw material dependencies draw from South American soybean harvests, Australian phosphate rock, and Chinese vitamin synthesis capacity. Single-source vulnerability in vitamin A and E manufacturing creates supply chain risk exposure for premix compounders. Distribution runs through performance-guaranteed multi-year contracts displacing spot-market purchasing among large Brazilian integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cattle Feed and Feed Additives Market functions as a geographic-arbitrage play, with EFSA antibiotic-reduction mandates compressing European formulation timelines while ANVISA's permissive frameworks in Brazil attract supplier investment seeking regulatory relief.
For Market Incumbents: Hedge against microbiome-modulation capability scarcity by acquiring fermentation-science specialists in Denmark and the Netherlands before REACH registration timelines extend development cycles. Backward integration into captive vitamin A and E production in Jiangsu or Zhejiang reduces exposure to Chinese supply concentration. Defensive patent positioning around enzyme-probiotic convergence formulations protects premium tier pricing against emerging biotech entrants. For New Entrants and Emerging Players: Precision-nutrition algorithm platforms offer technology-first wedge penetration into India's underdeveloped cooperative dairy sector, where FSSAI compliance differentiation displaces unorganized suppliers. Target Gujarat and Maharashtra dairy cooperatives with sensor-based ration optimization services bundled with mineral premix distribution. Direct-to-farm technical advisory relationships bypass established premix distributor networks compressed by precision-livestock monitoring decentralization. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration burdens and carbon-accounting certification requirements outstrip mid-cap R&D budgets, creating distressed acquisition opportunities among European specialty additive manufacturers. Long-term viability favors compounders with verified low-emission additive portfolios and embedded technical-service capabilities in high-performance dairy systems. Acquisition target archetype: regional premix distributors with cooperative dairy relationships in underpenetrated smallholder markets. Monitor EFSA enforcement timeline crystallization as inflection indicator for microbiome-modulating additive demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Accounting Certification Program | EU Green Deal feed-carbon scoring requirements favor suppliers with verified low-emission portfolios. |
| Backward Integration into Vitamin Synthesis | Captive production of synthetic A and E in China or Germany reduces single-source supply vulnerability. |
| Precision-Nutrition Service Launch | Algorithmic ration adjustment capabilities displace traditional premix distributors in Netherlands dairy cooperatives. |
| Long-Term Supply Agreement | Performance-guaranteed contracts with feed-conversion metrics displace spot purchasing in Mato Grosso feedlots. |
| Joint Venture in Enzyme-Probiotic Convergence | Rumen fermentation enhancers combining fibrolytic enzymes with live cultures capture premium dairy system margins. |
Methodological Framework
Multiple input streams — structured interviews with compound feed procurement managers, fermentation-science R&D directors, and cooperative dairy nutrition advisors; secondary validation through ANVISA regulatory filings, EFSA guidance documents, and customs trade data; plus SEC 10-K disclosures from integrated agribusiness conglomerates — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates and supply-side capacity assessments.
Data-stream reconciliation across product type, feed additive category, livestock application, and geographic production cluster dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment growth rate reconciliation against macro livestock herd expansion forecasts and regulatory enforcement timeline assumptions. Industry-specific forecast inputs incorporated EFSA antibiotic-reduction mandate implementation schedules and Mato Grosso commercial feedlot capacity buildout trajectories.
The model holds under stable regulatory enforcement timelines and intact South American harvest cycles; deviation in EU Green Deal Farm to Fork Strategy acceleration or Argentine export policy shocks would shift additive demand trajectories and protein meal cost structures. Forecasts reflect documented assumptions regarding REACH registration completion rates and precision-livestock monitoring adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
US Home and Garden Fungicides Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
Triazole Fungicides Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
North America Agricultural Disinfectants Market
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
South America Feed Antibiotics Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
Agriculture Micronutrients Market