
 Global Carbofuran Market | 2026-2036
Global Carbofuran Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbofuran Market Analysis
Neonicotinoid alternatives is broadening the niche economics for carbofuran in regions where ban cascades have not yet fully displaced systemic insecticides. Bayer CropScience leverages its legacy registration portfolio to sustain access in markets with phased restriction timelines. FMC Corporation anchors its position through specialized granular formulations for soil-applied nematode control. UPL Ltd. competes on cost-adjusted supply chains across South Asian agricultural belts.
Carbofuran is a methylcarbamate insecticide-nematicide with a molecular weight of 221.25 g/mol, formulated typically as 3% or 5% granular products or 400 g/L emulsifiable concentrates for soil and foliar application against chewing and sucking pests. The compound functions as a cholinesterase inhibitor, delivering rapid knockdown in high-value row crops and protected vegetables where contact toxicity remains commercially justified. Granular formulations command the largest volume share due to their reduced operator exposure profile and targeted root-zone delivery, while liquid emulsifiable concentrates retain relevance in orchard and ornamental systems requiring precision spraying. Wettable powder formulations face structural decline as suspended concentrates and soluble granules displace them in distributor inventories, driven by convenience metrics and drift-reduction compliance.
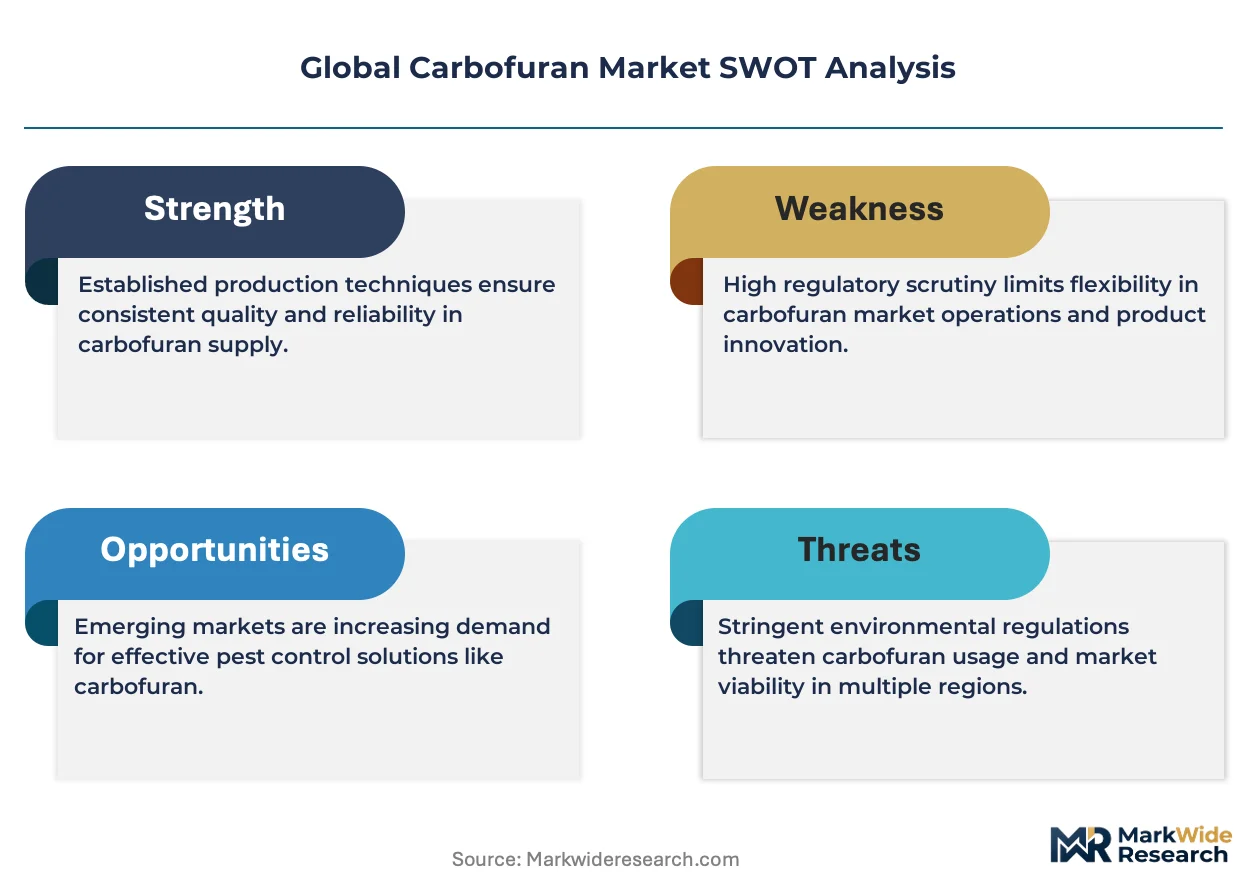
The US EPA maintains restricted-use classification for carbofuran products, requiring certified applicator oversight and buffering near water bodies, while India's Central Insecticides Board imposes residue tolerance ceilings that shape import and domestic formulation decisions. Brazil's ANVISA and the EU's ECHA have both advanced prohibition schedules that progressively narrow the addressable market for legacy carbamate chemistries. Stakeholders must monitor regulatory divergence between jurisdictions with active tolerance reviews and those grandfathering existing registrations, as this polarity will determine where manufacturing assets retain viable deployment horizons.
Market Dynamics
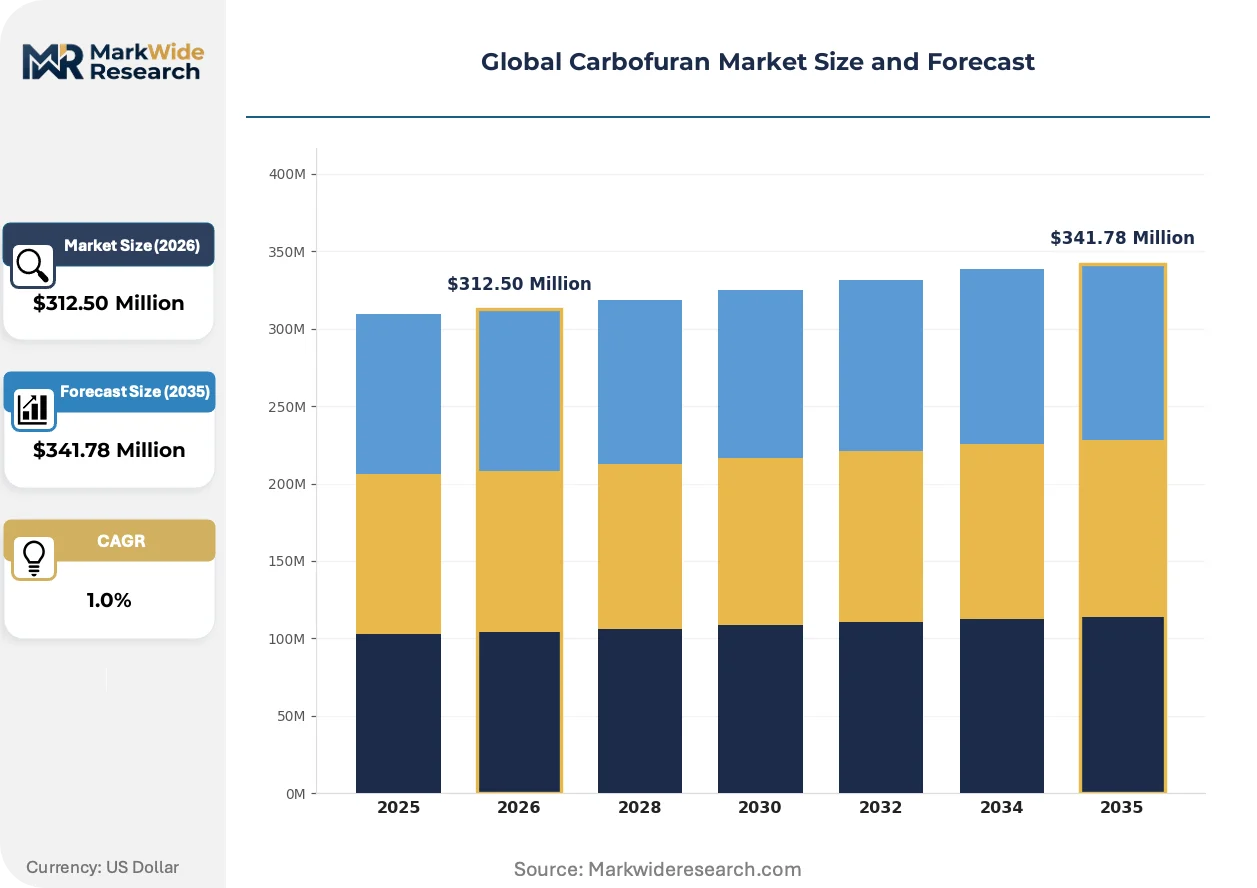
Regulatory divergence between jurisdictions with active tolerance reviews and those grandfathering existing registrations is compressing addressable horizons for carbofuran manufacturers while concentrating residual demand in South Asian and Latin American agricultural belts.
Growth Catalysts
- Soil-applied nematode control:Granular formulations retain their position in cotton and sugarcane systems where root-zone delivery precision justifies continued registration maintenance.
- India's Central Insecticides Board tolerance ceilings:Residue limit structures shape import and domestic formulation decisions, sustaining baseline consumption through calibrated compliance.
- Neonicotinoid ban cascades:Phased restrictions on competing systemic insecticides in select jurisdictions temporarily broaden niche economics for legacy carbamate chemistry.
Market Restraints
- REACH neurotoxic carbamate restrictions:ECHA prohibition schedules progressively narrow European usage volumes and eliminate formulation manufacturing assets.
- Technical limitation in residue management:Carbofuran's high water solubility and soil mobility create persistent groundwater contamination liability that accelerates regulatory phase-out timelines.
- Substitution threat from biological nematicides:Purpureocillium lilacinum and Bacillus firmus-based alternatives gain traction in protected vegetable systems where operator exposure liability drives chemistry switching.
Strategic Opportunities
- Underpenetrated geographies in Southeast Asian rice belts:Vietnam and Indonesia maintain granular carbofuran access for rice stem borer management where neonicotinoid resistance has elevated carbamate utility.
- Regulatory tailwind from Brazil's ANVISA re-evaluation windows:Phased restriction timelines create temporary market access extensions for specialized soil-application equipment paired with carbofuran delivery.
- Technology convergence of precision application and closed-transfer systems:Integration of automated soil injectors with granular product handling reduces operator exposure metrics and extends registration viability.
Industry Challenges
- Certification timeline compression:US EPA restricted-use classification renewal cycles demand accelerated toxicology package updates that strain regulatory affairs capacity.
- Supply chain reconfiguration friction:Active ingredient sourcing shifts from Chinese manufacturers to Indian alternative suppliers disrupts formulation quality consistency and batch certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbofuran Market |
| Market Size in 2026 | $312.50 Million |
| Market Size in 2035 | $341.78 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powder, Pellets Formulation: Emulsifiable Concentrate, Suspended Concentrate, Soluble Granules, Wettable Powder Application: Agricultural Crops, Vegetables, Fruits, Ornamentals Distribution Channel: Online Retailers, Agrochemical Distributors, Wholesale Suppliers, Direct Sales |
| Companies Covered | Bayer CropScience, Syngenta AG, FMC Corporation, UPL Ltd., ADAMA Ltd., Sumitomo Chemical Co., Ltd., Nufarm Limited, Hunan Haili Chemical, Hubei Sanonda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbofuran Market Emerging Trajectories
Formulation chemistry and application methodology are diverging sharply between jurisdictions with accelerating restriction timelines and those maintaining grandfathered access, creating a bifurcated innovation pathway.
Microencapsulated carbofuran formulations are overtaking conventional granular products in orchard and high-value vegetable systems where extended release kinetics reduce application frequency. Protected cultivation operators in Spain and Italy adopt these variants despite EU-wide prohibition schedules. The technology compresses addressable volume by concentrating residual demand in premium crop segments willing to absorb higher unit costs for compliance flexibility.
REACH authorization requirements for Annex XIV substances are forcing carbofuran manufacturers to submit comprehensive substitution plans or seek time-limited derogations for critical agricultural uses. The industrial consequence is a contraction of formulation R&D investment in European assets. Specialty crop segments in Greece and Portugal face the most acute supply discontinuity risks as 2025 sunset dates approach.
Buyer concentration among large-scale agricultural cooperatives is consolidating procurement decisions for carbofuran and alternative chemistries into centralized technical committees. Distributor networks in India's Maharashtra and Gujarat states lose direct farmer relationships as cooperative purchasing platforms displace traditional retail channels. This pattern is most visible in sugarcane processing regions where mill-affiliated farmer associations negotiate bulk nematicide supply contracts.
Global Carbofuran Market Segmentation
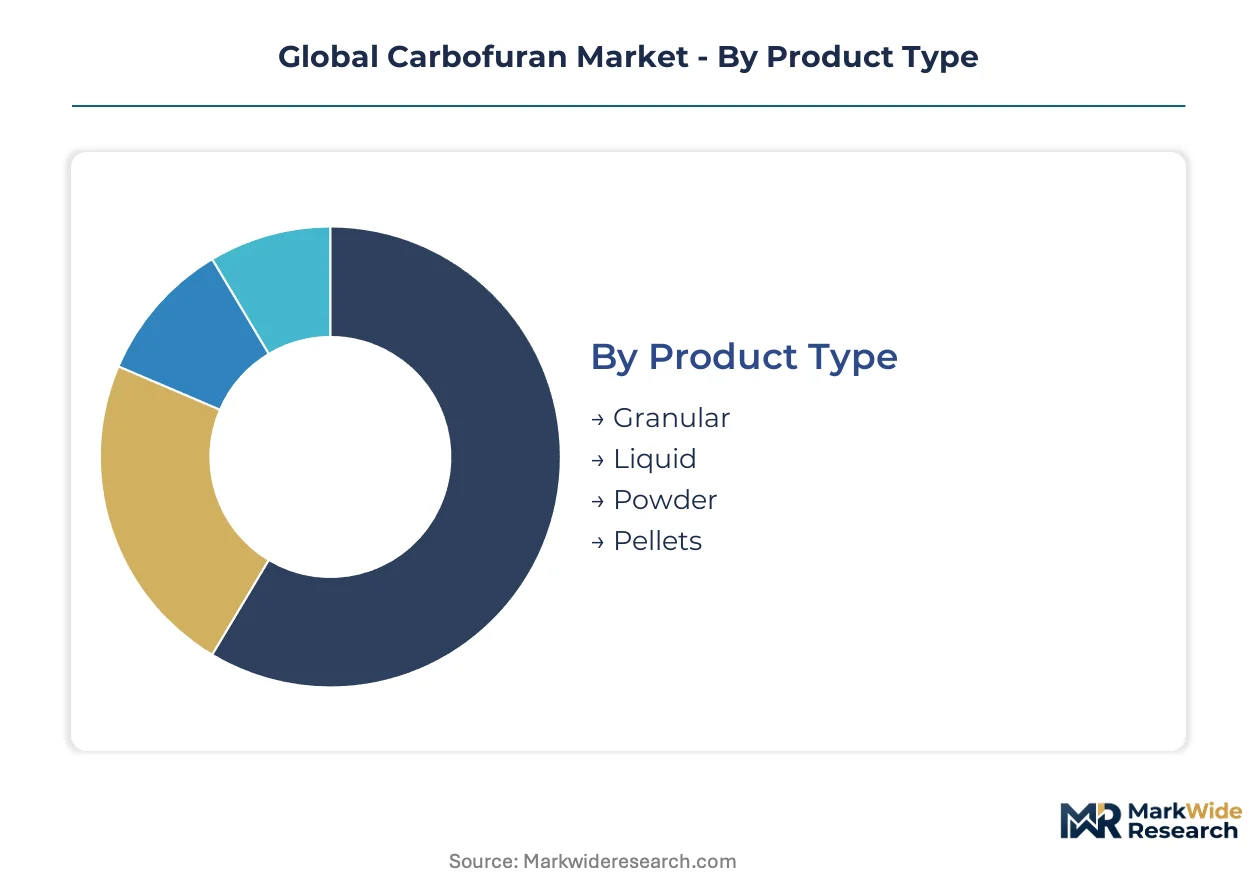
Carbofuran segmentation reveals how regulatory burden and application risk concentrate demand across formulation types. Certification requirements from EPA, ECHA, and India's Central Insecticides Board create divergent compliance costs that reshape competitive positioning within each category.
Product Type:
EPA restricted-use classification and ECHA REACH authorization requirements impose tiered certification burdens across physical forms, with granular products facing lighter handler exposure protocols than liquid alternatives.
- Granular:3% and 5% active ingredient formulations dominate rice cultivation across Vietnam and Indonesia where root-zone delivery reduces operator contact. India's cotton belt sustains baseline volumes despite tightening residue ceilings from the Central Insecticides Board.
- Liquid:400 g/L emulsifiable concentrates retain orchard and ornamental applications in Brazil where ANVISA phased restrictions have not yet eliminated foliar spraying. Precision application equipment requirements elevate compliance costs compared to granular alternatives.
- Powder:Wettable powder formulations face structural decline as distributors in Maharashtra and Gujarat shift inventory toward suspended concentrates.
- Pellets:Compressed matrix products serve protected vegetable systems in Spain and Italy with extended-release characteristics.
Granular sits at the top of the volume ranking, with pellets climbing the fastest.
Formulation:
Cost tier differentiation separates premium microencapsulated variants from commodity wettable powders, with formulation sophistication determining accessible crop segments and geographic markets.
- Emulsifiable Concentrate:Oil-based liquid formulations requiring solvent stabilization face heightened EPA buffer zone restrictions near water bodies. Brazil's sugarcane cooperatives negotiate bulk supply contracts for soil-injected applications.
- Suspended Concentrate:Aqueous dispersion systems displace wettable powders in Indian distributor inventories driven by convenience metrics and drift-reduction compliance.
- Soluble Granules:Rapid-dissolution formats command premium positioning in high-value vegetable systems where application precision justifies unit cost elevation.
- Wettable Powder:Legacy dry formulations concentrate in price-sensitive segments with minimal regulatory oversight, primarily Southeast Asian rice belts.
Emulsifiable concentrate maintains the broadest installed base, though suspended concentrate is expanding most quickly through distributor channel upgrades.
Application:
End-use crop value directly determines tolerance for carbofuran's neurotoxic profile, with residue limit stringency varying sharply across food versus non-food systems.
- Agricultural Crops:Cotton and sugarcane applications in India and Brazil sustain the largest volume flows where nematode pressure exceeds substitution economics. Central Insecticides Board tolerance structures shape import decisions.
- Vegetables:Protected cultivation in Spain and Italy adopts microencapsulated variants despite EU prohibition schedules, with grower cooperatives absorbing compliance premiums for stem borer control.
- Fruits:Orchard systems in Brazil require precision spraying equipment that pairs with liquid formulation delivery, creating equipment-chemistry bundling.
- Ornamentals:Non-food status permits continued access in jurisdictions where agricultural bans have eliminated food-crop applications.
Agricultural crops anchor volume consumption, with ornamentals gaining share fastest as food-system restrictions cascade.
Distribution Channel:
Customer concentration among agricultural cooperatives is consolidating procurement decisions into centralized technical committees, displacing traditional retail relationships.
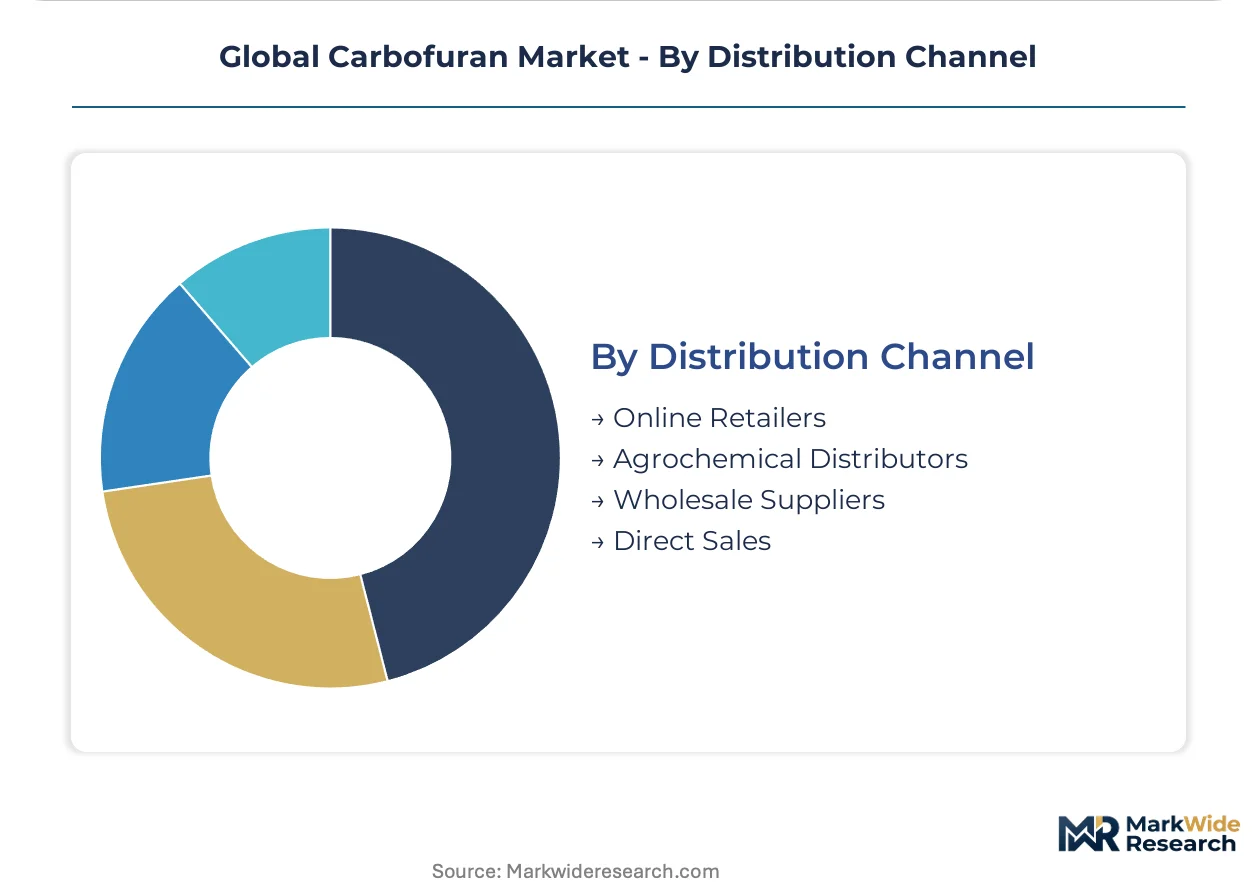
- Agrochemical Distributors:Traditional retail networks in India's Gujarat state lose direct farmer access as cooperative purchasing platforms capture sugarcane nematicide decisions.
- Direct Sales:Large-scale cotton processors negotiate captive supply contracts that bypass distributor markups entirely.
- Wholesale Suppliers:Volume aggregation points serve smallerholder rice cultivators across Vietnam and Indonesia with granular product bulk packaging.
- Online Retailers:Digital procurement channels remain marginal due to EPA and Central Insecticides Board certification requirements that demand physical documentation.
Agrochemical distributors retain the deepest volume penetration, while direct sales is climbing fastest through cooperative consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's sugarcane cooperatives anchor residual carbofuran procurement volumes as regulatory divergence fragments manufacturing deployment across jurisdictions with active tolerance reviews versus grandfathered access regimes.
United States
Cotton nematode pressure in the Mississippi Delta sustains granular formulation demand despite EPA restricted-use classification tightening buffer zones near water bodies. The agency's certification renewal cycles strain registrant toxicology capacity. Texas High Plains cotton ginneries negotiate captive supply contracts that displace traditional distributor channels.
India
Cotton belt applications in Gujarat and Maharashtra generate baseline consumption volumes as the Central Insecticides Board calibrates residue tolerance ceilings. The regulator's import licensing structures shape domestic formulation decisions. Sugar mill-affiliated farmer associations in western Maharashtra consolidate procurement through cooperative purchasing platforms.
Brazil
Sugarcane nematode management in São Paulo state sustains soil-injected emulsifiable concentrate applications. ANVISA phased restriction timelines create temporary market access extensions for specialized application equipment. São Paulo-based processing cooperatives negotiate bulk supply contracts that bypass wholesale aggregation points.
Vietnam
Rice stem borer resistance to neonicotinoids elevates granular carbofuran utility across the Mekong Delta. The country's national agricultural regulator maintains registration access where competing chemistries face displacement. Can Tho province distribution networks serve smallholder cultivators with bulk-packaged granular products.
Spain
Protected vegetable cultivation in Almería and Murcia adopts microencapsulated variants despite EU-wide prohibition schedules. ECHA REACH authorization requirements force submission of comprehensive substitution plans. Grower cooperatives absorb compliance premiums for stem borer control in greenhouse tomato systems.
Global Carbofuran Market Vendor Landscape
Global majors compete with regional champions across registration portfolio depth and geographic access corridors, producing a tiered structure where legacy agrochemical conglomerates anchor premium positions while Asian chemical manufacturers capture cost-sensitive volume segments. The vendor base stratifies across three archetypes: diversified multinationals with legacy carbamate portfolios, specialized nematicide formulators, and commodity active ingredient suppliers. Dominant competitive moves include M&A-driven registration portfolio consolidation and backward integration into active ingredient synthesis.
Within the diversified multinational tier, Bayer CropScience and FMC Corporation occupy positions exemplifying registration-led market access strategies, while UPL Ltd. represents the cost-adjusted supply chain archetype competing across South Asian agricultural belts. Hunan Haili Chemical and Hubei Sanonda anchor the Chinese manufacturing cluster serving export formulation demand.
| Leading Market Players |
|---|
| Bayer CropScience |
| Syngenta AG |
| FMC Corporation |
| UPL Ltd. |
| ADAMA Ltd. |
| Sumitomo Chemical Co., Ltd. |
| Nufarm Limited |
| Hunan Haili Chemical |
| Hubei Sanonda |
| Others |
Supply Flow & Price Mechanics
Agricultural cooperative procurement committees across Maharashtra and São Paulo state dominate volume negotiations, compressing distributor markups and anchoring contract-based long-term offtake as the prevailing pricing model for granular carbofuran formulations.
Pricing Analysis
Input-cost pass-through from methyl isocyanate and phenol derivatives governs formulation pricing, with Indian and Chinese active ingredient suppliers adjusting quotes on 60-day lag structures. Three-tier pricing structure across premium microencapsulated, standard emulsifiable concentrate, and economy wettable powder levels separates compliance-grade orchard products from commodity rice applications. Pricing pressure stems from biological nematicide substitution in protected vegetable systems, with cost compression running through standard-tier liquid formulations. Smallholder cultivators across Vietnam's Mekong Delta exhibit highest price sensitivity, while Spanish greenhouse cooperatives absorb premium-tier premiums for stem borer control.
Supply Chain Analysis
Freight cost volatility from Chinese and Indian manufacturing clusters to Southeast Asian rice belts and Brazilian sugarcane regions elevates landed cost uncertainty for granular product shipments. Active ingredient synthesis concentrates in China and India, with formulation finishing distributed across regional hubs serving EPA, ANVISA, and Central Insecticides Board compliance requirements. Supply chain risk centers on single-source vulnerability for methyl isocyanate precursors following consolidation among Chinese specialty chemical manufacturers. Distribution runs through agrochemical distributor networks in Gujarat and wholesale aggregation points serving Vietnamese smallholders, with direct sales channels capturing cooperative procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on backward integration into active ingredient synthesis and premium-tier microencapsulation technology adoption, offsetting commodity-grade price erosion.
For Market Incumbents: Deploy registration portfolio leverage as the primary defensive mechanism. Extend EPA restricted-use classification maintenance cycles through accelerated toxicology package investments, while consolidating granular formulation capacity in Indian assets to serve Central Insecticides Board compliance structures. Biological nematicide substitution in European protected cultivation demands counter-positioning through precision application equipment bundling in Brazil's ANVISA extension windows. For New Entrants and Emerging Players: Specialized soil-injection equipment manufacturers represent the most penetrable buyer archetype for technology-chemistry bundling partnerships. Target São Paulo sugarcane cooperatives seeking ANVISA-compliant nematide delivery systems, and penetrate Vietnam's Can Tho province distribution networks through bulk granular packaging formats. A go-to-market angle anchored in closed-transfer system integration reduces operator exposure liability for registrant partners. For Investors and Strategic Acquirers: Specialty chemical conglomerates with existing carbamate synthesis infrastructure are the most active acquirer in this space, seeking registration portfolio depth in grandfathered-access jurisdictions. Five-to-ten-year viability hinges on geographic diversification into South Asian and Latin American markets with active tolerance reviews. Acquisition target archetype: Indian formulators with Central Insecticides Board import licensing and established cooperative relationships. The signal to watch is ECHA substitution plan submission deadlines for European asset write-down acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Captures margin from Chinese methyl isocyanate suppliers while securing batch certification timelines. |
| Microencapsulation Technology Licensing | Opens premium-tier access in Spanish Almería greenhouse systems despite EU prohibition schedules. |
| Precision Application Equipment Joint Venture | Pairs granular carbofuran delivery with automated soil injectors for ANVISA compliance extension. |
| Registration Portfolio Acquisition in India | Consolidates Central Insecticides Board licenses for cotton and sugarcane nematicide applications. |
| Biological Nematicide Co-formulation Development | Addresses operator exposure liability driving chemistry switching in protected vegetable cultivation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with agrochemical distributor procurement heads, Central Insecticides Board regulatory affairs officers, Brazilian sugarcane cooperative technical committees, and EPA-certified applicator trainers with secondary validation against customs trade data, SEC 10-K filings from listed agrochemical majors, ANVISA registration databases, and ECHA REACH authorization records. Bottom-up volume aggregation from country-level formulation shipments triangulated against top-down active ingredient production estimates.
Historical reference periods anchored the forecast window to pre-pandemic baseline volumes and post-restriction adjustment trajectories across the analysis window. Segmentation dimensions modeled include formulation type, application crop category, and regulatory jurisdiction cluster. CAGRs derived from regression analysis of shipment volumes against neonicotinoid displacement rates and biological substitution penetration curves, with forecast inputs incorporating ANVISA re-evaluation timeline assumptions and Central Insecticides Board tolerance ceiling calibration patterns.
Underlying measurement precision varies by segment; granular formulation volumes in India and Brazil carry tighter precision than microencapsulated specialty products in European protected cultivation. Forecasts reflect assumptions regarding regulatory grandfathering duration and cooperative procurement consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
Europe Feed Enzymes Market
Agricultural Chemicals
Europe Feed Premix Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
Europe Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
Argentina Feed Additives Market
Agricultural Chemicals
Global Agricultural Fumigants Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
China Herbicide Market
Agricultural Chemicals
Seed Binders Market