
 Asia-Pacific Feed Additives Market | 2026-2036
Asia-Pacific Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Additives Market Analysis
A capital-intensity divergence between integrated multinationals and regional specialists is redrawing competitive boundaries across the Asia-Pacific feed additives sector. Cargill Inc. leverages its captive supply of key raw materials to maintain cost discipline in amino acid production. BASF SE anchors its position through advanced enzyme fermentation platforms serving poultry and aquaculture customers. DSM-Firmenich AG differentiates via precision-premix technologies that address species-specific nutritional gaps.
Feed additives comprise biologically active substances—including amino acids, enzymes, vitamins, and minerals—formulated into dry, liquid, powder, or pellet forms to enhance animal nutrition, improve feed efficiency, and support livestock health outcomes. These inputs function by optimizing digestive processes, correcting dietary deficiencies, and mitigating pathogen pressure in intensive production systems. Amino acids and enzymes together command the largest share of product value, reflecting their role in reducing crude protein requirements and lowering nitrogen excretion. Aquaculture represents the fastest-growing application segment, driven by expanding shrimp and finfish farming across Indonesia, Vietnam, and India where water quality management intensifies additive dependency.
China's SAMR enforces GB standards on feed additive safety and labeling, while India's FSSAI and BIS regulate import quality and domestic manufacturing compliance. The EU Green Deal's deforestation-free supply chain requirements are reshaping export-oriented sourcing across Southeast Asian operations. Stakeholders must monitor evolving residue thresholds and traceability mandates that will determine market access and procurement flexibility across the region.
Market Dynamics
Enzyme fermentation platforms are redrawing production economics across the Asia-Pacific feed additives sector, compressing unit costs for amino acid and probiotic manufacturers while raising capital barriers for new entrants.
Growth Catalysts
- Vietnam's Mekong Delta aquaculture expansion:Shrimp and pangasius producers are scaling intensive farming systems that depend on water quality management additives. This concentration of production creates sustained pull for specialized formulations.
- China's SAMR feed safety standards:Tightened residue limits under updated GB standards are forcing domestic producers toward certified additive suppliers. Import requirements are reshaping cross-border procurement patterns.
- Phytase enzyme adoption:Poultry operations across Indonesia and Thailand are deploying phytase formulations to reduce phosphorus excretion and meet environmental compliance. Feed conversion improvements justify the input cost premium.
Market Restraints
- Soybean meal price volatility:Amino acid producers face margin compression when oilseed inputs spike. The Asia-Pacific region imports over half its soybean requirements, exposing formulation costs to currency and freight fluctuations.
- Concentrated fermentation capacity:Industrial-scale enzyme production clusters in China's Jiangsu and Shandong provinces. Disruptions at these hubs propagate through regional supply chains with limited alternative sourcing.
- EU Green Deal deforestation requirements:Southeast Asian export-oriented operations must demonstrate traceable, deforestation-free supply chains for soy and palm derivatives. Compliance documentation adds procurement friction and disqualifies some traditional suppliers.
Strategic Opportunities
- India's underpenetrated aquaculture belt:Andhra Pradesh and Gujarat shrimp farms operate at lower additive intensity than Vietnamese counterparts. Rising export orientation toward EU and US markets will drive compliance-grade input adoption.
- Precision-premix technology convergence:Digital formulation tools combined with real-time livestock monitoring enable species-specific nutrition protocols. Early deployments in Japanese poultry operations point to scalable models.
- Indonesia's BIS-equivalent feed safety mandates:Pending national standards alignment will consolidate fragmented local producers and create openings for certified multinational premix suppliers with established quality systems.
Industry Challenges
- Fermentation process engineering talent:Industrial microbiology and bioprocess optimization skills concentrate in Chinese and Korean research hubs. Regional producers struggle to recruit specialists capable of scaling novel enzyme platforms.
- Multi-jurisdiction certification timelines:Products requiring simultaneous SAMR, FSSAI, and BIS approvals face sequential review processes. Registration backlogs delay commercialization by 18-24 months from formulation readiness.
- Legacy feed mill integration:Established operations across Thailand and Malaysia run equipment with limited precision dosing capabilities. Retrofitting for micro-premix handling demands capital outlays that compress near-term returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Additives Market |
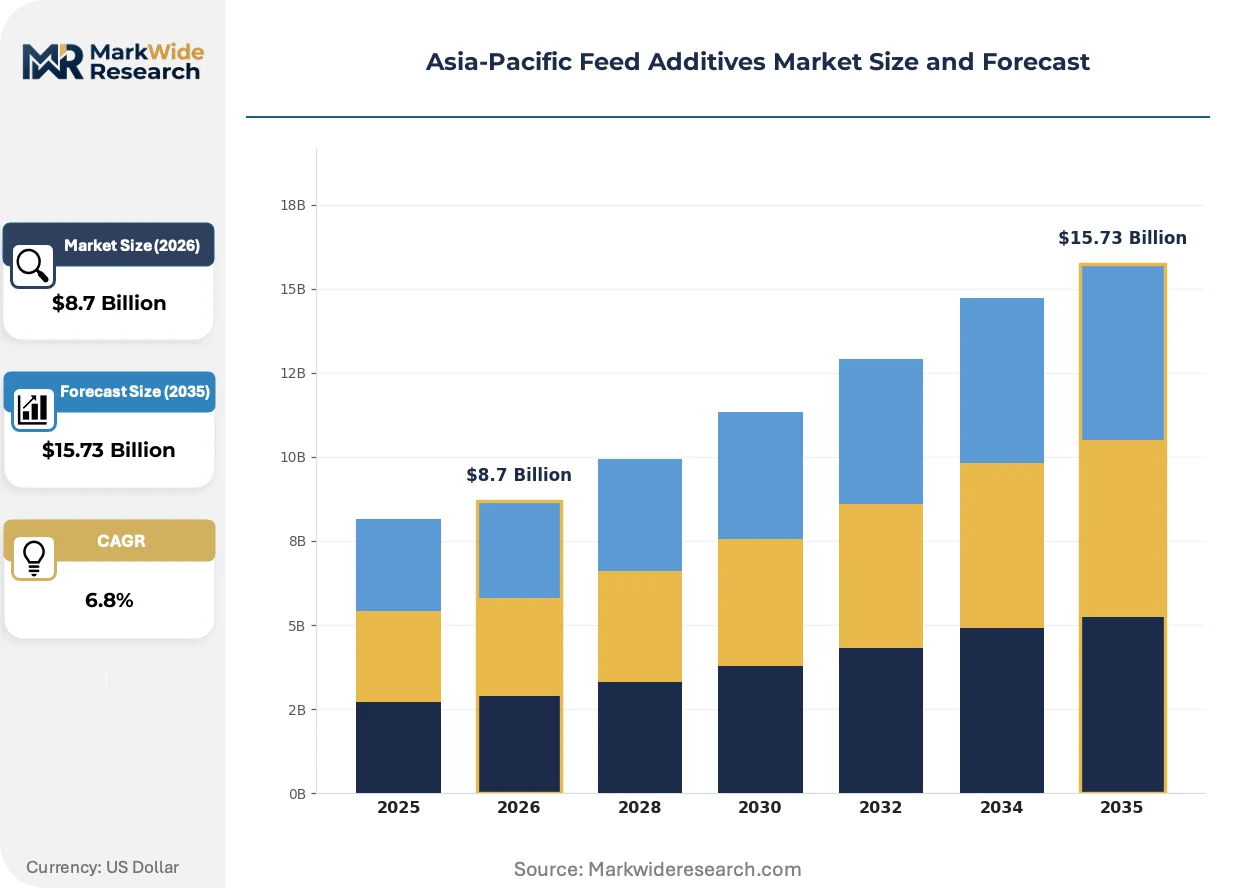
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minerals, Amino Acids, Enzymes, Vitamins Application: Poultry, Ruminants, Swine, Aquaculture Form: Dry, Liquid, Powder, Pellet End User: Farmers, Feed Manufacturers, Distributors, Veterinarians |
| Companies Covered | Cargill Inc., ADM, Evonik Industries AG, BASF SE, DSM-Firmenich AG, Adisseo, Ajinomoto Co., Inc., Nutreco NV, Kemin Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Additives Market Emerging Trajectories
Biotechnology advancement and regulatory stringency are converging to reshape how feed additives are formulated, validated, and procured across Asia-Pacific livestock and aquaculture operations.
Micro-encapsulation technology for heat-sensitive probiotics and enzymes is fragmenting the competitive landscape between integrated fermentation specialists and toll-manufacturing partners. Vietnamese and Indonesian shrimp feed producers are adopting these stabilized formulations at accelerating rates. The technology is fragmenting traditional supply relationships by enabling regional compounders to source active ingredients from non-traditional suppliers without sacrificing shelf stability.
China's SAMR is tightening GB standard enforcement on antibiotic residue thresholds in animal feed. The industrial consequence is a forced pivot toward acidifier, probiotic, and phytogenic alternatives for growth promotion. Poultry integrators in Guangdong and Shandong provinces are most affected, responding by locking in multi-year supply contracts with verified additive producers capable of batch-level traceability documentation.
Buyer concentration among Southeast Asian aquaculture conglomerates is compressing supplier negotiation cycles and unbundling technical service from product pricing. Large Vietnamese shrimp producers now source base additives through centralized procurement while retaining separate advisory relationships with nutrition consultants. This pattern is most visible in the Mekong Delta, where vertically integrated farming groups account for a rising share of formulated feed demand.
Asia-Pacific Feed Additives Market Segmentation
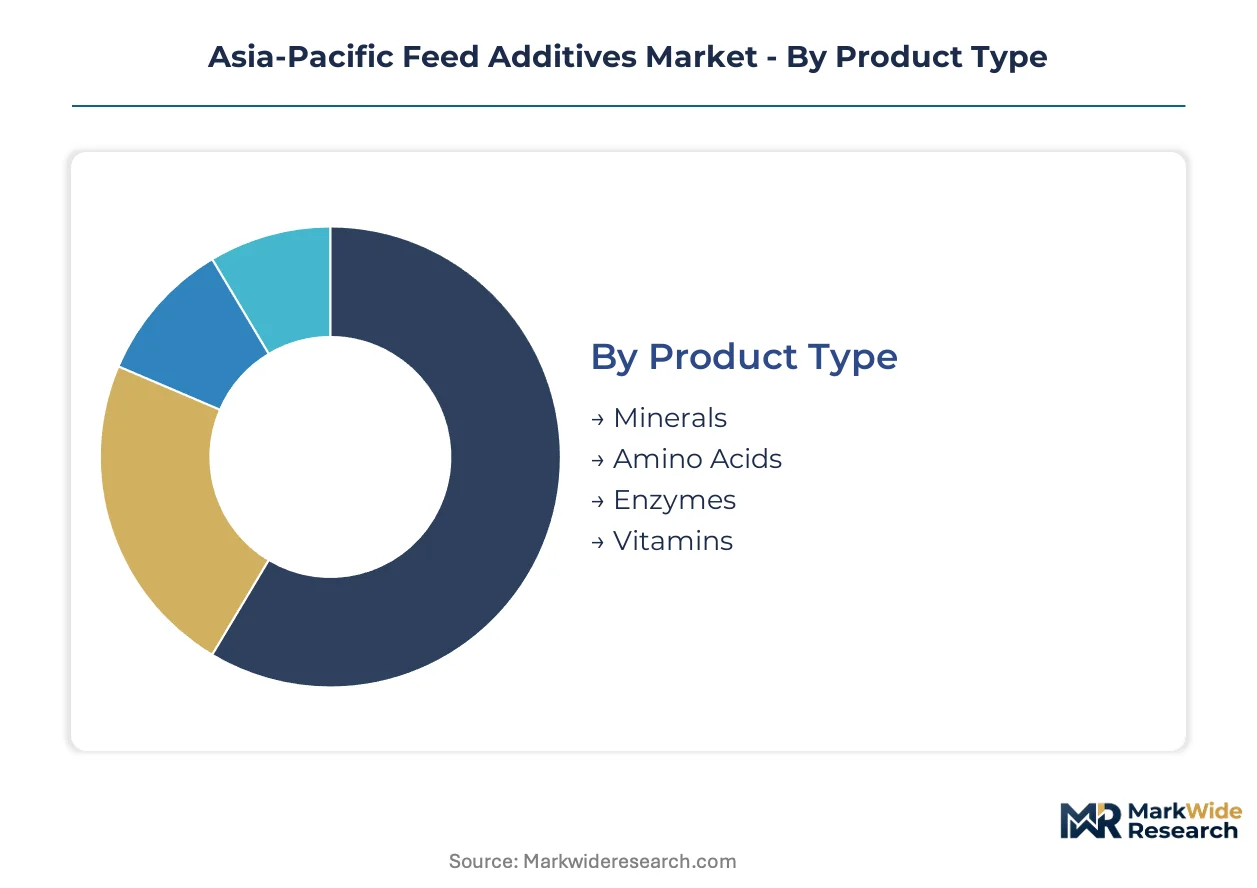
Feed additive purchasing patterns across Asia-Pacific diverge sharply by production system intensity and species-specific nutritional requirements. Understanding these fault lines reveals where formulation premiums command pricing power versus where commoditization pressures dominate procurement decisions.
Product Type:
Amino acids face the strongest substitution pressure from alternative protein sources and precision-feeding technologies that reduce crude protein requirements across poultry and swine operations.
- Amino Acids:Lysine, methionine, and threonine formulations reduce nitrogen excretion while optimizing feed conversion ratios in intensive broiler and layer operations. Demand concentrates in China's Guangdong and Shandong provinces where SAMR-enforced residue limits are forcing domestic producers toward certified suppliers with batch-level traceability documentation.
- Enzymes:Phytase, protease, and carbohydrase platforms improve nutrient digestibility and lower environmental compliance costs for phosphorus excretion. Vietnamese shrimp producers in the Mekong Delta are scaling phytase-intensive formulations to manage water quality in intensive pangasius and shrimp farming systems.
- Vitamins:Fat-soluble and water-soluble micronutrient premixes correct dietary deficiencies in high-density livestock operations. India's FSSAI import quality standards are reshaping procurement toward BIS-compliant domestic manufacturers.
- Minerals:Macro and trace element formulations support bone development and metabolic function across ruminant and poultry species. Indonesian feed compounders source mineral premixes through centralized procurement channels serving vertically integrated farming groups.
Amino acids retain volume leadership; enzymes hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity protein production from premium export-oriented aquaculture where additive intensity justifies input premiums.
- Aquaculture:Shrimp and finfish operations in Vietnam, Indonesia, and India depend on water quality management additives to sustain intensive stocking densities. Andhra Pradesh and Gujarat farms are accelerating additive adoption to meet EU and US export compliance requirements.
- Poultry:Broiler and layer integrators across Thailand, Malaysia, and China deploy enzyme and acidifier formulations to improve feed conversion and replace antibiotic growth promoters under tightening residue standards.
- Swine:Commercial pig operations in Vietnam and the Philippines utilize amino acid and probiotic formulations to optimize lean meat yield and reduce nitrogen excretion in concentrated production zones.
- Ruminants:Dairy and beef cattle producers in India and Australia apply mineral and vitamin premixes to correct pasture deficiencies and support high-yielding genetics in intensive feeding systems.
Poultry commands the largest absolute volume; aquaculture is climbing the fastest.
Form:
Supply concentration in Chinese fermentation clusters shapes form selection based on heat stability requirements and legacy mill equipment capabilities.
- Dry:Granular and crystalline formulations dominate amino acid and mineral distribution due to extended shelf stability and compatibility with conventional feed mill handling systems. Thai and Malaysian operations with limited precision dosing capabilities prefer dry forms for retrofit avoidance.
- Liquid:Pumpable enzyme and acidifier solutions enable post-pelleting application for heat-sensitive actives. Vietnamese aquaculture feed producers are adopting liquid phytase systems for uniform distribution in extruded shrimp feeds.
- Powder:Fine-particle vitamin and probiotic premixes require specialized handling equipment but offer dosing precision for micro-ingredient inclusion. Micro-encapsulation technology is stabilizing powder formulations for regional compounders without captive fermentation capacity.
- Pellet:Compressed additive concentrates simplify handling for small-scale farmers and distributors with limited technical infrastructure. Indonesia's fragmented local producers favor pellet forms for compatibility with basic mixing equipment.
Dry forms retain volume leadership; liquid formulations are gaining share fastest.
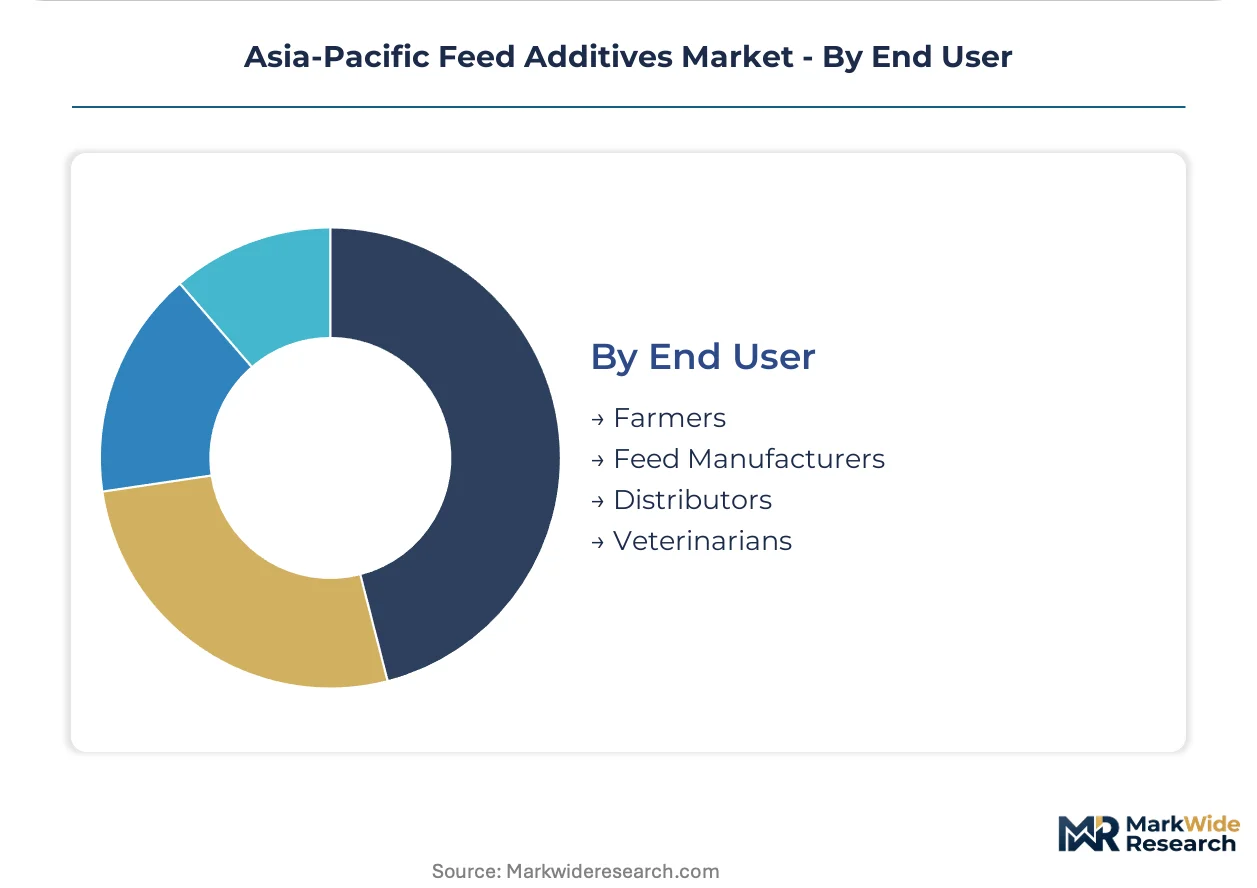
End User:
Customer type determines technical service bundling versus unbundled commodity procurement patterns across the value chain.
- Feed Manufacturers:Large compounders in China, Thailand, and Vietnam source base additives through centralized procurement while retaining separate nutrition advisory relationships. These buyers concentrate demand and compress supplier negotiation cycles through volume commitments.
- Farmers:Commercial livestock and aquaculture producers purchase premixes and concentrates for on-farm mixing or direct supplementation. Vertical integration in Vietnam's Mekong Delta is shifting farmer procurement toward captive feed mill supply.
- Distributors:Regional trading networks aggregate demand from fragmented small-scale operations across Indonesia and the Philippines. These intermediaries face margin pressure from direct manufacturer-to-farm channels.
- Veterinarians:Animal health practitioners prescribe therapeutic and prophylactic additive regimens for disease management and performance optimization. Regulatory alignment between SAMR, FSSAI, and BIS is extending registration timelines for veterinary-directed products.
Feed manufacturers retain volume leadership; veterinarians represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vietnam's Mekong Delta aquaculture belt show the lowest price elasticity, absorbing premium additive costs for water quality compliance, while Indonesian smallholders remain highly sensitive to input price fluctuations.
China
Guangdong and Shandong provinces concentrate the region's largest poultry integrator demand for amino acid and enzyme formulations. SAMR-enforced GB standards on residue limits are forcing domestic producers toward certified suppliers with batch-level traceability documentation. Jiangsu and Shandong fermentation clusters anchor industrial-scale enzyme production capacity serving regional supply chains.
Vietnam
Shrimp and pangasius producers in the Mekong Delta are scaling intensive farming systems that depend on water quality management additives. The country's export orientation toward EU and US markets intensifies compliance-grade input requirements. Vertically integrated farming groups in An Giang and Cần Thơ provinces account for a rising share of formulated feed demand.
India
Andhra Pradesh and Gujarat shrimp farms operate at lower additive intensity than Vietnamese counterparts but are accelerating adoption to meet export compliance standards. FSSAI and BIS regulations are reshaping procurement toward certified domestic manufacturers. The country's aquaculture belt is expanding precision-premix usage as export orientation rises.
Indonesia
Commercial poultry operations across Java and Sumatra are deploying phytase formulations to meet environmental compliance on phosphorus excretion. Pending national feed safety mandates aligned with BIS-equivalent standards will consolidate fragmented local producers. Regional compounders source mineral premixes through centralized procurement channels serving vertically integrated farming groups.
Thailand
Broiler and layer integrators are unbundling technical service from product pricing through centralized procurement of base additives. Legacy feed mill equipment with limited precision dosing capabilities creates retrofit pressure for micro-premix handling. Operations in the Central Plains and Eastern Seaboard industrial zones face margin compression from direct manufacturer-to-farm channel expansion.
Asia-Pacific Feed Additives Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation capacity and captive raw material supply determining cost discipline. The upper tier commands pricing power through scale and certification depth, while mid-cap players compete on formulation flexibility and regional service density. Three archetypes dominate: diversified chemical conglomerates with fermentation platforms, nutrition-focused specialists with precision-premix capabilities, and regional compounders with distribution reach. Competitive moves center on multi-year supply contract lock-ins with verified producers and geographic expansion into underpenetrated aquaculture belts.
Within the integrated fermentation tier, Cargill Inc. and BASF SE exemplify cost discipline through captive supply chains and advanced enzyme platforms respectively. DSM-Firmenich AG occupies a position bridging precision-premix technology with species-specific nutritional protocols. These three entities anchor the premium tier where batch-level traceability documentation and multi-jurisdiction certification capabilities determine market access.
| Leading Market Players |
|---|
| Cargill Inc. |
| ADM |
| Evonik Industries AG |
| BASF SE |
| DSM-Firmenich AG |
| Adisseo |
| Ajinomoto Co., Inc. |
| Nutreco NV |
| Kemin Industries |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day fermentation batch cycles in Chinese enzyme production clusters determine working capital intensity and supplier pricing power across Asia-Pacific feed additive procurement. This lead-time band concentrates cost pressure on regional compounders lacking captive fermentation capacity while rewarding integrated multinationals with inventory flexibility and margin protection.
Pricing Analysis
Technical service bundling drives lifetime value for multinational premix suppliers serving Vietnamese aquaculture conglomerates. Three-tier pricing structure across certified-premium, standard-compliance, and economy-grade tiers segments buyers by export orientation and residue documentation requirements. Pricing pressure stems from soybean meal cost volatility transmitted through amino acid formulations. Indonesian smallholders exhibit highest price sensitivity, while Mekong Delta shrimp producers absorb premiums for water quality compliance.
Supply Chain Analysis
Sixty-day-plus order-to-delivery windows for specialized enzyme concentrates expose regional compounders to fermentation hub disruptions in Jiangsu and Shandong provinces. Supply concentrates in China, Vietnam, and Thailand for fermentation-derived actives; India and Indonesia for mineral premix compounding. Raw material dependencies include corn-derived dextrose, soy protein isolates, and phosphate rock. Single-source vulnerability propagates from concentrated fermentation capacity. Distribution runs through feed manufacturer direct procurement and distributor networks serving fragmented farmers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme fermentation platforms are evolving toward interoperability standards that will commoditize non-integrated compounders while rewarding ecosystem orchestrators with data-rich formulation protocols.
For Market Incumbents: Fortify certification depth by locking multi-year supply contracts with SAMR-verified producers capable of batch-level traceability documentation. Prioritize backward integration into captive raw material supply to offset soybean meal price volatility. Defend against precision-premix technology convergence by acquiring digital formulation tool capabilities. For New Entrants and Emerging Players: Differentiate on micro-encapsulation technology for heat-sensitive probiotics serving Vietnamese and Indonesian shrimp feed producers. Target India's underpenetrated Andhra Pradesh and Gujarat aquaculture belt where export compliance requirements accelerate additive adoption. Pursue toll-manufacturing partnerships with regional compounders lacking fermentation capacity as primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fermentation scale economies and multi-jurisdiction certification barriers favor acquisition of mid-cap specialists over greenfield capacity builds. Target precision-premix technology providers with established BIS and FSSAI registration pathways. Monitor EU Green Deal deforestation-free supply chain enforcement as signal for procurement friction and disqualification risk.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Investment | SAMR, FSSAI, and BIS registration capabilities unlock market access across China, India, and Indonesia procurement channels. |
| Fermentation Capacity Expansion | Industrial-scale enzyme production in Jiangsu and Shandong provinces anchors regional supply chain resilience. |
| Precision-Premix Technology Acquisition | Digital formulation tools combined with real-time livestock monitoring enable species-specific nutrition protocol deployment. |
| Backward Integration into Raw Materials | Captive supply of corn-derived dextrose and phosphate inputs insulates margin from commodity price volatility. |
| Micro-Encapsulation Partnership | Stabilized probiotic and enzyme formulations fragment traditional supply relationships for regional compounders. |
Methodological Framework
A spread of perspectives from fermentation plant managers, feed compounder procurement leads, aquaculture farm operations directors, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SAMR GB standard filings, FSSAI import quality registrations, customs and trade flow data, and SEC disclosures from listed chemical conglomerates. Bottom-up volume modeling across amino acid, enzyme, vitamin, and mineral product categories triangulated against top-down market sizing from production capacity assessments.
Segmentation dimensions modeled include product type, application species, formulation form, and end-user channel across the projection horizon. CAGRs derived from production volume trajectories, capacity utilization trends, and pricing elasticity assumptions by buyer archetype. Industry-specific forecast inputs incorporated phytase adoption rates in Indonesian poultry operations and shrimp farm additive intensity differentials between Vietnamese and Indian aquaculture belts.
Forecasts assume regulatory continuity in SAMR GB standard enforcement, FSSAI-BIS alignment timelines, and EU Green Deal supply chain documentation requirements; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
South America Silage Inoculant Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Asia Pacific Feed Pelletizing Agents Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market
Agricultural Chemicals
Europe Feed Antibiotics Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Global Medicated Feed Additives Market
Agricultural Chemicals
Poultry Premix Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market