
 United States Feed Enzymes Market | 2026-2036
United States Feed Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
United States Feed Enzymes Market Outlook
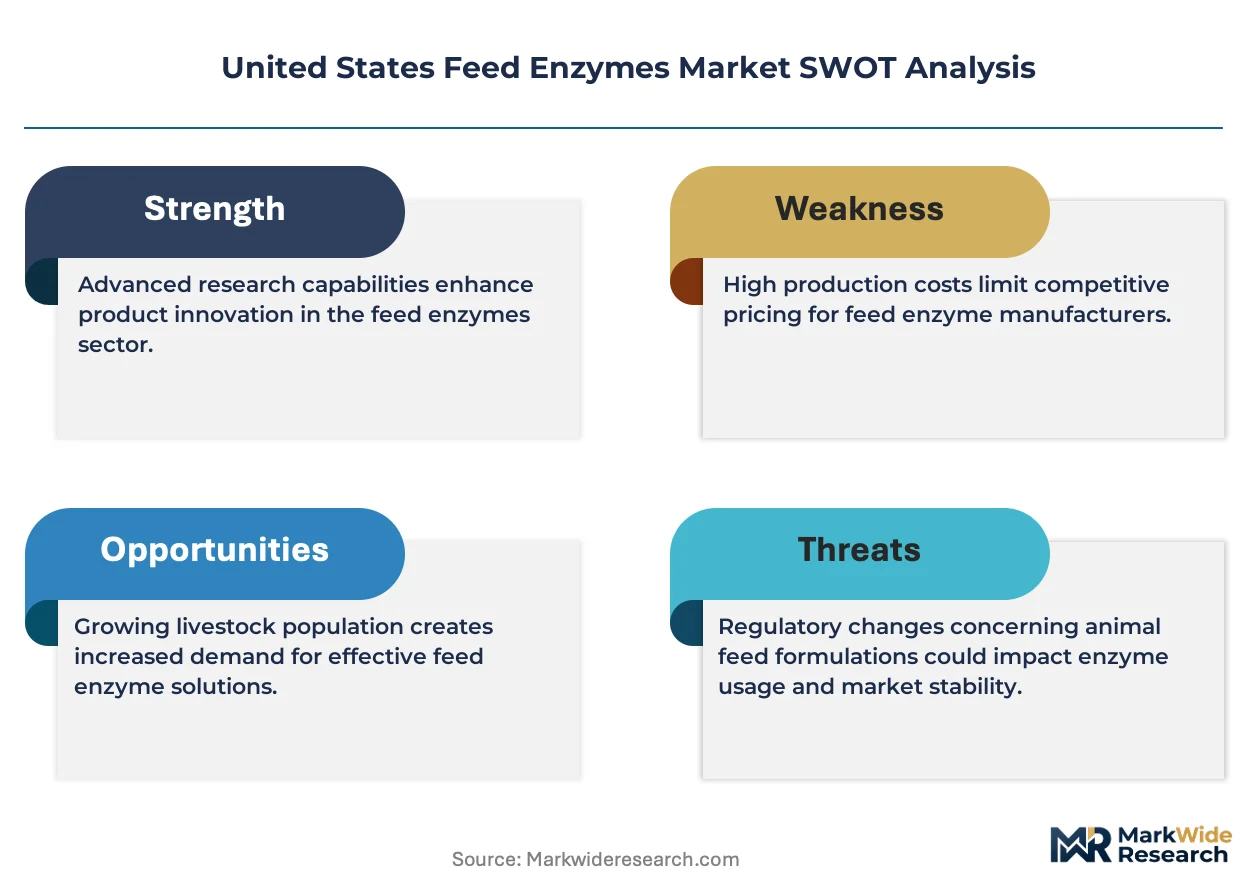
Poultry integration across the southeastern United States is hardening as the dominant demand channel for feed enzymes. Cargill, Incorporated leverages its vertically integrated protein supply chain to push enzyme formulations through company-owned feed mills. Novonesis A/S sustains technology leadership in phytase innovation through dedicated fermentation capacity in the Midwest. Kemin Industries, Inc. anchors its position with specialty blends targeting gut health in antibiotic-free production systems.
Feed enzymes are protein-based biological catalysts, typically produced via submerged fermentation of fungal or bacterial strains, that hydrolyze anti-nutritional factors in animal feed to improve nutrient digestibility and reduce environmental phosphorus and nitrogen excretion. Phytases dominate current volume due to mandatory phosphorus reduction protocols, while carbohydrases capture expanding margin pools as corn-soybean meal ratios fluctuate and NSP-related digestibility gains command premium pricing. Liquid formulations lead in integrator direct channels for automated dosing systems, though pelleted enzymes grow fastest among smaller independent feed mills seeking handling convenience.
The FDA's Center for Veterinary Medicine shapes product registration pathways for novel enzyme strains, while USDA grading standards for meat and poultry indirectly enforce feed quality benchmarks that enzyme suppliers must meet. State-level environmental regulations in Iowa and North Carolina on manure phosphorus loading directly tighten phytase specifications for swine and poultry operations. Stakeholders must monitor evolving FDA positions on enzyme classification between feed additives and veterinary drugs, as this determination will reshape compliance costs and market access timelines.
Market Dynamics
The FDA's guidance on antibiotic alternatives is compressing the substitution timeline for feed enzymes into swine and poultry rations, while Corn Belt feed mills exploit scale economies to lock in enzyme supply contracts ahead of smaller competitors.
Growth Catalysts
- VFD Implementation:The FDA's Veterinary Feed Directive restricts antibiotic use in livestock feed, forcing integrators to adopt phytase and carbohydrase blends as performance substitutes.
- Phosphorus Regulation:State-level manure phosphorus loading limits in Iowa and North Carolina mandate phytase inclusion rates that exceed baseline nutritional requirements.
- Integrator Consolidation:Poultry operations in Georgia and Arkansas are centralizing feed procurement through company-owned mills, creating concentrated demand pools for enzyme suppliers.
Market Restraints
- Fermentation Input Costs:Corn steep liquor and soybean meal price volatility directly squeezes margins for submerged fermentation-based enzyme production.
- Midwest Production Concentration:Dedicated fermentation capacity clusters in Illinois and Indiana, exposing supply chains to regional weather disruptions and energy price spikes.
- Strain Registration Friction:The FDA's Center for Veterinary Medicine requires novel enzyme strain validation through multi-year efficacy trials, delaying product commercialization.
Strategic Opportunities
- Dairy Enzyme Penetration:Ruminant feed enzyme adoption lags poultry and swine by a significant margin across Wisconsin and New York dairy belts.
- Precision Dosing Hardware:Automated liquid enzyme injection systems at feed mill extruders enable real-time formulation adjustments based on grain quality variability.
- IRA Biofuel Crossover:Inflation Reduction Act tax credits for sustainable aviation fuel create shared fermentation infrastructure with enzyme manufacturers.
Industry Challenges
- Fermentation Specialist Scarcity:Industrial microbiology and downstream processing expertise for fungal strain optimization remains concentrated among retiring cohorts at Midwest universities.
- Legacy Mill Retrofit Costs:Independent feed mills in the Southeast lack capital budgets for liquid enzyme storage tanks and automated dosing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Feed Enzymes Market |
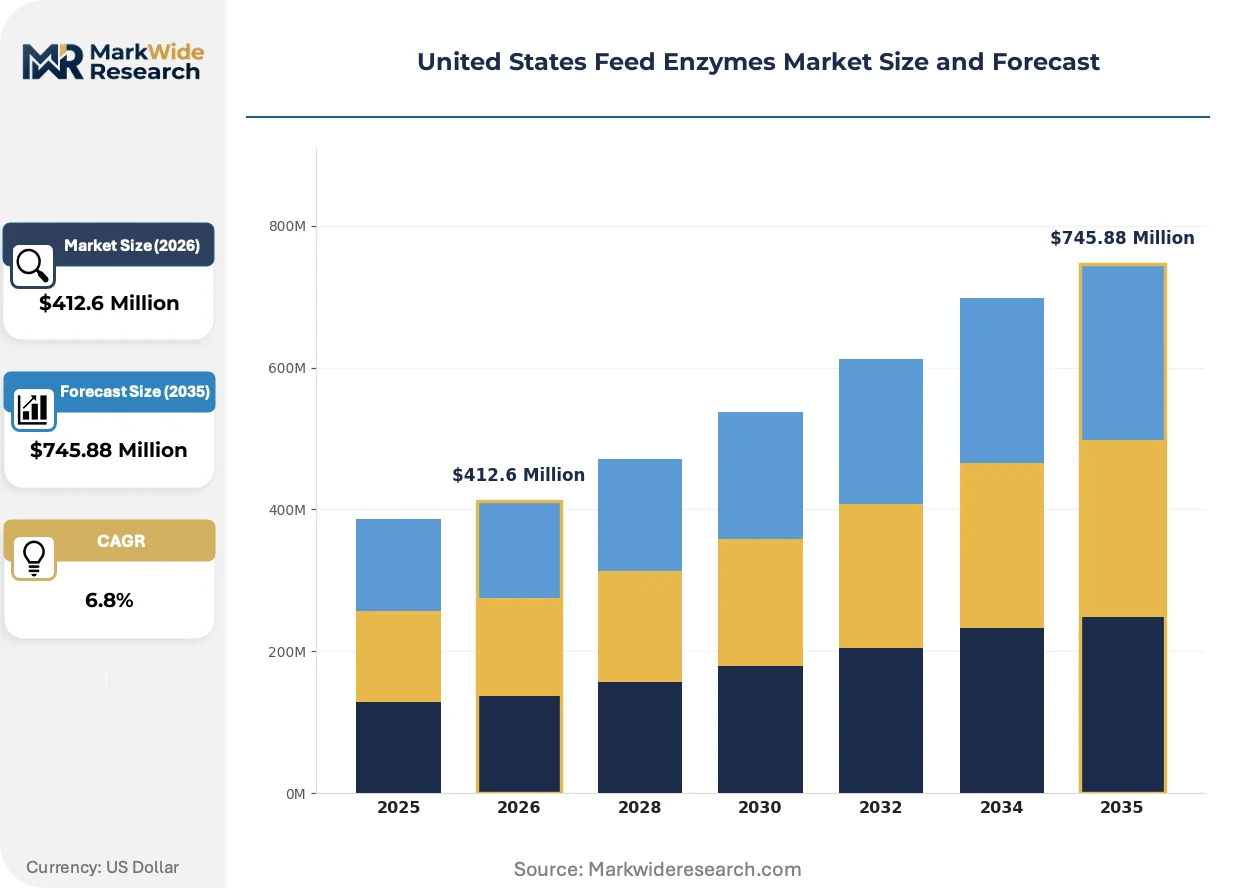
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbohydrases, Proteases, Phytases, Lipases Animal Type: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granulated, Pelleted Distribution Channel: Direct Sales, Online, Distributors, Retail |
| Companies Covered | Alltech, Inc., Archer Daniels Midland Co., Brenntag SE, IFF (Danisco Animal Nutrition), DSM-Firmenich AG, BASF SE, Novonesis A/S, Kemin Industries, Inc., Cargill, Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Feed Enzymes Market Strategic Shifts
Enzyme engineering and delivery mechanisms are undergoing parallel transformation, with protein optimization converging against hardware automation to reshape how feed mills incorporate biological catalysts into production lines.
Next-generation phytase variants with enhanced thermostability are rewriting the economics of pelleting processes. Poultry integrators in the Southeast are adopting these heat-resistant enzymes at accelerating rates, eliminating the need for post-pelleting liquid application systems and compressing capital requirements for new feed mill construction.
The EPA's emerging nutrient trading frameworks for Chesapeake Bay watersheds are tightening phosphorus discharge calculations for Maryland and Virginia poultry operations. This regulatory pressure forces integrators to specify higher-potency phytase concentrations in feed contracts, shifting procurement specifications toward enzyme activity units rather than inclusion rates.
Direct enzyme procurement from manufacturers is displacing distributor intermediaries among top-twenty feed producers. Large mills in Iowa and Minnesota now negotiate volume contracts with fermentation companies for dedicated strain production, bypassing traditional ingredient suppliers and capturing margin that previously accrued to regional distributors.
United States Feed Enzymes Market Segmentation
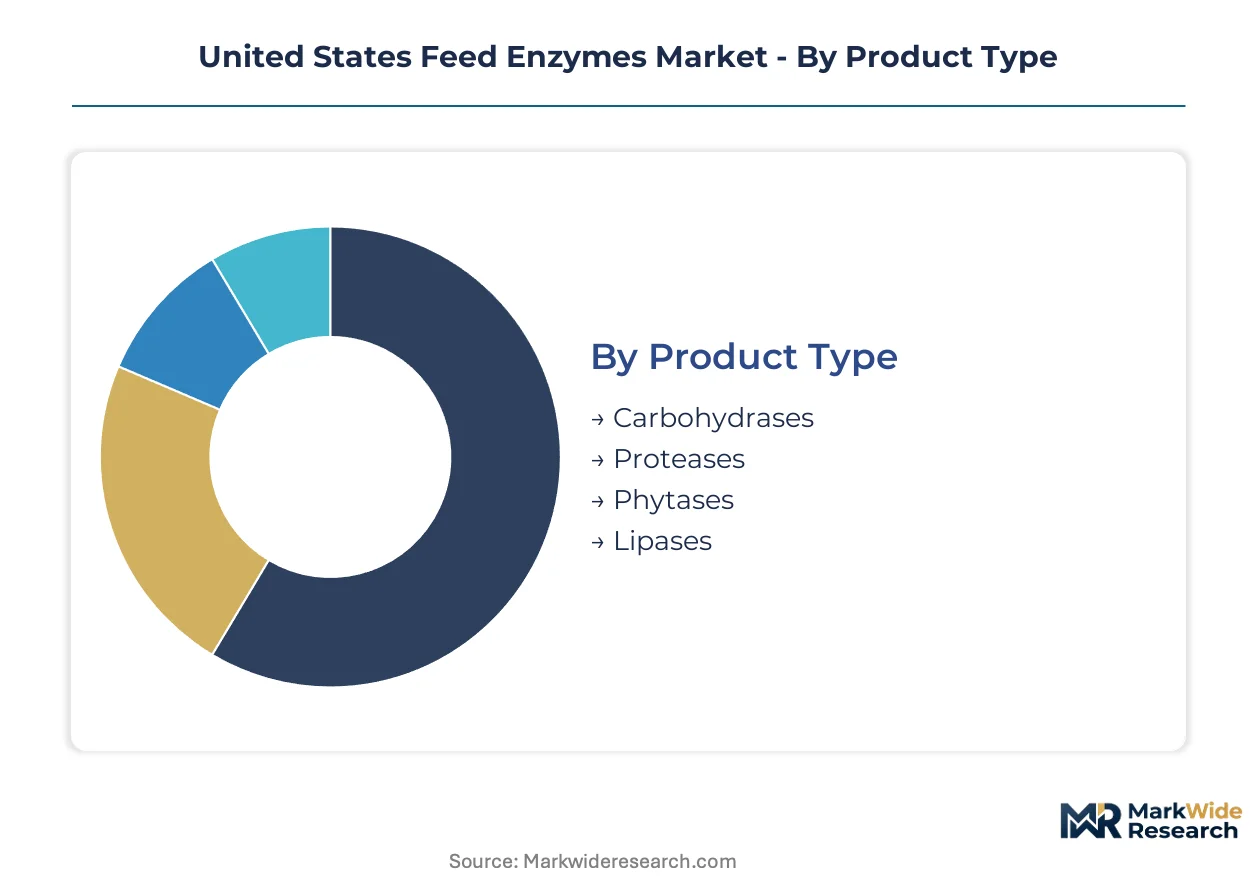
Enzyme suppliers configure product portfolios around four intersecting axes that determine formulation economics, dosing infrastructure requirements, and regulatory compliance pathways. Each segmentation dimension carries distinct margin profiles and customer concentration patterns across the Corn Belt and southeastern poultry belts.
Product Type:
Thermostability specifications and substrate specificity define competitive positioning within each enzyme class, with pelleting temperatures and grain composition dictating strain selection.
- Phytases:These enzymes catalyze the hydrolysis of phytate-bound phosphorus in plant-based feedstuffs, releasing digestible inorganic phosphate and reducing environmental phosphorus excretion. Iowa and North Carolina swine operations specify phytase inclusion rates above nutritional baselines to meet state manure phosphorus loading limits. Mature deployment sits with phytases. Newer deployment is concentrated in next-generation thermostable variants that withstand pelleting temperatures without post-pelleting liquid application.
- Carbohydrases:Xylanase, β-glucanase, and cellulase blends target non-starch polysaccharides in corn-soybean meal matrices, improving energy digestibility and reducing gut viscosity in poultry. Georgia integrators deploy carbohydrase blends as corn quality fluctuates, capturing margin premiums when NSP-related digestibility gains justify higher formulation costs.
- Proteases:Exogenous proteolytic enzymes supplement endogenous protein digestion, particularly relevant in reduced-protein diet formulations for swine. Arkansas poultry operations trial protease-carbohydrase combinations to optimize amino acid utilization.
- Lipases:These enzymes hydrolyze dietary triglycerides to improve fat absorption efficiency, finding niche application in high-oil byproduct rations and young animal starter feeds.
Phytases command volume leadership through regulatory mandates, while carbohydrases capture expanding margin pools as grain quality variability intensifies.
Animal Type:
Species-specific digestive physiology and production system intensity create divergent enzyme performance requirements and customer concentration patterns.
- Poultry:High-throughput broiler operations in Georgia and Arkansas drive concentrated demand for heat-stable phytase and carbohydrase blends integrated into company-owned feed mill formulations. Mature deployment sits with poultry. Newer deployment is concentrated in antibiotic-free production systems requiring gut health-focused enzyme combinations.
- Swine:Iowa and North Carolina operations face the strictest state-level phosphorus discharge regulations, mandating phytase inclusion rates that exceed standard nutritional requirements.
- Ruminants:Wisconsin and New York dairy belts show underpenetration relative to monogastric species, with rumen microbial degradation limiting exogenous enzyme efficacy and slowing adoption.
- Aquaculture:Catfish operations in Mississippi and Alabama represent emerging demand for phytase and carbohydrase formulations adapted to aquatic feed pelleting processes.
Monogastric species anchor current revenue concentration, with ruminant applications representing the steepest expansion trajectory for suppliers overcoming rumen protection technical barriers.
Form:
Physical formulation determines dosing equipment requirements, storage stability, and integration points within feed manufacturing workflows.
- Liquid:Aqueous enzyme preparations enable automated injection at feed mill extruders, supporting real-time formulation adjustments based on incoming grain quality assays. Large integrator-owned mills in Iowa and Minnesota favor liquid systems for precision dosing and labor efficiency.
- Powder:Spray-dried enzyme preparations offer extended shelf stability and simplified handling for smaller independent mills lacking liquid storage infrastructure. Mature deployment sits with powder. Newer deployment is concentrated in granulated and pelleted forms.
- Granulated:Fluid-bed granulation improves flowability and reduces dust exposure during handling, bridging powder convenience with enhanced physical stability.
- Pelleted:Thermostable enzyme incorporation directly into feed pellets eliminates post-pelleting application steps, compressing capital requirements for new mill construction and retrofit projects.
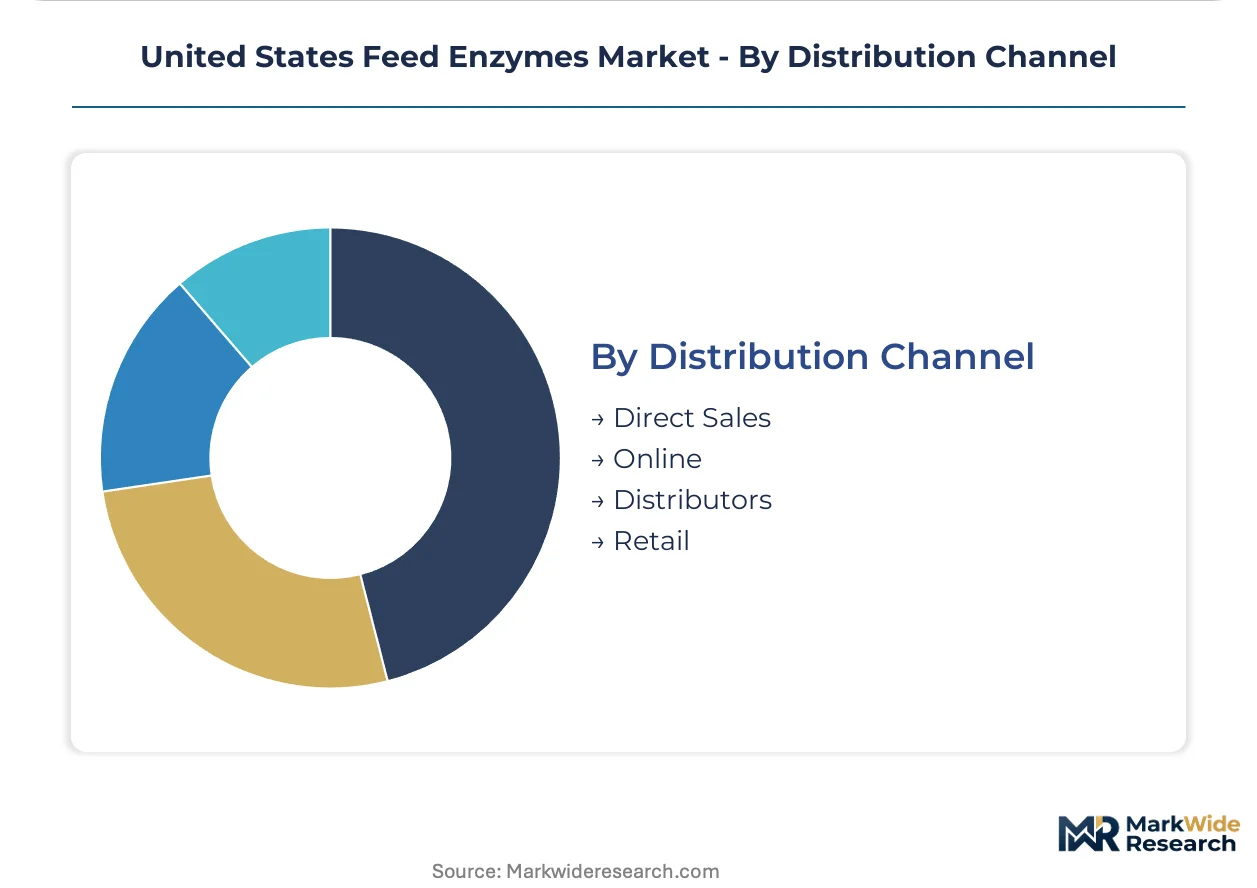
Liquid formulations dominate integrator direct channels, while pelleted enzymes gain share fastest among independent mills prioritizing handling convenience over dosing precision.
Distribution Channel:
Procurement patterns are shifting as scale concentration restructures intermediary economics and manufacturer-customer relationships.
- Direct Sales:Volume contracts between fermentation companies and top-twenty feed producers bypass traditional distributors, capturing margin previously accruing to regional intermediaries. Iowa and Minnesota mills negotiate dedicated strain production directly with manufacturers.
- Distributors:Regional ingredient suppliers maintain relevance among mid-tier independent mills requiring technical support and smaller volume flexibility. Mature deployment sits with distributors. Newer deployment is concentrated in direct manufacturer relationships.
- Online:Digital procurement platforms emerge for specialty enzyme blends and smaller volume orders, though feed enzyme technical complexity limits pure e-commerce penetration.
- Retail:Farm supply stores and cooperatives serve hobby-scale and specialty livestock producers with pre-formulated enzyme premixes.
Direct procurement is displacing distributor intermediaries at the top of the customer pyramid, while distributor networks retain structural importance in fragmented mid-market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern fermentation capacity supplies enzyme formulations to southeastern poultry integrators, while Corn Belt feed mills consume the majority of domestic phytase and carbohydrase volumes. State-level phosphorus regulations in Iowa and North Carolina reshape procurement specifications faster than federal benchmarks.
Iowa
Swine operations in central Iowa face the nation's strictest manure phosphorus loading limits, mandating phytase inclusion rates that exceed standard nutritional requirements. The Iowa Department of Natural Resources enforces discharge permits that directly tighten feed formulation specifications. Sioux City and Des Moines anchor concentrated demand pools where large feed mills negotiate direct supply contracts with fermentation companies.
North Carolina
Poultry integrators in the eastern counties specify high-potency phytase concentrations to meet watershed phosphorus caps under state environmental quality regulations. The North Carolina Department of Environmental Quality administers nutrient management plans that force contract specifications toward enzyme activity units rather than inclusion rates. Wilmington and Fayetteville processing clusters drive concentrated procurement through company-owned feed mills.
Georgia
Broiler operations across the Piedmont region deploy heat-stable carbohydrase blends as corn quality fluctuates seasonally. The Georgia Department of Agriculture enforces feed quality benchmarks that align with USDA grading standards for poultry meat. Gainesville and Athens anchor the densest concentration of integrator-owned mills expanding automated liquid dosing systems.
Arkansas
Northwest Arkansas poultry processors trial protease-carbohydrase combinations to optimize amino acid utilization in reduced-protein diet formulations. State environmental regulations on poultry litter management indirectly enforce enzyme performance standards through nutrient management certification requirements. Springdale and Rogers host vertically integrated operations centralizing feed procurement decisions.
Illinois
Dedicated fermentation capacity clusters around Chicago and Peoria, exposing supply chains to regional energy price volatility and weather disruption risks. The Illinois EPA coordinates with federal FDA registration pathways for novel enzyme strain commercialization. Decatur processing facilities represent shared infrastructure nodes where enzyme manufacturers and biofuel producers compete for fermentation tank capacity.
United States Feed Enzymes Market Competitive Environment
Top-tier vendors anchor concentrated supply relationships with top-twenty feed producers, while mid-tier specialists serve fragmented independent mills through distributor networks. The market structure favors scale-driven fermentation companies with captive strain development capabilities alongside ingredient conglomerates leveraging vertically integrated protein supply chains. Three archetypes dominate: dedicated enzyme manufacturers with Midwest fermentation assets, diversified nutrition companies with formulation integration, and chemical distributors with blending and logistics infrastructure. Competitive moves center on direct procurement contract capture and thermostable strain development partnerships.
Among dedicated fermentation specialists, Novonesis A/S and Kemin Industries, Inc. occupy positions exemplifying technology-led archetypes focused on strain innovation and specialty blends. Cargill, Incorporated represents the integrated nutrition conglomerate archetype, leveraging company-owned feed mill networks to push formulation adoption. These three companies illustrate the competitive spectrum spanning pure-play enzyme technology, specialty health-focused positioning, and supply chain vertical control.
| Leading Market Players |
|---|
| Alltech, Inc. |
| Archer Daniels Midland Co. |
| Brenntag SE |
| IFF (Danisco Animal Nutrition) |
| DSM-Firmenich AG |
| BASF SE |
| Novonesis A/S |
| Kemin Industries, Inc. |
| Cargill, Incorporated |
| Others |
Value Chain & Pricing Dynamics
Captive fermentation capacity in Illinois and Indiana anchors both supply positioning and pricing power for domestic enzyme manufacturers. Vertically integrated protein conglomerates leverage company-owned feed mill networks to internalize margin pools that would otherwise accrue to third-party suppliers.
Pricing Analysis
Short lead-time premiums command substantial markups among Corn Belt integrators facing sudden corn quality shifts requiring real-time carbohydrase adjustments. Three-tier pricing structure across premium thermostable strains, standard liquid formulations, and economy powder blends reflects certification grade and volume scale differentiation. Cost compression in standard liquid tiers is intensifying because fermentation input volatility squeezes mid-tier supplier margins. Independent feed mills in the Southeast exhibit highest price sensitivity due to capital constraints, while top-twenty producers lock in long-term offtake contracts at lower unit economics.
Supply Chain Analysis
Rail freight and bulk liquid tanker costs from Midwest fermentation hubs to southeastern poultry belts constitute a material share of delivered enzyme economics. Production concentrates in Illinois, Indiana, and Iowa, with corn steep liquor and soybean meal as primary fermentation substrates. Single-source vulnerability runs through dedicated strain production lines at Decatur and Peoria facilities, where biofuel manufacturers compete for shared tank capacity. Distribution runs through direct manufacturer contracts with top-twenty feed producers, supplemented by regional distributor networks serving fragmented independent mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation specialist scarcity across Midwest universities props pricing for technical talent and constrains capacity expansion timelines. This bottleneck reinforces incumbent advantages while limiting new entrant scale-up velocity.
For Market Incumbents: Cement captive strain development partnerships with land-grant university microbiology departments to preempt talent pipeline erosion. Lock in multi-year liquid enzyme supply contracts with Georgia and Arkansas integrators before precision dosing hardware commoditizes formulation advantages. The FDA's evolving enzyme classification guidance threatens compliance cost escalation; early engagement with Center for Veterinary Medicine review pathways preserves market access timelines.
For New Entrants and Emerging Players: The FDA's Veterinary Feed Directive implementation opens a window for antibiotic-free production system specialists to capture gut health-focused enzyme share. Target Wisconsin and New York dairy belts where ruminant enzyme penetration lags monogastric species by significant margins. Pursue white-label manufacturing arrangements with Midwest fermentation facilities holding excess tank capacity to bypass capital-intensive infrastructure buildout.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified nutrition conglomerates seeking captive enzyme supply for vertically integrated protein operations. Five-to-ten year viability hinges on thermostable strain patent estates and EPA nutrient trading framework positioning. Watch for Iowa Department of Natural Resources phosphorus discharge rule tightening as inflection indicator for phytase demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermostable Strain Development Partnership | Heat-resistant phytase variants eliminate post-pelleting application capital requirements for Southeast integrators. |
| Precision Dosing Hardware Integration | Automated liquid injection systems at Iowa feed mills enable real-time formulation adjustments based on grain assays. |
| Dedicated Fermentation Capacity Expansion | Additional tank capacity in Illinois reduces biofuel crossover competition and secures supply commitments. |
| Direct Procurement Contract Capture | Volume agreements with top-twenty feed producers displace regional distributors and capture intermediary margin. |
| Regulatory Affairs Capability Buildout | FDA Center for Veterinary Medicine engagement accelerates novel strain registration and commercialization timelines. |
Study Parameters
Document review covered FDA Center for Veterinary Medicine guidance documents, EPA nutrient trading framework proposals, and state environmental quality regulations, complemented by interviews with fermentation plant managers, poultry integrator procurement directors, feed mill operations heads, and university microbiology department chairs. Secondary validation drew from USDA grading standards, Iowa Department of Natural Resources discharge permit databases, and SEC filings of publicly traded nutrition companies. Bottom-up enzyme volume estimates triangulated against top-down feed production statistics across the analysis window.
Historical pricing patterns for corn steep liquor and soybean meal cross-referenced against panel input from procurement executives to inform cost pass-through assumptions. Segmentation modeling incorporated product type, animal species, physical formulation, and distribution channel dimensions alongside regional regulatory stringency tiers. CAGRs derived from trend extrapolation adjusted for VFD implementation pace and integrator consolidation trajectories. Forecast inputs included corn-soybean meal ratio volatility projections and EPA Chesapeake Bay watershed nutrient trading adoption curves.
The model assumes a particular technology adoption path for thermostable phytase variants; alternative pathways for post-pelleting liquid application retention would alter the outlook for capital equipment demand. Forecasts reflect assumptions regarding FDA enzyme classification stability and state-level phosphorus regulation enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Turf and Ornamental Inputs Market
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
North America Plant Growth Regulators Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Feed Micronutrients Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
South America Soil Treatment Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
Field Marking Paint Market