
 Feed Mycotoxin Detoxifiers Market | 2026-2036
Feed Mycotoxin Detoxifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Mycotoxin Detoxifiers Market Intelligence
Yeast cell wall extracts is consolidating around clay-based mycotoxin binders in premium feed formulations. Biomin Holding leverages captive fermentation capacity to secure raw material supply across Central European markets. Cargill anchors its position through backward integration into yeast propagation and downstream feed additive distribution. Kemin Industries differentiates via bioavailability-focused formulation science targeting ruminant applications.
Feed mycotoxin detoxifiers are functional additives designed to sequester, transform, or mitigate the bioavailability of fungal metabolites such as aflatoxins, deoxynivalenol, and fumonisins in animal diets, typically administered at inclusion rates between 0.5 and 2.0 kilograms per metric ton of feed depending on contamination severity and species sensitivity. Their primary commercial purpose is to protect livestock productivity, reduce veterinary intervention costs, and ensure compliance with food chain residue limits. Clay-based products occupy the largest volume share due to cost accessibility and established efficacy against polar aflatoxins, while enzyme-based formulations represent the fastest-expanding margin pool as biotransformation technologies gain validation for trichothecene and zearalenone mitigation. Powder formulations dominate manufacturing throughput, though liquid delivery systems are gaining share in automated integrated feed mills.
The EU Green Deal and REACH frameworks enforce stringent maximum levels for regulated mycotoxins in compound feeds, compelling importer compliance and third-party certification. The FDA and USDA jointly oversee mycotoxin action levels in US feed grains, with FDA guidance documents shaping product registration pathways for novel detoxifier technologies. China's SAMR and GB standards for feed hygiene impose parallel testing protocols that influence export-oriented supplier R&D priorities. Stakeholders must monitor evolving multi-mycotoxin detection thresholds and biotransformation efficacy validation requirements as regulatory harmonization pressures intensify across major import jurisdictions.
Market Dynamics
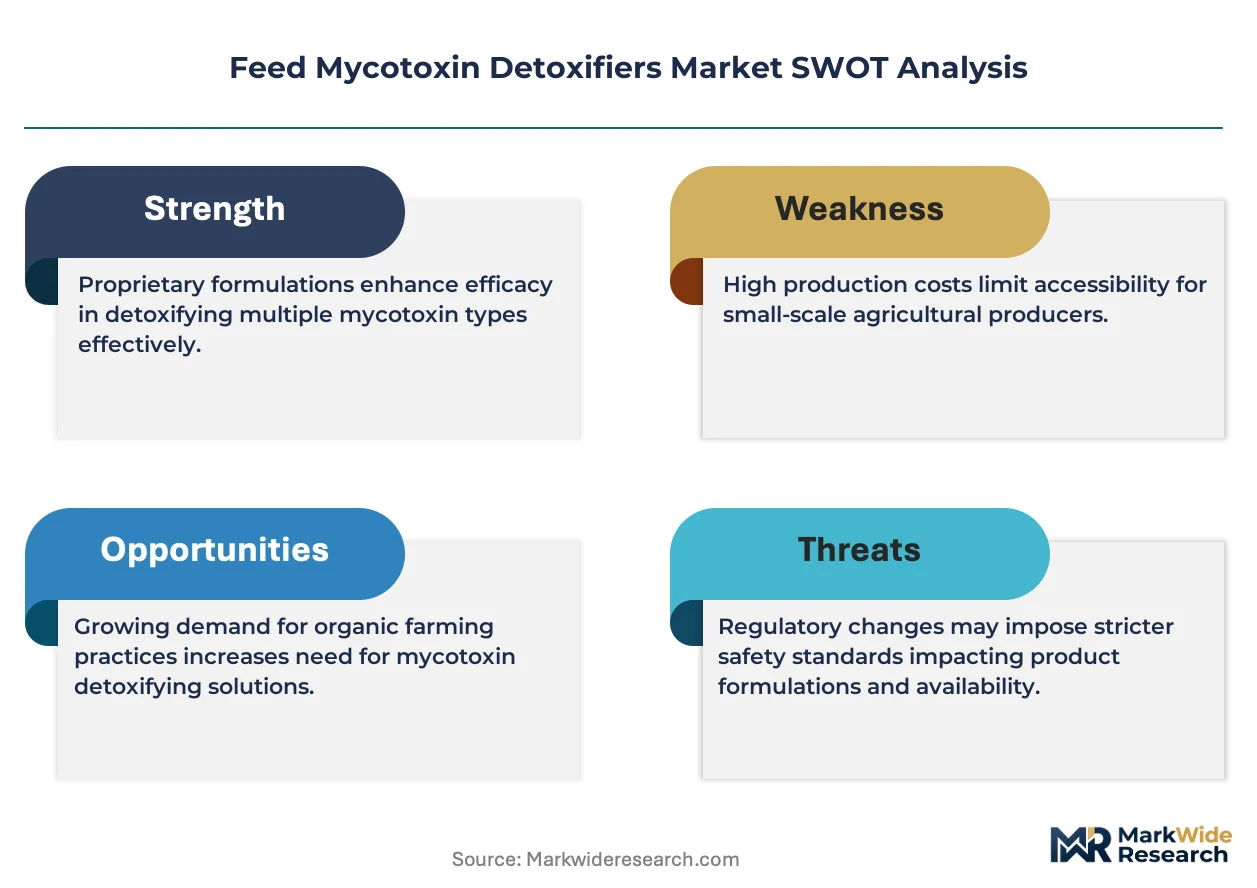
Yeast-derived biotransformation technologies are compressing the efficacy gap with legacy clay binders, forcing incumbents to defend margin positions through captive fermentation investments rather than formulation premiums alone.
Growth Catalysts
- EU Green Deal mycotoxin thresholds:REACH compliance mandates for imported feedstuffs are compelling third-party certification adoption across Brazilian and Argentinian grain exporters, expanding addressable market for validated detoxifier portfolios.
- Poultry productivity economics:Brazilian integrators are expanding yeast cell wall binder programs to reduce veterinary intervention costs and maintain export eligibility under EU residue protocols.
- Trichothecene biotransformation:Enzyme-based deoxynivalenol mitigation is gaining commercial validation in North American swine operations, opening premium pricing tiers beyond aflatoxin-only protection.
Market Restraints
- Montmorillonite supply concentration:Premium clay feedstock availability clusters in specific US and Chinese mining districts, exposing formulators to geopolitical friction and freight cost volatility.
- Multi-mycotoxin efficacy gaps:No single binder technology demonstrates validated adsorption across aflatoxins, fumonisins, and zearalenone simultaneously, forcing complex stacking protocols.
- SAMR registration timelines:China's GB standard compliance testing extends product approval cycles for novel biotransformation entrants, delaying revenue recognition.
Strategic Opportunities
- Indonesian feed manufacturing expansion:Southeast Asia's poultry and aquaculture belt lacks established local binder production, creating first-mover positioning for integrated yeast propagation facilities.
- Liquid delivery system automation:Integrated feed mills in Vietnam and Thailand are retrofitting automated dosing infrastructure, favoring pumpable detoxifier formulations over manual powder handling.
- Ruminant bioavailability science:Kemin Industries' rumen-protected approaches demonstrate pathway for species-specific formulation premiums beyond commodity poultry applications.
Industry Challenges
- Multi-mycotoxin detection capability scarcity:Commercial laboratories capable of simultaneous quantification of regulated and emerging mycotoxins remain concentrated in Western Europe and North America, creating testing bottlenecks for Asian feed manufacturers.
- Biomarker validation timelines:Establishing correlation between detoxifier inclusion and tissue residue reduction requires extended feeding trials, compressing product development cycles against regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Mycotoxin Detoxifiers Market |
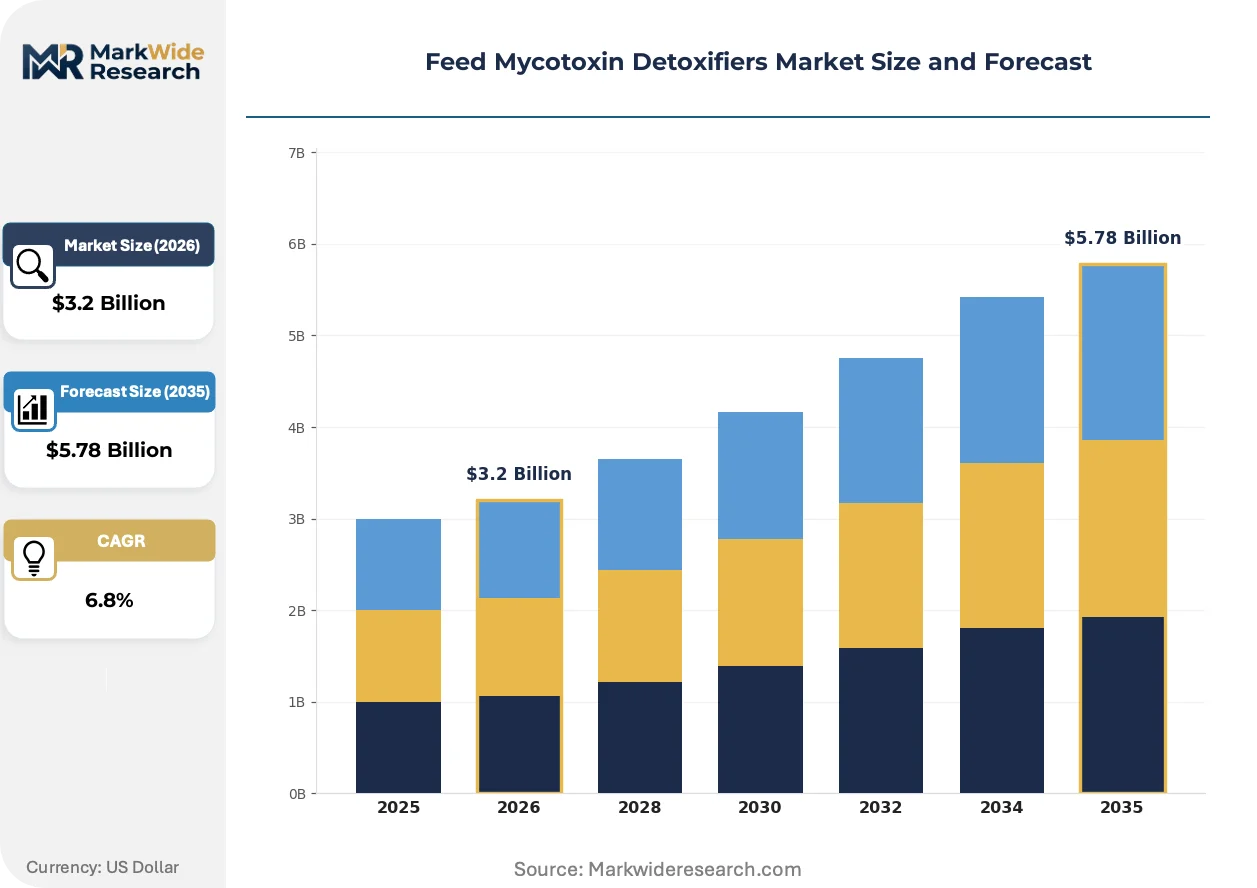
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clay-based, Yeast-derived, Enzyme-based, Activated Charcoal Application: Swine, Poultry, Ruminants, Aquaculture Formulation: Liquid, Powder, Granule, Pellet Distribution Channel: Online, Distributors, Retail, Direct Sales |
| Companies Covered | Biomin Holding, Nutreco, Cargill, Alltech, Adisseo, BASF SE, Kemin Industries, Impextraco, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Mycotoxin Detoxifiers Market Strategic Shifts & Innovations
Bioprocessing convergence and regulatory harmonization pressures are restructuring competitive advantage around captive supply chains rather than standalone formulation science.
Yeast cell wall extract technology is unifying adsorption and biotransformation functions within single-ingredient platforms. Brazilian poultry integrators are accelerating adoption of these hybrid binders at the expense of pure clay products. This convergence is compressing the addressable market for single-mechanism detoxifiers and rewarding fermentation-capable suppliers with structural margin protection.
REACH authorization requirements for feed additive precursors are tightening documentation burdens on non-EU manufacturers. The EU Green Deal's cascading mycotoxin limits are forcing third-party certification investments across Argentinian and Ukrainian grain export infrastructure. Feed compounders serving EU-import markets are now prioritizing detoxifier suppliers with EFSA-recognized validation protocols over lower-cost alternatives.
Automated liquid dosing systems are displacing manual powder incorporation in Vietnamese and Thai integrated feed mills. Technical service contracts bundling detoxifier supply with real-time mycotoxin monitoring are capturing preference from procurement functions previously focused on unit cost minimization. This service integration is most visible in Indonesia's expanding poultry operations, where mill automation investments outpace skilled labor availability.
Feed Mycotoxin Detoxifiers Market Segmentation
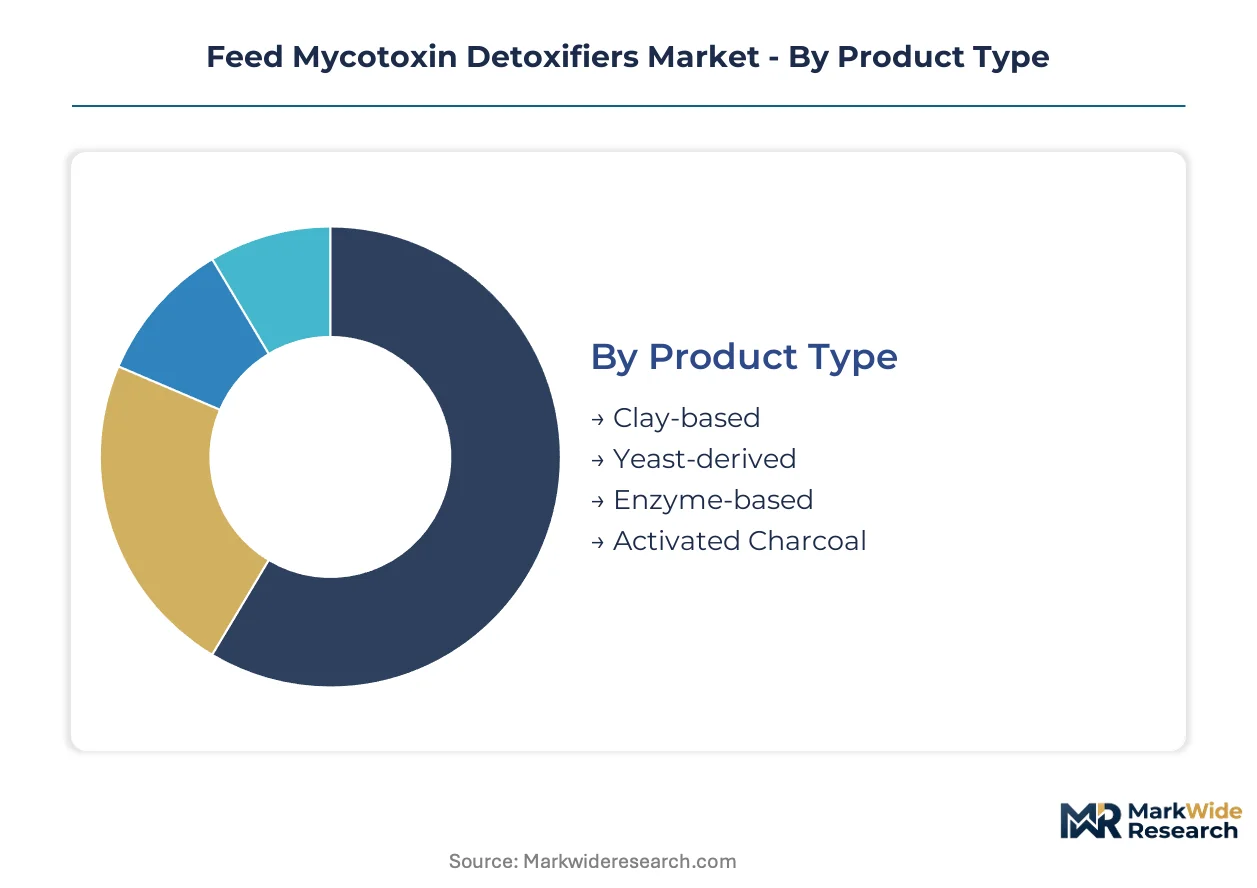
Detoxifier purchasing decisions fragment across species sensitivity thresholds, feed mill automation levels, and regulatory compliance burdens. Suppliers configure formulation portfolios to match divergent cost-performance tradeoffs rather than pursuing universal solutions.
Product Type:
Standardization dominates clay-based offerings while yeast-derived and enzyme-based platforms compete on proprietary bioprocessing customization.
- Clay-based:Montmorillonite and bentonite formulations adsorb polar aflatoxins through ion exchange at 0.5-2.0 kg per metric ton inclusion rates. Brazilian and Argentinian grain exporters deploy these binders to meet EU Green Deal import thresholds at lowest unit cost.
- Yeast-derived:Cell wall extracts from Saccharomyces cerevisiae fermentation bind a broader mycotoxin spectrum including zearalenone while providing prebiotic co-benefits. Poultry integrators in Southeast Asia favor these hybrid platforms for residue protocol compliance under EFSA-recognized validation.
- Enzyme-based:Esterase and epoxidase biotransformation enzymes target trichothecene mitigation in North American swine operations.
- Activated Charcoal:Broad-spectrum adsorbent reserved for acute contamination events in high-value ruminant applications.
Leading the category by volume: Clay-based. Growing fastest: Yeast-derived.
Application:
Species-specific metabolism drives formulation differentiation, with poultry and swine commanding premium pricing for rapid growth-phase protection.
- Swine:Deoxynivalenol sensitivity in nursery and grower phases necessitates trichothecene-specific detoxification. Enzyme-based biotransformation is gaining commercial validation in US Midwest operations facing Fusarium-contaminated corn.
- Poultry:Aflatoxin B1 carcinogenicity and immune suppression risks dominate broiler and layer economics. Yeast cell wall programs are expanding across Brazilian integrators to reduce veterinary intervention and maintain EU export eligibility.
- Ruminants:Rumen microbial degradation complicates bioavailability assessment, favoring rumen-protected formulations from specialized suppliers.
- Aquaculture:Emerging demand concentrates in Indonesian shrimp and Vietnamese pangasius feed mills with limited local binder production.
Highest volume concentration: Poultry. Steepest expansion trajectory: Aquaculture.
Formulation:
Automation readiness separates powder dominance from liquid system growth in integrated mill retrofits.
- Powder:Dry flowable products dominate manufacturing throughput through conventional batch mixing. Manual handling requirements limit adoption in Vietnamese and Thai facilities facing skilled labor scarcity.
- Liquid:Pumpable suspensions enable automated dosing infrastructure in modern feed mills. Indonesia's expanding poultry operations are retrofitting liquid delivery to outpace labor availability constraints.
- Granule:Dust-reduced intermediate form for premix manufacturers requiring handling efficiency.
- Pellet:Co-extruded formulations for top-dressing applications in smaller ruminant operations.
Volume leader: Powder. Gaining share fastest: Liquid.
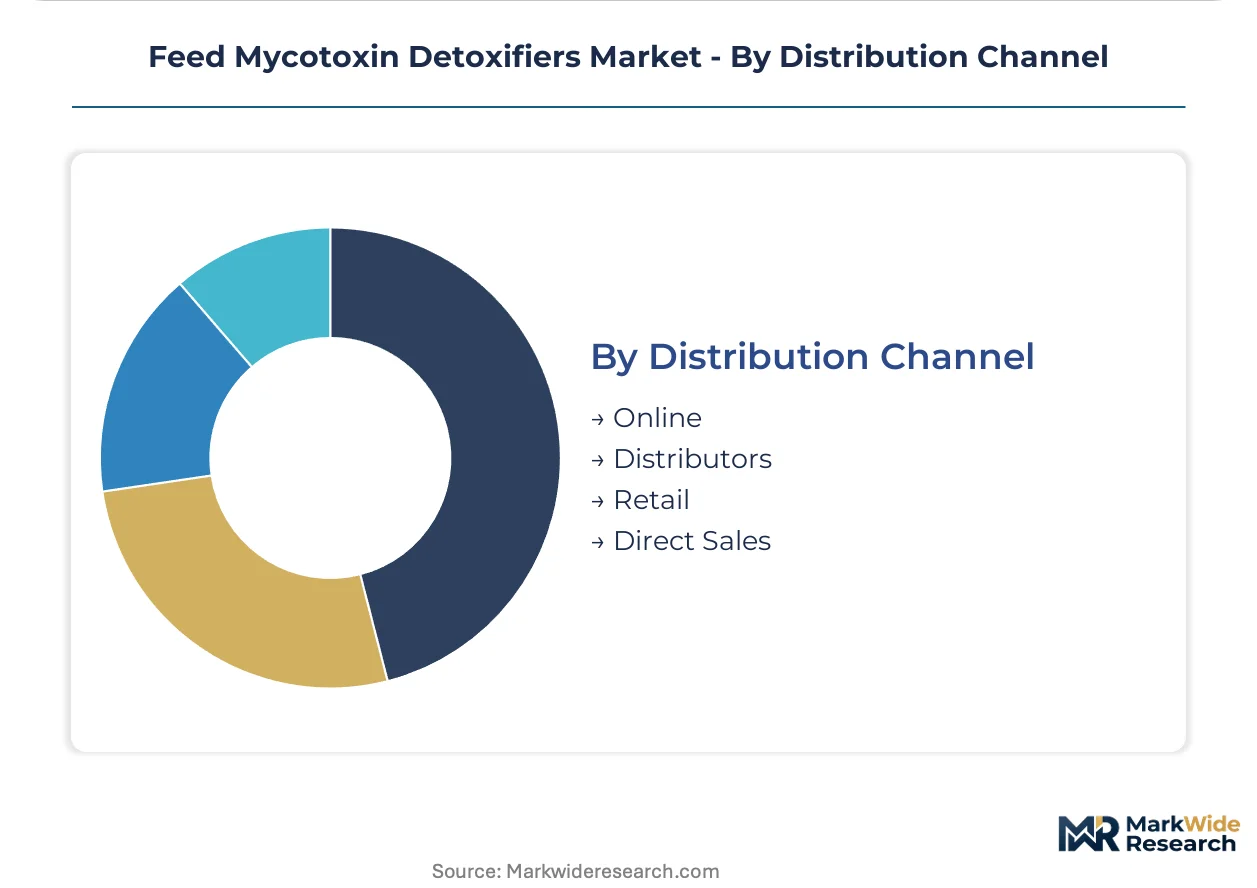
Distribution Channel:
Relationship intensity varies from technical service bundling in direct sales to transactional efficiency in digital procurement.
- Distributors:Regional feed additive specialists dominate in fragmented Asian markets lacking manufacturer presence. Technical service bundling with real-time mycotoxin monitoring captures procurement preference in Indonesia.
- Direct Sales:Integrated poultry and swine operations in Brazil and the US negotiate volume contracts with fermentation-capable suppliers. Backward integration into yeast propagation secures supply assurance for largest compounders.
- Online:Digital procurement platforms emerging for standardized clay binder replenishment in developed markets.
- Retail:Limited to smallholder supplement sales in regions with dispersed livestock ownership.
Channel concentration: Distributors. Expanding most quickly: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Batam Free Trade Zone and Vietnam's Chu Lai Open Economic Zone are accelerating feed manufacturing concentration. These tax-advantaged corridors attract integrated poultry and aquaculture operations seeking automated liquid dosing infrastructure.
Brazil
Poultry integrators in São Paulo and Paraná are expanding yeast cell wall binder programs to reduce veterinary costs. ANVISA aligns with EU residue protocols for export eligibility. Campinas industrial corridor hosts backward-integrated fermentation facilities serving domestic compounders.
United States
Midwest swine operations facing Fusarium-contaminated corn drive enzyme-based deoxynivalenol mitigation demand. FDA guidance shapes novel detoxifier registration pathways. Iowa-Illinois grain belt concentrates clay binder distribution through regional feed additive specialists.
Indonesia
Expanding poultry and shrimp feed manufacturing outpaces local binder production capacity. BPI certification requirements for imported feedstuffs create compliance premiums. Surabaya and Medan clusters retrofit liquid delivery automation to offset skilled labor scarcity.
Germany
Central European compounders prioritize EFSA-recognized validation protocols for REACH-compliant grain imports. ECHA authorization requirements tighten documentation burdens on non-EU suppliers. Bavarian fermentation facilities secure raw material supply across regional markets.
China
GB standard compliance testing extends SAMR approval cycles for biotransformation entrants. Yangtze River Delta feed mills face multi-mycotoxin detection capability gaps. Shandong Peninsula concentrates montmorillonite mining districts exposing formulators to freight volatility.
Feed Mycotoxin Detoxifiers Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with fermentation-capable suppliers commanding structural margin protection against commodity clay formulators. The vendor base organizes around three archetypes: captive yeast propagators securing upstream supply, formulation science specialists targeting species-specific premiums, and regional distributors bundling technical service with real-time monitoring. Dominant competitive moves include backward integration into yeast propagation and portfolio diversification toward hybrid adsorption-biotransformation platforms.
Within the captive fermentation tier, Biomin Holding and Cargill represent integrated supply chain models that insulate margin positions from raw material volatility. Kemin Industries occupies a specialization vector focused on bioavailability science for ruminant applications. Among European-based suppliers, BASF SE exemplifies diversified chemical platforms extending into feed additive adjacencies. These three anchors demonstrate how competitive advantage is restructuring around bioprocessing convergence rather than standalone formulation capabilities.
| Leading Market Players |
|---|
| Biomin Holding |
| Nutreco |
| Cargill |
| Alltech |
| Adisseo |
| BASF SE |
| Kemin Industries |
| Impextraco |
| ADM |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap clay mining operations in Shandong and Wyoming anchor upstream supply, translating geological concentration into pricing discipline that resists commoditization despite yeast-derived alternatives compressing formulation premiums.
Pricing Analysis
Short lead-time premiums command pricing separation from spot inventory liquidation in clay binder markets, with Brazilian grain exporters paying urgency markups for EU Green Deal compliance documentation. Three-tier pricing structure across EFSA-validated premium, standard-certified, and economy clay grades differentiates by certification burden and biomarker validation depth. Cost compression in economy montmorillonite tiers intensifies as Indonesian feed mills source undifferentiated Chinese supply. Poultry integrators in Southeast Asia exhibit highest price sensitivity, while North American swine operations facing deoxynivalenol contamination absorb enzyme-based biotransformation premiums.
Supply Chain Analysis
Returns and refurbishment flows remain negligible in mycotoxin binder supply chains, with batch-controlled fermentation waste from yeast propagation repurposed for lower-grade agricultural applications rather than true circular remanufacturing. Montmorillonite feedstock draws from concentrated Chinese Shandong Peninsula and American Wyoming mining districts, while Saccharomyces cerevisiae fermentation capacity clusters in Bavaria and São Paulo's Campinas corridor. Single-source vulnerability in premium clay grades exposes formulators to freight volatility and export licensing friction. Distribution runs through regional feed additive specialists bundling technical service with real-time mycotoxin monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Captive fermentation capacity and backward integration into yeast propagation represent the decisive upstream lever separating margin-protected suppliers from commodity clay formulators.
For Market Incumbents: Hedge against yeast-derived biotransformation compression by securing captive fermentation assets in Central Europe or Southeast Asia rather than defending clay formulation premiums alone. Biomin Holding's Bavarian facilities demonstrate how upstream control insulates against raw material volatility. EFSA-recognized validation protocols now outweigh unit cost in EU-import procurement decisions. For New Entrants and Emerging Players: Indonesian aquaculture feed mills lacking local binder production present the most penetrable buyer archetype, with shrimp and pangasius operations retrofitting automated liquid dosing faster than skilled labor availability permits. Vietnamese integrated poultry operations seeking technical service bundling over transactional procurement create second entry vector. Go-to-market through distributor partnerships offering real-time mycotoxin monitoring as attached service. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation-capable mid-caps in Southeast Asian tax-advantaged zones like Batam or Chu Lai, where feed manufacturing concentration outpaces local supply infrastructure. Long-term viability rests on hybrid adsorption-biotransformation platform ownership rather than single-mechanism specialization. Monitor SAMR registration timeline acceleration for novel biotransformation entrants as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeast Propagation | Cargill's captive fermentation secures raw material supply across Brazilian poultry markets. |
| EFSA-Recognized Validation Investment | Third-party certification unlocks EU Green Deal import premiums for Argentinian grain exporters. |
| Liquid Delivery System Automation | Pumpable formulations capture Indonesian mill retrofits outpacing skilled labor availability. |
| Multi-Mycotoxin Biotransformation R&D | Enzyme platforms targeting deoxynivalenol open premium tiers beyond aflatoxin-only protection. |
| Southeast Asian Manufacturing Footprint | Tax-advantaged zones in Batam and Chu Lai concentrate feed manufacturing investment flows. |
Research Approach
Multi-period observation of SAMR registration timelines, EU Green Deal threshold cascades, and yeast cell wall adoption rates anchored the trend analysis, supplemented by interviews with fermentation plant managers, feed mill procurement leads at Indonesian poultry integrators, technical R&D directors at European additive specialists, and distribution channel partners across Southeast Asia. Secondary validation drew from EFSA guidance documents, FDA mycotoxin action level publications, Chinese GB standard compliance protocols, and trade flow data through Brazilian and Argentinian grain export corridors. Bottom-up volume modeling triangulated against top-down value estimates.
Segment-weighting across product type, application species, formulation format, and distribution channel structured the analytical framework across the analysis window. CAGRs derived from historical trajectory fitting against regulatory inflection points and technology adoption S-curves. Species-specific bioavailability science and regional automation readiness scores served as forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization scope expansion and multi-mycotoxin detection capability diffusion beyond Western Europe. Practitioners should monitor EFSA validation protocol harmonization with Chinese SAMR standards and Indonesian BPI certification enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
US Home and Garden Fungicides Market
Agricultural Chemicals
United States Feed Enzymes Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
Neem Extract Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market