
 Global 2-Ethoxyethanol Market | 2026-2036
Global 2-Ethoxyethanol Market Size, Share, and Industry Trends Forecast 2026-2036
Global 2-Ethoxyethanol Market Foresight
Asian petrochemical producers is broadening glycol ether output to serve coating and ink compounders. BASF SE leverages integrated ethylene oxide streams to sustain cost-competitive 2-ethoxyethanol supply across European paint channels. Dow Chemical Company anchors North American distribution through captive glycol infrastructure and direct-to-mill relationships. Eastman Chemical Company specializes in high-purity grades for electronics and pharmaceutical extraction applications.
2-Ethoxyethanol, also known as ethylene glycol monoethyl ether, is a colorless liquid with a molecular formula of C4H10O2, a boiling point near 135°C, and miscibility with water and most organic solvents; manufacturers produce it via ethoxylation of ethylene oxide with ethanol. Its primary commercial purpose centers on dissolving resins and controlling viscosity in surface-coating formulations. Industrial Grade material dominates volume throughput across paint producers and textile mills, while Pharmaceutical Grade commands concentrated margin pools from agrochemical firms and chemical manufacturers facing stringent impurity ceilings. The Printing Inks application segment shows structural momentum as digital and packaging inkjet systems require precisely tuned solvent blends.
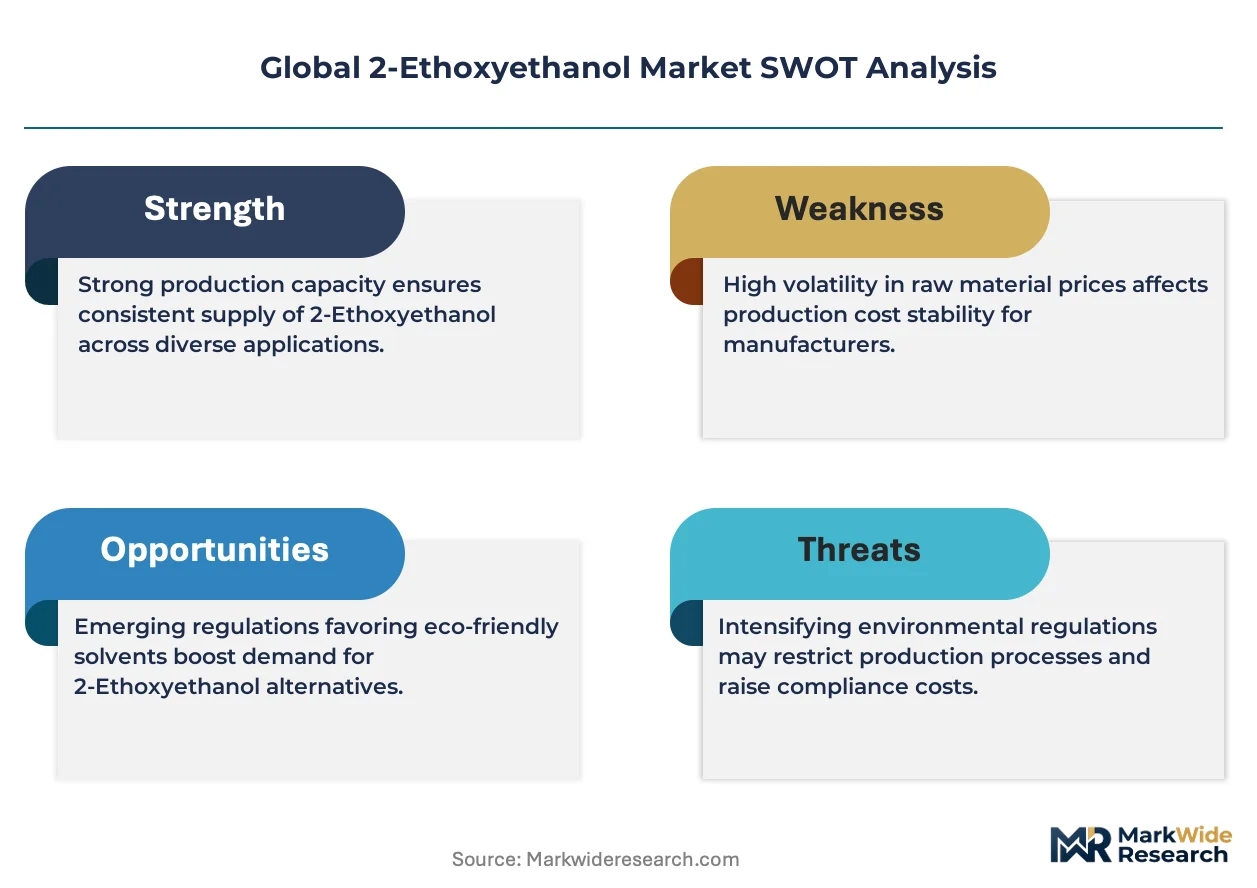
EPA toxicity evaluations under the Toxic Substances Control Act and REACH registration mandates from ECHA are elevating analytical and purification burdens for producers seeking access to United States and European Union markets. China's MEE enforces volatile organic compound emission caps that push coating formulators toward lower-solvent or closed-loop systems, indirectly constraining open-loop 2-ethoxyethanol consumption patterns. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate grade portfolios and regional supply commitments without overextending compliance infrastructure.
Market Dynamics
Water-based coating formulations are displacing solvent-heavy systems across architectural and industrial paint channels, compressing open-loop glycol ether consumption while elevating demand for precisely tuned solvent blends in digital printing and electronics cleaning applications.
Growth Catalysts
- REACH Registration Mandates:ECHA's tightened purity specifications for ethylene glycol ether derivatives are filtering out marginal producers and consolidating supply among integrated manufacturers with captive analytical capabilities.
- Packaging Inkjet Expansion:Digital printing systems require low-viscosity solvent carriers with tight evaporation curves, pulling 2-ethoxyethanol into narrow-specification ink formulations for flexible packaging converters.
- Shanghai-Ulsan Chemical Clusters:Concentrated specialty chemical manufacturing in these East Asian hubs generates localized demand for drum-quantity solvent supply with just-in-time logistics.
Market Restraints
- Ethylene Oxide Feedstock Volatility:Cracker output fluctuations and integrated petrochemical scheduling priorities create intermittent supply tightness for non-captive glycol ether producers.
- MEE VOC Emission Caps:China's Ministry of Ecology and Environment enforces volatile organic compound limits that push coating formulators toward closed-loop recovery systems, constraining fresh solvent purchases.
- Propylene Glycol Ether Substitution:Lower-toxicity propylene-based alternatives are capturing share in consumer-facing coating applications where hazard communication requirements drive reformulation.
Strategic Opportunities
- Pharmaceutical Extraction Grades:Ultra-high-purity specifications for active pharmaceutical ingredient processing command margin premiums from CDMOs facing FDA and EMA impurity ceilings.
- India BIS Certification Pathway:Bureau of Indian Standards implementation of solvent quality benchmarks creates first-mover advantage for producers establishing analytical partnerships with Mumbai and Ahmedabad chemical distributors.
- Semiconductor Wet Chemistry:Advanced node chip fabrication requires particle-controlled solvent blends where 2-ethoxyethanol serves as a precision cleaning component in photoresist stripping formulations.
Industry Challenges
- Analytical Chemist Talent Scarcity:EPA TSCA and REACH compliance documentation requires specialized expertise in trace impurity quantification that outpaces university training pipeline output.
- Multi-Jurisdiction Certification Timelines:Staggered registration deadlines across United States, European Union, and Chinese regulatory frameworks force redundant toxicology study investments.
- Legacy Equipment Compatibility:Paint producers running decades-old mixing infrastructure face gasket and seal material degradation when transitioning between solvent classes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 2-Ethoxyethanol Market |
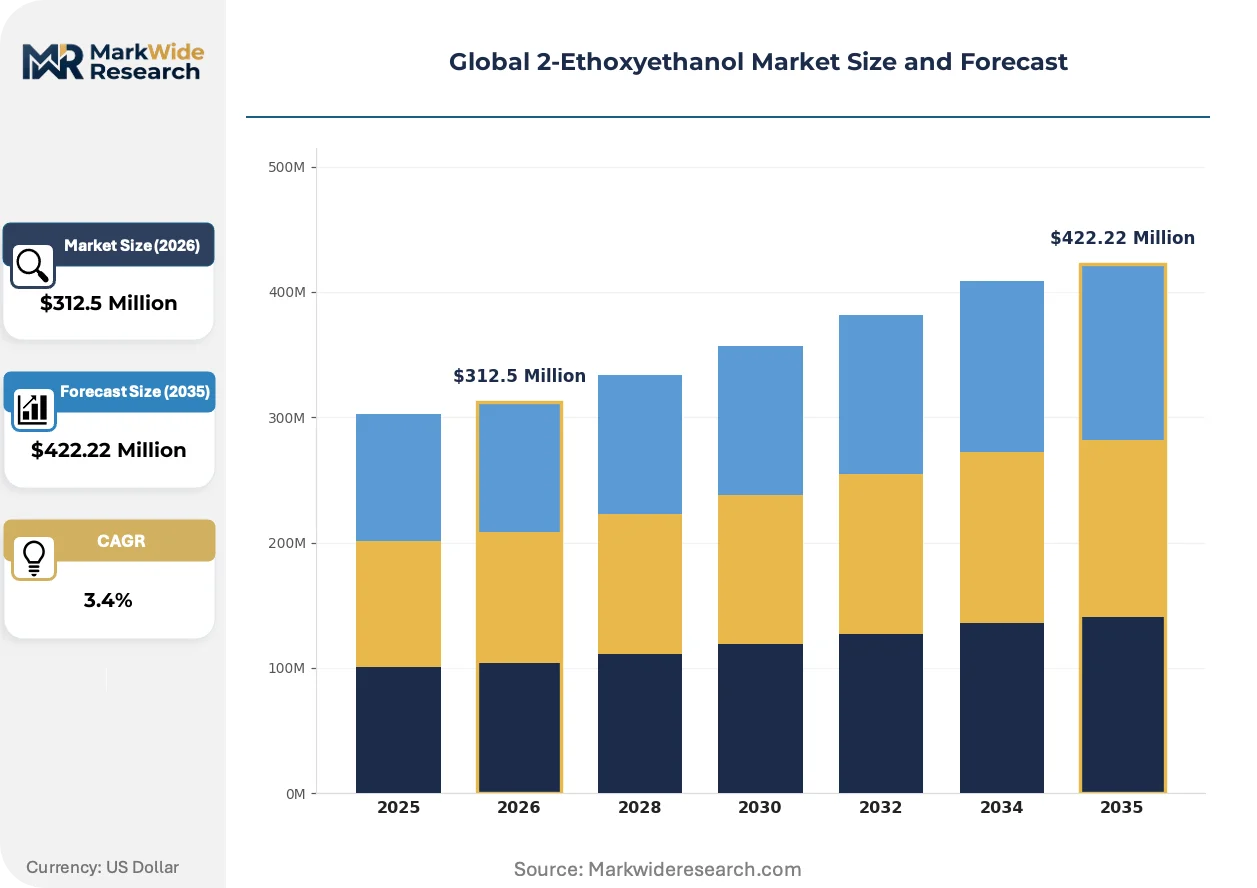
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $422.22 Million |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Industrial Grade, Technical Grade, Laboratory Grade Application: Paints & Coatings, Printing Inks, Adhesives, Textile Processing, Cleaning Agents, Pesticides End User Industry: Chemical Manufacturers, Agrochemical Firms, Printing Houses, Textile Mills, Paint Producers, Cleaning Service Providers Packaging Type: Drums, Bulk Containers, Carboys, Totes, Barrels, Intermediate Bulk Containers |
| Companies Covered | BASF SE, Dow Chemical Company, Eastman Chemical Company, SABIC, Oxea GmbH, Huntsman Corporation, Solvay S.A., Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 2-Ethoxyethanol Market Shifts & Advancements
Continuous processing technology and real-time analytical feedback loops are compressing batch-to-batch variation in glycol ether production, enabling specification grades that were previously achievable only through extensive post-processing.
Membrane separation technology for solvent dehydration and trace contaminant removal is converging with inline spectroscopic monitoring to produce pharmaceutical-grade 2-ethoxyethanol without energy-intensive distillation sequences. Specialty chemical producers in Germany and Japan are retrofitting existing ethoxylation trains with these hybrid purification systems. The capital efficiency of this approach is compressing entry barriers for mid-scale producers seeking electronics-grade certification.
EPA toxicity evaluations under the Toxic Substances Control Act are elevating data requirements for glycol ether reproductive toxicity endpoints, extending registration timelines and forcing producers to commission new mammalian study suites. Industrial coating formulators in the United States are responding by accelerating qualification of alternative solvent carriers in anticipation of potential hazard reclassification. The analytical services sector is capturing incremental revenue from rush toxicology screening contracts.
Specification-driven procurement contracts are replacing spot-market purchasing for volume coating manufacturers, with ink compounders and paint mills negotiating multi-year supply agreements that embed purity certification and logistics performance guarantees. Distributor intermediaries are losing share to direct mill relationships as buyers consolidate vendor bases and demand audit rights over manufacturing facilities. This pattern is most visible among German automotive OEM coating suppliers and Korean electronics chemical purchasers.
Global 2-Ethoxyethanol Market Segmentation
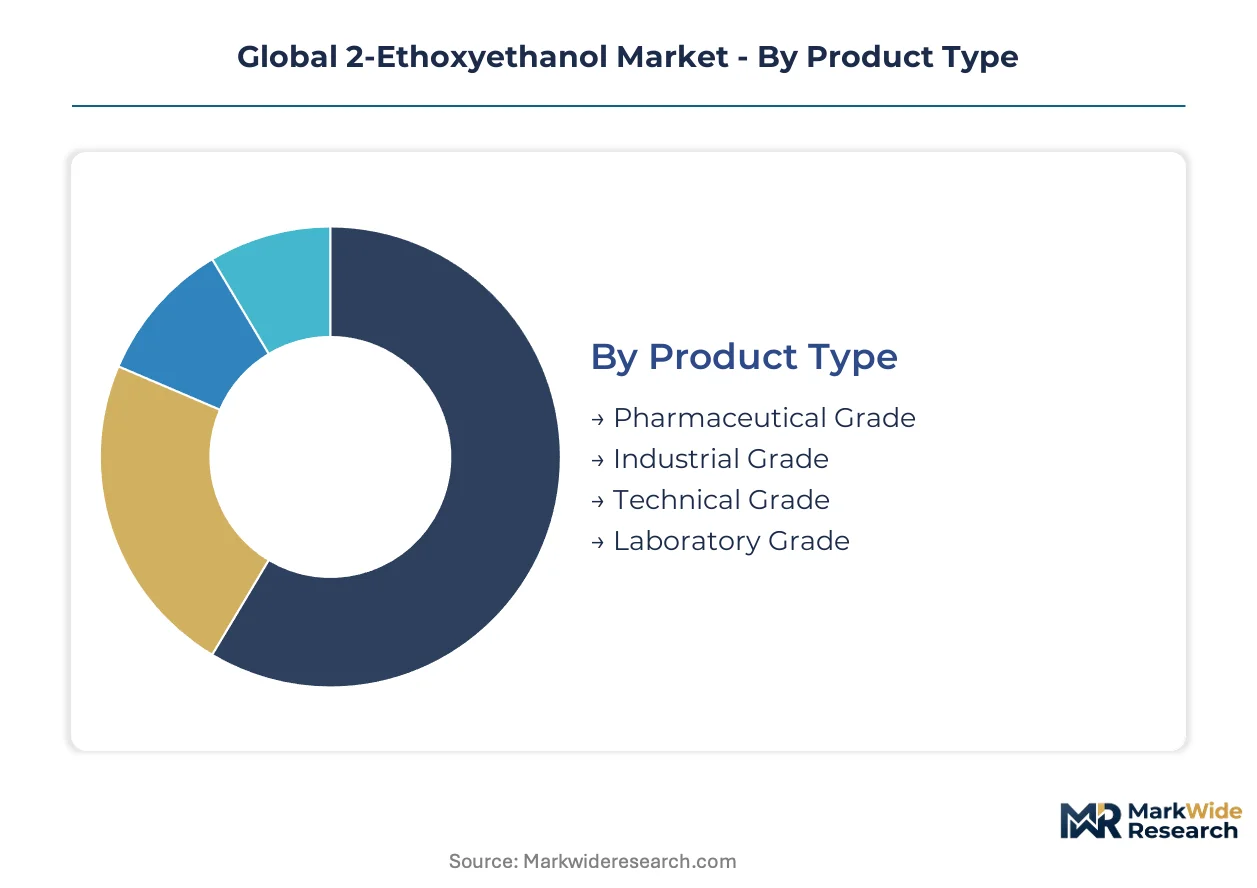
2-Ethoxyethanol demand fragments across purity tiers and logistics formats that dictate margin capture and regulatory burden. Specification grades determine whether producers compete on volume throughput or premium certification, while packaging choices reflect customer scale and geographic proximity to manufacturing clusters.
Product Type:
Industrial Grade commands volume share through paint and textile channels, while Pharmaceutical Grade concentrates margin pools in regulated extraction applications.
- Industrial Grade:Standard purity specifications serve coating formulators and textile mills with cost-sensitive procurement. Demand concentrates in German automotive paint channels and Chinese architectural coating plants facing MEE VOC emission caps that constrain open-loop consumption.
- Pharmaceutical Grade:Ultra-high-purity material meets FDA and EMA impurity ceilings for active pharmaceutical ingredient processing. CDMOs in Switzerland and Massachusetts generate concentrated orders for extraction-grade solvent with full certification documentation.
- Technical Grade:Intermediate purity tier serves agrochemical formulation where pesticide solubility requirements exceed industrial specifications but fall short of pharmaceutical thresholds.
- Laboratory Grade:Small-batch analytical and research applications in university and corporate R&D settings require NIST-traceable certification and minimal metal content.
Today's leader: Industrial Grade. Tomorrow's challenger: Pharmaceutical Grade.
Application:
Surface treatment applications dominate tonnage, while digital printing and precision cleaning pull solvent into higher-specification formulations.
- Paints & Coatings:Resin dissolution and viscosity control in water-based and solvent-borne systems. German OEM coating suppliers and Chinese architectural paint producers anchor demand, though water-based formulation shifts compress open-loop glycol ether consumption.
- Printing Inks:Digital and packaging inkjet systems require low-viscosity carriers with tight evaporation curves. Flexible packaging converters in Japan and Italy are expanding narrow-specification ink formulations that pull 2-ethoxyethanol into precisely tuned blends.
- Adhesives:Solvent-based bonding systems for industrial assembly and construction applications, particularly in Korean electronics manufacturing and Mexican automotive supply chains.
- Textile Processing:Dye carrier and fiber conditioning applications in Indian spinning mills and Turkish finishing plants.
- Cleaning Agents:Precision electronics cleaning and industrial degreasing, with semiconductor wet chemistry applications in Taiwan and Arizona fabs requiring particle-controlled blends.
- Pesticides:Agrochemical formulation solvent for emulsifiable concentrates, concentrated in Brazilian soybean belt and Australian grain belt distribution.
Coating tonnage still dominates, but inkjet and electronics cleaning applications are climbing the fastest.
End User Industry:
Paint producers and chemical manufacturers drive volume procurement, while agrochemical and electronics sectors concentrate premium-grade demand.
- Paint Producers:Architectural and industrial coating mills in Germany, China, and the United States generate drum-quantity and bulk orders with specification-driven procurement contracts replacing spot purchasing.
- Chemical Manufacturers:Intermediate synthesis and solvent blending operations in the Antwerp-Rotterdam chemical cluster and Singapore Jurong Island purchase technical and industrial grades for captive processing.
- Agrochemical Firms:Pesticide formulators in India and Brazil require pharmaceutical-grade certification for certain active ingredient extractions, creating margin premiums.
- Printing Houses:Flexible packaging converters in Italy and Japan driving narrow-specification ink solvent demand.
- Textile Mills:Dyeing and finishing operations in Turkey and Bangladesh purchasing industrial-grade material for fiber processing.
- Cleaning Service Providers:Electronics and precision equipment cleaning contractors in Taiwan and Arizona fabs requiring semiconductor-grade specifications.
Volume leadership sits with paint producers. Premium expansion is concentrated among agrochemical and electronics chemical purchasers.
Packaging Type:
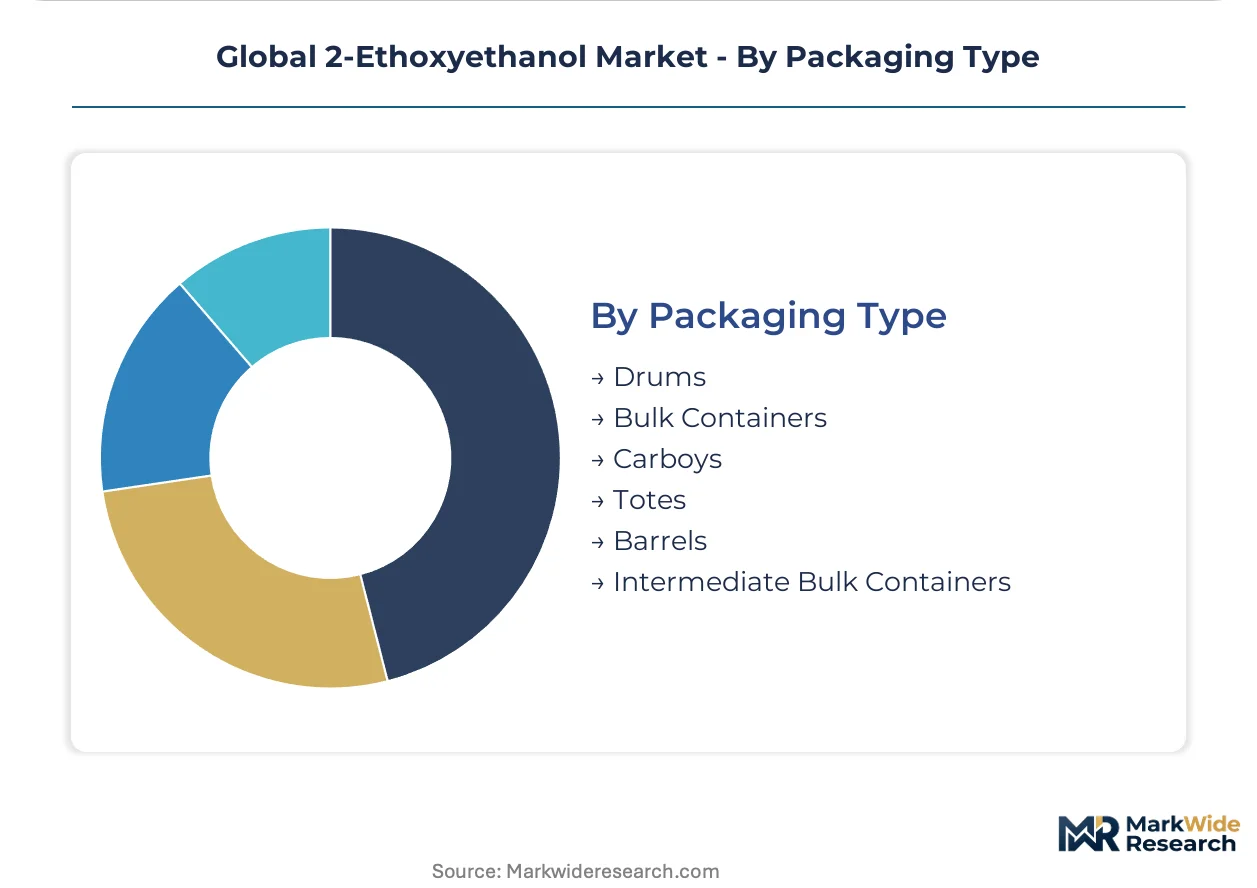
Container selection tracks customer scale and geographic distance from manufacturing assets, with bulk formats dominating integrated chemical clusters and smaller units serving dispersed end-users.
- Bulk Containers:Tank truck and railcar deliveries serve large coating mills and chemical manufacturers with direct-to-plant logistics, concentrated in German Ruhr industrial zone and Shanghai chemical park.
- Intermediate Bulk Containers:1000-liter totes bridge mid-scale users with just-in-time inventory needs, favored by Korean electronics chemical distributors and Indian agrochemical compounders.
- Drums:Standard 200-liter steel drums serve regional paint distributors and textile mills with moderate consumption rates and limited on-site storage.
- Barrels:Smaller wooden or fiber drums for specialty chemical distributors serving laboratory and pilot-scale customers.
- Carboys:Glass or plastic containers for high-purity pharmaceutical and laboratory grades requiring contamination protection.
- Totes:Flexible intermediate bulk containers for agrochemical and cleaning product formulators with seasonal demand patterns.
Bulk infrastructure anchors supply in manufacturing clusters. Tote and drum flexibility is gaining share among distributed specialty chemical users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting 2-ethoxyethanol production toward jurisdictions with lower compliance costs, even as REACH and EPA standards tighten purity requirements in premium markets. Manufacturers with captive ethylene oxide infrastructure exploit this gap by serving both high-specification European buyers and cost-sensitive Asian formulators from integrated hubs.
China
Architectural coating mills in Jiangsu and Zhejiang provinces drive drum-quantity solvent demand as water-based paint formulations displace solvent-heavy systems. MEE volatile organic compound emission caps push formulators toward closed-loop recovery, constraining fresh purchases but elevating specification requirements for retained solvent. The Shanghai chemical park anchors glycol ether output serving domestic inkjet ink compounders and Korean electronics chemical distributors.
Germany
Automotive OEM coating suppliers in the Ruhr industrial zone negotiate multi-year supply agreements embedding purity certification and direct-to-mill logistics. ECHA REACH registration mandates filter marginal producers, consolidating supply among integrated manufacturers with captive analytical capabilities. BASF SE leverages Ludwigshafen ethylene oxide streams to sustain cost-competitive supply across European paint channels.
United States
Industrial coating formulators accelerate qualification of alternative solvent carriers as EPA Toxic Substances Control Act toxicity evaluations extend registration timelines. Semiconductor fabs in Arizona and Oregon require particle-controlled solvent blends for photoresist stripping, pulling ultra-high-purity grades into advanced node chip fabrication. Dow Chemical Company anchors North American distribution through captive glycol infrastructure.
South Korea
Electronics chemical purchasers in the Ulsan industrial zone consolidate vendor bases and demand audit rights over manufacturing facilities, bypassing distributor intermediaries. MFDS pharmaceutical-grade specifications create margin premiums for extraction-grade solvent with full certification documentation. Local specialty chemical clusters generate just-in-time demand for intermediate bulk container deliveries.
India
Agrochemical formulators in Gujarat and Maharashtra require pharmaceutical-grade certification for certain active ingredient extractions, creating concentrated margin pools. BIS solvent quality benchmarks implementation creates first-mover advantage for producers establishing analytical partnerships with Mumbai and Ahmedabad chemical distributors. Textile dyeing operations in Tamil Nadu purchase industrial-grade material for fiber processing.
Global 2-Ethoxyethanol Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and electronics-grade specifications as differentiation vectors. The vendor base stratifies across integrated petrochemical majors with captive ethylene oxide supply, mid-scale specialty chemical producers with membrane purification capabilities, and regional distributors losing share to direct mill relationships. Three archetypes dominate: integrated upstream players controlling feedstock economics, specification specialists capturing premium margins in regulated applications, and logistics-anchored distributors serving dispersed small-batch users. Competitive moves concentrate on backward integration into ethylene oxide supply and multi-year procurement contracts embedding purity guarantees.
Within the integrated petrochemical tier, BASF SE and Dow Chemical Company exemplify upstream control strategies, while Eastman Chemical Company occupies a position as a specification specialist. BASF SE anchors European supply through Ludwigshafen infrastructure. Dow Chemical Company represents North American scale advantages in captive glycol distribution. Eastman Chemical Company exemplifies the high-purity archetype serving electronics and pharmaceutical extraction applications.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| Eastman Chemical Company |
| SABIC |
| Oxea GmbH |
| Huntsman Corporation |
| Solvay S.A. |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Ethylene oxide spot price movements at the Rotterdam hub cascade through glycol ether value chains into three distinct pricing tiers for 2-ethoxyethanol buyers. Pharmaceutical-grade certification commands substantial premiums over industrial material as REACH compliance costs concentrate among integrated producers with captive analytical infrastructure.
Pricing Analysis
Distributor margin compression now dominates channel economics as direct-to-mill relationships displace intermediary layers among German automotive coating suppliers and Korean electronics chemical purchasers. A three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade extraction solvents from industrial coating carriers and technical agrochemical grades. Price differentiation hinges on certification documentation depth and volume scale, with drum-quantity buyers facing sharper cost compression than bulk tank-truck purchasers. Margins are tightening due to redundant toxicology study investments across EPA TSCA and REACH registration timelines.
Supply Chain Analysis
Regional distribution centers in the Antwerp-Rotterdam chemical cluster and Shanghai chemical park anchor hub-and-spoke patterns serving dispersed coating mills and electronics fabs. Supply concentrates in Germany, China, and South Korea where integrated ethylene oxide infrastructure feeds captive glycol ether trains. Raw material dependencies draw from ethylene cracker output, ethanol feedstock, and specialized catalyst systems. Single-source vulnerability runs through Ludwigshafen and Ulsan manufacturing nodes where concentrated capacity creates chokepoint exposure. Distribution runs through direct mill relationships with specification-driven procurement contracts replacing spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance burdens in Europe create cost differentials against Asian production zones with streamlined registration pathways.
For Market Incumbents: Lock in multi-year supply agreements embedding purity certification and logistics performance guarantees before EPA TSCA toxicity reclassifications accelerate alternative solvent qualification among US coating formulators. Deepen backward integration into ethylene oxide supply to defend feedstock economics against cracker output volatility. Prioritize membrane purification capability investments to capture pharmaceutical-grade margin pools from CDMOs facing FDA impurity ceilings. For New Entrants and Emerging Players: Begin with India BIS certification partnerships in Mumbai and Ahmedabad distribution corridors where solvent quality benchmark implementation creates first-mover positioning ahead of formal mandate enforcement. Target agrochemical formulation segments in Gujarat and Maharashtra where pharmaceutical-grade extraction demand concentrates among pesticide producers. Pursue analytical service bundling as a go-to-market angle to differentiate beyond commodity solvent supply. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialty chemical producers possessing membrane separation retrofit capability and existing ethoxylation infrastructure in East Asian chemical parks. Five-to-ten year viability favors specification specialists over volume-commodity players as regulatory divergence between jurisdictions intensifies grade portfolio complexity. Watch for EPA TSCA reproductive toxicity endpoint reclassification announcements as the critical inflection signal for alternative solvent substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | BASF SE and Dow Chemical Company leverage captive feedstock to sustain cost-competitive supply across European and North American paint channels. |
| Membrane Purification Retrofit | Specialty chemical producers in Germany and Japan deploy hybrid dehydration systems to produce pharmaceutical-grade material without energy-intensive distillation. |
| Multi-Year Supply Agreement Embedding | German automotive OEM coating suppliers negotiate contracts with purity certification and audit rights over manufacturing facilities. |
| Pharmaceutical-Grade Certification Investment | CDMOs in Switzerland and Massachusetts generate concentrated orders for extraction-grade solvent with full FDA and EMA documentation. |
| Direct-to-Mill Logistics Partnership | Korean electronics chemical purchasers in Ulsan consolidate vendor bases and bypass distributor intermediaries through just-in-time IBC deliveries. |
Research Methodology
Bottom-up coating and ink formulation modeling reconciled against top-down ethylene oxide supply tracking forms the analytical core of this study. Primary interviews with plant managers at glycol ether production facilities, procurement leads at downstream paint and electronics OEMs, distribution channel partners in chemical parks, and technical R&D directors at solvent blenders combine with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Triangulation across these sources ensures demand estimates align with disclosed production capacity and trade flow patterns.
Historical trendline analysis of ethylene glycol ether derivative pricing and volume trajectories informs the projection framework across the analysis window. Segmentation dimensions modeled include grade tier purity specifications, end-use industry application mix, packaging format logistics requirements, and regional production hub concentration. CAGRs derive from fitted trend extrapolation adjusted for regulatory intervention timing and feedstock cost elasticity. Forecast inputs incorporate MEE VOC emission cap enforcement intensity and semiconductor node advancement rates for wet chemistry demand.
Several conditions sit outside the modeled scope, including sudden feedstock supply disruptions from cracker maintenance cycles, unanticipated EPA hazard reclassifications, and geopolitical trade restrictions affecting ethylene oxide derivative flows. Forecasts reflect documented assumptions around regulatory timeline adherence and substitution elasticity parameters. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Hydrogen Cyanamide Market
Solvents
Dibutyl Ether Market
Solvents
Global Xylenols Market
Solvents
Global Solvent Evaporation Market
Solvents
Phenylacetonitrile Market
Solvents
N-Pentyl Chloride Market
Solvents
Butyl Glycol Market
Solvents
Solvent Green 7 Market
Solvents
Decanol Market
Solvents
Japan Acetonitrile Market
Solvents
Vapor Degreasing Solvents Market
Solvents
Allyl Cyanide Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Ionic Liquids Market
Solvents
Dimethyl Ether (DME) Market
Solvents
Reactive Diluents Market