
 Hydrocarbon Solvents Market | 2026-2036
Hydrocarbon Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocarbon Solvents Market Outlook
Specialty chemical distribution networks is reconfiguring around consolidated bulk terminals and regional blending facilities. ExxonMobil Corporation leverages integrated refinery-solvent operations across the US Gulf Coast. Shell plc sustains long-term supply agreements with European automotive OEMs. TotalEnergies SE anchors its position through bio-based solvent R&D programs in France and Belgium.
Hydrocarbon solvents are petroleum-derived liquid mixtures composed primarily of aliphatic or aromatic carbon chains, typically refined through catalytic reforming or solvent extraction to achieve specific boiling point ranges between 30°C and 300°C. These solvents function primarily as diluents, carriers, and cleaning agents in industrial formulations where controlled evaporation rates determine application performance. Aliphatic solvents dominate volume consumption in paints and coatings applications due to lower aromatic content and favorable toxicity profiles. Aromatic solvents command premium positioning in ink manufacturing where superior solvency power enables higher pigment loading. Oxygenated solvents represent the fastest-growing structural category as formulators substitute traditional hydrocarbons to meet tightening volatile organic compound regulations.
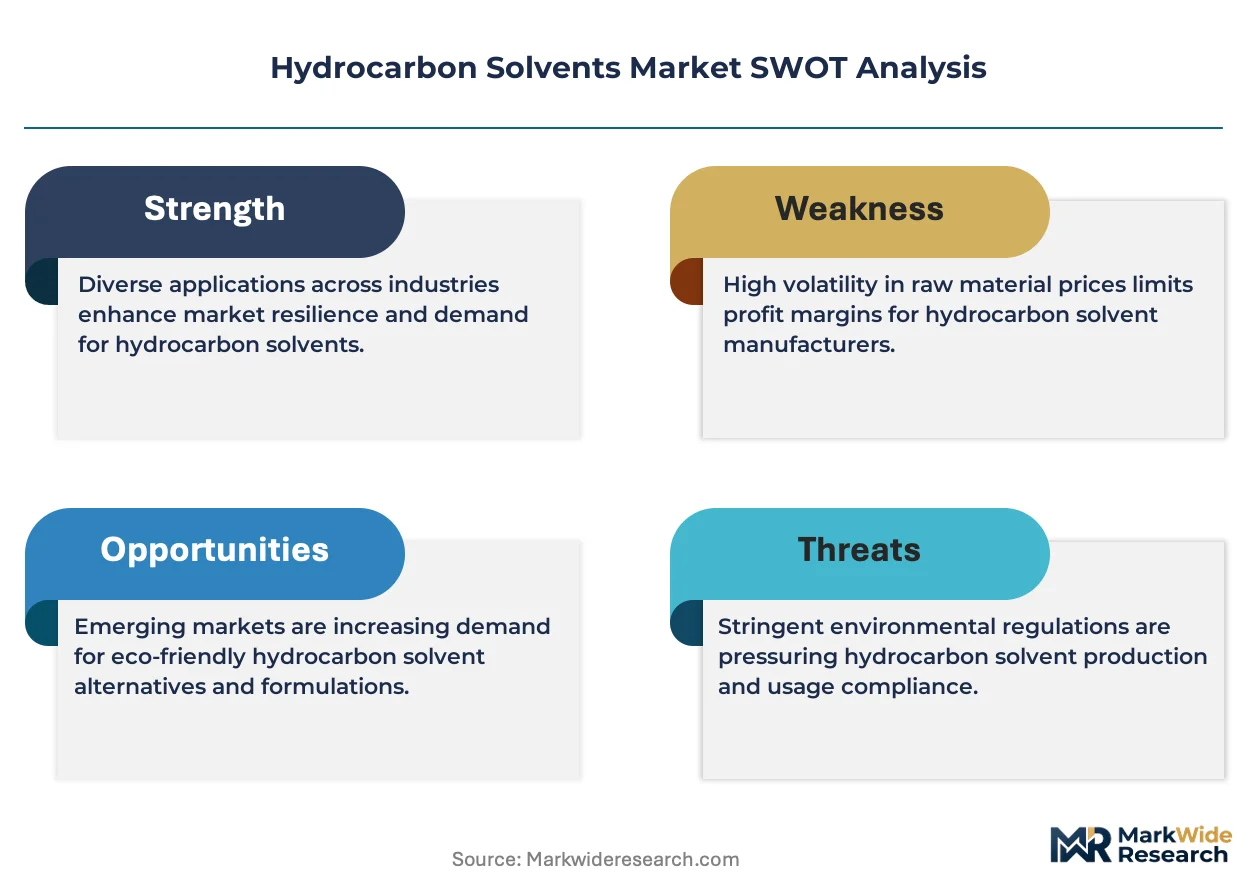
EPA regulations under the Clean Air Act constrain permissible solvent emissions in US manufacturing facilities, while REACH registration requirements in Europe mandate comprehensive toxicity documentation for aromatic solvent imports. China's MEE enforces increasingly stringent GB standards on industrial solvent emissions in the Yangtze River Delta manufacturing cluster. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualify alternative solvent chemistries before compliance deadlines tighten.
Market Dynamics
REACH compliance deadlines and EPA volatile organic compound thresholds are forcing simultaneous reformulation across automotive refinishing and construction coating supply chains, compressing product development cycles while elevating R&D spend requirements.
Growth Catalysts
- Automotive refinishing demand:Collision repair networks in Germany and China are expanding solvent consumption for high-gloss clearcoat applications as vehicle parc ages and premium finish standards tighten.
- REACH registration completion:Full toxicity dossier acceptance for C9-C12 aromatic streams has clarified import pathways into European Union manufacturing corridors, reducing regulatory uncertainty for formulators.
- Yangtze River Delta industrial clustering:Paints and coatings producers are consolidating procurement through Shanghai and Ningbo bulk terminals, achieving scale efficiencies in aliphatic solvent uptake.
Market Restraints
- Naphtha feedstock volatility:Catalytic reformer output swings tied to regional refinery maintenance schedules create input cost unpredictability for solvent blenders.
- MEE emission enforcement:China's Ministry of Ecology and Environment GB standard tightening in Jiangsu and Zhejiang provinces is constraining operational run rates at legacy solvent recovery facilities.
- Oxygenated solvent substitution:Bio-based esters and glycol ethers are capturing specification share in decorative coatings where odor and toxicity profiles drive purchasing decisions.
Strategic Opportunities
- India construction chemicals:Infrastructure spending in Maharashtra and Gujarat is expanding demand for high-boiling aliphatic solvents in waterproofing membrane formulations.
- EU Green Deal bio-based mandates:Renewable content thresholds in public procurement specifications are creating specification premiums for hydrotreated vegetable oil-derived hydrocarbon alternatives.
- Digital inventory platforms:Regional distributors are deploying just-in-time solvent blending through app-based ordering systems that compress working capital cycles for mid-size coatings manufacturers.
Industry Challenges
- Toxicologist certification scarcity:REACH-compliant safety data sheet authoring requires specialized regulatory toxicology expertise that remains concentrated in Basel and Rotterdam service hubs.
- Legacy formulation integration:Coatings manufacturers with extensive solvent-based product libraries face complex compatibility testing when introducing lower-aromatic alternatives without disrupting established application parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocarbon Solvents Market |
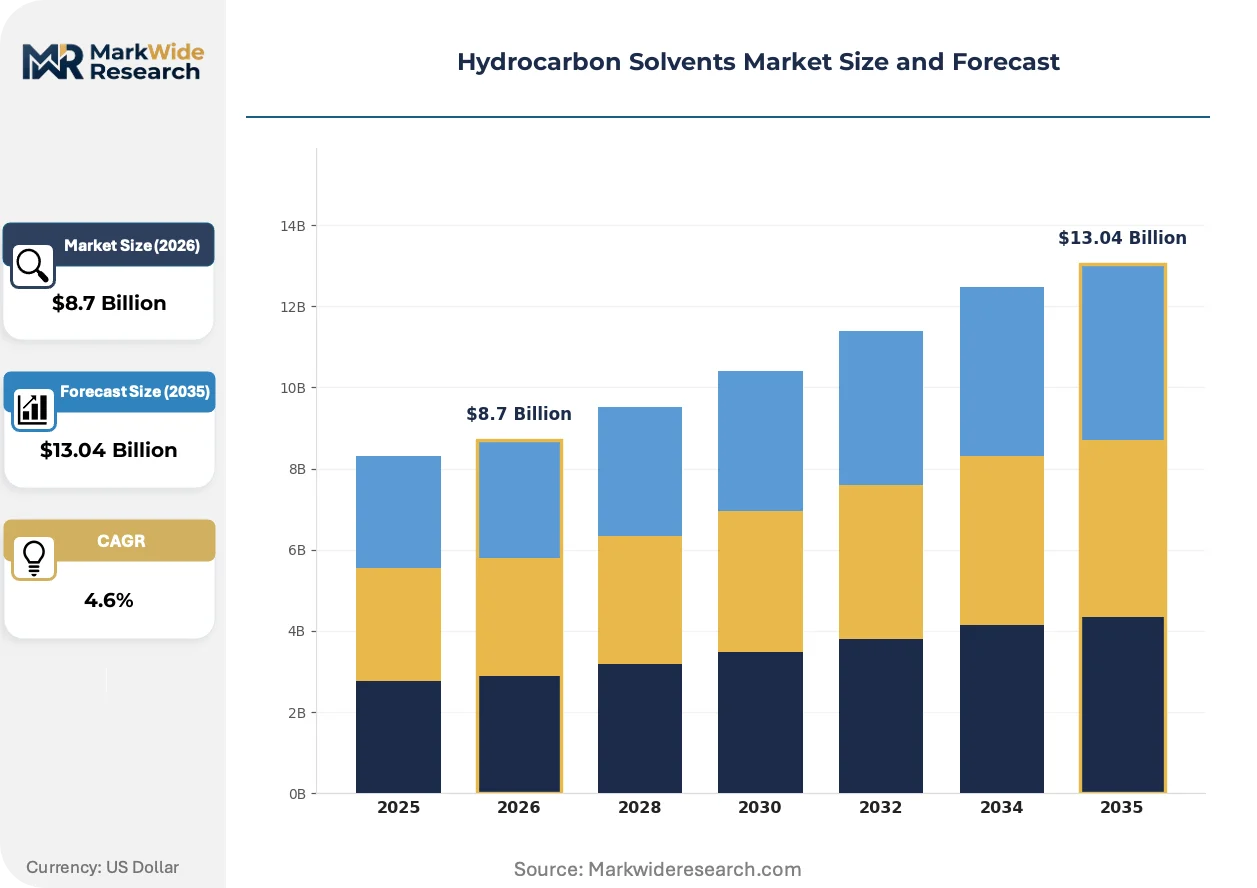
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aliphatic Solvents, Aromatic Solvents, Non-Aromatic Solvents, Oxygenated Solvents Application: Paints & Coatings, Adhesives, Cleaners, Ink Manufacturing End User: Automotive, Construction, Pharmaceuticals, Chemicals Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms |
| Companies Covered | ExxonMobil Corporation, Shell plc, TotalEnergies SE, Chevron Phillips Chemical Company LLC, BASF SE, Phillips 66, LyondellBasell Industries N.V., Calumet Inc., Sasol Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocarbon Solvents Market Strategic Shifts
Formulation science is pivoting toward controlled evaporation profile engineering as regulatory thresholds harden, with solvent producers investing in narrow-cut distillation capabilities and predictive modeling tools.
Membrane separation technology for solvent recovery and reuse is rendering obsolete conventional thermal distillation systems in high-volume coating operations. Automotive OEM paint shops in Stuttgart and Wolfsburg are retrofitting closed-loop recovery units that cut virgin solvent intake by half. The capital efficiency gains from membrane systems are compressing payback periods for environmental compliance investments.
EPA National Emission Standards for Hazardous Air Pollutants subpart HHHH is tightening control requirements for miscellaneous coating manufacturing operations. Facility-wide emission limits are compelling integrated producers to deploy carbon adsorption and thermal oxidizer combinations. Small and mid-size toll blenders in Ohio and Texas are consolidating through shared compliance infrastructure to defray capital burdens.
Specification-driven procurement now dominates solvent selection for architectural coatings, with buyers prioritizing hazard communication compliance over unit cost. Distributors with in-house regulatory documentation capabilities are displacing traditional merchant traders in specification-sensitive segments. This pattern concentrates most visibly in French and Italian decorative paints markets where retailer certification requirements have proliferated.
Hydrocarbon Solvents Market Segmentation
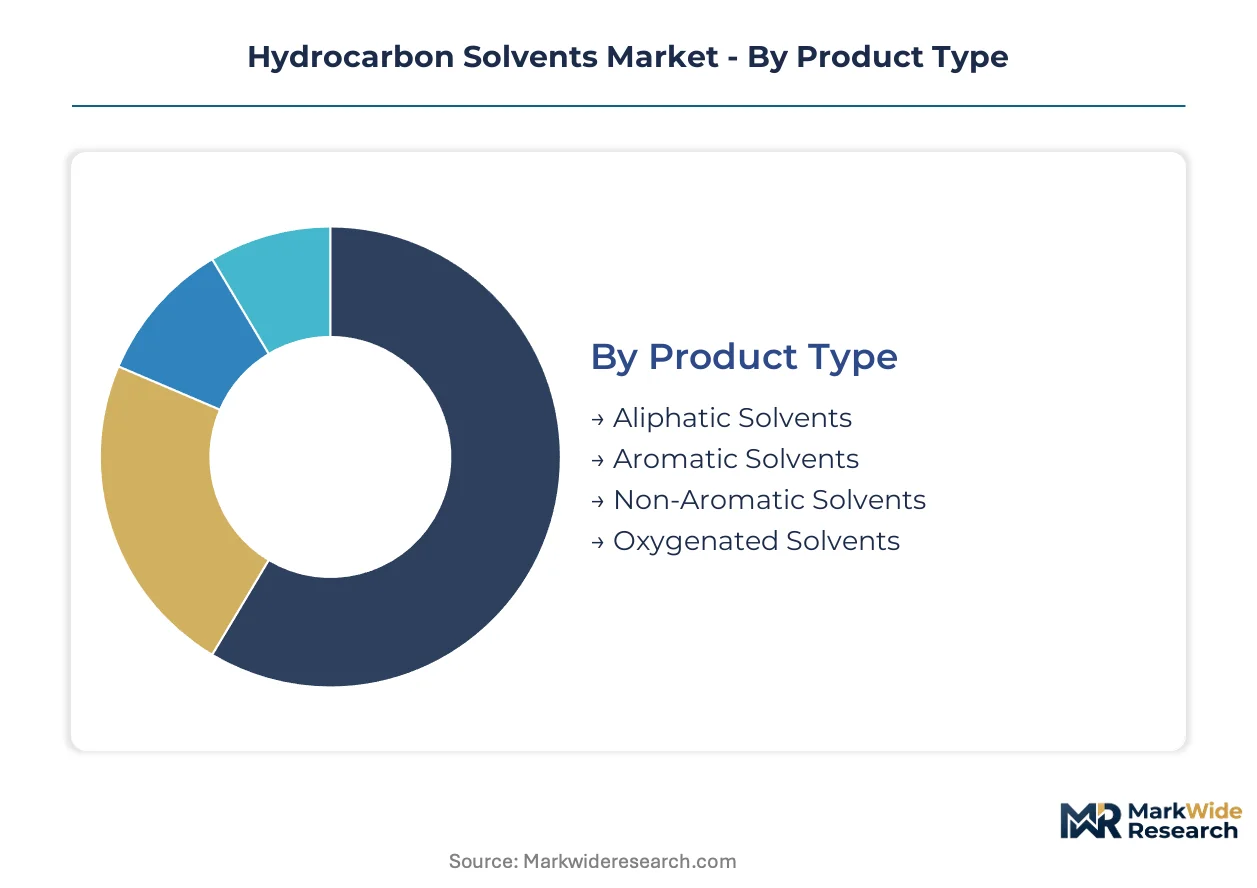
Segmentation in hydrocarbon solvents reveals distinct procurement rhythms across product chemistries and end-use verticals. Formulators select solvent grades based on evaporation profiles, regulatory limits, and compatibility with resin systems. Understanding these segment dynamics enables suppliers to align inventory positioning with demand cycles.
Product Type:
Aliphatic solvents turn inventory fastest in coating operations, while oxygenated alternatives cycle more slowly due to qualification testing requirements. Aromatic grades occupy intermediate velocity positions dependent on REACH documentation status.
- Aliphatic Solvents:These petroleum-derived mixtures contain straight-chain and branched hydrocarbons with boiling ranges typically between 30°C and 200°C. Demand concentrates in German and Chinese automotive refinishing shops where low aromatic content satisfies workplace exposure limits. Collision repair networks specify these grades for basecoat applications requiring controlled flash-off times.
- Aromatic Solvents:Ring-structured hydrocarbons including toluene and xylene derivatives deliver superior solvency power for high-solids coatings. Ink manufacturers in France and Italy specify these streams for gravure printing where pigment loading determines print quality. REACH registration completion for C9-C12 streams has stabilized import pathways into EU manufacturing corridors.
- Non-Aromatic Solvents:Hydrotreated paraffinic streams with near-zero benzene content serve pharmaceutical extraction and food-contact applications.
- Oxygenated Solvents:Ester and glycol ether chemistries substitute for traditional hydrocarbons in decorative coatings where odor profiles drive purchasing decisions.
Aliphatic solvents anchor the volume base while oxygenated solvents gain share at the steepest rate.
Application:
Cost tier differentiation separates specification-grade formulations from commodity blending applications. Premium coating segments command solvent purity certifications that standard industrial cleaners do not require.
- Paints & Coatings:Architectural and industrial coating formulations consume the majority of hydrocarbon solvent volume, with selection criteria centering on evaporation rate matching to resin cure schedules. Automotive OEM clearcoat operations in Stuttgart specify narrow-cut aliphatic streams for gloss retention.
- Adhesives:Solvent-borne pressure-sensitive adhesive production relies on toluene and hexane blends for tackifier dissolution. Tape manufacturers in Jiangsu province consolidate procurement through Shanghai bulk terminals to achieve scale efficiencies.
- Cleaners:Degreasing and precision cleaning applications favor low-residue aliphatic grades for metal fabrication and electronics assembly.
- Ink Manufacturing:Publication gravure and flexographic printing specify aromatic-rich cuts for deep color saturation on porous substrates.
Paints and coatings operations generate the highest absolute solvent throughput, though adhesive applications are expanding most quickly in Asia-Pacific industrial corridors.
End User:
Customer type segmentation separates multinational formulators with integrated solvent recovery from mid-size toll blenders purchasing spot volumes. Procurement sophistication varies sharply across these tiers.
- Automotive:OEM paint shops and collision repair networks specify solvents against manufacturer-approved material lists. BMW and Volkswagen assembly plants in Germany operate closed-loop recovery systems that cut virgin solvent intake.
- Construction:Waterproofing membrane and sealant formulators in Maharashtra and Gujarat drive demand for high-boiling aliphatic cuts. Infrastructure spending in these states expands specification volumes for bitumen modification.
- Pharmaceuticals:API extraction and crystallization processes require pharmacopeia-compliant grades with documented impurity profiles.
- Chemicals:Intermediate manufacturing and process solvents serve diverse industrial synthesis applications with less stringent purity requirements.
Automotive end users maintain the most stringent qualification protocols, while construction sector buyers are expanding procurement most aggressively.
Distribution Channel:
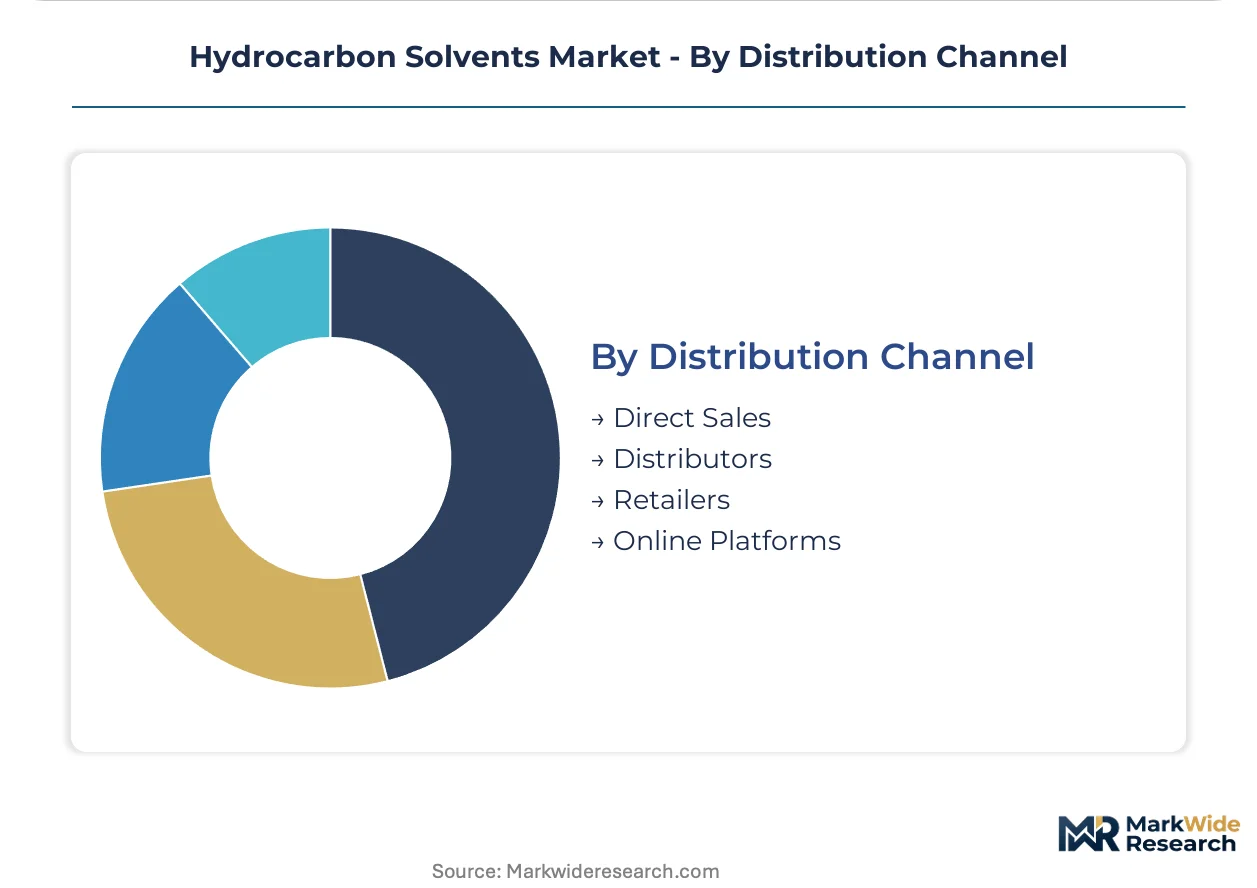
Supply concentration patterns favor direct relationships for high-volume consumers, while fragmented demand routes through distributor networks. Channel selection correlates with shipment size and regulatory documentation requirements.
- Direct Sales:Integrated refinery-solvent producers serve automotive OEMs and multinational coatings manufacturers through dedicated supply agreements. ExxonMobil leverages Gulf Coast infrastructure for pipeline-delivered volumes to Texas formulation plants.
- Distributors:Regional chemical distributors with in-house regulatory capabilities are displacing traditional merchant traders in specification-sensitive segments. French and Italian decorative paint markets concentrate procurement through distributors offering REACH-compliant safety data sheet authoring.
- Retailers:Small-volume consumers including independent body shops and maintenance facilities purchase packaged solvents through construction supply and automotive aftermarket channels.
- Online Platforms:Digital inventory systems enable just-in-time blending orders from mid-size coatings manufacturers, compressing working capital cycles.
Direct sales channels capture the largest revenue concentration, though distributor-mediated procurement is climbing the fastest as specification complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing leverage over European buyers due to concentrated refinery-solvent integration in the Yangtze River Delta, while Germany's REACH compliance costs inflate delivered premiums for aromatic grades. This asymmetry reshapes procurement routing for multinational coatings formulators.
China
Automotive refinishing networks in Jiangsu and Zhejiang provinces are scaling aliphatic solvent consumption for collision repair clearcoats. The MEE enforces tightening GB standards on industrial emissions across the Yangtze River Delta manufacturing cluster. Shanghai bulk terminals now consolidate procurement for paints and coatings producers seeking scale efficiencies in solvent uptake.
Germany
BMW and Volkswagen assembly plants in Stuttgart and Wolfsburg operate closed-loop solvent recovery systems that cut virgin intake by half. REACH registration completion for C9-C12 aromatic streams has clarified import pathways into EU manufacturing corridors. The BASF Ludwigshafen complex anchors specialty solvent blending for automotive OEM approved-material lists.
United States
EPA National Emission Standards for Hazardous Air Pollutants subpart HHHH tightens control requirements for coating manufacturing operations across Ohio and Texas. Small and mid-size toll blenders are consolidating through shared compliance infrastructure to defray capital burdens. ExxonMobil leverages integrated Gulf Coast refinery-solvent operations for pipeline-delivered volumes to Texas formulation plants.
India
Infrastructure spending in Maharashtra and Gujarat is expanding demand for high-boiling aliphatic solvents in waterproofing membrane formulations. BIS standards for industrial chemical purity are elevating qualification barriers for imported solvent grades. The Mumbai-Pune industrial corridor concentrates procurement for construction chemicals producers scaling bitumen modification operations.
France
TotalEnergies anchors bio-based solvent R&D programs through hydrotreated vegetable oil-derived hydrocarbon alternatives in France and Belgium. The EU Green Deal renewable content thresholds in public procurement specifications create specification premiums for sustainable grades. Decorative paint markets in Île-de-France concentrate procurement through distributors offering REACH-compliant safety data sheet authoring capabilities.
Hydrocarbon Solvents Market Competitive Environment
Integrated petrochemical majors and independent specialty blenders split the market between captive refinery supply and flexible toll manufacturing. The structure consolidates around refinery-adjacent production assets in the US Gulf Coast and Northwest Europe. Three archetypes dominate: vertically integrated oil majors with pipeline infrastructure, regional distributors with regulatory documentation capabilities, and independent refiners with narrow-cut distillation specialization. Competitive intensity centers on M&A for blending capacity and strategic partnerships for bio-based feedstock access.
Within the integrated major tier, ExxonMobil Corporation and Shell plc exemplify refinery-solvent integration with dedicated supply agreements spanning automotive OEM corridors. TotalEnergies SE occupies a position emphasizing bio-based solvent R&D programs across French and Belgian facilities. These three anchors represent divergent strategic vectors: ExxonMobil leverages Gulf Coast infrastructure for scale, Shell sustains long-term European automotive relationships, and TotalEnergies pursues renewable content differentiation under EU Green Deal mandates.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| TotalEnergies SE |
| Chevron Phillips Chemical Company LLC |
| BASF SE |
| Phillips 66 |
| LyondellBasell Industries N.V. |
| Calumet Inc. |
| Sasol Limited |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta manufacturing cluster concentrates solvent refining capacity that translates into pricing leverage over European buyers sourcing aromatic grades. This geographic asymmetry compresses margins for formulators in Germany and France while rewarding integrated producers with captive naphtha feedstock.
Pricing Analysis
The customization-premium spread separates narrow-cut specialty grades from standard aliphatic blends. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in standard grades is intensifying because oxygenated solvent substitution erodes specification share. Mid-size toll blenders in Ohio and Texas exhibit highest price sensitivity, while automotive OEMs with closed-loop recovery systems prioritize supply security over unit cost.
Supply Chain Analysis
Contract-manufacturing concentration rests with integrated refinery-solvent operations along the US Gulf Coast and in the Yangtze River Delta. China, the United States, and Germany anchor geographic supply concentration. Raw material dependencies draw from catalytic reformer output, naphtha feedstock, and hydrotreated vegetable oil bio-based alternatives. Single-source vulnerability emerges from concentrated refinery maintenance schedules disrupting solvent blender input costs. Distribution runs through consolidated bulk terminals and regional blending facilities serving formulation plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive OEMs and multinational coatings manufacturers with integrated solvent recovery, squeezing margin capture from fragmented toll blenders.
For Market Incumbents: Harden supply security through backward integration into naphtha feedstock or captive catalytic reformer capacity. Lock in long-term offtake agreements with Yangtze River Delta bulk terminals before MEE emission enforcement tightens further. Prioritize certification investment for REACH-compliant safety data sheet authoring capabilities to displace merchant traders in French and Italian decorative paint markets.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat construction chemicals corridor represents the most penetrable entry point for high-boiling aliphatic solvents in waterproofing membrane formulations. Bio-based solvent alternatives under EU Green Deal mandates offer specification-premium positioning with lower capital intensity than conventional refining. Partner with regional distributors deploying digital inventory platforms to compress working capital cycles for mid-size coatings manufacturers.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated petrochemical majors spinning non-core solvent blending assets in Northwest Europe. Long-term viability hinges on feedstock flexibility and regulatory documentation capabilities rather than scale alone. Watch for membrane separation technology adoption rates in automotive OEM paint shops as inflection indicator for virgin solvent demand displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Feedstock | ExxonMobil's Gulf Coast infrastructure demonstrates margin protection against reformer output volatility. |
| Membrane Separation Technology Deployment | BMW and Volkswagen Stuttgart facilities cut virgin solvent intake through closed-loop recovery retrofits. |
| REACH-Compliant Documentation Capability Buildout | French distributors displace merchant traders by offering in-house safety data sheet authoring. |
| Bio-Based Solvent R&D Program Expansion | TotalEnergies anchors renewable differentiation through hydrotreated vegetable oil-derived alternatives. |
| Digital Inventory Platform Integration | Regional distributors compress working capital cycles for mid-size coatings manufacturers through app-based ordering. |
Study Parameters
A standing panel of solvent procurement managers at automotive OEMs, technical R&D directors at coatings formulators, distribution channel partners, and regulatory affairs specialists provided ongoing calibration. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA emission compliance disclosures. Bottom-up segment sizing and top-down macro anchoring were triangulated to ensure consistency across product type, application, and regional production hub dimensions.
Scenario-bracketing framed demand trajectories across the analysis window, with CAGRs derived from segment-level volume build-ups and price normalization assumptions. Segmentation dimensions modeled include grade tier, end-use industry, packaging format, and regional production hub. Forecast inputs incorporated naphtha feedstock price correlation coefficients and REACH registration completion timelines for aromatic solvent streams.
Macroeconomic conditions sit as an overlay; deviation in refinery utilization rates, industrial production indices, or construction spending would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution elasticity for oxygenated alternatives. Quarterly review of MEE emission enforcement actions, membrane separation technology adoption rates, and bio-based solvent procurement specifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Allyl Cyanide Market
Solvents
Propylene Glycol Market
Solvents
Piperylene Market
Solvents
Solvent Recovery Systems Market
Solvents
Acetone Market
Solvents
Pharmaceutical Solvent Market
Solvents
Global Ethyl Lactate Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Organic Solvents Market
Solvents
N-Pentyl Chloride Market
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Sugar Dissolvers Market
Solvents
Mixed Xylene Market
Solvents
Aprotic Solvents Market
Solvents
Trifluoroethanol Market
Solvents
Ethyl Pyruvate Market