
 Global Solvents Market | 2026-2036
Global Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solvents Market Outlook
Pharmaceutical formulators is reorganizing procurement priorities around high-purity grades, pulling volume from traditional paints and coatings buyers. BASF SE leverages integrated aromatics complexes to secure feedstock continuity across European and Asian production nodes. Dow anchors North American supply through Gulf Coast petrochemical infrastructure, while INEOS competes on aliphatic solvent scale from its UK and Belgian manufacturing positions.
Solvents are liquid organic compounds with defined boiling points, polarity indices, and solubility parameters that dissolve, suspend, or extract other substances without chemical alteration; industrial grades typically specify flash point, evaporation rate, and residual water content below defined thresholds. Alcohols command premium positioning in pharmaceutical and personal care applications where purity certification drives margin pools. Ketones retain structural importance in high-performance coatings, though aromatic solvents face demand pressure as automotive and construction end users adapt formulations to comply with tightening volatile organic compound regimes.
EPA regulations in the United States restrict hazardous air pollutant emissions from coating operations, while REACH and the EU Green Deal in Europe mandate substitution timelines for substances of very high concern, directly altering solvent blend specifications. China's MEE enforces national standards on industrial volatile organic compound discharge, reshaping domestic manufacturing compliance costs. Stakeholders must weigh bio-based pathway economics against fossil-derived unit costs as regulatory thresholds tighten across multiple jurisdictions without synchronized implementation calendars.
Market Dynamics
Pharmaceutical-grade solvent demand is compressing supply availability for industrial coatings formulators, creating procurement tension between purity-certified buyers and commodity purchasers.
Growth Catalysts
- REACH substitution mandates:ECHA timelines for substances of very high concern are pulling formulation investment toward bio-based alcohols and esters in European coatings operations.
- Active pharmaceutical ingredient synthesis:Multi-step drug manufacturing routes consume sequential solvent washes, expanding high-purity ketone and alcohol offtake from CDMO networks.
- China domestic chemical scaling:MEE enforcement of national VOC discharge standards is consolidating production licenses around compliant solvent facilities, tightening effective supply.
Market Restraints
- Naphtha feedstock volatility:Aromatic solvent margins compress when crude-linked naphtha prices spike, exposing European crackers to margin erosion.
- Aliphatic supply concentration:UK and Belgian manufacturing nodes control disproportionate C5-C6 solvent volume, creating geographic vulnerability to logistics disruption.
- Waterborne substitution ceiling:High-performance coatings requiring fast evaporation and specific solubility parameters cannot fully eliminate oxygenated solvents without performance trade-offs.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO production-linked incentive schemes for bulk drugs are expanding solvent demand from domestic API synthesis facilities.
- Supercritical CO2 hybrid extraction:Convergence with conventional solvent washing in botanical and pharmaceutical processing creates equipment-service bundling potential.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive solvents will advantage bio-based domestic production within European customs territory.
Industry Challenges
- Pharma-grade certification timelines:ICH Q3C residual solvent guideline compliance requires 12-18 month validation cycles that delay new supplier qualification.
- Multi-site inventory synchronization:Just-in-time pharmaceutical manufacturing demands solvent delivery precision that strains legacy logistics coordination across distributed production networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solvents Market |
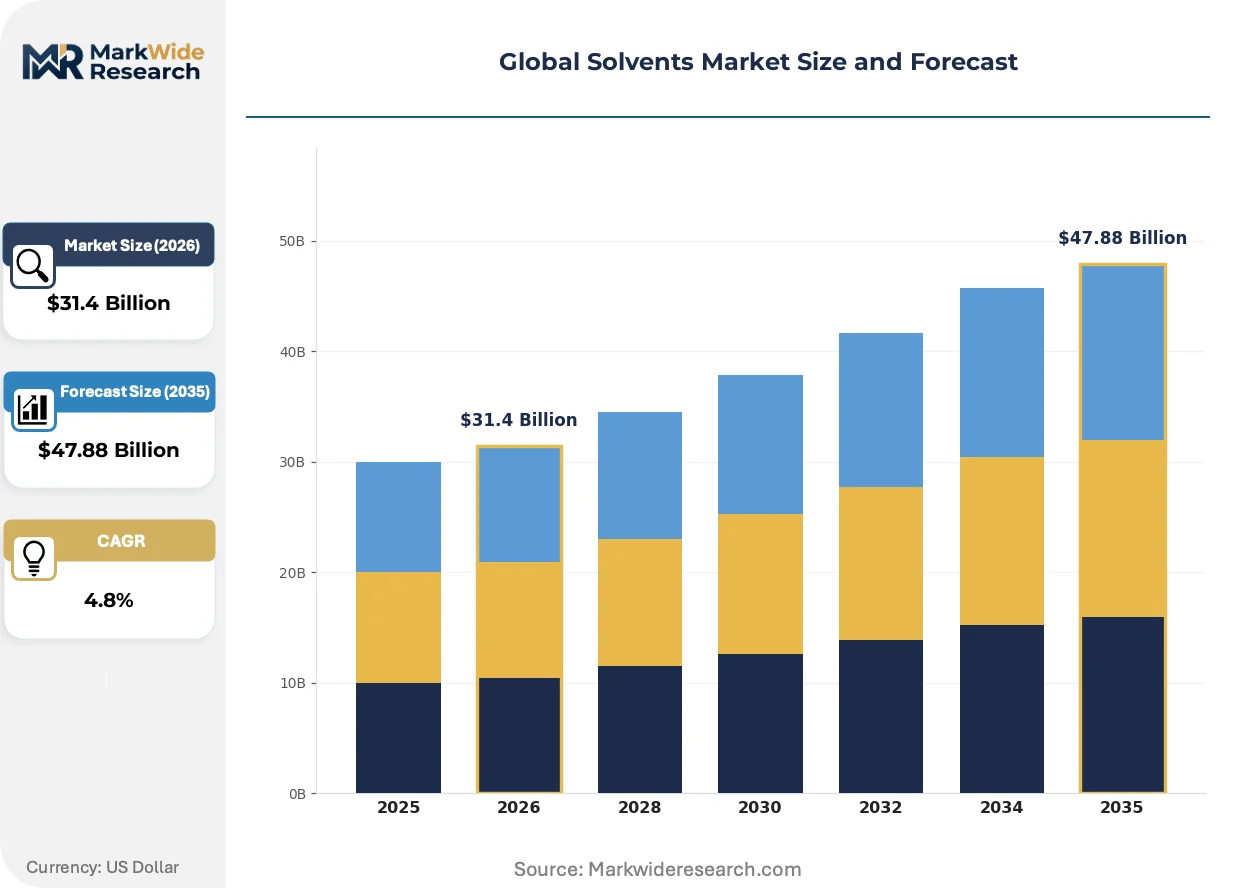
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $47.88 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aromatic Solvents, Aliphatic Solvents, Alcohols, Ketones Application: Paints & Coatings, Adhesives, Pharmaceuticals, Cleaning Products End User: Automotive, Construction, Food & Beverage, Personal Care Delivery Mode: Bulk, Canister, Drum, Pail |
| Companies Covered | Shell plc, Eastman Chemical Company, BASF SE, Honeywell International Inc., INEOS, Dow, LyondellBasell Industries Holdings BV, Ashland, Exxon Mobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solvents Market Strategic Shifts
Bio-based pathway commercialization is fragmenting competitive advantage between fermentation-derived and catalytic conversion routes, with regulatory carbon accounting becoming the decisive selection criterion.
Renewable n-butanol produced via microbial fermentation is bifurcating the oxygenated solvents segment. Coatings formulators in Germany and the Netherlands are qualifying bio-based batches for architectural applications, while pharmaceutical buyers maintain fossil-derived specifications pending excipient-grade certification completion. The technology is bifurcating supply chains into parallel certified and uncertified streams with diverging margin structures.
EPA hazardous air pollutant Maximum Achievable Control Technology standards for coating operations are tightening emission limits on glycol ether and xylene content. US automotive refinish shops face capital expenditure requirements for vapor recovery systems or reformulation toward exempt compounds. Southern California air quality management districts are enforcing the most stringent local interpretations, pushing volume toward compliant methyl acetate blends.
Pharmaceutical manufacturers are consolidating solvent procurement through qualified supplier lists that bundle specification management, inventory holding, and waste handling into single-source arrangements. CDMOs in Switzerland and Singapore are displacing spot-market purchasing with multi-year tolling agreements that transfer working capital burden upstream. This concentration is most visible in injectable drug manufacturing where USP-grade certification requirements limit viable supplier pools to three or four qualified sources per molecule class.
Global Solvents Market Segmentation
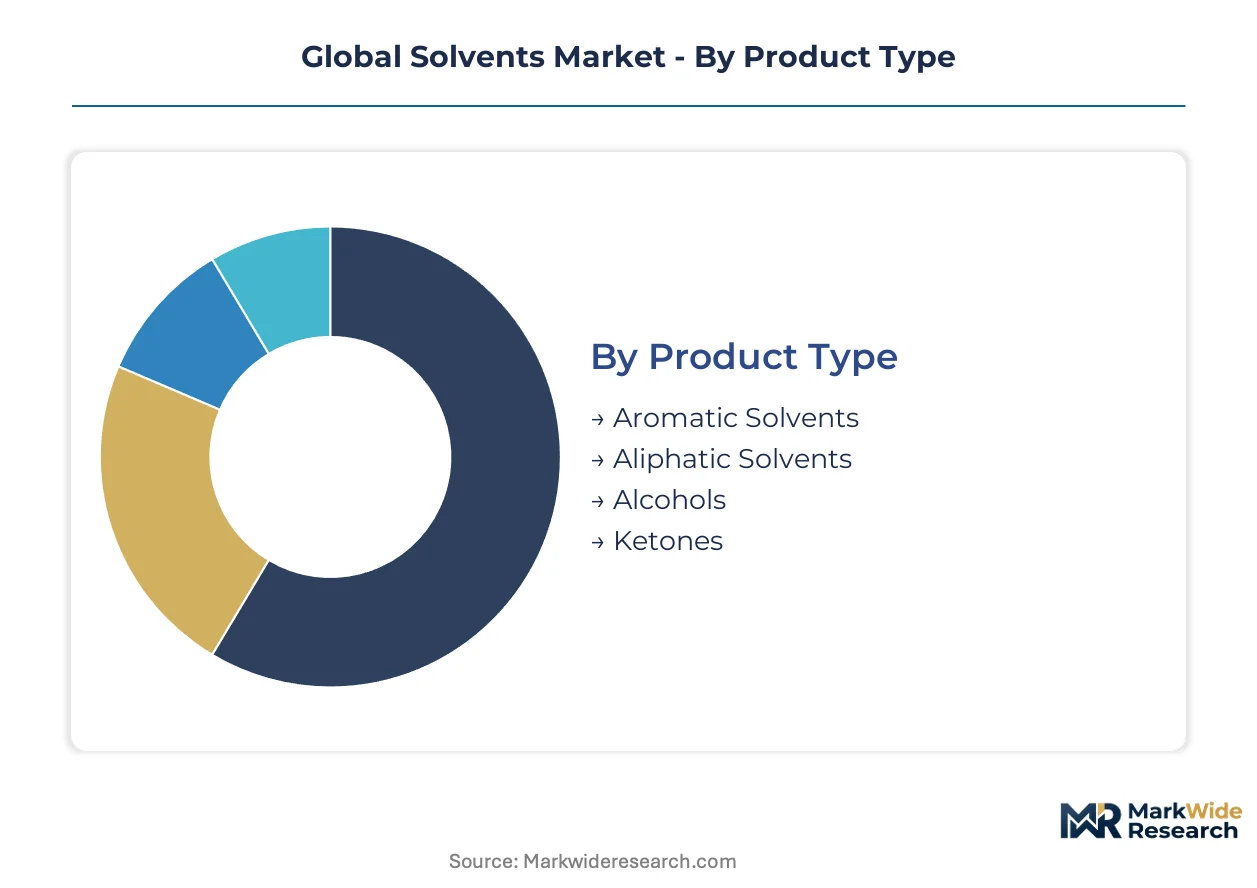
Solvent specifications diverge sharply across end-use contexts, with pharmaceutical purity grades commanding certification overhead that industrial coatings buyers rarely require. Regulatory thresholds on volatile organic compound content are fragmenting supply chains into compliant and non-compliant streams with diverging margin structures.
Product Type:
REACH substitution mandates and EPA hazardous air pollutant standards are reclassifying solvent categories by emissions profile rather than chemical family alone.
- Alcohols:Oxygenated compounds with defined polarity indices and controlled residual water specifications below pharmaceutical-grade thresholds. Demand concentrates in pharmaceutical synthesis and personal care formulation where USP and excipient certifications create supplier stickiness; ECHA timelines for substances of very high concern are accelerating bio-based ethanol and n-butanol qualification in European coatings.
- Ketones:Carbonyl-functional solvents with rapid evaporation rates and strong solubility parameters for high-performance resin systems. Acetone and methyl ethyl ketone offtake clusters in automotive refinish and industrial coating applications where Southern California air quality management districts enforce the most stringent glycol ether and xylene limits.
- Aromatic Solvents:Benzene-ring structures including toluene and xylene isomers with high solvency power for hydrocarbon resins.
- Aliphatic Solvents:Saturated C5-C7 paraffinic and naphthenic fractions with controlled aromatic content for low-odor applications.
Alcohols handle the majority of throughput; ketones are gaining share fastest as automotive formulators reformulate to meet tightening volatile organic compound regimes.
Application:
Customer procurement patterns split between just-in-time pharmaceutical manufacturing and bulk-scheduled industrial coatings operations.
- Paints & Coatings:The largest volume sink for oxygenated and hydrocarbon solvents, spanning architectural, automotive, and industrial protective formulations. Demand concentrates in China where MEE enforcement of national VOC discharge standards is consolidating production licenses around compliant solvent facilities.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and finished dosage form manufacturing requiring ICH Q3C residual solvent guideline compliance. Multi-step drug routes consume sequential solvent washes; CDMOs in Switzerland and Singapore are displacing spot-market purchasing with multi-year tolling agreements that transfer working capital burden upstream.
- Adhesives:Solvent-borne systems for pressure-sensitive tapes, laminating, and structural bonding applications.
- Cleaning Products:Industrial degreasing, precision electronics cleaning, and consumer household formulations.
Paints and coatings absorb the highest absolute volumes; pharmaceuticals is expanding most quickly as procurement consolidates through qualified supplier lists with bundled waste handling services.
End User:
Performance requirements and regulatory exposure vary dramatically across customer industries, with automotive and construction facing the most stringent VOC compliance timelines.
- Automotive:OEM coating lines and refinish shops requiring fast-evaporating solvent systems with precise flow control. EPA Maximum Achievable Control Technology standards for coating operations are tightening emission limits on glycol ether and xylene content; US refinish shops face capital expenditure requirements for vapor recovery systems or reformulation toward exempt compounds.
- Construction:Architectural coatings, adhesives, and sealants with seasonal demand patterns and regional formulation variations. Demand concentrates in Germany and the Netherlands where coatings formulators are qualifying bio-based alcohol batches for architectural applications ahead of EU Green Deal carbon border adjustments.
- Food & Beverage:Extraction, processing aids, and equipment cleaning applications requiring food-contact compliance.
- Personal Care:Fragrance delivery, nail care formulations, and cosmetic ingredient synthesis.
Automotive maintains the deepest solvent specification expertise; construction is climbing the fastest as bio-based pathway commercialization fragments competitive advantage between fermentation-derived and catalytic conversion routes.
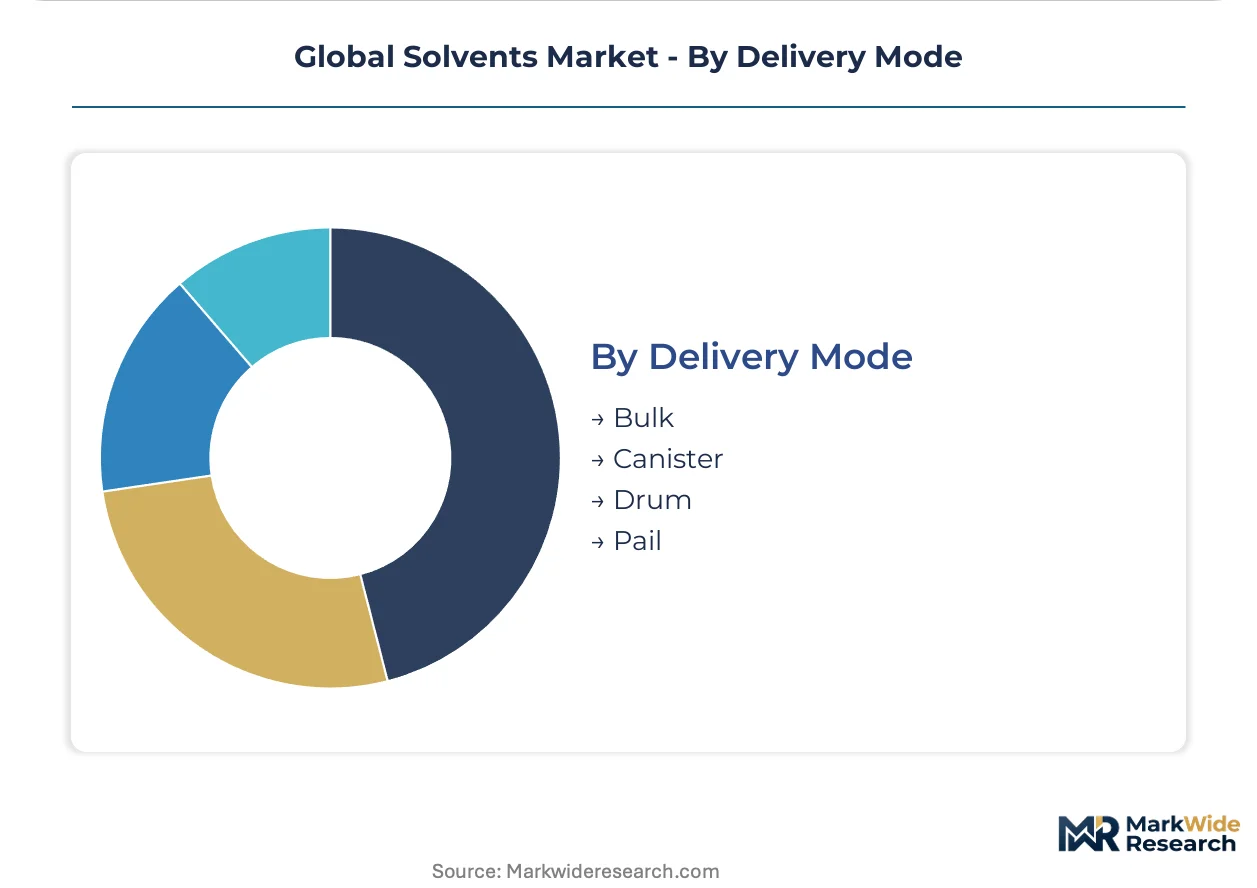
Delivery Mode:
Packaging economics track customer scale and inventory velocity, with pharmaceutical manufacturers demanding precision delivery that strains legacy logistics coordination.
- Bulk:Tank truck and railcar delivery for high-volume coatings and adhesives manufacturers with captive storage infrastructure. Dow anchors North American supply through Gulf Coast petrochemical infrastructure; INEOS competes on aliphatic solvent scale from UK and Belgian manufacturing positions.
- Drum:Standard 55-gallon steel and composite containers for mid-scale industrial users with moderate consumption rates.
- Pail:Five-gallon containers for small-batch formulators and maintenance shops.
- Canister:Aerosol and specialty packaging for retail consumer products and precision application equipment.
Bulk handles the majority of throughput; drum is the fastest mover on share as multi-site inventory synchronization demands strain just-in-time pharmaceutical manufacturing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in Switzerland and Singapore anchor high-purity solvent procurement through multi-year tolling agreements. Coatings formulators in Germany and the Netherlands are qualifying bio-based alcohol batches ahead of carbon border adjustments. Chinese chemical producers face MEE consolidation of production licenses around compliant facilities.
United States
Automotive refinish shops and OEM coating lines drive oxygenated solvent consumption for fast-evaporation systems. EPA Maximum Achievable Control Technology standards tighten emission limits on glycol ether and xylene content. Southern California air quality management districts enforce the most stringent local interpretations, pushing volume toward compliant methyl acetate blends in Los Angeles Basin operations.
Germany
Coatings formulators qualify bio-based ethanol and n-butanol batches for architectural applications ahead of EU Green Deal carbon border adjustments. ECHA timelines for substances of very high concern accelerate substitution investment. The Ruhr industrial cluster concentrates aromatics complex operations with integrated feedstock continuity across European production nodes.
China
Domestic chemical production scaling and rising pharmaceutical output concentrate solvent demand in coastal manufacturing provinces. MEE enforcement of national VOC discharge standards consolidates production licenses around compliant solvent facilities. The Yangtze River Delta tightens effective supply as MEE compliance costs reshape domestic manufacturing economics.
Switzerland
CDMO networks expand high-purity ketone and alcohol offtake for multi-step active pharmaceutical ingredient synthesis. Swissmedic certification requirements limit viable supplier pools to qualified sources per molecule class. Basel-area pharmaceutical manufacturing consolidates procurement through single-source arrangements bundling specification management and waste handling.
India
CDSCO production-linked incentive schemes for bulk drugs expand solvent demand from domestic API synthesis facilities. Maharashtra and Gujarat pharmaceutical clusters scale manufacturing capacity under national pharmaceutical mission programs. Hyderabad and Ahmedabad API hubs strain solvent logistics coordination across distributed production networks.
Global Solvents Market Competitive Environment
Player mix skews toward integrated petrochemical majors with captive feedstock positions and specialized chemical companies with purity certification capabilities. The structure concentrates around aromatics complex operators and oxygenated solvent specialists. Strategic archetypes include integrated refiners controlling naphtha-derived aromatic supply, fermentation-based bio-alcohol producers, and pharmaceutical-grade purity certifiers. Dominant competitive moves encompass backward integration into feedstock production and geographic expansion through tolling partnerships.
Within the integrated petrochemical tier, Shell plc and Exxon Mobil Corporation exemplify scale-driven positions anchored by global refining networks. BASF SE occupies a position representing European aromatics complex integration. Dow sits within the North American supply anchor archetype through Gulf Coast infrastructure. These three demonstrate how feedstock continuity and geographic node control differentiate competitive positioning in solvent markets.
| Leading Market Players |
|---|
| Shell plc |
| Eastman Chemical Company |
| BASF SE |
| Honeywell International Inc. |
| INEOS |
| Dow |
| LyondellBasell Industries Holdings BV |
| Ashland |
| Exxon Mobil Corporation |
| Others |
Value Chain & Pricing Dynamics
Bio-based n-butanol substitution for fossil-derived oxygenated solvents is redrawing feedstock geography while fragmenting pricing economics across certification tiers. This substitution dynamic concentrates supply investment in fermentation-capable regions while compressing margins for conventional petrochemical routes.
Pricing Analysis
Fossil-derived versus fermentation-derived versus catalytic-conversion supply tiers stratify the solvents market into divergent margin pools. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and commodity-grade levels reflects ICH Q3C certification overhead and REACH compliance investment. Cost compression in commodity aromatics is intensifying because naphtha feedstock volatility exposes European crackers to margin erosion. Pharmaceutical manufacturers show the least price sensitivity due to qualified supplier list constraints; coatings formulators face acute pressure from waterborne substitution ceilings.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical manufacturing while coatings producers maintain strategic stockpiles against feedstock volatility. Supply concentrates in China, the United States, and Germany, with the Yangtze River Delta, Gulf Coast petrochemical corridor, and Ruhr industrial cluster anchoring regional nodes. Feedstock draws from crude-linked naphtha, bio-ethanol agricultural inputs, and natural gas liquids. Single-source vulnerability runs through UK and Belgian C5-C6 aliphatic solvent manufacturing positions. Distribution runs through integrated aromatics complexes for bulk industrial buyers and qualified supplier networks for pharmaceutical-grade offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Solvents Market sits in early-cycle expansion as REACH substitution mandates and EPA hazardous air pollutant standards accelerate bio-based pathway adoption ahead of carbon border adjustment implementation.
For Market Incumbents: Secure captive bio-ethanol and n-butanol feedstock positions through fermentation partnership structures before EU Green Deal carbon border adjustments advantage domestic European production. Defend against CDMO procurement consolidation by bundling inventory holding and waste handling services into multi-year tolling agreements. Prioritize ICH Q3C certification investment to maintain qualified supplier list positioning as pharmaceutical procurement tightens.
For New Entrants and Emerging Players: Lead with fermentation-derived alcohol qualification for architectural coatings in Germany and the Netherlands where ECHA timelines are accelerating substitution investment. Target India's CDSCO production-linked incentive schemes for bulk drug manufacturing as domestic API synthesis capacity scales under national pharmaceutical mission programs. Position around supercritical CO2 hybrid extraction equipment-service bundling for botanical and pharmaceutical processing applications.
For Investors and Strategic Acquirers: The market sits at a substitution-driven phase that favors bio-based pathway specialists with regulatory certification capabilities and integrated feedstock positions. Long-term viability over the next decade hinges on carbon accounting compliance and excipient-grade certification completion. Watch MEE enforcement intensity in China as the signal indicating whether domestic consolidation tightens effective supply or opens import substitution opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Feedstock | Fermentation-derived n-butanol secures margin pools ahead of EU carbon border adjustments. |
| Pharmaceutical-Grade Certification Investment | ICH Q3C compliance opens CDMO tolling agreements in Switzerland and Singapore. |
| Long-term Supply Agreement Structuring | Multi-year offtake contracts transfer working capital burden to solvent suppliers. |
| Joint Venture for Regional Production | Local manufacturing in India captures CDSCO incentive scheme volume expansion. |
| Green Manufacturing Transition | MEE-compliant facilities in China retain production licenses as consolidation proceeds. |
Study Parameters
A standing panel of solvent procurement managers at pharmaceutical CDMOs, coatings formulators, and petrochemical plant directors provided ongoing calibration across the study period. Primary interviews with technical R&D directors, distribution channel partners, and regulatory affairs specialists combined with secondary validation from ECHA substance registry data, EPA enforcement records, SEC 10-K filings, and customs trade databases. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
External benchmark consistency checks against ACC and Cefic industry reports validated projection trajectories across the modeling period. Segmentation dimensions included product type, application end-use, purity grade tier, and regional production hub classification. CAGRs derived from regression analysis of historical consumption patterns and regulatory-driven substitution elasticity. Forecast inputs incorporated MEE license consolidation timelines and EU Green Deal implementation pacing.
The analysis sits within stated boundaries; outcomes outside synchronized regulatory implementation calendars would require recalibration. Forecasts reflect documented assumptions regarding bio-based pathway cost convergence and pharmaceutical manufacturing outsourcing trends. Practitioners should keep alternative scenarios live as ECHA substance of very high concern designation schedules and China MEE enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Sugar Dissolvers Market
Solvents
Global Droppers Market
Solvents
Ethoxydiglycol Market
Solvents
Nitromethane Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
Decanol Market
Solvents
Green Solvents Market
Solvents
Global Trichloroethylene and Perchloroethylene Market
Solvents
Chloroacetonitrile Market
Solvents
Coating Solvents Market
Solvents
High Purity Solvents Market
Solvents
Nitroglycerin Market
Solvents
5-Isopropyl-M-Xylene Market
Solvents
Alpha-Methylstyrene Market
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market