
 Global Bio Solvents Market | 2026-2036
Global Bio Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio Solvents Market Foresight
Industrial cleaning and degreasing operations are unwinding their reliance on petroleum-derived solvents as environmental compliance costs mount. BASF SE leverages its integrated fermentation capabilities to secure feedstock cost advantages across European production hubs. Cargill Incorporated anchors its position through captive corn and soybean oil supply chains that underpin methyl soyate output. Vertec Biosolvents Inc. specializes in high-purity D-limonene formulations for precision electronics cleaning where residue tolerance sits below 50 parts per million.
Bio solvents comprise renewable-derived liquid organic compounds engineered to dissolve, disperse, or extract materials without persistent toxicological burden, typically exhibiting flash points above 60 degrees Celsius and biodegradability exceeding 60 percent within 28 days under OECD 301 testing protocols. Their primary commercial purpose centers on replacing xylene, toluene, and acetone in industrial formulations where worker exposure and air quality standards constrain conventional chemistry. Ethyl lactate and terpene solvents command expanding share in paints and coatings as architectural and automotive OEM formulators pursue VOC reduction targets without sacrificing drying time or film adhesion. Methyl soyate occupies a mature, cost-competitive position in agrochemical tank-mix applications and industrial degreasing where solvency power requirements remain moderate. Bioethanol retains volume leadership in printing inks and cleaners through established supply infrastructure, though margin compression from fuel-ethanol competition constrains specialty-grade investment.
EPA VOC regulations under the Clean Air Act, REACH authorization requirements administered by ECHA, and China's GB standards on hazardous substance limits collectively constrain petrochemical solvent availability while creating compliance-driven substitution demand. FDA oversight of residual solvent limits in pharmaceutical manufacturing and EU Green Deal carbon-border adjustments further tighten specification requirements for imported chemical intermediates. Stakeholders must monitor regulatory divergence between jurisdictions where solvent classification thresholds and biodegradability testing protocols remain unharmonized, as compliance strategy misalignment risks market access friction or stranded formulation investments.
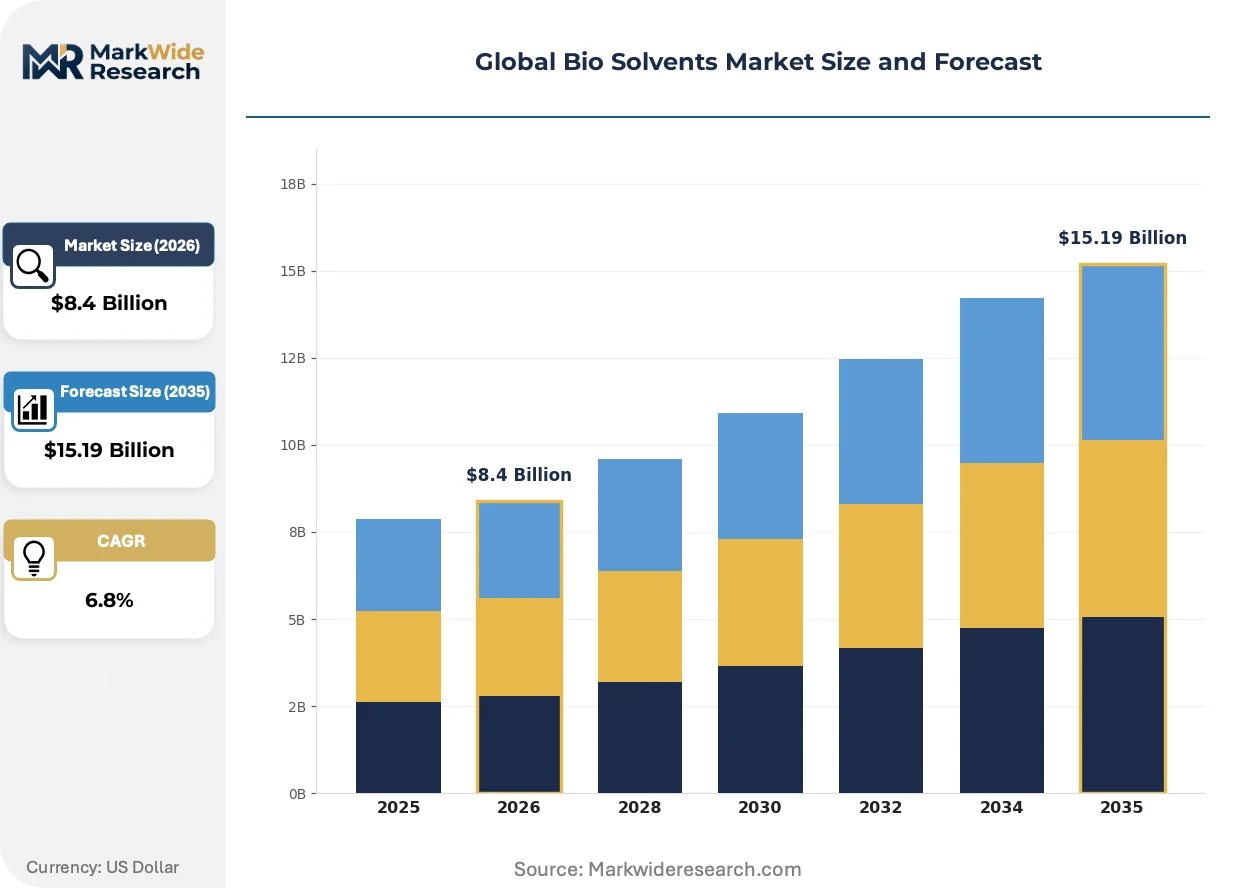
Market Dynamics
REACH authorization requirements and EPA VOC regulations are compressing petrochemical solvent availability while redirecting formulation R&D toward ethyl lactate and terpene alternatives across industrial cleaning and coatings sectors.
Growth Catalysts
- EPA Clean Air Act enforcement:Architectural coatings formulators in the United States face mandatory VOC reduction timelines, accelerating substitution of xylene and toluene with bio-based alternatives that meet 60-degree flash point thresholds.
- Agrochemical tank-mix expansion:India and China are scaling pesticide formulation capacity, driving methyl soyate procurement for emulsifiable concentrate applications where moderate solvency power suffices.
- Fermentation platform maturation:Integrated bioprocessing infrastructure across European production hubs is decomposing feedstock cost barriers for ethyl lactate and bioethanol output.
Market Restraints
- Oilseed price volatility:Soybean and corn commodity swings directly compress margins for methyl soyate producers without captive agricultural supply chains.
- Solvency power gaps:Bio-based alternatives face technical limitations in heavy-duty degreasing applications where petroleum-derived chlorinated solvents retain performance advantages.
- REACH authorization timelines:ECHA's substance-by-substance evaluation process creates regulatory friction, delaying market access for novel bio-solvent chemistries.
Strategic Opportunities
- Electronics precision cleaning:High-purity D-limonene formulations for semiconductor and circuit board manufacturing represent underpenetrated demand where residue tolerance sits below 50 parts per million.
- EU Green Deal carbon-border adjustments:Import tariffs on carbon-intensive chemical intermediates create regulatory tailwinds for European-produced bio solvents in pharmaceutical manufacturing.
- Textile processing conversion:India's dyeing and finishing sector is piloting terpene-based scouring agents as water-scarcity regulations tighten discharge standards.
Industry Challenges
- OECD 301 biodegradability certification:Testing protocol complexity and 28-day validation timelines delay product commercialization for early-stage bio-solvent developers.
- Formulation integration complexity:Paint and coatings manufacturers face retrofit costs for blending equipment and quality control systems when switching from established petrochemical solvent baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio Solvents Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethyl Lactate, Methyl Soyate, Terpene Solvents, D-Limonene, Bioethanol Application: Paints & Coatings, Agrochemicals, Printing Inks, Cleaners & Degreasers, Adhesives End User Industry: Pharmaceuticals, Personal Care, Chemical Manufacturing, Textile Processing, Electronics Packaging Type: Drums, Intermediate Bulk Containers, Totes, Barrels, Bottles |
| Companies Covered | BASF SE, Archer Daniels Midland Company, Vertec Biosolvents Inc., Stepan Company, Solvay S.A., GF Biochemicals, Dow Inc., Cargill Incorporated, Gevo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio Solvents Market Shifts & Advancements
Enzymatic esterification and membrane separation technologies are decomposing traditional production economics while regulatory pressure on residual solvents intensifies specification requirements across pharmaceutical and electronics manufacturing.
Supercritical CO2 extraction paired with bio-based co-solvents is decomposing the technical barriers that previously confined natural solvent production to small-batch specialty applications. Automotive OEM clearcoat formulators in Germany and Japan are adopting these hybrid systems at pilot scale. The structural consequence is decomposing the volume-premium tradeoff that historically separated commodity solvents from precision-grade alternatives.
China's GB standards on hazardous substance limits are tightening residual solvent thresholds in imported chemical intermediates, forcing reformulation of printing ink and adhesive products destined for Chinese manufacturing facilities. Domestic bioethanol producers are expanding specialty-grade fractionation capacity to capture this compliance-driven substitution demand. Electronics contract manufacturers in Shenzhen and Shanghai are now requiring supplier documentation of biodegradability percentages under OECD protocols.
Formulation houses are unbundling solvent supply from technical service contracts, shifting toward specification-based procurement where buyers independently source certified bio solvents and blend in-house. This pattern disrupts the traditional integrated distributor model that dominated industrial solvent channels in North America. The shift is most visible among mid-sized architectural coatings producers in the United States Midwest who are building direct relationships with fermentation-based suppliers to secure volume commitments.
Global Bio Solvents Market Segmentation
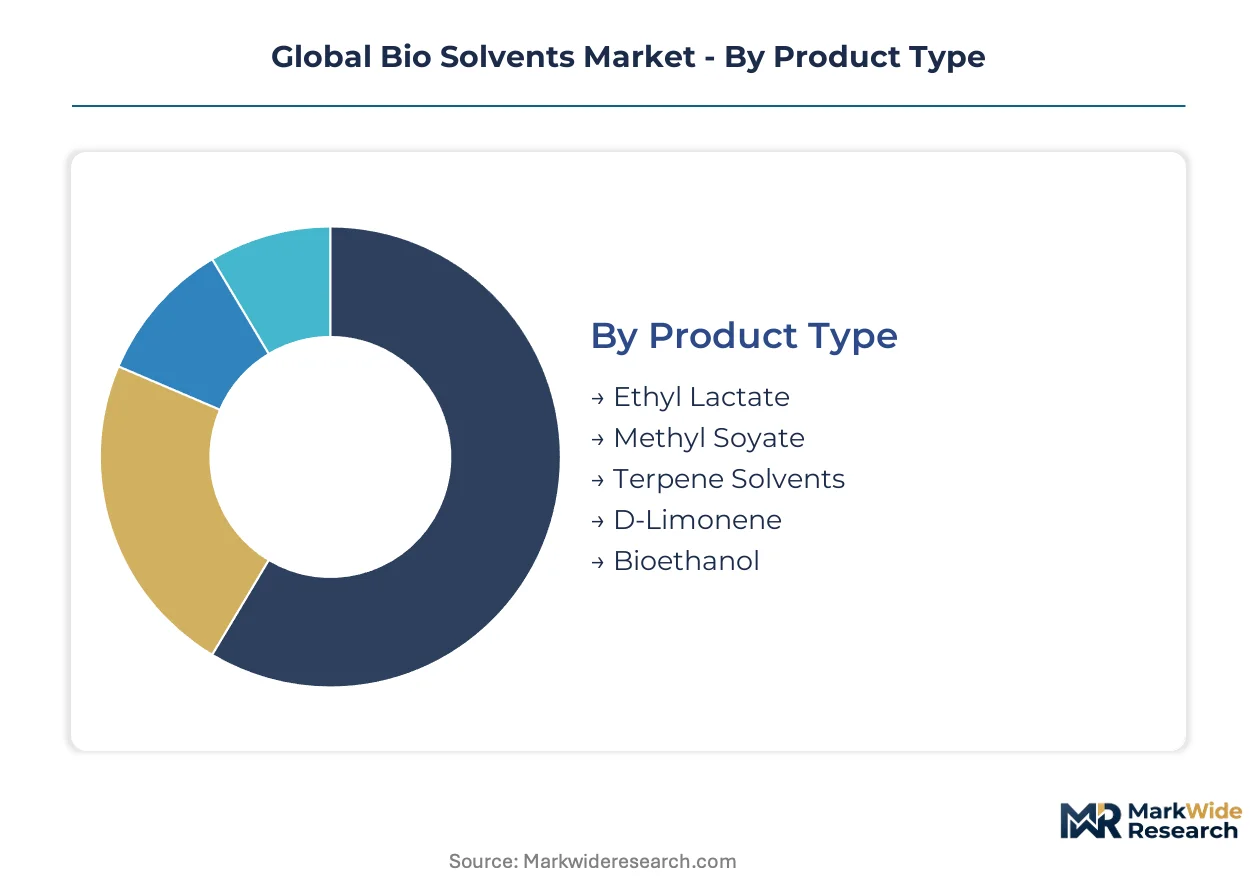
Bio solvent procurement patterns diverge sharply across product chemistries and end-use specifications. Regulatory thresholds on flash points, biodegradability, and residual limits force formulators to match segment capabilities against compliance requirements rather than solvency power alone.
Product Type:
REACH authorization timelines and EPA VOC classifications differentiate commercial viability across fermentation-derived and plant-extraction platforms.
- Ethyl Lactate:Ester solvent produced through lactic acid fermentation with 60-degree-plus flash points and full OECD 301 biodegradability. Architectural coatings formulators in Germany and Japan are substituting xylene in high-solids systems as ECHA authorization requirements tighten on petrochemical alternatives.
- Methyl Soyate:Fatty acid methyl ester refined from soybean oil transesterification, carrying moderate solvency power and cost positioning. Agrochemical tank-mix applications in India and industrial degreasing operations across the US Midwest anchor volume procurement where performance requirements permit lower polarity.
- Terpene Solvents:Hydrocarbon fractions distilled from citrus peel and pine resin, valued for high solvency and renewable sourcing. REACH-compliant alternatives to aromatic petroleum solvents in European industrial cleaning.
- D-Limonene:Cyclic terpene extracted from citrus rind with precision-grade purity specifications. Electronics contract manufacturers in Shenzhen require sub-50 ppm residue documentation for circuit board cleaning applications.
- Bioethanol:Fermentation-derived alcohol with established fractionation infrastructure. Printing ink formulators retain volume leadership despite margin pressure from fuel-ethanol competition for feedstock corn.
Established volume favors methyl soyate; emerging adoption favors ethyl lactate.
Application:
Cost tier stratification separates commodity-scale procurement from specification-driven premium positioning.
- Paints & Coatings:OEM clearcoat and architectural formulations where VOC reduction mandates under EPA Clean Air Act and GB standards force solvent substitution without drying time penalties.
- Agrochemicals:Emulsifiable concentrate and tank-mix adjuvant applications where methyl soyate dominates Indian and Chinese pesticide formulation expansion.
- Printing Inks:Gravure and flexographic systems where bioethanol retains infrastructure advantages despite narrowing specialty-grade margins.
- Cleaners & Degreasers:Industrial maintenance and precision electronics cleaning where residue tolerance thresholds separate commodity from premium-grade procurement.
- Adhesives:Pressure-sensitive and structural formulations where terpene solvents substitute toluene in European tape and label manufacturing.
Coatings command the steepest expansion trajectory; agrochemicals anchor the largest volume base.
End User Industry:
Customer type segmentation tracks regulatory stringency divergence across FDA, EMA, and OECD jurisdictions.
- Pharmaceuticals:Residual solvent limits under ICH Q3C and FDA guidance force high-purity ethyl lactate adoption in active pharmaceutical ingredient synthesis and tablet coating.
- Personal Care:Fragrance extraction and cosmetic formulation where D-limonene serves dual function as solvent and active ingredient in European natural product lines.
- Chemical Manufacturing:Intermediate and reagent applications where bio-based solvents reduce scope 3 emissions under EU Green Deal carbon-border adjustment mechanisms.
- Textile Processing:Scouring and dyeing operations in India's Tiruppur cluster where water-scarcity regulations tighten discharge standards and terpene alternatives pilot at scale.
- Electronics:Semiconductor and printed circuit board cleaning where sub-50 ppm residue specifications and OECD 301 biodegradability documentation are now mandatory in Shenzhen and Shanghai supplier qualifications.
Electronics represents the fastest-climbing specification tier; chemical manufacturing holds the broadest cross-segment demand.
Packaging Type:
Supply concentration in drum and IBC formats reflects downstream formulator scale and inventory turnover requirements.
- Drums:200-liter steel and fiber containers serving mid-volume coatings and agrochemical formulators with weekly replenishment cycles.
- Intermediate Bulk Containers:1000-liter flexible and rigid totes capturing automotive OEM and large architectural coatings producers with integrated blending operations.
- Totes:Rectangular polyethylene containers for cleanroom and electronics manufacturing where space optimization and residue-free dispensing are prioritized.
- Barrels:Traditional wooden and steel formats retaining share in artisanal and small-batch chemical manufacturing.
- Bottles:Laboratory and pilot-scale packaging for pharmaceutical R&D and analytical applications requiring certified purity documentation.
IBC formats gain share in direct-procurement relationships; drums defend position in distributor-mediated channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bio solvent exports flow increasingly toward Chinese automotive OEM formulators seeking REACH-compliant alternatives to aromatic petroleum solvents. This trade corridor reflects tightening environmental standards on both ends of the supply chain.
United States
Architectural coatings formulators in the Midwest are accelerating ethyl lactate procurement as EPA Clean Air Act enforcement compresses xylene availability. The agency's VOC reduction timelines for industrial maintenance coatings expire in phases through 2027. Chicago-area blending facilities are retrofitting tankage to handle higher-flash-point bio-based feedstocks.
Germany
Automotive OEM clearcoat producers in Bavaria pilot supercritical CO2 extraction systems paired with terpene co-solvents for carbon-border compliance. ECHA's REACH authorization requirements for petrochemical solvents redirect formulation R&D toward fermentation-derived alternatives. The Stuttgart industrial cluster hosts pilot lines testing high-solids bio-based systems for export to Asian assembly plants.
China
Electronics contract manufacturers in Shenzhen and Shanghai now mandate OECD 301 biodegradability documentation for circuit board cleaning solvents. GB standards on hazardous substance limits tighten residual solvent thresholds in imported chemical intermediates. Domestic bioethanol producers expand specialty-grade fractionation capacity to capture compliance-driven substitution demand from printing ink formulators.
India
Agrochemical tank-mix applications in Gujarat and Maharashtra drive methyl soyate procurement as pesticide formulation capacity scales. The country's PLI scheme for chemical manufacturing incentivizes domestic solvent production infrastructure. The Tiruppur textile cluster pilots terpene-based scouring agents as water-scarcity regulations tighten discharge standards for dyeing operations.
Japan
Precision electronics cleaning specifications from METI push semiconductor fabricators toward sub-50 ppm residue tolerance for D-limonene formulations. Automotive OEMs in the Nagoya region adopt bio-based clearcoat systems for export compliance with EU Green Deal carbon-border adjustments. Osaka-area chemical traders are building direct procurement relationships with European fermentation-based suppliers.
Global Bio Solvents Market Competitive Landscape
Listed leaders compete with private specialists across integrated fermentation capabilities and captive agricultural supply chains. The vendor base stratifies between diversified chemical conglomerates with bioprocessing platforms and focused biosolvent developers serving specification-driven niches. Three archetypes dominate: integrated bioprocessors with backward control over feedstock supply, specialty extractors of high-purity terpenes for electronics applications, and regional methyl ester producers anchored in oilseed processing infrastructure. Capacity expansion and strategic partnerships constitute the primary competitive moves, with formulators seeking volume commitments through direct supplier relationships rather than distributor intermediation.
Among European-based integrated chemical producers, BASF SE and Solvay S.A. occupy positions exemplifying the diversified bioprocessor archetype, while Cargill Incorporated represents the agricultural-captive supply chain model. Vertec Biosolvents Inc. sits within the specialty terpene extraction tier, reflecting the precision-grade positioning required by electronics manufacturing specifications. These three entities collectively illustrate the competitive tension between scale-driven fermentation platforms and specification-focused extraction technologies.
| Leading Market Players |
|---|
| BASF SE |
| Archer Daniels Midland Company |
| Vertec Biosolvents Inc. |
| Stepan Company |
| Solvay S.A. |
| GF Biochemicals |
| Dow Inc. |
| Cargill Incorporated |
| Gevo Inc. |
| Others |
Supply & Pricing Matrix
Sixty-day fermentation cycle times for ethyl lactate production concentrate margin pressure on European bioprocessors without captive corn supply, while 45-day inventory turns at Indian methyl soyate refiners feed pricing power back to oilseed crushers with backward-integrated crushing capacity. This lead-time asymmetry between fermentation platforms and transesterification infrastructure shapes how procurement managers negotiate volume commitments across specification tiers.
Pricing Analysis
Next-generation enzymatic esterification platforms command 15-20% premiums over conventional acid-catalyzed ethyl lactate, while first-generation methyl soyate from commodity soybean oil sits at the economy tier. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade ethyl lactate with ICH Q3C documentation from industrial-grade alternatives and unrefined methyl esters. Pricing pressure stems from fuel-ethanol competition for feedstock corn, which compresses specialty-grade bioethanol margins. Agrochemical formulators in India exhibit highest price sensitivity due to tank-mix volume procurement patterns, while electronics contract manufacturers in Shenzhen accept premium positioning for sub-50 ppm D-limonene specifications.
Supply Chain Analysis
The United States and Brazil anchor soybean oil supply for methyl soyate production, while Germany and China concentrate fermentation capacity for ethyl lactate and bioethanol output. Feedstock dependencies rest on corn and soybean commodity markets, citrus peel waste streams from juice processing, and pine resin tapping operations in southeastern US states. Single-source vulnerability concentrates in Brazilian soybean exports subject to weather-driven crop volatility. Distribution runs through direct procurement relationships between fermentation-based suppliers and mid-sized coatings formulators, bypassing traditional distributor intermediation in North American channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, REACH, and GB standards fragments procurement specifications into incompatible compliance tiers, creating white-space opportunities for specialists serving single-jurisdiction formulators rather than global suppliers chasing harmonized standards.
For Market Incumbents: Fortify captive feedstock positions through long-term offtake agreements with corn processors in the US Midwest and oilseed crushers in Brazil, insulating margin structures from commodity swings. ECHA's substance-by-substance REACH authorization timelines threaten market access for novel bio-solvent chemistries, demanding early-stage regulatory engagement as a defensive priority. Capacity addition in Indian chemical manufacturing clusters under PLI scheme incentives captures agrochemical tank-mix demand growth. For New Entrants and Emerging Players: Lead with high-purity D-limonene extraction capabilities serving electronics precision cleaning specifications in Shenzhen and Shanghai, where sub-50 ppm residue documentation creates qualification barriers for established commodity suppliers. Underpenetrated demand for terpene-based textile scouring agents in India's Tiruppur cluster offers geographic white space with tightening water-scarcity discharge standards. Go-to-market positioning as specification-only supplier with OECD 301 certification documentation bypasses volume competition with integrated bioprocessors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with orphaned bio-solvent divisions lacking feedstock integration, where fermentation assets trade at discount to replacement cost. Long-term viability frames around regulatory compliance as persistent cost of market access rather than cyclical demand driver. Watch ECHA authorization timelines for petrochemical solvent substitutes as inflection signal for substitution velocity in European coatings formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn and soybean oil captive supply locks in margin structure against commodity volatility for fermentation platforms. |
| Green Manufacturing Transition | Enzymatic esterification and membrane separation technologies decompose production economics for ethyl lactate output. |
| Long-term Supply Agreement | Direct procurement relationships with automotive OEM clearcoat formulators secure volume commitments through carbon-border compliance. |
| Joint Venture | Supercritical CO2 extraction partnerships with terpene co-solvent producers pilot hybrid systems for German automotive OEMs. |
| Capacity Expansion | Specialty-grade bioethanol fractionation capacity in China captures compliance-driven substitution from printing ink formulators under GB standards. |
Research Methodology
A standing panel of fermentation plant managers, coatings formulator procurement leads, agrochemical tank-mix technical directors, and electronics contract manufacturing quality officers provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA Clean Air Act enforcement documentation, ECHA REACH authorization registers, Chinese GB standards publications, and SEC 10-K filings from listed chemical producers. Bottom-up capacity and demand modeling triangulated against top-down trade flow analysis from customs data.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window, with segmentation modeling across product chemistry, application end-use, end-user industry vertical, and regional production hub. CAGRs derived from rolling regression of annual demand observations against regulatory enforcement phase-in schedules and feedstock cost trajectories. Forecast inputs incorporated OECD 301 biodegradability certification timelines and formulation retrofit cost curves for paint and coatings manufacturers.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement pressure or feedstock price stability would require recalibration against alternative scenarios. Forecasts reflect documented assumptions regarding REACH authorization velocity and PLI scheme implementation in Indian chemical manufacturing. Recalibration cycles align with material shifts in EPA enforcement phases, ECHA substance evaluations, and GB standards revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Diethanolamide Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
Saudi Arabia Methanol Market
Solvents
1, 1-Difluoroethane Market
Solvents
Phenylacetonitrile Market
Solvents
Methyl Diethanolamine Market
Solvents
Allyl Cyanide Market
Solvents
Isoamylene Market
Solvents
Xylene Market
Solvents
Aprotic Solvents Market
Solvents
Ethoxydiglycol Market
Solvents
3-Butylene Glycol Market
Solvents
Global Tert-Butanol Market
Solvents
Citrus Solvents Market
Solvents
N-Pentyl Chloride Market
Solvents
Hexylene Glycol Market