
 Chloroacetonitrile Market | 2026-2036
Chloroacetonitrile Market Size, Share, and Industry Trends Forecast 2026-2036
Chloroacetonitrile Market Analytics
REACH is repositioning the competitive threshold for European chloroacetonitrile suppliers by mandating comprehensive substance registration and toxicity documentation. Transpek-Silox Industry Private Limited leverages its integrated chlorination infrastructure to sustain cost advantages in technical grade production. Lonza Group Ltd. anchors its position through pharmaceutical-grade specialization and stringent quality protocols that align with EMA guidelines. Shandong Zhanhua Yonghao Chemical Co., Ltd. competes aggressively on volume, dominating bulk supply contracts to Asian agrochemical formulators.
Chloroacetonitrile, the chlorinated nitrile with formula ClCH₂CN and molecular weight 75.5 g/mol, serves primarily as an intermediate in organic synthesis, notably for pesticides, pharmaceuticals, and dye precursors via nucleophilic substitution pathways. Pharmaceutical grade chloroacetonitrile commands premium positioning due to stringent impurity thresholds demanded by FDA and EMA filings, while technical grade occupies volume leadership in agrochemical intermediate applications. The pesticides application segment is accelerating fastest as global crop protection manufacturers seek efficient cyanomethylation reagents, though dyes represents a mature demand pool with limited expansion trajectory.
EPA oversight in the United States classifies chloroacetonitrile as a hazardous substance under TSCA, requiring rigorous handling protocols and emission controls that shape facility siting decisions. EMA pharmaceutical guidelines and China's NMPA registration requirements collectively elevate analytical documentation burdens for cross-border suppliers. India's CDSCO and BIS frameworks are tightening import inspection regimes for chloroacetonitrile destined for pharmaceutical and agrochemical formulation. Stakeholders must monitor evolving purity mandates across these jurisdictions to anticipate qualification timelines and avoid supply disqualification.
Market Dynamics
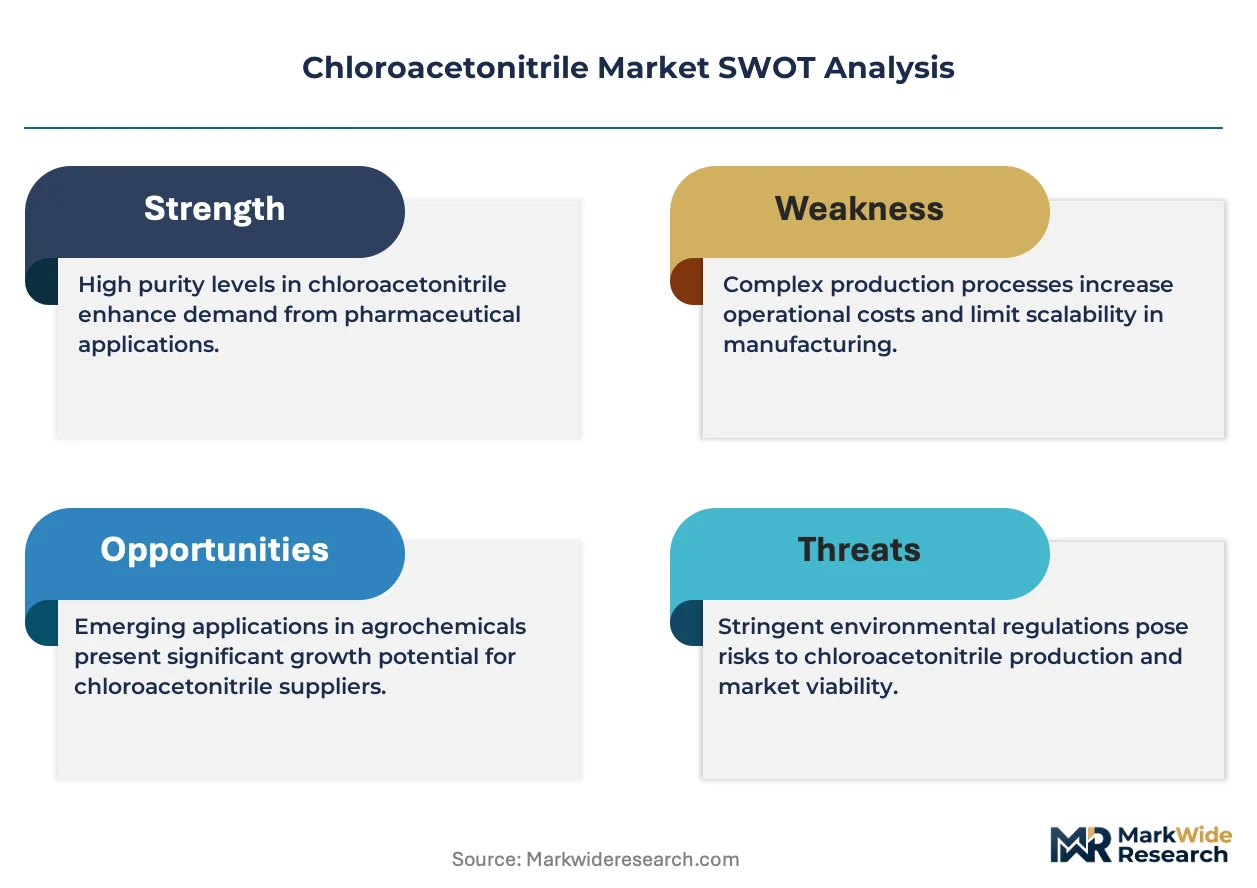
REACH compliance mandates are compressing supplier margins across European chloroacetonitrile production while simultaneously elevating qualification barriers for cross-border pharmaceutical procurement. This regulatory asymmetry is redistributing volume toward integrated Asian manufacturers with captive chlorination capacity.
Growth Catalysts
- Agrochemical cyanomethylation demand:Pesticide manufacturers are scaling chloroacetonitrile consumption for herbicide and fungicide intermediate synthesis. Formulators prioritize this reagent for its selective nucleophilic substitution efficiency.
- REACH-driven purity escalation:European pharmaceutical filings now require sub-50 ppm impurity thresholds that disqualify technical-grade suppliers. This specification compression creates dedicated demand pools for certified pharmaceutical-grade material.
- China's integrated chlor-alkali base:Shandong and Jiangsu province chemical parks combine chlorine, acetonitrile, and chloroacetonitrile production within single-site complexes. This upstream control delivers 15-20% cost advantages on bulk agrochemical contracts.
Market Restraints
- Acetonitrile feedstock volatility:Chloroacetonitrile production costs track acrylonitrile byproduct availability from acrylic fiber manufacturing. Asian textile demand fluctuations transmit directly into chloroacetonitrile margin compression.
- Single-source chlorination dependency:Technical-grade production concentrates among three Chinese integrated producers. Any disruption at Zhanhua Yonghao or Transpek-Silox facilities would constrain global agrochemical intermediate supply.
- EPA TSCA emission controls:United States facility siting requires Best Available Control Technology for hydrogen cyanide and chlorine gas handling. These capital requirements exclude mid-scale entrants from North American production.
Strategic Opportunities
- Indian pharmaceutical formulation expansion:CDSCO is accelerating API registration timelines under its PLI scheme for active pharmaceutical ingredients. Chloroacetonitrile suppliers can capture this demand by establishing dedicated pharmaceutical-grade purification capacity near Hyderabad and Ahmedabad clusters.
- Continuous flow chlorination technology:Microreactor systems enable precise temperature control for exothermic chlorination reactions. This process intensification reduces solvent waste and qualifies facilities for EMAS environmental certification.
- Bio-based acetonitrile feedstock:Fermentation-derived acetonitrile from agricultural waste streams is reaching pilot-scale purity. Early qualification with this feedstock positions suppliers for EU Green Deal carbon border adjustment compliance.
Industry Challenges
- Pharmaceutical-grade analytical capability gaps:FDA and EMA filings require ICH Q3D elemental impurity testing and nitrosamine risk assessments. Few technical-grade producers possess in-house LC-MS/MS infrastructure for these documentation packages.
- Multi-jurisdiction registration synchronization:Suppliers must simultaneously navigate EPA PMN notifications, REACH registration updates, and NMPA import drug master file submissions. Misaligned timeline expectations between regulatory bodies extend qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chloroacetonitrile Market |
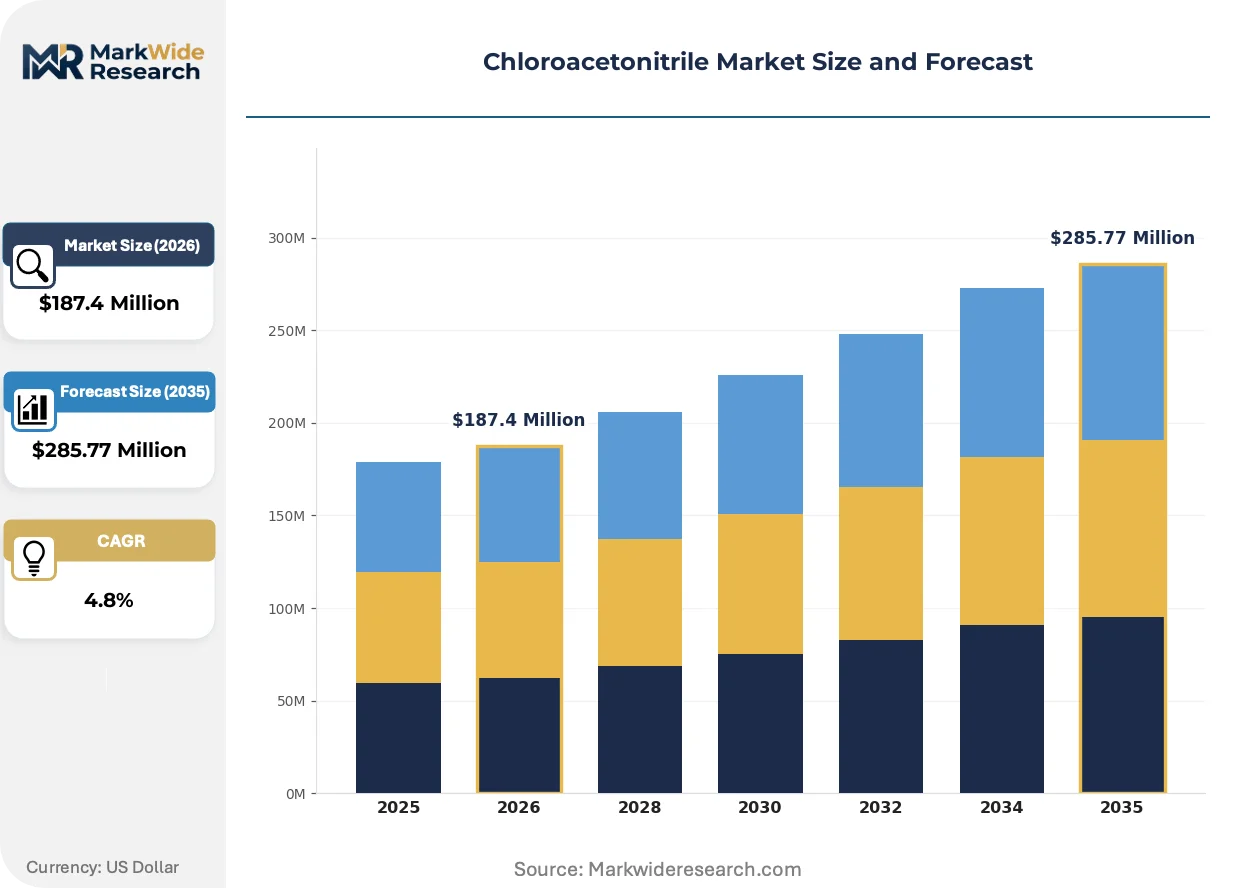
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Purity Grade, Pharmaceutical Grade, Industrial Grade Application: Pesticides, Pharmaceuticals, Agrochemicals, Dyes End User: Chemical Manufacturers, Pharmaceutical Companies, Agrochemical Firms, Research Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Transpek-Silox Industry Private Limited, Shandong Zhanhua Yonghao Chemical Co., Ltd., Lonza Group Ltd., Parchem fine & specialty chemicals, Xiamen Hisunny Chemical Co., Ltd., Alfa Aesar (Thermo Fisher Scientific), Anhui Xingyu Chemical Co., Ltd., HEBEI YANUO Bioscience Co., Ltd., Fuyang Guanda Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chloroacetonitrile Market Evolving Landscape
Chloroacetonitrile production is bifurcating between commodity agrochemical intermediates and high-specification pharmaceutical reagents. Technology investments now concentrate on purification depth rather than scale expansion.
Membrane-based chloroacetonitrile purification is expanding into pharmaceutical-grade supply chains. This technology replaces energy-intensive fractional distillation with selective pervaporation for water and hydrogen cyanide removal. Lonza and specialized European producers are retrofitting existing assets with ceramic membrane modules. The structural consequence is expanding into premium pricing tiers previously captured by Swiss and German specialty chemical houses.
REACH Article 33 substance of very high concern candidate listing is tightening documentation burdens for chloroacetonitrile handlers. ECHA's 2023-2024 evaluation window assessed chloroacetonitrile for potential carcinogenicity classification. European formulators are pre-emptively qualifying alternative cyanomethylation reagents while maintaining dual-source chloroacetonitrile inventories. Pharmaceutical API manufacturers face the most acute compliance timeline pressure given EMA filing amendment requirements.
Agrochemical procurement is consolidating toward annual volume contracts with fixed-price escalators indexed to acrylonitrile feedstock costs. This mechanism transfers price volatility risk from formulators to chloroacetonitrile producers. Indian and Chinese pesticide manufacturers are driving this contract structure standardization. The shift is most visible in Gujarat and Jiangsu procurement offices where procurement teams now reject spot-market purchasing for core intermediates.
Chloroacetonitrile Market Segmentation
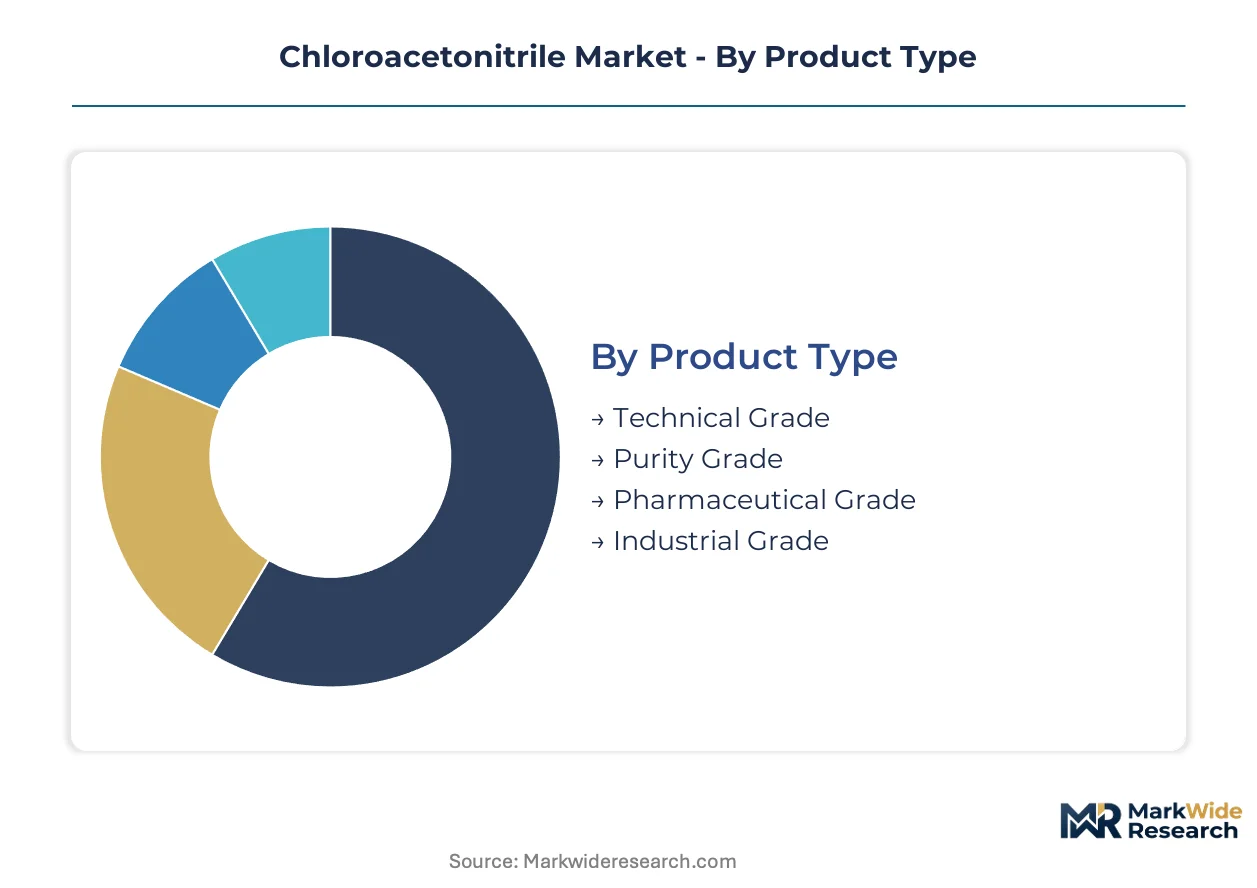
Chloroacetonitrile procurement patterns diverge sharply between bulk agrochemical intermediates and tightly regulated pharmaceutical reagents. Specification thresholds set by EMA, FDA, and NMPA create rigid partition lines that suppliers cannot cross without dedicated purification infrastructure. Understanding these segment boundaries reveals where margin pools concentrate versus where volume commoditization dominates.
Product Type:
Supply concentration in Shandong and Jiangsu province chemical parks directly shapes grade availability and pricing power across product tiers.
- Technical Grade:Contains 95-98% chloroacetonitrile with elevated hydrogen cyanide residuals. Agrochemical formulators in Gujarat and Jiangsu absorb this volume for herbicide intermediate synthesis where downstream purification handles impurity loads.
- Pharmaceutical Grade:Achieves 99.5%+ purity with sub-50 ppm elemental impurity thresholds mandated by ICH Q3D guidelines. EMA and FDA filings require dedicated batch documentation that only Lonza and select European producers currently supply, creating acute supply scarcity for generic API manufacturers.
- Purity Grade:Intermediate 98-99% specification serving specialty chemical synthesis where residual chlorides must be controlled but full pharmaceutical documentation is unnecessary.
- Industrial Grade:Lowest specification tier for non-critical applications including solvent extraction and metal finishing operations with minimal regulatory oversight.
Today's leader: Technical Grade. Tomorrow's challenger: Pharmaceutical Grade.
Application:
Cost tier separation between mature dye applications and expanding agrochemical cyanomethylation drives divergent investment returns.
- Pesticides:Cyanomethylation reagent demand from glyphosate and fungicide intermediate manufacturers is climbing fastest. Chinese integrated producers capture this volume through fixed-price annual contracts indexed to acrylonitrile feedstock costs.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis requires nucleophilic substitution pathways for antihypertensive and antiviral compounds. CDSCO's PLI scheme for API manufacturing is redirecting procurement toward Hyderabad and Ahmedabad clusters.
- Agrochemicals:Fertilizer and plant growth regulator applications outside core pesticides represent stable but limited expansion demand concentrated in Indian and Southeast Asian markets.
- Dyes:Mature demand pool for azo dye precursors with minimal growth trajectory and intense price competition among technical-grade suppliers.
Fastest expansion trajectory: Pesticides. Steepest margin compression: Dyes.
End User:
Customer type fragmentation between integrated chemical manufacturers and specialized pharmaceutical formulators determines qualification burden and contract structure.
- Chemical Manufacturers:Integrated chlor-alkali operators with captive chloroacetonitrile production for internal intermediate consumption. Transpek-Silox and Shandong Zhanhua Yonghao dominate this self-supply category.
- Pharmaceutical Companies:Generic API producers and innovator firms requiring pharmaceutical-grade material with full regulatory documentation packages. These buyers pay 40-60% premiums over technical grade but impose stringent audit requirements.
- Agrochemical Firms:Pesticide formulators purchasing technical grade through annual volume contracts with price escalators. Procurement teams in Gujarat and Jiangsu now reject spot-market purchasing for core intermediates.
- Research Institutions:Small-volume, high-specification demand for method development and early-stage synthesis with limited commercial significance.
Contract standardization leader: Agrochemical Firms. Premium pricing capture: Pharmaceutical Companies.
Distribution Channel:
Volume scale and customer relationship intensity dictate channel selection across end-user categories.
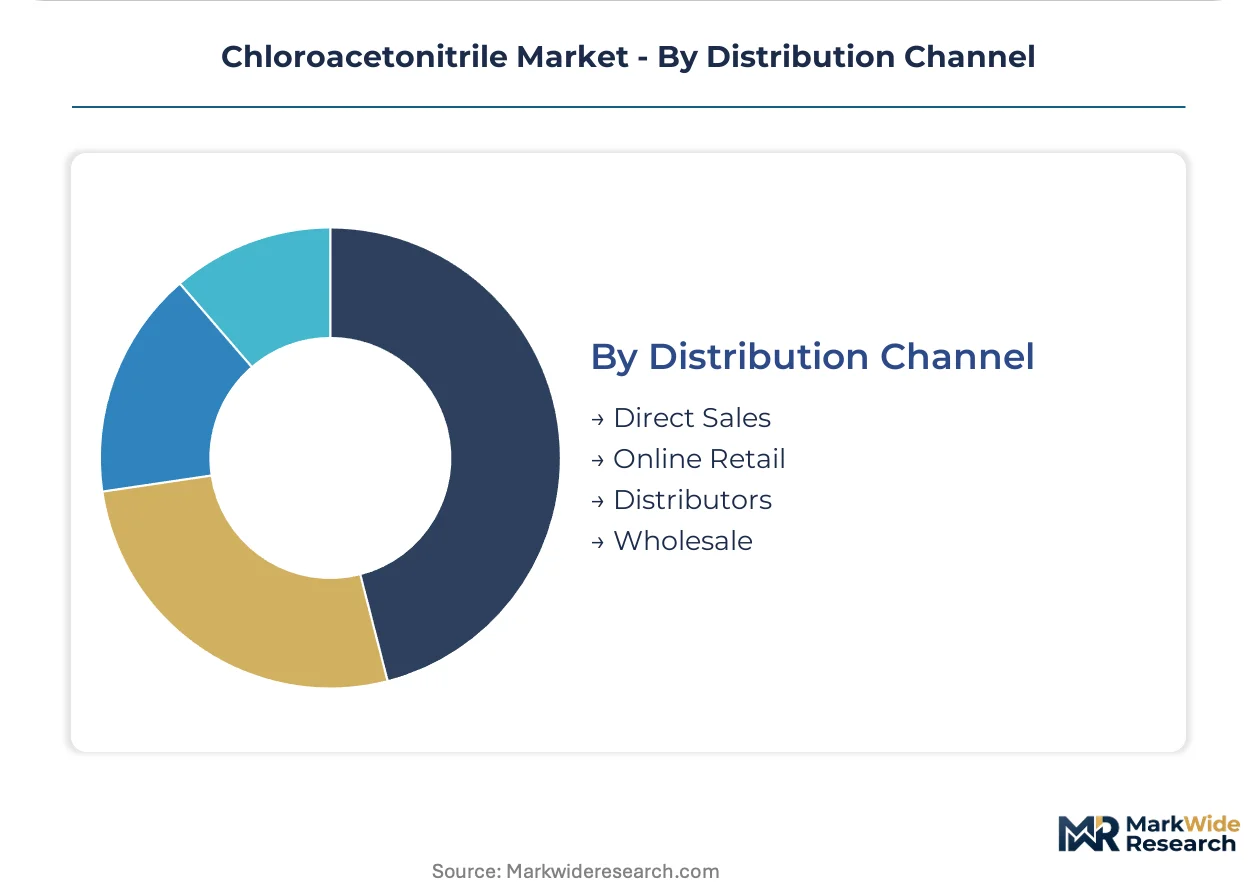
- Direct Sales:Annual contracts between chloroacetonitrile producers and large agrochemical formulators or pharmaceutical API manufacturers. These arrangements now incorporate REACH compliance certification and feedstock price indexation.
- Distributors:Regional chemical distributors handling technical-grade volumes for mid-scale pesticide manufacturers without direct supplier relationships. Inventory risk sits with distributors in volatile acetonitrile feedstock environments.
- Wholesale:Bulk aggregation for smaller agrochemical formulators and industrial users with irregular demand patterns and lower specification requirements.
- Online Retail:Emerging channel for research-grade and small-package quantities serving universities and contract research organizations with immediate fulfillment expectations.
Volume concentration: Direct Sales. Channel innovation: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineering talent clusters in Germany, Switzerland, and the Chinese provinces of Shandong and Jiangsu anchor chloroacetonitrile production capacity. These workforce concentrations determine where pharmaceutical-grade purification expertise and integrated chlor-alkali operations co-locate.
United States
EPA TSCA emission controls constrain new chloroacetonitrile facility development despite agrochemical formulation demand from Midwest crop protection manufacturers. The Best Available Control Technology mandate for hydrogen cyanide handling elevates capital thresholds for market entry. Houston-Gulf Coast chemical corridor hosts legacy chlorination infrastructure serving regional pesticide intermediate demand.
China
Shandong and Jiangsu province chemical parks combine captive chlorine, acetonitrile, and chloroacetonitrile production within single-site complexes. NMPA registration requirements and dual carbon goals are tightening environmental compliance timelines for export-oriented producers. Zhanhua Yonghao anchors technical-grade volume leadership through integrated chlor-alkali control.
Germany
REACH Article 33 documentation burdens and ECHA substance evaluation protocols compress margins for domestic chloroacetonitrile handlers. Pharmaceutical-grade demand from Ludwigshafen and Frankfurt API manufacturing clusters sustains premium-tier procurement. BASF corridor chemical parks maintain specialized purification capacity for EMA-compliant material.
India
CDSCO's PLI scheme for active pharmaceutical ingredients is accelerating API registration timelines in Hyderabad and Ahmedabad manufacturing zones. BIS import inspection regimes tighten qualification burdens for chloroacetonitrile destined for pharmaceutical formulation. Gujarat agrochemical procurement offices now reject spot-market purchasing for core cyanomethylation intermediates.
Switzerland
Swissmedic pharmaceutical guidelines and EMA alignment sustain demand for ultra-high-purity chloroacetonitrile in Basel-region innovator drug manufacturing. Lonza Group anchors pharmaceutical-grade specialization through stringent quality protocols. The country's precision chemical heritage supports premium pricing capture for documented reagent supply.
Chloroacetonitrile Market Competitive Landscape
The competitive structure tilts toward integrated chlor-alkali operators with captive feedstock control. Three strategic archetypes populate the market: Chinese provincial chemical park operators with backward integration into acrylonitrile and chlorine supply; Swiss and European pharmaceutical-grade specialists with EMA-aligned documentation infrastructure; and Indian and Chinese distributors aggregating technical-grade volumes for mid-scale agrochemical formulators. Capacity expansion and purification technology licensing represent the dominant competitive moves as players seek to cross grade boundaries.
Within the integrated production tier, Shandong Zhanhua Yonghao Chemical Co., Ltd. and Transpek-Silox Industry Private Limited exemplify the Chinese archetype of single-site chlor-alkali control. Lonza Group Ltd. occupies a position representing the European pharmaceutical-grade specialization vector. These three anchors illustrate how geographic concentration of feedstock infrastructure versus regulatory compliance expertise splits competitive positioning across the technical-pharmaceutical grade divide.
| Leading Market Players |
|---|
| Transpek-Silox Industry Private Limited |
| Shandong Zhanhua Yonghao Chemical Co., Ltd. |
| Lonza Group Ltd. |
| Parchem fine & specialty chemicals |
| Xiamen Hisunny Chemical Co., Ltd. |
| Alfa Aesar (Thermo Fisher Scientific) |
| Anhui Xingyu Chemical Co., Ltd. |
| HEBEI YANUO Bioscience Co., Ltd. |
| Fuyang Guanda Chemical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Agrochemical formulators in Gujarat and Jiangsu procurement offices anchor volume demand through fixed-price annual contracts indexed to acrylonitrile feedstock costs. This contract standardization transfers price volatility risk from buyers to chloroacetonitrile producers while compressing spot-market liquidity.
Pricing Analysis
Bundled long-term offtake agreements with embedded feedstock escalators dominate technical-grade procurement, while pharmaceutical-grade material trades through unbundled spot documentation packages with separate certification premiums. Price differentiation rests on ICH Q3D compliance depth and EMA-aligned analytical capability. Cost compression in technical-grade supply is intensifying because Chinese integrated producers leverage captive chlor-alkali control. Agrochemical formulators exhibit highest price sensitivity, while pharmaceutical API manufacturers absorb premium tiers to secure regulatory qualification.
Supply Chain Analysis
Dual-sourcing requirements from EMA-registered pharmaceutical manufacturers now mandate qualified backup suppliers for all critical reagents, reshaping procurement protocols. Supply concentrates in China, India, and Switzerland. Production draws from acrylonitrile byproduct streams, chlorine gas, and specialized purification solvents. Single-source vulnerability runs through Shandong and Jiangsu province chemical parks where three integrated producers control technical-grade output. Distribution runs through direct annual contracts for large agrochemical formulators and pharmaceutical API manufacturers, with regional distributors handling mid-scale pesticide producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in chloroacetonitrile hinges on purification technology investments that capture pharmaceutical-grade premiums, while technical-grade producers defend position through backward integration into acrylonitrile supply.
For Market Incumbents: Deploy membrane-based purification retrofits to cross the technical-pharmaceutical grade boundary and capture EMA-aligned documentation premiums. Defend against REACH-driven purity escalation by accelerating ICH Q3D analytical infrastructure investments. Lonza's pharmaceutical-grade specialization demonstrates how certification depth repels commodity competition. For New Entrants and Emerging Players: Distributor networks in Indian agrochemical hubs represent the most accessible entry channel for technical-grade volume. Target Hyderabad and Ahmedabad pharmaceutical clusters with dedicated pharmaceutical-grade purification capacity under CDSCO PLI scheme alignment. Qualify as secondary supplier to EMA-registered API manufacturers seeking dual-source compliance. For Investors and Strategic Acquirers: Integrated chlor-alkali operators with captive acetonitrile supply are the most active acquirer in this space, seeking purification technology to upgrade technical-grade output. Long-term viability centers on regulatory compliance capability rather than scale alone. Watch for ECHA substance of very high concern classification decisions as inflection indicators that would accelerate alternative cyanomethylation reagent substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Purification Retrofit | Lonza and European specialists capture EMA-compliant pharmaceutical-grade premiums through ceramic module deployment. |
| Backward Integration into Acetonitrile | Shandong and Jiangsu chemical parks secure 15-20% cost advantages via captive chlor-alkali control. |
| Continuous Flow Chlorination | Microreactor systems enable EMAS environmental certification while reducing solvent waste from exothermic reactions. |
| Dual-Source Qualification Programs | EMA-registered API manufacturers pre-empt REACH Article 33 risks by qualifying alternative cyanomethylation suppliers. |
| CDSCO PLI Scheme Alignment | Pharmaceutical-grade producers establish Hyderabad and Ahmedabad capacity to capture Indian API manufacturing expansion. |
Research Methodology
Multiple input streams — procurement director interviews at Gujarat and Jiangsu agrochemical formulators, regulatory affairs consultations with EMA-aligned pharmaceutical manufacturers, and customs trade flow analysis — were reconciled against secondary validation. Primary engagement covered plant managers at integrated chlor-alkali facilities, technical R&D directors at pharmaceutical-grade specialists, distribution channel partners handling technical-grade volumes, and CDSCO registration consultants. Secondary sources included REACH registration databases, ECHA evaluation protocols, SEC chemical company filings, and Indian BIS import inspection records. Bottom-up volume estimates from grade-specific production capacity were triangulated against top-down demand aggregation by end-use application.
Data-stream reconciliation across the projection horizon applied segmentation modeling by product grade, end-use industry, and regional regulatory cluster. Analytical frameworks incorporated pharmaceutical-grade purity thresholds, agrochemical cyanomethylation intensity coefficients, and dye precursor demand elasticity. CAGRs were derived from fitted growth curves calibrated to acrylonitrile feedstock availability projections and REACH compliance timeline assumptions. Forecast inputs included EMA filing amendment requirements, CDSCO PLI scheme uptake rates, and Chinese dual carbon policy implementation trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA carcinogenicity classification decisions and acrylonitrile byproduct supply disruptions from acrylic fiber demand cycles. Deviation in REACH Article 33 substance of very high concern listing timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Para Nitrochlorobenzene Market
Solvents
C2 Chlorinated Solvents Market
Solvents
Propylene Glycol Market
Solvents
Ketone-Based Solvents Market
Solvents
Citrus Solvents Market
Solvents
Isopropylamine Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
Fluid Neutralizing Market
Solvents
Piperylene Market
Solvents
Saudi Arabia Methanol Market
Solvents
Hydrosol Market
Solvents
Global Solvent Dyes Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
Global Solvent Evaporation Market
Solvents
Fluorinated Solvents Market
Solvents
Nitrobenzene Market