
 Isoparaffin Solvents Market | 2026-2036
Isoparaffin Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Isoparaffin Solvents Market Intelligence
Stringent limits on Volatile Organic Compounds (VOCs) enforced by the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) is expanding the use of high-purity isoparaffin solvents. ExxonMobil Corporation leverages its vast refining scale to produce a wide range of grades. Shell plc competes on its global distribution network and technical support for industrial clients. INEOS specializes in producing specialty solvents for niche, high-value applications.
Isoparaffin solvents are synthetic, high-purity hydrocarbons characterized by a branched-chain structure, resulting in low toxicity and minimal odor. Their primary function is to act as a diluent, carrier fluid, or cleaning agent in formulations where low reactivity is critical. Hydrocarbon solvents form the largest volume segment, though specialty solvents command higher price points. While the paints and coatings industry is the dominant end use, the cosmetics sector's need for ultra-pure grades is creating new opportunities.
Compliance with regulations like the EU's REACH and China's GB standards for chemical safety governs market access. The US FDA also sets purity requirements for isoparaffins used in products with dermal contact, such as cosmetics. Future competitive advantage will depend on a supplier's ability to document low-aromatic content and provide consistent, globally certified product.
Market Dynamics
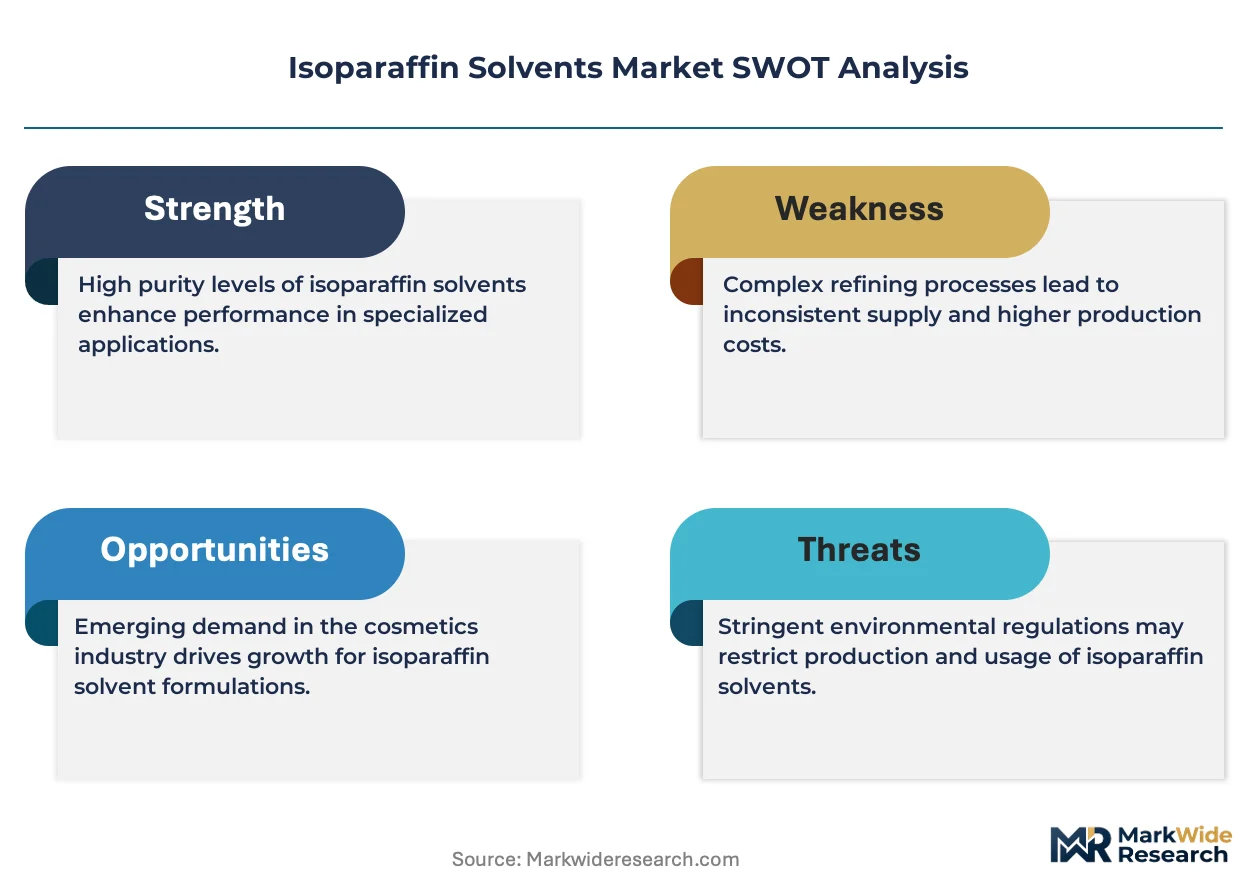
A regulatory-driven flight to quality is the central force shaping the market. Stringent Volatile Organic Compound limits from the EPA and ECHA compel end-users to prioritize high-purity, low-aromatic isoparaffin solvents over conventional hydrocarbon alternatives, creating a value-over-volume competitive environment.
Growth Catalysts
- EU Regulations:The European Union's REACH framework is tightening restrictions on aromatic compounds in consumer products, directly increasing the specification of high-purity isoparaffins in personal care and cosmetic formulations sold within the bloc.
- Cosmetics Sector Demand:The global cosmetics industry requires ultra-low odor, non-irritating, and stable carriers for products like foundations, sunscreens, and lotions, creating a premium-priced demand segment for the purest isoparaffin grades.
- Asian Industrialization:Rapid expansion of manufacturing in China and India, governed by regulations like China's GB standards, is driving consumption in industrial cleaning, metalworking fluids, and paints where low-VOC compliance is essential.
Market Restraints
- Feedstock Price Volatility:Isoparaffin production is directly linked to the price of crude oil and natural gas derivatives. Price fluctuations in these global energy commodities create input cost instability and margin pressure for solvent manufacturers.
- Threat from Bio-Based Alternatives:The development of bio-solvents derived from renewable sources presents a long-term substitution threat, particularly in applications where sustainability marketing is a key purchasing driver for end-customers.
- Energy-Intensive Synthesis:Achieving the high purity and low aromatic content required by regulations involves energy-intensive hydrogenation and distillation processes, contributing to a higher cost structure compared to conventional solvents.
Strategic Opportunities
- Electric Vehicle Fluids:The unique dielectric properties and thermal stability of isoparaffins create opportunities for use as immersion cooling fluids for batteries and power electronics in electric vehicles, an emerging high-performance application.
- Expansion in Southeast Asia:Industrializing economies in Southeast Asia represent an underpenetrated region for high-purity solvents, offering growth potential as local regulations on worker safety and environmental protection align with Western standards.
- Food-Grade Applications:Developing and certifying isoparaffin grades for incidental food contact applications, such as machinery lubricants or release agents in food processing plants, opens a new, high-value market governed by FDA and EFSA rules.
Industry Challenges
- Global Compliance Complexity:Manufacturers face significant administrative and testing costs to maintain concurrent compliance with disparate chemical control laws, including the EU's REACH, the US EPA's TSCA, and China's MEE regulations.
- Purity Maintenance in Logistics:Ensuring that ultra-high-purity isoparaffin grades remain free from contamination during bulk shipping, storage, and handling requires dedicated infrastructure and stringent protocols, adding logistical complexity and cost.
- Capital Investment for Upgrades:Upgrading existing refineries or building new facilities capable of producing the ultra-low aromatic grades demanded by the market requires substantial capital expenditure and long lead times for construction and commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoparaffin Solvents Market |
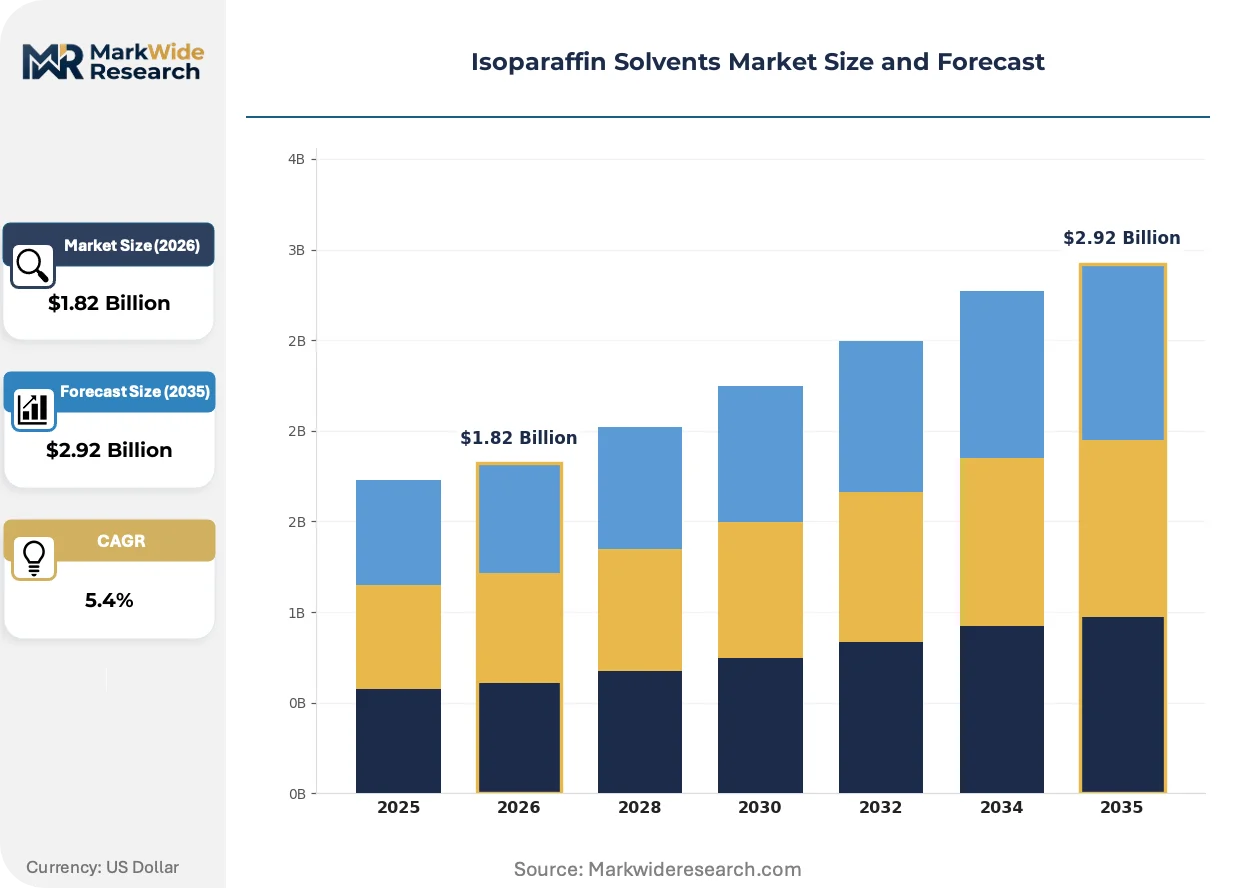
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Aromatic Solvents, Heavy Aromatic Solvents, Hydrocarbon Solvents, Specialty Solvents End Use Industry: Paints & Coatings, Adhesives, Cosmetics, Cleaning Products Application: Industrial Cleaning, Paint Thinning, Ink Production, Chemical Processing Packaging Type: Drums, Bulk Containers, Bottles, Pails |
| Companies Covered | Shell plc, Braskem S.A., TotalEnergies SE, Calumet Specialty Products Partners L.P., INEOS, ExxonMobil Corporation, Idemitsu Kosan Co. Ltd, Mehta Petro Refineries Ltd, Chevron Phillips Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoparaffin Solvents Market Strategic Shifts & Innovations
The market is shifting from commodity solvents to performance-oriented specialty materials. Application-specific formulations and verifiable purity documentation are becoming the primary basis of competition, displacing a historical focus on pure volume and price.
Advanced hydrotreating and isomerization processes create specific carbon chain structures for tailored performance. The personal care and pharmaceutical excipient sectors are rapidly adopting these to achieve precise evaporation rates and sensory profiles. This capability is modularizing the product portfolio, enabling custom solvent grades for niche applications.
Regulations like China's GB standards for chemical safety and VOC content are impacting industrial and consumer goods. This forces producers and importers to reformulate products like paints and adhesives to meet strict aromatic compound limits. The paints and coatings segment is most affected, accelerating its shift to compliant isoparaffins.
A demand for supply chain traceability and low-aromatic certification is redefining buying behavior. This displaces purchasing based on bulk price, as buyers in cosmetics and food contact applications prioritize suppliers with verifiable purity data. The shift is most visible in Europe and North America under strict consumer safety rules.
Isoparaffin Solvents Market Segmentation
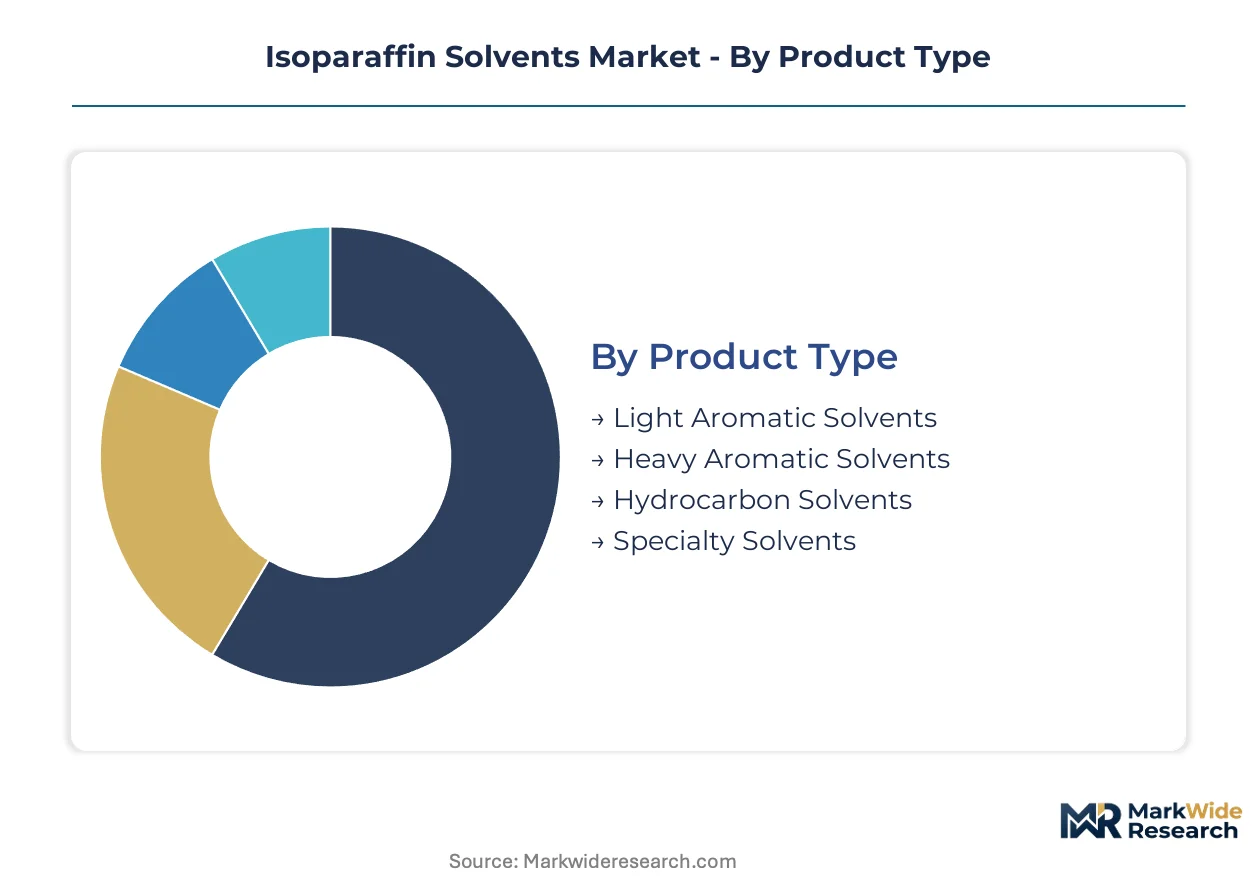
The Isoparaffin Solvents Market segments reveal varying demand profiles and compliance requirements across industries. Each segment reflects specific purity needs, operational scales, and regulatory landscapes influencing procurement decisions. Understanding these distinctions is critical for suppliers to tailor product offerings and market strategies effectively.
Product Type:
The product type segmentation highlights the volume-driven hydrocarbon solvents versus the premium, performance-oriented specialty grades.
- Specialty Solvents:These are highly refined isoparaffins designed for niche, high-value applications requiring precise performance characteristics. Demand concentrates in the cosmetics sector and pharmaceutical excipients due to strict purity and low odor requirements set by the US FDA.
- Hydrocarbon Solvents:Representing the largest volume segment, these include a broader range of paraffinic and naphthenic compounds with varying degrees of purity. Industrial cleaning and general manufacturing in China and India drive significant demand for these cost-effective options.
- Light Aromatic Solvents:These solvents contain lower molecular weight aromatic compounds, offering strong solvency but facing increasing regulatory pressure due to VOC emissions. The paints and coatings industry utilizes these where cost-effectiveness remains a primary consideration.
- Heavy Aromatic Solvents:Characterized by higher molecular weight aromatic content, these are typically used in applications requiring slower evaporation rates and strong solvency. Their use is declining in regulated consumer products in Europe due to ECHA restrictions.
Today's leader: Hydrocarbon Solvents. Tomorrow's challenger: Specialty Solvents.
End Use Industry:
Regulatory compliance and specific product performance needs differentiate demand across end-use industries.
- Paints & Coatings:This industry is the dominant consumer of isoparaffin solvents, utilizing them as diluents and carriers to achieve specific film properties and drying times. Stricter VOC limits in the EU and China's GB standards compel manufacturers to reformulate with compliant isoparaffins.
- Cosmetics:The cosmetics sector demands ultra-pure, low-odor, and non-irritating isoparaffin grades for formulations like foundations, sunscreens, and lotions. Consumer safety regulations and brand reputation drive the procurement of premium, certified products in Europe and North America.
- Adhesives:Isoparaffin solvents act as carriers and viscosity modifiers in adhesive formulations, influencing drying speed and bonding strength. Industrial applications in automotive and construction sectors in Germany and Japan require consistent quality.
- Cleaning Products:These solvents are employed in both industrial and household cleaning formulations for their degreasing and solvency properties. The shift to low-VOC cleaning solutions in the US, driven by EPA guidelines, is expanding demand for high-purity options.
The paints and coatings industry holds the largest share, but the cosmetics sector's need for ultra-pure grades is climbing the fastest.
Application:
Specific application requirements, from solvency to evaporation rates, dictate the type and purity of isoparaffin solvents procured.
- Industrial Cleaning:Isoparaffins serve as effective degreasers and cleaning agents for machinery, electronics, and metal parts in manufacturing facilities. Manufacturers in South Korea and India prioritize solvents offering efficient cleaning with minimal residue.
- Chemical Processing:In chemical processing, isoparaffins function as reaction diluents, extraction solvents, or carrier fluids due to their low reactivity and high purity. Pharmaceutical synthesis in Switzerland and Ireland demands highly consistent and documented grades.
- Paint Thinning:These solvents are used to adjust the viscosity and application properties of paints and coatings, ensuring smooth coverage and proper drying. DIY and professional painting applications in the US and Canada require reliable and consistent thinning performance.
- Ink Production:Isoparaffin solvents contribute to the flow, drying, and adhesion characteristics of printing inks, particularly in specialized applications. Packaging and textile printing industries in Italy and Mexico utilize these for their specific evaporation profiles.
Industrial Cleaning applications represent the highest volume segment, while specialized Chemical Processing applications command higher price differentiation.
Packaging Type:
The choice of packaging reflects the scale of industrial consumption, logistical requirements, and end-user convenience.
- Bulk Containers:These large-volume containers, such as ISO tanks and railcars, are used for high-volume industrial clients requiring continuous supply. Large chemical manufacturers and paint producers in China and the US prefer bulk deliveries for cost efficiency.
- Drums:Standard 200-liter drums are a common packaging choice for medium-scale industrial users and distributors. Manufacturing plants in Brazil and South Africa frequently receive isoparaffins in drums for manageable handling.
- Bottles:Smaller quantities of isoparaffin solvents are packaged in bottles, typically for specialized or consumer-facing applications. Personal care product manufacturers in France and Japan utilize bottled solvents for precise formulation and smaller batches.
- Pails:Pails offer an intermediate volume option, often used in smaller industrial settings or for specific maintenance applications. Automotive repair shops and construction sites in Australia and the UK find pails convenient for their operational needs.
Bulk Containers dominate procurement for large-scale industrial operations, while Bottles cater to specialized, higher-value applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The isoparaffin solvents market historically scaled alongside the expansion of global petrochemical refining capabilities. Major chemical producers in industrialized nations established early dominance through large-scale production and distribution networks. This foundational infrastructure continues to influence regional market dynamics.
United States
Demand for high-purity isoparaffins in the United States stems from its robust cosmetics and cleaning product sectors. The US EPA's stringent VOC limits drive reformulation efforts across industrial and consumer applications. Chemical manufacturing hubs along the Gulf Coast actively produce diverse grades for domestic and export markets.
Germany
Germany's chemical industry, a cornerstone of European manufacturing, exhibits strong demand for isoparaffin solvents in paints and coatings and chemical processing. The ECHA REACH framework mandates strict compliance for low-aromatic content, influencing procurement decisions. The Rhine-Ruhr region, a major industrial complex, concentrates significant solvent production and consumption.
China
China's rapid industrialization fuels substantial consumption of isoparaffin solvents for industrial cleaning and paints and coatings applications. Compliance with China's GB standards for chemical safety and MEE regulations on VOC emissions is essential for market access. Manufacturing centers in the Yangtze River Delta drive high-volume demand for compliant solutions.
India
India's expanding manufacturing base, particularly in paints, coatings, and industrial cleaning, creates growing demand for isoparaffin solvents. Local environmental protection policies increasingly influence the selection of lower-VOC alternatives. Gujarat's chemical industrial zones are becoming key production and distribution hubs for these essential materials.
France
France, a global leader in cosmetics and personal care, requires ultra-pure isoparaffin grades for its high-value formulations. The EU REACH framework directly impacts the specification of ingredients used in consumer products across the bloc. The Cosmetic Valley cluster around Chartres leads innovation in sensory profiles and non-irritating carriers.
Isoparaffin Solvents Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the isoparaffin solvents market, shaping its competitive structure. The market exhibits a tiered consolidation, with large integrated oil and gas companies anchoring the supply base through extensive refining operations. Strategic archetypes include global refining giants, specialized chemical manufacturers focusing on purity, and regional distributors providing localized service. Capacity expansion, portfolio diversification, and strategic partnerships are common competitive moves among major players to secure market share.
At the scale-driven end of the market, ExxonMobil Corporation exemplifies integrated refining capabilities, leveraging vast resources for broad product ranges. Shell plc, a global energy company, occupies a strong position through its extensive distribution network and technical support for industrial clients across diverse geographies. INEOS, a prominent chemical company, represents the archetype of a specialized producer, focusing on niche, high-value applications requiring precise formulations and documented purity. These entities collectively influence global supply and pricing dynamics, setting benchmarks for product quality and regulatory compliance.
| Leading Market Players |
|---|
| Shell plc |
| Braskem S.A. |
| TotalEnergies SE |
| Calumet Specialty Products Partners L.P. |
| INEOS |
| ExxonMobil Corporation |
| Idemitsu Kosan Co. Ltd |
| Mehta Petro Refineries Ltd |
| Chevron Phillips Chemical Company |
| Others |
Cost & Logistics Intelligence
Strict Volatile Organic Compound (VOC) regulations in Europe and North America gate access to premium-tier isoparaffin solvent markets, directly influencing pricing power and qualified supply chain configurations.
Pricing Analysis
A multi-tiered pricing structure governs the isoparaffin solvents market, with premium-mid-economy pricing differentiation reflecting purity levels and application specificity. Price differentiation stems from the low-aromatic content required by the cosmetics sector and the volume scale demanded by industrial cleaning. Pricing pressure stems from feedstock price volatility, particularly crude oil and natural gas derivatives. Industrial cleaning applications in China and India exhibit the highest price sensitivity, while cosmetics manufacturers in France prioritize certified purity over cost.
Supply Chain Analysis
Globally certified product quality and low-aromatic content requirements gate market entry for isoparaffin solvent suppliers. Supply concentration centers in the United States Gulf Coast and the Rhine-Ruhr region of Germany due to established refining infrastructure. The supply chain draws heavily from crude oil and natural gas derivatives as primary feedstocks. Commodity price volatility presents a structural supply chain risk. Distribution runs through a dual model of direct bulk sales to large industrial clients and regional distributors serving smaller, specialized end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isoparaffin solvents market offers geographic arbitrage opportunities, particularly leveraging lower energy costs for production in some regions against premium pricing for high-purity grades in regulated Western markets.
For Market Incumbents:Cement leadership by investing in advanced hydrotreating and isomerization processes to meet evolving regulatory standards like EU REACH. Secure long-term feedstock contracts to mitigate crude oil price volatility, a persistent threat to margin stability. Leverage vertical integration into refining operations to control purity and ensure consistent supply for demanding sectors like pharmaceuticals.
For New Entrants and Emerging Players:Specialized chemical distributors can target underpenetrated industrializing economies in Southeast Asia, where environmental regulations are gradually tightening. Focus on niche, high-value applications such as electric vehicle immersion cooling fluids, emphasizing unique dielectric properties. A go-to-market angle focused on verifiable purity documentation and application-specific technical support will attract discerning buyers.
For Investors and Strategic Acquirers:Roll-up economics work for specialized chemical manufacturers because of fragmented demand for niche, high-purity grades. Long-term viability hinges on the continued global shift towards low-VOC and low-aromatic formulations. Target acquisition archetypes include mid-sized producers with proprietary purification technologies or regional distributors possessing robust compliance infrastructure. A key signal to watch is the adoption rate of isoparaffins in new high-performance applications like EV battery cooling.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Ultra-Pure Grades | Increases supply of high-specification solvents for premium cosmetics and pharmaceutical sectors. |
| Backward Integration into Feedstock Production | Mitigates input cost volatility and enhances control over raw material quality. |
| Green Manufacturing Process Transition | Reduces energy intensity and aligns with global sustainability mandates from regulators. |
| Long-term Supply Agreements with Cosmetics Firms | Secures stable demand for high-purity grades and fosters collaborative product development. |
| Joint Venture for EV Fluid Development | Accelerates market entry into emerging high-growth electric vehicle applications. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a comprehensive understanding of the isoparaffin solvents market. Primary data collection involved discussions with chemical plant managers, procurement leads in the paints and cosmetics sectors, regulatory affairs specialists, and distribution channel partners. Secondary validation drew from customs and trade data, chemical industry association reports, and company annual filings to triangulate market size and growth trajectories.
The forecast framework anchored to historical data from comparable periods, projecting market evolution over the analysis window based on identified drivers and restraints. Segmentation dimensions modeled included product type, end-use industry, application, packaging type, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from a blend of historical trends, expert consensus, and projected impacts of crude oil price forecasts and regional VOC regulation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical events impacting crude oil prices and rapid bio-solvent innovation. These forecasts reflect underlying assumptions regarding regulatory enforcement and technological advancements. A model refresh is warranted upon material change in environmental regulations or feedstock commodity pricing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Decanol Market
Solvents
Organic Solvents Market
Solvents
Diethanolamide Market
Solvents
Global Dipropylene Glycol N-Butyl Ether Market
Solvents
Solvent Green 7 Market
Solvents
Methyl Ethyl Ketone (MEK) Market
Solvents
4-Dichlorobenzyl Alcohol (DCBA) Market
Solvents
Benzyl Alcohol Market
Solvents
Natural Distillates Market
Solvents
Ethoxydiglycol Market
Solvents
Phenol Derivatives Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
2-Phenylethanol Market
Solvents
Benzylamine Market
Solvents
Global Bio Solvents Market
Solvents
Global Glycidol Market