
 Low Sugar Fruit Snacks Market | 2026-2036
Low Sugar Fruit Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Low Sugar Fruit Snacks Market Intelligence
The Non-GMO Project Verified standard is bifurcating the low sugar fruit snack market between certified premium brands and conventional offerings. Welch's leverages its strong brand recognition in fruit-based products to command shelf space in major supermarkets across North America. General Mills competes by integrating its snack brands with low-sugar reformulations to capture health-conscious families. Bare Snacks specializes in baked fruit chip products, differentiating through simple ingredient lists and clean-label positioning.
Low sugar fruit snacks are processed fruit products formulated with reduced sugar content, often under 5 grams per serving, using natural sweeteners like stevia or monk fruit. They serve as healthier, portion-controlled alternatives to traditional snacks for on-the-go consumption. Within product types, fruit chips and leathers represent the fastest-growing categories, appealing to the expanding Health Conscious Adults demographic. This shift is moving the market's focus beyond the initial core segment of children's snacks.
Regulations from bodies like the US FDA, the European Food Safety Authority (EFSA), and the Food Safety and Standards Authority of India (FSSAI) are mandating clearer front-of-pack nutritional labeling. These rules directly influence product formulation, marketing claims, and import requirements related to sugar content. Consequently, producers must navigate a complex web of regional labeling laws while sourcing ingredients that meet both consumer taste expectations and regulatory compliance.
Market Dynamics
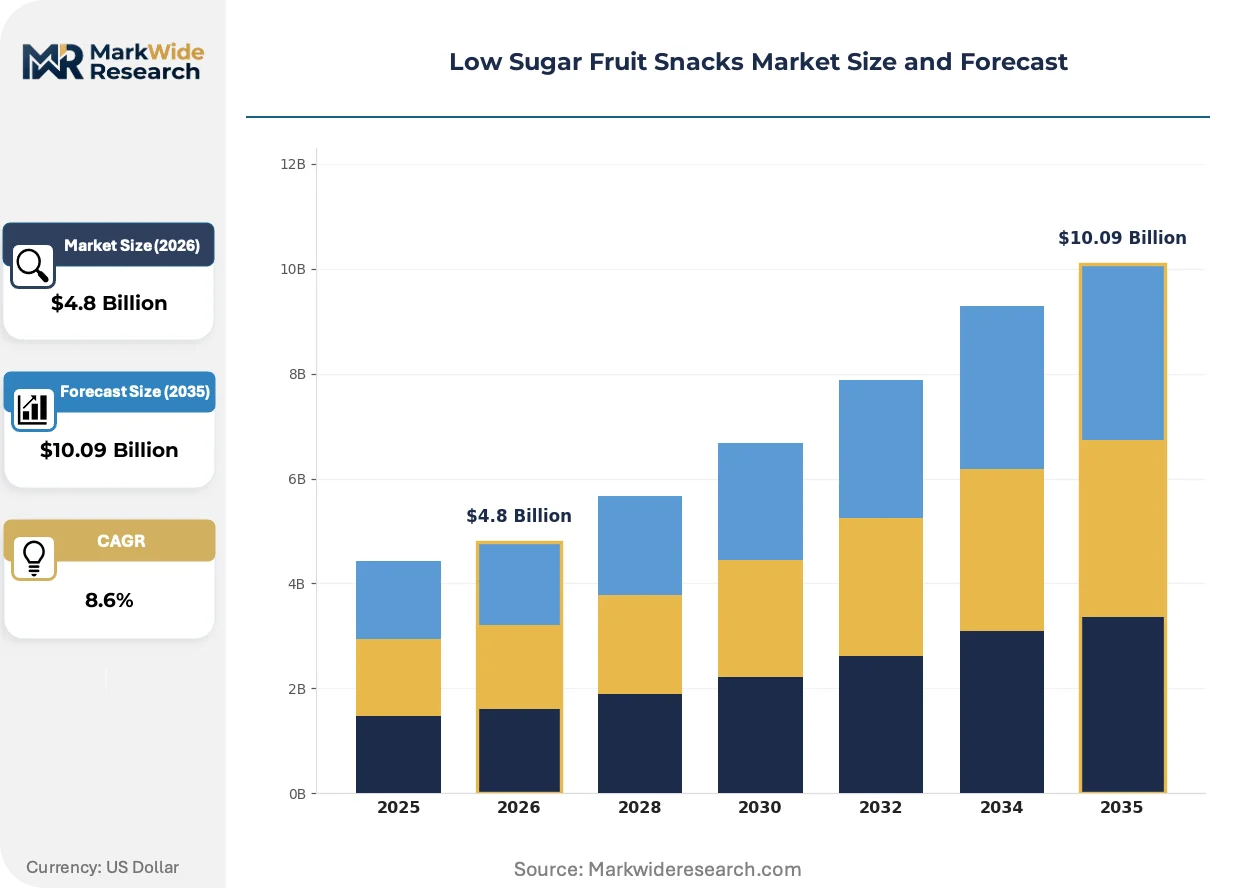
Regulatory pressure on added sugar content, exemplified by mandates from the US FDA and EFSA, is the central force shaping the low sugar fruit snack market. This pressure compels global reformulation efforts and bifurcates the market between compliant, premium products and legacy snacks.
Growth Catalysts
- Health Conscious Adults:This expanding demographic seeks convenient, portion-controlled, and healthier snack options for on-the-go lifestyles, directly fueling demand for products with clean labels and low sugar content.
- FDA Labeling Mandates:New rules in the United States requiring the declaration of "added sugars" on nutrition labels are forcing manufacturers to reformulate products, thereby creating a larger market for low sugar alternatives.
- Retail Channel Expansion:The proliferation of dedicated "wellness" aisles in major supermarkets across developed economies like Germany and Australia increases product visibility and accessibility for health-focused consumers.
Market Restraints
- Natural Sweetener Cost:The higher price and price volatility of natural sweeteners like stevia and monk fruit compared to conventional sugar or high-fructose corn syrup compress profit margins for manufacturers.
- Sensory Profile Challenges:Removing sugar, which acts as a bulking agent and texture enhancer, presents significant technical hurdles in maintaining the taste and mouthfeel that consumers expect from fruit snacks.
- Fresh Fruit Substitution:Whole, unprocessed fruit remains a primary and often cheaper substitute, posing a constant competitive threat with its superior health perception and inherent simplicity.
Strategic Opportunities
- Asia-Pacific Market Penetration:Developing wellness-oriented snack markets in countries such as South Korea and Japan, where disposable incomes are rising, offer significant growth potential beyond North America and Europe.
- Functional Ingredient Integration:Incorporating value-added functional ingredients like probiotics, plant-based protein, and fiber can create a new premium tier of snacks targeting specific health benefits beyond simple sugar reduction.
- Direct-to-Consumer Channels:Building direct-to-consumer (DTC) e-commerce platforms allows brands to bypass retail gatekeepers, cultivate direct customer relationships, and rapidly test new product innovations with target demographics.
Industry Challenges
- Fragmented Global Regulations:Manufacturers face the operational challenge of aligning product formulations and packaging claims with a complex and inconsistent web of nutritional labeling laws from the FDA, EFSA, and FSSAI.
- Certified Ingredient Sourcing:Securing a consistent and cost-effective supply chain for ingredients that meet standards like Non-GMO Project Verified is a significant hurdle for brands competing in the premium segment.
- Marketing and Health Claims:Brands must carefully navigate marketing language to communicate health benefits without making unsubstantiated claims that could attract regulatory scrutiny from bodies like the US Federal Trade Commission (FTC).
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Sugar Fruit Snacks Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gummies, Chewy Bars, Chips, Leather Ingredient Source: Natural, Organic, Non-GMO, Conventional Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops Target Demographic: Children, Health Conscious Adults, Athletes, Diabetics |
| Companies Covered | General Mills, Nestlé, Welch's, Danone, Kellanov, Kellogg Company, PepsiCo, Bare Snacks, RIND Snacks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Sugar Fruit Snacks Market Strategic Shifts & Innovations
Formulation science is intersecting with consumer demand for transparency, driving innovation toward snacks that feature simple ingredient lists and verifiable health credentials. This evolution prioritizes natural sweetening systems and processing techniques that preserve the fruit's inherent nutritional value.
Advanced dehydration and baking techniques, including vacuum-frying and gentle air-drying, preserve fruit nutrients and texture without requiring deep frying or high sugar content. Clean-label brands and health-conscious consumers are accelerating adoption of these methods. This technology is displacing traditional, additive-heavy fruit gummies and leathers that rely on sugar for preservation and texture.
New front-of-pack labeling (FOPL) systems in the European Union, such as the Nutri-Score, directly influence consumer choice and product development. This framework pressures manufacturers to improve the nutritional profile of their products to achieve a favorable score. Consequently, producers targeting the European market, especially for children's snacks, must prioritize sugar reduction to avoid poor on-shelf ratings.
Subscription-based and curated snack box services are altering how consumers discover and purchase low-sugar fruit snacks. This direct-to-consumer model bypasses traditional retail gatekeepers, offering consumers variety while providing brands with immediate market feedback. The shift is most prominent among urban millennial and Gen Z consumers in North America and Western Europe who value personalization and convenience.
Low Sugar Fruit Snacks Market Segmentation
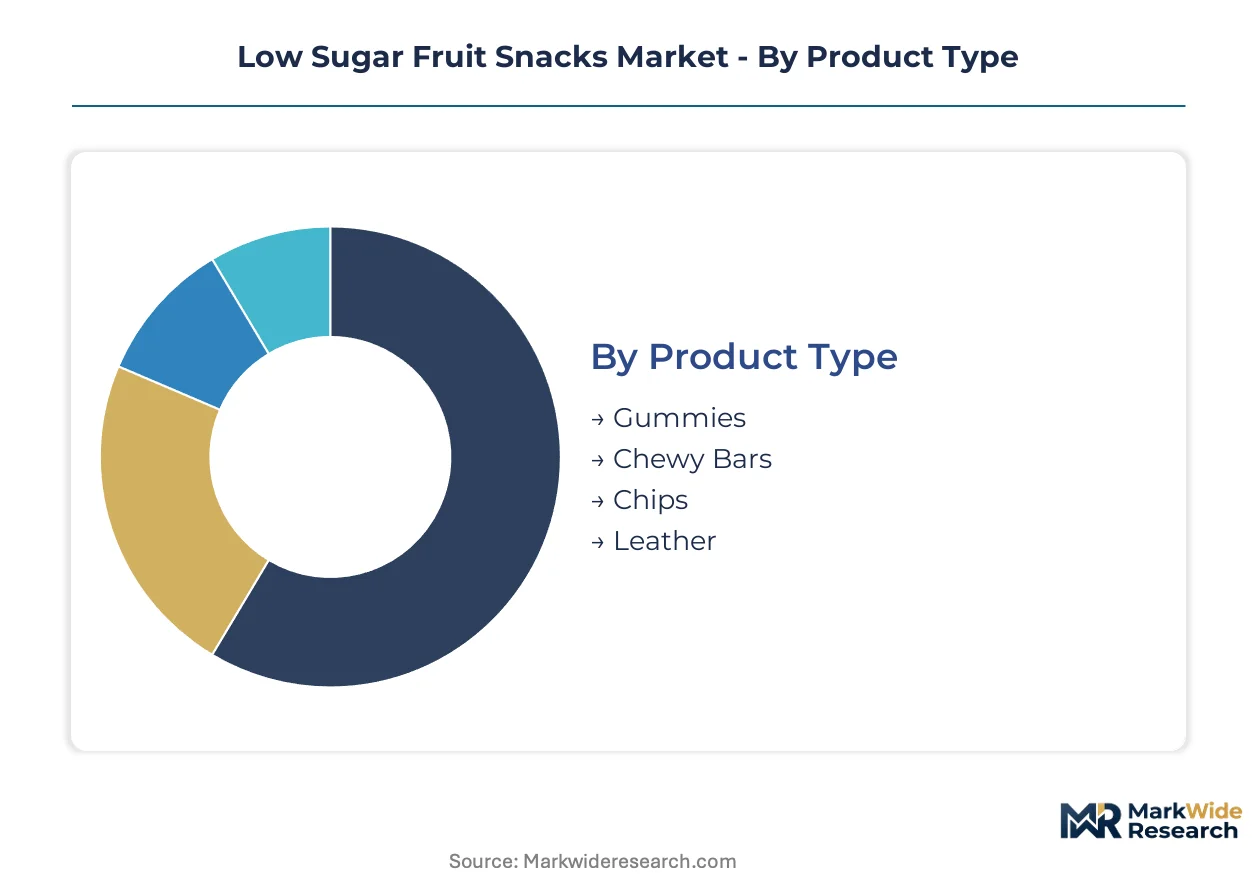
The low sugar fruit snacks market is segmented to reveal distinct consumer preferences and operational efficiencies across product types, ingredient sourcing, distribution, and target demographics. Understanding these divisions helps manufacturers tailor product development and market entry strategies effectively.
Product Type:
Margin pools in the low sugar fruit snacks market are concentrating within innovative product formats that offer distinct textural experiences and convenience for consumers.
- Gummies:These are soft, chewable fruit-flavored snacks, typically made with pectin or gelatin, offering a familiar and appealing texture to both children and adults. Demand for low sugar gummies remains high among parents seeking healthier alternatives for children's lunchboxes across North America.
- Chewy Bars:Often featuring a blend of dried fruits, nuts, and grains, these bars provide a more substantial and satiating snack option, popular with adults seeking on-the-go energy. Consumer demand for portion-controlled, fiber-rich chewy bars is noticeable in European markets.
- Chips:Thinly sliced and dehydrated or baked fruit pieces, offering a crispy texture without added oils or significant sugar, appealing to clean-label consumers.
- Leather:Flexible, sheet-like fruit snacks made from pureed and dried fruit, providing a concentrated fruit flavor and a chewy consistency.
Gummies hold installed capacity. Fruit chips are rotating up the share rankings.
Ingredient Source:
Supply concentration for low sugar fruit snacks is increasingly focused on certified ingredients that meet specific consumer values and regulatory compliance standards.
- Natural:Ingredients derived from natural sources, minimally processed, and free from artificial flavors, colors, or preservatives, appealing to a broad health-conscious base. Demand for naturally sourced sweeteners like stevia and monk fruit is particularly strong in the United States and Australia.
- Organic:Fruits and other ingredients grown and processed without synthetic pesticides, fertilizers, or genetically modified organisms, commanding a premium price point. European consumers, particularly in Germany, show a strong preference for certified organic low sugar fruit snacks.
- Non-GMO:Products made from ingredients that have not been genetically engineered, aligning with consumer demand for transparency and minimal intervention in food production.
- Conventional:Ingredients sourced through standard agricultural practices, often representing the most cost-effective option for mass-market product lines.
The Organic segment is seeing rapid uptake. Conventional ingredients show consistent market presence.
Distribution Channel:
Customer type dictates the effective distribution channels for low sugar fruit snacks, balancing convenience with product discovery and brand visibility.
- Online Retail:E-commerce platforms and brand-specific websites provide direct access to a wide product range, catering to tech-savvy consumers seeking convenience and specialized diet options. This channel is expanding most quickly for niche brands targeting urban millennials in North America.
- Supermarkets:Large retail chains offer extensive shelf space, high foot traffic, and broad consumer reach, serving as a primary sales channel for established and emerging brands. Major supermarkets in developed economies like Germany and the United Kingdom drive significant volume for low sugar fruit snacks.
- Convenience Stores:Smaller retail outlets offering quick grab-and-go options, targeting impulse purchases and immediate consumption.
- Specialty Shops:Health food stores and organic markets catering to specific dietary needs and premium product segments, emphasizing curated selections.
The Supermarkets channel dominates in volume. Online Retail is expanding most quickly.
Target Demographic:
Application drives product formulation and marketing strategies across target demographics for low sugar fruit snacks, addressing specific nutritional needs and lifestyle choices.
- Children:Products formulated to appeal to younger palates and parental concerns about sugar intake, often featuring fun shapes and mild flavors. Parents in countries like Canada and the United States prioritize low sugar options for children's snacks.
- Health Conscious Adults:Individuals actively seeking healthier food choices, valuing clean labels, natural ingredients, and functional benefits in their snacks. This demographic, particularly in Australia and Japan, drives demand for innovative low sugar fruit snack formulations.
- Athletes:Consumers requiring quick energy and nutrient replenishment, often seeking products with added protein or electrolytes to support physical activity.
- Diabetics:Individuals managing blood sugar levels, needing snacks with minimal impact on glycemic response, often relying on natural, non-caloric sweeteners.
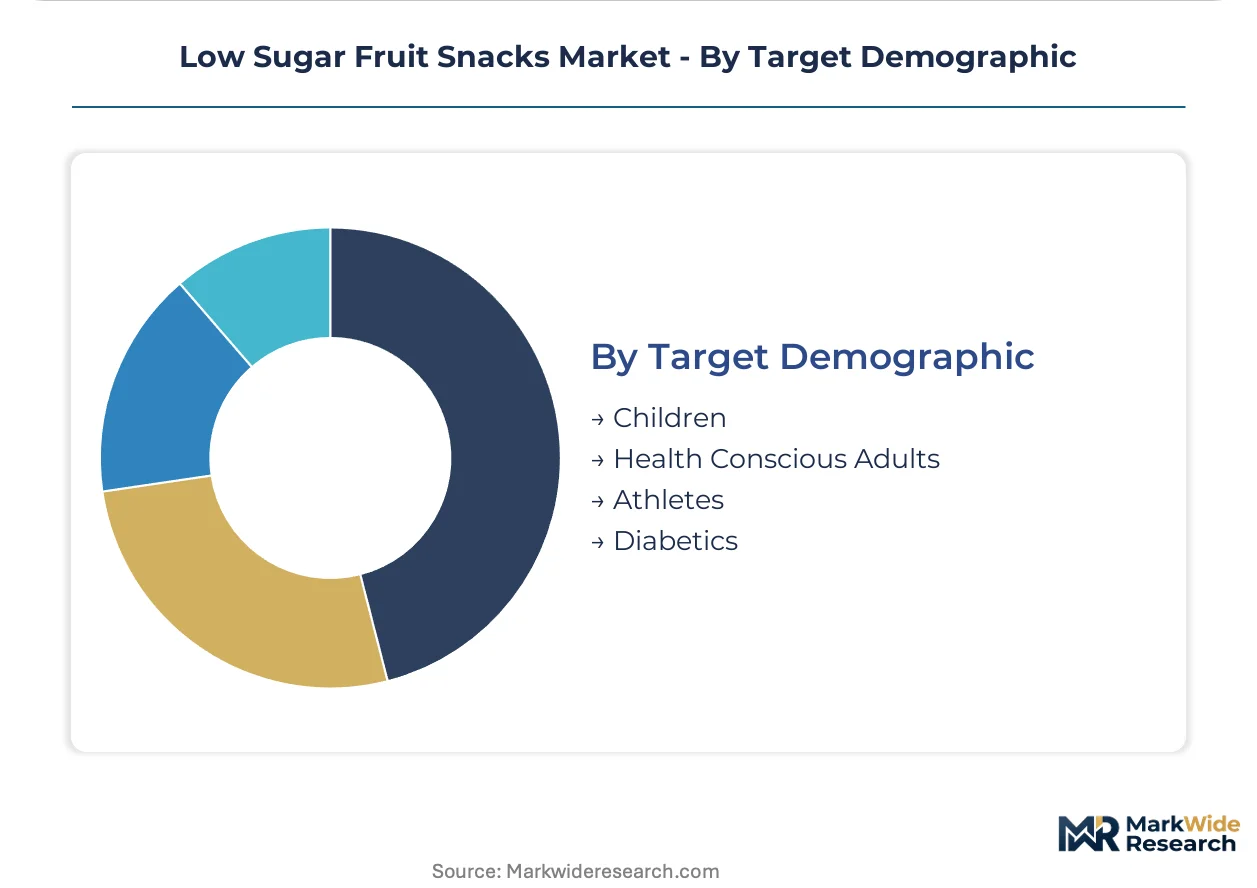
Consumer preference is shifting towards Health Conscious Adults. Children maintain their foundational market share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global trade infrastructure, including major shipping lanes and air cargo hubs, underwrites the widespread distribution of low sugar fruit snacks. Efficient logistics networks connect production centers with diverse consumer markets across continents. This facilitates rapid expansion of health-conscious food trends into new regions.
United States
Health Conscious Adults in the United States actively seek convenient, healthier snack options. The US FDA's mandates for "added sugars" labeling compel manufacturers to reformulate products. California's dynamic food technology ecosystem in cities like San Francisco is a hub for developing natural sweeteners and advanced processing methods.
Germany
German consumers show a strong preference for certified organic and clean-label low sugar fruit snacks. European Food Safety Authority (EFSA) guidelines and the Nutri-Score system pressure manufacturers to improve nutritional profiles. Bavaria, with its established organic food industry, hosts numerous producers specializing in premium low sugar fruit snack offerings.
Australia
Australian Health Conscious Adults drive demand for portion-controlled, convenient low sugar fruit snacks. The Therapeutic Goods Administration (TGA) oversees claims made on functional food products. Melbourne's innovative food sector supports a growing cluster of clean-label low sugar fruit snack companies.
Japan
Japanese consumers increasingly seek wellness-oriented snack options as disposable incomes rise. The Ministry of Health, Labour and Welfare (MHLW) establishes strict guidelines for food additives and nutritional labeling. Tokyo's advanced food research and development clusters are crucial for introducing and refining innovative low sugar fruit snack formulations.
South Korea
South Korean consumers are exploring wellness-oriented snack markets, valuing convenience in their food choices. The Ministry of Food and Drug Safety (MFDS) enforces comprehensive food safety and labeling regulations. Seoul's bustling metropolitan area offers a strong base for e-commerce platforms and curated snack box services.
Low Sugar Fruit Snacks Market Key Industry Players
Listed leaders compete with private specialists across product innovation and market reach in the low sugar fruit snack market. The industry exhibits a tiered structure, with established food conglomerates alongside agile, clean-label startups. Archetypes include diversified snack producers, fruit-focused specialists, and health-and-wellness brands. Dominant competitive moves involve portfolio diversification into low sugar options and strategic partnerships for ingredient sourcing.
Within the diversified snack producer archetype, General Mills and PepsiCo exemplify large-scale market penetration. These multinational corporations leverage extensive global distribution networks to introduce low sugar reformulations of existing, well-known brands across various markets. Fruit-focused specialists like Welch's, with its strong brand recognition built over decades, anchor the traditional fruit snack segment, adapting its offerings to meet evolving health demands. Bare Snacks, a company focused on baked fruit chips, represents the clean-label, simple ingredient specialist, differentiating through minimal processing and transparent sourcing. These diverse players collectively address a broad spectrum of consumer preferences, from familiar family brands to niche health-conscious offerings.
| Leading Market Players |
|---|
| General Mills |
| Nestlé |
| Welch's |
| Danone |
| Kellanov |
| Kellogg Company |
| PepsiCo |
| Bare Snacks |
| RIND Snacks |
| Others |
Cost & Logistics Intelligence
Natural sweetener substitution for conventional sugar simultaneously reshapes supply geography and pricing economics in the low sugar fruit snacks market. This dynamic influences ingredient sourcing decisions and final product costs for manufacturers.
Pricing Analysis
Volume-discount tiering structures differentiate low sugar fruit snack prices across various segments. Price differentiation stems from certification levels, such as Non-GMO Project Verified, and established brand premium. Pricing pressure originates from the higher cost and volatility of natural sweeteners like stevia and monk fruit, compressing manufacturer profit margins. Health Conscious Adults demonstrate lower price sensitivity for certified clean-label options, while conventional consumers remain highly price-sensitive.
Supply Chain Analysis
Certified ingredient sourcing presents a chokepoint for premium low sugar fruit snack producers. Supply concentrations for key ingredients like specific fruit varieties and natural sweeteners draw from diverse regions, including the United States, South America, and Asia. Raw material dependencies center on stevia, monk fruit, and various fruit concentrates. Commodity price volatility for these natural sweeteners represents a significant structural supply chain risk. Distribution runs through major supermarkets for established brands and online retail for niche clean-label offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a cyclical recovery, primarily driven by a renewed global focus on health and wellness following recent public health events.
For Market Incumbents: Fortify existing brand portfolios by aggressively reformulating traditional fruit snacks into low sugar variants. This protects market share against stricter FDA labeling mandates and consumer preference shifts. Invest in R&D for advanced natural sweetener blends and dehydration technologies to improve sensory profiles. Expand distribution to dedicated "wellness" aisles within major supermarkets across North America and Europe.
For New Entrants and Emerging Players: Lead with innovative product formats like fruit chips and leathers, targeting the expanding Health Conscious Adults demographic. Asia-Pacific markets, particularly South Korea and Japan, offer significant white-space opportunities for wellness-oriented snacks. A direct-to-consumer (DTC) e-commerce strategy allows for rapid product innovation and direct feedback from urban millennial and Gen Z consumers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with agile, clean-label specialists leveraging direct-to-consumer models. Long-term viability remains strong for brands focused on verifiable health credentials and transparent ingredient sourcing. Acquire companies with strong intellectual property in natural sweetening systems or advanced fruit processing. The expansion of mandatory front-of-pack labeling systems into new regions serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Expand low-sugar offerings into fruit chips and leathers to capture evolving consumer preferences. |
| Direct-to-Consumer Launch | Establish e-commerce platforms for niche brands, bypassing traditional retail gatekeepers. |
| Premium Tier Introduction | Integrate probiotics or plant-based protein for specific health benefits beyond sugar reduction. |
| Distribution Channel Expansion | Target wellness aisles in major supermarkets across Germany and Australia for increased visibility. |
| Sustainability Repositioning | Emphasize certified organic and Non-GMO ingredient sourcing to appeal to conscious consumers. |
Research Approach
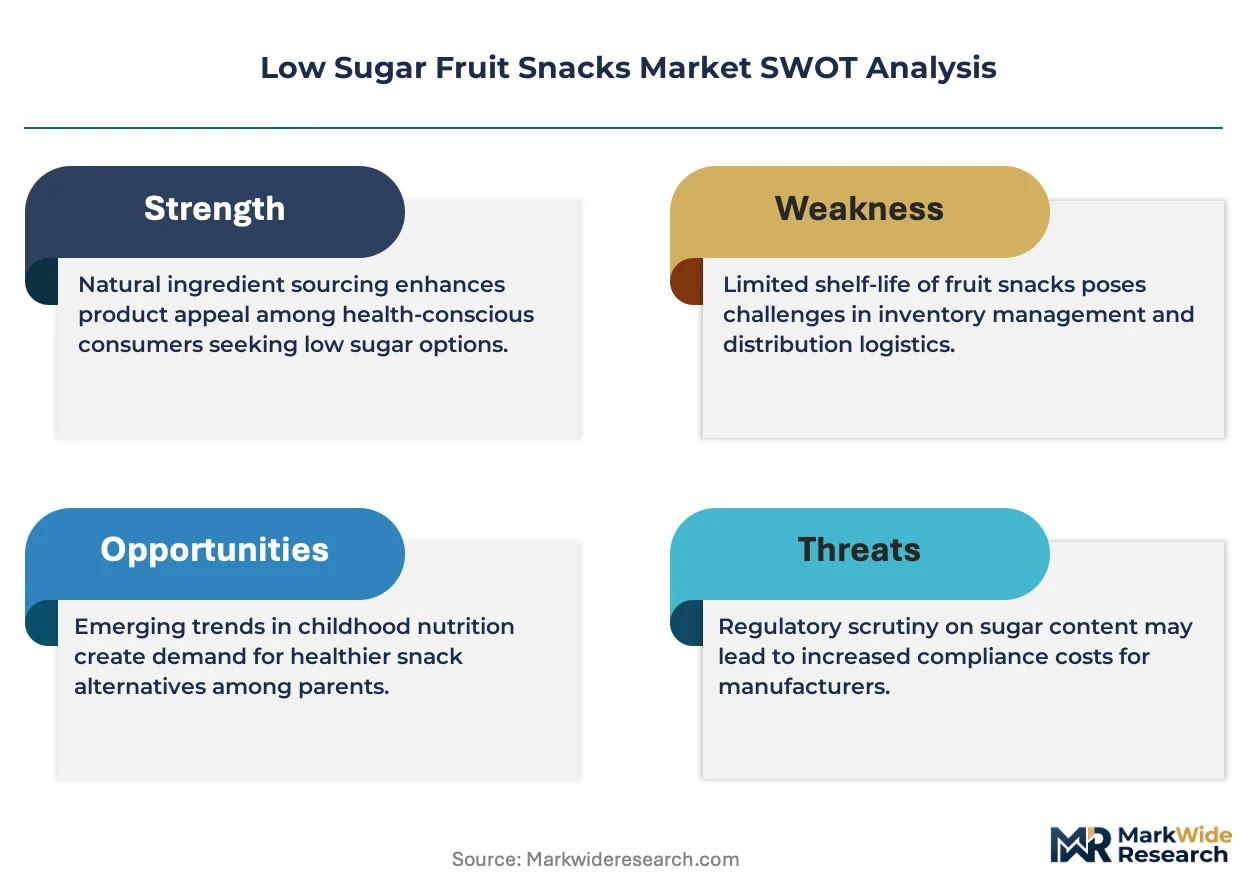
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation through market reports. Insights were gathered from product development scientists, regulatory affairs managers, retail category buyers, and health-conscious consumer focus groups. Secondary sources included FDA filings, EFSA reports, FSSAI regulations, and Nielsen/Circana retail audit data. The study employed both bottom-up and top-down triangulation to ensure data accuracy.
The forecasting boundary extends across the analysis window, utilizing a robust analytical framework. Market segmentation dimensions modeled included product type, ingredient source, distribution channel, and target demographic. Compound annual growth rates were derived from historical data and projected market dynamics, incorporating industry-specific inputs like evolving natural sweetener costs and the expansion of wellness aisles. This approach provides a comprehensive outlook on market trajectory.
Underlying assumptions cover the current regulatory landscape and consumer preference shifts, with deviation risk concentrated in unforeseen policy changes. Practitioners should keep alternative scenarios live as regulatory frameworks and consumer health priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
UAE Cereal Bar Market
Snacks
Salty Puffed Snacks Market
Snacks
United States Children's Snack Bar Market
Snacks
United States Snack Bar Market
Snacks
Corn Chips Market
Snacks
Sweet Potato Chips Market
Snacks
Middle East and North Africa Extruded Snack Food Market
Snacks
North America Energy Bar Market
Snacks
Germany Snack Bar Market
Snacks
Cereal Bars Market
Snacks
Energy Balls Market
Snacks
Kale Chips Market
Snacks
Fried Potato Chips Market
Snacks
Instant Meat Marinated Snacks Market
Snacks
Europe Extruded Snack Food Market
Snacks
Jerky Snacks Market