
 Nutritional Bar Market | 2026-2036
Nutritional Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Nutritional Bar Market Intelligence
Market Context with Strategic Players
Plant-based proteins are restructuring cost structures across the nutritional bar category as soy and pea isolates displace traditional dairy whey in mid-tier formulations. Clif Bar & Company leverages its organic supply chain to sustain premium positioning in outdoor and endurance segments. Quest Nutrition specializes in high-protein, low-carb formulations that anchor its dominance in ketogenic and weight-management channels. General Mills competes through mass-market distribution scale, extending its cereal-based ingredient expertise into snack bar formats.
Technical Definition and Structural Segments
A nutritional bar is a shelf-stable, ready-to-eat food product typically delivering 150–400 calories with defined macronutrient profiles, manufactured through cold extrusion or slab-forming processes and designed for portable meal supplementation or targeted nutrient delivery. Protein bars command the largest revenue pool due to established gym-channel penetration and repeat purchase rates among fitness enthusiasts, while snack bars represent the fastest-expanding segment as busy professionals seek portable alternatives to traditional confectionery. Online retail is capturing disproportionate growth in distribution channel dynamics, though supermarkets retain volume leadership through impulse-placement strategies.
Regulatory Frame and Forward-Looking Close
The FDA governs nutritional labeling and health claim substantiation under the Federal Food, Drug, and Cosmetic Act, while the USDA oversees organic certification pathways that premium brands exploit for differentiation. The FTC monitors advertising claims related to weight loss and performance benefits, creating compliance costs that favor established players with dedicated regulatory affairs functions. Stakeholders must monitor evolving positions from EFSA and Health Canada on protein intake thresholds, as harmonized standards would reshape export formulation requirements and testing protocols.
Market Dynamics
Clean-label formulation requirements are compressing R&D timelines across the nutritional bar category as manufacturers reformulate legacy recipes to eliminate artificial sweeteners and synthetic preservatives while maintaining shelf stability and taste profiles.
Growth Catalysts
- FDA Nutrition Facts modernization:Updated serving-size definitions and added-sugar disclosure rules are forcing transparency upgrades that premium brands leverage for competitive differentiation.
- Endurance sports participation:Marathon and ultramarathon registration volumes in Colorado and Oregon are expanding demand for sodium-dense, portable fueling formats with organic certification.
- Pea protein isolation advances:Wet-fractionation improvements at Midwest processing facilities are reducing plant-protein bitterness, enabling broader dairy-free formulation adoption.
Market Restraints
- Almond supply concentration:California's Central Valley dominates global almond production, exposing bar manufacturers to irrigation-water allocation volatility and pollination-cost inflation.
- Technical limitation:Clean-label emulsifiers lack the oxidative stability of TBHQ and BHT, shortening shelf life from 18 months to 9-12 months in ambient distribution.
- Regulatory friction:EFSA's pending protein-health-claim substantiation requirements are delaying EU launch timelines for brands dependent on performance marketing.
Strategic Opportunities
- Geriatric nutrition white space:Texture-modified, high-protein bars for dysphagia patients remain underdeveloped in Japan's aging prefectures outside Tokyo and Osaka.
- Regulatory tailwind:India's FSSAI functional-food notification pathway is opening claims for ayurvedic adaptogen inclusion in sports nutrition formats.
- Direct-to-patient distribution:Hospital discharge nutrition protocols are creating institutional procurement channels for medically tailored meal bars.
Industry Challenges
- Formulation talent scarcity:Food scientists with dual expertise in protein chemistry and sensory science command premium compensation, constraining mid-tier brand R&D expansion.
- Organic certification timeline:Three-year land-conversion requirements for USDA organic supply chains delay new ingredient sourcing by 36-48 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutritional Bar Market |
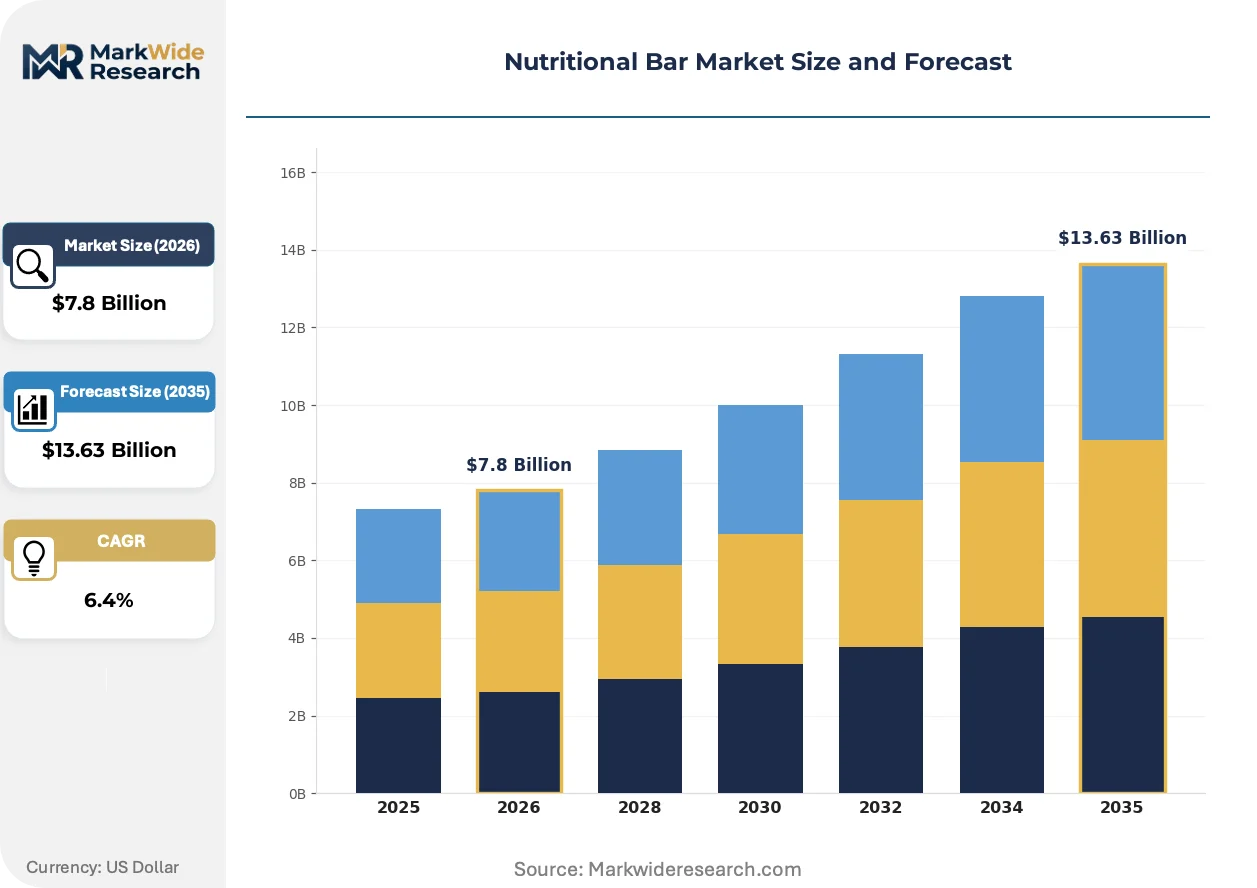
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Meal Replacement Bars, Snack Bars, Energy Bars Ingredient Type: Nuts, Fruits, Grains, Chocolate Target Audience: Fitness Enthusiasts, Weight Watchers, Athletes, Busy Professionals Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores |
| Companies Covered | Clif Bar & Company, Quest Nutrition, The Kellogg Company, General Mills, Glanbia Performance Nutrition, Premier Nutrition, Mars Incorporated, PepsiCo, Mondelez International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutritional Bar Market Strategic Shifts & Innovations
Precision fermentation and cellular agriculture are beginning to intersect with conventional bar manufacturing, creating novel ingredient categories that challenge established protein sourcing economics and clean-label positioning strategies.
Precision-fermented whey proteins are expanding into sports nutrition formulations as Perfect Day and similar suppliers achieve price parity with conventional dairy isolates. Endurance athletes and CrossFit participants in Austin and Denver are adopting these lactose-free alternatives at accelerating rates. This biotechnology is compressing the traditional dairy supply chain and enabling brands to market identical amino acid profiles without animal agriculture associations.
The EU's Corporate Sustainability Reporting Directive is mandating Scope 3 emissions disclosure for nutritional bar importers above revenue thresholds. Manufacturers sourcing South American cocoa and Southeast Asian coconut must now document deforestation-free supply chains or face market access restrictions. Premium organic brands with existing supplier audit infrastructure are absorbing compliance costs more efficiently than mass-market competitors.
Subscription-based replenishment models are displacing supermarket impulse purchases among remote workers and frequent travelers. Direct-to-consumer brands with personalized macronutrient matching are capturing loyalty in tech-centric metropolitan areas like Seattle and San Francisco. This channel rotation is most visible among software engineers and consultants who prioritize convenience over in-store browsing.
Nutritional Bar Market Segmentation
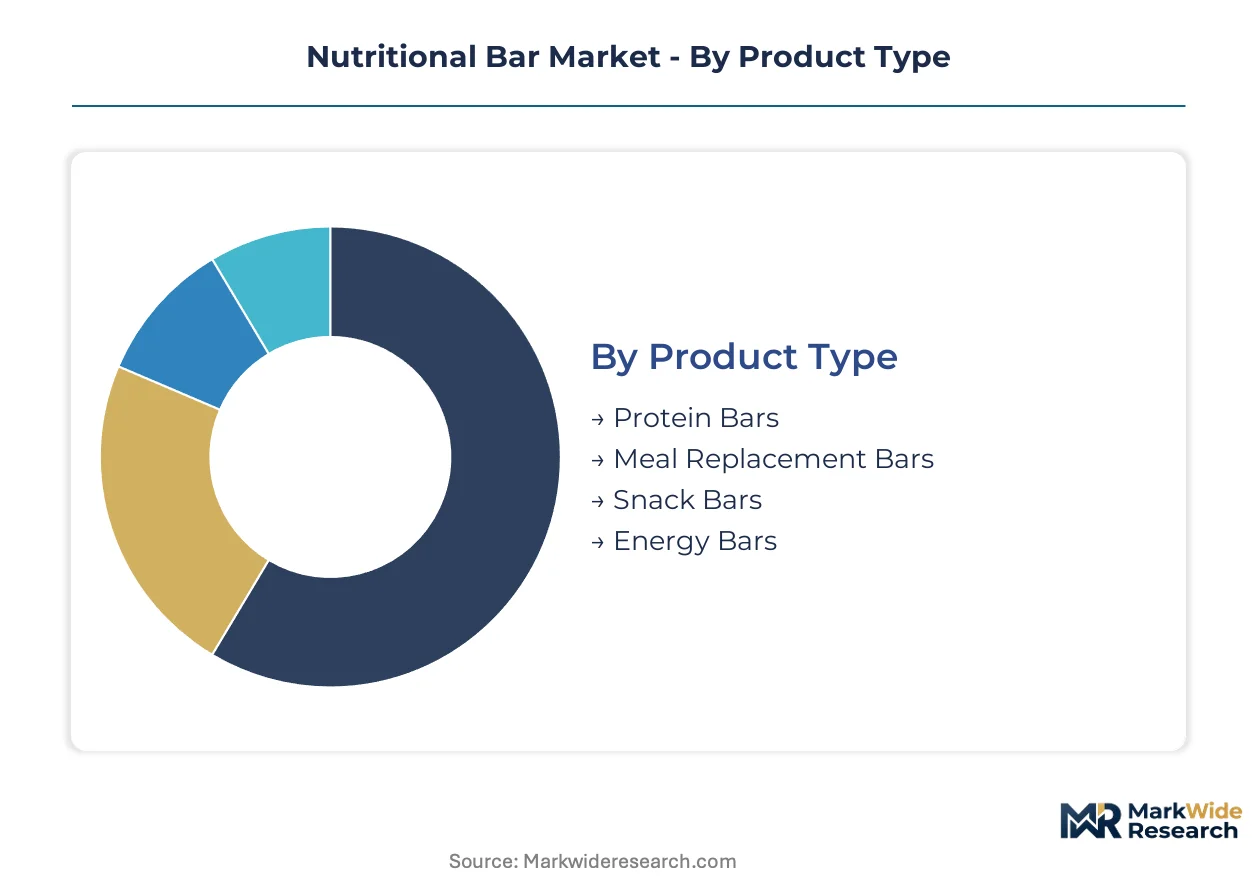
Nutritional bar manufacturers align formulation architecture with distinct consumption occasions and channel economics. Segment boundaries increasingly blur as protein fortification penetrates snack formats and meal-replacement brands pursue impulse-placement strategies.
Product Type:
Volume concentration favors mass-market snack formats while premium pricing power clusters in performance-positioned variants.
- Protein Bars:Formulations deliver 15-25g protein per serving through whey, casein, or plant isolates with controlled carbohydrate profiles. Demand concentrates among CrossFit participants and bodybuilders in Texas and Florida, driven by gym-channel distribution and repeat purchase loyalty programs.
- Snack Bars:Lower-protein formats emphasize whole-food ingredients and portability for between-meal consumption. Busy professionals in Seattle and Austin are displacing traditional confectionery with these alternatives, prioritizing convenience and perceived nutritional upgrade over macronutrient precision.
- Meal Replacement Bars:Calorie-dense formulations at 300-400 kcal with vitamin-mineral fortification for controlled nutrition.
- Energy Bars:Carbohydrate-focused compositions targeting endurance athletes with rapid glycogen delivery.
Mature deployment sits with Protein Bars. Newer deployment is concentrated in Snack Bars.
Ingredient Type:
Cost tiering follows agricultural commodity volatility and clean-label certification premiums.
- Nuts:Almond and cashew bases dominate premium positioning with protein density and texture functionality. California's Central Valley irrigation constraints are compressing margin structures for mid-tier brands dependent on conventional almond supply.
- Grains:Oat and quinoa formulations anchor mass-market accessibility with soluble fiber claims and lower price points. European demand for gluten-free ancient grains is reshaping sourcing patterns toward South American suppliers.
- Fruits:Date and dried berry inclusions provide natural sweetness and binding functionality.
- Chocolate:Cocoa-based coatings and inclusions bridge confectionery crossover appeal.
Ingredient premiums concentrate in Nuts. Volume scaling centers on Grains.
Target Audience:
Customer archetypes map to distinct channel preferences and price elasticity profiles.
- Fitness Enthusiasts:Protein-seeking consumers with high brand loyalty and subscription purchasing patterns. Colorado and Oregon endurance communities are driving sodium-dense, organic-certified format innovation through specialty retail and direct-to-consumer channels.
- Busy Professionals:Convenience-prioritizing segment with low pantry inventory and high impulse responsiveness. Remote workers in metropolitan corridors are accelerating subscription-model adoption with personalized macronutrient matching.
- Weight Watchers:Calorie-controlled and portion-managed consumers seeking satiety signaling.
- Athletes:Performance-optimized consumers with event-specific fueling protocols and coach-influenced brand selection.
Established loyalty programs serve Fitness Enthusiasts. Fastest audience expansion is occurring among Busy Professionals.
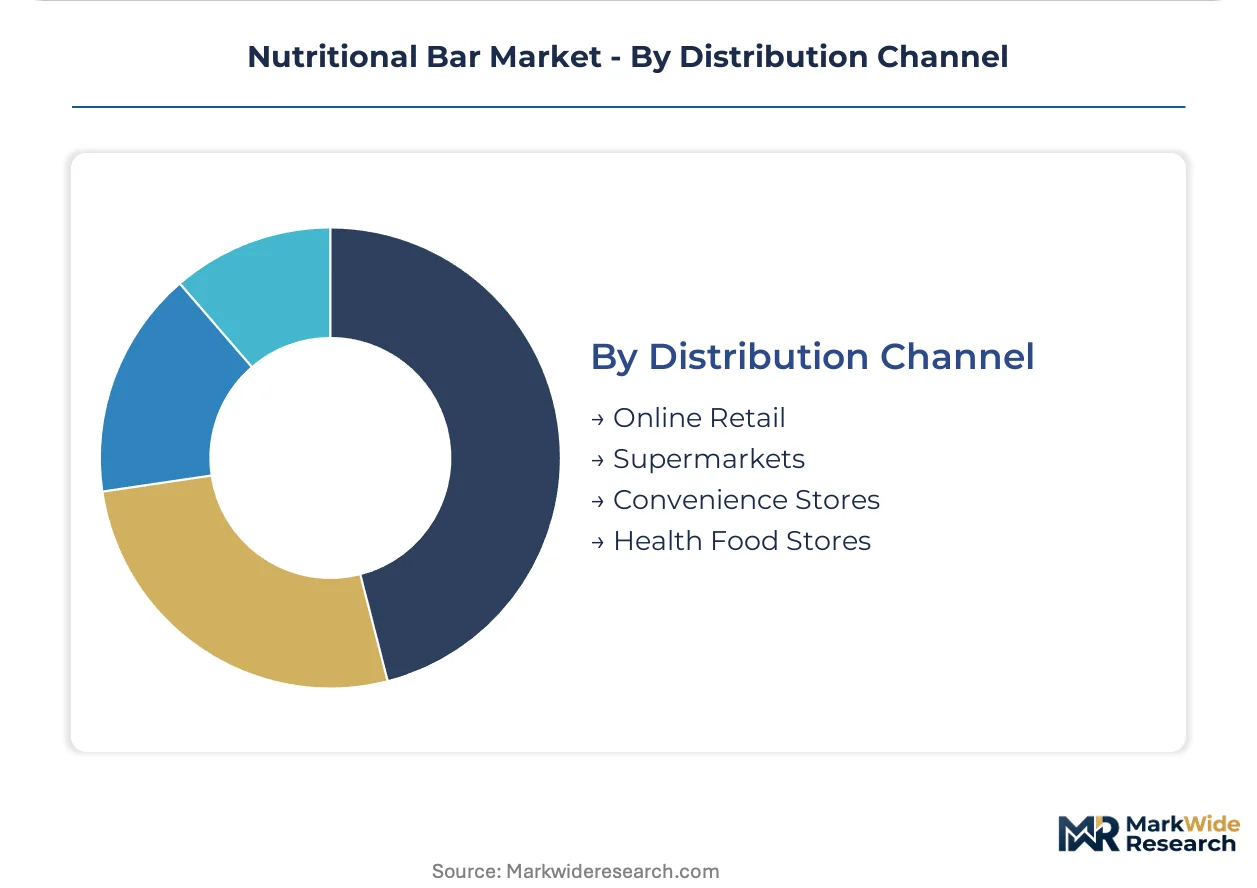
Distribution Channel:
Channel margins and inventory turnover rates determine brand tier accessibility and promotional intensity.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription replenishment and personalization algorithms. Tech-sector professionals in San Francisco and Seattle are displacing supermarket trips with automated reorder systems and flavor-curation services.
- Supermarkets:Mass-market volume leadership through end-cap placement and promotional pricing. Impulse-location strategies in California and New York retail chains sustain trial conversion for emerging brands.
- Convenience Stores:Grab-and-go positioning with single-serve pricing and travel-oriented consumption.
- Health Food Stores:Curated assortment with staff recommendation influence and organic certification filtering.
Volume concentration remains with Supermarkets. Channel expansion is climbing fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for nutritional bars concentrates among fitness enthusiasts in Colorado and Texas, where gym-channel penetration and subscription-model adoption outpace other developed markets. Clean-label formulation requirements and FDA Nutrition Facts modernization are compressing R&D timelines while reshaping competitive positioning.
United States
CrossFit participants in Austin and Denver drive protein bar consumption through specialty retail and direct-to-consumer channels. The FDA's updated Nutrition Facts labeling requirements force transparency upgrades that premium brands leverage for differentiation. California's Central Valley anchors almond supply chains, exposing manufacturers to irrigation-water allocation volatility.
Germany
Endurance athletes in Bavaria and North Rhine-Westphalia demand sodium-dense, organic-certified fueling formats for marathon participation. EFSA's pending protein-health-claim substantiation requirements delay EU launch timelines for performance-marketing brands. Berlin-based clean-label startups exploit the EU Green Deal's sustainability disclosure mandates for competitive positioning.
United Kingdom
Busy professionals in London and Manchester displace traditional confectionery with snack bars prioritizing convenience over macronutrient precision. The Competition and Markets Authority scrutinizes subscription-model pricing transparency. Scotland's Highland regions supply oat-based ingredients for gluten-free ancient grain formulations.
India
Fitness enthusiasts in Maharashtra and Karnataka expand protein bar adoption through gym-channel distribution and repeat purchase loyalty programs. FSSAI's functional-food notification pathway opens claims for ayurvedic adaptogen inclusion in sports nutrition formats. Gujarat's processing facilities reduce plant-protein bitterness through wet-fractionation improvements.
Japan
Geriatric nutrition demand concentrates in aging prefectures outside Tokyo and Osaka, where texture-modified, high-protein bars for dysphagia patients remain underdeveloped. METI's standards for functional food claims create compliance pathways for medical nutrition formats. Nagoya's food technology clusters advance sensory science for senior-appropriate formulations.
Nutritional Bar Market Key Industry Players
Portfolio diversification dominates the current landscape as established food conglomerates and specialist nutrition brands reposition across protein, snack, and meal-replacement segments. The vendor base spans three tiers: mass-market conglomerates with cereal-based expertise, premium organic specialists with captive supply chains, and direct-to-consumer innovators with personalized macronutrient algorithms. Two competitive moves define current dynamics: M&A activity consolidating distribution scale and backward integration into plant-protein processing securing ingredient cost control.
Within the premium organic tier, Clif Bar & Company exemplifies supply chain differentiation through certified organic sourcing, while Quest Nutrition anchors the high-protein, low-carb specialization vector. General Mills occupies a position among mass-market conglomerates extending cereal-based ingredient expertise into snack bar formats.
| Leading Market Players |
|---|
| Clif Bar & Company |
| Quest Nutrition |
| The Kellogg Company |
| General Mills |
| Glanbia Performance Nutrition |
| Premier Nutrition |
| Mars Incorporated |
| PepsiCo |
| Mondelez International |
| Others |
Cost & Logistics Intelligence
Fitness enthusiasts in Colorado and Texas anchor demand concentration, binding pricing power to gym-channel subscription models and repeat purchase loyalty programs rather than transactional supermarket dynamics.
Pricing Analysis
Volume-mass snack bars trade at commodity-adjacent margins while premium protein formats capture sustained markup through certification premiums and personalized macronutrient matching. Three-tier pricing structure across premium, standard, and economy levels reflects USDA organic certification status, protein isolate quality grade, and channel service bundling. Cost compression in mid-tier nut-based formulations is intensifying because California almond supply volatility feeds raw material uncertainty. Price-sensitive mass-market consumers in supermarket channels drive promotional intensity, while least-sensitive endurance athletes in specialty retail accept subscription premiums for sodium-dense, organic-certified formats.
Supply Chain Analysis
Dual-sourcing requirements for plant-protein isolates now mandate Midwest wet-fractionation facilities alongside traditional dairy processing infrastructure to mitigate single-origin risk. Geographic supply concentration centers on the United States for almond and oat bases, Canada for pea protein fractionation, and Southeast Asia for coconut derivatives. Raw material dependencies rest on California irrigation allocations, Midwest processing capacity, and South American ancient grain flows. Single-source vulnerability in California's Central Valley exposes manufacturers to pollination-cost inflation and water-rights volatility. Distribution runs through direct-to-consumer subscription platforms for premium tiers and mass-market retail for volume penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's Central Valley irrigation constraints prop pricing across nut-dependent formulations, sustaining premium capture for brands with captive organic supply chains and certified sourcing infrastructure.
For Market Incumbents: Anticipate precision-fermented whey displacement by securing offtake agreements with Perfect Day and similar suppliers before price parity erodes dairy-based differentiation. Defend against direct-to-consumer entrants by deepening gym-channel exclusivity and subscription-lock-in programs. Prioritize backward integration into Midwest pea-protein processing to control isolate cost structures and reduce California almond dependency.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier to trial conversion among remote workers in Seattle and San Francisco. Target texture-modified geriatric nutrition formats in Japan's aging prefectures outside Tokyo and Osaka, where medical nutrition protocols remain underpenetrated. Pursue FSSAI functional-food notification in India for ayurvedic adaptogen positioning in Maharashtra and Karnataka gym channels.
For Investors and Strategic Acquirers: The window for entry favors premium organic specialists with three-year land-conversion pipelines already underway, as USDA certification timelines create 36-48 month moats against fast-follower replication. Mid-tier brands with dual expertise in protein chemistry and sensory science represent acquisition targets given formulation talent scarcity. Watch EFSA protein-health-claim substantiation rulings as the inflection signal for EU market access and performance-marketing compliance costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plant-Protein Processing | Midwest wet-fractionation investments reduce isolate cost volatility and enable clean-label formulation control. |
| Direct-to-Consumer Subscription Launch | Automated replenishment captures remote worker loyalty in tech-centric metropolitan corridors with personalized algorithms. |
| USDA Organic Certification Pipeline | Three-year land-conversion requirements create supply moats that premium brands exploit for competitive differentiation. |
| Precision-Fermented Whey Partnership | Perfect Day supply agreements enable lactose-free positioning with identical amino acid profiles before price parity erodes. |
| Geriatric Nutrition Format Development | Texture-modified, high-protein bars for dysphagia patients address Japan's aging prefecture demand outside Tokyo and Osaka. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across formulation scientists, gym-channel procurement managers, retail category buyers, and supply chain directors at Midwest processing facilities. FDA Nutrition Facts modernization documents, FSSAI functional-food notifications, and EFSA health-claim substantiation filings provided regulatory trajectory inputs. Bottom-up volume modeling from SKU-level retail audit data reconciled with top-down category expenditure estimates across the analysis window.
Data-stream reconciliation across protein bar, snack bar, meal replacement, and energy bar segments enabled coherent growth rate derivation without category double-counting. Modeled dimensions spanned product type, ingredient certification tier, target audience archetype, and distribution channel economics. CAGR trajectories incorporated gym-channel penetration rates, subscription-model adoption curves, and clean-label reformulation timelines as industry-specific forecast inputs throughout the projection horizon.
Inputs from FDA, FSSAI, and EFSA regulatory databases were available through the study window; gaps in pending EFSA protein-health-claim rulings introduce uncertainty bands for EU launch timeline assumptions. Forecasts reflect documented assumptions regarding almond supply stability, precision-fermentation scale-up trajectories, and subscription-model retention rates. Deviation in California irrigation-water allocation or EFSA substantiation requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Corn Chips Market
Snacks
South America Frozen Snacks Market
Snacks
UK Snack Market
Snacks
Sweet Potato Chips Market
Snacks
Instant Meat Marinated Snacks Market
Snacks
Low Calorie Cookies Market
Snacks
Low-Fat Tortillas Market
Snacks
Southeast Asia Savory Snacks Market
Snacks
Fat Free Snacks Market
Snacks
Seafood Snacks Market
Snacks
Oat-Based Snacks Market
Snacks
Europe Popcorn Market
Snacks
Low Fat Protein Snacks Market
Snacks
Thailand Snack Bar Market
Snacks
China Snack Bar Market
Snacks
North America Snack Food Market