
 Gluten-Free Pizza Crust Market | 2026-2036
Gluten-Free Pizza Crust Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Pizza Crust Market Analysis
Gluten-free baking expertise is collapsing across commercial kitchens, forcing manufacturers to pre-formulate crusts that require minimal skill to finish. Dr. Schär AG / SPA leverages European milling heritage to sustain premium positioning in North American retail. Amy's Kitchen, Inc. anchors its portfolio with certified gluten-free production lines that dominate frozen aisle placement. Bob's Red Mill Natural Foods, Inc. competes through ingredient-forward branding that controls consumer trust in whole-grain alternatives.
A gluten-free pizza crust is a flatbread base formulated without wheat, barley, or rye proteins, typically using rice flour, tapioca starch, or almond flour with hydrocolloid binders to achieve extensibility and browning comparable to conventional dough, produced for both retail home preparation and food service finishing. Frozen crusts lead volume due to extended shelf stability and food service operational simplicity, while refrigerated formats capture margin pools through freshness positioning in premium channels. Almond flour formulations represent the fastest-growing ingredient segment as consumers prioritize protein density and lower glycemic indexes in specialty diets.
The FDA enforces gluten-free labeling standards below 20 parts per million, compelling manufacturers to validate supply chains and testing protocols for market access. The USDA Organic certification and Non-GMO Project verification create additional compliance layers that segment price tiers and channel eligibility. Stakeholders must monitor evolving grain-adjacent allergen regulations and clean-label ingredient innovations to maintain formulation flexibility and retail placement.
Market Dynamics
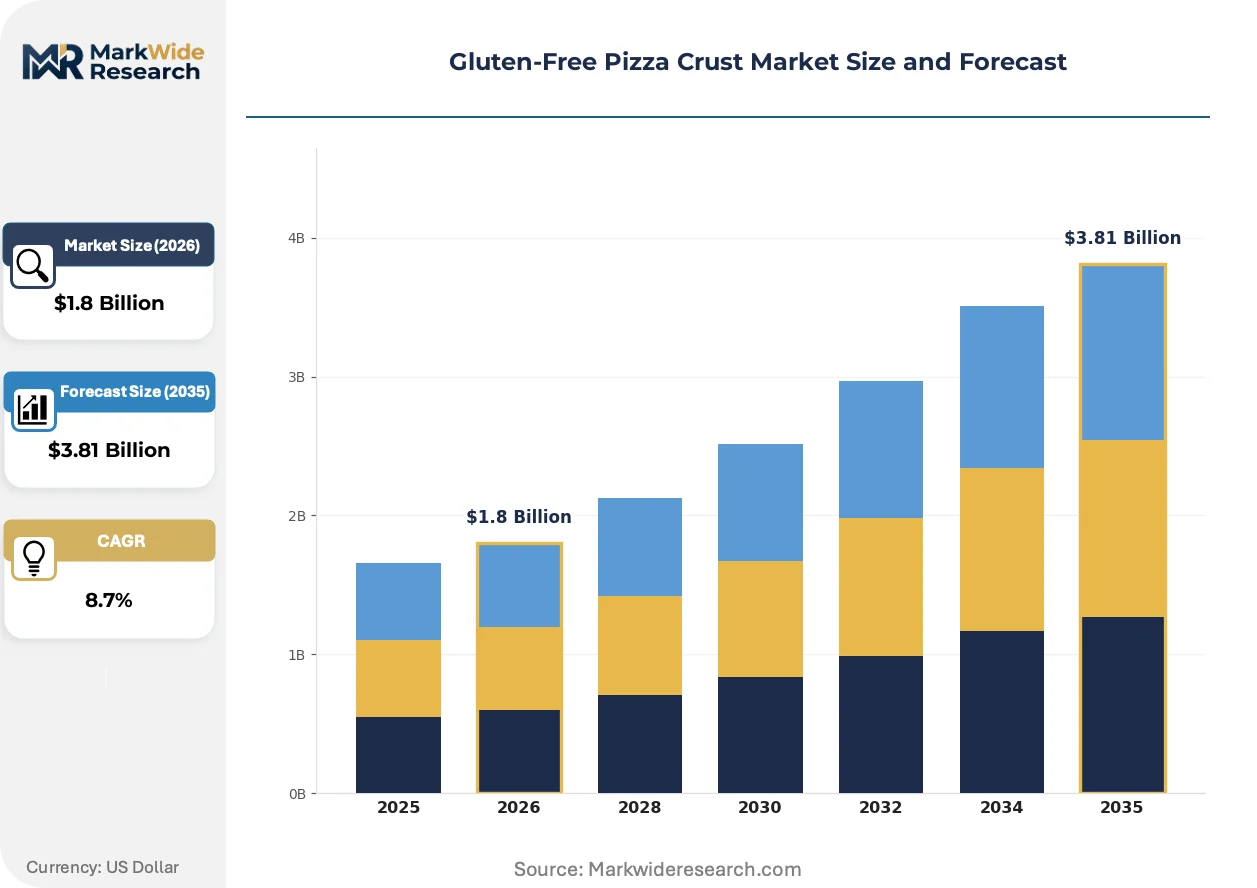
Pre-formulated crust manufacturing is consolidating gluten-free baking expertise away from restaurant kitchens, forcing food service operators to depend on external suppliers for quality consistency and regulatory compliance.
Growth Catalysts
- US FDA Gluten-Free Labeling Rule:The sub-20 ppm standard validates consumer trust and expands retail shelf access for certified manufacturers.
- Celiac Disease Diagnostic Rates:Rising physician screening in the United States expands the addressable patient population requiring strict dietary adherence.
- Almond Flour Protein Density:This ingredient shift attracts ketogenic and paleo diet followers beyond traditional celiac consumers.
Market Restraints
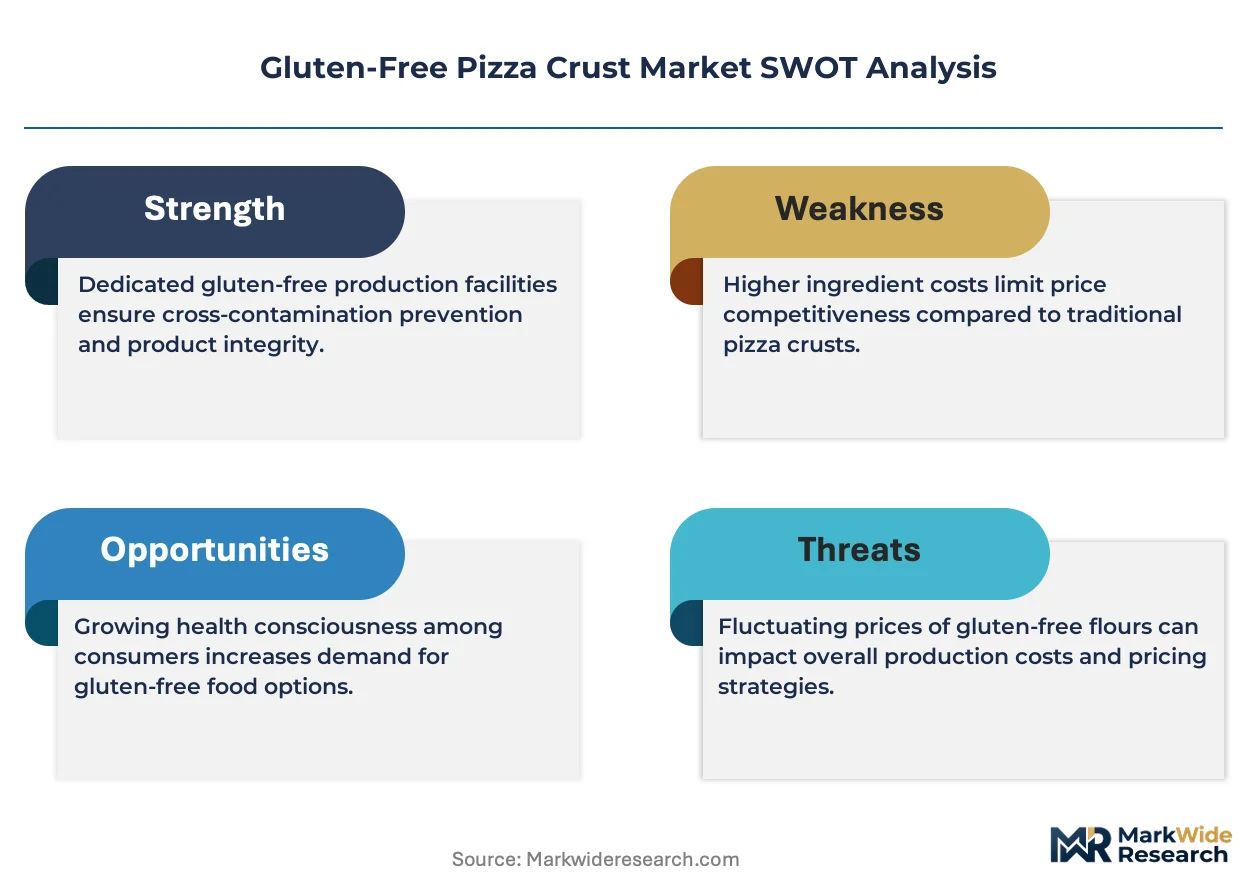
- Specialty Ingredient Cost Volatility:Tapioca starch and rice flour prices fluctuate with Asian agricultural output, squeezing margin structures.
- Supply Concentration in European Milling:Premium gluten-free flour sourcing clusters with Dr. Schär AG and select Italian suppliers, creating bottleneck risk.
- Technical Texture Limitations:Hydrocolloid binders fail to replicate wheat gluten extensibility in thin-crust applications, constraining format innovation.
Strategic Opportunities
- Underpenetrated Food Service Chains:Independent pizzerias in secondary US metropolitan areas lack certified gluten-free protocols, creating white space for turnkey crust programs.
- USDA Organic Certification Tailwind:Dual-certified organic-gluten-free products command premium placement in natural grocery channels.
- Direct-to-Restaurant Distribution:Bypassing broadline distributors with specialized frozen logistics captures margin from high-volume independent operators.
Industry Challenges
- Gluten Cross-Contamination Prevention:Dedicated production lines require capital-intensive facility segregation and environmental monitoring systems.
- Multi-Certification Timeline Compression:Simultaneous pursuit of FDA compliance, Non-GMO Project verification, and kosher certification extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Pizza Crust Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Refrigerated, Mixes, Ready-to-Bake Ingredient Source: Rice Flour, Almond Flour, Corn Flour, Tapioca Starch Distribution Channel: Retail Stores, Online, Food Service, Supermarkets End User: Households, Restaurants, Cafes, Pizzerias |
| Companies Covered | Kinnikinnick Foods Inc., Capello’s, Udi's Gluten Free, Amy’s Kitchen, Inc., Namaste Foods LLC, Dr. Schär AG / SPA, Bob’s Red Mill Natural Foods, Inc., Cali'flour Foods, Rich Products Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Pizza Crust Market Emerging Trajectories
Ingredient science and regulatory precision are converging to redefine what gluten-free crusts can achieve in texture, nutrition, and supply chain transparency.
Sourdough fermentation protocols adapted for rice and sorghum bases are supplanting chemically leavened alternatives in premium retail. Artisan pizzerias in Portland, Oregon and Austin, Texas have adopted these living-culture methods to differentiate their frozen retail lines. The technique compresses additive dependence while delivering the blistered crust aesthetics that conventional gluten-free products fail to achieve.
The FDA's updated guidance on gluten-free oat processing has tightened supply chain documentation requirements for cross-contact prevention. Manufacturers must now validate equipment cleaning protocols and supplier oat purity through third-party audit trails. Frozen crust producers sourcing oat flour are restructuring supplier contracts to include batch-level gluten testing, with the greatest operational impact falling on mid-sized regional bakeries lacking in-house laboratories.
Restaurant procurement teams are consolidating gluten-free SKUs from multiple specialty vendors onto single-source contracts with certified manufacturers. This concentration displaces the fragmented purchasing of retail mixes by individual kitchen managers. The shift is most visible in the US fast-casual pizza segment, where chains like Blaze Pizza and MOD Pizza have standardized on two approved crust suppliers to simplify training and liability exposure.
Gluten-Free Pizza Crust Market Segmentation
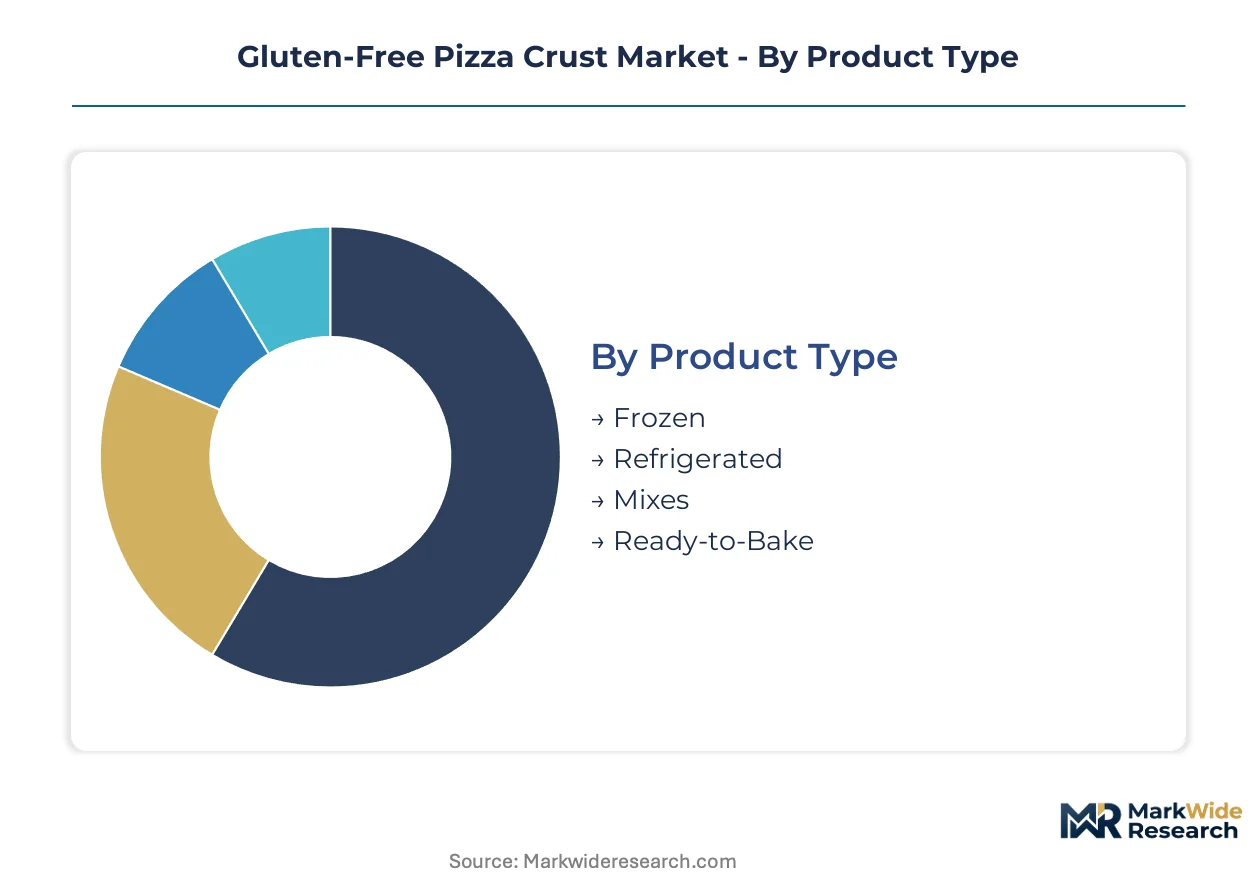
Segmentation in the gluten-free pizza crust market reveals how formulation choices and channel strategies concentrate profit pools. Manufacturers align production capabilities with distinct consumption occasions, from home preparation to commercial food service finishing.
Product Type:
Frozen formats command the deepest margin pools due to extended shelf stability and operational simplicity for food service operators. Refrigerated products capture premium positioning through freshness claims in natural grocery channels.
- Frozen:Pre-baked crusts formulated with hydrocolloid binders and blast-frozen for distribution through broadline food service networks. Demand concentrates with US fast-casual pizza chains standardizing on two approved suppliers to simplify training protocols and reduce cross-contamination liability exposure.
- Refrigerated:Fresh dough balls or pressed bases requiring cold-chain logistics and shorter rotation cycles. Demand clusters in premium natural grocery channels in California and the Pacific Northwest, where consumers prioritize freshness positioning over extended shelf life.
- Mixes:Dry ingredient blends requiring hydration and proofing by home bakers or restaurant kitchens with remaining gluten-free baking expertise.
- Ready-to-Bake:Par-baked shells requiring only topping application and final oven finish, bridging convenience and customization for mid-tier pizzerias.
Frozen holds installed capacity across dedicated production lines. Refrigerated is rotating up the share rankings through premium channel expansion.
Ingredient Source:
Cost structures diverge sharply based on agricultural sourcing geography and protein content targets. Almond flour carries the steepest raw material premium but commands pricing power through ketogenic and paleo diet positioning.
- Rice Flour:Milled from white or brown rice as the foundational gluten-free carbohydrate base, typically blended with starches for structural integrity. US retail volume concentrates in conventional grocery channels where price sensitivity dominates purchase decisions and supply chains source from Arkansas and California rice belts.
- Almond Flour:Blanched almond meal delivering protein density and lower glycemic indexes compared to starch-heavy alternatives. Demand is climbing the fastest among ketogenic and paleo diet followers in metropolitan health-conscious clusters, particularly Austin, Portland, and Denver.
- Corn Flour:Masa harina or fine cornmeal providing distinct flavor profiles and yellow coloration for regional pizza styles.
- Tapioca Starch:Extracted from cassava root as a texturizing agent and binding enhancer in multi-flour blends, subject to Asian agricultural output volatility.
Rice flour anchors baseline production economics. Almond flour is climbing the fastest tier in revenue contribution.
Distribution Channel:
Channel selection determines certification requirements and margin capture. Food service bypasses retail slotting fees but demands dedicated allergen-control documentation.
- Retail Stores:Conventional grocery placement requiring FDA gluten-free certification and competitive shelf positioning against private label alternatives.
- Online:Direct-to-consumer and marketplace platforms enabling subscription models and bulk purchasing for households with celiac disease.
- Food Service:Direct distribution to restaurants and chains with specialized frozen logistics, bypassing broadline distributors to capture margin from high-volume independent operators.
- Supermarkets:Natural and specialty grocery channels commanding dual-certified organic-gluten-free premiums.
Food service holds contracted volume commitments. Online is gaining share fastest through subscription retention models.
End User:
User type dictates formulation complexity and regulatory scrutiny intensity. Commercial operators face liability exposure that drives consolidation toward certified suppliers.
- Households:Home preparation ranging from scratch baking to finished crust finishing, with purchase decisions driven by certification trust and convenience positioning.
- Restaurants:Full-service establishments requiring consistent portion control and training simplicity for kitchen staff with variable gluten-free protocol familiarity.
- Cafes:Limited-service operators with constrained oven configurations favoring thin-crust formats that compensate for hydrocolloid texture limitations.
- Pizzerias:Dedicated pizza operations with the highest certification stakes, where FDA sub-20 ppm compliance and dedicated production line verification determine supplier selection.
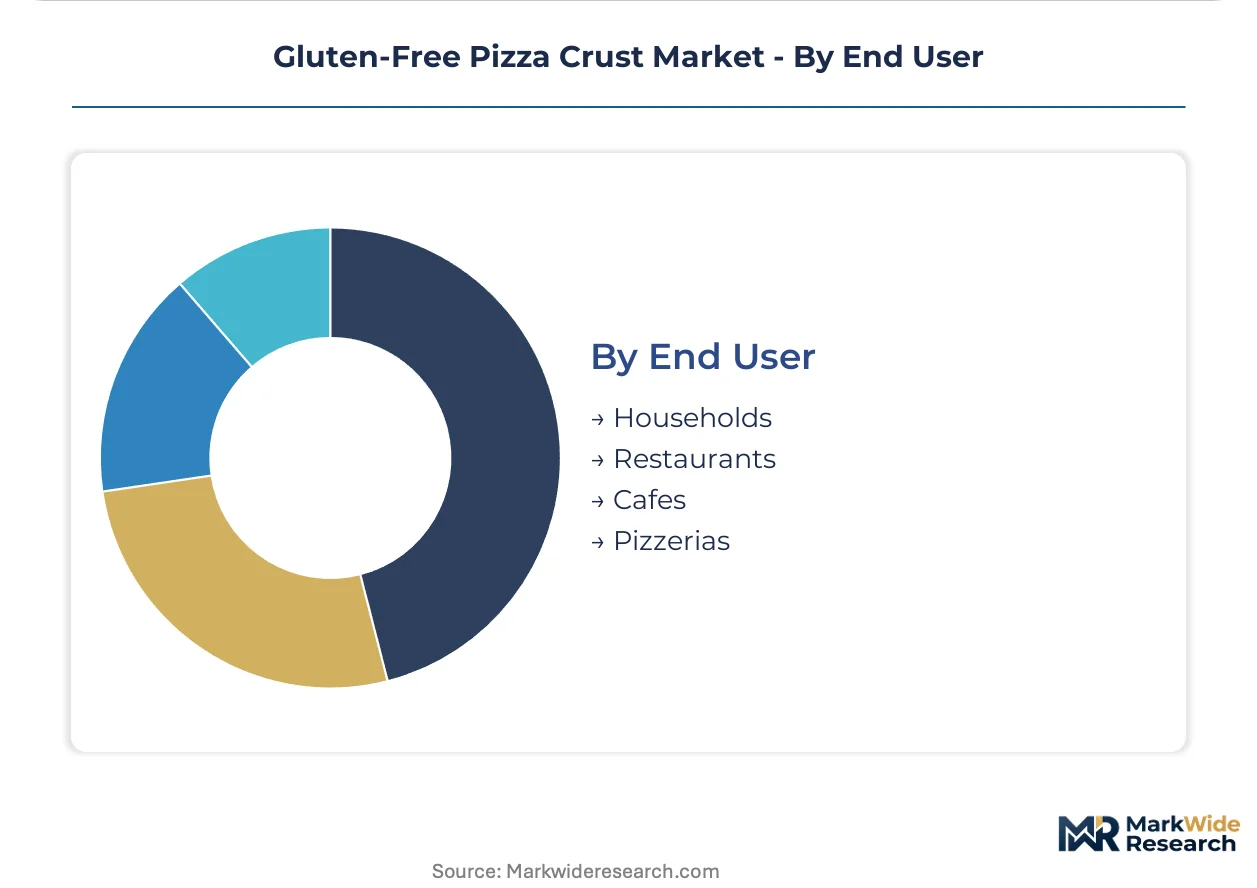
Pizzerias hold the most stringent supplier qualification requirements. Restaurants are rotating up the share rankings as fast-casual chains expand gluten-free menu penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States households favor frozen retail formats for home preparation, while European food service channels absorb pre-formulated crusts through centralized procurement. Asian markets remain nascent, with Japan and South Korea importing certified products rather than developing domestic milling infrastructure.
United States
FDA's sub-20 ppm labeling standard drives certified product penetration across fast-casual pizza chains. Celiac disease diagnostic rates climb through expanded physician screening protocols. Portland, Oregon and Austin, Texas host artisan pizzeria clusters adopting sourdough-fermented rice bases for frozen retail differentiation.
Italy
EFSA gluten thresholds align with domestic artisan traditions, preserving Dr. Schär AG's European milling dominance. Traditional wheat-growing regions in Emilia-Romagna now dedicate facility lines to certified gluten-free production. Turin-based suppliers export premium flour blends to North American manufacturers seeking provenance credibility.
Germany
REACH compliance requirements extend to hydrocolloid binder sourcing for industrial bakeries. Bavarian food technology institutes develop enzymatic texture modifiers for thin-crust applications. Munich's frozen food distributors consolidate multi-brand gluten-free portfolios under single-source logistics contracts.
Canada
Health Canada maintains parallel gluten-free standards below 20 ppm, facilitating cross-border supply chain integration with US manufacturers. Prairie province oat processors face tightened documentation for cross-contact prevention. Toronto's restaurant procurement teams standardize on two approved crust suppliers to reduce training complexity.
Australia
TGA oversight of gluten-free claims limits import penetration to certified manufacturers with third-party audit trails. Melbourne and Sydney natural grocery channels command dual-certified organic-gluten-free premiums. Domestic rice flour milling concentrates in New South Wales, reducing dependence on Asian agricultural volatility.
Gluten-Free Pizza Crust Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with European milling heritage separating premium positioning from commodity alternatives. The market structures around three archetypes: vertically integrated flour millers with captive supply chains, certified frozen food specialists with dedicated allergen-control facilities, and ingredient-forward brands commanding consumer trust through whole-grain transparency. Competitive moves concentrate on direct-to-restaurant distribution bypassing broadline distributors, and dual-certification pursuit of organic-gluten-free premiums to capture natural grocery placement.
Within the European milling tier, Dr. Schär AG / SPA anchors premium positioning through Italian supply relationships. Amy's Kitchen, Inc. exemplifies the certified production specialist archetype with segregated facility infrastructure. Bob's Red Mill Natural Foods, Inc. occupies the ingredient-forward positioning that controls whole-grain alternative narratives in North American retail.
| Leading Market Players |
|---|
| Kinnikinnick Foods Inc. |
| Capello's |
| Udi's Gluten Free |
| Amy's Kitchen, Inc. |
| Namaste Foods LLC |
| Dr. Schär AG / SPA |
| Bob's Red Mill Natural Foods, Inc. |
| Cali'flour Foods |
| Rich Products Corporation |
| Others |
Supply Flow & Price Mechanics
Sixty-day frozen inventory cycles across US broadline distributors compress working capital requirements while amplifying pricing power for certified manufacturers with dedicated allergen-control facilities. This lead-time band concentrates margin capture with pre-formulated crust specialists who have locked in multi-year almond flour offtake agreements, leaving smaller regional bakeries exposed to spot-market rice flour volatility.
Pricing Analysis
Long-term offtake contracts dominate volume procurement between fast-casual pizza chains and certified frozen crust manufacturers, insulating against tapioca starch spot-price swings. Three-tier pricing structure across premium, standard, and economy levels segments by certification tier—FDA sub-20 ppm compliance plus USDA Organic dual-certification commands shelf placement premiums in natural grocery channels. Cost compression in economy rice-flour tiers intensifies because Asian agricultural output fluctuations transmit directly to ingredient costs. Price-sensitive independent pizzerias in secondary US metropolitan areas gravitate toward standard-tier products, while least-sensitive health-conscious households in Portland and Austin absorb almond flour premiums for ketogenic positioning.
Supply Chain Analysis
Italy and the United States anchor premium gluten-free flour milling, with Dr. Schär AG's Turin-based operations supplying provenance-credentialed blends to North American manufacturers. Raw material flows draw from Arkansas rice belts, California almond orchards, and Southeast Asian cassava plantations for tapioca starch extraction. Single-source vulnerability clusters in European hydrocolloid binder production, where REACH compliance requirements constrain supplier switching. Distribution runs through specialized frozen logistics networks that bypass broadline distributors for direct-to-restaurant delivery, capturing margin from high-volume independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as fast-casual pizza chains consolidate gluten-free SKU procurement onto single-source contracts, fragmenting the vendor landscape and compressing margins for undifferentiated regional suppliers.
For Market Incumbents: Shield certified production line capacity through facility segregation investments that prevent cross-contamination liability exposure from emerging oat-flour entrants. Deepen backward integration into almond flour milling to control protein-density tier pricing against commodity rice-flour competitors. Prioritize dual-certification pursuit of USDA Organic plus FDA compliance to defend natural grocery shelf positioning. For New Entrants and Emerging Players: Anchor in sourdough-fermented rice base formulations that deliver blistered crust aesthetics unattainable through chemically leavened alternatives. Target underpenetrated independent pizzerias in secondary US metropolitan areas lacking certified gluten-free protocols. Pursue direct-to-restaurant distribution with specialized frozen logistics to bypass entrenched broadline relationships. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory compliance barriers compound faster than consumer demand fragmentation. Acquisition candidates should display segregated facility infrastructure with validated third-party audit trails for FDA sub-20 ppm standards. Monitor celiac disease diagnostic rate acceleration as the inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | USDA Organic plus FDA compliance unlocks premium placement in Whole Foods and Sprouts channels. |
| Direct-to-Restaurant Distribution | Bypassing Sysco and US Foods captures margin from high-volume independent pizzerias. |
| Almond Flour Backward Integration | In-house California orchard partnerships insulate against commodity starch price volatility. |
| Sourdough Fermentation Protocol Development | Living-culture methods differentiate frozen retail lines in Portland and Austin clusters. |
| Food Service Chain Standardization | Approved supplier status at Blaze Pizza and MOD Pizza locks in contracted volume commitments. |
Methodological Framework
The analysis maps frozen crust manufacturing, refrigerated fresh dough, and dry mix sub-sectors, each validated through interviews with plant managers at dedicated allergen-control facilities, procurement leads at fast-casual pizza chains, distribution channel partners in frozen logistics, and regulatory affairs specialists navigating FDA certification. Secondary sources include FDA gluten-free labeling guidance documents, USDA Organic certification databases, customs records for rice and almond flour trade flows, and SEC filings from publicly traded food manufacturers. Bottom-up capacity assessments triangulate against top-down consumption estimates across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks from retail audit data and food service procurement surveys. The analytical framework models segmentation across product format, ingredient source, distribution channel, and end-user type throughout the forecast period. CAGRs derive from regression analysis against celiac disease diagnostic trends, specialty diet adoption patterns, and food service chain expansion trajectories. Industry-specific inputs include hydrocolloid binder cost indices and almond flour protein premium spreads.
Decision-makers should treat outputs as directional under stable FDA enforcement and intact Asian agricultural supply assumptions; material deviation in tapioca starch trade flows or gluten-free oat processing guidance would warrant model refresh. Specific risk factors include REACH compliance tightening on hydrocolloid sourcing and cross-contact prevention documentation requirements for oat flour supply chains. Recalibration cycles align with material shifts in celiac screening protocols and fast-casual chain procurement consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Cookies Market
Bakery Products
On-The-Go Breakfast Products Market
Bakery Products
Pancake Mixes Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Bakery Fillings Market
Bakery Products
Bread Mix Market
Bakery Products
Gulf Cooperation Council Frozen Bakery Products Market
Bakery Products
Bread Crumbs Market
Bakery Products
Pancakes Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Toasted Flour Market
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Personalized Bakery Products Market
Bakery Products
Specialty Bakery Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
No-Fat Cake Market