
 Bakery Fillings Market | 2026-2036
Bakery Fillings Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Fillings Market Analytics
European fruit concentrate processors is broadening their output of clean-label bakery fillings to serve reformulation needs across Western Europe. Puratos Group leverages its Belgian R&D footprint to develop enzyme-stabilized fruit preparations with extended shelf stability. Corbion sustains competitive positioning through its fermentation-derived preservative systems that reduce synthetic additive dependence. Cargill anchors global supply with vertically controlled pectin and starch sourcing for industrial-scale filling production.
Bakery fillings are viscous or semi-solid preparations—typically comprising fruit purees, dairy creams, chocolate suspensions, or nut pastes bound by hydrocolloids, starches, or proteins—designed to provide flavor, moisture, and textural contrast in baked goods, with functional parameters including water activity below 0.85 for ambient stability and viscosity ranges of 5,000–50,000 cP for machine depositions. Fruit fillings lead volume due to their versatility across cakes and pastries, though chocolate fillings command premium positioning in artisanal and gift segments where cocoa content and tempering compatibility determine margin pools. Cream fillings represent the fastest-growing category as commercial bakeries adopt UHT-processed dairy and plant-based alternatives to reduce cold-chain dependency.
EFSA evaluates novel food enzymes and additive safety for fillings distributed in the European Union, while REACH governs residual chemical limits in flavoring substances and processing aids. FDA standards for acidified foods and GRAS determinations shape export compliance for fillings entering the United States. Stakeholders must monitor evolving clean-label certification requirements and dual-track reformulation investments that balance natural positioning with cost-controlled manufacturing scale.
Market Dynamics
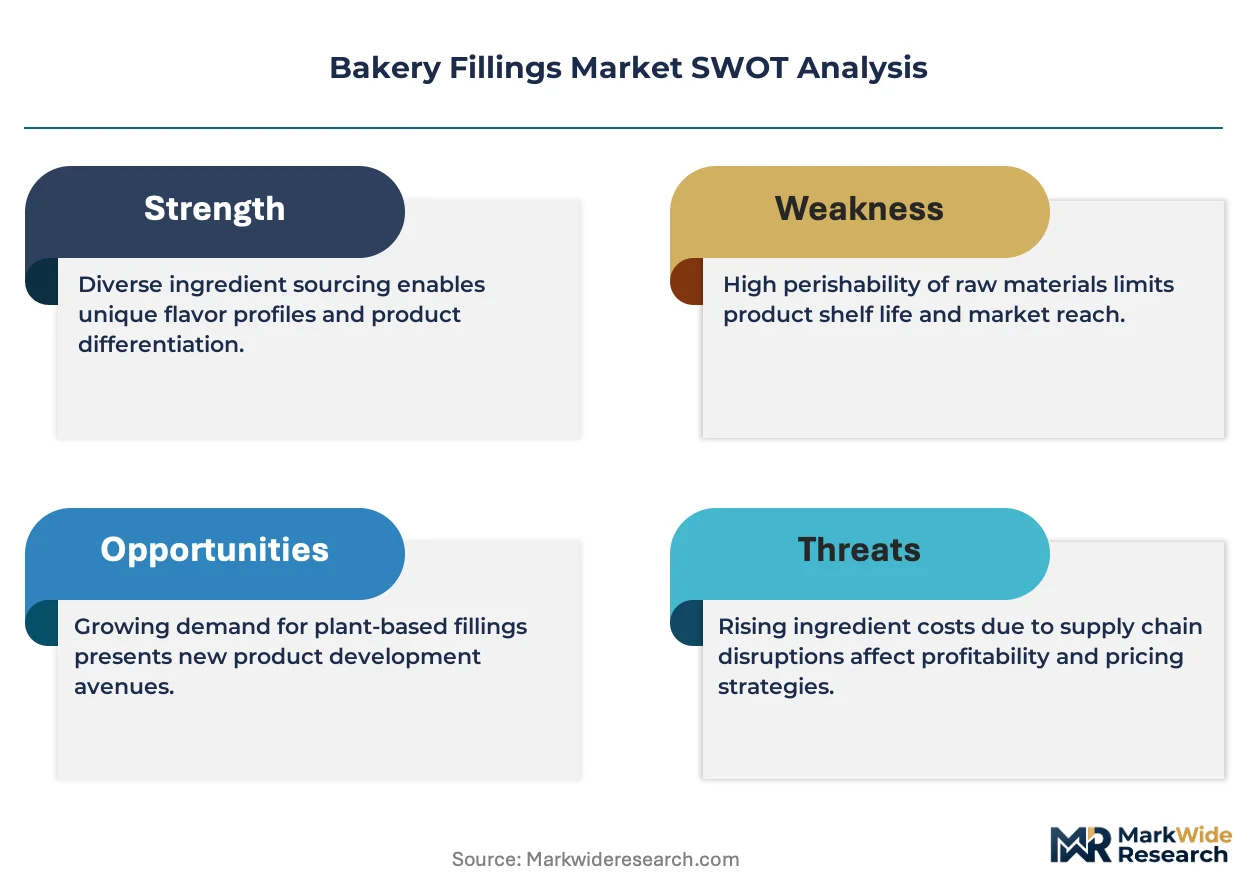
Clean-label reformulation pressure from EFSA and REACH is compressing synthetic additive use across European bakery filling supply chains, forcing producers to rebuild stabilizer systems around pectin, starch, and fermentation-derived alternatives.
Growth Catalysts
- EFSA Additive Restrictions:Tightening safety evaluations for synthetic colorants and preservatives are accelerating natural stabilizer adoption in fruit and cream fillings distributed across EU member states.
- UHT Processing Technology:Extended shelf-life dairy and plant-based cream formulations are reducing cold-chain dependency for commercial bakeries in Germany and France.
- Munich-Hamburg Industrial Cluster:Concentrated demand from automated production facilities is standardizing paste and gel filling formats for high-volume cake and pastry manufacturing.
Market Restraints
- Citrus Pectin Supply Volatility:Weather-dependent harvests in Spain and Mexico create input cost instability for fruit gel formulations.
- Clean-Label Cost Premium:Natural stabilizers and enzyme-based preservation add 15-25% to formulation costs versus synthetic alternatives.
- REACH Compliance Burden:Registration and residual chemical testing requirements for flavoring substances extend product development timelines by 8-14 months.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated industrial bakery sectors present volume expansion potential for standardized filling formats.
- Plant-Based Cream Convergence:Oat and fava bean protein emulsions combined with UHT technology are opening premium positioning in vegan pastry segments.
- EU Green Deal Procurement:Public sector and institutional bakery contracts with sustainability mandates favor low-carbon footprint filling suppliers.
Industry Challenges
- Enzyme Stabilization Expertise Gap:Shortage of food technologists trained in protein-hydrocolloid interactions slows clean-label reformulation at mid-size producers.
- Legacy Equipment Retrofit Costs:Depositor and filling line upgrades required for higher-viscosity natural formulations strain capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Fillings Market |
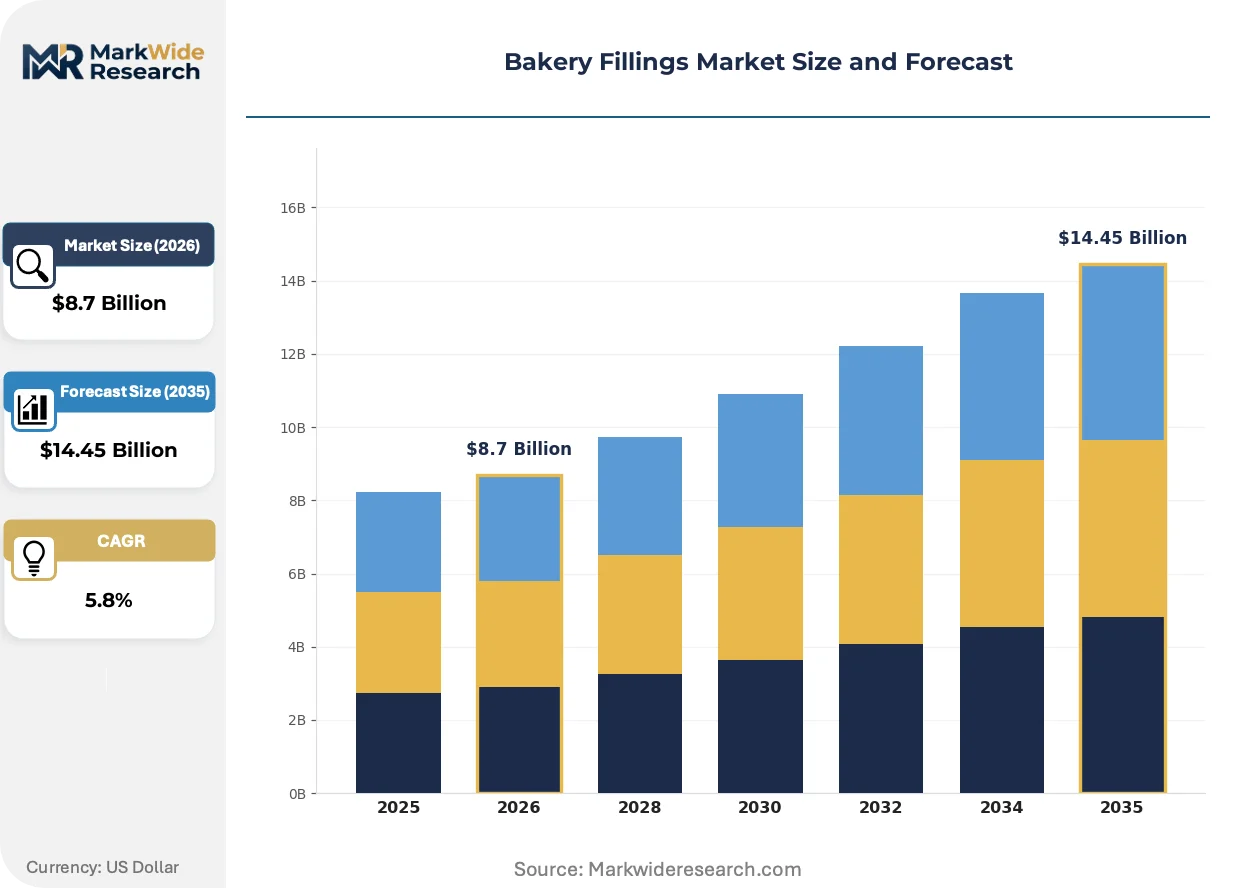
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream Fillings, Fruit Fillings, Chocolate Fillings, Nut Fillings Application: Cakes, Pastries, Bread, Cookies End User: Commercial Bakeries, Retail Bakeries, Food Service, Home Bakers Form: Liquid, Paste, Powder, Gel |
| Companies Covered | Ingredion, DSM, Puratos Group, DuPont de Nemours, Corbion, Cargill, Tate & Lyle, Novozymes, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Fillings Market Evolving Landscape
Enzymatic stabilization and fermentation-derived preservation systems are displacing synthetic hydrocolloids across European bakery filling production, while regulatory timelines compress and buyer procurement criteria harden around clean-label certification.
High-pressure processing (HPP) is integrating into fruit filling manufacturing to achieve ambient stability without thermal degradation of flavor compounds. Artisanal and premium commercial bakeries in Belgium and the Netherlands are adopting HPP-treated purees for layered cake applications. This technology is integrating extended shelf-life assurance with cleaner ingredient declarations, compressing the traditional trade-off between preservation and label simplicity.
REACH authorization requirements for residual chemical limits in flavoring substances are tightening traceability obligations across filling supply chains. Industrial producers must now document processing aid residues from raw material through finished product. Small-to-mid-size filling manufacturers in Southern Europe face disproportionate compliance costs, accelerating consolidation toward vertically integrated compounders with in-house analytical capabilities.
Direct sourcing contracts between industrial bakeries and fruit concentrate processors are shortening traditional distribution tiers. Large German and French bakery groups now specify cultivar, harvest timing, and processing method in procurement agreements. This pattern is most visible in the Schwarzwald cake and tart segments, where origin-linked fruit specifications command shelf price premiums and lock in supplier relationships across multi-year frameworks.
Bakery Fillings Market Segmentation
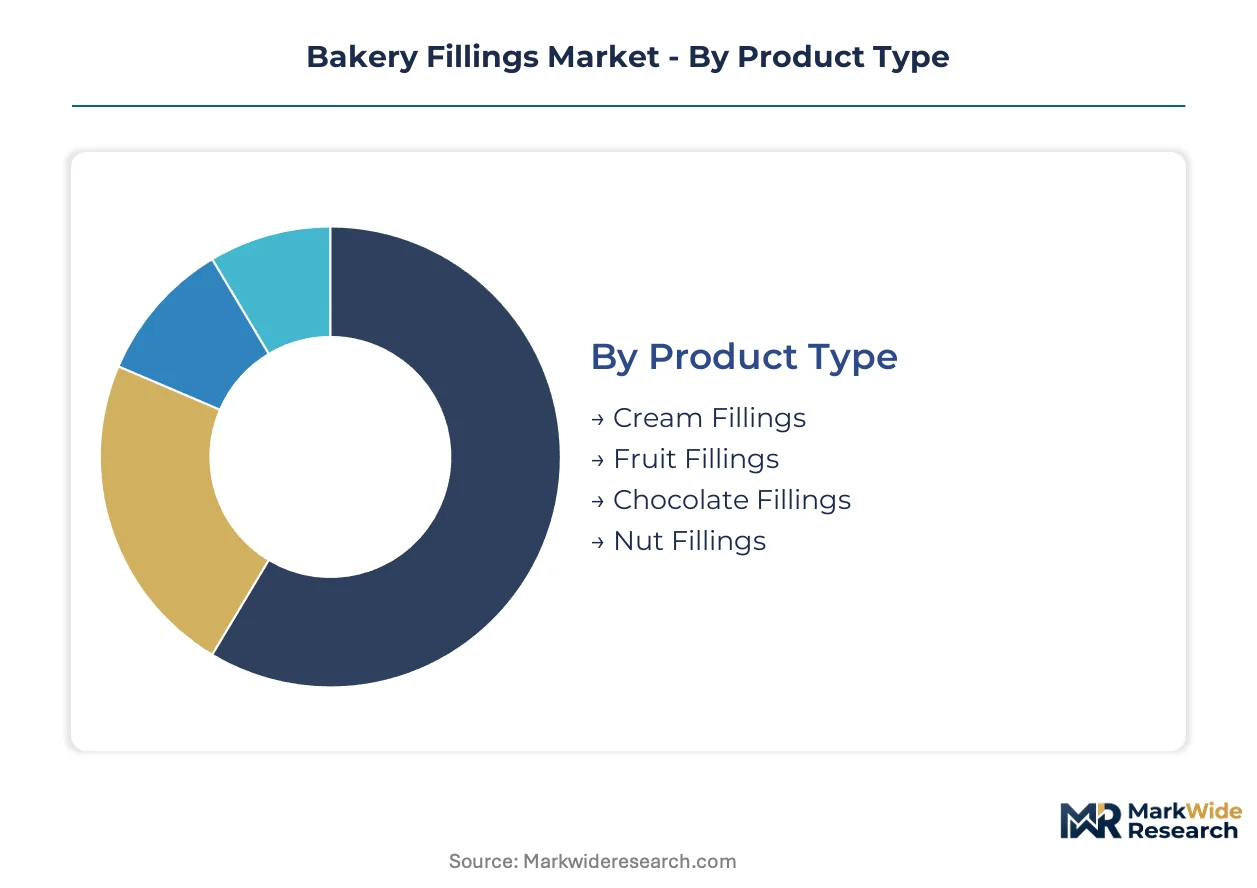
Bakery filling manufacturers configure production assets around viscosity specifications and deposition compatibility. Segment boundaries determine stabilizer selection, shelf-life engineering, and the regulatory pathways each formulation must navigate.
Product Type:
Supply concentration in pectin and starch sourcing shapes competitive positioning across filling categories, with vertical integration into hydrocolloid production determining margin capture.
- Fruit Fillings:Pectin-gelled fruit purees with water activity below 0.85 for ambient stability. Demand concentrates in Germany's industrial bakery clusters around Munich and Hamburg, where standardized paste formats serve high-volume cake manufacturing. EFSA additive restrictions are accelerating natural stabilizer adoption.
- Cream Fillings:UHT-processed dairy or plant-based emulsions bound by modified starch or protein hydrocolloids. France and Belgium lead adoption as commercial bakeries reduce cold-chain dependency. Oat and fava bean protein variants are climbing the fastest in vegan pastry segments.
- Chocolate Fillings:Cocoa butter suspensions requiring tempering compatibility and precise viscosity control for machine deposition.
- Nut Fillings:Ground paste preparations from almond, hazelnut, or peanut bases, common in artisanal and premium gift segments.
Today's leader: Fruit Fillings. Tomorrow's challenger: Cream Fillings.
Application:
End-use specifications drive divergent formulation priorities across baked goods categories, with cake and pastry applications commanding premium stabilizer investments.
- Cakes:Layered applications demand fillings with thermal stability during baking and clean sliceability. Schwarzwald cake producers in Germany specify origin-linked fruit cultivars, locking suppliers into multi-year procurement frameworks with cultivar and harvest timing requirements.
- Pastries:Laminated dough compatibility requires fillings that resist moisture migration and maintain viscosity through freeze-thaw cycles. Belgian and Dutch artisanal bakeries are adopting HPP-treated fruit purees for premium layered applications.
- Bread:Swirl and injection applications favor lower-viscosity pastes that distribute evenly without compromising crumb structure.
- Cookies:Sandwich and filled varieties require shelf-stable preparations with minimal water activity to preserve texture integrity.
Cakes command the deepest supplier relationships. Pastries offer the steepest technology upgrade trajectory.
End User:
Customer scale determines formulation standardization versus customization trade-offs, with procurement power concentrated in automated production facilities.
- Commercial Bakeries:Automated depositor lines require viscosity-standardized fillings in bulk formats. Industrial clusters in Germany and France drive volume for paste and gel preparations with documented processing aid traceability for REACH compliance.
- Retail Bakeries:Smaller-batch operations favor flexible packaging and shorter lead times over long-term procurement contracts.
- Food Service:Institutional bakery contracts with EU Green Deal sustainability mandates favor low-carbon footprint suppliers.
- Home Bakers:Consumer-packaged formats prioritize convenience and extended refrigerated shelf life.
Commercial bakeries anchor current volume. Food service procurement criteria are shifting fastest.
Form:
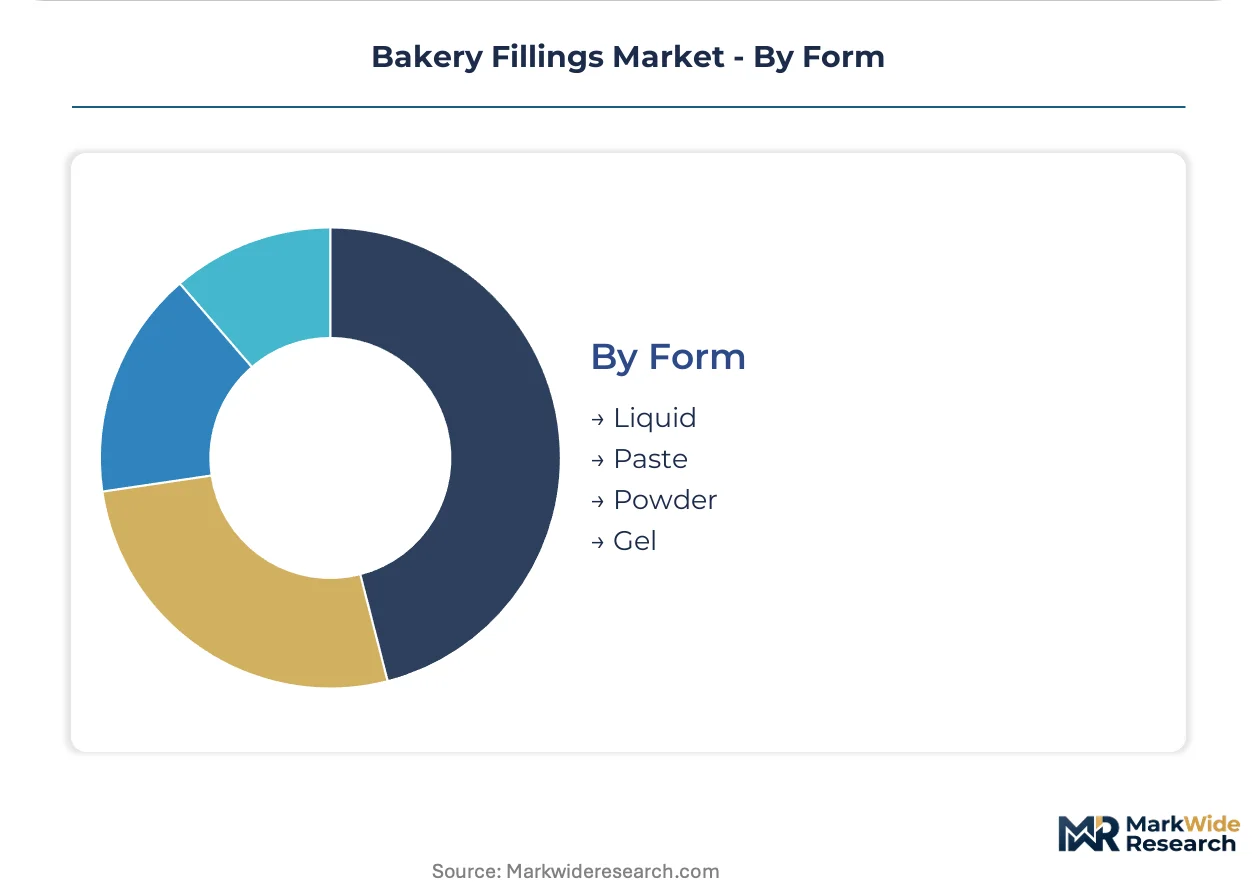
Physical state determines equipment compatibility and preservation technology requirements, with paste and gel formats dominating industrial scale production.
- Paste:Semi-solid preparations with viscosity ranges of 5,000–50,000 cP optimized for machine deposition. Standardized formats serve Germany's automated cake and pastry manufacturing lines.
- Gel:Pectin or starch-set preparations providing structural integrity in layered applications. Spain and Mexico citrus harvest volatility creates input cost instability.
- Liquid:Pumpable emulsions for injection and swirl applications in bread manufacturing.
- Powder:Dehydrated preparations requiring reconstitution, common in food service and export markets where reduced weight lowers logistics costs.
Paste dominates industrial throughput. Gel carries the highest reformulation risk from clean-label transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as clean-label compliance costs diverge across jurisdictions, pushing reformulation investment toward markets with established natural ingredient supply chains and predictable enforcement frameworks.
Germany
Industrial bakery clusters around Munich and Hamburg drive standardized paste and gel filling demand for automated cake manufacturing lines. EFSA additive restrictions and REACH residual chemical testing compress development timelines, favoring compounders with in-house analytical capabilities. Bavarian filling producers leverage proximity to fruit concentrate processors to lock in multi-year procurement frameworks with cultivar specifications.
France
UHT-processed cream fillings gain traction as commercial bakeries reduce cold-chain dependency, with Paris basin manufacturers leading plant-based emulsion adoption. ANSM and DGCCRF enforcement of EU food additive regulations accelerates natural stabilizer transitions. Auvergne-Rhône-Alpes hosts fermentation-derived preservative specialists serving reformulation needs across Western European markets.
Belgium
Artisanal and premium commercial bakeries in Flanders and Wallonia adopt HPP-treated fruit purees for layered cake applications, compressing preservation-label trade-offs. Federal Food Agency oversight of novel processing technologies shapes equipment investment patterns. Brussels corridor R&D facilities develop enzyme-stabilized preparations with extended shelf stability for export markets.
Netherlands
Rotterdam port logistics anchor pectin and starch import flows for industrial-scale filling production serving German and French bakery groups. NVWA enforcement of REACH traceability obligations drives documentation system upgrades across mid-size compounders. Gelderland processing plants specialize in high-viscosity natural formulations for automated depositor lines.
Poland
Underpenetrated industrial bakery sectors present volume expansion potential for standardized filling formats as Warsaw and Łódź manufacturing bases modernize. Polish Chief Sanitary Inspectorate alignment with EU additive regulations reduces regulatory friction for Western European suppliers. Silesian production corridors attract contract manufacturing investment from German bakery groups seeking cost-controlled capacity.
Bakery Fillings Market Competitive Landscape
European producers anchor the clean-label reformulation tier; North American ingredient specialists hold scale advantages in hydrocolloid supply. Market structure tilts toward consolidation as REACH compliance burdens and enzyme stabilization expertise gaps squeeze mid-size compounders. Three archetypes dominate: vertically integrated hydrocolloid suppliers, fermentation-derived preservation specialists, and R&D-forward European compounders. Competitive intensity centers on backward integration into pectin sourcing and strategic partnerships with industrial bakery groups for multi-year procurement frameworks.
Among the fermentation-derived preservation tier, DSM and Corbion exemplify positioning around enzyme-based shelf-life extension systems. Puratos Group occupies a central role within European R&D-forward compounders, leveraging Belgian technical facilities to anchor clean-label formulation development. Cargill represents the vertically integrated archetype through captive starch and pectin supply chains serving industrial-scale production requirements.
| Leading Market Players |
|---|
| Ingredion |
| DSM |
| Puratos Group |
| DuPont de Nemours |
| Corbion |
| Cargill |
| Tate & Lyle |
| Novozymes |
| Archer Daniels Midland |
| Others |
Value Network & Pricing Analysis
Citrus pectin and modified starch costs cascade through bakery filling pricing tiers, with Spanish and Mexican harvest volatility feeding premium volatility for gel-based formulations while standardized paste formats absorb cost compression through volume contracting with German industrial bakeries.
Pricing Analysis
Distributor margins compress as direct sourcing contracts between fruit concentrate processors and industrial bakery groups disintermediate traditional tiers. Three-tier pricing structure across premium, standard, and economy levels separates HPP-treated artisanal purees from UHT-processed cream emulsions and commodity fruit pastes. Price differentiation rests on clean-label certification intensity and cultivar traceability documentation. Pricing pressure stems from REACH compliance testing costs that compound natural stabilizer premiums. Commercial bakeries in Munich-Hamburg clusters exhibit lowest price sensitivity due to procurement scale, while Polish mid-size manufacturers face acute margin compression.
Supply Chain Analysis
Workforce availability constraints in Belgian R&D corridors and Dutch Gelderland processing plants limit enzyme stabilization expertise expansion, forcing technology transfer delays for clean-label reformulation. Supply concentrates in Spain and Mexico for citrus pectin, Germany and France for UHT cream processing, and Belgium for fermentation-derived preservation systems. Raw material dependencies span citrus peel for pectin, dairy and oat protein for cream emulsions, and cocoa butter for chocolate suspensions. Single-source vulnerability runs through Spanish citrus harvests exposed to drought cycles. Distribution runs through Rotterdam port logistics anchoring hydrocolloid import flows for German and French bakery manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bakery fillings represent a late-cycle quality story as procurement criteria harden around EFSA-compliant clean-label specifications, with industrial bakeries paying sustained premiums for documented additive-free formulations.
For Market Incumbents: Lock in multi-year procurement frameworks with Munich-Hamburg industrial clusters before mid-size Polish bakeries modernize capacity. Deepen backward integration into pectin sourcing to offset Spanish citrus volatility. Prioritize enzyme stabilization R&D investment to close expertise gaps that slow reformulation timelines for REACH-compliant product lines. For New Entrants and Emerging Players: Launch via contract manufacturing partnerships with Silesian production corridors serving German bakery groups seeking cost-controlled capacity. Target Poland and Czech Republic industrial bakery modernization waves with standardized paste formats. Exploit fermentation-derived preservation white space as synthetic additive restrictions tighten across EU member states. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance burdens and analytical capability gaps squeeze mid-size Southern European compounders. Five-to-ten year viability favors vertically integrated hydrocolloid suppliers with captive pectin supply and in-house enzyme stabilization expertise. Watch for inflection when EFSA publishes revised additive safety evaluations that accelerate synthetic hydrocolloid displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pectin Sourcing | Captive citrus peel supply from Spanish processors insulates margin from harvest volatility. |
| Enzyme Stabilization R&D Partnership | Belgian technical facilities anchor clean-label shelf-life extension for EFSA-compliant formulations. |
| UHT Processing Capacity Expansion | Auvergne-Rhône-Alpes fermentation specialists serve French cream filling cold-chain reduction demand. |
| HPP Technology Equipment Investment | Flanders artisanal bakeries adopt high-pressure processing for premium layered cake applications. |
| Direct Sourcing Contract Structuring | German Schwarzwald cake producers lock cultivar specifications into multi-year procurement frameworks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with bakery R&D directors, industrial procurement managers at German and French manufacturing clusters, fruit concentrate processor operations heads, and hydrocolloid supply chain planners with secondary validation against EFSA additive safety evaluations, REACH authorization databases, EU trade statistics for pectin and starch imports, and customs records for citrus peel processing volumes. Bottom-up filling production estimates triangulated against top-down bakery sector consumption models.
Segment-weighting approaches distributed value and volume across product type dimensions including fruit, cream, chocolate, and nut fillings; application categories spanning cakes, pastries, bread, and cookies; end-user tiers from commercial bakeries through food service; and form factors distinguishing paste, gel, liquid, and powder preparations. CAGRs derived from regression analysis against bakery production indices and clean-label certification penetration curves. Forecast inputs incorporated EFSA regulatory timeline assumptions and UHT processing technology adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA additive ban acceleration or Spanish citrus harvest collapse scenarios. Projections reflect assumptions about regulatory enforcement consistency and natural stabilizer cost convergence timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Aerating Cake Emulsifier Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Organic Bread Flour Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Bakery Premixes Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Biscuits Market
Bakery Products
Ice Cream Cones Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
Pancakes Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Soft Biscuit Market
Bakery Products
Batter and Breader Premixes Market
Bakery Products
Frozen Bakery Market