
 Germany Food Flavor and Enhancer Market | 2026-2036
Germany Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Food Flavor and Enhancer Market Foresight
The EU Green Deal's Farm to Fork strategy is hardening sustainability requirements across German food manufacturing. Givaudan leverages its biotechnology platform to develop fermentation-derived natural flavors for clean-label applications. Symrise AG anchors its position through deep backward integration into botanical sourcing and extraction capabilities. Döhler GmbH specializes in fruit and vegetable-based flavor systems that align with reformulation mandates from major German retail chains.
Food flavor and enhancer systems comprise aromatic compounds, taste modulators, and savory precursors engineered at parts-per-million precision to deliver consistent sensory profiles in processed foods. These formulations undergo gas chromatography-mass spectrometry analysis and stability testing under thermal and pH stress to ensure performance across manufacturing conditions. Natural flavors command premium positioning as beverage manufacturers reformulate away from artificial additives, while spray-dried powder forms capture growing share in snack seasoning applications where extended shelf stability proves critical. Flavor enhancers, particularly yeast extract and ribonucleotide blends, concentrate margin pools in culinary preparations and savory dairy segments where sodium reduction drives technical substitution.
BfR (German Federal Institute for Risk Assessment) evaluates flavor substance safety through systematic toxicological assessment, while EU REACH and EFSA frameworks govern novel ingredient authorization and labeling thresholds. The EU F-Gas Regulation indirectly shapes extraction solvent availability for natural flavor production, pushing investment toward supercritical CO2 and aqueous methods. Stakeholders must monitor BfR's evolving stance on natural flavor complexity and botanical extract standardization as these determinations will gate market access for next-generation clean-label formulations.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is hardening sustainability requirements across German food manufacturing, forcing flavor houses to rebuild supply chains around bio-based extraction and fermentation-derived aromatic compounds.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon solvents is redirecting capital toward supercritical CO2 extraction infrastructure for natural flavor production, expanding domestic processing capacity.
- Bakery and confectionery reformulation:Clean-label mandates from major German retail chains are pulling demand for botanical-derived vanilla and citrus flavor systems.
- Bavaria's food processing corridor:Concentrated procurement from meat and dairy processors in Lower Bavaria and Upper Palatinate creates scale economies for savory flavor enhancer deployment.
Market Restraints
- Raw material volatility:Weather-driven supply fluctuations for vanilla beans from Madagascar and citrus oils from Mediterranean growing regions compress margin predictability for natural flavor portfolios.
- BfR toxicological assessment timelines:Novel botanical extract approvals face extended evaluation periods, gating speed-to-market for innovation pipelines.
- Yeast extract supply concentration:Production of savory flavor precursors clusters among limited Central European fermentation facilities, creating bottleneck risk.
Strategic Opportunities
- Baden-Württemberg organic food cluster:Premium organic confectionery and beverage producers in Stuttgart and Freiburg represent underpenetrated demand for certified organic flavor systems.
- Precision fermentation convergence:Integration of synthetic biology with traditional extraction is opening routes to rare aromatic molecules previously unavailable at commercial scale.
- German Packaging Act amendments:Extended producer responsibility incentives are accelerating demand for water-based flavor carriers that eliminate solvent residues and simplify recycling compliance.
Industry Challenges
- Flavor chemist talent scarcity:Specialized expertise in gas chromatography-olfactometry and stability modeling is concentrating among retiring professionals without sufficient pipeline replacement.
- Legacy ERP integration:Mid-tier flavor houses face friction connecting batch-level traceability systems to customer EDI networks for real-time allergen documentation.
- Clean-label certification complexity:Navigating simultaneous EU organic, Naturland, and private retail standard audits extends product launch timelines by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Food Flavor and Enhancer Market |
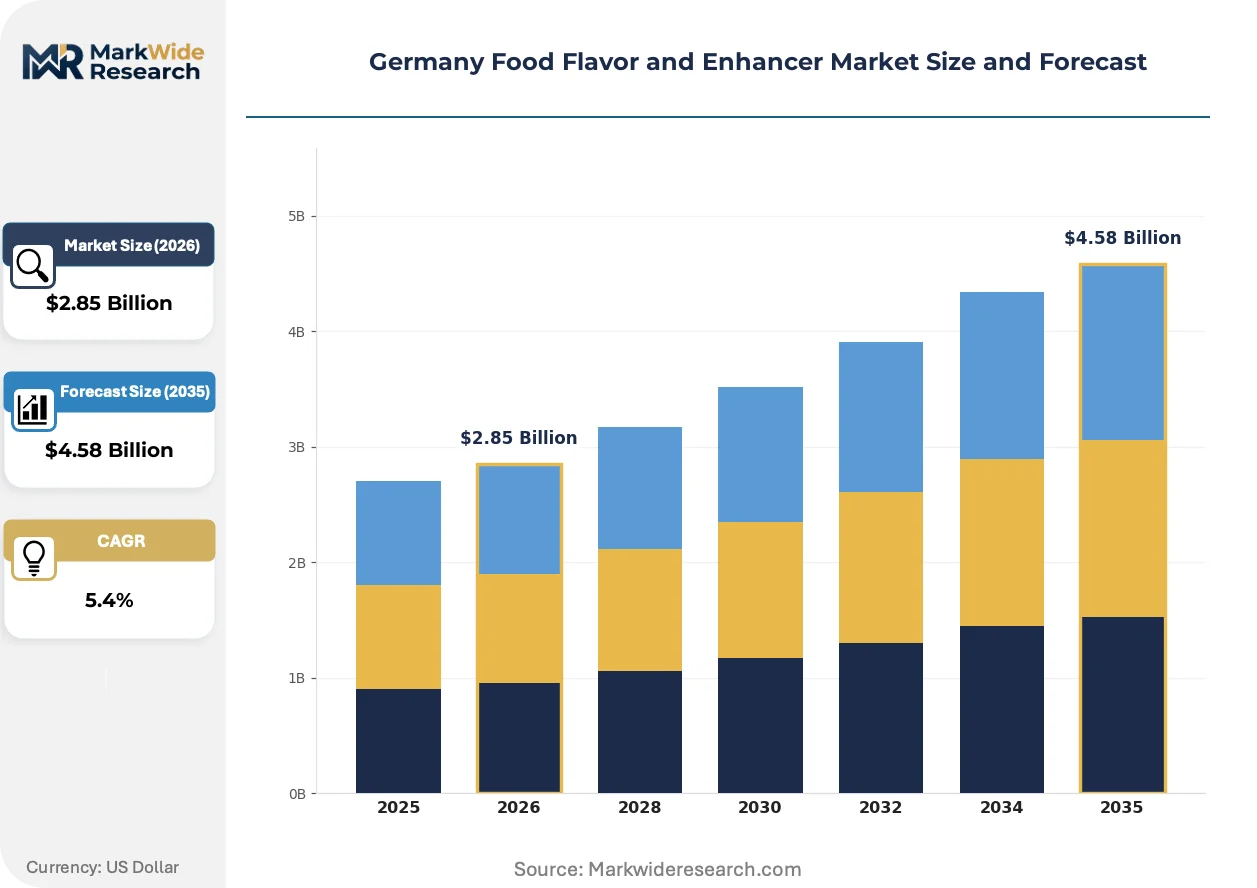
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.58 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Nature-Identical Flavors, Flavor Enhancers, Acidulants Form: Liquid, Powder, Emulsions, Gel, Spray-Dried Powder Application: Bakery & Confectionery, Beverage Manufacturing, Dairy Product Processing, Snack Foods, Culinary Preparations End User: Food Processing Units, Flavoring Companies, Culinary Experts, Beverage Producers |
| Companies Covered | Givaudan, Firmenich, Kerry Group, International Flavors and Fragrances Inc., Symrise AG, Archer Daniels Midland Company, Takasago International Corporation, Flavorchem Corp., Döhler GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Food Flavor and Enhancer Market Shifts & Advancements
Biotechnology platforms and extraction method innovation are compressing the cost gap between natural and synthetic flavor systems, while regulatory chemistry is redefining permissible formulation boundaries.
Precision fermentation is integrating into industrial flavor production as Givaudan and specialized biotech firms deploy engineered yeast strains to biosynthesize vanillin and other high-value aromatics. Mid-sized German beverage manufacturers are adopting these bio-identical natural flavors at accelerating pace to meet clean-label commitments without sacrificing cost position. The technology is integrating upstream into captive supply chains, reducing dependency on tropical agricultural sourcing and compressing working capital requirements for volatile raw materials.
EU REACH authorization requirements for novel flavor substances are tightening substance evaluation protocols, extending pre-market data packages and toxicological study burdens. The industrial consequence is a bifurcation between established GRAS-listed materials and higher barriers for innovative botanical extracts seeking market entry. Savory flavor enhancers face particular scrutiny as EFSA re-evaluates ribonucleotide exposure assessments, prompting reformulation activity in German ready-meal and soup manufacturing.
Direct procurement relationships between flavor houses and German retail private-label programs are displacing traditional distribution through regional ingredient brokers. Discounters Aldi and Lidl now specify flavor systems at corporate level, consolidating specification authority and compressing supplier bases to audited direct partners. This concentration is most visible in North Rhine-Westphalia, where Düsseldorf and Cologne headquarters operations centralize technical buying for national store networks.
Germany Food Flavor and Enhancer Market Segmentation
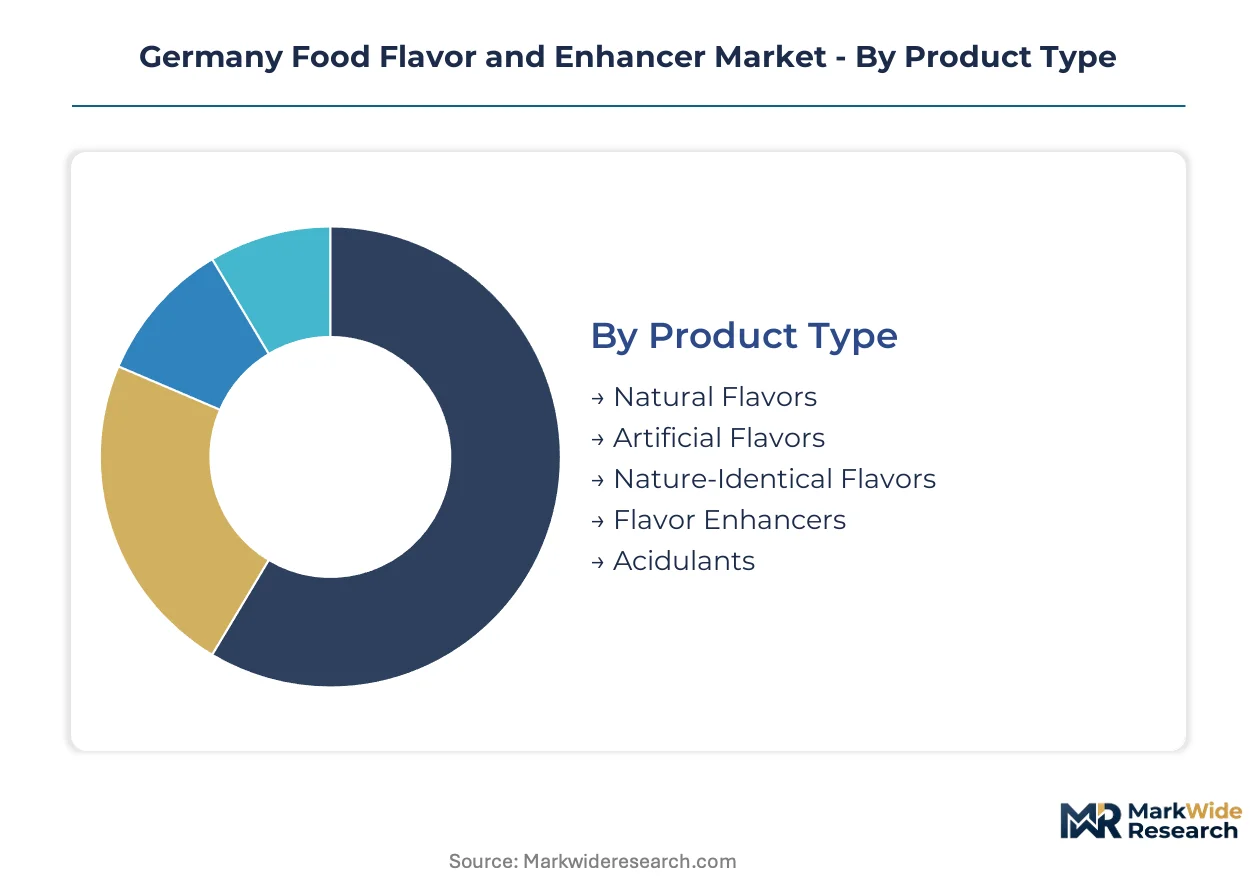
Flavor and enhancer procurement patterns diverge sharply across product chemistry, physical form, and downstream application. Understanding these segment boundaries clarifies where formulation investments concentrate and which technical specifications gate market access.
Product Type:
Supply concentration varies dramatically by extraction source and regulatory classification, with natural-derived portfolios requiring fundamentally different sourcing infrastructure than synthetic alternatives.
- Natural Flavors:Botanical extracts and fermentation-derived aromatic compounds face constrained feedstock availability from Madagascar vanilla and Mediterranean citrus. Bavarian meat processors and Baden-Württemberg organic beverage manufacturers pull disproportionate volume as clean-label mandates harden.
- Flavor Enhancers:Yeast extract and ribonucleotide blends concentrate production among Central European fermentation facilities. Sodium reduction requirements in German ready-meal manufacturing are accelerating technical substitution toward these savory precursors.
- Artificial Flavors:Petrochemical-derived aromatic molecules maintain cost advantages in mass-market confectionery.
- Nature-Identical Flavors:Chemically synthesized but structurally identical to natural counterparts, bridging cost and label positioning.
- Acidulants:pH-modulating compounds supporting flavor brightness and microbial stability in beverage systems.
Natural Flavors absorbs the bulk of installed capacity; Flavor Enhancers is expanding most quickly.
Form:
Physical state selection hinges on manufacturing integration requirements, with thermal stability and dosing precision driving specification divergence across German processing facilities.
- Liquid:Solvent-based or aqueous solutions enabling precise metering in continuous beverage production lines. North Rhine-Westphalia dairy processors favor liquid systems for homogeneous distribution in flavored milk applications.
- Spray-Dried Powder:Encapsulated aromatic matrices delivering extended shelf stability through moisture protection. Snack seasoning manufacturers in Lower Bavaria specify these forms for dry-mix compatibility and storage resilience.
- Powder:Free-flowing granules for dry blending in bakery premixes and confectionery compounds.
- Emulsions:Oil-in-water dispersions stabilizing lipophilic flavors in aqueous beverage matrices.
- Gel:Viscous concentrates for controlled-release applications in confectionery centers.
Liquid captures the dominant share of current formulation demand; Spray-Dried Powder is climbing the fastest as savory snack production scales.
Application:
End-use intensity correlates with reformulation pressure intensity, with retail-facing categories facing steeper clean-label requirements than foodservice or industrial channels.
- Beverage Manufacturing:Flavor systems must survive pasteurization thermal stress and acidic pH environments. German mineral water and fruit juice bottlers in the Rhineland are specifying natural citrus and botanical extracts to meet Aldi and Lidl corporate sourcing mandates.
- Bakery & Confectionery:Aromatic stability through Maillard reaction temperatures defines technical performance. Stuttgart-area organic confectionery producers are driving certified organic flavor system penetration.
- Dairy Product Processing:Flavor integration into fermented matrices and heat-treated milk products.
- Snack Foods:Powder seasoning adherence and fat-phase flavor distribution in extruded and fried products.
- Culinary Preparations:Ready-meal and soup applications where sodium reduction intensifies enhancer demand.
Beverage Manufacturing commands the largest formulation volume; Bakery & Confectionery is gaining share fastest on organic certification expansion.
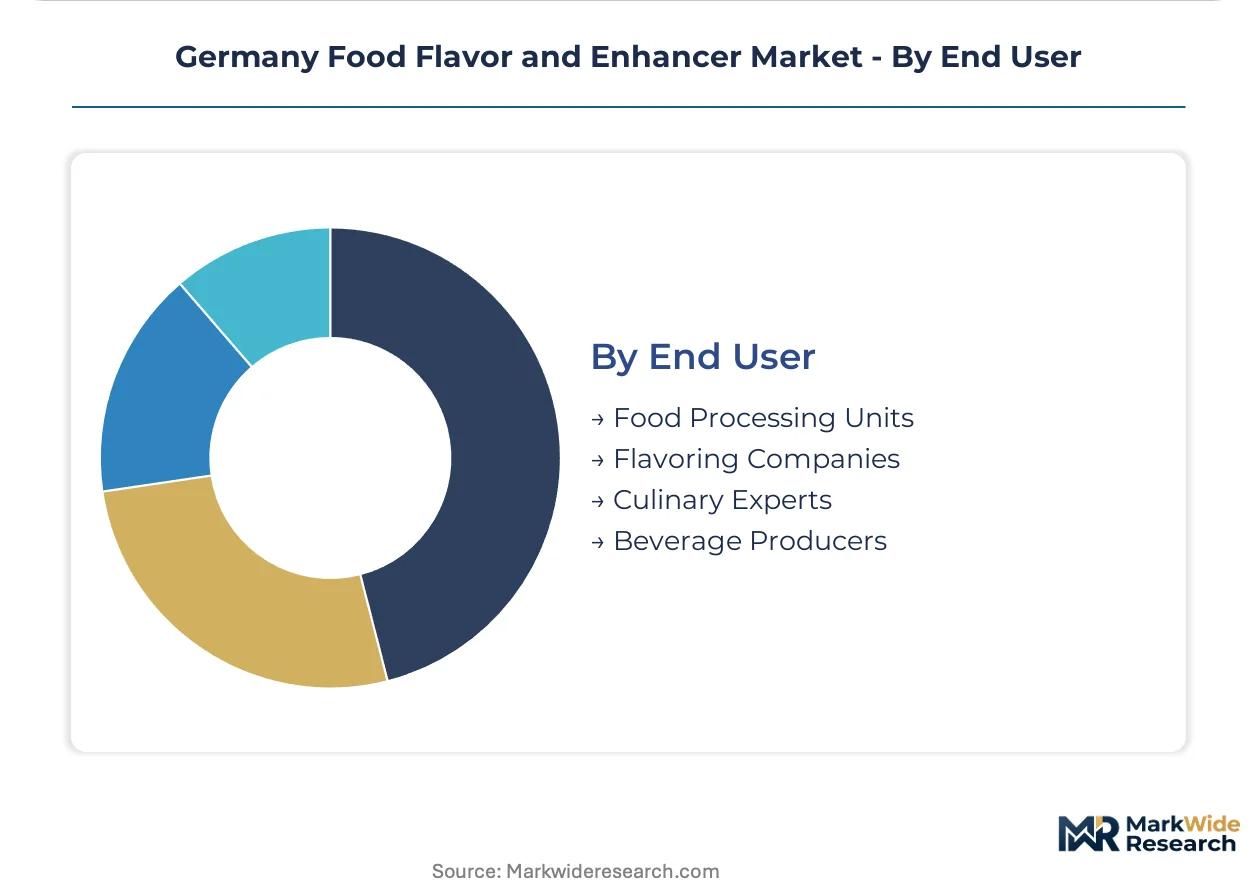
End User:
Procurement authority is consolidating toward direct technical relationships, displacing traditional broker intermediation across German food manufacturing.
- Food Processing Units:Integrated meat, dairy, and baked goods manufacturers with captive flavor specification authority. Lower Bavarian meat processors concentrate procurement for savory enhancer systems at regional scale.
- Beverage Producers:Mineral water, soft drink, and juice bottlers with corporate-level technical buying. Düsseldorf and Cologne headquarters operations centralize flavor system selection for national retail distribution.
- Flavoring Companies:Compound flavor houses blending base materials for downstream food manufacturers.
- Culinary Experts:Foodservice and prepared meal developers specifying small-batch custom formulations.
Food Processing Units represent the deepest volume concentration; Beverage Producers are expanding specification authority most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's food processing corridor anchors procurement concentration for flavor enhancement systems across Germany, with Lower Bavaria and Upper Palatinate driving savory enhancer demand from meat and dairy processors.
Bavaria
Lower Bavarian meat processors and Upper Palatinate dairy facilities pull disproportionate volume for yeast extract and ribonucleotide blends. The EU F-Gas Regulation redirects extraction capital toward supercritical CO2 infrastructure in this corridor. Munich anchors technical specification authority for corporate procurement networks.
North Rhine-Westphalia
Düsseldorf and Cologne headquarters operations centralize flavor system selection for Aldi and Lidl national store networks. BfR toxicological assessments govern novel botanical extract approvals sought by regional beverage bottlers. Rhineland mineral water and juice producers specify natural citrus extracts under retail clean-label mandates.
Baden-Württemberg
Stuttgart-area organic confectionery producers and Freiburg beverage manufacturers drive certified organic flavor system penetration. EU REACH authorization requirements tighten substance evaluation protocols for innovative botanical extracts. The state's organic food cluster represents underpenetrated demand for premium natural flavor portfolios.
Hesse
Frankfurt's logistics infrastructure supports distribution consolidation for spray-dried powder forms into snack seasoning channels. Germany's national packaging regulations accelerate water-based flavor carrier adoption to simplify recycling compliance. The Rhine-Main metropolitan area concentrates mid-tier flavor house technical operations.
Germany Food Flavor and Enhancer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and extraction technology sophistication. The vendor base organizes into three tiers: integrated multinationals with captive biotechnology platforms, mid-sized specialists with backward integration into botanical sourcing, and regional compounders serving price-sensitive applications. Strategic differentiation concentrates on precision fermentation capabilities and direct retail relationships displacing traditional broker channels.
Within the integrated multinational tier, Givaudan and Firmenich occupy positions defined by biotechnology platform scale and fermentation-derived aromatic production. Symrise AG anchors the specialist tier through deep integration into botanical extraction capabilities. Kerry Group exemplifies the diversified nutrition-ingredient conglomerate archetype with flavor systems embedded within broader formulation portfolios.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich |
| Kerry Group |
| International Flavors and Fragrances Inc. |
| Symrise AG |
| Archer Daniels Midland Company |
| Takasago International Corporation |
| Flavorchem Corp. |
| Döhler GmbH |
| Others |
Supply & Pricing Matrix
Flavor chemist concentration in Bavaria and North Rhine-Westphalia creates labor-cost differentials that widen pricing spreads between premium fermentation-derived natural flavors and commodity synthetic alternatives. The scarcity of gas chromatography-olfactometry expertise forces mid-tier compounders toward lower-margin contract manufacturing while integrated multinationals capture value through captive biotechnology platforms.
Pricing Analysis
Value-based pricing anchors on clean-label certification outcomes and sodium-reduction yield improvements in finished formulations. Three-tier pricing structure across premium, standard, and economy levels separates EU-organic certified botanical extracts from conventional natural flavors and petrochemical-derived synthetics. Cost compression in the standard tier is intensifying because Aldi and Lidl procurement consolidation demands volume discounts from direct suppliers. Mass-market confectionery manufacturers exhibit highest price sensitivity; certified organic beverage producers show lowest sensitivity due to premium positioning.
Supply Chain Analysis
Workforce availability constraints in Bavarian extraction facilities and Rhineland beverage corridors are extending lead times for specialized fermentation technicians. Madagascar, Mediterranean citrus-growing regions, and Central European yeast extract facilities anchor geographic supply concentration. Feedstock draws from vanilla bean harvests, citrus oil distillations, and ribonucleotide fermentation batches. Single-source vulnerability in Madagascar vanilla sourcing creates structural risk. Distribution runs through direct technical relationships with retail private-label programs, displacing traditional regional ingredient brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EU REACH authorization timelines and BfR toxicological assessment burdens force capital-constrained compounders toward exit or acquisition. Smaller players lacking precision fermentation capabilities face unsustainable compliance costs.
For Market Incumbents: Lock in backward integration into botanical sourcing and supercritical CO2 extraction infrastructure to defend margin position against precision fermentation disruptors. Deepen direct retail relationships with Aldi and Lidl corporate technical buyers to secure specification authority before further procurement consolidation. Prioritize certification investment in EU organic and Naturland standards to maintain premium-tier access. For New Entrants and Emerging Players: Launch via certified organic flavor systems targeting Baden-Württemberg's underpenetrated premium confectionery cluster. Target white-space in precision fermentation-derived vanillin for mid-sized German beverage manufacturers seeking clean-label reformulation without tropical agricultural dependency. Pursue partnership routes with established compounders lacking biotechnology platforms rather than greenfield capacity builds. For Investors and Strategic Acquirers: Re-rating potential sits with mid-sized specialists possessing deep backward integration into botanical extraction given accelerating natural flavor substitution mandates. Five-to-ten year viability favors compounders with demonstrated BfR approval track records and existing retail direct relationships. Watch BfR's evolving stance on natural flavor complexity as the critical inflection signal for next-generation formulation market access.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Givaudan's biotechnology platform reduces dependency on Madagascar vanilla sourcing volatility. |
| Supercritical CO2 Extraction Investment | EU F-Gas Regulation phasedown redirects capital toward solvent-free natural flavor production. |
| Direct Retail Technical Partnership | Aldi and Lidl procurement consolidation rewards audited direct suppliers with specification authority. |
| Certified Organic Portfolio Expansion | Baden-Württemberg organic food cluster pulls disproportionate demand for premium positioning. |
| Savory Enhancer Capacity Addition | Sodium reduction mandates in German ready-meal manufacturing accelerate yeast extract deployment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with flavor house R&D directors, German retail chain technical buyers, Bavarian meat processor procurement leads, and BfR regulatory affairs specialists. Secondary sources incorporated EU REACH substance databases, EFSA scientific opinions, BfR flavor substance assessments, and German Federal Statistical Office trade flow records. Bottom-up segment modeling triangulated against top-down market sizing across the analysis window.
Granularity-level modeling deployed separate forecast tracks for natural flavors, flavor enhancers, and synthetic alternatives by physical form and application vertical. Beverage manufacturing, bakery and confectionery, and culinary preparation end-uses were modeled with distinct reformulation pressure assumptions. CAGRs derived from regression analysis of historical procurement patterns and regulatory mandate implementation schedules. Precision fermentation adoption curves and EU F-Gas Regulation compliance timelines served as industry-specific forecast inputs.
Madagascar vanilla crop yields, Mediterranean citrus harvest variability, and BfR approval timeline extensions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding clean-label mandate enforcement consistency and retail procurement consolidation pace. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
Veratrole Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Anti-Sagging Agents Market
Food Enhancers and Additives
Flour Improvers Market
Food Enhancers and Additives
Browning Enhancers Market
Food Enhancers and Additives
Mexico Water Enhancer Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
Germany Water Enhancer Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
Liquid Water Enhancers Market