
 Bread Mix Market | 2026-2036
Bread Mix Market Size, Share, and Industry Trends Forecast 2026-2036
Bread Mix Market Analysis
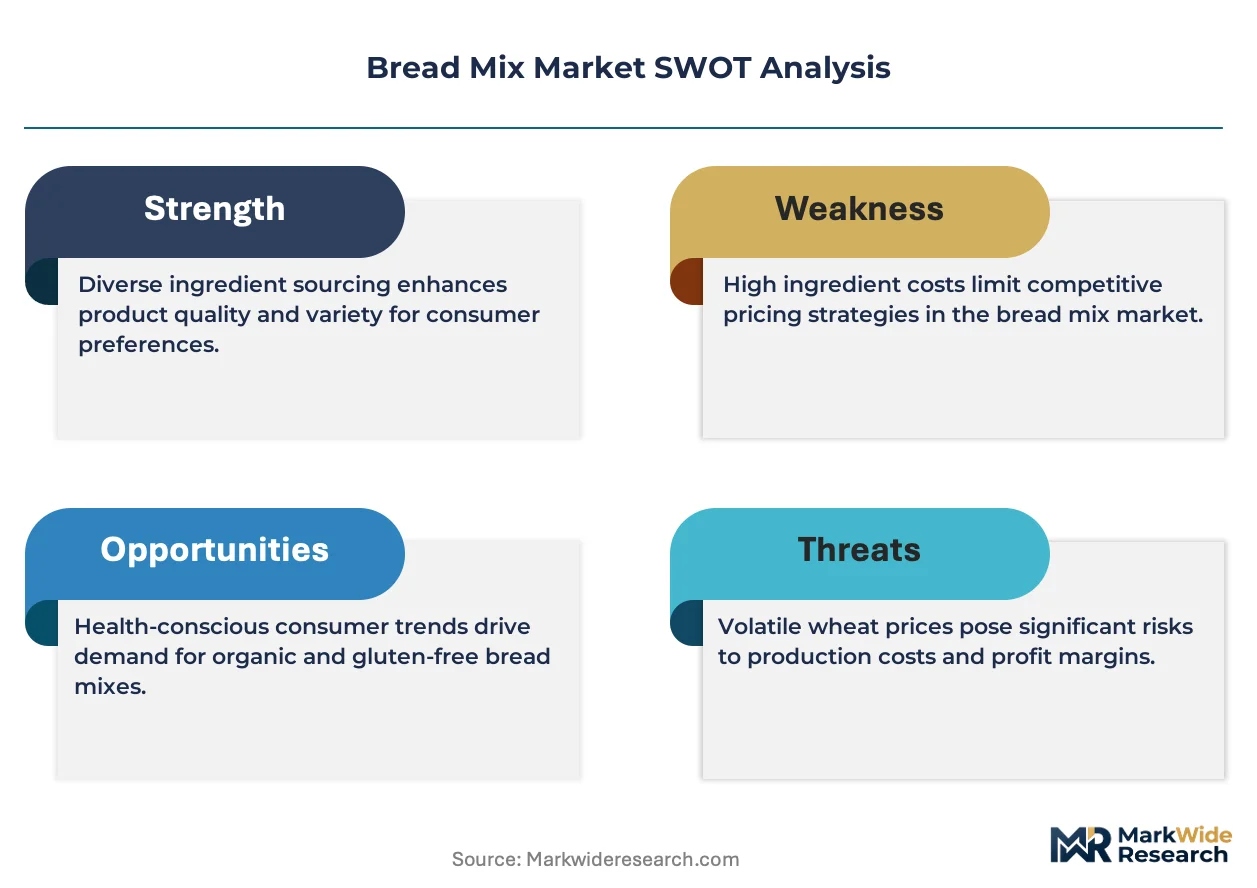
The gap between premium artisan bread mixes and commodity white bread formulations is realigning purchasing patterns across commercial and retail channels. General Mills leverages its milling infrastructure to control input costs across both tiers. Puratos Group differentiates through sourdough starter technologies and enzyme-based conditioning systems. King Arthur Baking Company anchors the premium segment with heritage branding and specialty grain sourcing.
Bread mix denotes a pre-formulated blend of refined or whole grain flours, leavening agents, salt, and functional additives requiring only hydration and fermentation before baking. Protein content typically ranges from 10-14% for standard applications, with gluten-free variants utilizing hydrocolloid gums to mimic viscoelastic dough structure. Whole wheat and multigrain categories command margin premiums due to shorter supply chains for specialty grains and certification requirements. The gluten-free segment leads volume growth, though white bread mixes still dominate absolute tonnage in foodservice procurement.
FDA labeling rules and EFSA health claim protocols shape permissible nutritional declarations across North American and European markets. The USDA organic standard and EU Green Deal agricultural targets further constrain sourcing flexibility for major blenders. Stakeholders must monitor evolving enzyme approval lists and regional allergen threshold regulations to protect formulation continuity and market access.
Market Dynamics
Clean-label mandates from the FDA and EFSA are forcing blenders to reformulate around enzyme replacements and natural fermentation aids, compressing R&D timelines while elevating input costs across both artisan and commodity tiers.
Growth Catalysts
- EU Green Deal agricultural targets:Subsidies for regenerative grain farming in France and Germany are expanding domestic specialty wheat supply, reducing import dependency for heritage flour sourcing.
- Cafe channel expansion:Independent coffee shops in Melbourne, Portland, and Copenhagen are installing in-house ovens, creating pull for small-batch sourdough mixes with 48-hour cold fermentation protocols.
- Enzyme-based conditioning:Advances in fungal amylases and lipoxygenases are enabling clean-label dough stabilization without azodicarbonamide or DATEM, satisfying EFSA additive restrictions.
Market Restraints
- Specialty grain supply concentration:Heritage wheat varietals from Turkey and Kazakhstan face export quota volatility, squeezing margin for multigrain and ancient-grain formulations.
- Gluten-free hydrocolloid cost structure:Guar gum and xanthan gum prices track petroleum derivatives and Indian monsoon cycles, creating unpredictable input cost spikes.
- Substitution threat from frozen dough:Par-baked and frozen dough formats from industrial bakeries are capturing foodservice accounts seeking labor reduction over mix flexibility.
Strategic Opportunities
- Underpenetrated precision fermentation:Biotech-derived whey and egg white replacers from Perfect Day and Clara Foods enable vegan brioche mixes targeting flexitarian households in the Netherlands and UK.
- Direct-to-bakery subscription channels:Fresh-milled, small-batch mix deliveries bypass distributor markups, capturing price-insensitive home bakers in Brooklyn, Berlin, and Tokyo.
- USDA organic certification tailwind:Updated National Organic Program standards for processing aids are opening loopholes for enzyme-based organic mixes previously excluded from the category.
Industry Challenges
- Fermentation science talent scarcity:Industrial microbiologists capable of optimizing starter cultures for commercial scale command premium salaries, constraining mid-tier blender R&D staffing.
- Clean-label reformulation capex:Replacing chemical conditioners with natural alternatives requires new mixing equipment and extended shelf-life testing protocols, extending payback periods.
- Allergen threshold harmonization:Divergent ppm limits for sesame, lupin, and mustard across FDA, EFSA, and Health Canada force parallel label runs, complicating export logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread Mix Market |
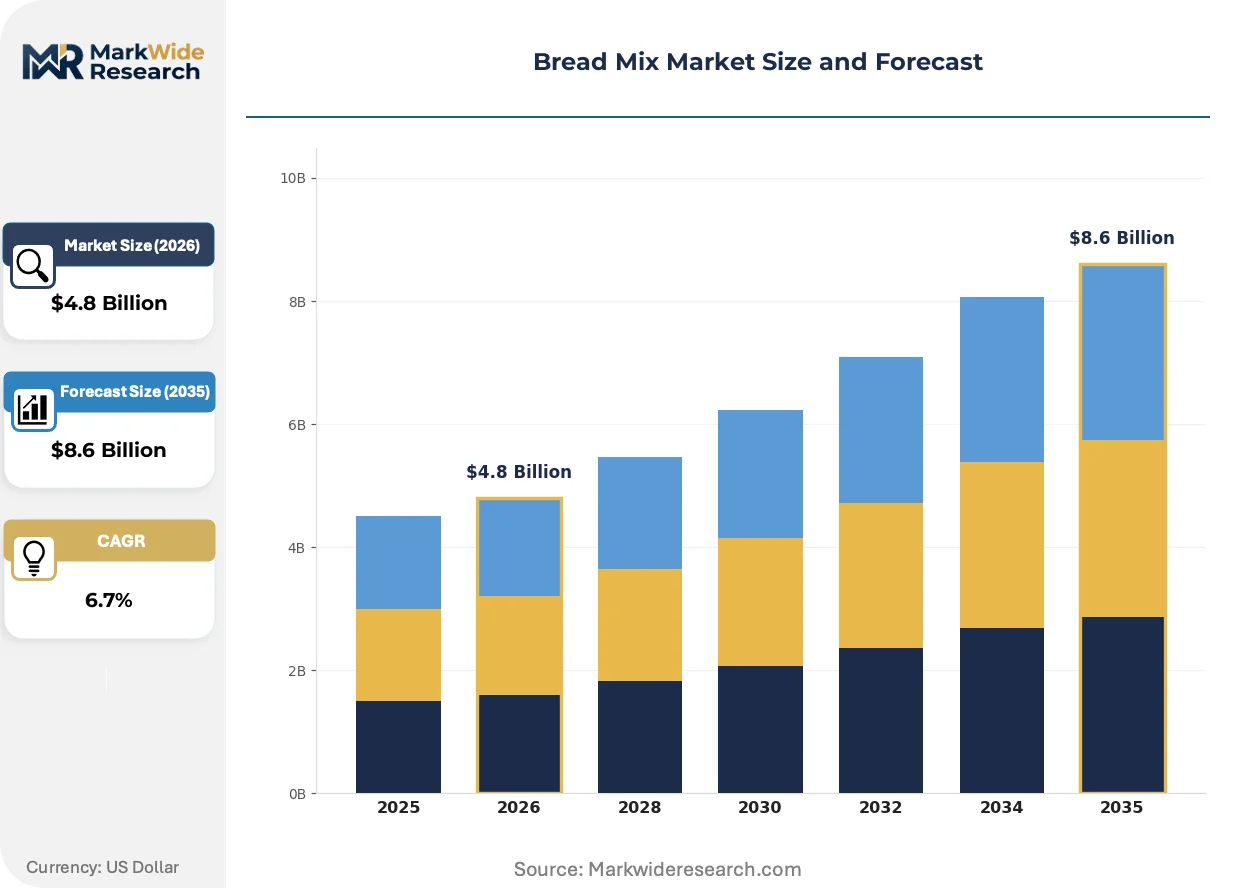
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Wheat, Gluten-Free, Multigrain, White Bread Application: Baking, Foodservice, Retail, Home Use Distribution Channel: Offline Retail, Online, Supermarkets, Specialty Stores End User: Households, Bakeries, Restaurants, Cafes |
| Companies Covered | General Mills, Archer Daniels Midland Company, Cargill, Puratos Group, Associated British Foods, King Arthur Baking Company, Continental Mills, Sonneveld Group, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread Mix Market Emerging Trajectories
Active dry yeast alternatives and precision fermentation inputs are restructuring formulation possibilities, while regulatory clarity on enzyme approvals and shifting procurement patterns among foodservice operators are redefining competitive positioning.
Sourdough starter concentrates using freeze-dried wild lactobacillus cultures are overtaking commercial instant yeast in premium cafe applications. Artisan bakeries in San Francisco and Copenhagen are adopting these concentrates to reduce fermentation labor while maintaining flavor complexity. The technology is overtaking commodity yeast suppliers in the $8-plus per kilogram mix segment, compressing volume for conventional leavening agents.
EFSA's updated health claim protocols for whole grain and fiber content are restricting permissible nutritional declarations on European bread mix packaging. Blenders must now submit clinical evidence for glycemic response claims, elevating substantiation costs. German and Dutch manufacturers are responding by pivoting marketing toward texture and heritage storytelling rather than explicit health promises.
Foodservice procurement is consolidating through broadline distributor private-label programs, displacing independent mix brands in institutional accounts. Sysco and US Foods are requiring exclusive formulation partnerships with guaranteed volume commitments, locking out smaller blenders from K-12 and healthcare channels. This concentration is most visible in the US Southeast, where contract food management companies like Compass Group and Sodexo have centralized purchasing decisions at regional hubs.
Bread Mix Market Segmentation
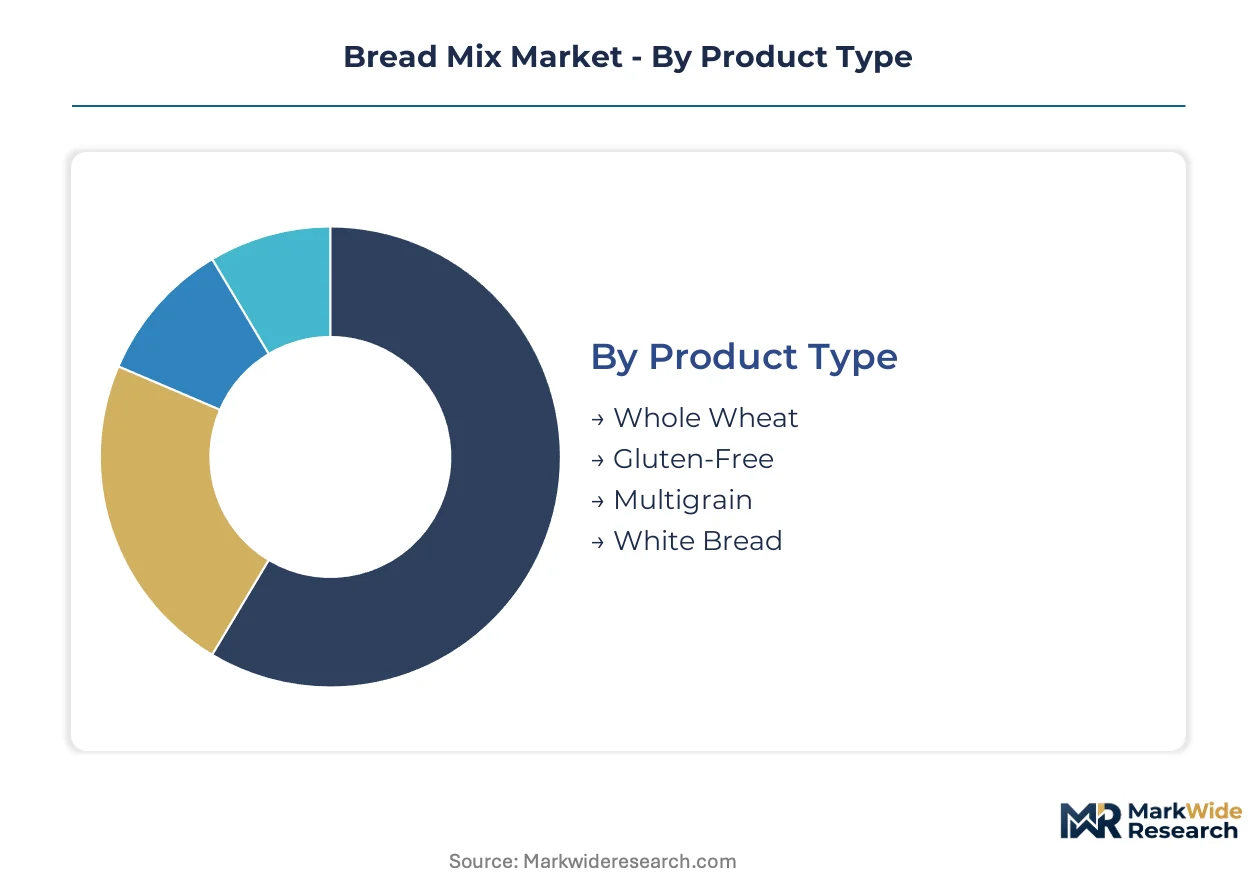
Bread mix segmentation reveals divergent technical requirements across consumption contexts, from industrial-scale foodservice operations demanding consistency to home bakers prioritizing heritage grain provenance. Understanding these segment boundaries enables targeted formulation strategies and channel-specific positioning.
Product Type:
Product type segmentation distinguishes between standalone formulations requiring minimal baker intervention versus embedded systems integrating pre-activated fermentation stages.
- Whole Wheat:Formulations with 100% whole grain flour content, bran inclusion, and elevated fiber levels typically 12-14% protein. German craft bakeries and Dutch health-conscious households drive demand, constrained by shorter shelf life from wheat germ oil oxidation requiring nitrogen-flushed packaging.
- Gluten-Free:Hydrocolloid-stabilized blends utilizing rice, tapioca, or sorghum bases with xanthan or guar gum structure replication. Melbourne and Portland cafe channels are expanding fastest as celiac-safe menu options become non-negotiable for independent operators.
- Multigrain:Composite formulations incorporating seeds, ancient grains, and multiple cereal sources for texture complexity.
- White Bread:Refined flour bases with minimal bran content, optimized for volume and soft crumb structure in high-throughput foodservice.
White bread leads volumes today; gluten-free is gaining share fastest.
Application:
Application segmentation maps to operational intensity, separating intermittent home use from continuous commercial production environments.
- Baking:Professional-grade mixes calibrated for deck ovens, rack systems, and convection environments with precise hydration specifications. Artisan bakeries in Copenhagen and San Francisco specify 48-hour cold fermentation protocols, pulling premium sourdough concentrates.
- Foodservice:High-volume formulations optimized for speed-scratch preparation in institutional kitchens and chain restaurants.
- Retail:Consumer-packaged goods positioned for grocery aisle pickup, emphasizing convenience and extended shelf stability.
- Home Use:Small-batch formats with simplified instructions and forgiving fermentation windows for occasional bakers.
Baking commands the highest per-kilogram pricing; foodservice generates the largest absolute tonnage.
Distribution Channel:
Channel segmentation reflects procurement behavior divergence between planned stock-up purchasing and immediate need fulfillment.
- Offline Retail:Traditional brick-and-mortar including convenience stores and neighborhood grocers with limited SKU breadth.
- Online:Direct-to-consumer platforms and marketplace fulfillment enabling subscription models and fresh-milled small-batch access. Brooklyn and Berlin home bakers increasingly bypass distributor markups through specialty miller subscriptions.
- Supermarkets:Mass-market retail with private-label penetration and promotional pricing cycles.
- Specialty Stores:Curated assortments emphasizing organic certification, heritage grains, and local provenance.
Supermarkets dominate transaction volume; specialty stores deliver the steepest margin expansion.
End User:
End user segmentation aligns technical support requirements with operational sophistication and scale.
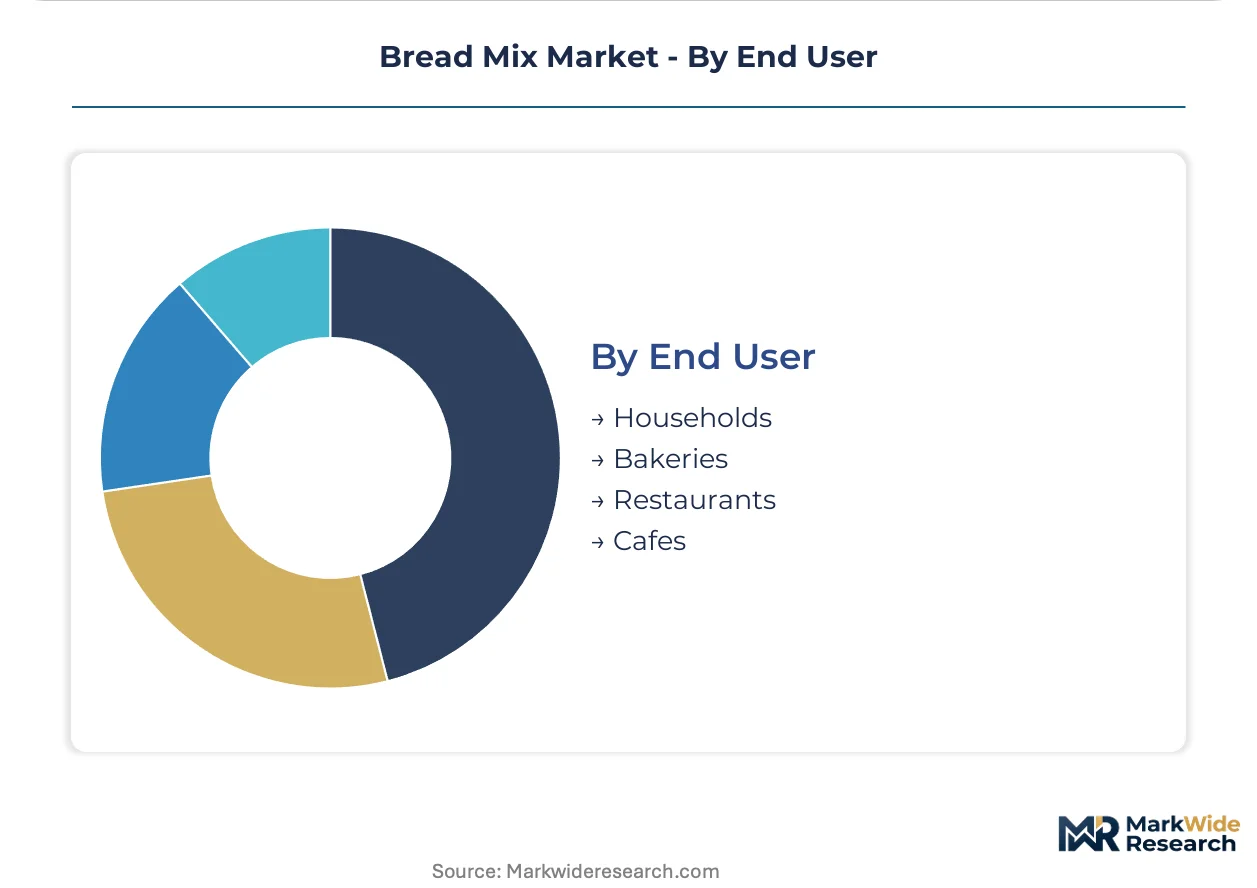
- Households:Occasional consumption with emphasis on simplicity, storage stability, and recipe guidance. Japanese and UK flexitarian households are adopting precision-fermentation-enabled vegan brioche formats.
- Bakeries:Professional operations requiring consistent fermentation behavior, scalable batch sizing, and technical troubleshooting support.
- Restaurants:Front-of-house bread programs demanding speed-scratch solutions with minimal labor allocation.
- Cafes:In-house baking installations seeking differentiation through signature sourdough and limited-batch offerings.
Bakeries anchor procurement volumes; cafes are expanding most quickly as oven installations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisan bakers and industrial millers cluster in heritage grain corridors and metropolitan food hubs. Workforce density in traditional baking crafts sustains regional specialization. Regulatory divergence on additive approvals shapes cross-border formulation strategies.
Germany
Craft baking guilds in Bavaria and Baden-Württemberg sustain demand for heritage wheat mixes with 14% protein content. The EU Green Deal subsidizes regenerative grain farming in Lower Saxony, expanding domestic specialty wheat supply. Berlin-Brandenburg hosts precision-fermentation startups developing vegan brioche formulations for flexitarian households.
United States
Independent cafes in Brooklyn and Portland install deck ovens, pulling small-batch sourdough concentrates with 48-hour cold fermentation protocols. FDA clean-label mandates force reformulation around enzyme replacements, compressing R&D timelines. The Pacific Northwest clusters heritage grain millers supplying organic multigrain blends to subscription channels.
France
Traditional boulangeries in Île-de-France and Auvergne-Rhône-Alpes anchor demand for T80 and T110 flour mixes. ANSM labeling requirements for sesame and lupin allergens complicate export logistics to North American markets. Lyon-based cooperatives pioneer ancient-grain sourcing from regenerative farms in Nouvelle-Aquitaine.
Japan
Home bakers in Tokyo and Osaka adopt precision-fermentation-enabled vegan brioche formats. METI standards for food processing aids constrain enzyme approval lists, protecting formulation continuity for domestic blenders. The Kansai region concentrates industrial millers supplying convenience store chains with extended-shelf-life white bread mixes.
Australia
Celiac-safe menu requirements in Melbourne cafes expand gluten-free hydrocolloid-stabilized blends. TGA allergen threshold regulations for mustard and lupin diverge from FDA and EFSA limits, forcing parallel label runs. Sydney specialty stores curate organic certified mixes bypassing distributor markups through direct-to-bakery subscriptions.
Bread Mix Market Vendor Landscape
Capital-heavy millers compete with asset-light specialty blenders across tiered market positions. Consolidation concentrates volume among integrated grain processors controlling upstream supply. Three archetypes dominate: heritage-brand premium specialists, diversified commodity processors, and regional craft suppliers. Strategic moves center on sourdough starter technology licensing and exclusive distributor partnerships locking out mid-tier competitors.
Among North American diversified processors, General Mills and Archer Daniels Midland occupy positions spanning commodity and premium tiers through captive milling infrastructure. Puratos Group anchors the enzyme-based conditioning segment, representing the European specialist archetype with sourdough concentrate capabilities. King Arthur Baking Company exemplifies the heritage-brand premium position, sourcing specialty grains through shorter supply chains.
| Leading Market Players |
|---|
| General Mills |
| Archer Daniels Midland Company |
| Cargill |
| Puratos Group |
| Associated British Foods |
| King Arthur Baking Company |
| Continental Mills |
| Sonneveld Group |
| ADM |
| Others |
Supply Flow & Price Mechanics
Enzyme-based conditioning technology adoption simultaneously compresses formulation costs and concentrates supplier power among biotech-enabled blenders. FDA and EFSA clean-label mandates force mid-tier manufacturers toward premium natural inputs, eroding price competitiveness against vertically integrated millers.
Pricing Analysis
Bundled sourdough starter concentrates with technical fermentation support command premium positioning, while unbundled commodity flour bases compete on volume scale. Three-tier pricing structure across premium artisan, standard commercial, and economy foodservice levels tracks protein content and heritage grain certification. Pricing pressure stems from frozen dough substitution in institutional accounts seeking labor reduction. Foodservice procurement teams exhibit highest price sensitivity; craft bakeries in Copenhagen and San Francisco accept steep premiums for provenance guarantees.
Supply Chain Analysis
Direct-to-bakery subscription channels bypass distributor markups for price-insensitive home bakers in Brooklyn, Berlin, and Tokyo. Heritage wheat varietals draw from Turkey, Kazakhstan, and regenerative farms in Lower Saxony and Nouvelle-Aquitaine. Guar gum and xanthan gum hydrocolloids hinge on Indian monsoon cycles and petroleum derivative pricing. Single-source vulnerability concentrates in Anatolian heritage grain corridors. Distribution runs through broadline distributors consolidating institutional accounts with exclusive formulation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bread mix market functions as a geographic-arbitrage play where EU Green Deal subsidies for regenerative grain farming in Germany and France create 15-20% input cost advantages against import-dependent North American blenders facing volatile heritage wheat quotas.
For Market Incumbents: Hedge against frozen dough substitution by locking exclusive distributor partnerships with Sysco and US Foods regional hubs. Deepen backward integration into captive milling infrastructure to control specialty grain supply chains and protect margin from Turkish export quota volatility. Prioritize enzyme-based organic certification investment as USDA National Organic Program standards evolve. For New Entrants and Emerging Players: The premium-to-economy price gap in gluten-free hydrocolloid-stabilized blends offers white-space entry targeting Melbourne and Portland cafe channels with celiac-safe speed-scratch solutions. Precision-fermentation-enabled vegan brioche formats for Dutch and UK flexitarian households represent the most penetrable segment. Pursue direct-to-bakery subscription go-to-market positioning bypassing established distributor networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional craft suppliers with heritage grain sourcing relationships but lacking enzyme-based conditioning capabilities. Five-to-ten year viability favors acquisition targets consolidating sourdough starter technology licensing positions. Monitor EFSA enzyme approval list expansions as inflection indicator for clean-label formulation scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Perfect Day and Clara Foods biotech inputs enable vegan brioche mix differentiation for flexitarian channels. |
| Direct-to-Bakery Subscription Launch | Fresh-milled small-batch deliveries bypass distributor markups in Brooklyn, Berlin, and Tokyo home baker segments. |
| Heritage Grain Sourcing Agreement | Regenerative farm partnerships in Lower Saxony secure EU Green Deal subsidized supply against Turkish quota volatility. |
| Enzyme-Based Organic Certification | USDA National Organic Program processing aid updates open previously excluded formulation categories. |
| Sourdough Starter Technology Licensing | Freeze-dried wild lactobacillus concentrates displace commercial instant yeast in premium cafe applications. |
Methodological Framework
Direct dialogue with bakery operations managers, flour mill procurement directors, cafe chain culinary leads, and enzyme supplier technical R&D heads grounded qualitative insights. Secondary validation drew from FDA enzyme approval databases, EFSA health claim submission records, USDA organic certification registries, and EU Green Deal agricultural subsidy disclosures. Bottom-up volume modeling across product tiers triangulated against top-down category spend estimates.
Segment-level value outputs across the projection horizon reflect protein content tiers, application intensity, and distribution channel markup structures. Modeled dimensions span product type, end-use operational scale, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for clean-label reformulation adoption curves and frozen dough substitution elasticities. Forecast inputs incorporated heritage grain supply concentration indices and hydrocolloid cost volatility patterns.
Caveats apply where EFSA enzyme approval delays, Turkish heritage wheat export restrictions, or guar gum monsoon failures could materially shift the outlook. Forecasts reflect documented assumptions around cafe channel oven installation rates and precision fermentation ingredient cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low Calorie Cake Market
Bakery Products
Gluten-Free Bread Market
Bakery Products
Fondant Market
Bakery Products
Ice Cream Cones Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Vegan Donuts Market
Bakery Products
India Cake Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
North America Bakery Products Market
Bakery Products
Dough Whitener Market
Bakery Products
Bread Crumbs Market
Bakery Products
US Retail Packaged Bread Market
Bakery Products
Pastry Margarine Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Bread Improver Market
Bakery Products
United States Bread Market