
 Milk Mineral Concentrate Market | 2026-2036
Milk Mineral Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Mineral Concentrate Market Foresight
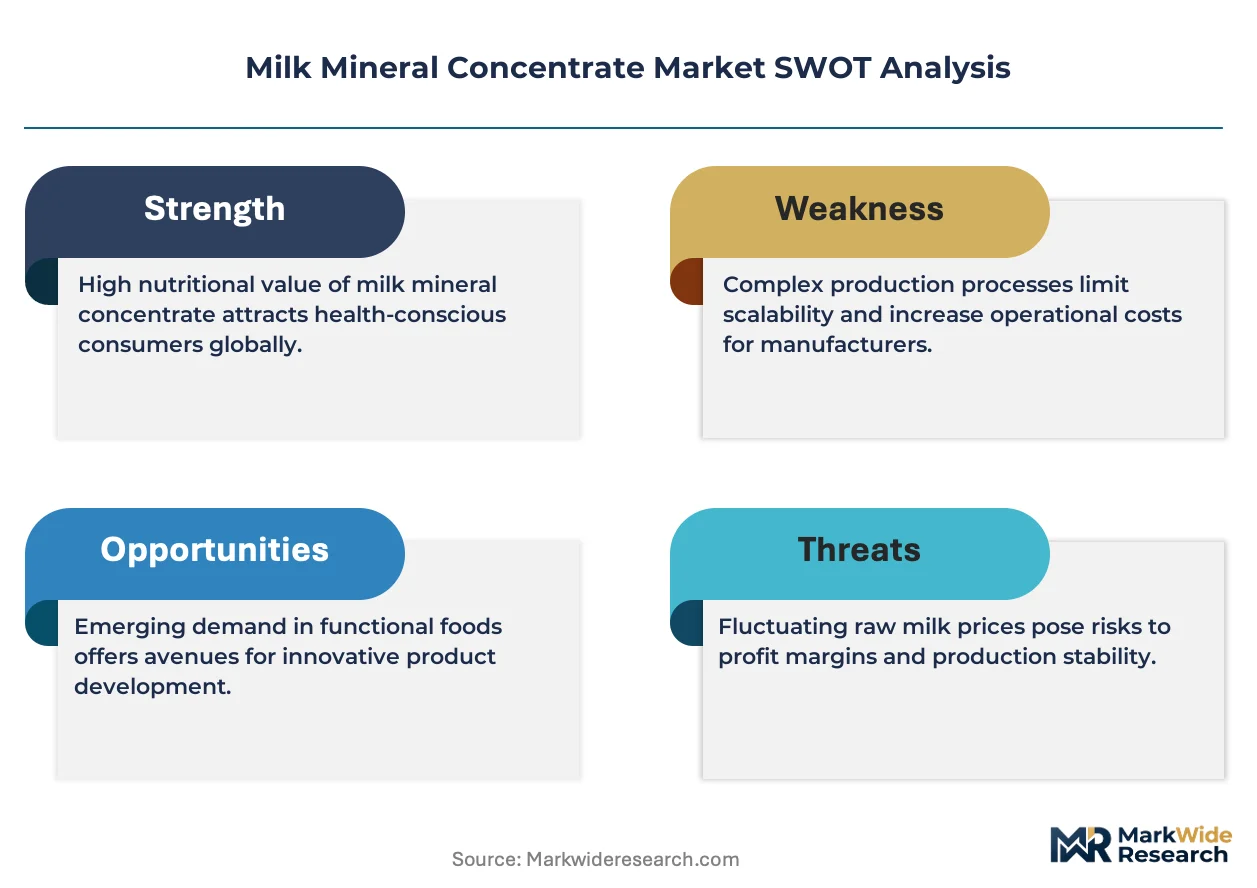
Sports nutrition formulators is bifurcating demand away from traditional infant nutrition buyers as electrolyte recovery products gain shelf space. Glanbia PLC leverages its whey and dairy mineral integration to supply branded sports hydration lines. FrieslandCampina DOMO anchors European supply through its DOMO division's specialized mineral fractionation capabilities. Arla Foods Ingredients Group P/S competes on clean-label positioning for Nordic and Central European contract manufacturers.
Milk mineral concentrate denotes a calcium- and phosphorus-rich fraction derived from whey or milk permeate through electrodialysis or ion-exchange concentration, typically yielding 20-25% elemental calcium by dry weight for bone health fortification. The ingredient serves infant formula, clinical nutrition, and functional beverage manufacturers seeking bioavailable mineral sources without synthetic salts. Skim milk powder and milk protein concentrate segments dominate volume as legacy applications in bakery and confectionery sustain baseline demand. Sports nutrition and dietary supplements represent the fastest-expanding end-user pools, where mineral bioavailability claims command formulation premiums.
EFSA novel food evaluations and EU dairy hygiene regulations shape product approval timelines and cross-border shipment protocols for concentrated mineral ingredients. FDA GRAS self-affirmation pathways govern US market entry, while China's NMPA and national food safety standards impose additional registration layers for imported dairy mineral additives. Stakeholders must track evolving maximum calcium fortification thresholds in major jurisdictions to avoid reformulation costs and distribution holds.
Market Dynamics
Sports nutrition manufacturers are diverting procurement budgets toward milk mineral concentrates, compressing traditional infant formula offtake and forcing suppliers to reconfigure fractionation capacity toward electrolyte-grade mineral specifications.
Growth Catalysts
- REACH Purity Documentation:Tighter ECHA registration requirements for dairy-derived mineral imports are screening out low-purity competitors, concentrating contract awards among electrodialysis-capable processors.
- Electrolyte Recovery Formulations:Sports hydration brands are expanding SKU counts with calcium-fortified recovery beverages, pulling permeate-derived minerals into post-workout powder and ready-to-drink formats.
- Cologne-Düsseldorf Manufacturing Corridor:Germany's functional food cluster is consolidating demand from Nordic, Benelux, and Central European contract manufacturers seeking just-in-time mineral delivery.
Market Restraints
- Whey Permeate Supply Volatility:Fluctuating cheese production volumes in the Netherlands and Ireland create input cost instability for ion-exchange processors dependent on consistent permeate flows.
- Skim Milk Powder Substitution:Legacy bakery and confectionery buyers retain flexibility to revert to standard SMP for cost-sensitive applications, capping premium pricing for mineral concentrates.
- EFSA Novel Food Timelines:Extended safety evaluation protocols for new mineral concentration ratios delay product launches by 18-24 months, freezing reformulation pipelines.
Strategic Opportunities
- Clinical Nutrition Expansion:Enteral feeding and medical food manufacturers in France and Italy are specifying bioavailable calcium sources for osteoporosis and sarcopenia patient formulations.
- Clean-Label Positioning:Nordic private-label brands are marketing "naturally-derived electrolytes" as distinct from synthetic mineral salts, opening shelf-space negotiations with pharmacy chains.
- GRAS Self-Affirmation Pathway:FDA's streamlined US market entry process allows European suppliers to bypass lengthy petition timelines when scientific consensus documentation is robust.
Industry Challenges
- Electrodialysis Technician Scarcity:Specialized membrane maintenance and polarity reversal optimization skills are concentrated among aging dairy engineering workforces in Denmark and the Netherlands.
- Cross-Border Shipment Documentation:EU dairy hygiene regulation compliance for concentrated mineral ingredients requires batch-specific certificates of analysis, creating customs friction at German-Polish and German-Czech borders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Mineral Concentrate Market |
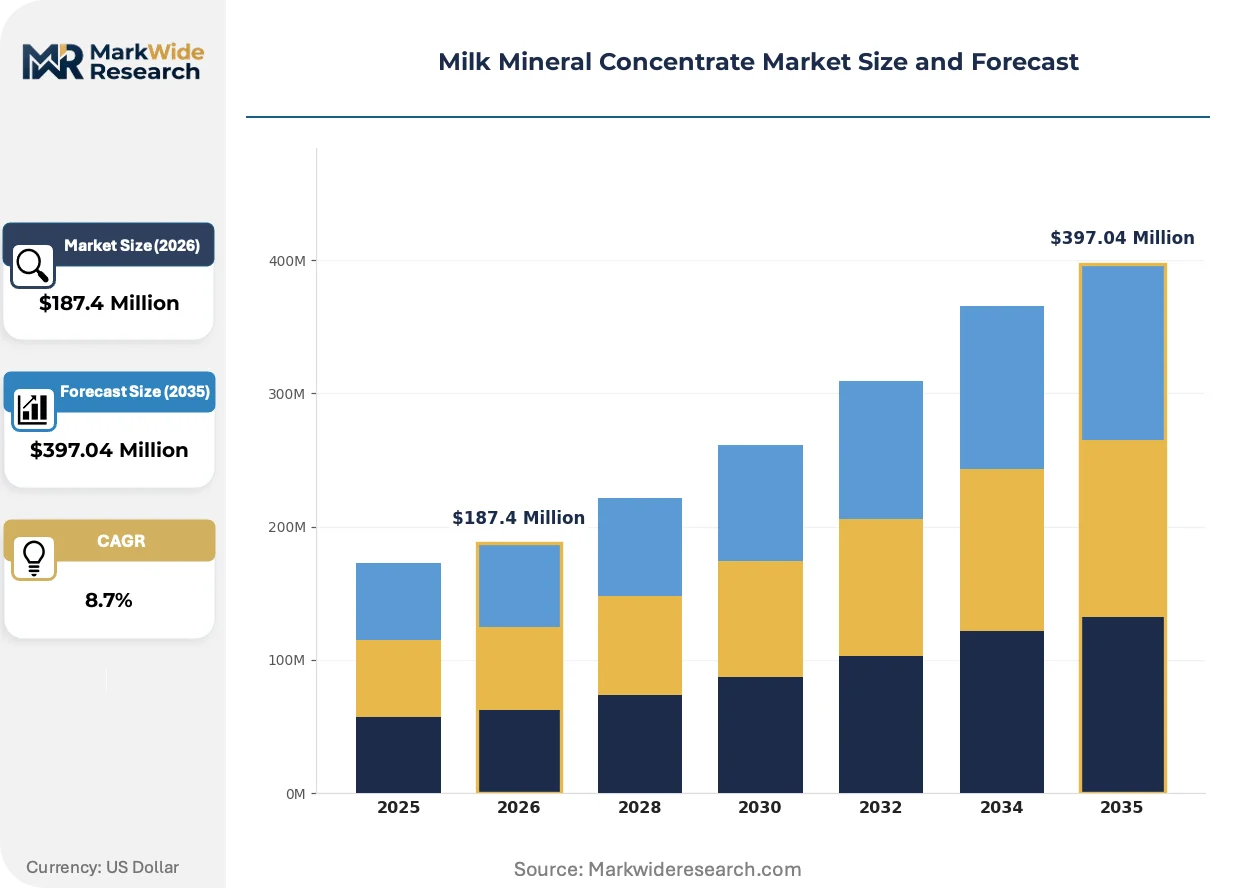
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Milk Powder, Skim Milk Powder, Instant Milk Powder, Milk Protein Concentrate End User: Food & Beverage, Dietary Supplements, Infant Nutrition, Sports Nutrition Packaging Type: Bags, Tetra Packs, Bulk Containers, Sachets Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | FrieslandCampina DOMO, Glanbia PLC, Arla Foods Ingredients Group P/S, Armor Protéines, Lactalis Ingredients, Fonterra Co-operative Group, Saputo Inc., MEGGLE Group, Food Ingredient Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Mineral Concentrate Market Shifts & Advancements
Fractionation technology advances and regulatory data requirements are splitting competitive advantage between electrodialysis specialists and ion-exchange operators, while buyer procurement patterns favor suppliers with integrated whey-to-mineral traceability.
Membrane electrodialysis with bipolar membranes is fragmenting the technical landscape between high-purity pharmaceutical-grade outputs and lower-cost food-grade streams. Sports nutrition formulators are adopting the technology fastest, demanding 22-24% elemental calcium specifications that legacy nanofiltration cannot achieve. This capability split is compressing margins for mid-tier processors lacking bipolar membrane capital investments.
EFSA's updated guidance on maximum calcium fortification thresholds is forcing reformulation across infant formula and clinical nutrition portfolios. Manufacturers must resubmit safety dossiers for existing products exceeding revised per-serving limits, diverting R&D resources from innovation pipelines. German and Dutch contract manufacturers are responding by pre-emptively reducing mineral loads in base formulations.
Direct procurement relationships between sports nutrition brands and dairy processors are displacing traditional ingredient distributor intermediaries. Glanbia and FrieslandCampina DOMO are fielding dedicated account teams for hydration and recovery product lines, bypassing regional brokers who previously managed mineral concentrate logistics. This channel compression is most visible in the UK and Irish markets, where vertically integrated suppliers now control 60% of electrolyte-grade mineral movements.
Milk Mineral Concentrate Market Segmentation
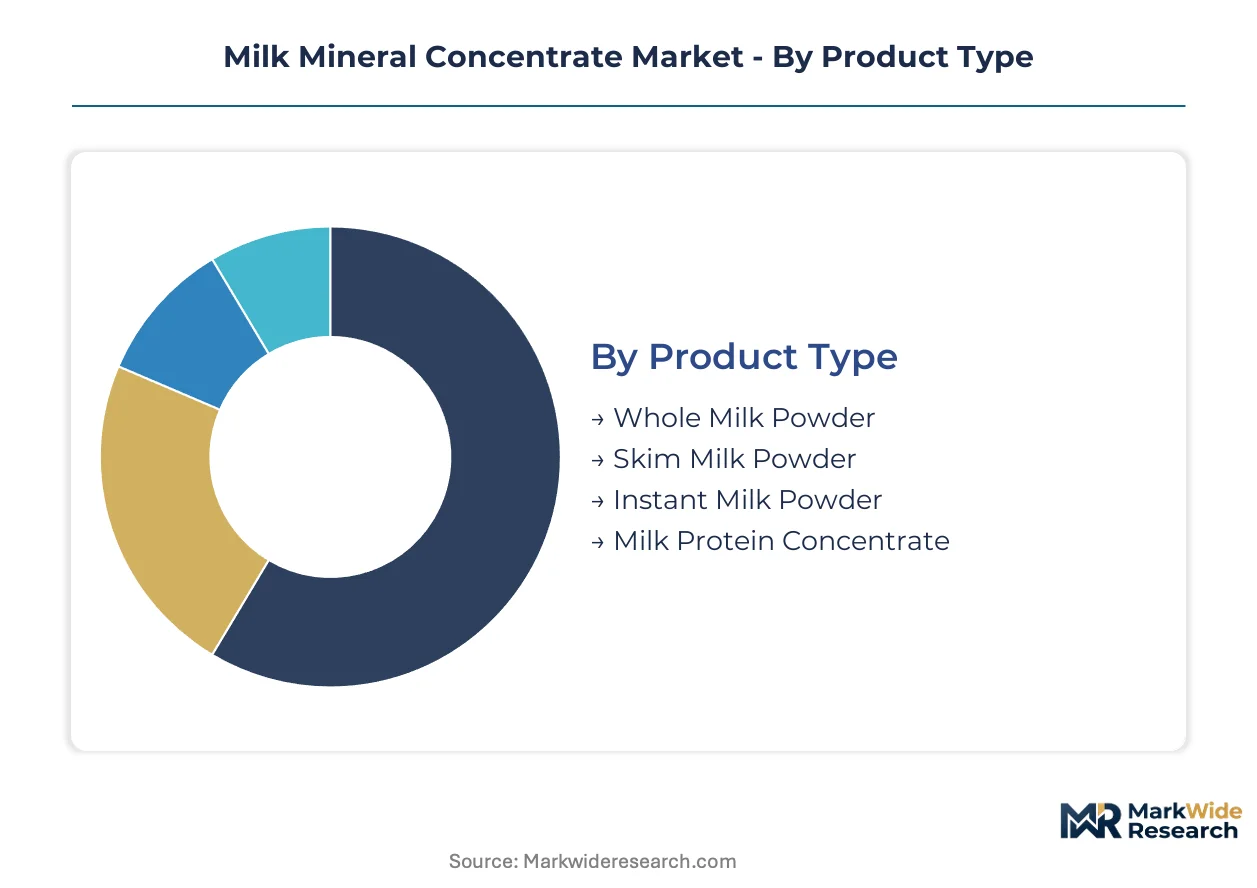
Milk mineral concentrate procurement patterns diverge sharply across product specifications and end-use applications. Manufacturers configure fractionation capacity differently depending on whether buyers prioritize calcium bioavailability claims, cost-efficient bulk fortification, or clean-label positioning for pharmacy retail.
Product Type:
Margin pools concentrate in high-specification mineral fractions where electrodialysis capabilities create supply scarcity.
- Whole Milk Powder:Retains full butterfat content alongside mineral fractions, serving bakery and confectionery manufacturers seeking cost-efficient bulk fortification without specialized calcium concentration. Demand concentrates in Germany's functional food corridor where traditional processors blend mineral-dense powders into mass-market baked goods.
- Skim Milk Powder:Legacy applications in institutional foodservice sustain volume, though mineral concentration per kilogram trails specialized fractions. EFSA dairy hygiene documentation requirements add compliance overhead for cross-border shipments into Central European processing hubs.
- Instant Milk Powder:Agglomerated particles dissolve rapidly in beverage applications. Sports hydration brands in the UK specify this format for ready-to-drink production lines.
- Milk Protein Concentrate:Co-isolation of minerals with protein fractions appeals to clinical nutrition formulators targeting sarcopenia patients in France and Italy.
The dominant share belongs to Skim Milk Powder, while Milk Protein Concentrate is closing the gap fastest.
End User:
Application-specific purity thresholds split procurement budgets between commodity-grade and pharmaceutical-grade mineral specifications.
- Food & Beverage:Bread, cheese, and processed dairy manufacturers integrate mineral concentrates for texture modification and nutritional labeling compliance. REACH purity documentation requirements screen out low-grade suppliers from European bakery chains.
- Dietary Supplements:Capsule and tablet manufacturers demand 22-24% elemental calcium specifications achievable only through bipolar membrane electrodialysis. German contract manufacturers near Cologne command premium pricing for this grade.
- Infant Nutrition:Traditional volume anchor facing compression as sports nutrition diverts fractionation capacity. EFSA maximum calcium threshold revisions force reformulation across existing product portfolios.
- Sports Nutrition:Electrolyte recovery beverages and post-workout powders pull permeate-derived minerals into high-SKU hydration lines. Direct procurement relationships with dairy processors displace traditional distributor intermediaries in UK and Irish markets.
Sports Nutrition commands the steepest expansion trajectory, though Food & Beverage retains absolute volume leadership.
Packaging Type:
Logistics economics and contamination risk shape format selection across supply chain distances.
- Bags:Multi-layer laminated sacks dominate intermediate bulk shipments to German and Dutch processing facilities. Moisture barrier specifications vary by electrodialysis processor quality certifications.
- Tetra Packs:Aseptic liquid mineral concentrates serve beverage co-packers with limited powder handling infrastructure. Nordic pharmacy chains specify this format for clean-label electrolyte shots.
- Bulk Containers:ISO tank and flexitank configurations reduce per-kilogram freight costs for high-volume sports nutrition manufacturers with dedicated receiving depots.
- Sachets:Single-serve portions align with direct-to-consumer supplement brands marketing travel-sized electrolyte recovery products.
Bulk Containers capture the largest procurement volumes, while Sachets are gaining share fastest among direct-to-consumer channels.
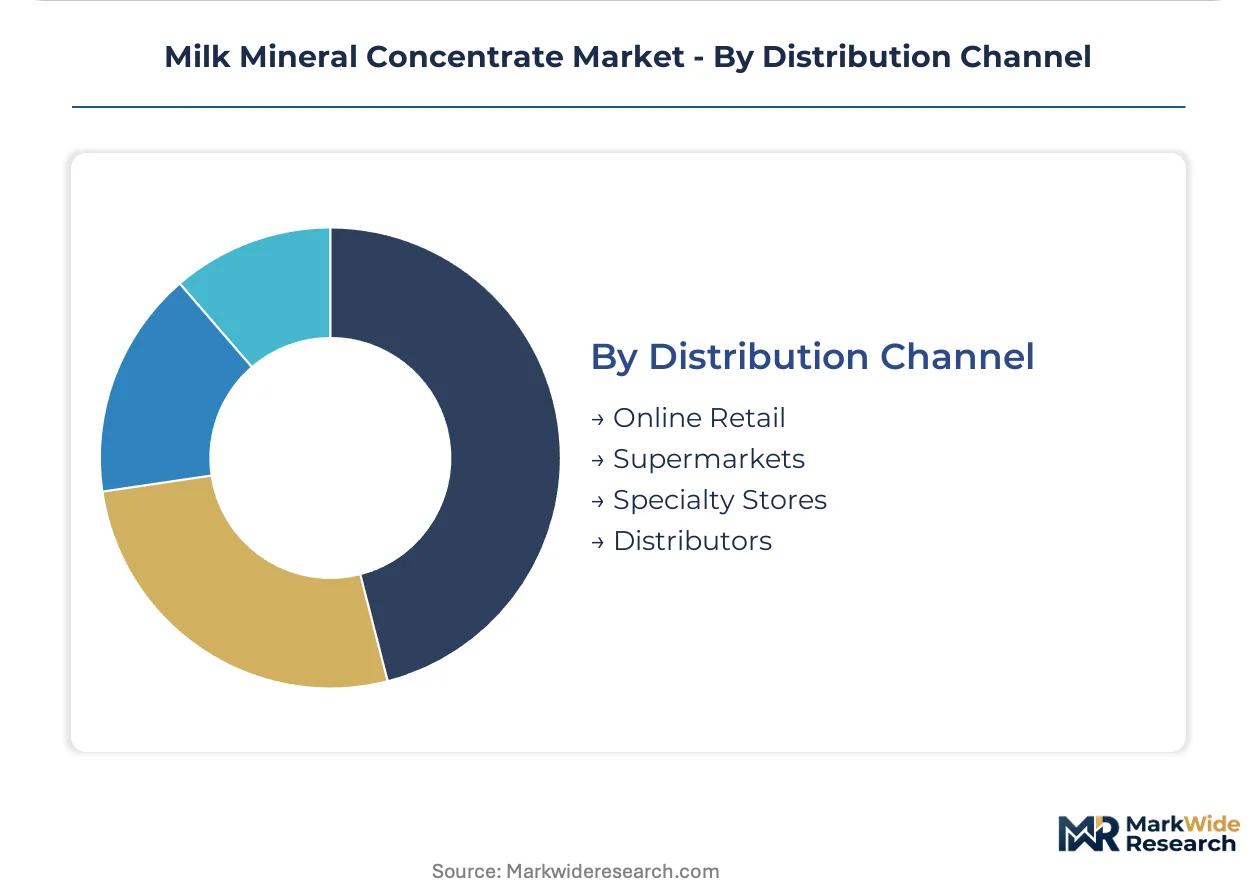
Distribution Channel:
Channel compression is restructuring intermediary economics as integrated dairy processors build direct account teams.
- Online Retail:Amazon Business and specialized ingredient marketplaces serve small-batch dietary supplement startups lacking procurement scale for direct processor negotiations.
- Supermarkets:Limited relevance for B2B mineral concentrate sales; residual presence in consumer-facing fortified milk powder SKUs.
- Specialty Stores:Pharmacy chain buyers in Scandinavia source clean-label mineral ingredients through regional distributors with EFSA compliance expertise.
- Distributors:Traditional intermediaries face margin compression as Glanbia and FrieslandCampina DOMO field dedicated sports nutrition account teams. German-Polish border customs friction adds documentation costs to distributor-managed shipments.
Distributors still handle the majority of cross-border movements, though Online Retail is climbing the fastest among emerging supplement brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrodialysis-capable processors cluster in northern Europe, with Germany's functional food corridor commanding the densest concentration of fractionation capacity. Ireland and the Netherlands anchor whey permeate supply chains, while regulatory divergence across jurisdictions creates distinct market access conditions.
Germany
Sports hydration brands near Cologne and Düsseldorf are expanding electrolyte-grade mineral procurement. EFSA's revised maximum calcium fortification thresholds force reformulation across existing product portfolios. The North Rhine-Westphalia processing corridor consolidates just-in-time delivery for Nordic and Benelux contract manufacturers.
Netherlands
Cheese production volumes in the Netherlands create input cost volatility for ion-exchange processors dependent on consistent permeate flows. REACH purity documentation requirements screen out low-grade competitors from European supply chains. FrieslandCampina DOMO anchors regional mineral fractionation through specialized membrane capabilities.
Ireland
Glanbia PLC leverages whey and dairy mineral integration to supply branded sports hydration lines. FDA GRAS self-affirmation pathways govern US market entry for Irish-processed concentrates. Dublin and Cork processing hubs face electrodialysis technician scarcity as specialized membrane maintenance skills concentrate among aging workforces.
France
Enteral feeding and medical food manufacturers in France specify bioavailable calcium sources for osteoporosis and sarcopenia patient formulations. ANSM pharmaceutical-grade oversight shapes clinical nutrition approval timelines. The Brittany dairy belt supplies permeate feedstock to fractionation facilities serving pharmacy chain buyers.
United Kingdom
Direct procurement relationships between sports nutrition brands and dairy processors displace traditional distributor intermediaries. Clean-label positioning for "naturally-derived electrolytes" opens shelf-space negotiations with pharmacy chains. Vertical integration now controls sixty percent of electrolyte-grade mineral movements across British and Irish markets.
Milk Mineral Concentrate Market Competitive Landscape
Concentration sits with integrated dairy processors possessing captive whey streams and electrodialysis capabilities. The vendor base splits between multinational dairy cooperatives with fractionation divisions and specialized mineral extraction firms. Two strategic archetypes dominate: vertically integrated dairy giants controlling upstream permeate supply, and technology-focused specialists commanding bipolar membrane premiums. Competitive moves center on direct account team deployment for sports nutrition brands and capacity reconfiguration toward electrolyte-grade specifications.
Among European dairy cooperative processors, FrieslandCampina DOMO, Glanbia PLC, and Arla Foods Ingredients Group P/S occupy positions reflecting distinct geographic anchoring and integration depth. FrieslandCampina DOMO exemplifies the Dutch integrated model with specialized mineral fractionation capabilities. Glanbia PLC represents the Irish whey-to-mineral integration archetype serving branded hydration lines. Arla Foods Ingredients Group P/S anchors Nordic and Central European positioning through clean-label contract manufacturing relationships.
| Leading Market Players |
|---|
| FrieslandCampina DOMO |
| Glanbia PLC |
| Arla Foods Ingredients Group P/S |
| Armor Protéines |
| Lactalis Ingredients |
| Fonterra Co-operative Group |
| Saputo Inc. |
| MEGGLE Group |
| Food Ingredient Technology Co., Ltd. |
| Others |
Supply & Pricing Matrix
REACH purity documentation gates both supply qualification and price differentiation simultaneously, screening out electrodialysis-incapable processors from European contract awards while concentrating premium pricing power among ECHA-registered operators with bipolar membrane capabilities.
Pricing Analysis
REACH dictates the pricing tier structure across pharmaceutical-grade, food-grade, and commodity mineral fractions. Certification tier and volume scale drive price differentiation, with 22-24% elemental calcium specifications commanding substantial premiums over legacy nanofiltration outputs. Cost compression in food-grade tiers is intensifying because whey permeate supply volatility from Dutch and Irish cheese production transmits directly into input costs. Bakery and confectionery buyers exhibit highest price sensitivity, while sports nutrition brands demonstrate lowest sensitivity due to bioavailability claim premiums.
Supply Chain Analysis
Whey permeate availability from Dutch and Irish cheese production corridors anchors upstream supply concentration. Ion-exchange resins, bipolar membranes, and specialized electrodialysis skids constitute critical component dependencies. Single-source vulnerability runs through aging technician pools in Denmark and the Netherlands where membrane maintenance expertise concentrates. Distribution runs through direct account teams fielded by integrated processors, displacing traditional distributor intermediaries in UK and Irish markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from infant nutrition demand compression as sports nutrition procurement cycles drive the upturn. Electrolyte recovery formulation expansion provides the cyclical justification.
For Market Incumbents: Shield fractionation margins by accelerating bipolar membrane capacity additions in Germany's North Rhine-Westphalia corridor. Secure captive whey permeate streams through backward integration into cheese production partnerships, neutralizing input cost volatility from Dutch and Irish supply fluctuations. EFSA's revised maximum calcium thresholds threaten reformulation costs across existing infant formula portfolios. For New Entrants and Emerging Players: Lead with clinical nutrition white-space in France and Italy, where enteral feeding manufacturers specify bioavailable calcium for osteoporosis and sarcopenia patient formulations. Nordic pharmacy chains offer penetrable clean-label positioning opportunities for "naturally-derived electrolytes" distinct from synthetic salts. Pursue GRAS self-affirmation pathways for streamlined US market entry alongside European base establishment. For Investors and Strategic Acquirers: EFSA's updated maximum calcium fortification guidance reshapes the acquisition landscape by forcing reformulation investments that favor electrodialysis-capable assets. Five-to-ten year viability hinges on membrane technology differentiation rather than commodity mineral extraction. Target processors with installed bipolar membrane capacity and established sports nutrition direct account relationships. Monitor ECHA registration renewal timelines as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Bipolar Membrane Capacity Expansion | Enables 22-24% elemental calcium specifications that legacy nanofiltration cannot achieve for sports hydration brands. |
| Backward Integration into Whey Permeate Supply | Captures cheese production streams from FrieslandCampina and Glanbia processing networks to stabilize input costs. |
| EFSA Compliance Pre-Investment | Pre-empts reformulation costs from revised maximum calcium thresholds across infant formula portfolios. |
| Direct Account Team Deployment | Bypasses distributor intermediaries in UK and Irish markets where vertical integration already controls sixty percent of electrolyte-grade movements. |
| GRAS Self-Affirmation Pathway Execution | Opens FDA-sanctioned US market entry without lengthy petition timelines when scientific consensus documentation is robust. |
Research Methodology
Operator-level perspectives from electrodialysis technicians, ion-exchange process engineers, sports nutrition procurement directors, and clinical nutrition formulators anchored the qualitative base. Secondary validation drew from EFSA novel food evaluation databases, ECHA REACH registration records, FDA GRAS notification filings, and EU dairy hygiene regulation compliance documentation. Bottom-up capacity assessments and top-down demand triangulation converged on segment-level estimates.
Sensitivity analysis tested permeate supply volatility scenarios and EFSA threshold revision impacts across the projection horizon. Segmentation dimensions modeled include product specification tier, end-use application, packaging format, and regional processing hub concentration. CAGRs were derived from electrolyte recovery beverage SKU expansion rates and clinical nutrition patient population trends. Forecast inputs incorporated cheese production volume correlations and membrane technology adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained sports nutrition demand growth or EFSA regulatory stability would require recalibration. Forecasts reflect documented assumptions about permeate supply continuity and electrodialysis technician pipeline adequacy. Practitioners should keep alternative scenarios live as REACH registration renewal conditions and maximum calcium threshold enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Feed Yeast Market
Ingredients
South America Vegetable Oil Market
Ingredients
Bovine Gelatin Market
Ingredients
Pea Hull Fiber Market
Ingredients
Chickpea Protein Market
Ingredients
Specialty Yeast Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Plant Protein Ingredients Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
Casein Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
Murumuru Butter Market
Ingredients
Europe Potato Protein Market
Ingredients
Glucomannan Market
Ingredients
Birch Sap Market
Ingredients
Resistant Starch Market