
 North America Wheat Flour Market | 2026-2036
North America Wheat Flour Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wheat Flour Market Intelligence
Food processing demand is shifting toward clean-label and heritage wheat varieties as commercial bakeries reformulate product lines. Ardent Mills, LLC anchors North American supply through its extensive milling network and grain sourcing infrastructure. General Mills, Inc leverages consumer brand recognition to sustain premium positioning in retail flour segments. King Arthur Flour Co. differentiates through specialty and organic product depth, occupying a defensible niche against commodity competitors.
North America wheat flour consists of finely ground endosperm from hard and soft wheat varieties, typically milled to protein specifications between 8% and 14% depending on intended baking performance. The material serves as a structural base for bread, pasta, confectionery, and processed foods across commercial and industrial applications. All-purpose flour and bread flour dominate volume throughput, though specialty flour commands disproportionate margin pools due to artisanal and dietary-segment premiums. Distribution through supermarkets sustains the largest volume share, while online retail represents the fastest-growing channel as direct-to-consumer baking ingredient sales accelerate.
The FDA enforces Current Good Manufacturing Practices and allergen labeling requirements that directly shape milling facility investments and product formulation transparency. USDA grading standards for wheat protein content and moisture levels determine pricing tiers and end-use eligibility across domestic and cross-border trade. The EPA regulates air emissions from grain handling and milling operations, adding compliance costs that favor larger capitalized processors. Stakeholders must monitor evolving FDA traceability rules and climate-driven wheat yield variability as dual forces that will reshape sourcing geography and facility location decisions.
Market Dynamics
The FDA's updated Food Safety Modernization Act traceability requirements are forcing North American millers to reconfigure facility layouts and invest in lot-tracking infrastructure, compressing margins for smaller operators while favoring capitalized processors with integrated grain sourcing networks.
Growth Catalysts
- Heritage wheat varieties:Commercial bakeries across the U.S. Great Plains are reformulating product lines around Red Fife and Turkey Red wheats, creating pull-through demand for identity-preserved milling infrastructure.
- FSMA Rule 204 compliance deadlines:The FDA's enhanced record-keeping mandates for high-risk foods are accelerating capital deployment into automated traceability systems at regional milling facilities.
- Artisanal bakery cluster expansion:Independent bakeries in Toronto, Montreal, and Portland are consolidating purchasing power through cooperative buying arrangements, sustaining premium flour throughput.
Market Restraints
- Hard red winter wheat price volatility:Climate-driven yield variability across Kansas and Oklahoma is compressing forward-contracting windows and amplifying working capital requirements.
- Great Plains supply concentration:Sixty percent of North American hard wheat originates within a three-state radius, exposing processors to simultaneous drought and logistics disruption risks.
- Gluten-free formulation substitution:Almond flour and cassava starch blends are capturing shelf space in retail baking aisles, constraining all-purpose flour volume growth in household segments.
Strategic Opportunities
- Direct-to-consumer channel development:Subscription-based heritage flour boxes are penetrating underserved households in the U.S. Mountain West and Canadian Prairie provinces.
- USDA Organic certification expansion:Premium pricing for certified organic wheat flour is attracting acreage conversion in North Dakota and Saskatchewan, building captive supply for early certifiers.
- Stone-milled flour co-manufacturing:Partnerships between artisan brands and regional mills are enabling small-batch production without dedicated capital expenditure.
Industry Challenges
- Milling automation technician scarcity:Facility upgrades for FSMA compliance are outpacing the regional supply of technicians trained on integrated pest management and pneumatic conveying systems.
- Identity-preserved supply chain complexity:Segregating heritage and organic wheat streams through elevators, rail, and port infrastructure is multiplying handling costs and contamination risk exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wheat Flour Market |
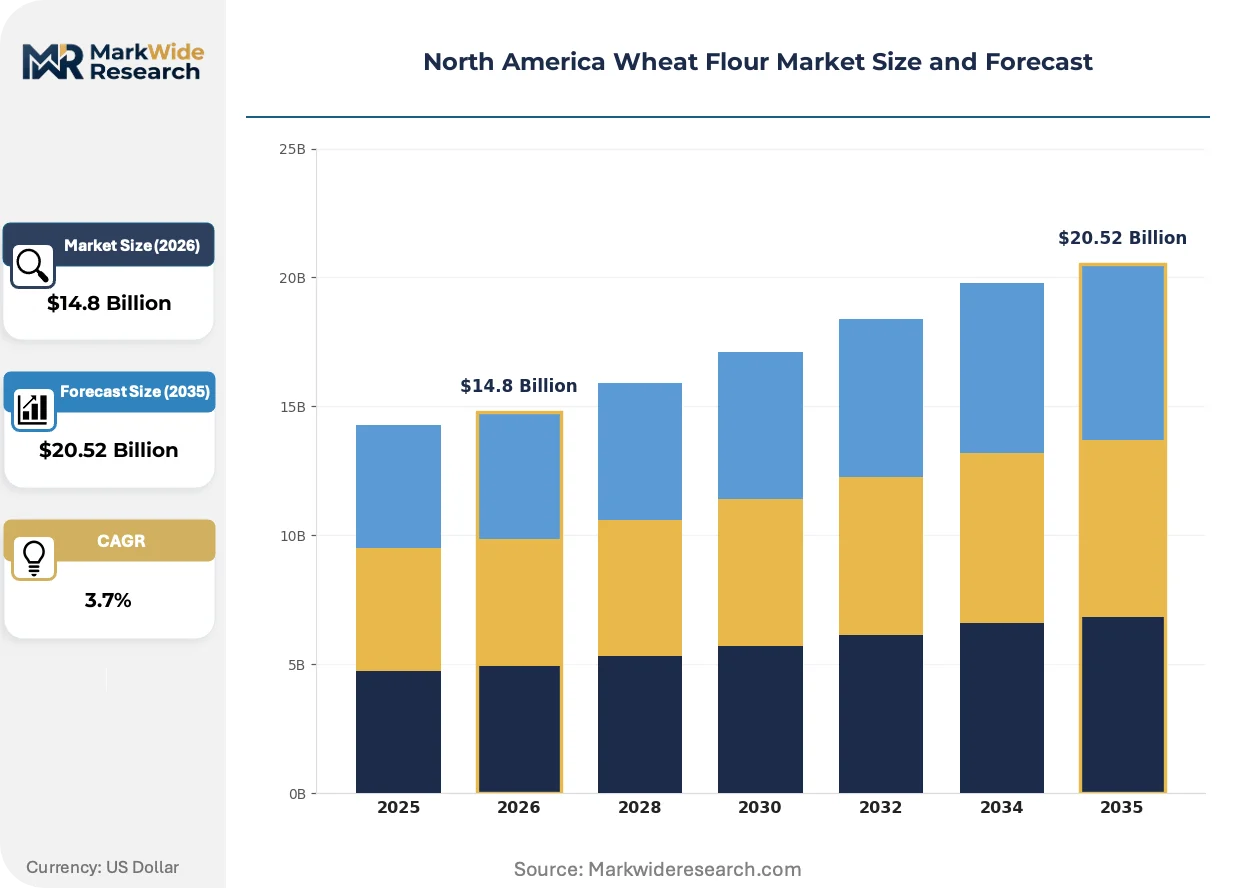
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20.52 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Purpose Flour, Whole Wheat Flour, Bread Flour, Specialty Flour End User: Households, Restaurants, Bakeries, Food Processing Packaging Type: Bags, Bulk, Boxes, Pouches Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | Grain Craft, North Dakota Mill, Ardent Mills, LLC, King Arthur Flour Co., Bob’s Red Mill Natural Foods, General Mills, Inc, Miller Milling, Italgrani USA, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wheat Flour Market Strategic Shifts & Innovations
Automation and transparency requirements are converging to reshape North American milling economics, with technology investments now determining facility viability rather than mere efficiency gains.
Near-infrared spectroscopy for real-time protein and moisture analysis is expanding into mid-sized U.S. and Canadian mills, enabling lot-specific blending adjustments that were previously exclusive to large-scale operations. Regional cooperatives in Minnesota and Manitoba are adopting these systems to maintain elevator premiums. The technology is expanding into identity-preserved traceability, compressing the quality-assurance timeline from days to minutes and reducing rejected shipments.
The FDA's Food Safety Modernization Act Section 204 food traceability rule is mandating granular lot-tracking from farm to retail shelf. North American millers must implement electronic record-keeping systems capable of two-hour response to contamination queries. Hard wheat processors serving industrial bakeries are most affected, with many retrofitting legacy facilities rather than greenfield construction to meet compliance deadlines.
Home baking ingredient purchasing has rotated toward direct-from-mill channels, with specialty flour brands capturing consumer relationships previously held by supermarket intermediaries. Subscription platforms and farm-to-pantry e-commerce are displacing conventional grocery distribution for heritage and organic varieties. This pattern is most visible in Pacific Coast and Northeast U.S. metropolitan markets, where delivery density supports last-mile economics.
North America Wheat Flour Market Segmentation
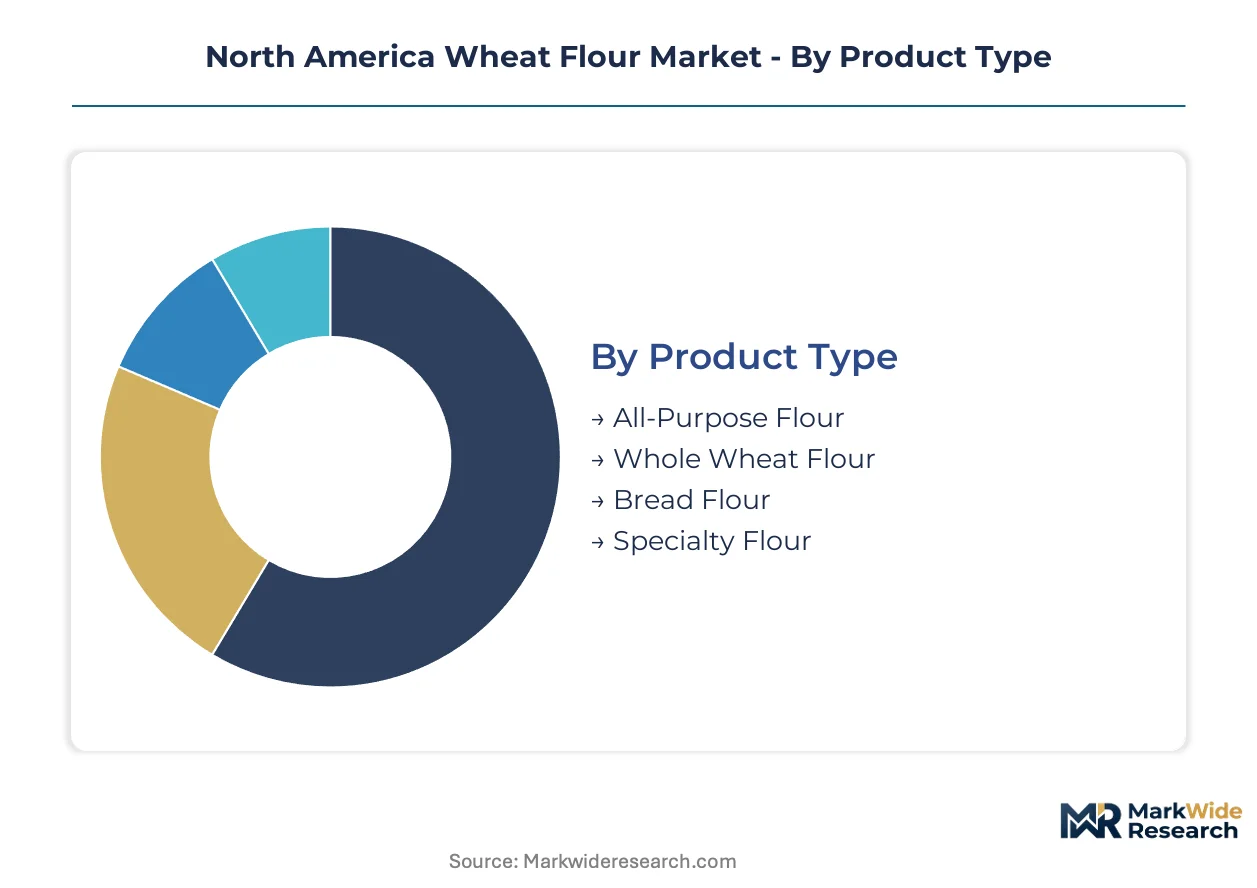
Wheat flour segmentation in North America reflects divergent paths between commodity throughput and specialty differentiation. Protein specifications, end-use performance requirements, and supply chain complexity create distinct margin pools across each dimension.
Product Type:
Customization intensity varies sharply across this category, from standardized commodity milling to identity-preserved heritage processing with full lot segregation.
- All-Purpose Flour:Milled to 10-12% protein from blended hard and soft wheat varieties, this segment serves general baking applications where formulation flexibility outweighs performance optimization. Demand concentrates in household segments across the U.S. Midwest and Canadian Prairie provinces, constrained by gluten-free substitution in retail baking aisles.
- Bread Flour:Higher protein content (12-14%) from hard red spring or hard red winter wheat delivers gluten strength for commercial yeast-leavened products. Demand concentrates in artisanal bakery clusters across Portland, Toronto, and Montreal, driven by cooperative purchasing arrangements that sustain premium throughput.
- Whole Wheat Flour:Contains complete wheat kernel including bran and germ, requiring modified milling flows and shorter shelf-life management.
- Specialty Flour:Identity-preserved varieties including Red Fife, Turkey Red, and certified organic wheats command elevated margins through traceability premiums.
Most installed capacity flows through All-Purpose Flour. Expansion is steepest in Specialty Flour.
End User:
Volume scale inversely correlates with margin capture across this category, with industrial processors driving tonnage and artisanal operators extracting premium pricing.
- Food Processing:Industrial bakeries and prepared food manufacturers specify exact protein and ash content for automated production lines, requiring consistent lot-to-lot performance. Demand concentrates in the U.S. Great Plains states where wheat production clusters, driven by clean-label reformulation pressures from retail brand owners.
- Bakeries:Independent and artisanal operators purchase smaller volumes with higher service requirements, including technical support and custom blending. Demand concentrates in metropolitan markets across the Pacific Coast and Northeast U.S., driven by heritage wheat variety adoption and direct-from-mill purchasing relationships.
- Households:Retail package consumers show channel migration toward online subscription platforms for specialty varieties.
- Restaurants:Foodservice operators balance cost control with menu differentiation through flour selection.
Food Processing commands the largest volume share. Bakeries are expanding most quickly.
Packaging Type:
Handling economics and contamination risk exposure separate this category, with food safety compliance costs favoring integrated packaging operations.
- Bulk:Railcar and tanker shipments dominate industrial procurement, minimizing per-unit handling costs while requiring dedicated receiving infrastructure. Demand concentrates at Ardent Mills and General Mills facilities serving large-scale commercial bakeries, driven by FSMA Rule 204 traceability mandates that favor capitalized processors with automated lot-tracking systems.
- Bags:Multi-wall paper and woven polypropylene formats serve mid-scale food processors and foodservice distributors with moderate volume requirements and storage flexibility.
- Boxes:Corrugated containers with inner liners protect specialty and organic flours during direct-to-consumer shipment.
- Pouches:Flexible retail formats target household convenience and portion control in premium positioning.
Bulk packaging carries the highest tonnage. Boxes are gaining share fastest through e-commerce channel development.
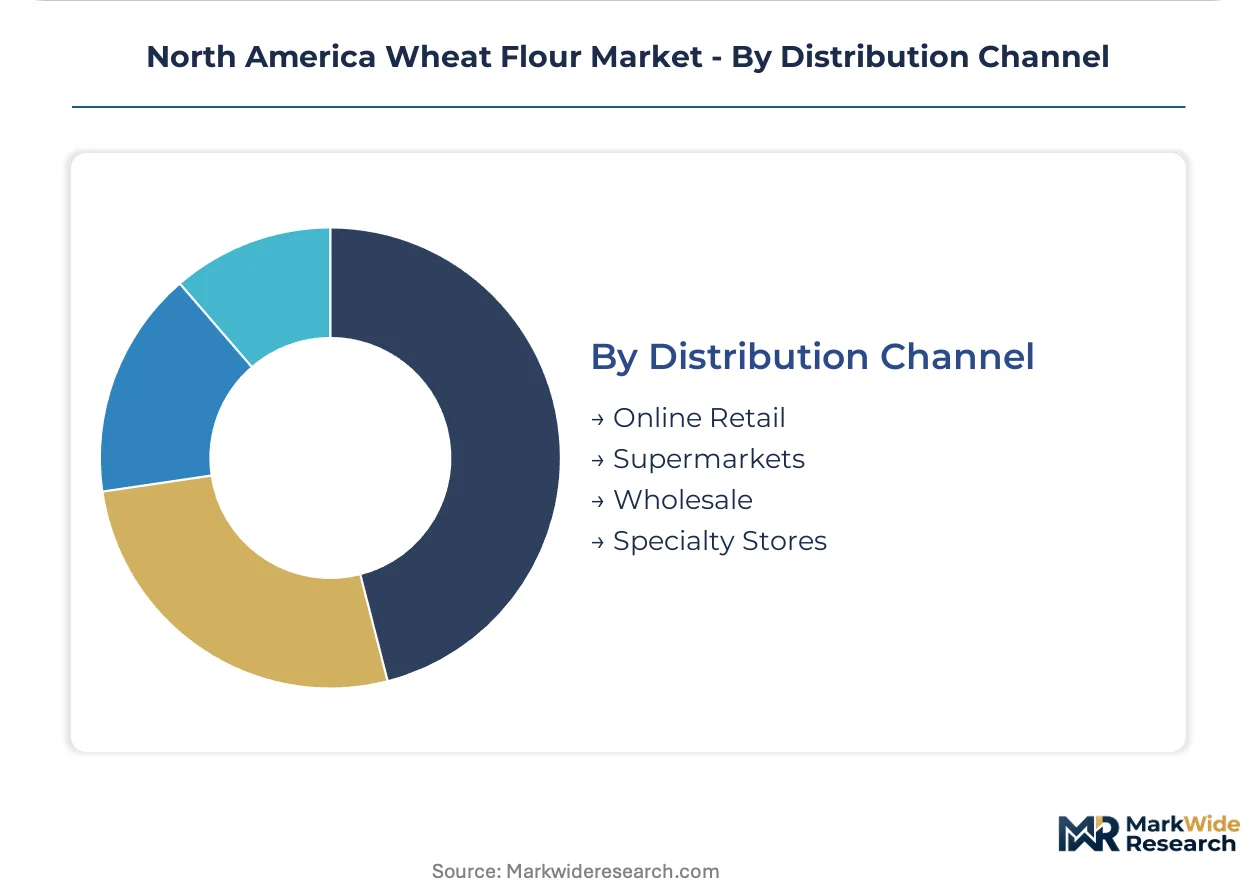
Distribution Channel:
Customer relationship ownership and margin retention vary dramatically, with intermediaries ceding ground to direct engagement models.
- Supermarkets:Traditional retail grocery maintains the largest volume position through established shelf placement and promotional programming. Demand concentrates in conventional all-purpose and bread flour segments across the U.S. South and Midwest, constrained by gluten-free aisle expansion and center-store traffic declines.
- Online Retail:Direct-to-consumer platforms and subscription services are displacing conventional intermediaries for heritage and organic varieties. Demand concentrates in Pacific Coast and Northeast U.S. metropolitan markets, driven by delivery density supporting last-mile economics and consumer willingness to pay traceability premiums.
- Wholesale:Distributor networks serve foodservice and smaller food processors with consolidated procurement and logistics.
- Specialty Stores:Natural food retailers and farm-direct outlets cater to organic and heritage variety enthusiasts.
Supermarkets retain the largest installed throughput. Online Retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millers in North America are relocating processing capacity across state and provincial lines to exploit gaps in FSMA compliance costs and organic certification infrastructure. This regulatory arbitrage favors operators with capital to absorb traceability system investments while smaller facilities face margin compression.
United States
The Great Plains states of Kansas, Oklahoma, and North Dakota concentrate hard red winter and spring wheat production, driving demand for high-protein bread flour milling. FDA enforcement of FSMA Rule 204 traceability mandates is accelerating capital deployment into automated lot-tracking systems at regional facilities. Artisanal bakery clusters in Portland, Oregon and Brooklyn, New York are consolidating purchasing power through cooperative arrangements, sustaining premium throughput for heritage varieties.
Canada
Prairie provinces Saskatchewan and Manitoba are expanding certified organic wheat acreage, building captive supply chains for early certifiers seeking premium positioning. Health Canada and the Canadian Food Inspection Agency enforce parallel traceability requirements that favor integrated grain sourcing networks with cross-border compliance capabilities. Toronto and Montreal bakeries are driving identity-preserved demand through direct-from-mill purchasing relationships that bypass traditional distributor intermediaries.
Mexico
Industrial bakery growth in Mexico City and Guadalajara is pulling U.S. and Canadian hard wheat imports for tortilla and bread production, though domestic wheat cultivation remains limited. COFEPRIS food safety regulations are gradually converging with FDA standards, creating compliance alignment opportunities for North American integrated processors. Baja California and Sonora states are emerging as transshipment corridors for U.S. grain moving to Pacific Coast Latin American markets.
North America Wheat Flour Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated milling networks dominating industrial procurement while artisan-focused brands capture premium retail positioning. The market exhibits tiered consolidation: capitalized multi-facility operators serving food processing customers coexist with regional stone mills and direct-to-consumer specialty brands. Three archetypes define competitive positioning: scale-driven commodity processors, heritage-focused niche specialists, and vertically integrated grain-to-retail operators. Capacity expansion through automated facility upgrades and strategic partnerships for identity-preserved supply chains represent the dominant competitive moves.
Among North American integrated millers, Ardent Mills, LLC and General Mills, Inc exemplify scale-driven commodity processing with extensive grain sourcing infrastructure and multi-regional distribution networks. King Arthur Flour Co. occupies a specialist position within the heritage and organic tier, representing the archetype of brand-differentiated premium positioning built on product depth and consumer recognition rather than volume throughput.
| Leading Market Players |
|---|
| Grain Craft |
| North Dakota Mill |
| Ardent Mills, LLC |
| King Arthur Flour Co. |
| Bob's Red Mill Natural Foods |
| General Mills, Inc |
| Miller Milling |
| Italgrani USA |
| Archer Daniels Midland Company |
| Others |
Cost & Logistics Intelligence
Backward integration into grain sourcing networks anchors both supply security and pricing power for North American millers confronting FSMA compliance cost dispersion. This structural choice separates capitalized operators capable of absorbing traceability infrastructure investments from smaller facilities facing margin compression.
Pricing Analysis
Distributor margin capture varies sharply across channel tiers, with direct-to-mill relationships commanding 15-25 point spreads below supermarket retail markups. Three-tier pricing structure across premium heritage, standard commercial, and economy commodity levels reflects protein specification and certification grade differentiation. Pricing pressure stems from climate-driven wheat input volatility across Kansas and Oklahoma production zones. Food processing buyers exhibit highest price sensitivity due to volume scale and formulation flexibility, while artisanal bakeries accept premium positioning for identity-preserved traceability.
Supply Chain Analysis
Direct-to-bakery channels handle heritage variety demand across Portland, Toronto, and Montreal metropolitan clusters. Geographic supply concentration centers on the U.S. Great Plains states, Canadian Prairie provinces, and limited Mexican cultivation zones. Raw material flows draw from hard red winter wheat, hard red spring wheat, and certified organic acreage expansion. Single-source vulnerability runs through Great Plains drought exposure and rail logistics chokepoints at Chicago and Kansas City interchanges. Distribution runs through bulk rail for industrial processors, bagged formats for foodservice, and boxed direct-to-consumer for specialty e-commerce.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America wheat flour market functions as a regulatory compounder where FSMA Rule 204 compliance deadlines are accelerating capital deployment into traceable milling infrastructure and reshaping competitive viability thresholds.
For Market Incumbents: Lock in identity-preserved supply chain control through elevator network partnerships and organic certification acreage commitments. Defensive positioning requires automated lot-tracking system deployment ahead of enforcement windows, while gluten-free substitution threats in retail channels demand heritage variety portfolio depth to sustain premium throughput.
For New Entrants and Emerging Players: Begin with direct-to-consumer subscription positioning in underserved Mountain West and Canadian Prairie households where delivery density economics now support last-mile profitability. The most penetrable white space sits in stone-milled co-manufacturing partnerships that enable small-batch production without dedicated capital expenditure, leveraging existing FSMA-compliant regional facilities.
For Investors and Strategic Acquirers: Roll-up economics work for regional stone mills with established heritage brand recognition because compliance cost dispersion is forcing sub-scale facility exits at favorable multiples. Long-term viability hinges on organic certification infrastructure and cross-border Canadian-U.S. operational capabilities. The signal to watch is USDA organic acreage conversion velocity in North Dakota and Saskatchewan as captive supply formation indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FSMA Traceability Infrastructure Deployment | Automated lot-tracking systems at regional facilities satisfy FDA two-hour query response mandates. |
| Heritage Wheat Identity-Preserved Supply Chain | Red Fife and Turkey Red segregation through elevators and rail enables premium positioning. |
| Direct-to-Consumer Channel Development | Subscription platforms bypass supermarket intermediaries for heritage and organic variety distribution. |
| Stone-Milled Co-Manufacturing Partnerships | Artisan brands access small-batch production without dedicated capital expenditure commitments. |
| USDA Organic Certification Expansion | North Dakota and Saskatchewan acreage conversion builds captive supply for early certifiers. |
Research Approach
Multiple input streams — milling facility operators, grain elevator procurement managers, artisan bakery purchasing coordinators, and food processing formulation leads — were reconciled against USDA crop reports, FDA compliance guidance documents, Canadian Grain Commission trade statistics, and rail logistics carrier disclosures. Bottom-up volume modeling across protein specifications and packaging formats was cross-validated through top-down market sizing from trade association production surveys.
Historical shipment patterns were weighted against panel input from regional millers regarding capacity utilization and capital expenditure intentions across the projection horizon. Segmentation dimensions modeled include product type tier, end-use application, packaging format, and distribution channel structure. CAGRs were derived through trend extrapolation adjusted for regulatory compliance cost phasing and organic acreage conversion trajectories. Wheat yield variability assumptions and FSMA enforcement timeline uncertainty were incorporated as scenario inputs.
Several conditions sit outside the modeled scope, including extreme climate events beyond historical yield variance bands and trade policy disruptions affecting cross-border grain flows. Forecasts reflect assumptions regarding compliance deadline adherence and consumer willingness-to-pay premiums for traceability. Periodic stress-testing of base assumptions is recommended given climate-driven production volatility and evolving FDA enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Africa Wheat Flour Market
Grains
Global Flour Market
Grains
Global Precooked Corn Flour Market
Grains
Green Pea Grits Market
Grains
Rolled Oats Market
Grains
Brazil Maize Market
Grains
Cornmeal Market
Grains
IQF Rice Market
Grains
Soya Flour Market
Grains
Corn Gluten Feed Market
Grains
Global Maize Market
Grains
Asia-Pacific Guar Market
Grains
Europe Maize Market
Grains
Wild Rice Market
Grains
Gluten Free Ancient Grain Market
Grains
Organic Rice Market