
 Global Zinc Phosphate Market | 2026-2036
Global Zinc Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Zinc Phosphate Market Intelligence
The qualification cycle for ISO 12944 certification is unwinding the traditional supplier base for anti-corrosive pigments. This technical barrier creates openings for specialists with documented performance data. Heubach leverages its extensive portfolio of anti-corrosive solutions to serve multinational clients in regulated industries. SNCZ, in contrast, specializes in developing modified zinc phosphate grades that meet niche performance requirements for marine and industrial coatings.
Zinc phosphate is an inorganic chemical compound, Zn3(PO4)2, used to create a crystalline conversion coating on steel, aluminum, and other metallic substrates. This coating layer provides a porous base for subsequent painting or finishing, significantly enhancing corrosion resistance and paint adhesion. The paints and coatings sector represents the largest application, consuming the bulk of production volume for metal surface treatment. Demand for modified zinc phosphate products is growing as end-users in the aerospace and heavy machinery industries seek high-performance, chromium-free alternatives.
Regulatory frameworks are a primary market catalyst, with the European Union's REACH and the US EPA actively restricting hexavalent chromium-based inhibitors. These rules compel coatings formulators and metal fabricators in Germany and the United States to adopt safer alternatives for corrosion protection. Consequently, suppliers face a strategic choice: either enhance standard zinc phosphate efficacy or pivot toward developing next-generation, metal-free inhibitor technologies. This decision will define future market leadership and investment priorities.
Market Dynamics
The primary force shaping the zinc phosphate market is the regulatory-driven displacement of hexavalent chromium. This strategic shift, mandated by frameworks like the European Union's REACH, is compelling a fundamental re-evaluation of corrosion protection chemistry across multiple industries.
Growth Catalysts
- Regulatory Mandates:The European Union's REACH regulation continues to tighten restrictions on hexavalent chromium, compelling coatings formulators to adopt safer and compliant alternatives like zinc phosphate for metal protection.
- Aerospace Demand:High-performance material requirements from aerospace manufacturers for lightweight, chromium-free corrosion inhibitors are creating a significant pull for advanced and modified zinc phosphate grades.
- Industrialization in China:Demand for protective coatings is concentrating in China's heavy machinery and infrastructure sectors, driving high-volume consumption of zinc phosphate for steel and equipment fabrication.
Market Restraints
- Substitution from Organics:The development of advanced metal-free organic inhibitors presents a significant substitution threat, offering competitive performance in certain less-demanding applications and challenging zinc phosphate's market position.
- Performance Gaps:In highly aggressive saline or chemical environments, standard zinc phosphate grades do not consistently match the historical performance benchmarks set by chromate-based systems, limiting adoption for certain critical uses.
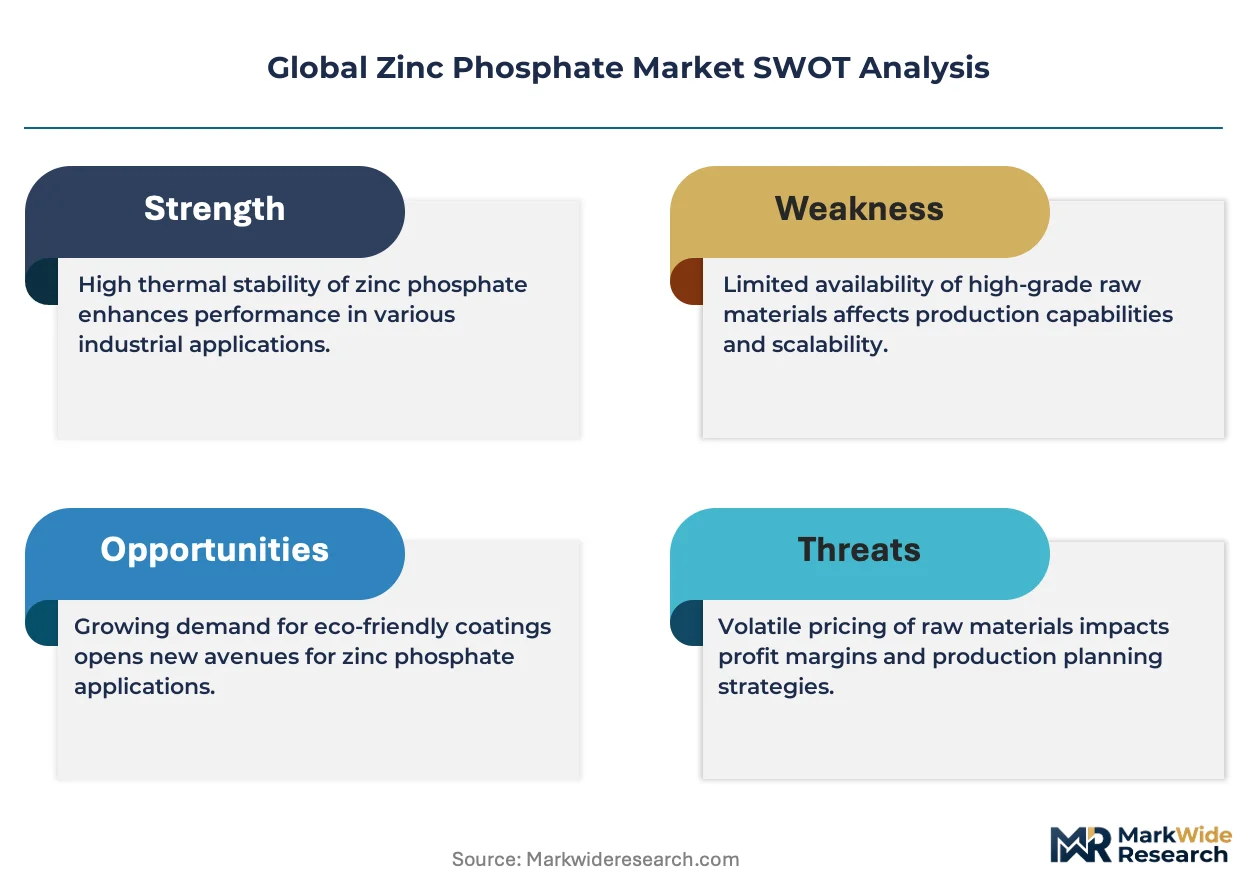
- Raw Material Volatility:Fluctuations in the price and availability of key precursors, specifically high-purity zinc oxide and phosphoric acid, introduce cost instability for pigment manufacturers and can impact final product pricing.
Strategic Opportunities
- Hybrid Pigment Development:Combining zinc phosphate with nanomaterials such as functionalized silica or graphene oxide offers a pathway to create next-generation hybrid pigments with superior barrier and inhibitive properties.
- Modified Grades for EVs:Developing specialized zinc phosphate formulations for the corrosion protection of electric vehicle battery enclosures and chassis components represents a significant new application area.
- Expansion in Southeast Asia:As nations in Southeast Asia begin to adopt stricter environmental regulations mirroring those in Europe, an opportunity emerges to introduce chromium-free coating systems to underpenetrated industrial markets.
Industry Challenges
- Certification Timelines:The lengthy and expensive qualification cycle for anti-corrosive pigments under standards like ISO 12944 creates a significant operational hurdle, delaying the market entry of new formulations.
- Formulation Complexity:A lack of global standardization for modified zinc phosphate grades forces multinational coating producers to manage complex, region-specific formulations, increasing R&D and supply chain costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Zinc Phosphate Market |
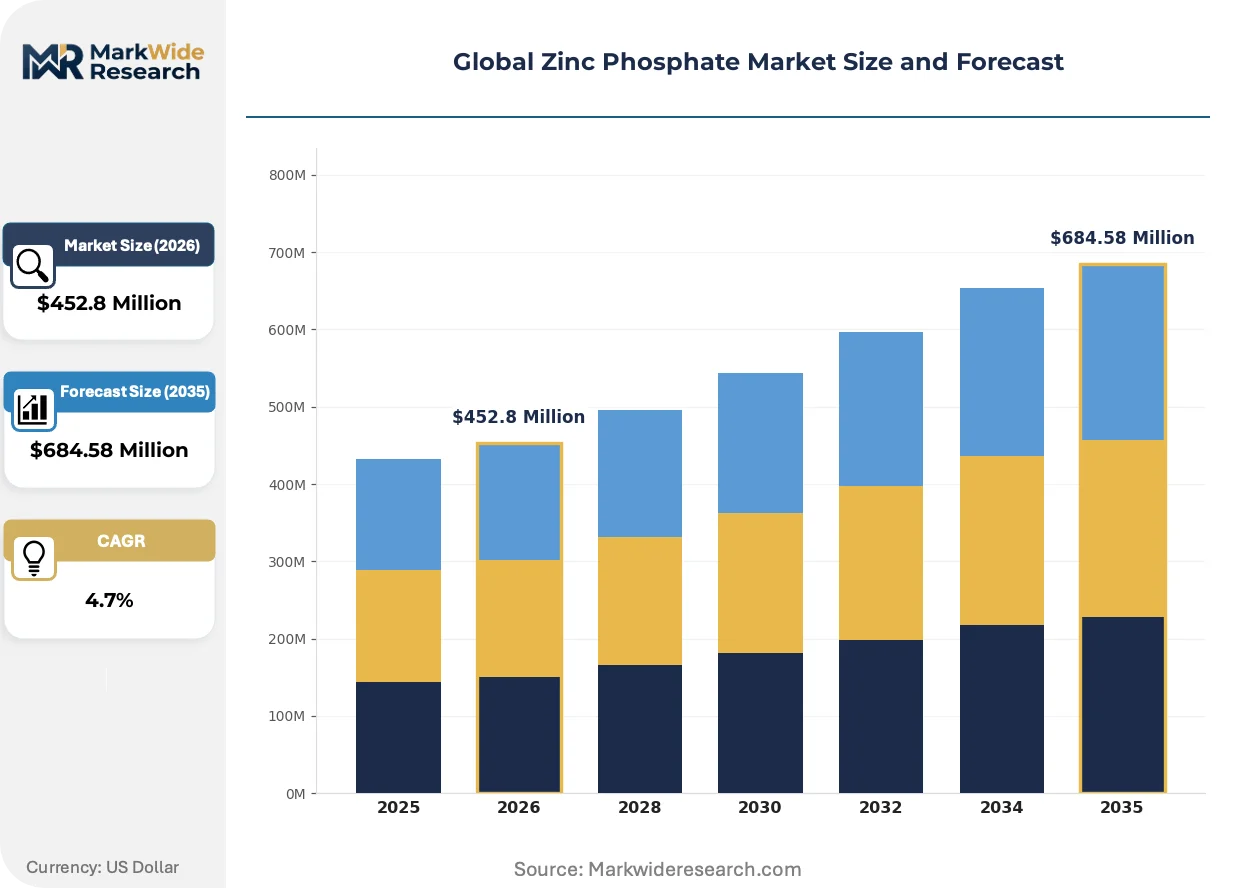
| Market Size in 2026 | $452.8 Million |
| Market Size in 2035 | $684.58 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inorganic Zinc Phosphate, Nano Zinc Phosphate, Modified Zinc Phosphate, Micro Zinc Phosphate Application: Corrosion Protection, Paints & Coatings, Adhesives, Catalyst Additives, Metal Surface Treatment End Use Industry: Defense Contractors, Aerospace Manufacturers, Heavy Machinery Fabricators, Marine Equipment Suppliers Packaging Type: Bulk Bags, Fiber Drums, Paper Bags, Plastic Containers |
| Companies Covered | WPC Technology, Hanchang Industries, SNCZ, Noelson Chemicals, Xinsheng Chemicals, Heubach, Nubiola, Numinor, Delaphos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Zinc Phosphate Market Strategic Shifts & Innovations
The market is defined by a pivot toward performance-driven chemistry, spurred by regulatory pressures and the specific demands of advanced manufacturing. This evolution prioritizes documented efficacy and specialized formulations over traditional, commodity-grade materials.
Modified zinc phosphate, incorporating elements like calcium or strontium, provides tailored inhibitive properties for specific substrates and environments. End-users in the marine and coil coatings sectors are adopting these specialized grades to achieve performance targets that standard zinc phosphate cannot meet. This move toward specialization is fragmenting the market, shifting it from a single commodity product to a portfolio of niche, performance-differentiated solutions.
The European Union's REACH framework, with its stringent restrictions on hexavalent chromium, acts as a powerful market catalyst. This regulation forces a complete portfolio requalification for coatings suppliers serving the automotive and industrial sectors in member states like Germany. Consequently, research and development investment is accelerating toward validating and scaling production of effective chromium-free alternatives, with zinc phosphate being a primary candidate.
A clear shift toward data-driven supplier qualification is altering procurement dynamics. This change is displacing legacy purchasing relationships, especially among formulators of industrial and aerospace coatings. Buyers now require extensive performance data, including results from standardized tests like salt spray exposure, to validate a pigment's efficacy before it is approved, a trend most visible in North America and Europe.
Global Zinc Phosphate Market Segmentation
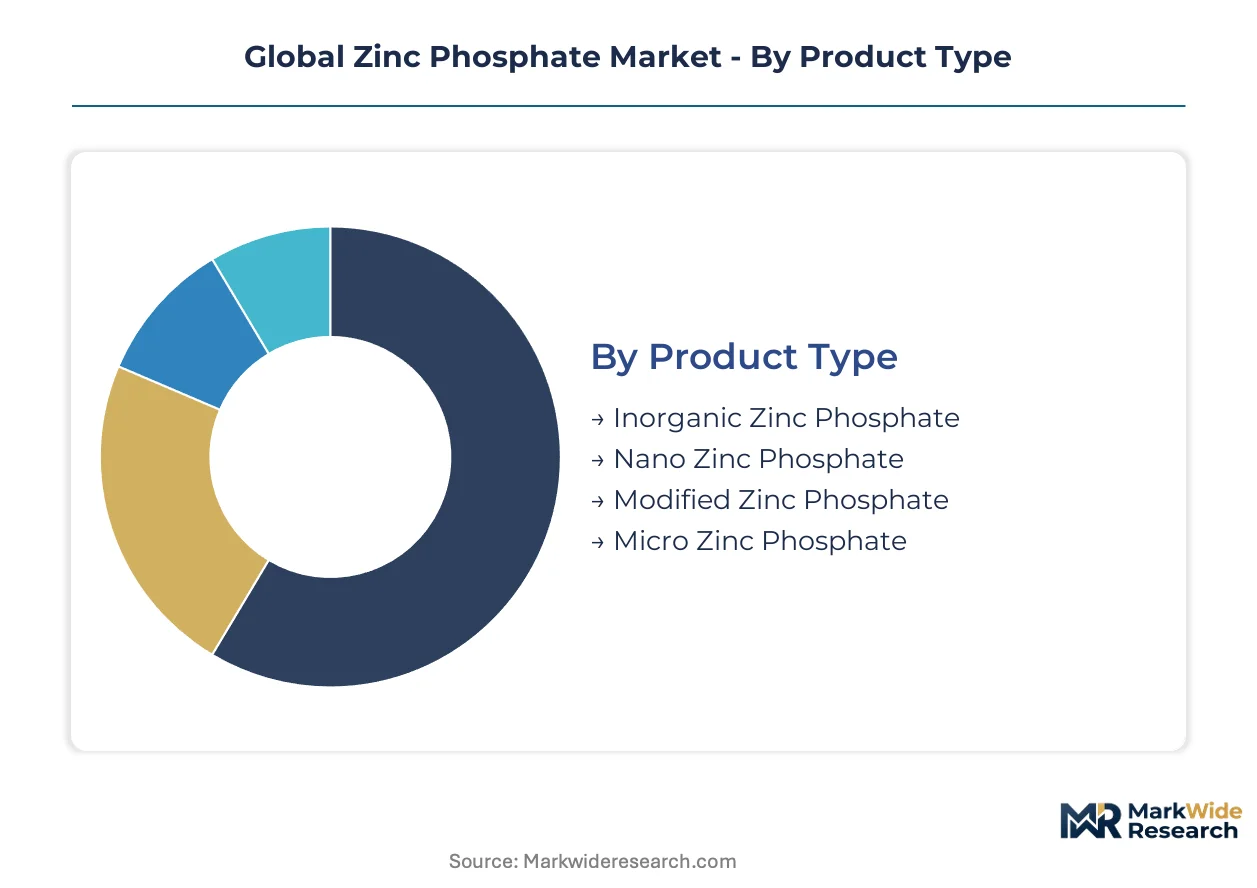
The zinc phosphate market's segmentation reveals the diverse chemical compositions, application methods, and end-user requirements driving product innovation. Understanding these distinct segments allows suppliers to align their portfolios with specific performance needs and regulatory compliance mandates across various industries.
Product Type:
Margin pools within product types are often highest for specialized formulations addressing stringent performance or regulatory requirements.
- Inorganic Zinc Phosphate:This traditional compound, Zn3(PO4)2, serves as a fundamental anti-corrosive pigment in primer and topcoat formulations. General industrial coatings sector extensively utilizes this product, driven by cost-effectiveness and broad compatibility with various binder systems.
- Modified Zinc Phosphate:These grades incorporate additional elements like calcium or strontium to enhance inhibitive properties or improve solubility for specific applications. Aerospace manufacturers and marine equipment suppliers seek these tailored solutions for improved performance in harsh environments.
- Nano Zinc Phosphate:Ultrafine particle sizes offer enhanced surface area and improved dispersion, contributing to superior barrier properties in advanced coating systems.
- Micro Zinc Phosphate:Standard particle size grades provide foundational corrosion resistance for high-volume applications in automotive and construction coatings.
The dominant share belongs to Inorganic Zinc Phosphate, while Modified Zinc Phosphate is closing the gap fastest.
Application:
The market's application focus highlights where zinc phosphate delivers its primary value proposition across industrial processes.
- Paints & Coatings:This segment represents the largest consumption volume, utilizing zinc phosphate as a primary anti-corrosive pigment in primers and topcoats for metal substrates. Demand is particularly strong in China's industrial sector for infrastructure and machinery protection.
- Metal Surface Treatment:Zinc phosphate forms a crystalline conversion coating on steel and aluminum, enhancing paint adhesion and providing initial corrosion resistance. Automotive and appliance manufacturers widely adopt this process for component preparation.
- Corrosion Protection:Zinc phosphate acts as an active inhibitor, forming a protective layer on metal surfaces to prevent rust and degradation.
- Adhesives:Certain formulations incorporate zinc phosphate as a filler or a corrosion-inhibiting additive in specialized adhesive systems.
- Catalyst Additives:A niche application where zinc phosphate contributes to specific chemical reactions or acts as a component in catalyst formulations.
Paints & Coatings holds the largest volume, with Metal Surface Treatment exhibiting significant expansion.
End Use Industry:
Customer type differentiation reveals the varied performance and regulatory demands that shape product development and supplier relationships.
- Aerospace Manufacturers:This industry requires high-performance, chromium-free corrosion inhibitors for aircraft structures and components, driving demand for advanced and modified zinc phosphate grades. Regulatory compliance with standards like REACH is a critical purchasing criterion for airframe builders.
- Heavy Machinery Fabricators:Producers of construction equipment, agricultural machinery, and industrial vehicles consume substantial volumes of zinc phosphate for durable protective coatings. China's advanced manufacturing sector drives much of this demand for equipment destined for demanding operational environments.
- Defense Contractors:Military applications require robust corrosion protection for vehicles, weaponry, and infrastructure, often under extreme conditions.
- Marine Equipment Suppliers:Shipbuilders and offshore platform manufacturers seek specialized zinc phosphate formulations for protection against aggressive saline environments.
Heavy Machinery Fabricators represent the largest consumer base, while Aerospace Manufacturers are driving innovation in high-performance grades.
Packaging Type:
Supply concentration for packaging types reflects logistical efficiencies and scale requirements for different end-user operations.
- Bulk Bags:Large industrial users, such as major coatings manufacturers and metal treatment facilities, procure zinc phosphate in bulk bags for high-volume processing. This packaging type optimizes shipping costs and reduces handling frequency.
- Fiber Drums:Intermediate-volume users and specialized formulators often receive zinc phosphate in fiber drums, balancing ease of handling with sufficient quantity for batch production. These drums offer protection and stackability.
- Paper Bags:Smaller quantities for specific formulations or smaller-scale operations are typically supplied in multi-ply paper bags.
- Plastic Containers:Lab-scale quantities or highly specialized, moisture-sensitive grades may be packaged in sealed plastic containers.
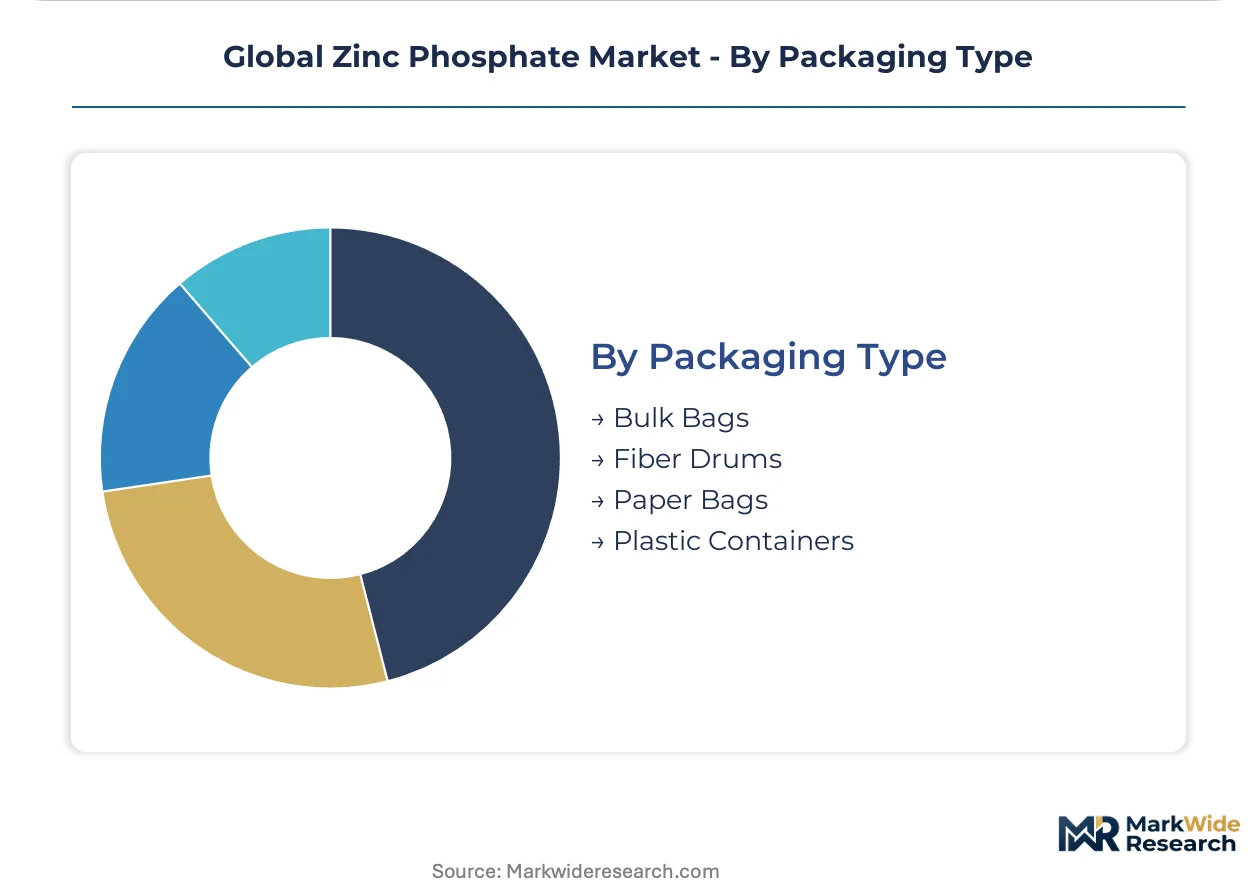
Bulk Bags account for the majority of the market's volume, with Fiber Drums seeing consistent uptake from mid-sized operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration for zinc phosphate products centers significantly in regions undergoing rapid industrialization and those with stringent environmental regulations. Demand for high-performance coatings in advanced manufacturing sectors drives specific requirements for modified zinc phosphate grades. Regulatory shifts in major economies compel a re-evaluation of corrosion protection chemistries.
China
China's heavy machinery and infrastructure sectors generate substantial demand for protective coatings. The country's GB standards increasingly align with international environmental protocols, pushing for chromium-free alternatives. Industrial clusters in the Yangtze River Delta actively integrate zinc phosphate into advanced manufacturing processes for steel and equipment fabrication.
Germany
German automotive and industrial sectors require high-performance, chromium-free corrosion inhibitors for metal components. The European Union's REACH regulation directly impacts coatings formulators and metal fabricators in Germany. North Rhine-Westphalia, a key industrial region, sees significant investment in validating and scaling effective zinc phosphate formulations.
United States
Aerospace and defense contractors in the United States seek advanced zinc phosphate solutions for critical corrosion protection. The US EPA's restrictions on hexavalent chromium compel manufacturers to adopt safer alternatives. The Pacific Northwest, with its robust aerospace manufacturing base, focuses on qualifying new chromium-free coating systems.
India
India's expanding construction and automotive industries drive consumption of zinc phosphate for foundational corrosion resistance. The Bureau of Indian Standards (BIS) promotes material specifications that encourage local production and quality control. Maharashtra, a major industrial hub, witnesses increased adoption of zinc phosphate in various metal treatment applications.
Vietnam
Vietnam's growing manufacturing sector, particularly in electronics and automotive components, represents an emerging market for zinc phosphate. The nation's environmental agencies are gradually introducing stricter regulations, mirroring European standards. Industrial zones around Ho Chi Minh City are adopting chromium-free coating technologies for export-oriented production.
Global Zinc Phosphate Market Key Industry Players
Player mix skews toward specialized chemical manufacturers and established pigment producers, catering to diverse industrial needs. The market exhibits a tiered structure, with a few large players offering broad portfolios alongside numerous niche specialists. Key competitive moves include portfolio diversification into modified grades and strategic partnerships for technology development.
Specialized pigment manufacturers like SNCZ focus on developing modified zinc phosphate grades that address niche performance requirements for marine and industrial coatings. Heubach, a global chemical company, leverages its extensive portfolio of anti-corrosive solutions to serve multinational clients in regulated industries. Noelson Chemicals, an Asia-based producer, exemplifies the regional suppliers scaling production to meet industrial demand in rapidly growing markets.
| Leading Market Players |
|---|
| WPC Technology |
| Hanchang Industries |
| SNCZ |
| Noelson Chemicals |
| Xinsheng Chemicals |
| Heubach |
| Nubiola |
| Numinor |
| Delaphos |
| Others |
Cost & Logistics Intelligence
Hexavalent chromium displacement reshapes zinc phosphate supply geography and pricing economics, as formulators pivot towards compliant alternatives like modified zinc phosphate, impacting raw material sourcing and end-product costs.
Pricing Analysis
Cost-plus contract patterns, often indexed to zinc oxide and phosphoric acid, dominate long-term offtake agreements. Price differentiation stems from purity grade, ISO 12944 certification, and volume scale for large industrial buyers. Upward pricing pressure arises from raw material volatility and the significant R&D investment required for developing advanced modified grades. General industrial coatings segment buyers exhibit high price sensitivity, while aerospace manufacturers and marine equipment suppliers prioritize performance over cost for specialized formulations.
Supply Chain Analysis
Single-source vulnerabilities for high-purity zinc oxide and phosphoric acid represent a critical chokepoint in the zinc phosphate supply chain. Geographic supply concentrates in China, India, and European chemical manufacturing hubs like Germany. Key raw material dependencies include high-grade zinc metal and industrial phosphoric acid. Raw material price volatility poses a structural risk to pigment manufacturers. Downstream distribution runs through direct sales channels to major coatings companies and specialized chemical distributors serving smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The zinc phosphate market offers a service-attach opportunity, with technical support and advanced formulation consulting services expanding faster than primary pigment sales.
For Market Incumbents: Fortify market share by investing in hybrid pigment development, combining zinc phosphate with nanomaterials for superior performance. Acquire niche technology providers specializing in advanced chromium-free formulations to counter substitution threats from organic inhibitors. Expand production capacity for modified zinc phosphate grades in regions with stringent regulations, leveraging strategic partnerships with major coatings formulators to accelerate ISO 12944 certification cycles.
For New Entrants and Emerging Players: Certification fast-track programs, particularly for ISO 12944, offer a pathway to market entry by demonstrating documented performance. Target specialized applications like electric vehicle battery enclosures or underpenetrated industrial markets in Southeast Asia. A go-to-market strategy focused on delivering tailored, chromium-free solutions with extensive performance data for specific substrates will differentiate offerings from commodity producers.
For Investors and Strategic Acquirers: The market sits at a regulatory-driven growth phase that favors specialist chemical manufacturers with proprietary R&D and strong intellectual property. Acquisition targets should include mid-sized firms possessing advanced modified zinc phosphate technologies or robust distribution networks in emerging industrial economies. The acceleration of new product approvals under REACH or US EPA serves as a key signal to watch, indicating broader market acceptance of chromium-free solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Pigment Development | Creates superior barrier and inhibitive properties for advanced coating systems. |
| REACH Compliance Investment | Secures market access in Europe for chromium-free zinc phosphate formulations. |
| EV Battery Formulation | Captures specialized demand from the rapidly expanding electric vehicle sector. |
| Southeast Asia Market Entry | Leverages environmental regulation shifts in emerging industrial economies. |
| ISO 12944 Certification Acceleration | Validates performance data to overcome market entry barriers for new products. |
Research Approach
The analysis maps anti-corrosive pigments, metal surface treatments, and industrial coatings sub-sectors, each validated through primary interviews with coatings formulators, heavy machinery fabricators, and aerospace engineers. Secondary research involved reviewing EU REACH documents, US EPA regulations, industrial association reports, and customs trade data. A combination of bottom-up data aggregation and top-down market sizing ensures comprehensive coverage.
Output validation against external benchmarks confirmed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end-use industry, packaging type, and regional regulatory alignment. Compound annual growth rates were derived from historical trends, projected regulatory impacts, and anticipated technological adoption rates. Forecast inputs incorporated raw material pricing forecasts, industrial production indices, and environmental policy timelines.
Decision-makers should treat outputs as directional under current regulatory and technological adoption base assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions regarding the pace of chromium-free alternative adoption and raw material stability. Practitioners should keep alternative scenarios live as geopolitical events or unforeseen supply chain disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
China Collagen Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Lauramidopropyl Betaine Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Global Quaternary Ammonium Compounds Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Methyl Anthranilate Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market