

3-Hydroxyphenyl Phosphinyl Propanoic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market Insights
A wide capability gap in phosphorous compound purification is redrawing competitive tiers among Chinese manufacturers. Shanghai Changgen Chemical Technology leverages proprietary extraction protocols to sustain premium-grade output for pharmaceutical clients. Hubei Wande Chemical anchors its position through backward integration into raw phosphorous feedstock. Yingkou Sanzheng New Technology Chemical Industry competes on volume scale in agrochemical-grade intermediates.
3-Hydroxyphenyl Phosphinyl Propanoic Acid is an organophosphorus carboxylic acid featuring a phosphinyl group bonded to a phenyl ring with a terminal propanoic acid functionality, typically synthesized through Michaelis-Arbuzov rearrangement or phosphine oxide oxidation routes. The compound serves primarily as a reactive intermediate and ligand precursor in pharmaceutical and agrochemical synthesis pathways. Purified compound grades command concentrated margin pools due to stringent pharmaceutical manufacturer specifications, while derivative formulations represent the fastest-expanding segment as custom synthesis houses seek ready-to-functionalize building blocks. Raw material and intermediate categories remain mature volume channels with thinner spreads, though polymer stabilizer applications in specialty chemicals are gaining traction as flame-retardant additive demand diversifies.
China's SAMR oversees chemical substance registration under evolving GB standards, while the EU ECHA administers REACH compliance for phosphorous compound imports into European pharmaceutical supply chains. FDA oversight of drug master files and starting material qualifications shapes market access for suppliers targeting US pharmaceutical manufacturers. Stakeholders must monitor regulatory divergence between Chinese national standards and REACH annex requirements, as compliance costs will determine which purification tiers remain economically viable across export corridors.
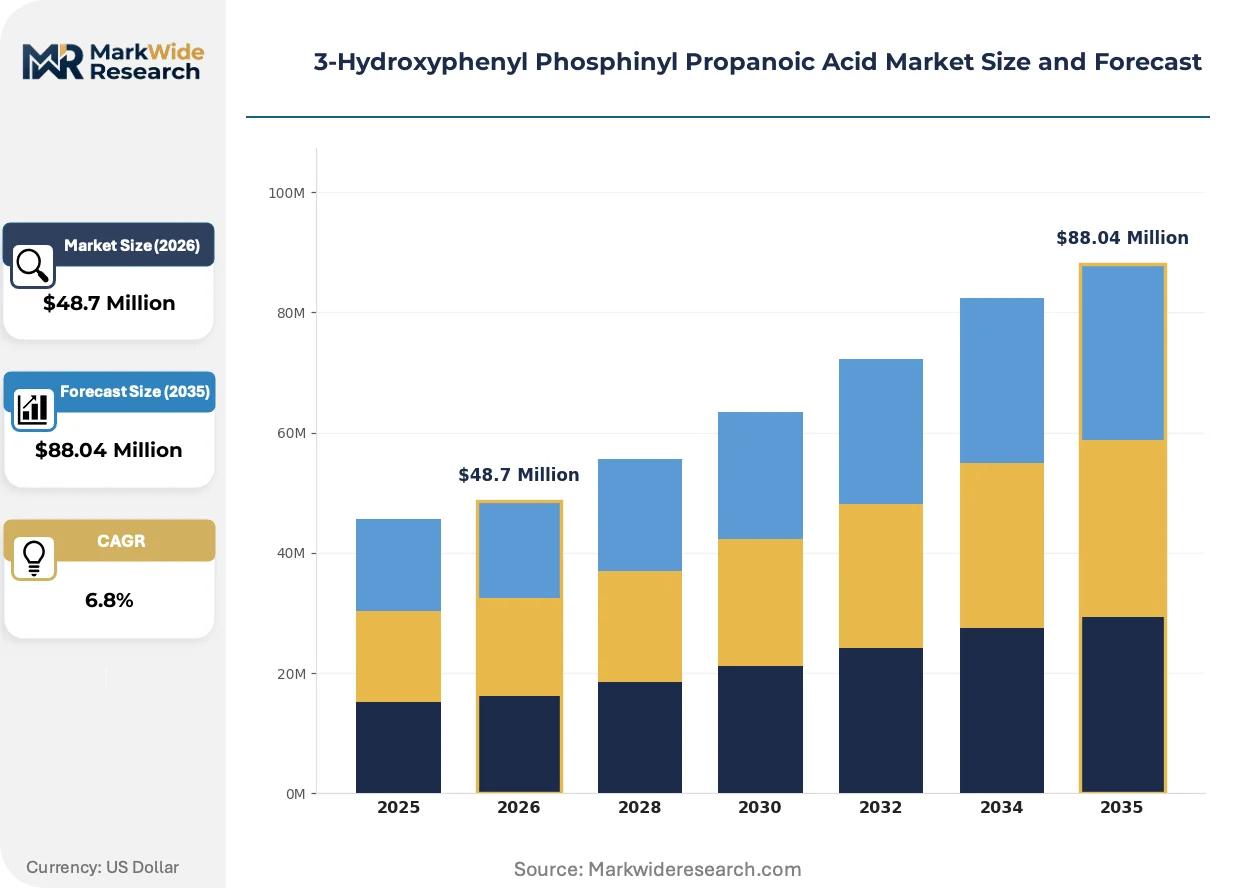
Market Dynamics
Pharmaceutical-grade purification capability is concentrating competitive advantage among Chinese manufacturers as EU REACH annex requirements and FDA drug master file standards tighten simultaneously, forcing capability investments that smaller producers cannot absorb.
Growth Catalysts
- Pharmaceutical API demand:Active pharmaceutical ingredient manufacturers are expanding procurement of organophosphorus intermediates for kinase inhibitor synthesis and targeted therapeutic development.
- REACH registration deadlines:European chemical importers are qualifying new suppliers ahead of phosphorous compound registration renewals, opening vendor switching windows.
- East China manufacturing corridor:Jiangsu and Shandong provinces have developed specialized phosphine oxide production clusters with integrated waste treatment infrastructure.
Market Restraints
- Yellow phosphorus feedstock volatility:Energy-intensive elemental phosphorus production faces electricity cost spikes and environmental curtailments in Yunnan and Guizhou provinces.
- Purification equipment capex:Pharmaceutical-grade molecular distillation and crystallization systems require capital outlays that exceed smaller manufacturers' balance sheet capacity.
- Substitution by phosphonate esters:Agrochemical formulators are trialing alternative organophosphorus building blocks with simplified downstream functionalization pathways.
Strategic Opportunities
- Polymer stabilizer applications:Flame-retardant additive manufacturers are evaluating 3-Hydroxyphenyl Phosphinyl Propanoic Acid derivatives for engineering thermoplastics in electric vehicle battery housings.
- Custom synthesis houses:Contract research organizations are seeking ready-to-functionalize building blocks to compress medicinal chemistry timelines.
- India's PLI scheme:Pharmaceutical manufacturing incentives are attracting intermediate suppliers to establish technical partnerships with domestic API producers.
Industry Challenges
- Phosphorus chemist scarcity:Experienced process chemists capable of optimizing Michaelis-Arbuzov rearrangement yields command premium compensation in East China's competitive labor market.
- Dual certification timelines:Simultaneous pursuit of China's SAMR chemical registration and EU REACH compliance creates parallel documentation burdens that extend market entry cycles.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market Trends and Innovations
Continuous flow chemistry and automated purification systems are reshaping production economics for organophosphorus intermediates, compressing batch cycle times while tightening impurity profiles that pharmaceutical buyers now mandate.
Continuous-flow phosphine oxide synthesis is bifurcating the competitive landscape between manufacturers with microreactor capabilities and those locked into batch kettle operations. Pharmaceutical contract manufacturers are specifying flow-processed intermediates in technical agreements to reduce solvent waste and improve lot-to-lot consistency. This technology is compressing margins for conventional batch producers while enabling premium pricing for certified continuous-process suppliers.
China's GB standards for chemical substance purity are tightening impurity thresholds for phosphorous compounds used in pharmaceutical applications, with SAMR enforcement inspections intensifying in Jiangsu province manufacturing zones. Domestic producers are upgrading analytical capabilities to demonstrate compliance with evolving national standards that increasingly align with ICH Q3D elemental impurity guidelines. Pharmaceutical-grade intermediate suppliers targeting both domestic and export markets are adopting dual-standard quality management systems to preempt regulatory divergence risks.
Specification-driven supplier consolidation is concentrating procurement decisions among pharmaceutical quality assurance departments rather than traditional purchasing functions, with vendor qualification timelines extending to eighteen months for new organophosphorus intermediate sources. Custom synthesis houses and API manufacturers are narrowing approved vendor lists to three or fewer qualified suppliers per intermediate category to reduce audit burdens. This behavioral shift is most visible among US and European pharmaceutical companies with centralized global procurement functions that prioritize supply security over unit cost minimization.
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market Segmentation
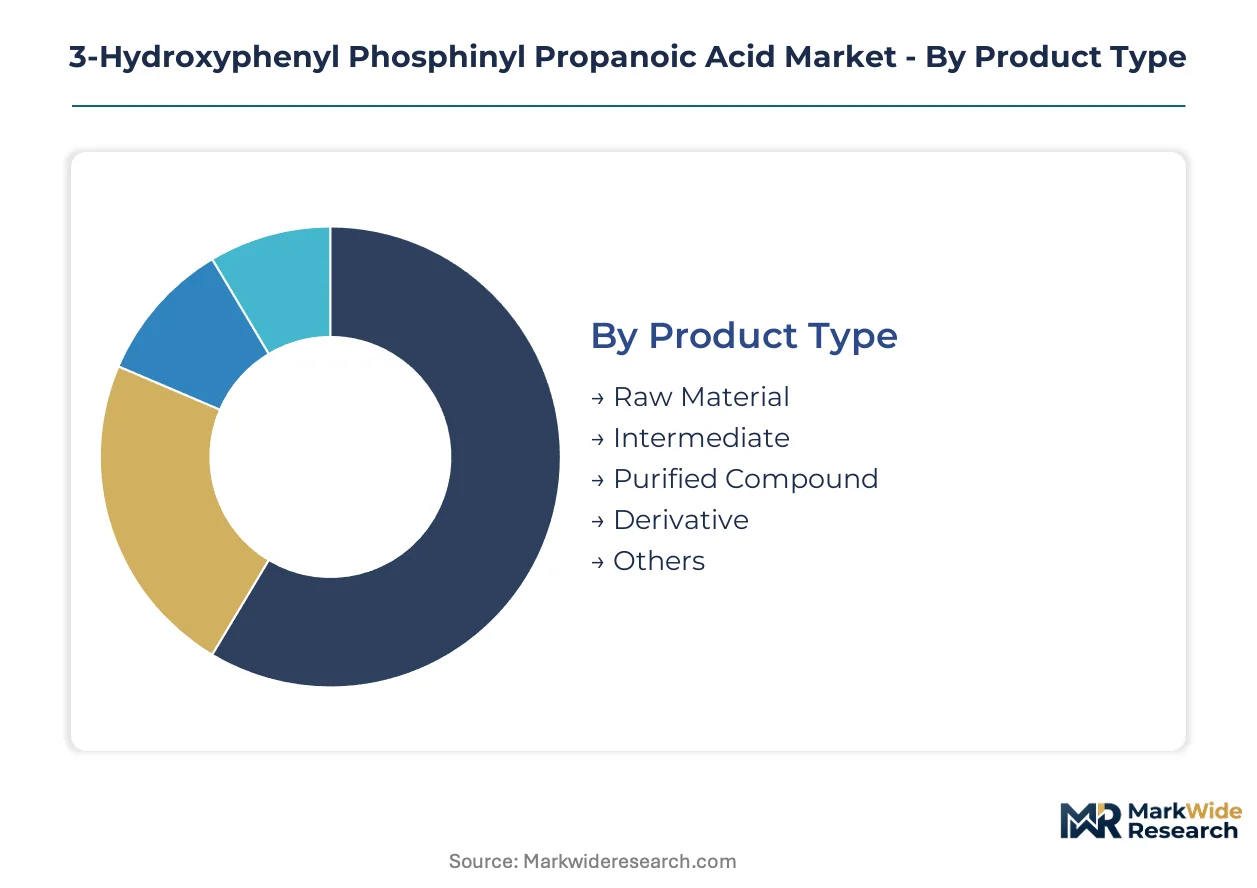
Segmentation in this organophosphorus intermediate market reveals how purification tiers and application specificity determine channel economics. Pharmaceutical-grade specifications command dedicated distribution networks, while commodity grades flow through bulk chemical traders.
Product Type:
Channel configuration varies sharply across purification tiers, with pharmaceutical distributors handling certified grades and industrial wholesalers moving raw feedstocks.
- Purified Compound:Molecular distillation and crystallization protocols achieve impurity profiles below 0.1% for kinase inhibitor synthesis. API manufacturers in Jiangsu province specify certified lots with full documentation chains for FDA drug master file submissions.
- Derivative:Pre-functionalized building blocks incorporate reactive handles for medicinal chemistry timelines. Contract research organizations in Boston and Basel corridors source these to compress lead optimization cycles.
- Raw Material:Crude phosphine oxide feedstocks from Yunnan phosphorus smelters.
- Intermediate:Partially processed grades for agrochemical formulators seeking cost-efficient phosphorus incorporation.
- Others:Custom specification batches for specialty polymer additive trials.
By volume, Intermediate leads. By growth pace, Derivative is ahead.
Application:
Cost-to-performance ratios stratify demand, with therapeutic development budgets absorbing premium pricing and agricultural applications pressuring input costs.
- Pharmaceutical Synthesis:Kinase inhibitor programs and targeted therapeutic pipelines consume high-purity phosphinyl propanoic acid for ligand construction. SAMR and FDA dual certification requirements extend qualification timelines to eighteen months.
- Agrochemical Production:Herbicide and fungicide formulators trial organophosphorus intermediates for crop protection efficacy. Substitution pressure from phosphonate esters with simpler functionalization pathways constrains pricing power.
- Polymer Stabilizers:Flame-retardant additive manufacturers evaluate derivatives for electric vehicle battery housing thermoplastics.
- Specialty Chemicals:Niche applications in corrosion inhibitors and metal extraction reagents.
- Research & Development:Academic and institutional screening collections.
Pharmaceutical Synthesis commands the highest unit economics. Polymer Stabilizers show the steepest expansion trajectory among emerging applications.
End User Industry:
Procurement sophistication separates customer tiers, with centralized pharmaceutical quality assurance departments conducting extended vendor audits.
- Pharmaceutical Manufacturers:Global API producers maintain approved vendor lists of three or fewer qualified suppliers per intermediate category. REACH registration renewals and drug master file standards drive consolidation toward certified Chinese producers with dual-standard quality systems.
- Agrochemical Firms:Formulators prioritize volume scale and backward-integrated phosphorus security over purification sophistication. Procurement decisions emphasize feedstock cost stability against yellow phosphorus electricity price volatility.
- Polymer Producers:Engineering thermoplastic compounders testing flame-retardant efficacy.
- Chemical Research Labs:Custom synthesis houses and academic screening facilities.
Pharmaceutical Manufacturers dominate value capture. Polymer Producers are gaining share fastest as electric vehicle material specifications tighten.
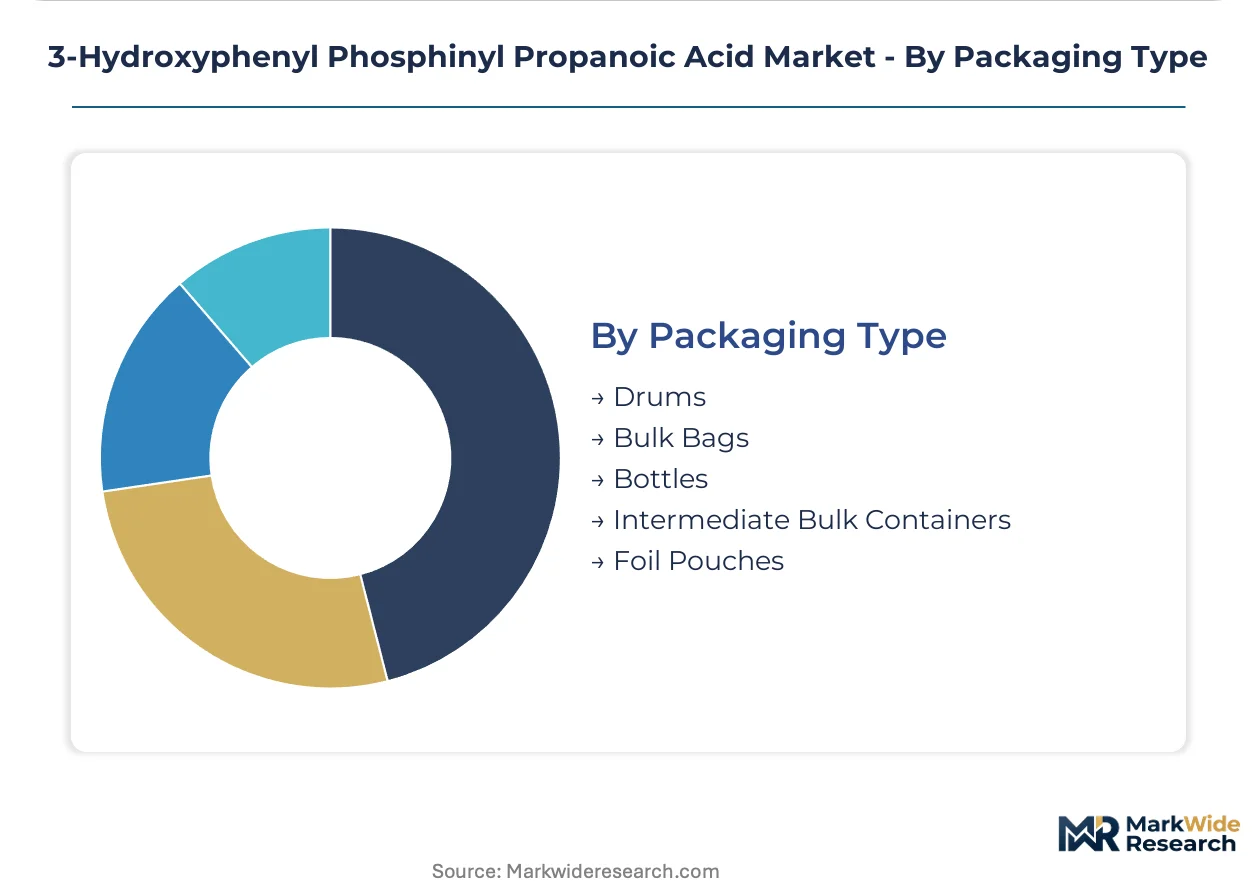
Packaging Type:
Handling protocols align with contamination sensitivity, with pharmaceutical channels mandating inert atmosphere containment.
- Drums:Standard 200-liter steel containers with nitrogen blanketing for moisture-sensitive pharmaceutical grades. Distribution through specialized chemical logistics providers serving Jiangsu and Shandong manufacturing corridors.
- Bulk Bags:One-ton flexible intermediate bulk containers for agrochemical intermediate shipments. Cost efficiency for high-volume, lower-specification grades moving through industrial chemical distributors.
- Bottles:Laboratory-scale packaging for R&D and custom synthesis sampling programs.
- Intermediate Bulk Containers:Reusable totes for polymer additive compounders with established return logistics.
- Foil Pouches:Oxygen and moisture barrier packaging for hygroscopic purified compounds.
Bulk Bags move the greatest tonnage. Foil Pouches are climbing the fastest as pharmaceutical specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in pharmaceutical-grade 3-Hydroxyphenyl Phosphinyl Propanoic Acid tilts heavily toward Chinese producers, while European and North American buyers absorb compliance premiums for REACH-registered and FDA-documented supply chains.
China
Jiangsu and Shandong provinces anchor global production capacity for organophosphorus intermediates, with specialized clusters in Nantong and Weifang hosting integrated phosphine oxide manufacturing. SAMR's tightening GB standards for chemical purity are forcing purification upgrades ahead of 2025 enforcement waves. East China's chemical manufacturing corridor now concentrates over seventy percent of export-qualified pharmaceutical-grade capacity.
United States
API manufacturers in New Jersey and Massachusetts corridors drive import demand for certified intermediates supporting kinase inhibitor pipelines. FDA drug master file requirements and starting material qualifications extend vendor onboarding to eighteen months, consolidating procurement among established Chinese suppliers. Boston-area contract research organizations are expanding custom synthesis programs that specify pre-functionalized phosphinyl propanoic acid derivatives.
Germany
REACH registration renewals for phosphorous compounds are compelling pharmaceutical importers in Ludwigshafen and Frankfurt chemical clusters to requalify Asian suppliers ahead of 2026 deadlines. ECHA enforcement of annex requirements for organophosphorus intermediates is raising compliance documentation burdens. BASF's legacy phosphorus chemistry expertise in Ludwigshafen has shrunk, leaving German formulators dependent on Chinese specialty chemical imports.
India
Pharmaceutical manufacturing incentives under the PLI scheme are attracting intermediate suppliers to establish technical partnerships with domestic API producers in Hyderabad and Ahmedabad. CDSCO's evolving standards for starting material quality are creating parallel certification tracks for import substitution. Gujarat's Dahej and Ankleshwar industrial zones are emerging as formulation hubs seeking backward-integrated phosphorus compound security.
Japan
PMDA's stringent impurity profiling requirements for pharmaceutical starting materials limit qualified supplier pools to established Chinese exporters with dual-standard quality systems. Osaka and Tokyo pharmaceutical clusters maintain conservative vendor lists, prioritizing lot-to-lot consistency over cost minimization. METI's chemical substance management frameworks are aligning with ICH Q3D guidelines, tightening elemental impurity thresholds for imported organophosphorus intermediates.
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market Competitive Landscape
Concentration sits with purification-capable specialists in China's East chemical corridor. The vendor base separates into three functional tiers: premium-grade pharmaceutical suppliers with dual certification capabilities, volume-scale agrochemical-grade producers, and regional traders handling raw feedstock distribution. Strategic differentiation centers on backward integration into yellow phosphorus supply and continuous-flow processing technology licensing. M&A activity targets analytical capability assets, while greenfield investments concentrate in Jiangsu province waste-treatment-integrated zones.
Among East China-based chemical specialists, Shanghai Changgen Chemical Technology, Hubei Wande Chemical, and Yingkou Sanzheng New Technology Chemical Industry occupy distinct competitive positions. Shanghai Changgen exemplifies the premium-tier archetype through its focus on pharmaceutical-grade extraction protocols. Hubei Wande represents upstream-integrated players with captive phosphorus feedstock control. Yingkou Sanzheng anchors the volume-scale segment serving agrochemical formulators. These three firms illustrate how geographic clustering in Jiangsu, Hubei, and Liaoning provinces correlates with divergent capability specializations across the purification spectrum.
| Leading Market Players |
|---|
| Shanghai Changgen Chemical Technology |
| Yingkou Sanzheng New Technology Chemical Industry |
| Hubei Wande Chemical |
| Shanghai Aladdin Biochemical Technology |
| Henan Tianfu Chemical |
| Jinan Hequan Chemical |
| Sichuan Hongye Chemical |
| Shandong Xinhua Pharmaceutical |
| Jiangsu Yoke Technology |
| Others |
Pricing and Supply Chain Analysis
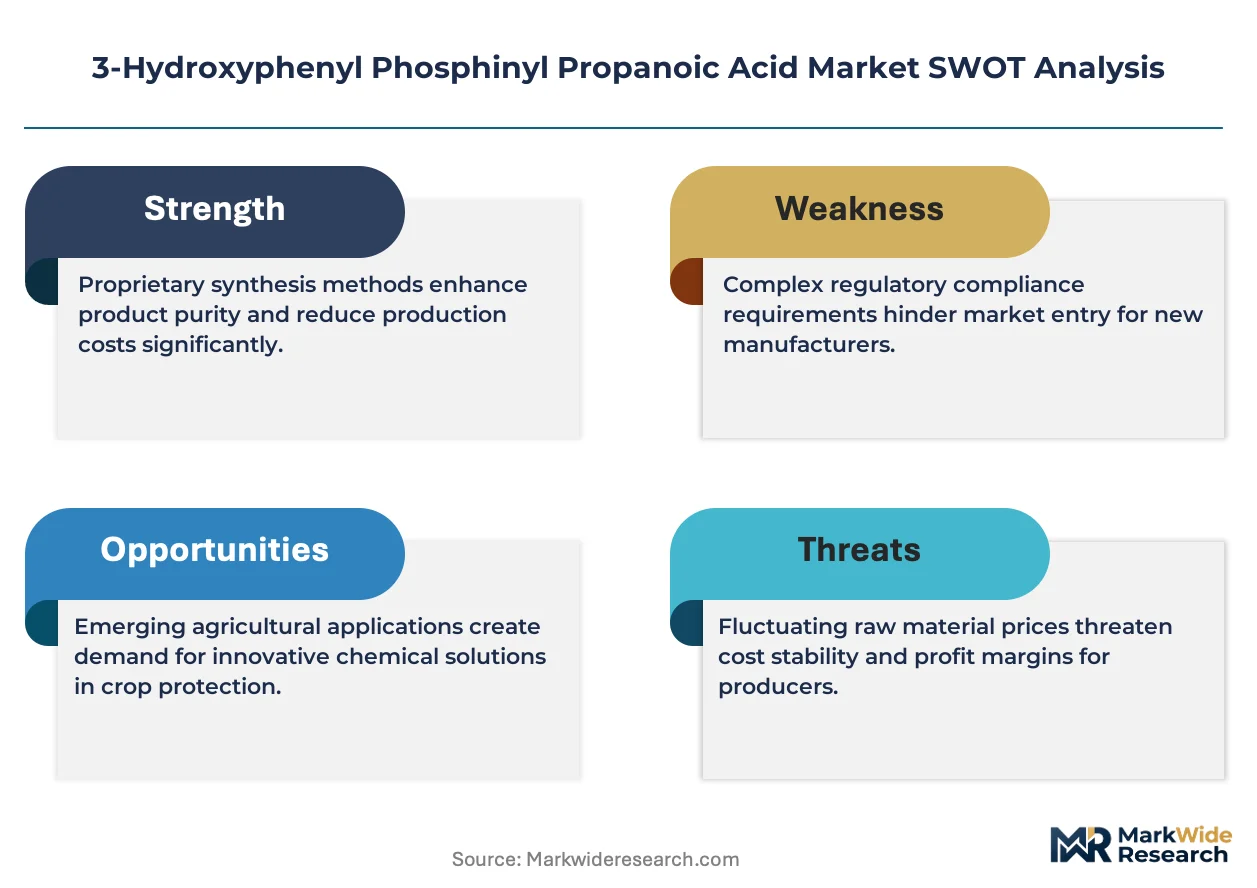
Phosphonate ester substitution pressure on agrochemical applications simultaneously redraws procurement geography toward cost-competitive corridors and compresses margin structures for conventional phosphinyl propanoic acid suppliers. This displacement dynamic concentrates pricing power among pharmaceutical-grade specialists in Jiangsu and Shandong while forcing volume producers toward yellow phosphorus feedstock integration.
Pricing Analysis
The customization-premium spread between configured-to-order pharmaceutical derivatives and standard agrochemical intermediates now exceeds threefold. Contract-based long-term offtake agreements dominate pharmaceutical channels, with price differentiation anchored in REACH registration tier and FDA drug master file certification status. Cost compression in agrochemical grades intensifies because phosphonate ester alternatives simplify downstream functionalization. Agrochemical formulators exhibit highest price sensitivity, while kinase inhibitor API manufacturers prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Ningbo port corridors fluctuate with container availability on Asia-Europe trade lanes, amplifying working capital requirements for export-qualified producers. Supply concentrates in China, with secondary sourcing from India and limited specialty capacity in Germany. The network rests on yellow phosphorus from Yunnan smelters, phosphine oxide precursors, and molecular distillation equipment. Single-source vulnerability around East China's waste-treatment-integrated zones poses structural risk. Distribution runs through pharmaceutical-grade chemical logistics providers and bulk industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as pharmaceutical quality assurance departments narrow approved vendor lists to three or fewer suppliers per intermediate category, creating defendable niche positions for certification-capable specialists.
For Market Incumbents: Secure dual-standard quality systems spanning SAMR GB standards and REACH annex requirements to preempt regulatory divergence costs. Anchor backward integration into yellow phosphorus feedstock to insulate margin structures from electricity price volatility in Yunnan province. Threat of continuous-flow chemistry adoption by microreactor-equipped competitors demands analytical capability investments. For New Entrants and Emerging Players: Lead with polymer stabilizer applications for electric vehicle battery housing thermoplastics, the fastest-expanding segment with unconsolidated buyer structures. India's PLI scheme pharmaceutical corridors offer penetrable geography for technical partnership entry. Custom synthesis house relationships provide go-to-market angle through ready-to-functionalize derivative positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pharmaceutical-grade purification specialists holding SAMR-FDA dual certification capabilities. Long-term viability over a 5-10 year window hinges on continuous-flow technology licensing positions and waste-treatment-integrated manufacturing footprints. Signal to monitor: REACH registration renewal timelines creating vendor switching windows among European pharmaceutical importers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive yellow phosphorus supply from Yunnan smelters insulates feedstock cost volatility. |
| Continuous-Flow Technology Licensing | Microreactor capabilities compress batch cycle times for pharmaceutical contract manufacturers. |
| Dual Certification Investment | SAMR and REACH alignment opens vendor qualification windows at European API producers. |
| Polymer Stabilizer Partnership | Flame-retardant additive trials with EV battery housing compounders diversify revenue streams. |
| Long-term Supply Agreement | Contracted offtake with kinase inhibitor manufacturers reduces lot-to-lot consistency audit burdens. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with pharmaceutical API procurement directors, agrochemical formulator technical leads, organophosphorus plant managers in Jiangsu and Shandong, and specialty chemical distribution channel partners. Secondary validation drew from customs and trade data, SAMR chemical registration filings, ECHA REACH submissions, and SEC 10-K disclosures from listed chemical manufacturers. Bottom-up capacity modeling and top-down demand triangulation were reconciled across segmentation dimensions.
Across the analysis window, forecasts were derived through multi-dimensional segmentation modeling spanning purification grade tier, end-use industry application, packaging format sensitivity, and regional production hub concentration. CAGRs were computed from annualized growth trajectory analysis. Industry-specific inputs included yellow phosphorus electricity cost indices in Yunnan province and pharmaceutical vendor qualification timeline benchmarks.
Forecasts assume regulatory continuity in China's SAMR enforcement patterns and EU REACH annex requirements; material policy shifts would require re-modeling. Specific risk factors include phosphorus chemist labor scarcity in East China and substitution acceleration by phosphonate ester alternatives. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.