
 Global Black Masterbatch Market | 2026-2036
Global Black Masterbatch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Black Masterbatch Market Foresight
Carbon black pigment is shifting from commodity furnace grades toward specialized low-PAH and conductive variants as compounders face stricter automotive and food-contact specifications. Cabot Corporation leverages its vertically integrated carbon black supply chain to sustain cost advantages across high-volume automotive programs. Avient Corporation anchors its position through tailored masterbatch formulations for wire and cable sheathing in North American utility infrastructure.
Black masterbatch is a concentrated dispersion of carbon black or alternative pigments in a thermoplastic carrier resin, engineered to deliver UV protection, conductivity, or color consistency at loadings typically between fifteen and fifty percent by weight. The carbon black product type dominates volume owing to its cost-performance ratio in packaging and agricultural film, while organic black grades capture premium margins in consumer electronics housings where regulatory limits on polycyclic aromatic hydrocarbons apply. Wire and cable applications represent the fastest-expanding segment as electrification projects multiply across power distribution and telecommunications networks.
EPA regulations on particulate emissions influence carbon black production economics in the United States, while REACH registration requirements in Europe restrict certain aromatic oil extender formulations used in masterbatch compounding. China's GB standards on plastic product safety and its dual carbon goals are redirecting domestic manufacturers toward cleaner furnace technologies and bio-based carrier resins. Stakeholders must monitor evolving chemical substance restrictions across multiple jurisdictions while evaluating backward integration into carbon black manufacturing or captive compounding assets to secure supply continuity.
Market Dynamics
Carbon black feedstock volatility and polymer carrier resin supply concentration in Northeast Asia are compressing margin structures and forcing compounders toward captive carbon black sourcing or regional compounding partnerships.
Growth Catalysts
- Automotive electrification:Battery enclosure and high-voltage cable sheathing specifications in Germany and China are expanding conductive black masterbatch specifications. OEMs specify loadings above thirty percent by weight for EMI shielding.
- REACH low-PAH mandates:ECHA restrictions on polycyclic aromatic hydrocarbons in consumer-contact plastics are redirecting European compounders toward specialized carbon black grades. Food packaging and toy segments drive premium formulation demand.
- Wire and cable infrastructure buildouts:Utility-scale grid modernization across the United States and India is multiplying jacketing and insulation compound volumes. Cross-linked polyethylene carriers dominate these specifications.
Market Restraints
- Carbon black feedstock cost volatility:Heavy aromatic oil and coal tar prices fluctuate with refinery output decisions in the United States and China. Masterbatch producers lack pricing power to pass through swings.
- Supply concentration in carbon black manufacturing:Furnace black production clusters in Shandong Province and Texas Gulf Coast create geographic risk exposure. Disruptions at these nodes propagate through compounding networks.
- Technical ceiling in loading rates:Dispersion quality degrades above fifty percent carbon black by weight in polyethylene carriers. High-performance applications require alternative conductive fillers.
Strategic Opportunities
- Bio-based carrier resins:European packaging brands specify polylactic acid and bio-polyethylene masterbatch carriers to meet EU Green Deal targets. Compounders with fermentation-derived resin partnerships capture sustainability premiums.
- India wire and cable market:Central Electricity Authority transmission expansion targets and telecommunications fiber deployment are outpacing domestic compounding capacity. Import substitution opportunities exist for integrated producers.
- Recycled polymer integration:Post-consumer polyethylene and polypropylene streams require black masterbatch to mask color inconsistency. Mechanical recycling facilities in the Netherlands and Japan seek dedicated supply agreements.
Industry Challenges
- Colorimetric certification timelines:Automotive OEMs require eighteen-to-twenty-four month qualification cycles for exterior trim masterbatch approvals. Compounders must maintain sample libraries and testing protocols across multiple production sites.
- Dispersion equipment capex intensity:Twin-screw extrusion lines with specialized screw geometries for high-load carbon black compounding require seven-figure capital commitments. Regional players face barriers to capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Black Masterbatch Market |
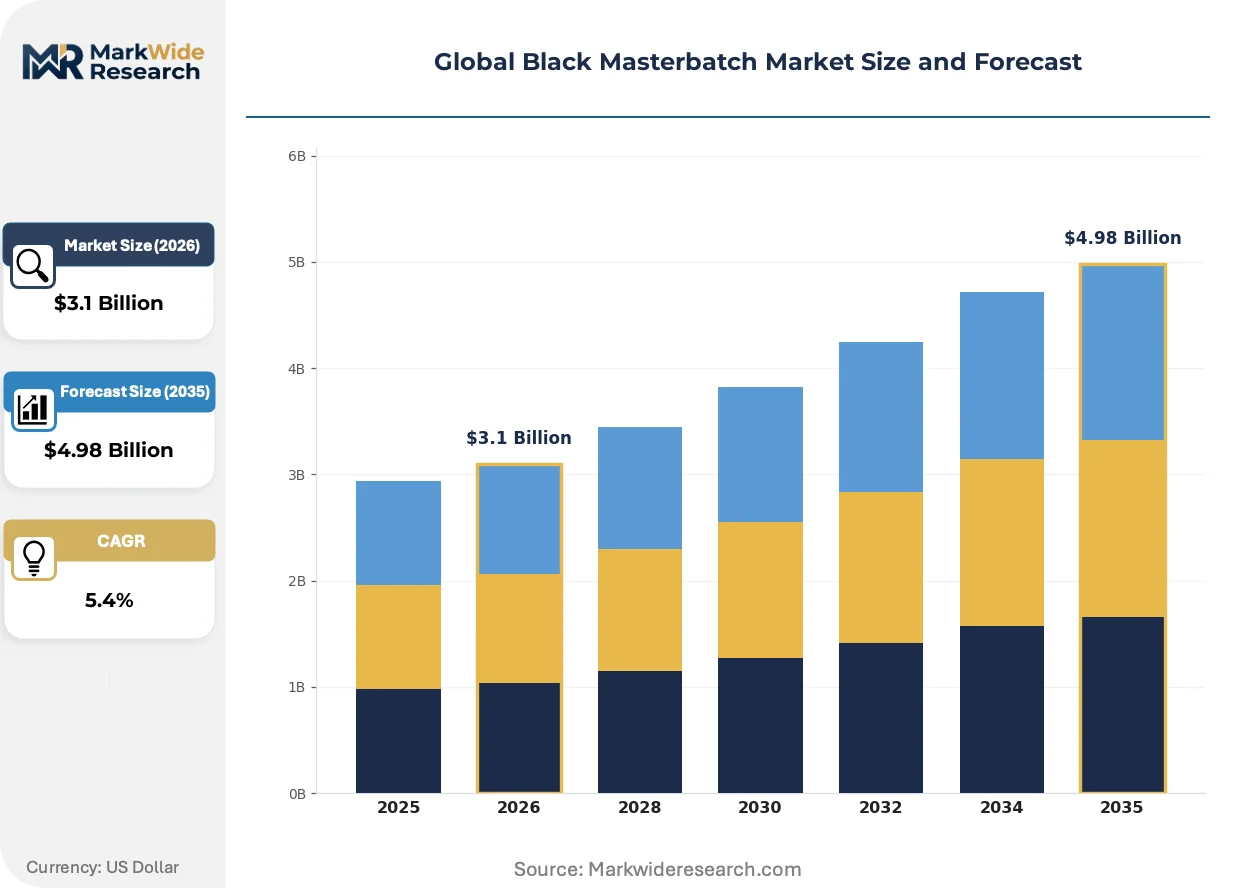
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Black, Organic Black, Inorganic Black, Synthetic Black, Pellet Form Application: Packaging, Wire & Cable, Automotive OEMs, Construction Materials, Consumer Electronics End User Industry: Plastic Manufacturers, Tier-1 Suppliers, OEMs, Compounders, Molders Distribution Channel: Direct Sales, Distributors, Online Retailers, Industrial Suppliers |
| Companies Covered | EuroPlas, Cabot Corporation, Avient Corporation, Tosaf Compounds Limited, Plastika Kritis, Ampacet Corporation, Clariant, Charming Masterbatch, LyondellBasell Industries Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Black Masterbatch Market Shifts & Advancements
Formulation science and regulatory chemistry are converging to redefine competitive advantage around dispersion quality, carrier sustainability, and compliance documentation rather than commodity scale.
Specialized low-PAH and conductive carbon black grades are modularizing masterbatch product architectures. Automotive suppliers in Germany and Japan specify these variants for under-hood and battery applications. Compounders now configure carrier resin and pigment combinations as interchangeable modules rather than fixed recipes.
REACH registration requirements for aromatic oil extenders are forcing reformulation of legacy masterbatch compounds across European wire and cable segments. ECHA substance evaluation deadlines in 2025-2026 compress decision timelines for compounders. Producers are accelerating migration to paraffinic and naphthenic oil alternatives in high-voltage insulation grades.
Direct mill supply relationships are displacing distributor intermediation in North American agricultural film and geomembrane segments. Large processors in Iowa and Alberta negotiate carbon black and masterbatch volumes through annual indexed contracts. Channel compression rewards compounders with captive carbon black assets and multi-site logistics networks.
Global Black Masterbatch Market Segmentation
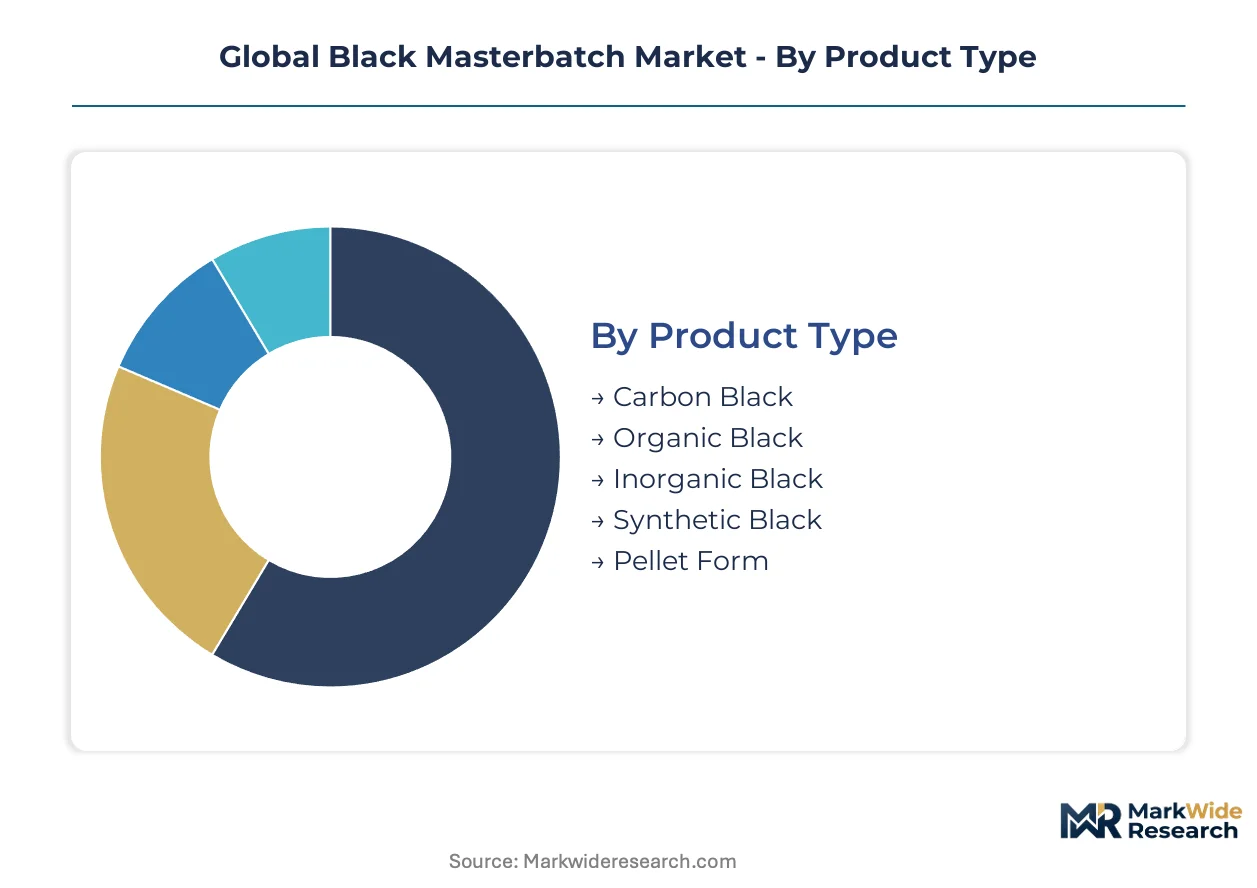
Black masterbatch formulation requirements diverge sharply across end-use specifications, forcing compounders to maintain parallel production lines with distinct dispersion equipment and carrier resin inventories. Segmentation discipline separates commodity volume plays from premium specialty positions.
Product Type:
Furnace-based carbon black production demands the heaviest capital commitments, with reactor installations and emission control systems requiring nine-figure investments that barrier new entrants.
- Carbon Black:Furnace-grade carbon black dominates volume through cost-performance ratio in polyethylene agricultural films and geomembranes. Shandong Province and Texas Gulf Coast production clusters supply compounders across Asia-Pacific and North American packaging markets. REACH low-PAH mandates in Europe are redirecting formulation strategies toward specialized grades.
- Organic Black:High-purity organic pigments command premium positioning in consumer electronics housings where polycyclic aromatic hydrocarbon limits apply. Japanese and German OEMs specify these grades for under-hood automotive components. ECHA substance evaluations compress qualification timelines for compounders migrating from legacy formulations.
- Inorganic Black:Iron oxide and mixed metal oxide variants serve construction materials requiring thermal stability above standard polymer processing temperatures.
- Synthetic Black:Engineered pigment structures target conductive applications in battery enclosures and electromagnetic interference shielding specifications.
- Pellet Form:Pre-dispersed pellet concentrates reduce dust exposure and simplify handling for small-scale molders without twin-screw compounding capability.
Carbon black absorbs the bulk of installed capacity; organic black is expanding most quickly.
Application:
Wire and cable jacketing commands the most demanding technical specifications, with cross-linked polyethylene carriers and high-load conductive formulations requiring specialized screw geometries and downstream cooling systems.
- Wire & Cable:Utility-scale grid modernization across the United States and India is multiplying jacketing compound volumes. Central Electricity Authority transmission targets and telecommunications fiber deployment outpace domestic Indian compounding capacity. Cross-linked polyethylene carriers dominate high-voltage insulation specifications with carbon black loadings above thirty percent by weight for electromagnetic interference shielding.
- Automotive OEMs:Battery enclosure specifications in Germany and China specify conductive masterbatch for electric vehicle platforms. OEM qualification cycles extend eighteen to twenty-four months for exterior trim approvals, locking compounders into long-term sample library commitments.
- Packaging:Agricultural film processors in Iowa and Alberta negotiate annual indexed contracts directly with carbon black suppliers, compressing distributor margins.
- Construction Materials:Geomembrane and geotextile applications require UV-stabilized formulations for extended outdoor exposure.
- Consumer Electronics:Premium housings for laptops and smartphones drive low-PAH organic pigment demand under RoHS and REACH consumer-contact limits.
Packaging retains the largest volume footprint; wire and cable is climbing the fastest.
End User Industry:
Tier-1 suppliers face the most compressed margin structures, caught between OEM price pressure and carbon black feedstock volatility they cannot pass through contractually.
- Tier-1 Suppliers:Automotive component manufacturers manage eighteen-to-twenty-four month qualification protocols across multiple production sites. German and Japanese OEMs require dispersion quality documentation and colorimetric certification that locks compounders into dedicated supply relationships.
- OEMs:Original equipment manufacturers in automotive and electronics sectors specify masterbatch formulations directly, bypassing compounder recommendations for critical applications. Battery enclosure and high-voltage cable programs in China and Germany drive conductive grade specifications.
- Plastic Manufacturers:Film extruders and injection molders represent high-volume, price-sensitive demand concentrated in packaging and agricultural applications.
- Compounders:Independent masterbatch producers without captive carbon black assets face margin compression from feedstock volatility and polymer carrier resin concentration in Northeast Asia.
- Molders:Small-scale processors favor pellet form concentrates to avoid capital investment in dispersion equipment.
Plastic manufacturers represent the broadest customer base; Tier-1 suppliers are gaining share fastest.
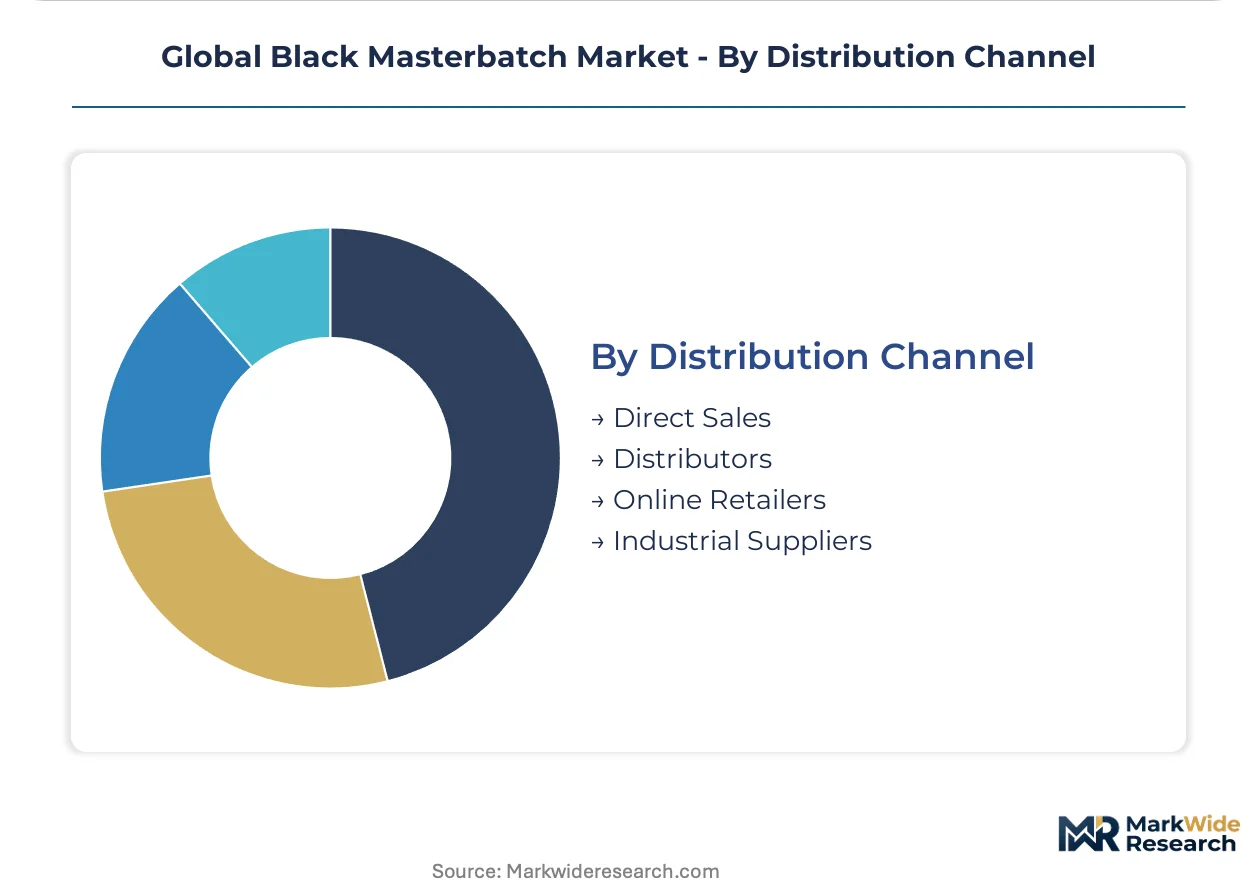
Distribution Channel:
Direct sales relationships require the most intensive working capital commitment, with annual indexed contracts and multi-site logistics networks demanding sophisticated inventory management systems.
- Direct Sales:Large agricultural film processors in Iowa and Alberta negotiate carbon black and masterbatch volumes through annual contracts indexed to feedstock benchmarks. Channel compression rewards compounders with captive carbon black assets and established logistics networks.
- Distributors:Regional intermediaries serve small and mid-scale molders without volume to justify direct mill relationships. Distributor networks retain relevance in fragmented European packaging markets.
- Online Retailers:Digital procurement platforms target small-batch orders from prototype molders and specialty compounders seeking rapid turnaround.
- Industrial Suppliers:Broad-line distributors bundle masterbatch with polymer resins and processing additives for convenience-driven procurement.
Direct sales captures the highest volume throughput; online retailers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shandong Province special economic zones concentrate furnace black production capacity, while Germany's Ruhr industrial belt anchors European compounding expertise. Tax incentives in India's Gujarat and petrochemical integration in Texas Gulf Coast regions redirect investment flows across the value chain.
China
Domestic compounding capacity expansion in Shandong Province serves packaging and agricultural film processors. GB standards on plastic product safety and dual carbon goals redirect manufacturers toward cleaner furnace technologies. Yangtze River Delta polymer consumption clusters demand specialized low-PAH grades for export-oriented electronics manufacturing.
Germany
Battery enclosure specifications for electric vehicle platforms drive conductive masterbatch qualification cycles. ECHA restrictions on polycyclic aromatic hydrocarbons compress formulation migration timelines toward paraffinic oil alternatives. Ruhr industrial belt compounders maintain eighteen-to-twenty-four month automotive OEM approval protocols.
United States
Utility-scale grid modernization multiplies wire and cable jacketing compound volumes across Midwest agricultural film processors. EPA regulations on particulate emissions influence carbon black production economics in Texas Gulf Coast clusters. Iowa and Alberta processors negotiate direct mill supply relationships, compressing distributor intermediation.
India
Central Electricity Authority transmission expansion targets outpace domestic compounding capacity in power distribution applications. BIS standards on cable insulation materials redirect import substitution opportunities toward integrated producers. Gujarat special economic zones attract backward integration investments from compounders seeking captive carbon black sourcing.
Japan
Consumer electronics housing specifications drive premium organic pigment demand under METI-guided RoHS compliance frameworks. Kansai region OEMs require dispersion quality documentation for under-hood automotive components. Domestic compounders specialize in high-purity formulations for laptop and smartphone manufacturing supply chains.
Global Black Masterbatch Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in carbon black manufacturing contrasting fragmented compounding tiers. Three archetypes dominate: vertically integrated petrochemical majors with captive pigment assets, independent compounders serving regional packaging markets, and technology-focused specialists targeting automotive qualification protocols. Capacity expansion and strategic partnerships represent the dominant competitive moves, as feedstock volatility pressures margin structures.
Among North American integrated producers, Cabot Corporation exemplifies the upstream-controlled archetype through carbon black supply chain ownership, while Avient Corporation occupies a position as a formulation specialist serving infrastructure wire and cable segments. Tosaf Compounds Limited represents the regional independent model, anchoring compounding expertise across European packaging and agricultural film markets without captive pigment production.
| Leading Market Players |
|---|
| EuroPlas |
| Cabot Corporation |
| Avient Corporation |
| Tosaf Compounds Limited |
| Plastika Kritis |
| Ampacet Corporation |
| Clariant |
| Charming Masterbatch |
| LyondellBasell Industries Holdings |
| Others |
Supply & Pricing Matrix
Automotive OEM qualification cycles stretching eighteen to twenty-four months for exterior trim approvals force compounders to carry dedicated sample inventories and multi-site testing protocols, inflating working capital requirements and compressing pricing flexibility for non-qualified spot buyers.
Pricing Analysis
Short lead-time premiums command fifteen to twenty percent markups over standard contract terms as agricultural film processors in Iowa and Alberta negotiate annual indexed agreements with direct mill suppliers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified low-PAH grades from commodity furnace black formulations. Cost compression in standard-grade wire and cable compounds is intensifying because carbon black feedstock volatility outpaces contractual pass-through mechanisms. Tier-1 automotive suppliers exhibit the lowest price sensitivity due to locked qualification protocols, while small-scale molders purchasing pellet concentrates through distributor channels face the highest cost elasticity.
Supply Chain Analysis
Dual-sourcing mandates from German and Japanese OEMs require compounders to qualify secondary carbon black suppliers across Shandong Province, Texas Gulf Coast, and Ruhr industrial belt production clusters. Raw material dependencies center on heavy aromatic oils, coal tar distillates, and polymer carrier resins concentrated in Northeast Asia. Single-source vulnerability propagates from furnace black production nodes through compounding networks during regional emission compliance shutdowns. Distribution runs through direct annual contracts for large processors, with regional intermediaries retaining relevance only in fragmented European packaging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furnace black reactor capacity constraints in Shandong Province and Texas Gulf Coast prop pricing premiums for qualified compounders, creating a supply-constrained market structure favoring asset-backed incumbents.
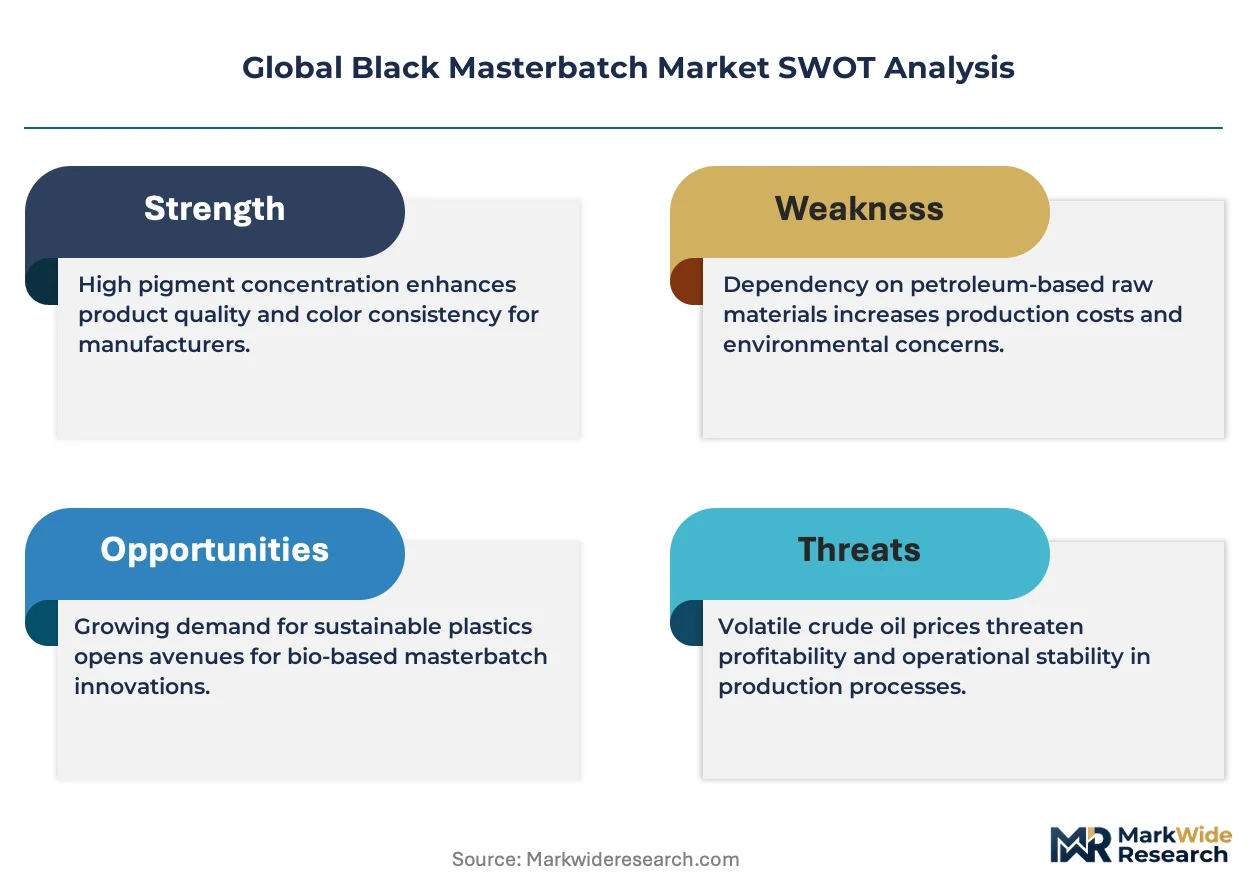
For Market Incumbents: Hedge carbon black feedstock exposure through captive sourcing partnerships or indexed long-term offtake agreements with Shandong and Gulf Coast producers. Expand dispersion equipment footprints in Gujarat special economic zones to capture Indian wire and cable import substitution demand before domestic capacity catches transmission expansion targets. Defensive consolidation around low-PAH certification capabilities addresses ECHA substance evaluation deadlines compressing European formulation migration timelines. For New Entrants and Emerging Players: Conductive masterbatch formulations for battery enclosure specifications represent the most penetrable wedge as electrification programs in Germany and China outpace incumbent qualification bandwidth. Target India's Central Electricity Authority transmission buildouts where domestic compounding capacity lags grid modernization timelines. Bio-based carrier resin partnerships with European fermentation-derived suppliers offer a sustainability-premium go-to-market angle bypassing commodity carbon black margin compression. For Investors and Strategic Acquirers: The window for entry favors compounders with captive carbon black assets and established automotive qualification libraries. Long-term viability across the analysis window hinges on backward integration into furnace black production or exclusive tolling arrangements with Shandong and Texas Gulf Coast clusters. Monitor ECHA low-PAH enforcement intensity and Indian BIS cable insulation standard implementation as inflection indicators for premium grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Black Production | Cabot Corporation's captive supply chain sustains cost advantages across high-volume automotive programs. |
| Low-PAH Grade Certification Investment | ECHA restrictions redirect European compounders toward specialized carbon black grades for food packaging. |
| Regional Compounding Partnership in Gujarat | Central Electricity Authority targets outpace domestic capacity, creating import substitution opportunities. |
| Bio-Based Carrier Resin Partnership | EU Green Deal targets drive European packaging brands toward polylactic acid masterbatch specifications. |
| Direct Mill Supply Agreement | Iowa and Alberta processors compress distributor margins through annual indexed carbon black contracts. |
Research Methodology
Trade databases, customs filings, and SEC 10-K disclosures formed the secondary backbone, supplemented by technical literature on carbon black dispersion science and REACH regulatory guidance. Primary fieldwork encompassed plant managers at furnace black facilities, procurement leads at Tier-1 automotive suppliers, distribution channel partners across European packaging markets, and technical R&D directors at masterbatch compounders. Bottom-up and top-down triangulation validated volume estimates against polymer consumption clusters and carbon black production capacity disclosures.
Bottom-up modeling aggregated segment-level demand across wire and cable, automotive, packaging, and electronics applications, while top-down approaches cross-referenced carbon black consumption intensity ratios against regional polymer production data. Segmentation dimensions encompassed product type, end-use industry, carrier resin chemistry, and regional regulatory compliance tiers. CAGRs derived from installed capacity expansion timelines, OEM electrification program announcements, and grid infrastructure investment pipelines across the analysis window.
Several conditions sit outside the modeled scope, including unannounced carbon black reactor shutdowns for emission compliance, abrupt REACH substance list expansions, and polymer carrier resin supply disruptions from Northeast Asia petrochemical complexes. Forecasts reflect assumptions around ECHA enforcement intensity, Indian transmission buildout pacing, and automotive qualification cycle durations. Deviation in carbon black feedstock benchmark pricing or furnace black capacity utilization rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
N-Propyl Propionate Market
Specialty Compounds
Global Quaternary Ammonium Compounds Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Acrylic Pad Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
Thioglycolate Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
High Performance Foam Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Scratch-Resistant Compound Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
United Kingdom Collagen Peptides Market