
 Calcium Sulfite Market | 2026-2036
Calcium Sulfite Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Sulfite Market Analysis
REACH is rebalancing the cost-of-entry calculus for European suppliers by mandating stricter impurity documentation and supply chain transparency for sulfite chemicals. Solvay S.A. leverages its integrated chlor-alkali platform to sustain captive sulfite production with lower feedstock volatility. American Elements anchors North American supply through rare earth and advanced materials co-production capabilities that compete on specification breadth.
Calcium sulfite is an inorganic salt with the formula CaSO₃, typically produced through the reaction of calcium hydroxide with sulfur dioxide gas or sulfurous acid, yielding a white crystalline solid with reducing and oxygen-scavenging properties. The compound functions primarily as a dechlorinating agent in municipal water systems, a sulfur dioxide absorbent in flue gas treatment, and a bleaching stabilizer in certain food applications. Calcium sulfite crystals occupy the premium tier where high purity enables pharmaceutical and specialized food-grade applications with tighter specification windows. Flue gas desulfurization slurry formulations dominate volume flows as coal-fired power plants and industrial boilers across Asia maintain compliance-driven demand, though water treatment applications are expanding fastest as dechlorination standards tighten in developed markets.
EPA drinking water regulations and OSHA workplace exposure limits in the United States shape product formulation and handling protocols for domestic manufacturers and importers. ECHA's REACH annex restrictions and the EU F-Gas Regulation indirectly influence calcium sulfite positioning as utilities evaluate sulfur-based alternatives in emission control strategies. China's MEE emission standards and GB water quality benchmarks create a dual compliance environment for producers serving both export and domestic markets. Stakeholders must monitor how carbon border adjustment mechanisms and evolving sulfate discharge limits reshape regional cost competitiveness without assuming uniform regulatory convergence.
Market Dynamics
Flue gas desulfurization retrofits in China's coal-fired power sector are compressing procurement timelines for calcium sulfite suppliers, while REACH compliance costs in Europe are forcing purity-grade bifurcation across export channels.
Growth Catalysts
- EPA dechlorination mandates:Municipal water utilities across the United States face tightening residual chlorine limits, expanding specification-grade calcium sulfite procurement for distribution system dechlorination.
- China MEE emission standards:Power plant FGD system upgrades in Shandong and Shanxi provinces are accelerating sulfite absorbent volume flows through Q4 retrofit deadlines.
- Food-grade bleaching stabilization:Japanese processors are qualifying high-purity calcium sulfite crystals for noodle and tofu applications under revised FSSAI-equivalent purity protocols.
Market Restraints
- Sulfur dioxide feedstock volatility:Smelter off-gas supply interruptions in Chile and Peru create input cost instability for non-integrated calcium sulfite producers.
- REACH documentation burden:ECHA's tightened impurity disclosure requirements for sulfite chemicals add 12-18 month certification delays for European market entry.
- Sodium bisulfite substitution:Liquid bisulfite systems are displacing solid calcium sulfite in compact municipal treatment plants where handling automation is prioritized.
Strategic Opportunities
- India municipal water infrastructure:Jal Jeevan Mission rural pipeline expansion creates first-time dechlorination chemical demand in previously unserved districts.
- Pharmaceutical oxygen scavenging:Injectable-grade sulfite specifications are opening parenteral drug stabilization applications with 40% purity premiums over technical grades.
- Carbon border adjustment positioning:EU CBAM scope expansion favors low-carbon-intensity sulfite production from European chlor-alkali integration versus Asian coal-derived alternatives.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS trace metal testing capability gaps at mid-tier producers delay REACH-grade certification timelines by 6-9 months.
- Legacy FGD system incompatibility:Retrofitting 1990s-era limestone scrubbers for sulfite-enhanced chemistry requires $2-4 million per unit capital outlays that strain utility capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Sulfite Market |
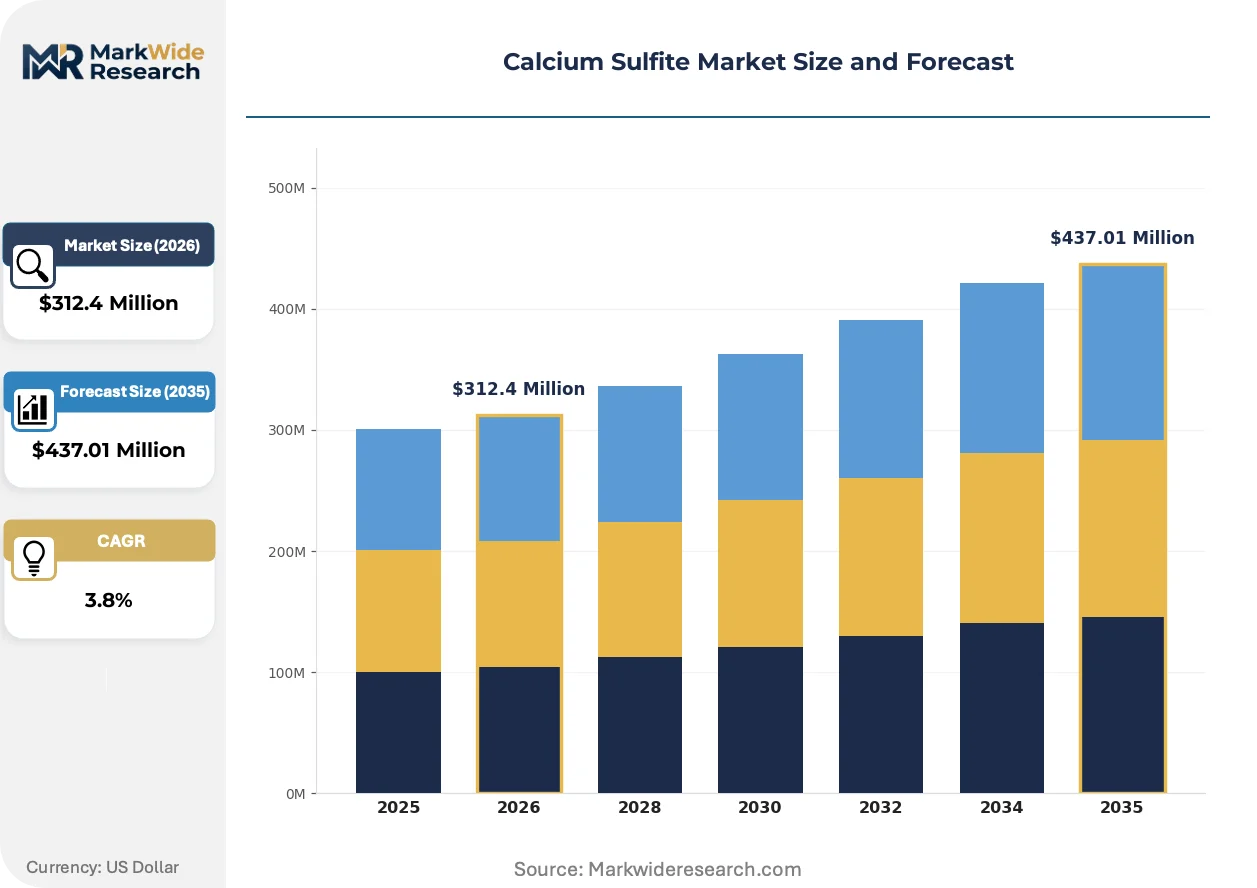
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Sulfite Slurry, Calcium Sulfite Caustic, Calcium Sulfite Crystals, Calcium Sulfite Dried Application: Flue Gas Desulfurization, Water Treatment, Production of White Pigments, Food Preservation End User: Power Plants, Water Treatment Facilities, Paint Manufacturers, Food Processors Packaging Type: Bulk Bags, Drums, Small Bags, IBC Totes |
| Companies Covered | Qingdao Sunny Energy-Saving Materials Co., Ltd., Shimmer Chemicals Private Limited, Aditya Birla Chemicals, American Elements, GFS Chemicals, Inc., Solvay S.A., Merck KGaA, Pure Tech Inc., NOAH Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Sulfite Market Emerging Trajectories
Calcium sulfite production chemistry is pivoting toward closed-loop sulfur recovery systems that co-produce gypsum construction feedstock, compressing waste disposal liabilities while opening circular economy positioning.
Membrane electrodialysis purification is converging with traditional recrystallization methods to yield pharmaceutical-grade calcium sulfite with sub-10 ppm heavy metal specifications. Korean and German specialty chemical houses are piloting this hybrid approach for parenteral drug applications. The technology is converging with existing chlor-alkali infrastructure to create integrated sulfite-gypsum production platforms that eliminate sulfur waste streams.
REACH Annex XVII restrictions on sulfite impurities are forcing European suppliers to implement blockchain-tracked supply chain documentation from sulfur source to final crystal. ECHA's 2023 guidance on Substance of Very High Concern candidate list screening has triggered reformulation investments across water additive portfolios. German and Dutch water utilities now require third-party-verified purity certificates that add 8-12% to delivered product costs.
Specification-driven procurement consolidation is compressing supplier counts at major municipal water authorities. United States utilities serving populations above 500,000 are reducing qualified vendor lists from 6-8 to 2-3 sources with dedicated analytical support capabilities. The shift is most visible in California and Texas, where regional water district mergers are centralizing chemical purchasing through master service agreements with multi-year purity guarantees.
Calcium Sulfite Market Segmentation
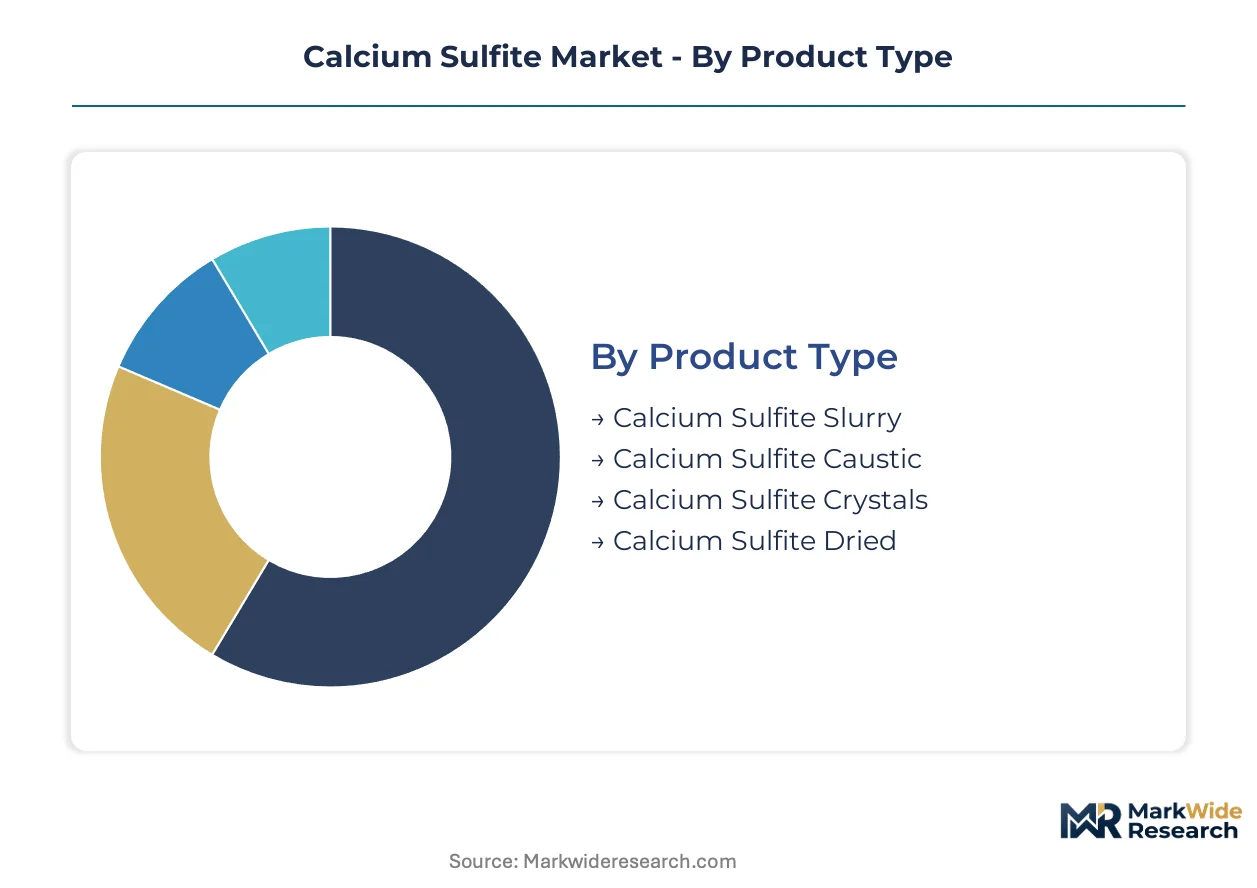
Calcium sulfite procurement patterns diverge sharply across product forms and end-use specifications. Application requirements for purity, moisture content, and handling characteristics create distinct supply chain configurations for each segment cluster.
Product Type:
Slurry and caustic formulations concentrate production capacity near chlor-alkali complexes where sulfur dioxide integration minimizes logistics costs.
- Calcium Sulfite Slurry:Aqueous suspension containing 15-30% solids by weight, pumped directly to flue gas scrubber systems. Coal-fired power plants in Shandong and Shanxi provinces account for concentrated demand as MEE retrofit deadlines compress procurement timelines.
- Calcium Sulfite Crystals:High-purity crystalline solid with sub-50 ppm heavy metal specifications enabling pharmaceutical and specialized food-grade applications. Japanese noodle and tofu processors are qualifying supply under tightened purity protocols, creating specification premiums over technical grades.
- Calcium Sulfite Caustic:Alkaline solution variant co-produced with sodium hydroxide in integrated chlor-alkali operations. Solvay S.A. leverages captive sulfur dioxide feedstock to stabilize input costs.
- Calcium Sulfite Dried:Dehydrated powder form with extended shelf stability for remote deployment. Bulk chemical distributors stock inventory for municipal water utilities with intermittent demand patterns.
Calcium Sulfite Slurry absorbs the bulk of installed capacity; Calcium Sulfite Crystals is expanding most quickly.
Application:
Cost tier differentiation separates commodity sulfur absorption from premium dechlorination and food-grade specifications.
- Flue Gas Desulfurization:Dominant volume application where calcium sulfite functions as SO₂ absorbent in wet scrubber systems. China's coal-fired fleet sustains baseline demand despite capacity retirements in coastal provinces.
- Water Treatment:Dechlorination agent for municipal distribution systems facing tightened residual chlorine limits. EPA mandates in the United States are expanding specification-grade procurement for utilities serving populations above 500,000.
- Production of White Pigments:Intermediate in titanium dioxide and lithopone manufacturing. Paint manufacturers in Germany and the Netherlands require REACH-compliant documentation adding 8-12% to delivered costs.
- Food Preservation:Oxygen-scavenging stabilizer in bleaching processes for starch and flour treatment. FSSAI-equivalent protocols in export markets constrain supplier qualification.
Flue Gas Desulfurization commands the largest production footprint; Water Treatment is climbing the fastest on regulatory tightening.
End User:
Customer type determines packaging, certification depth, and analytical support requirements.
- Power Plants:Continuous bulk consumers with dedicated slurry storage and direct pipeline delivery. Regional utility mergers in California and Texas are consolidating qualified vendor lists from 6-8 to 2-3 sources.
- Water Treatment Facilities:Specification-driven procurement with third-party purity verification. Sodium bisulfite liquid systems are displacing solid calcium sulfite in compact plants where handling automation is prioritized.
- Paint Manufacturers:Intermediate demand tied to titanium dioxide production cycles. REACH Annex XVII documentation requirements extend certification timelines.
- Food Processors:Smallest volume segment with strictest purity thresholds. Injectable-grade specifications are opening parenteral drug stabilization applications with substantial purity premiums.
Power Plants anchor volume commitments; Water Treatment Facilities are gaining share fastest on infrastructure expansion.
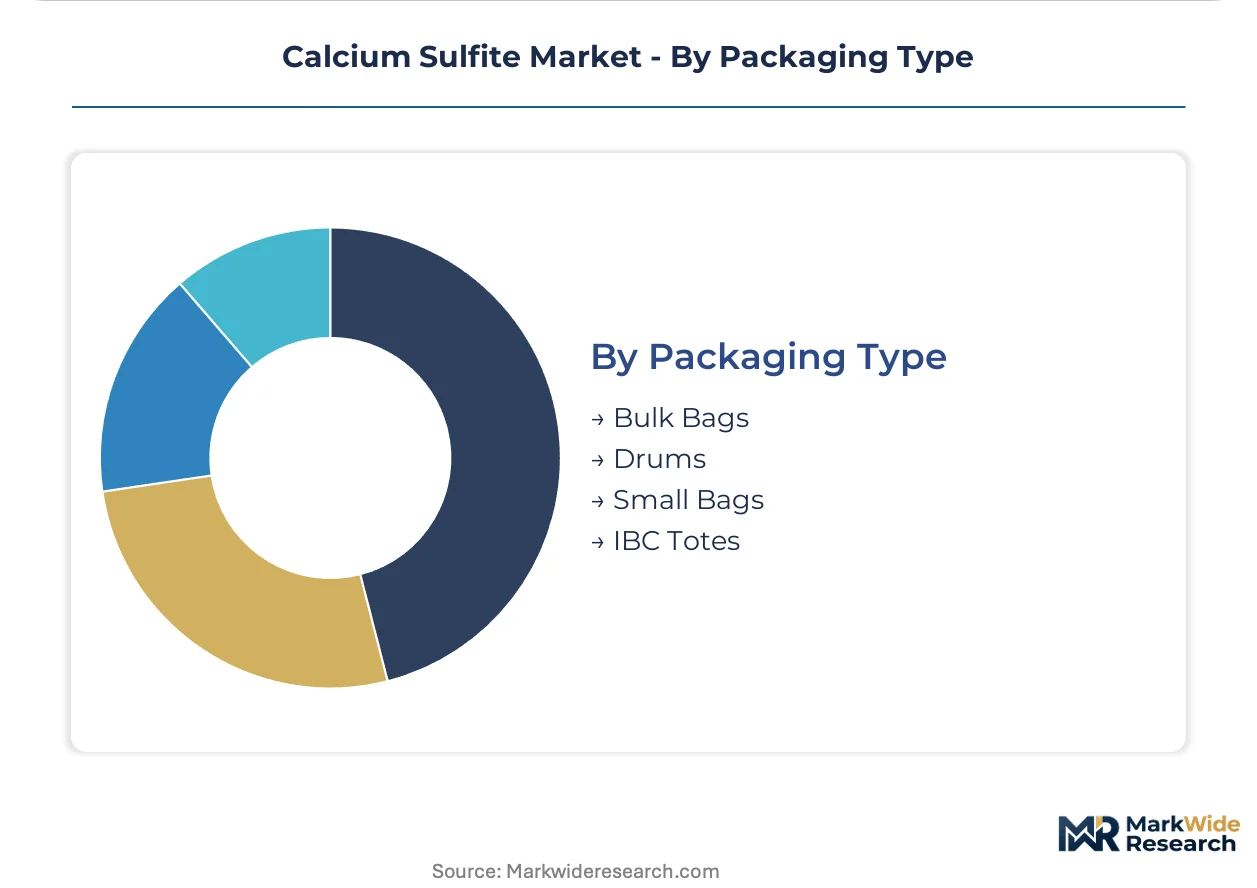
Packaging Type:
Logistics configuration varies with customer scale, site constraints, and handling automation levels.
- Bulk Bags:One-ton flexible intermediate containers for high-volume FGD and water treatment sites. Rail-served power plants in Shanxi province receive direct bulk bag shipments.
- Drums:200-liter steel or plastic containers for mid-scale industrial users. Paint manufacturers prefer drum delivery for controlled batch dosing.
- Small Bags:25-50 kg units for food processors and small municipal plants. Manual handling requirements limit adoption in automated facilities.
- IBC Totes:Intermediate bulk containers combining mobility with volume efficiency. Water treatment facilities with limited storage capacity deploy IBC totes for just-in-time replenishment.
Bulk Bags dominate tonnage flows; IBC Totes are expanding fastest on flexibility advantages in constrained sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal economic zones concentrate calcium sulfite capacity through integrated chlor-alkali complexes serving Shandong and Jiangsu industrial corridors. Municipal water infrastructure upgrades and power sector emission controls are reshaping procurement geography across four demand centers.
China
Shandong province power plants drive slurry demand through MEE-mandated FGD retrofits completing before year-end deadlines. GB water quality benchmarks tighten dechlorination chemical specifications for municipal utilities. Qingdao and Yantai chemical parks host integrated production platforms supplying both domestic utilities and export markets.
United States
EPA residual chlorine limits expand specification-grade procurement among utilities serving populations above 500,000. OSHA workplace exposure protocols shape handling requirements for dechlorination chemical distributors. California and Texas regional water district mergers consolidate qualified vendor lists through centralized master service agreements.
Germany
REACH Annex XVII impurity disclosure requirements extend certification timelines for sulfite water additives. ECHA Substance of Very High Concern screening triggers reformulation investments across municipal treatment portfolios. Rhine-Ruhr industrial corridor utilities now require third-party-verified purity certificates adding cost premiums to delivered product.
India
Jal Jeevan Mission rural pipeline expansion creates first-time dechlorination chemical demand in previously unserved districts. BIS water quality standards constrain supplier qualification for municipal procurement tenders. Gujarat and Maharashtra industrial clusters develop regional distribution networks serving western state water authorities.
Japan
FSSAI-equivalent purity protocols for food-grade applications drive qualification of high-crystal sulfite for noodle and tofu processing. METI chemical safety guidelines influence handling specifications for oxygen-scavenging applications. Osaka-Kobe industrial zone processors test pharmaceutical-grade specifications for parenteral drug stabilization.
Calcium Sulfite Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered specification segments. The vendor base separates into integrated chemical majors with captive sulfur dioxide feedstock, regional distributors serving single-country municipal markets, and specialty houses targeting pharmaceutical-grade purity premiums. Two dominant competitive moves are reshaping positioning: chlor-alkali producers deepening backward integration into sulfur recovery systems, and REACH-compliant suppliers investing in blockchain-tracked supply chain documentation to defend European market access.
Within the integrated chemical major tier, Solvay S.A. and Merck KGaA occupy positions exemplifying divergent strategic approaches. Solvay S.A., as a Belgian S.A., anchors European production through chlor-alkali platform integration. Merck KGaA, as a German KGaA, represents the pharmaceutical-grade specification vector with analytical chemistry capabilities supporting parenteral drug applications. American Elements, as a U.S.-based entity, sits within the North American rare earth and advanced materials co-production archetype competing on specification breadth.
| Leading Market Players |
|---|
| Qingdao Sunny Energy-Saving Materials Co., Ltd. |
| Shimmer Chemicals Private Limited |
| Aditya Birla Chemicals |
| American Elements |
| GFS Chemicals, Inc. |
| Solvay S.A. |
| Merck KGaA |
| Pure Tech Inc. |
| NOAH Technologies Corporation |
| Others |
Supply Flow & Price Mechanics
ICP-MS analytical chemistry specialists concentrated in Germany's Rhine-Ruhr corridor and China's Qingdao chemical parks drive labor-cost spreads between REACH-certified pharmaceutical grades and technical FGD slurry formulations. REACH documentation burdens and chlor-alkali integration advantages compress margin structures for non-captive producers while rewarding purity-grade specialization.
Pricing Analysis
Compressed lead-time premiums for MEE-mandated FGD retrofits in Shandong province command spot-market surcharges against annual contract baselines. Three-tier pricing structure across pharmaceutical-grade crystals, specification water-treatment solids, and commodity FGD slurry separates buyers by purity certification and analytical support depth. Cost compression in technical grades intensifies as sodium bisulfite liquid systems displace solid calcium sulfite in compact municipal plants. Water utilities serving populations above 500,000 show least price sensitivity due to master service agreement purity guarantees, while rural Indian districts under Jal Jeevan Mission exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for spent sulfite-gypsum co-production are compressing waste disposal liabilities at integrated chlor-alkali platforms in Belgium and coastal China. Primary supply concentrates in China, Belgium, and the United States, with captive sulfur dioxide feedstock from smelter off-gas and chlor-alkali operations anchoring cost positions. Raw material dependencies span sulfur dioxide gas, calcium hydroxide, and membrane electrodialysis purification chemicals. Single-source vulnerability in Chilean and Peruvian smelter off-gas creates input instability for non-integrated producers. Distribution runs through rail-served bulk terminals for power plants, drum networks for paint manufacturers, and IBC tote channels for constrained municipal sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH Annex XVII impurity disclosure requirements erect 12-18 month certification barriers that moat integrated European chlor-alkali producers against Asian commodity imports.
For Market Incumbents: Anchor backward integration into sulfur recovery systems to neutralize smelter off-gas volatility from Chile and Peru. Deepen captive chlor-alkali platform advantages in Belgium and coastal China to defend margin position against sodium bisulfite substitution in compact municipal plants. Prioritize blockchain-tracked supply chain documentation investments to maintain European market access under ECHA Substance of Very High Concern screening protocols. For New Entrants and Emerging Players: The premium-to-economy price-point gap in pharmaceutical-grade crystals offers white-space entry for membrane electrodialysis purification specialists. Target India's Jal Jeevan Mission rural pipeline expansion for first-time dechlorination chemical demand in unserved districts. Qualify under BIS water quality standards with regional distribution partnerships in Gujarat and Maharashtra industrial clusters as the go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors mid-tier producers with ICP-MS trace metal testing capabilities and pending REACH certification timelines. Long-term viability hinges on carbon border adjustment positioning as EU CBAM scope expansion favors low-carbon-intensity European production. Watch for MEE retrofit completion deadlines in China's coal-fired power sector as the inflection signal for FGD slurry demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Recovery | Captive SO₂ feedstock from chlor-alkali platforms neutralizes Chilean smelter disruption risk. |
| Membrane Electrodialysis Purification Scale-Up | Hybrid recrystallization yields sub-10 ppm heavy metal specifications for parenteral drug applications. |
| Blockchain-Tracked Supply Chain Documentation | ECHA REACH compliance requires third-party-verified purity certificates from sulfur source to crystal. |
| Regional Distribution Network Expansion | Gujarat and Maharashtra hubs serve Jal Jeevan Mission rural pipeline dechlorination demand. |
| Pharmaceutical-Grade Certification Investment | Injectable-grade sulfite specifications open oxygen-scavenging applications with purity premiums. |
Methodological Framework
Independent corroboration across plant managers at chlor-alkali complexes, procurement leads at Shandong power utilities, and technical R&D directors at water treatment chemical houses underwrites the qualitative findings. Primary interviews with distribution channel partners and regulatory affairs specialists at ECHA-notified bodies combined with secondary validation from customs/trade data, ACC/Cefic chemical industry reports, and SEC 10-K filings from integrated producers. Bottom-up segmentation modeling triangulates against top-down macro chemical demand indicators.
Rate-of-change decomposition across the analysis window isolates volume drivers by grade tier, end-use industry, packaging format, and regional production hub. CAGRs derive from weighted average of historical trajectory and regulatory-inflected demand shifts. Modeled inputs include EPA residual chlorine limit enforcement timelines, MEE FGD retrofit completion patterns, and REACH certification queue dynamics at ECHA.
Inputs from chlor-alkali platform operators and municipal utility procurement officers were available through the study window; gaps in real-time smelter off-gas pricing from Chile and Peru introduce uncertainty bands around sulfur feedstock cost assumptions. Practitioners should monitor ECHA Substance of Very High Concern candidate list updates and China MEE emission standard enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
Oxalic Acid Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
Triammonium Citrate Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
United States Iodine Market
Bulk Chemicals
Asia-Pacific Formic Acid Market
Bulk Chemicals
Tin Fluoborate Market
Bulk Chemicals
Global Purified Terephthalic Acid (PTA) Market
Bulk Chemicals
North America Lime Market