
 Monostarch Phosphate Market | 2026-2036
Monostarch Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Monostarch Phosphate Market Foresight
Multi-source procurement for phosphate-modified starch intermediates is pivoting toward vertically integrated corn processors with captive phosphate esterification capacity. Cargill Incorporated leverages its North American corn origination network to anchor supply security for food-grade monostarch phosphate. Ingredion competes through specialty starch R&D intensity, while Roquette Freres dominates European pea and potato starch alternatives for phosphate modification.
Monostarch phosphate is a chemically modified starch produced by esterifying native starch with orthophosphoric acid, yielding a product with enhanced freeze-thaw stability, improved viscosity under shear, and tolerance to acidic pH environments for industrial processing. The compound functions primarily as a thickener, stabilizer, and emulsifier across food systems, pharmaceutical suspensions, and cosmetic emulsions. Modified starch commands the largest value share among product types due to its versatility in processed foods, while specialty starch represents the fastest-growing category as pharmaceutical companies demand excipients with precise dissolution profiles. Food and beverage applications sustain the broadest demand base, though pharmaceutical applications are deepening as oral disintegrating tablet formulations expand.
FDA food additive regulations under 21 CFR 172.892 govern phosphate substitution limits in starch esters for U.S. market access, while EFSA's re-evaluation of phosphates as food additives is tightening maximum permitted levels across European formulations. China's SAMR enforces GB standards for modified starch purity in domestic food manufacturing, creating compliance differentiation between export and domestic-grade producers. Stakeholders must monitor regulatory divergence on phosphate carryover limits as formulation decisions in one jurisdiction increasingly constrain recipe portability into others.
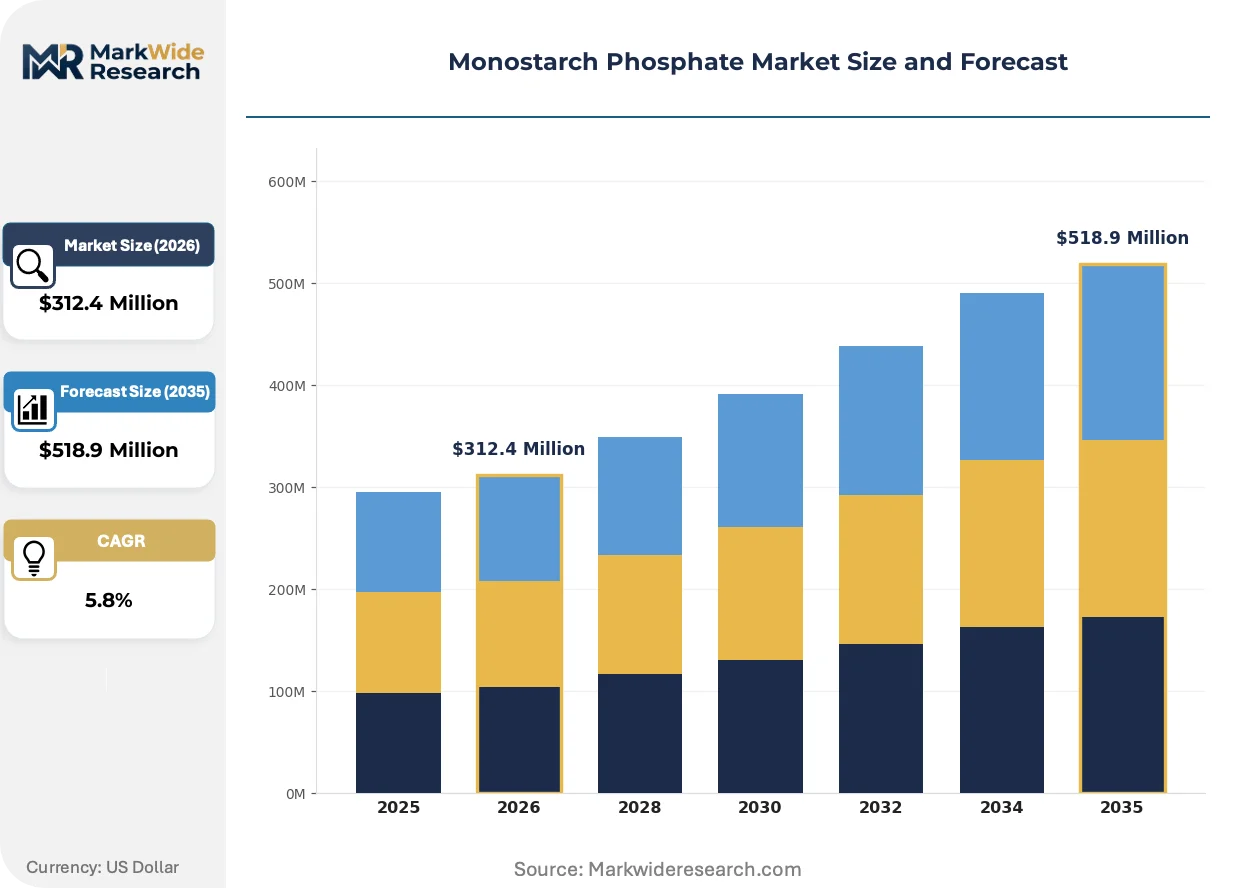
Market Dynamics
Phosphate esterification capacity is concentrating among corn wet-millers with captive orthophosphoric acid supply, compressing margins for toll-modifiers and reshaping procurement security calculations for food-grade monostarch phosphate buyers.
Growth Catalysts
- EFSA phosphate re-evaluation:Tightened purity thresholds under EFSA's 2023-2025 food additive review cycle are accelerating technical-grade inventory obsolescence, creating replacement demand for certified-compliant monostarch phosphate in European dairy and meat applications.
- Freeze-thaw stability requirements:Frozen dough and par-baked bakery segments are specifying phosphate-modified starches to maintain viscosity through industrial blast-freezing and distribution cold chains.
- Shandong province cluster density:China's corn wet-milling concentration in Shandong enables integrated phosphate esterification at scale, reducing logistics costs for regional food processors versus imported modified starches.
Market Restraints
- Orthophosphoric acid price volatility:Phosphate rock supply disruptions and energy-intensive acid production create input cost instability that compound margin pressure on non-integrated modifiers.
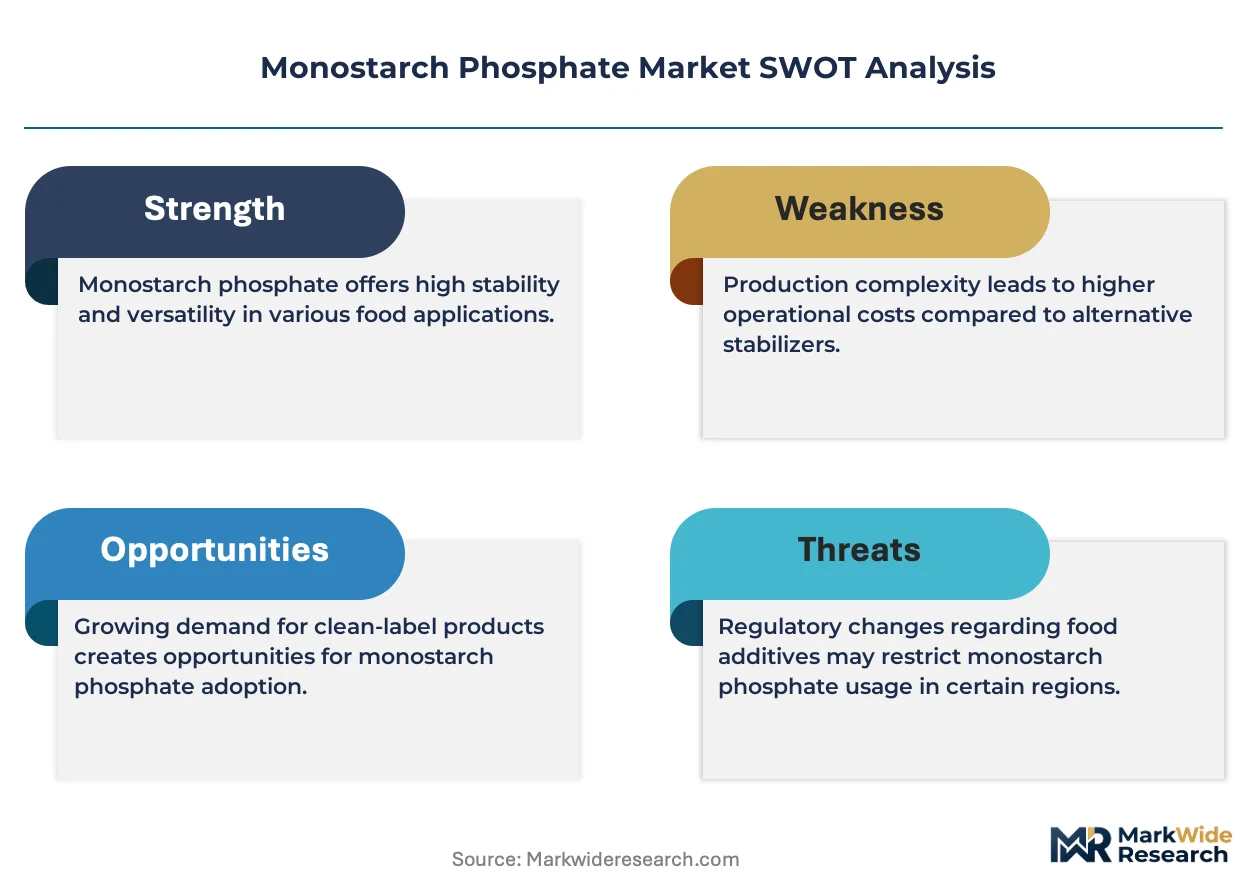
- Substitution by native starch blends:Clean-label formulators in premium retail channels are substituting cold-water-swelling native starches and hydrocolloid combinations for phosphate-modified alternatives where regulatory thresholds permit.
- Dual certification burden:Exporters to both FDA-regulated and EFSA-regulated markets face divergent phosphate carryover limits, forcing parallel inventory management and recipe versioning that elevates working capital requirements.
Strategic Opportunities
- Pharmaceutical excipient expansion:Oral disintegrating tablet formulations are creating demand for precisely controlled dissolution profiles that specialty-grade monostarch phosphate can deliver, opening higher-margin segments beyond food applications.
- Pea and potato starch phosphate modification:Non-corn starch bases are gaining traction in allergen-free and non-GMO formulations, with European processors leading technical development of alternative raw material esterification.
- Direct processor partnerships:Food manufacturers are bypassing distribution intermediaries to contract directly with wet-millers for modified starch supply, securing volume allocation and technical collaboration on custom viscosity specifications.
Industry Challenges
- Phosphate esterification chemist scarcity:The specialized knowledge required to manage degree of substitution, pH tolerance, and cross-linking ratios is concentrated among aging technical workforces in Midwestern US and European starch processing hubs.
- Clean-label formulation trade-offs:Technical teams face pressure to eliminate phosphate-modified ingredients while maintaining freeze-thaw stability and shear tolerance in industrial processing lines designed around modified starch rheology.
- SAMR-GB standard alignment:Exporters to China must reconcile domestic-grade purity specifications with export-grade certifications, creating batch segregation complexity and audit trail documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monostarch Phosphate Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unmodified Starch, Modified Starch, Specialty Starch, Instant Starch Application: Food & Beverage, Pharmaceuticals, Cosmetics, Industrial End User: Food Manufacturers, Pharmaceutical Companies, Personal Care Brands, Chemical Producers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ajinomoto Co. Inc., Corn Products International Inc., Roquette Freres, Ingredion, Tate & Lyle, BASF, Avebe U.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monostarch Phosphate Market Shifts & Advancements
Clean-label pressure and pharmaceutical precision requirements are bifurcating technical development paths, with one stream pursuing phosphate reduction and the other advancing substitution-controlled specialty grades for controlled-release applications.
Enzyme-assisted esterification is absorbing process development investment from major starch processors seeking to reduce orthophosphoric acid consumption and energy inputs while maintaining degree-of-substitution consistency. Pharmaceutical excipient manufacturers are piloting these biocatalytic routes for specialty-grade production, though food-grade scale-up remains limited by cost parity thresholds. The technology is absorbing technical talent from conventional chemical esterification teams and compressing R&D timelines for next-generation modified starches.
REACH registration requirements for phosphate ester intermediates are tightening documentation burdens on European modified starch producers, with ECHA substance evaluation deadlines forcing supply chain audits back to phosphate rock origins. Industrial consequences include elevated compliance costs that disadvantage smaller toll-modifiers versus integrated corn processors with dedicated regulatory affairs capacity. Specialty starch segments serving pharmaceutical and cosmetic applications are most affected, with formulators accelerating supplier consolidation toward REACH-registered producers.
Specification-driven procurement is replacing commodity spot purchasing for phosphate-modified starches, with food manufacturers embedding technical teams at wet-miller facilities to co-develop viscosity profiles for specific processing lines. Direct technical collaboration is displacing traditional distributor-mediated transactions in North American and European markets, compressing channel margins and elevating importance of application laboratories at supplier sites. This pattern is most visible in frozen dough and retorted sauce segments where shear stability failures carry high line-down costs.
Monostarch Phosphate Market Segmentation
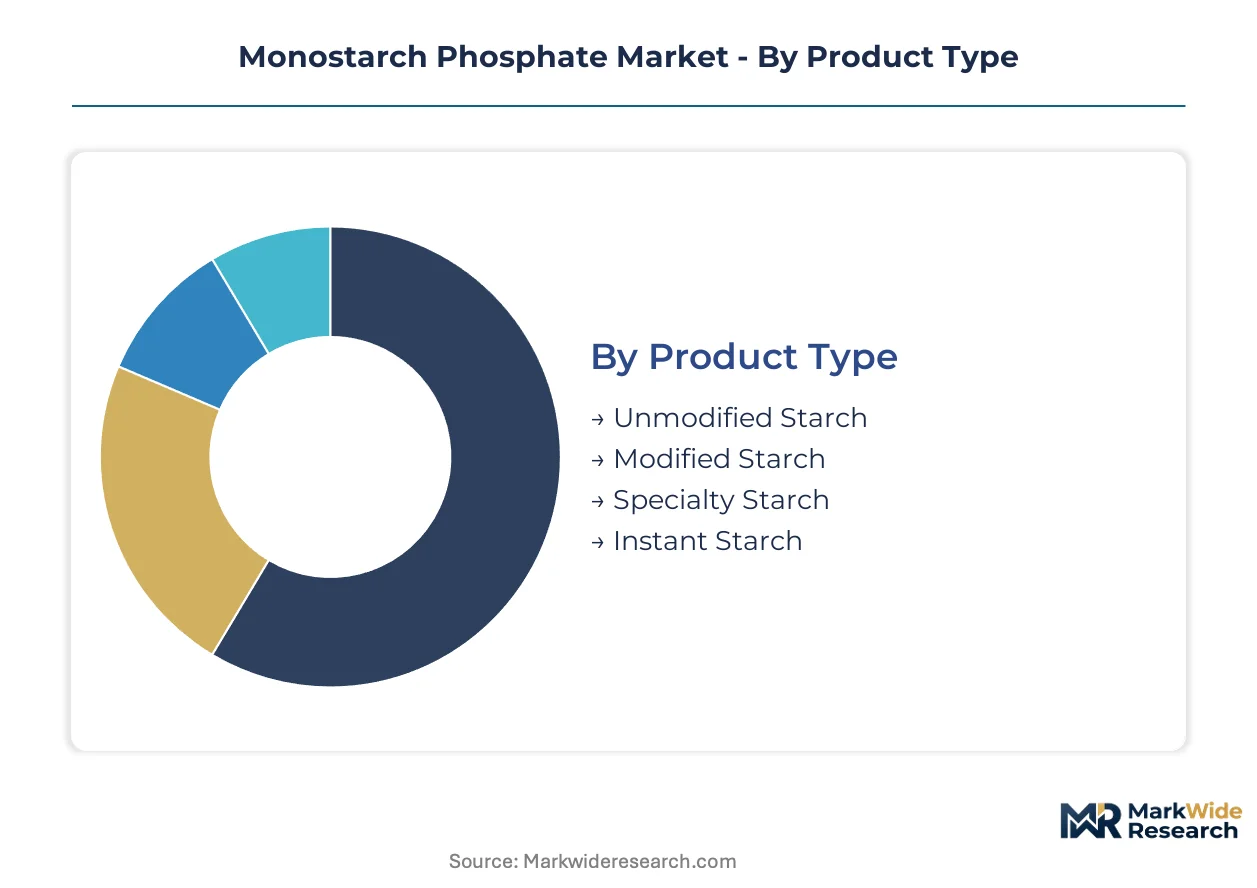
Monostarch phosphate procurement patterns diverge sharply across product grades and end-use specifications. Food manufacturers prioritize freeze-thaw stability and shear tolerance, while pharmaceutical buyers demand precise dissolution control that only specialty grades deliver.
Product Type:
Supply concentration among corn wet-millers with captive phosphate esterification capacity has compressed margins for toll-modifiers and reshaped procurement security calculations.
- Modified Starch:Esterified native starch with orthophosphoric acid delivers enhanced viscosity under shear and acid pH tolerance for industrial processing lines. Food manufacturers in China's Shandong province specify this grade for frozen dough and retorted sauce applications where line-down costs from stability failures run high.
- Specialty Starch:Precision-controlled degree of substitution enables targeted dissolution profiles for pharmaceutical excipient applications. Oral disintegrating tablet formulations from European and North American drug manufacturers are absorbing expanding volumes of this highest-margin category.
- Unmodified Starch:Native starch without phosphate modification serves cost-sensitive applications where clean-label positioning outweighs functional performance requirements.
- Instant Starch:Pre-gelatinized variants enable cold-water swelling for convenience food formulations and quick-preparation bakery mixes.
Today's leader: Modified Starch. Tomorrow's challenger: Specialty Starch.
Application:
Cost tier differentiation separates commodity food-grade volumes from certified pharmaceutical and cosmetic grades that command premium positioning.
- Food & Beverage:The broadest demand base spans frozen dough, dairy, meat, and sauce applications where freeze-thaw stability and emulsification are non-negotiable. EFSA's tightened phosphate purity thresholds are accelerating technical-grade inventory obsolescence and replacement demand across European dairy and meat processors.
- Pharmaceuticals:Controlled-release and oral disintegrating tablet formulations require excipients with dissolution profiles that only specialty-grade monostarch phosphate can deliver. FDA's 21 CFR 172.892 phosphate substitution limits and EFSA's re-evaluation create dual certification burdens that favor integrated producers with dedicated regulatory affairs capacity.
- Cosmetics:Emulsion stabilization for skin-care and hair-care formulations absorbs modest volumes, with REACH registration requirements for phosphate ester intermediates tightening supplier qualification standards.
- Industrial:Adhesive, textile sizing, and paper coating applications consume technical-grade modified starch where functional performance outweighs food-grade purity requirements.
Food & Beverage commands current volume leadership. Pharmaceuticals are climbing the fastest as oral disintegrating tablet formulations expand.
End User:
Customer type determines specification intensity, with pharmaceutical companies embedding technical teams at supplier sites while food manufacturers balance performance against clean-label pressure.
- Food Manufacturers:Frozen dough and par-baked bakery segments specify phosphate-modified starches to maintain viscosity through industrial blast-freezing and distribution cold chains. Direct processor partnerships are displacing distributor-mediated transactions as manufacturers seek volume allocation security.
- Pharmaceutical Companies:Excipient buyers demand batch-to-batch consistency in degree of substitution and dissolution profiles, with supplier consolidation accelerating toward REACH-registered producers with dedicated application laboratories.
- Personal Care Brands:Cosmetic formulators prioritize emulsion stability and skin-feel characteristics, with allergen-free and non-GMO positioning driving interest in pea and potato starch phosphate modifications.
- Chemical Producers:Industrial end users procure technical-grade modified starch for adhesive and textile applications where cost efficiency dominates specification requirements.
Food Manufacturers anchor present demand. Pharmaceutical Companies represent the steepest expansion trajectory as controlled-release formulations proliferate.
Distribution Channel:
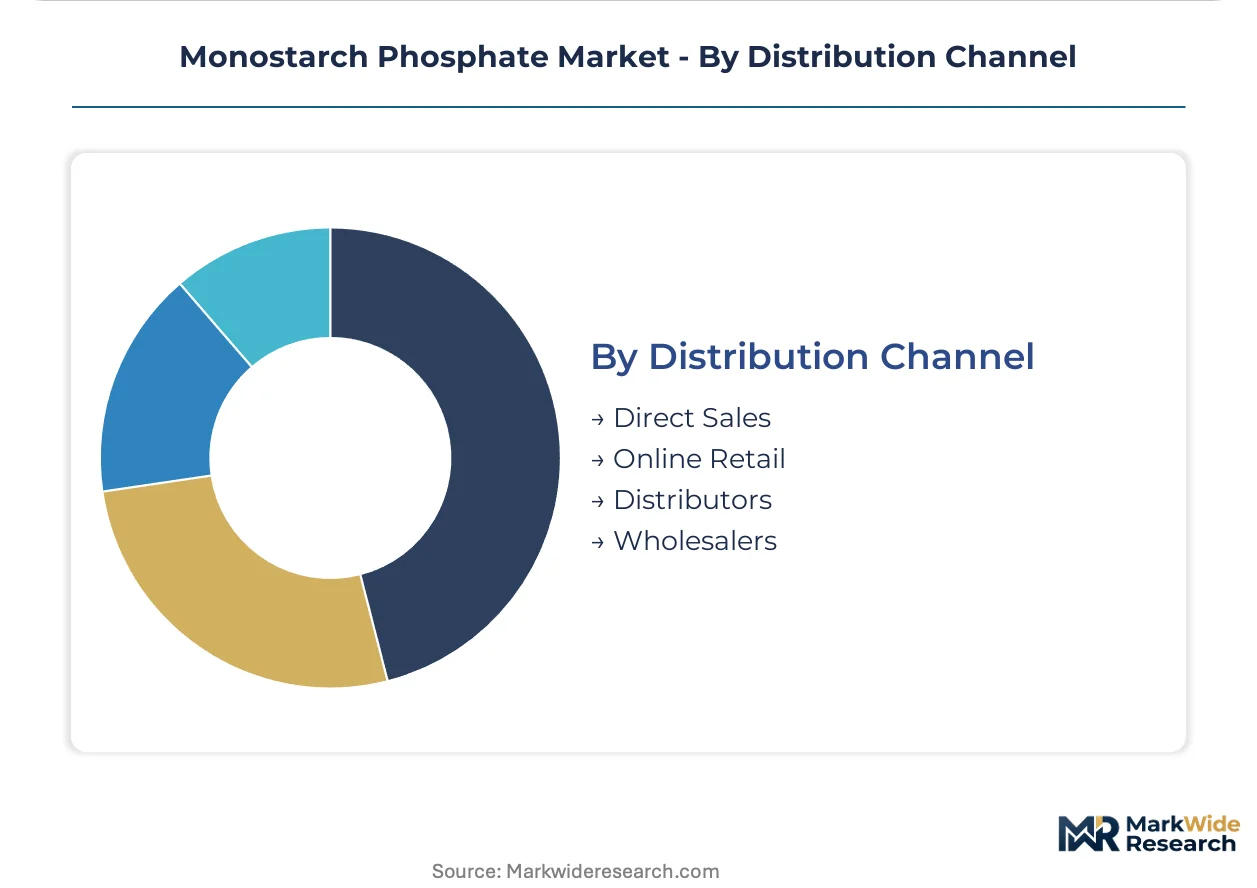
Volume concentration among large food and pharmaceutical processors is compressing channel margins and elevating importance of direct technical collaboration.
- Direct Sales:Specification-driven procurement with embedded technical teams at wet-miller facilities now dominates North American and European markets for frozen dough and retorted sauce segments.
- Distributors:Regional chemical distributors serve mid-tier food manufacturers and industrial processors lacking scale for direct processor partnerships.
- Wholesalers:Bulk volume aggregation supports smaller bakery and sauce producers with standardized viscosity specifications.
- Online Retail:Limited to specialty and instant starch variants for small-scale cosmetic and artisan food producers.
Direct Sales leads current channel mix. Distributors face margin compression as procurement concentrates among integrated processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence on phosphate carryover limits is redirecting investment toward jurisdictions with aligned certification standards, compressing export opportunities for producers serving multiple compliance regimes simultaneously.
United States
Frozen dough manufacturers in the Midwest specify phosphate-modified starches for blast-freezing tolerance. FDA's 21 CFR 172.892 governs phosphate substitution limits for domestic market access. Corn wet-milling clusters in Iowa and Illinois anchor captive phosphate esterification capacity for regional food processors.
China
Domestic food manufacturers in Shandong province expand modified starch procurement for clean-label formulations. SAMR enforces GB standards for modified starch purity, creating compliance differentiation between export and domestic-grade producers. The province's corn wet-milling concentration enables integrated phosphate esterification at scale.
Germany
Pharmaceutical excipient buyers demand batch-to-batch consistency in degree of substitution for controlled-release formulations. REACH registration requirements for phosphate ester intermediates tighten documentation burdens on modified starch producers. Industrial processors in North Rhine-Westphalia lead technical development of pea and potato starch phosphate modifications.
France
Roquette Freres dominates European pea and potato starch alternatives for phosphate modification. EFSA's re-evaluation of phosphates as food additives tightens maximum permitted levels across European formulations. The company's Lestrem facility anchors specialty starch R&D intensity for allergen-free positioning.
Japan
Oral disintegrating tablet formulations from domestic drug manufacturers absorb expanding volumes of specialty-grade monostarch phosphate. METI oversees industrial standards for modified starch applications in pharmaceutical and food sectors. Technical development concentrates in the Kansai region's excipient manufacturing corridor.
Monostarch Phosphate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade specialization and enzyme-assisted esterification routes. The vendor base compresses toward integrated corn processors with captive orthophosphoric acid supply, while toll-modifiers face margin pressure from input cost volatility. Three archetypes dominate: North American grain-originators with origination networks, European pea-potato starch specialists, and Asian fermentation-derived processors. Competitive moves concentrate on backward integration into phosphate rock supply and direct technical partnerships with frozen dough and pharmaceutical formulators.
Within the grain-origination archetype, Cargill Incorporated and Archer Daniels Midland Company represent integrated processors leveraging captive corn supply chains. Roquette Freres exemplifies the European alternative-starch vector, while Ingredion occupies a position bridging standard and specialty grades through R&D intensity. Tate & Lyle and BASF sit within the ingredient-systems tier, anchoring formulation partnerships rather than commodity supply. These six entities collectively represent the competitive core, with the remainder fragmenting across regional toll-modifiers and single-site specialists.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ajinomoto Co. Inc. |
| Corn Products International Inc. |
| Roquette Freres |
| Ingredion |
| Tate & Lyle |
| BASF |
| Avebe U.A. |
| Others |
Supply & Pricing Matrix
Captive phosphate esterification capacity at integrated corn wet-millers anchors both supply security and pricing power for food-grade monostarch phosphate. This backward integration into orthophosphoric acid production insulates major processors from input cost volatility that compresses margins for toll-modifiers across the United States, China, and Germany.
Pricing Analysis
Distributor margins in European markets face compression as direct technical partnerships displace traditional channel relationships. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels reflects certification burden divergence between FDA and EFSA compliance regimes. Pricing pressure stems from orthophosphoric acid feedstock volatility and substitution by native starch blends in clean-label retail channels. Mid-tier food manufacturers exhibit highest price sensitivity, while pharmaceutical excipient buyers prioritize batch consistency over unit economics.
Supply Chain Analysis
Specialized phosphate esterification chemist scarcity in Midwestern US and European starch processing hubs constrains capacity expansion timelines. Supply concentrates in China's Shandong province, the United States Corn Belt, and France's potato starch corridor, with raw material dependencies centering on corn, pea, and potato feedstocks plus phosphate rock-derived orthophosphoric acid. Single-source vulnerability around phosphate rock supply from concentrated mining jurisdictions elevates contingency planning requirements. Distribution runs through direct processor partnerships for large-volume food and pharmaceutical accounts, with regional chemical distributors serving mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EFSA's 2023-2025 phosphate re-evaluation cycle accelerating certified-compliant inventory replacement across European dairy and meat applications.
For Market Incumbents: Acquire specialized phosphate esterification technical teams to counter workforce scarcity in Midwestern US and European processing hubs. Expand captive orthophosphoric acid capacity to defend margin position against input cost volatility from phosphate rock supply disruptions. Prioritize dual FDA-EFSA certification infrastructure to capture replacement demand from technical-grade inventory obsolescence. For New Entrants and Emerging Players: Pharmaceutical excipient buyers seeking REACH-registered suppliers with dissolution profile precision represent the most penetrable white-space target. Pea and potato starch phosphate modification for allergen-free positioning offers technical differentiation in European and North American specialty segments. Pursue enzyme-assisted esterification pilot partnerships to bypass conventional chemical process barriers. For Investors and Strategic Acquirers: Roll-up economics work for toll-modifiers with regional customer relationships because integrated corn processors face capacity constraints at specialty-grade purity thresholds. Five-to-ten year viability hinges on regulatory certification infrastructure rather than commodity scale. Monitor EFSA phosphate carryover limit finalization as inflection indicator for European replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orthophosphoric Acid | Corn wet-millers with captive acid supply insulate margins from phosphate rock price volatility. |
| Dual Certification Infrastructure Investment | Parallel FDA and EFSA compliance capacity enables recipe portability across Atlantic markets. |
| Enzyme-Assisted Esterification Scale-Up | Biocatalytic routes reduce energy inputs while maintaining degree-of-substitution consistency. |
| Direct Processor Partnership Expansion | Embedded technical teams at wet-miller facilities secure volume allocation for frozen dough manufacturers. |
| Specialty Starch R&D Intensification | Precision-controlled dissolution profiles capture oral disintegrating tablet formulation demand. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Plant managers at corn wet-milling facilities, procurement leads at frozen dough manufacturers, regulatory affairs directors at excipient suppliers, and technical R&D heads at starch processors provided operational perspectives. Secondary sources include FDA 21 CFR filings, EFSA food additive re-evaluation documentation, SAMR GB standards publications, and trade flow data from customs authorities. Bottom-up capacity and demand modeling triangulates against top-down market sizing across the analysis window.
Granularity-level modeling spans product type, application, end user, and distribution channel dimensions, with additional segmentation by regional regulatory cluster. CAGRs derive from trend extrapolation adjusted for substitution dynamics and regulatory milestone impacts. Forecast inputs incorporate phosphate rock supply disruption scenarios, clean-label formulation substitution rates, and pharmaceutical excipient specification tightening trajectories throughout the forecast period.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes carry tighter precision than technical-grade industrial applications due to documented batch certification requirements. Forecasts reflect assumptions around EFSA re-evaluation implementation timing, SAMR-GB standard alignment progress, and enzyme-assisted process cost parity achievement. Material deviation in phosphate rock supply stability or regulatory threshold finalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
South America Food Preservatives Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Australia Feed Additives Market
Food Additives and Ingredients
Fruit and Vegetable Processing Enzymes Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Global Organic Food Preservatives Market
Food Additives and Ingredients
Clean Label Ingredients Market