
 Ammonia Caramel Market | 2026-2036
Ammonia Caramel Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonia Caramel Market Outlook
Class I plain caramel specification upgrades are unwinding across European beverage supply chains, forcing reformulation investments upstream. DDW The Color House leverages captive extraction capabilities to sustain margin pools in premium liquid grades. Sensient Technologies Corporation anchors North American supply through dedicated caramel colorant facilities in Wisconsin. Sethness Products Company differentiates via specialized paste formulations for high-heat bakery applications.
Ammonia caramel denotes a Class III caramel color produced by heating carbohydrates with ammonium compounds under controlled pressure, yielding a red-brown hue with a positive colloidal charge optimized for beer, soy sauce, and soft drink matrices. Its primary commercial purpose centers on delivering stable, light-resistant coloration in acidic liquid environments where sulfite-bearing alternatives fail. Liquid formats dominate volume throughput in beverage manufacturing, while powder grades capture margin concentration in export-oriented confectionery channels. Bakery applications show structural acceleration as clean-label positioning displaces azo dyes across European private-label bread programs.
US FDA 21 CFR 73.85 governs identity and purity standards for caramel coloring, while EFSA maintains specific 4-MeI exposure thresholds that constrain process chemistry choices in EU facilities. India's FSSAI has aligned with Codex Alimentarius parameters for Class III caramel, reducing import friction for multinational suppliers. Stakeholders must monitor evolving 4-MeI regulatory thresholds across jurisdictions, as tightening toxicology benchmarks could force capital-intensive reactor modifications or segment abandonment in sensitive applications.
Market Dynamics
EU regulators through EFSA are compressing 4-MeI exposure thresholds, forcing ammonia caramel producers to reconfigure reactor chemistry or abandon sensitive beverage applications entirely. This regulatory compression is reshaping capital allocation across Class III caramel manufacturing.
Growth Catalysts
- India's FSSAI Codex alignment:Reduced import friction enables multinational suppliers to penetrate India's processed food corridor, where sauce and confectionery producers actively substitute synthetic dyes with ammonia caramel alternatives.
- Clean-label bakery displacement:European private-label bread programs are eliminating azo dyes, creating immediate formulation pull for heat-stable caramel colorants in high-temperature applications.
- Asia-Pacific beverage procurement:Cola and dark beer manufacturers across India, Thailand, and Vietnam are expanding liquid caramel colorant volumes to achieve consistent red-brown hue stability in acidic matrices.
Market Restraints
- Sugar feedstock volatility:Sucrose and glucose syrup prices fluctuate with Brazilian and Indian monsoon cycles, compressing margin predictability for caramel producers locked into annual beverage supply contracts.
- Process chemistry rigidity:Ammonia-based reactors cannot pivot quickly to sulfite or ammonium-sulfite hybrid processes, stranding capital when EFSA tightens 4-MeI thresholds without warning.
- Natural colorant substitution:Anthocyanin and beetroot extracts are capturing premium beverage positioning in Nordic markets, eroding ammonia caramel's historic dominance in clean-label soft drinks.
Strategic Opportunities
- India's sauce manufacturing corridor:Domestic soy sauce and condiment producers in Maharashtra and Gujarat lack captive caramel colorant production, creating white space for toll manufacturing partnerships.
- EU F-Gas Regulation spillover:Refrigeration-dependent natural colorants face supply chain headwinds, indirectly stabilizing demand for shelf-stable ammonia caramel in temperature-sensitive logistics channels.
- Powder-grade export channels:Confectionery manufacturers in Middle Eastern and African markets prioritize dry-format caramel for extended shelf life, commanding margin premiums over liquid alternatives.
Industry Challenges
- Reactor reconfiguration timelines:EFSA-mandated 4-MeI reductions require 18-24 month capital cycles for pressure vessel and catalyst bed modifications, creating compliance gaps during transition periods.
- Analytical chemist scarcity:Specialized expertise in colloidal charge measurement and HPLC-based 4-MeI quantification concentrates in Western European labor pools, constraining quality control scaling in emerging production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonia Caramel Market |
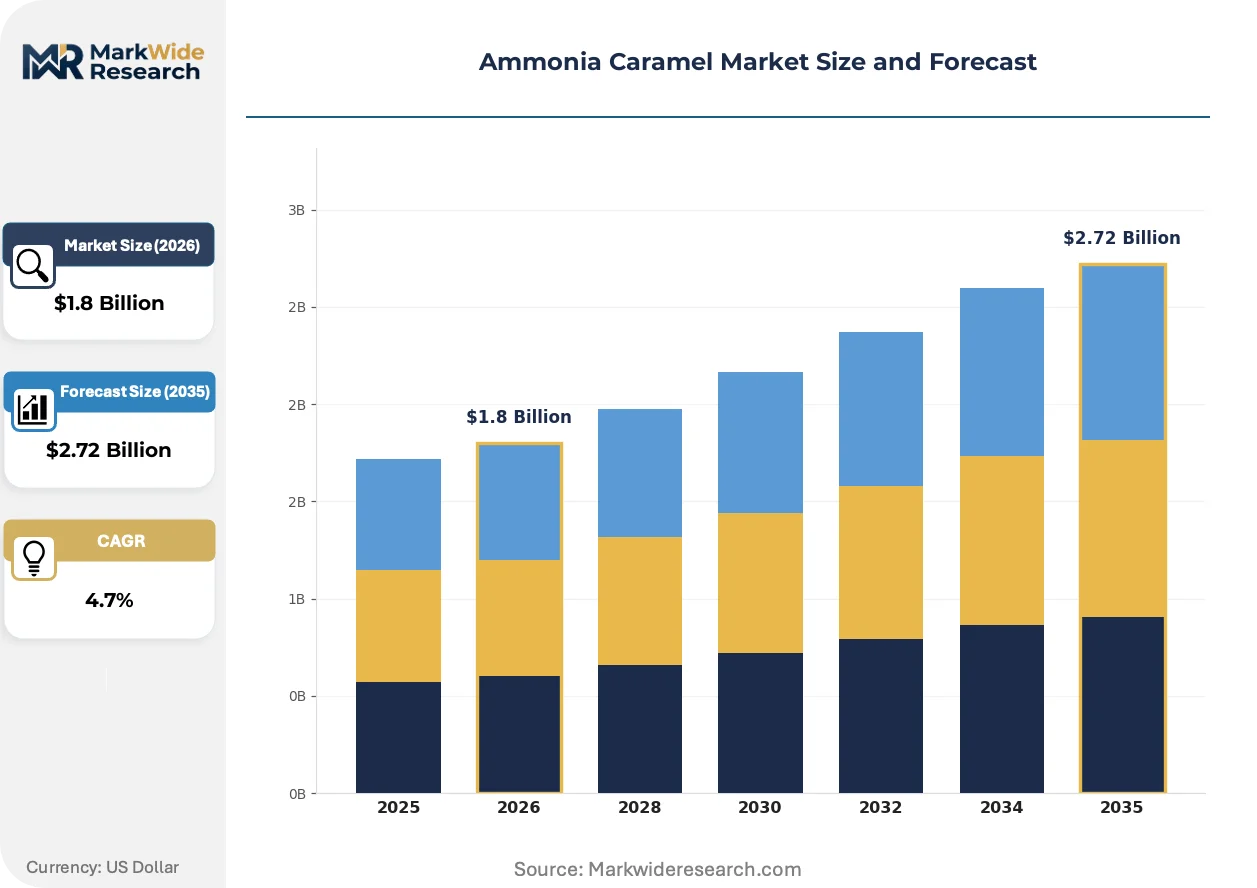
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Paste, Granulated Application: Beverages, Bakery, Confectionery, Sauces End User: Food Industry, Beverage Manufacturers, Home Cooks, Catering Services Distribution Channel: Online Retail, Supermarkets, Wholesalers, Direct Sales |
| Companies Covered | DDW The Color House, Sethness Products Company, Sensient Technologies Corporation, Aarkay Food Products Ltd, Roquette, Nigay, Ingredion Incorporated, D.D. Williamson & Co., Inc., Bakels Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonia Caramel Market Strategic Shifts
Membrane filtration and continuous processing technologies are fragmenting traditional batch reactor economics, while regulatory chemistry specifications and procurement consolidation reshape competitive positioning across liquid and powder formats.
Membrane-based carbohydrate clarification is fragmenting upstream supply structures. This technology removes protein and ash impurities before caramelization, yielding higher purity feedstocks with predictable reaction kinetics. Beverage manufacturers in Germany and the Netherlands are specifying membrane-clarified inputs for premium cola formulations. The technology is fragmenting historical supplier relationships built on commodity glucose specifications, enabling direct processor-to-brand procurement.
REACH Annex XVII amendments are expanding substance restriction scopes that indirectly affect caramel colorant adjuvants and processing aids. Industrial consequence includes mandatory substitution of certain catalyst carriers and pH adjustment compounds used in ammonium-based reactions. Powder-grade exporters to EU confectionery channels are most affected, accelerating reformulation investments to maintain EFSA compliance documentation.
Beverage procurement departments are consolidating supplier panels from six-to-eight vendors down to two-to-three strategic partners with captive reactor capacity and multi-jurisdiction regulatory dossiers. Direct contracting with integrated caramel producers is replacing distributor-mediated spot purchasing in North American and Western European markets. This concentration is most visible in cola and energy drink verticals, where formulation consistency requirements override price minimization objectives.
Ammonia Caramel Market Segmentation
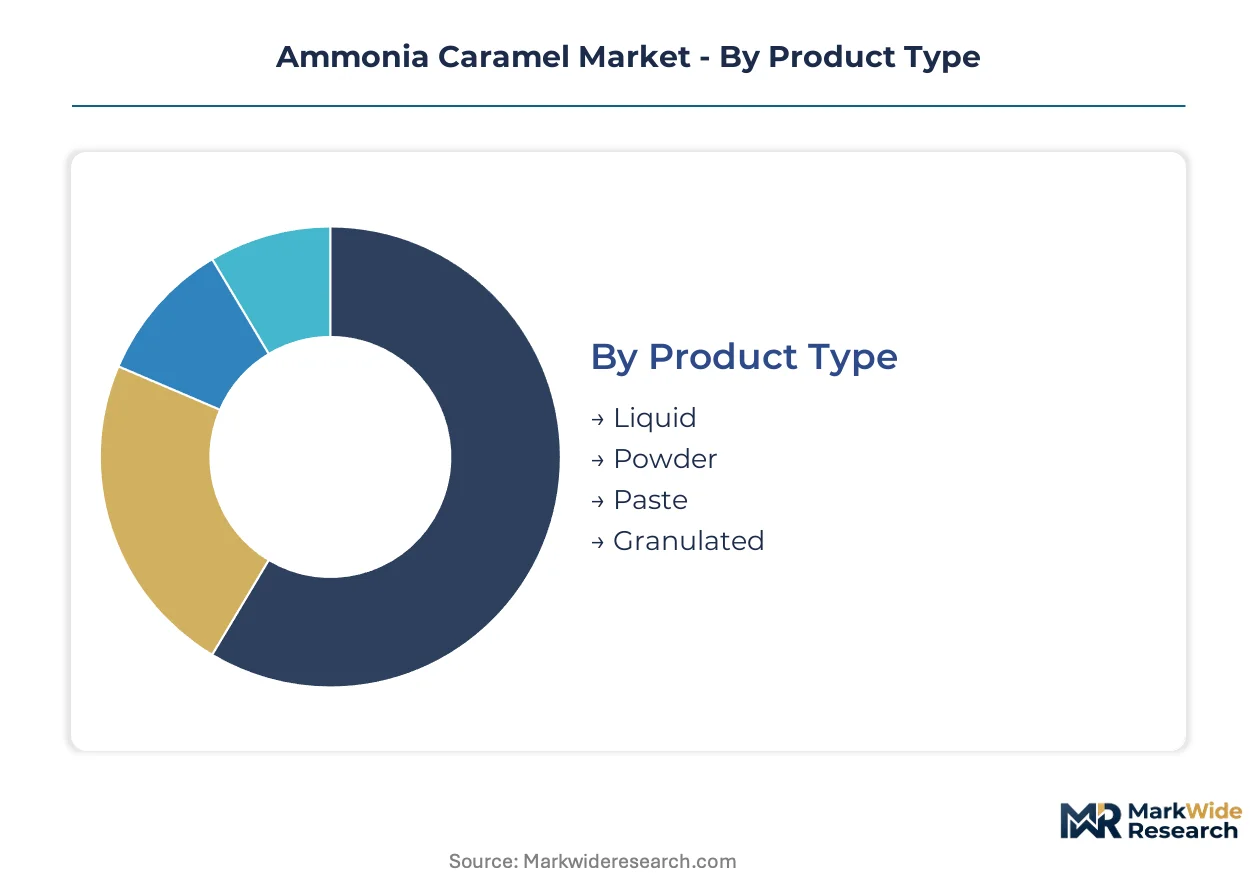
Segmentation in ammonia caramel reveals divergent vulnerability to natural colorant substitution, with liquid beverage grades facing anthocyanin displacement while powder confectionery formats retain structural insulation through shelf-stability requirements.
Product Type:
Liquid formats confront the most acute substitution pressure from beetroot and grape-skin extracts in Nordic clean-label beverages, whereas powder and paste grades maintain defensible positions in heat-processed and shelf-stable applications.
- Liquid:Dominates cola and dark beer manufacturing with optimized colloidal charge for acidic matrices. Procurement concentrates among Thai and Vietnamese beverage bottlers expanding caramel colorant volumes for export-oriented soft drink lines.
- Powder:Captures margin premiums in Middle Eastern and African confectionery export channels where extended shelf life dictates dry-format preference. Manufacturers in Maharashtra and Gujarat sauce corridors increasingly specify powder grades for inventory stability.
- Paste:Specialized high-heat bakery applications in European private-label bread programs.
- Granulated:Emerging format for precision dosing in industrial catering operations.
Liquid retains volume leadership; powder holds the steepest expansion curve.
Application:
Cost tier stratification separates premium beverage formulations from commodity bakery applications, with sauce manufacturing occupying a mid-tier position defined by import tariff exposure.
- Beverages:Largest consumption segment spanning carbonated soft drinks, dark beers, and energy drinks. German and Dutch cola producers are specifying membrane-clarified caramel inputs, fragmenting historical commodity glucose supplier relationships.
- Bakery:Structural acceleration as EFSA-mandated azo dye elimination across European private-label bread programs creates immediate formulation pull for heat-stable caramel colorants.
- Confectionery:Powder-grade dominance in Middle Eastern and African markets prioritizing dry-format logistics.
- Sauces:Soy sauce and condiment manufacturing in India's Maharashtra and Gujarat corridors.
Beverages command the revenue pool; bakery applications are expanding most quickly.
End User:
Customer type fragmentation concentrates procurement power among multinational beverage manufacturers while dispersing demand across fragmented food industry and catering channels.
- Food Industry:Processed sauce and confectionery producers in India substituting synthetic dyes with ammonia caramel alternatives.
- Beverage Manufacturers:Consolidating supplier panels from six-to-eight vendors down to two-to-three strategic partners with captive reactor capacity.
- Home Cooks:Minimal penetration; caramel colorant demand concentrates in industrial formulations.
- Catering Services:Granulated format adoption for precision dosing in large-batch food service operations.
Beverage manufacturers concentrate procurement leverage; food industry channels gain share fastest.
Distribution Channel:
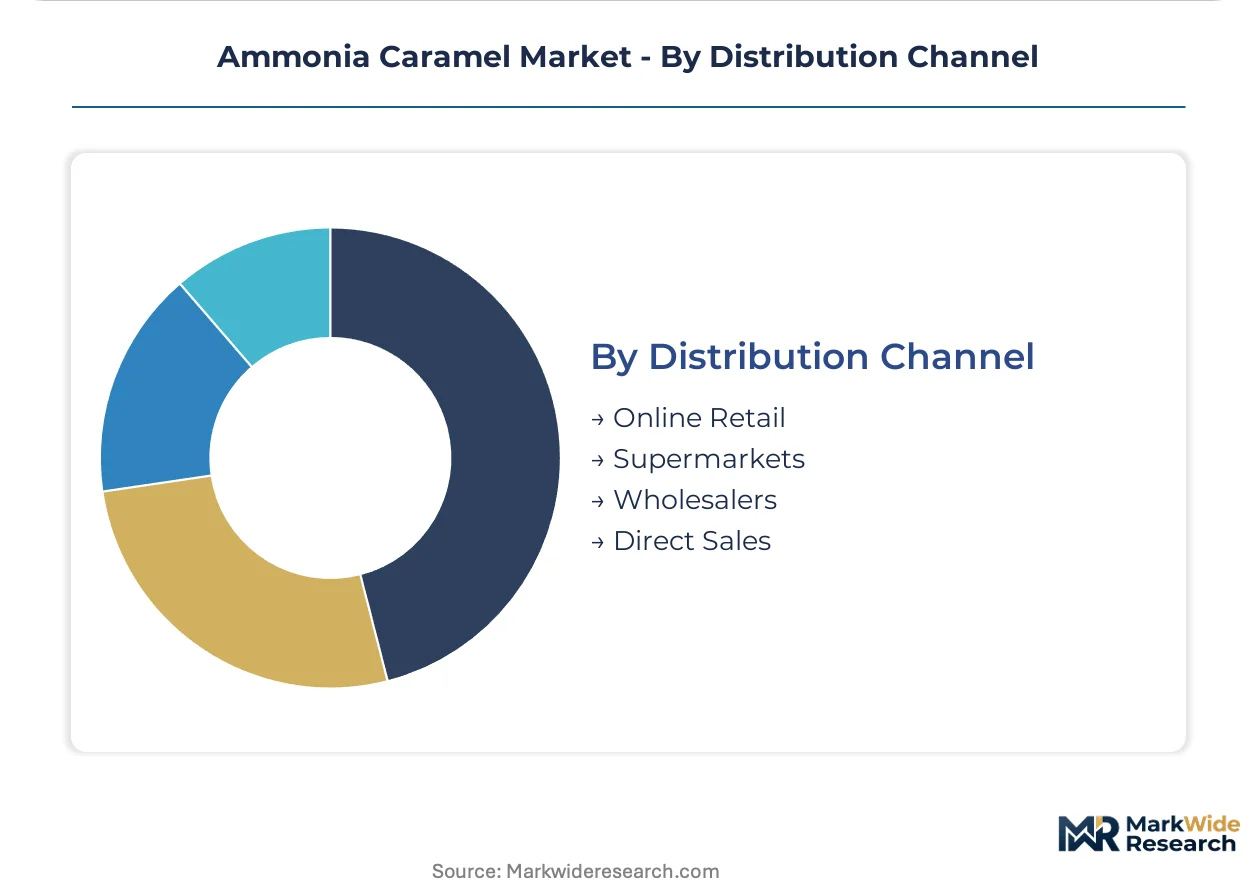
Supply concentration dynamics favor direct sales relationships with integrated producers, eroding distributor-mediated spot purchasing in developed markets.
- Direct Sales:Dominant in North American and Western European cola and energy drink verticals where formulation consistency requirements override price minimization.
- Wholesalers:Primary channel for powder-grade exports to Middle Eastern and African confectionery manufacturers.
- Supermarkets:Limited role; industrial-scale procurement bypasses retail intermediaries.
- Online Retail:Emerging for small-batch catering and specialty food service procurement.
Direct sales anchor volume throughput; online retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German beverage manufacturers absorb membrane-clarified caramel premiums for formulation consistency, while Indian sauce producers prioritize cost-minimized powder grades. This demand bifurcation shapes supplier investment allocation across regions.
Germany
Membrane-clarified caramel inputs command specification in premium cola formulations from Düsseldorf and Hamburg bottling clusters. EFSA's evolving 4-MeI thresholds force reactor reconfigurations across Bavarian and North Rhine-Westphalian production facilities. Private-label bread programs in Baden-Württemberg are eliminating azo dyes, pulling heat-stable paste formulations from regional caramel specialists.
United States
Consolidated procurement panels among Chicago and Atlanta beverage bottlers favor direct contracts with integrated reactor operators. FDA 21 CFR 73.85 compliance documentation anchors supplier selection in carbonated soft drink verticals. Wisconsin-based production facilities serve North American cola and energy drink manufacturers through captive capacity arrangements.
India
Sauce and condiment manufacturers in Maharashtra and Gujarat corridors substitute synthetic dyes with ammonia caramel alternatives at scale. FSSAI's Codex alignment reduces import friction for multinational suppliers entering Mumbai and Ahmedabad processing hubs. Domestic confectionery producers in Karnataka specify powder grades for inventory stability in tropical storage conditions.
Netherlands
Rotterdam and Amsterdam beverage formulators specify membrane-clarified inputs, fragmenting historical commodity glucose supplier relationships. REACH Annex XVII amendments mandate substitution of certain catalyst carriers in ammonium-based reactions. Eindhoven region caramel processors face reformulation investments to maintain EFSA compliance documentation for EU confectionery exports.
Vietnam
Ho Chi Minh City and Hanoi bottling operations expand liquid caramel volumes for export-oriented cola lines targeting ASEAN markets. Local sauce manufacturers lack captive colorant production, creating toll manufacturing opportunities for regional suppliers. Beverage procurement concentrates among multinational bottlers with formulation consistency requirements overriding spot price minimization.
Ammonia Caramel Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the ammonia caramel value chain. The market structures around three tiers: integrated reactor operators with captive regulatory dossiers, specialized paste formulators for high-heat applications, and toll manufacturers serving fragmented sauce corridors. Consolidation pressures concentrate procurement leverage among beverage manufacturers, forcing supplier panel reduction from six-to-eight vendors toward two-to-three strategic partners. Dominant competitive moves include membrane filtration technology licensing and backward integration into carbohydrate clarification.
Within the integrated reactor tier, DDW The Color House and Sensient Technologies Corporation exemplify archetypes combining captive extraction capabilities with multi-jurisdiction regulatory compliance. Sethness Products Company occupies a specialist position, its name signaling heritage in product-specific formulations. These three anchors represent distinct strategic postures: technology-driven membrane clarification, scale-driven direct contracting, and application-specific heat stability expertise. Their collective positioning illustrates how supplier differentiation fragments across liquid beverage grades, powder export channels, and paste bakery applications.
| Leading Market Players |
|---|
| DDW The Color House |
| Sethness Products Company |
| Sensient Technologies Corporation |
| Aarkay Food Products Ltd |
| Roquette |
| Nigay |
| Ingredion Incorporated |
| D.D. Williamson & Co., Inc. |
| Bakels Group |
| Others |
Value Chain & Pricing Dynamics
Reactor scale economies at integrated Wisconsin and Bavarian facilities anchor price floors across liquid beverage grades, concentrating supply leverage among three-to-four operators with captive regulatory dossiers while marginalizing toll-dependent competitors in cost-sensitive powder segments.
Pricing Analysis
EFSA's evolving 4-MeI thresholds dictate the pricing tier structure across ammonia caramel grades, separating membrane-clarified premium inputs for German cola bottlers from commodity-grade powder for Indian sauce corridors. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and reactor reconfiguration status, with EFSA-compliant documentation commanding substantial premia. Cost compression in standard liquid grades is intensifying because Brazilian sucrose volatility feeds directly into annual beverage supply contracts. Indian sauce manufacturers exhibit highest price sensitivity, while German private-label bread programs absorb paste-grade premia for azo dye substitution compliance.
Supply Chain Analysis
Inventory cycles stretching 18-24 months for EFSA-mandated reactor modifications strain working capital across European production facilities, forcing selective capacity allocation toward higher-margin powder export channels. Manufacturing concentrates in the United States, Germany, and India, with Wisconsin-based facilities serving North American beverage bottlers through direct contracting arrangements. Feedstock supply draws from Brazilian sucrose and Indian glucose syrup, both exposed to monsoon-driven harvest volatility. Single-source vulnerability concentrates in specialized catalyst carriers facing REACH Annex XVII substitution mandates. Distribution runs through direct sales relationships with integrated producers in developed markets, while powder-grade exports to Middle Eastern and African confectionery manufacturers rely on wholesaler intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anthocyanin and beetroot extract substitution in Nordic clean-label beverages threatens incumbent positioning, requiring defensive chemistry investments and application-specific moat construction.
For Market Incumbents: Consolidate supplier relationships with multinational beverage manufacturers from six-to-eight vendors toward two-to-three strategic partners, locking in formulation consistency requirements that override spot price minimization. Deepen backward integration into membrane filtration technology to sustain margin pools in premium liquid grades while EFSA tightens 4-MeI exposure thresholds. Prioritize reactor reconfiguration completion ahead of regulatory compliance deadlines to avoid segment abandonment in sensitive beverage applications. For New Entrants and Emerging Players: Differentiate on toll manufacturing capabilities for India's Maharashtra and Gujarat sauce corridors, where domestic producers lack captive caramel colorant production. Target powder-grade export channels to Middle Eastern and African confectionery markets prioritizing dry-format logistics and extended shelf stability. Pursue toll manufacturing partnerships with regional sauce manufacturers as the most penetrable entry vector, leveraging FSSAI Codex alignment to reduce import friction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated reactor operators with captive regulatory dossiers and membrane clarification capabilities over commodity-dependent toll manufacturers. Long-term viability hinges on EFSA compliance trajectory and natural colorant substitution velocity across premium beverage segments. Acquisition candidates with established EFSA documentation and Wisconsin or Bavarian production footprints offer defensive positioning. Watch membrane filtration technology licensing activity as inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Reconfiguration Investment | EFSA-mandated 4-MeI reductions require 18-24 month capital cycles for pressure vessel modifications. |
| Membrane Filtration Licensing | German and Dutch cola producers specify membrane-clarified inputs, fragmenting historical commodity glucose relationships. |
| Toll Manufacturing Partnership | India's Maharashtra and Gujarat sauce corridors lack captive production, creating white space for regional suppliers. |
| Powder-Grade Export Expansion | Middle Eastern and African confectionery markets prioritize dry-format logistics, commanding margin premia over liquid alternatives. |
| Regulatory Dossier Consolidation | Multi-jurisdiction FDA and EFSA compliance documentation anchors supplier selection in consolidated procurement panels. |
Study Parameters
Operator-level perspectives from caramel plant managers, beverage procurement leads at multinational bottlers, FSSAI regulatory affairs specialists, and European bakery R&D directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA 21 CFR 73.85 filings, EFSA scientific opinions on 4-MeI exposure, FSSAI Codex alignment notifications, and customs trade data on glucose syrup imports. Bottom-up capacity assessments at Wisconsin, Bavarian, and Maharashtra production facilities triangulated against top-down demand modeling across beverage, bakery, and sauce applications.
Sensitivity analysis across feedstock price scenarios and regulatory tightening velocities shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product format, application vertical, end-user procurement scale, and regional regulatory cluster. CAGRs derived from installed capacity utilization trends, substitution elasticity estimates, and import tariff exposure calculations. Forecast inputs incorporated EFSA 4-MeI threshold evolution assumptions and Brazilian sucrose harvest volatility patterns.
Forecasts assume regulatory continuity in EFSA, FDA, and FSSAI regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Firming Agents Market
Food Additives and Ingredients
Ph Adjuster Market
Food Additives and Ingredients
Food Grade Calcium Hydroxide Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Alpha-Linolenic Acid Market
Food Additives and Ingredients
Brazil Food Ingredient Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
Global Lutein and Lutein Esters Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Calcium Butyrate Market