
 Food Glazing Agents Market | 2026-2036
Food Glazing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Food Glazing Agents Market Analysis
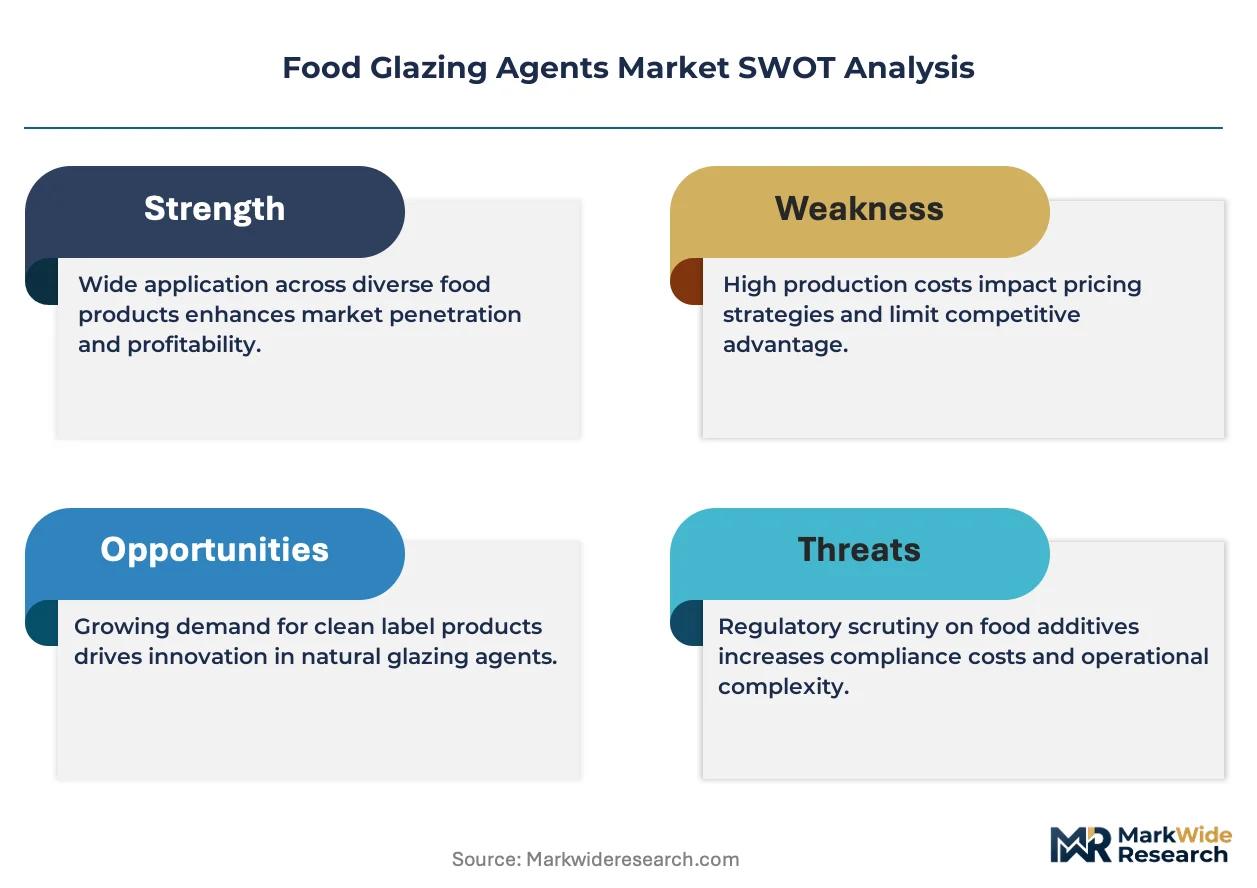
Multi-source procurement for natural resin feedstocks is recalibrating how food glazing agent suppliers secure raw material pipelines. Archer-Daniels-Midland Company leverages its integrated agricultural processing network to control carnauba wax supply chains from Brazilian cultivation through refined extraction. Kerry Group plc anchors its competitive position through specialized emulsion technologies that reduce dosage rates in confectionery coatings. BASF SE differentiates via synthetic polymer expertise applied to polyethylene glycol formulations for pharmaceutical-grade glazing applications.
Food glazing agents comprise surface-active compounds—primarily shellac, carnauba wax, beeswax, and polyethylene glycol—that form moisture-barrier films on finished food products at application temperatures between 60°C and 95°C. These coatings prevent moisture loss, control oxygen permeability, and deliver gloss uniformity across panned confections and fresh produce. Wax-based glazing agents dominate volume consumption due to established supply chains and cost structures in commodity confectionery, while shellac segments command premium positioning in pharmaceutical-grade and artisan chocolate applications where alcohol-soluble resin clarity matters. Natural gums represent the fastest-growing product category as formulators replace synthetic polyethylene glycol in clean-label bakery and fruit coating systems targeting EFSA-compliant export markets.
FDA food additive regulations under 21 CFR 172 govern shellac and wax coating identity standards in the United States, while EFSA sets maximum residue thresholds for hydrocarbon solvents in refined wax products across EU member states. India's FSSAI has begun aligning import specifications for glazing agents with CODEX Alimentarius benchmarks, affecting cross-border trade flows from Southeast Asian manufacturers. Stakeholders must monitor evolving purity certifications and regional solvent-extraction restrictions when selecting feedstock suppliers and co-manufacturing partners.
Market Dynamics
Clean-label confectionery mandates from EFSA and FDA are forcing wholesale reformulation of shellac and wax-based coating systems across European and North American manufacturing bases. This regulatory compression is redrawing supplier qualification criteria and raw material sourcing protocols.
Growth Catalysts
- EFSA Purity Standards:Tightening solvent residue limits for shellac coatings in EU export markets are accelerating demand for certified-refined natural resins from qualified Brazilian and Indian suppliers.
- Industrial Bakery Clusters:Germany's concentrated baking infrastructure generates sustained volume procurement of glazing systems for extended-shelf-life bread and pastry applications.
- Alcohol-Soluble Resin Clarity:Shellac's optical properties in artisan chocolate and pharmaceutical tablet coatings command premium positioning against synthetic polyethylene glycol alternatives.
Market Restraints
- Carnauba Wax Supply Concentration:Brazilian drought cycles and harvesting labor constraints create recurring input volatility for wax-dependent coating formulations.
- Hydrocarbon Solvent Restrictions:EFSA maximum residue thresholds for refined wax products impose costly purification upgrades on Southeast Asian processors serving EU markets.
- Natural Gum Performance Gaps:Clean-label gum alternatives currently lack the moisture-barrier efficiency of synthetic polyethylene glycol in high-humidity storage conditions.
Strategic Opportunities
- India FSSAI-CODEX Alignment:India's harmonization of import specifications with international benchmarks opens formalized pathways for compliant Southeast Asian manufacturers.
- Pharmaceutical-Grade Formulations:Polyethylene glycol glazing for nutraceutical and tablet applications represents an underexploited segment with distinct purity certification requirements.
- Emulsion Technology Convergence:Integration of reduced-dosage emulsion systems with automated confectionery panning equipment cuts coating material consumption per unit output.
Industry Challenges
- Clean-Label Reformulation Timelines:Confectionery manufacturers face compressed product redevelopment cycles to meet EFSA-compliant export deadlines without synthetic additive dependencies.
- Multi-Source Resin Qualification:Building redundant feedstock pipelines for shellac and carnauba wax requires duplicative supplier audits and solvent-extraction verification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Glazing Agents Market |
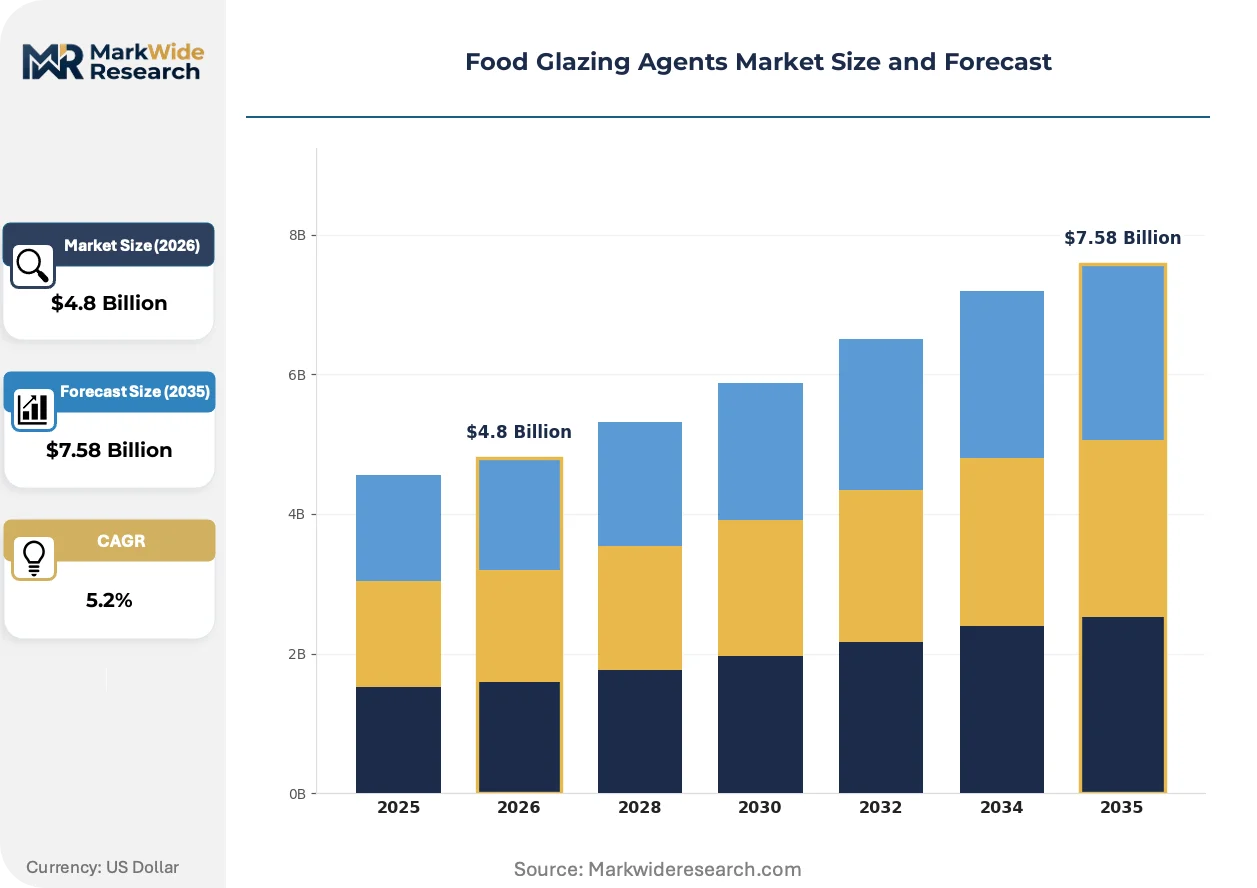
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wax-Based, Shellac, Polyethylene Glycol, Natural Gums Application: Bakery Products, Confectionery, Fruits & Vegetables, Dairy Products End User: Food Manufacturers, Retail Chains, Food Service Operators, Caterers Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade |
| Companies Covered | International Flavors & Fragrances, Inc., DuPont de Nemours, Inc., Archer-Daniels-Midland Company, Ingredion Incorporated, Wilmar International Limited, Kerry Group plc, BASF SE, Capol GmbH, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Glazing Agents Market Emerging Trajectories
Formulation chemistry and coating application hardware are converging to reduce dosage rates while maintaining barrier performance. This dual-track evolution is compressing material intensity benchmarks across confectionery and fresh produce segments.
Micro-encapsulated carnauba wax dispersions with sub-micron particle distribution are rewriting surface coverage economics in high-speed panning operations. Artisan chocolate manufacturers and contract confectionery co-packers in Belgium and Switzerland are adopting these systems to cut wax application rates by half while preserving gloss uniformity. The technology is compressing per-unit coating costs and enabling thinner moisture barriers that do not alter bite texture.
EFSA's 2023 updates to hydrocarbon solvent residue thresholds in food-grade waxes are forcing extraction technology upgrades across Southeast Asian refining facilities. Indian and Thai processors serving EU export markets must install molecular distillation or supercritical CO2 systems to maintain market access. Shellac segments face parallel pressure as pharmaceutical-grade resin clarity standards tighten for alcohol-soluble coatings in German and French tablet manufacturing.
Buyer concentration among industrial bakery groups is consolidating procurement leverage and compressing supplier margins. Germany's Rewe and Aldi supply chains now mandate consolidated glazing agent tenders across pan-European manufacturing footprints. This behavior shift is displacing fragmented national distributor networks with direct manufacturer relationships and volume-tiered pricing structures visible most acutely in Benelux and Nordic fresh produce coating contracts.
Food Glazing Agents Market Segmentation
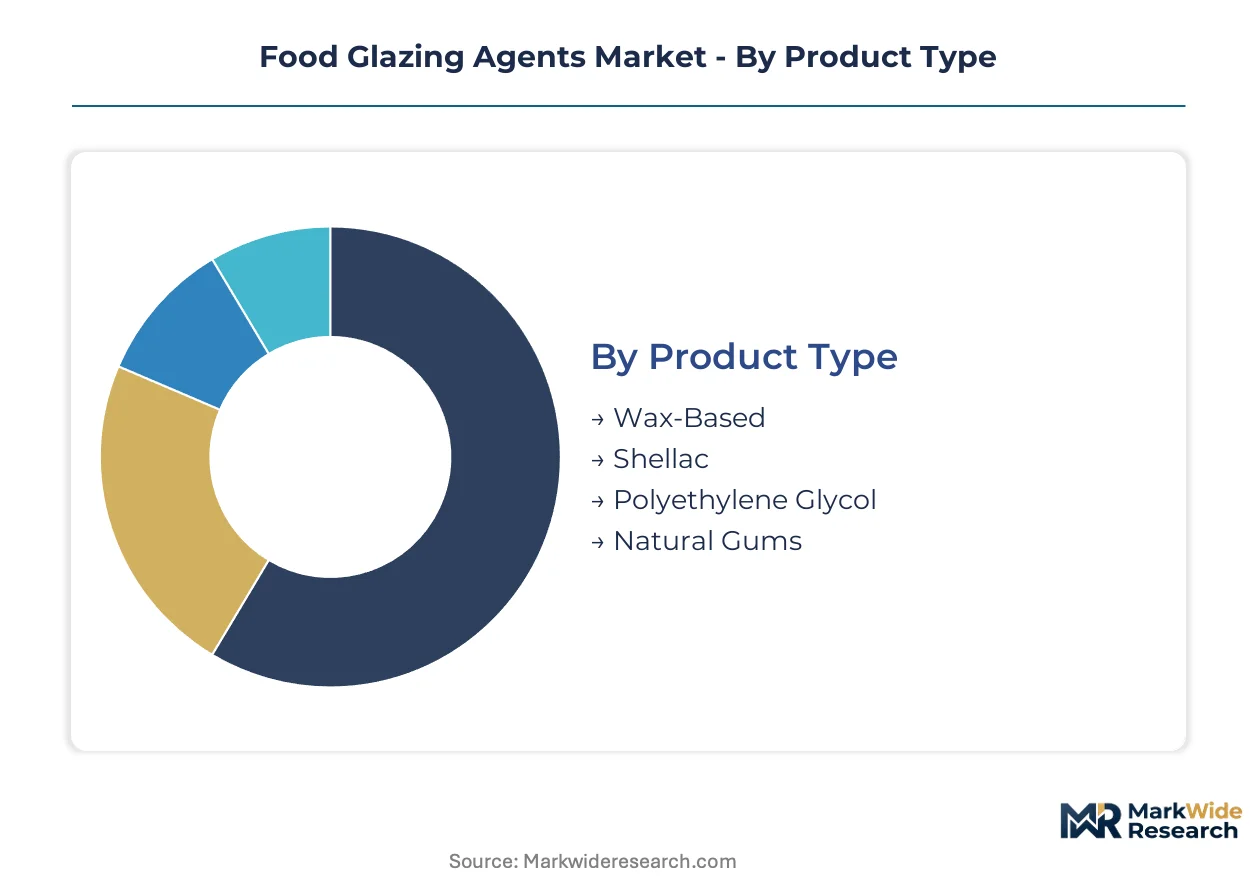
Food glazing agent procurement patterns diverge sharply across product chemistry, end-use application, and purity certification tiers. Buyers prioritize moisture-barrier performance, regulatory compliance, and clean-label positioning in distinct combinations that reshape supplier qualification criteria.
Product Type:
Cost tier separates commodity wax buyers from premium resin purchasers, with purification standards and supply chain reliability driving divergence.
- Wax-Based:Carnauba and beeswax formulations dominate high-volume confectionery coatings due to established Brazilian supply chains and cost structures. Germany's industrial bakery clusters sustain bulk procurement for extended-shelf-life bread applications, though Brazilian drought cycles inject recurring price volatility.
- Shellac:Alcohol-soluble resin coatings command premium positioning in artisan chocolate and pharmaceutical tablet manufacturing where optical clarity matters. EFSA solvent residue limits are accelerating demand for certified-refined Indian and Thai supply.
- Polyethylene Glycol:Synthetic polymer glazing delivers consistent moisture-barrier performance in high-humidity storage conditions. FDA 21 CFR 172 compliance requirements govern US pharmaceutical and nutraceutical applications.
- Natural Gums:Clean-label alternatives to synthetic coatings are expanding most quickly as formulators target EFSA-compliant export markets with plant-derived barrier systems.
Wax-Based coatings lead volumes today; Natural Gums are climbing the fastest.
Application:
Customer type determines performance specifications, with industrial manufacturers demanding automation-compatible coatings versus artisan producers prioritizing sensory attributes.
- Confectionery:Panned candy and chocolate coatings require gloss uniformity at high-speed production rates. Belgium and Switzerland's artisan manufacturers adopt micro-encapsulated wax dispersions to halve application rates without texture compromise.
- Bakery Products:Extended-shelf-life bread and pastry coatings prioritize moisture retention over visual gloss. Germany's Rewe and Aldi supply chains now mandate consolidated glazing tenders across pan-European manufacturing footprints.
- Fruits & Vegetables:Fresh produce coatings reduce dehydration and extend retail display life. Benelux and Nordic distribution contracts increasingly specify direct manufacturer relationships over fragmented national distributor networks.
- Dairy Products:Cheese and yogurt surface treatments demand food-grade purity certifications with neutral flavor profiles. India's FSSAI-CODEX alignment is opening formalized import pathways for compliant Southeast Asian processors.
Confectionery leads volumes today; Fruits & Vegetables are gaining share fastest.
End User:
Volume scale creates procurement leverage divergence, with concentrated manufacturing bases commanding tiered pricing structures unavailable to fragmented operators.
- Food Manufacturers:Integrated production facilities purchase glazing agents in bulk quantities with direct supplier contracts. Automated panning equipment integration is compressing per-unit coating consumption through reduced-dosage emulsion systems.
- Retail Chains:Private-label bakery and confectionery programs require consistent coating performance across multiple co-manufacturing sites. Consolidated tenders are displacing national distributor relationships in favor of volume-tiered direct agreements.
- Food Service Operators:Commercial bakeries and prepared food facilities prioritize cost-efficient coatings with minimal application complexity. Performance gaps in natural gum alternatives limit clean-label adoption in high-throughput environments.
- Caterers:Event and institutional food service represents a price-sensitive segment with limited specification stringency. Procurement typically flows through broadline distributors rather than direct manufacturer relationships.
Food Manufacturers lead volumes today; Retail Chains are expanding most quickly.
Grade:
Application maturity separates established food-grade specifications from emerging pharmaceutical and cosmetic purity tiers with distinct certification requirements.
- Food Grade:Standard purity coatings for direct food contact applications governed by FDA and EFSA additive regulations. EFSA's tightened hydrocarbon solvent thresholds are forcing extraction technology upgrades across Southeast Asian refining facilities.
- Pharmaceutical Grade:Ultra-pure coatings for tablet and nutraceutical applications with stringent residue limits. Molecular distillation and supercritical CO2 purification systems are becoming mandatory for EU market access.
- Industrial Grade:Non-food applications including packaging and processing equipment coatings with reduced purity requirements. Price competition from commodity wax suppliers characterizes this segment.
- Cosmetic Grade:Specialized coatings for personal care products with sensory and stability specifications distinct from food applications. Smaller volume segment with premium pricing structures.
Food Grade leads volumes today; Pharmaceutical Grade shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial bakery clusters concentrate sustained volume procurement of glazing systems for extended-shelf-life bread and pastry applications. Regulatory divergence across major jurisdictions is fragmenting supplier qualification criteria and reshaping raw material sourcing protocols.
Germany
Rewe and Aldi supply chains mandate consolidated glazing agent tenders across pan-European manufacturing footprints. EFSA purity standards for shellac and wax-based coatings tighten compositional requirements for EU export compliance. The industrial bakery concentration around North Rhine-Westphalia and Bavaria drives bulk procurement of moisture-barrier systems.
United States
FDA food additive regulations under 21 CFR 172 govern shellac and wax coating identity standards for confectionery and pharmaceutical applications. Confectionery manufacturers face compressed product redevelopment cycles to meet clean-label mandates without synthetic additive dependencies. Midwestern food manufacturing corridors sustain demand for polyethylene glycol glazing in nutraceutical tablet production.
Brazil
Carnauba wax harvesting from northeastern palm plantations supplies global confectionery coating feedstocks. Brazilian drought cycles and harvesting labor constraints create recurring input volatility for wax-dependent formulations. São Paulo-based processors control refined extraction infrastructure serving European and North American export markets.
India
FSSAI alignment of import specifications with CODEX Alimentarius benchmarks affects cross-border trade flows from Southeast Asian manufacturers. Shellac resin processing clusters in Maharashtra and Bihar supply pharmaceutical-grade clarity coatings to German and French tablet manufacturers. Mumbai and Delhi-NCR logistics hubs facilitate regional distribution of natural gum alternatives targeting clean-label bakery segments.
Thailand
EFSA hydrocarbon solvent residue thresholds force molecular distillation upgrades at Southeast Asian refining facilities. Bangkok-centered processors must install supercritical CO2 extraction systems to maintain EU market access for food-grade wax products. Domestic confectionery growth complements export-oriented purification infrastructure investments.
Food Glazing Agents Market Vendor Landscape
Global majors compete with regional champions across raw material control and specialized emulsion technologies. Market structure tilts toward consolidated agricultural processors with captive supply chains, while mid-tier specialists compete on formulation chemistry. Three archetypes dominate: integrated agribusiness conglomerates controlling cultivation-to-refinement pipelines, specialty chemical houses with synthetic polymer expertise, and regional glazing specialists with local regulatory navigation capabilities. Capacity expansion and backward integration into feedstock sourcing represent the dominant competitive moves.
Within the integrated agribusiness tier, Archer-Daniels-Midland Company exemplifies upstream control over Brazilian carnauba wax cultivation networks. Kerry Group plc occupies a position among specialty formulation houses with reduced-dosage emulsion capabilities. BASF SE anchors the synthetic polymer segment with polyethylene glycol expertise applied to pharmaceutical-grade applications.
| Leading Market Players |
|---|
| International Flavors & Fragrances, Inc. |
| DuPont de Nemours, Inc. |
| Archer-Daniels-Midland Company |
| Ingredion Incorporated |
| Wilmar International Limited |
| Kerry Group plc |
| BASF SE |
| Capol GmbH |
| Cargill, Incorporated |
| Others |
Supply Flow & Price Mechanics
Micro-encapsulated carnauba wax dispersions are compressing per-unit coating economics while simultaneously concentrating procurement leverage among automated confectionery manufacturers. This dual shift redraws supplier margins and reshapes raw material sourcing protocols across Brazilian cultivation networks and Southeast Asian refining facilities.
Pricing Analysis
Input-cost pass-through from Brazilian drought cycles and EFSA-mandated solvent-extraction upgrades flows directly into wax-based coating quotations. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certifications separates premium shellac resin coatings from commodity wax alternatives. Price differentiation hinges on purity certification attainment and volume-scale procurement leverage. Food manufacturers with automated panning lines command the least price sensitivity, while caterers and food service operators exhibit acute cost consciousness.
Supply Chain Analysis
Carnauba wax supply rests on northeastern Brazilian palm plantations, Indian shellac processing clusters in Maharashtra and Bihar, and Thai refining facilities serving EU export markets. Raw material dependencies include crude carnauba wax, lac insect resin harvests, and hydrocarbon solvent feedstocks for extraction processes. Single-source vulnerability concentrates around Brazilian climatic volatility and labor availability constraints. Distribution runs through direct manufacturer relationships with industrial bakery clusters and consolidated retail chain tenders displacing fragmented national distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as clean-label regulatory mandates perpetuate reformulation demand across confectionery and pharmaceutical coating applications. EFSA and FDA compliance requirements ensure sustained procurement of certified-refined natural resins and upgraded extraction infrastructure.
For Market Incumbents: Extend backward integration into Brazilian carnauba wax cultivation networks to secure feedstock pipelines against drought-induced volatility. Deepen emulsion technology R&D to maintain dosage-rate advantages as micro-encapsulation becomes table stakes. Counter emerging regional specialists by locking in multi-year supply agreements with German and Benelux industrial bakery clusters. For New Entrants and Emerging Players: Capture pharmaceutical-grade polyethylene glycol glazing segments where BASF's synthetic polymer expertise has left service gaps in nutraceutical tablet applications. Exploit India's FSSAI-CODEX alignment by establishing compliant refining capacity for Southeast Asian export markets. Lead with supercritical CO2 extraction capabilities as a regulatory-compliant go-to-market wedge against solvent-dependent incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among Southeast Asian processors facing EFSA-mandated extraction upgrades but lacking capital access. Long-term viability centers on feedstock-adjacent refining assets with pharmaceutical-grade certification pathways. Watch for Brazilian drought severity and EFSA solvent threshold enforcement as inflection triggers for consolidation activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Cultivation | Archer-Daniels-Midland's Brazilian carnauba wax networks demonstrate margin protection against supply volatility. |
| Supercritical CO2 Extraction Installation | Thai and Indian processors gain EFSA market access by replacing hydrocarbon solvent systems. |
| Reduced-Dosage Emulsion Development | Kerry Group's specialized technologies cut coating consumption per unit in high-speed panning operations. |
| Pharmaceutical-Grade Certification Investment | Polyethylene glycol formulators unlock nutraceutical tablet demand with FDA 21 CFR 172 compliance. |
| Consolidated Retail Chain Tendering | Rewe and Aldi supply chains displace national distributors through volume-tiered direct manufacturer agreements. |
Methodological Framework
Coverage spans Germany, the United States, Brazil, India, and Thailand, with primary inputs from each market informing demand modeling and supply-side validation. The analysis combines interviews with confectionery plant managers, industrial bakery procurement leads, wax refining technical directors, pharmaceutical tablet manufacturing executives, and retail chain category buyers. Secondary validation draws from FDA 21 CFR 172 filings, EFSA additive regulations, FSSAI import specifications, customs and trade flow data, and SEC filings from publicly traded agribusiness conglomerates. Bottom-up demand aggregation and top-down supply capacity assessments triangulate market sizing.
Granularity-level modeling operates at product chemistry tier, application segment, purity certification grade, and end-user procurement scale. The projection horizon incorporates volume and value outputs across wax-based, shellac, polyethylene glycol, and natural gum categories. CAGRs derive from segment-level growth rate reconciliation against macroeconomic drivers and regulatory enforcement timelines. Forecast inputs include EFSA solvent residue threshold implementation schedules, Brazilian agricultural yield variability, and industrial bakery automation adoption curves.
Regulatory enforcement delays, Brazilian climatic extremes, and clean-label reformulation cost absorption failures are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about EFSA compliance deadlines and CODEX harmonization progress. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Sunset Yellow FCF Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
Semi-Finished Pastry Ingredients Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
South Africa Food Emulsifiers Market
Food Additives and Ingredients
Chymosine Market