
 United States Food Acidulants Market | 2026-2036
United States Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
United States Food Acidulants Market Outlook
Asset-light toll manufacturing and third-party fermentation leasing is tilting competitive dynamics toward mid-scale entrants who avoid capital-heavy citric acid bioreactor investments. Cargill, Incorporated leverages backward integration into corn dextrose feedstock to anchor domestic citric acid cost positions. Jungbunzlauer Suisse AG competes through specialized organic acid fermentation expertise, while Bartek Ingredients Inc. differentiates via malic and fumaric acid product depth for confectionery clients.
Food acidulants comprise organic and inorganic compounds—citric, lactic, acetic, and phosphoric acids—added to adjust pH, enhance flavor profiles, inhibit microbial spoilage, and stabilize color in processed foods, typically dosed between 0.1% and 2.0% by weight depending on application. Citric acid dominates product type volumes due to its GRAS status and versatility across beverage acidification, though phosphoric acid retains structural importance in cola formulations where tartness modulation requires lower dosage rates. Application demand in dairy products and beverages commands the largest margin pools, while bakery and confectionery segments present faster growth trajectories as clean-label reformulations accelerate.
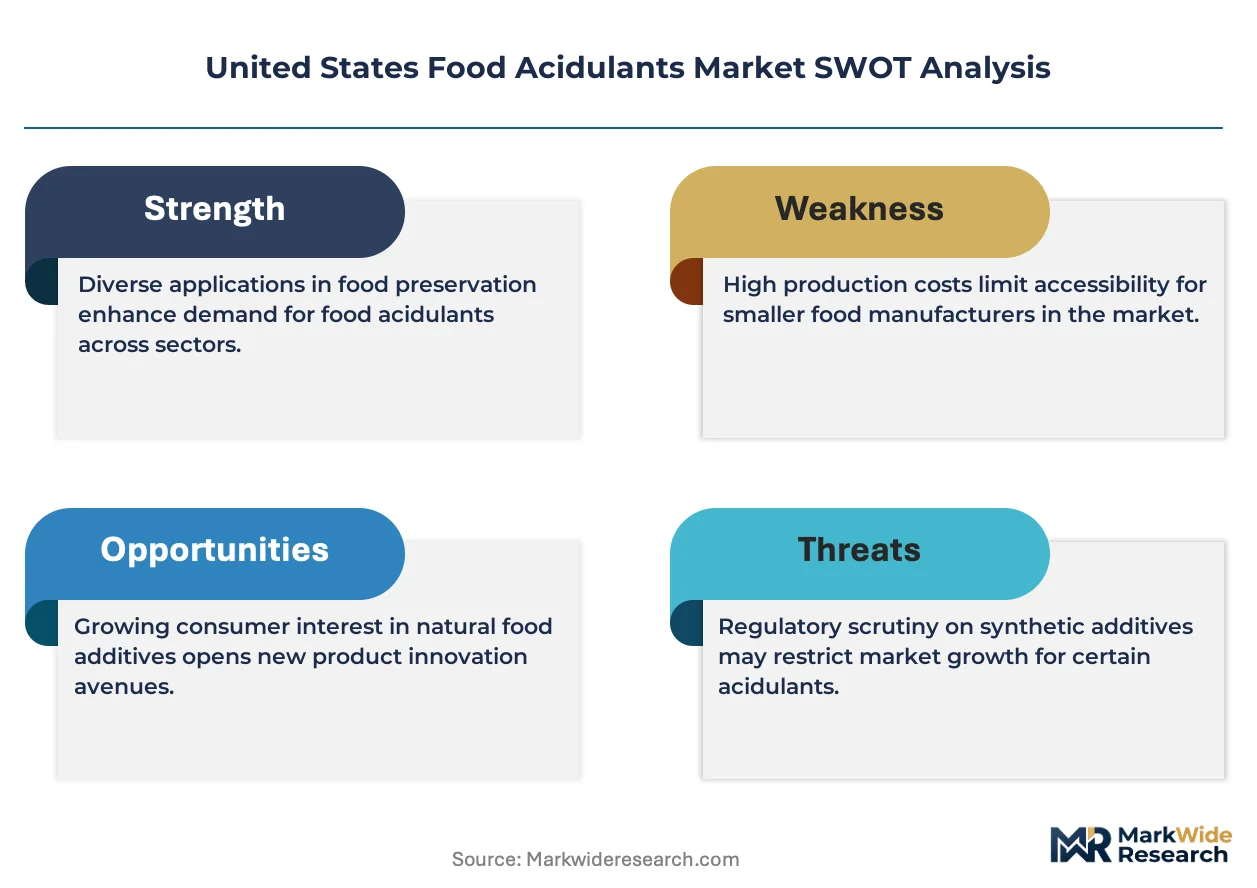
FDA oversight under 21 CFR Part 172 and USDA FSIS labeling requirements shape acidulant purity specifications and GRAS affirmation pathways, directly influencing manufacturer qualification timelines and customer switching costs. OSHA Process Safety Management standards and EPA Clean Air Act permitting for fermentation emissions further constrain plant siting and expansion economics in major production states. Stakeholders must monitor evolving FDA guidance on natural versus synthetic acidulant labeling claims, as classification disputes threaten to redraw competitive boundaries between fermentation-derived and chemically synthesized supply sources.
Market Dynamics
Clean-label reformulation mandates from FDA are compressing acidulant qualification timelines while simultaneously fragmenting supplier bases as mid-scale fermentation operators capture toll manufacturing contracts from capital-constrained incumbents.
Growth Catalysts
- 21 CFR Part 172 Enforcement:Tightened FDA purity standards for food-additive GRAS affirmation are accelerating processor switching toward qualified domestic fermentation-derived acidulant suppliers in Wisconsin and Pennsylvania dairy corridors.
- Ready-to-Drink Beverage Expansion:Northeast and Great Lakes clean-label producers are expanding acidulant procurement volumes as pH stabilization requirements intensify across extended shelf-life formulations.
- Confectionery Reformulation:Malic and fumaric acid applications in sugar-free and reduced-calorie candy segments are pulling specialized organic acid demand from California and Illinois processing clusters.
Market Restraints
- Corn Dextrose Feedstock Volatility:Citric acid production economics remain tethered to Midwest grain price swings, compressing margin stability for non-integrated fermentation operators.
- Great Lakes Supply Concentration:Fermentation capacity clustering around Chicago-Milwaukee corridor creates geographic vulnerability to regional EPA Clean Air Act permitting delays.
- Phosphoric Acid Substitution Ceiling:Cola manufacturers face technical barriers replacing phosphoric acid with organic alternatives without altering signature taste profiles and mouthfeel characteristics.
Strategic Opportunities
- Texas and Southeast Processing Corridors:Underpenetrated acidulant demand in emerging dairy and beverage manufacturing clusters offers first-mover positioning for toll fermentation operators.
- USDA FSIS Labeling Harmonization:Pending alignment between FDA and USDA acidulant declaration standards could streamline multi-jurisdiction product launches for national brands.
- Bioreactor Digital Twin Integration:Convergence of fermentation process modeling with real-time pH monitoring systems enables predictive acidulant dosing optimization for contract manufacturers.
Industry Challenges
- Fermentation Microbiology Talent Scarcity:Specialized strain engineering and bioprocess optimization expertise concentrates among aging cohorts at legacy Midwest producers, constraining expansion timelines.
- OSHA PSM Compliance Burden:Process Safety Management standards for large-scale organic acid fermentation facilities impose capital-intensive relief system upgrades and documented management-of-change protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Food Acidulants Market |
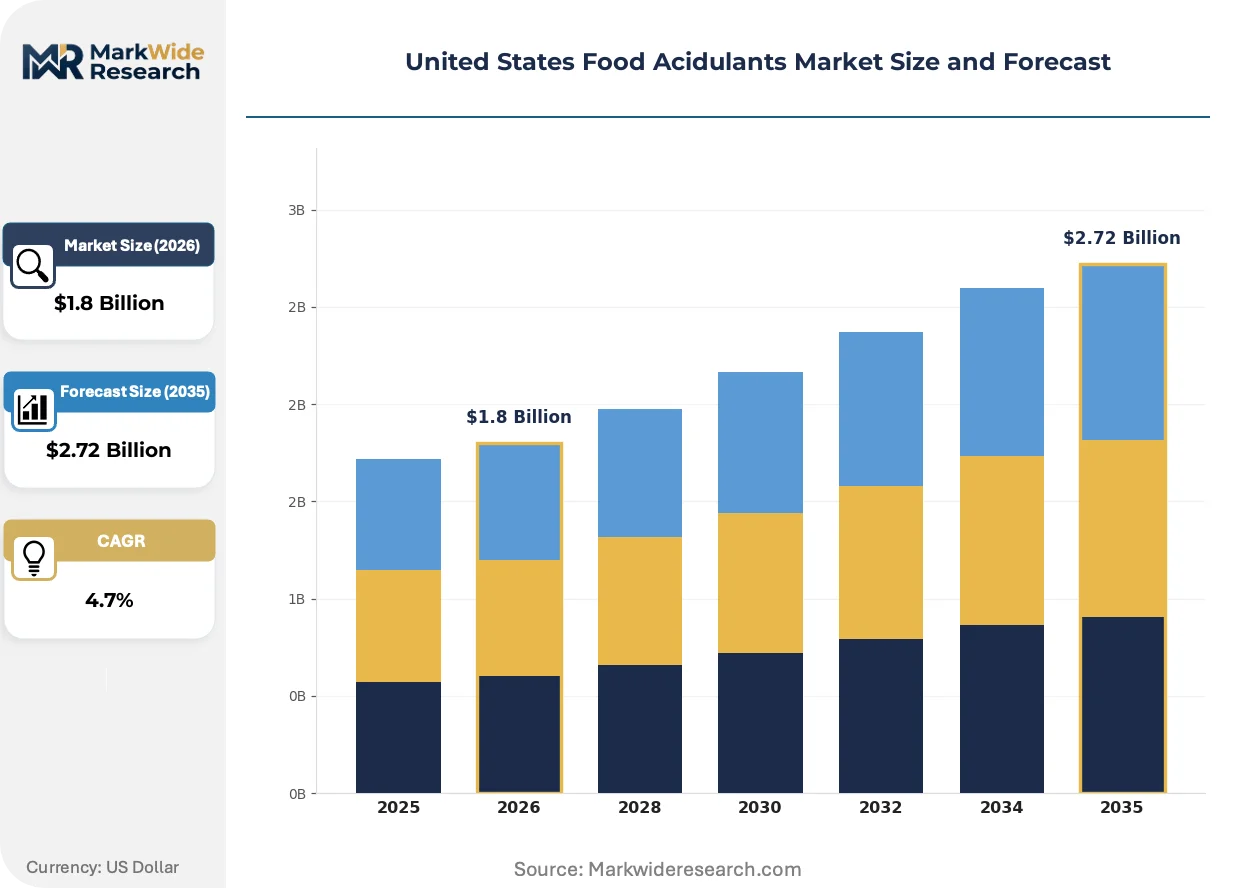
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Acetic Acid, Lactic Acid, Phosphoric Acid Application: Dairy Products, Beverages, Bakery, Confectionery End User: Food Manufacturers, Beverage Producers, Retailers, Food Service Form: Liquid, Powder, Granular, Crystalline |
| Companies Covered | Cargill, Incorporated, Tate & Lyle PLC, Jungbunzlauer Suisse AG, Corbion NV, Archer Daniels Midland Company, Brenntag AG, Bartek Ingredients Inc., FBC Industries, Hawkins Watts Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Food Acidulants Market Strategic Shifts
Digital fermentation control systems and biosynthetic pathway engineering are compressing acidulant production batch variability while enabling novel organic acid isomers previously uneconomical at commercial scale.
Continuous fermentation monitoring through integrated spectroscopic sensors is virtualizing traditional offline titration workflows for citric acid and lactic acid producers. Mid-scale toll operators in Pennsylvania and Ohio are adopting these systems fastest, enabling real-time pH trajectory correction that reduces batch failure rates and compresses quality assurance labor intensity across extended production runs.
FDA guidance development on natural versus synthetic acidulant labeling claims is forcing reformulation transparency disclosures from fermentation-derived suppliers. Beverage processors in California and New York are pre-emptively restructuring supplier qualification protocols to anticipate classification disputes, redirecting procurement toward operators with documented non-GMO substrate chains and third-party natural certification.
Direct acidulant procurement from fermentation tollers is displacing traditional distributor intermediation among large dairy processors. Wisconsin and Minnesota cheese and yogurt manufacturers are establishing captive supply agreements with regional bioreactor operators, compressing working capital cycles and enabling customized acidulant blends for specific pH stability requirements in extended shelf-life applications.
United States Food Acidulants Market Segmentation
Acidulant procurement patterns diverge sharply across product chemistry, application requirements, and end-user scale, forcing suppliers to maintain parallel qualification protocols. Technical specifications for FDA 21 CFR Part 172 compliance vary by segment, fragmenting vendor bases and compressing contract timelines for multi-segment processors.
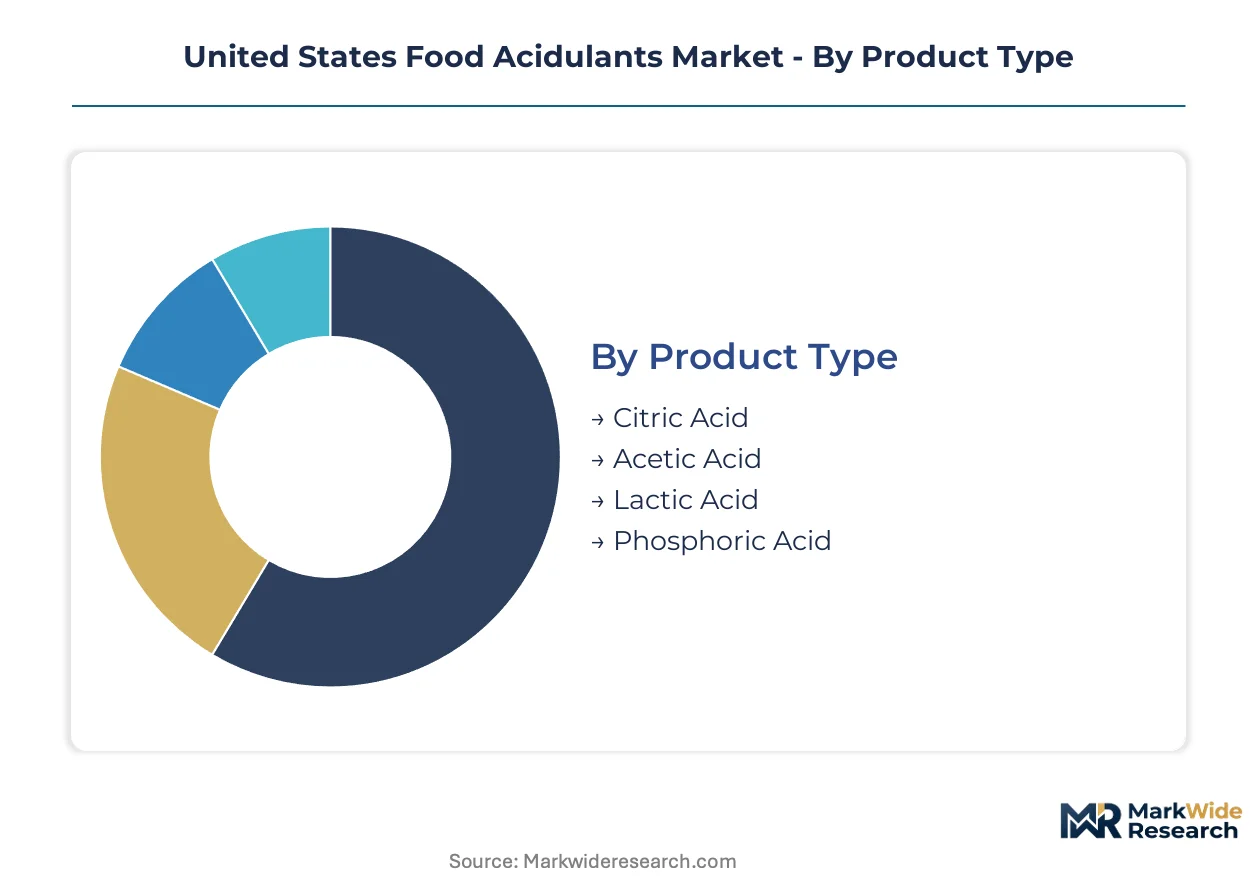
Product Type:
After-sales technical support intensity concentrates in fermentation-derived organic acids where batch variability demands ongoing pH optimization consultation.
- Citric Acid:Fermentation-derived from Aspergillus niger on corn dextrose substrate, this GRAS-affirmed acid dominates beverage acidification and dairy pH stabilization. Wisconsin and Pennsylvania dairy corridors drive procurement volumes as clean-label reformulations displace synthetic alternatives.
- Phosphoric Acid:Inorganic acid produced through wet-process phosphate rock digestion, essential for cola formulations requiring low-dosage tartness modulation without flavor masking. Technical barriers to organic substitution preserve structural demand from Atlanta and Plano beverage headquarters clusters.
- Acetic Acid:Synthetic and fermentation-derived grades serve pickling and sauce applications with varying purity specifications.
- Lactic Acid:Fermentation-produced from carbohydrate substrates, concentrated in dairy and meat preservation segments across Midwest processing states.
By volume, citric acid leads. By growth pace, lactic acid is ahead.
Application:
Cost tier stratification separates commodity acidification from premium functional applications where pH stability extends shelf-life economics.
- Dairy Products:Cheese, yogurt, and processed milk applications require precise pH control for protein stability and microbial inhibition. California and Wisconsin processors command the largest margin pools through extended shelf-life formulations.
- Beverages:Carbonated soft drinks, juices, and ready-to-drink formulations drive bulk acidulant consumption with stringent clarity and taste neutrality requirements. Northeast clean-label producers are expanding procurement fastest.
- Bakery:Dough conditioning and preservation applications leverage acidulant blends for crumb structure and mold inhibition.
- Confectionery:Sugar-free and reduced-calorie candy segments pull specialized malic and fumaric acid demand from Illinois and California processing clusters.
By revenue concentration, dairy and beverages dominate. By expansion trajectory, confectionery is climbing the fastest.
End User:
Customer type determines contract structure, with large food manufacturers demanding captive supply agreements while food service relies on distributor intermediation.
- Food Manufacturers:Integrated dairy, bakery, and confectionery processors with direct acidulant specification authority. Minnesota and Wisconsin cheese manufacturers are establishing captive fermentation tolling agreements to compress working capital cycles.
- Beverage Producers:National and regional brands with centralized procurement from Atlanta, Plano, and Purchase headquarters locations.
- Retailers:Private-label product developers sourcing through co-manufacturer networks with limited direct acidulant engagement.
- Food Service:Restaurant chains and institutional feeders purchasing through broadline distributors with standardized acidulant blends.
By procurement scale, food manufacturers lead. By contract flexibility, food service is gaining share fastest.
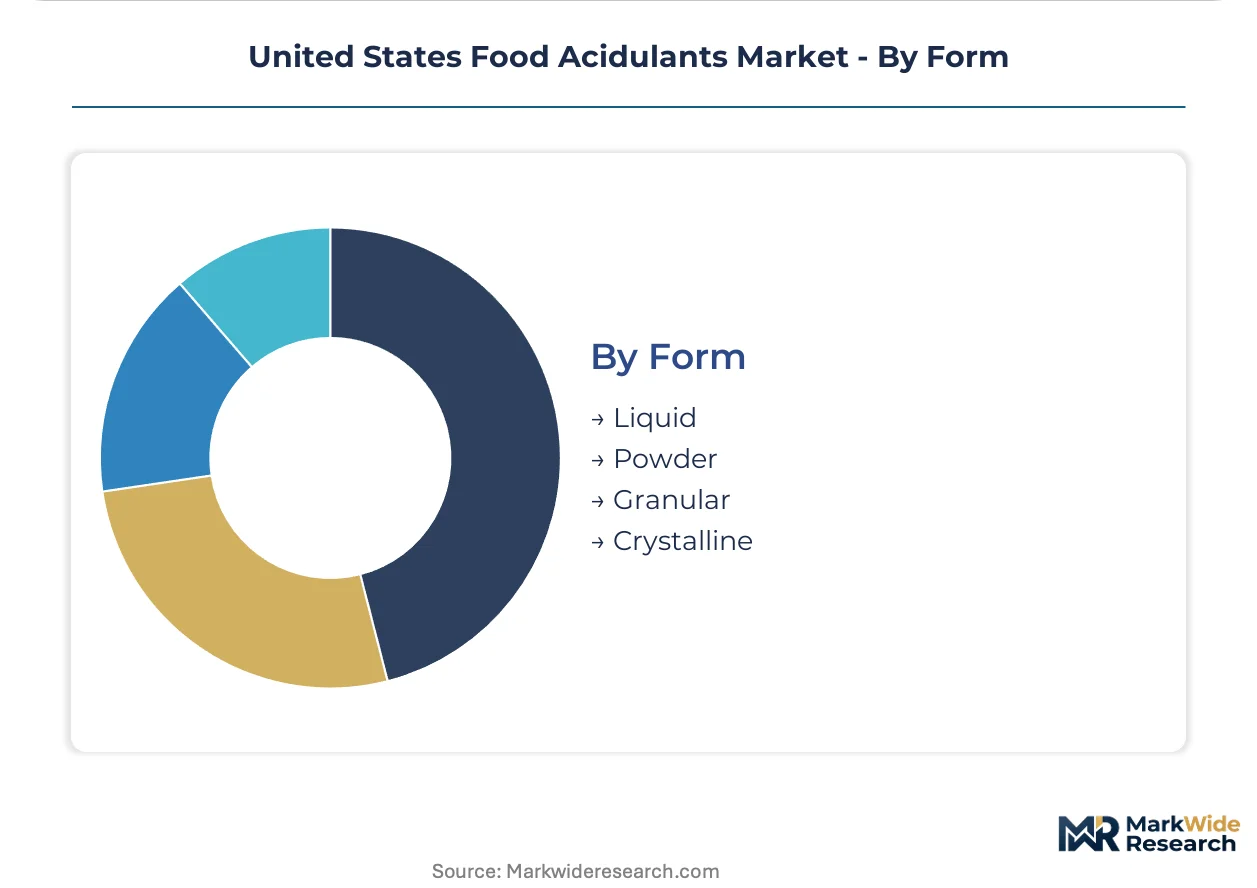
Form:
Volume economics favor powder and liquid formats while granular and crystalline grades command premium positioning in specialized applications.
- Liquid:Pre-diluted solutions enabling precise dosing integration in continuous beverage processing lines. Texas and Southeast dairy expansions are driving tanker-trailer delivery infrastructure investment.
- Powder:Spray-dried and anhydrous grades dominating bakery and dry-mix applications with extended storage stability requirements.
- Granular:Free-flowing crystalline forms for confectionery tableting and controlled-release formulations.
- Crystalline:High-purity acid grades for pharmaceutical-adjacent food applications demanding documented impurity profiles.
By tonnage, liquid and powder lead. By value per kilogram, crystalline shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Wisconsin dairy corridor commands premium acidulant pricing against Southeast processing clusters where toll fermentation infrastructure remains underdeveloped. California beverage manufacturers absorb elevated logistics costs from Midwest supply origins. Pennsylvania cheese processors leverage proximity to Appalachian fermentation capacity for compressed procurement cycles.
Northeast Corridor
Clean-label ready-to-drink beverage producers in Massachusetts and New York are expanding acidulant procurement volumes. FDA 21 CFR Part 172 enforcement tightens supplier qualification timelines across the region. Greater Boston processing clusters drive demand for fermentation-derived citric acid with documented non-GMO substrate chains.
Great Lakes Region
Wisconsin and Minnesota dairy manufacturers establish captive tolling agreements with regional bioreactor operators. EPA Clean Air Act permitting constraints limit fermentation capacity expansion around the Chicago-Milwaukee corridor. Illinois confectionery processors pull specialized malic and fumaric acid demand from localized organic acid specialists.
California
Extended shelf-life yogurt and plant-based dairy alternatives drive precision pH stabilization requirements. California Department of Public Health labeling standards exceed federal baselines for acidulant declaration transparency. Central Valley processing clusters absorb elevated freight costs from Midwest citric acid origins.
Southeast
Emerging dairy and beverage manufacturing in Georgia and Florida creates first-mover positioning for toll fermentation operators. OSHA Process Safety Management standards impose capital-intensive relief system upgrades for new large-scale facilities. Texas Gulf Coast chemical infrastructure offers phosphoric acid sourcing advantages for cola formulation hubs.
Pennsylvania
Cheese and processed milk applications require precise acidulant blends for protein stability in extended distribution networks. Pennsylvania Department of Agriculture inspection protocols align with USDA FSIS labeling requirements for multi-jurisdiction product launches. Appalachian fermentation capacity serves regional processors with compressed working capital cycles.
United States Food Acidulants Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with targeted chemistry expertise. The vendor base stratifies between backward-integrated agribusiness conglomerates and mid-scale fermentation tollers. Three archetypes dominate: corn dextrose-integrated citric acid producers, specialized organic acid fermenters, and regional toll manufacturing operators. Competitive dynamics center on captive supply agreements and bioreactor digital twin integration.
Among integrated agribusiness operators, Cargill, Incorporated anchors the upstream control archetype through corn dextrose feedstock dominance. Jungbunzlauer Suisse AG occupies a position exemplifying specialized organic acid fermentation expertise. Bartek Ingredients Inc. represents the targeted chemistry tier with concentrated malic and fumaric acid capabilities for confectionery applications.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Tate & Lyle PLC |
| Jungbunzlauer Suisse AG |
| Corbion NV |
| Archer Daniels Midland Company |
| Brenntag AG |
| Bartek Ingredients Inc. |
| FBC Industries |
| Hawkins Watts Limited |
| Others |
Value Chain & Pricing Dynamics
Corn dextrose feedstock volatility determines both the spread between integrated and non-integrated supplier pricing tiers and the geographic clustering of fermentation capacity around Midwest grain origination points. FDA 21 CFR Part 172 compliance costs compress margin pools for toll operators while elevating qualification premiums for documented natural-certification holders.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the dairy and beverage processor base. Three-tier pricing structure across fermentation-grade premium, standard technical, and economy industrial tiers separates suppliers by FDA documentation depth and non-GMO substrate certification. Pricing pressure stems from Midwest grain price swings transmitting directly into citric acid production economics. Small-scale confectionery manufacturers exhibit highest price sensitivity, while extended shelf-life dairy processors absorb premiums for batch-to-batch pH consistency guarantees.
Supply Chain Analysis
Toll fermentation operators in Wisconsin, Pennsylvania, and Ohio hold the majority of contract manufacturing capacity for organic acid production. Raw material flows draw from Iowa and Illinois corn dextrose refineries, Appalachian phosphate rock processing for phosphoric acid, and regional carbohydrate feedstock distributors. Single-source vulnerability concentrates in the Chicago-Milwaukee corridor where EPA Clean Air Act permitting constraints limit capacity expansion. Distribution runs through tanker-trailer liquid delivery networks for beverage processors and rail-served bulk powder terminals for dairy and bakery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic acid substitution threats from fermentation-derived alternatives and natural pH modifiers force phosphoric acid incumbents into defensive positioning. Incumbents must navigate tightening FDA natural-versus-synthetic classification guidance that threatens to resegment supplier qualification protocols.
For Market Incumbents: Build captive tolling moats through backward integration into regional bioreactor capacity in Wisconsin and Pennsylvania dairy corridors. Secure corn dextrose supply agreements with Midwest grain processors to buffer feedstock volatility exposure. Invest in documented non-GMO substrate chain certification to preempt FDA natural-labeling disputes that threaten to displace synthetic acidulant demand.
For New Entrants and Emerging Players: Southeast processing corridor underpenetration offers first-mover positioning in Georgia and Florida dairy expansions where fermentation infrastructure remains undeveloped. Target ready-to-drink beverage co-manufacturers in Texas seeking localized acidulant sourcing to reduce freight costs from Midwest origins. Pursue toll manufacturing contracts with mid-scale dairy processors seeking compressed working capital cycles outside distributor intermediation.
For Investors and Strategic Acquirers: Pending FDA guidance finalization on natural acidulant labeling reshapes the acquisition landscape toward fermentation-derived specialists with third-party certification infrastructure. Position for five-to-ten year horizon consolidation as qualification cost barriers elevate scale economics. Monitor EPA Clean Air Act permitting velocity in the Great Lakes region as inflection indicator for regional capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Corn dextrose supply agreements with Iowa and Illinois grain processors compress margin volatility exposure. |
| Bioreactor Digital Twin Deployment | Predictive pH optimization reduces batch failure rates for Pennsylvania and Ohio toll operators. |
| Non-GMO Certification Investment | Third-party natural labeling documentation preempts FDA 21 CFR Part 172 classification disputes. |
| Southeast Corridor Capacity Expansion | Georgia and Florida dairy growth creates first-mover positioning outside Midwest supply concentration. |
| Captive Tolling Agreement Structuring | Direct supply relationships with Wisconsin and Minnesota cheese manufacturers displace distributor intermediation. |
Study Parameters
Cross-validation between fermentation plant managers and dairy processor procurement leads anchors the qualitative findings on acidulant specification evolution. Secondary validation incorporates FDA 21 CFR guidance documents, USDA FSIS labeling directives, EPA Clean Air Act permitting records, and SEC filings from integrated agribusiness operators. Bottom-up volume modeling from individual bioreactor capacity and top-down demand triangulation from dairy and beverage processing clusters converge across the analysis window.
Calibration against historical corn dextrose price transmission patterns and acidulant contract renewal cycles refines projection outputs. Segmentation dimensions span acid chemistry type, application requirement tier, end-user scale category, and regional processing corridor concentration. CAGRs derive from fitted growth curves against observed procurement volume trajectories, with fermentation microbiology talent availability and EPA permitting velocity as industry-specific forecast modifiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by mid-scale toll operators or accelerated FDA natural-labeling enforcement would shift outcomes. Quarterly review of EPA permitting backlogs in the Great Lakes region and FDA guidance publication timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Allulose for Food Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market